
 Containment and Handling Drilling Waste Management Market | 2026-2036
Containment and Handling Drilling Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Containment and Handling Drilling Waste Management Market Insights
Modular tank system bundling is consolidating buyer preference across North American land rigs. Baker Hughes leverages integrated containment-to-treatment workflows to anchor long-term rig contracts. Halliburton sustains technology leadership through automated cuttings conveyance systems. Schlumberger differentiates via digital waste tracking platforms that extend service stickiness with exploration firms.
Containment and handling drilling waste management encompasses engineered systems for capturing, transporting, and temporarily storing drilling byproducts at temperatures exceeding 150°C and pressures above 10,000 psi, using steel-framed tanks, polymer-sealed drums, or solidification matrices to prevent subsurface contamination before final treatment or disposal. Tank systems dominate capital allocation among containment methods due to their reusability across multi-well programs, while vacuum extraction leads handling technique growth by reducing worker exposure and accelerating rig-to-disposal transfer cycles. Solidification matrices command premium pricing for remote locations lacking pipeline infrastructure, and automated handling systems are displacing manual collection in high-dayrate environments where non-productive time carries steep penalties.
EPA Subtitle D standards and OSHA workplace exposure limits shape equipment specifications and operating protocols across US onshore operations, while Texas Railroad Commission pit closure rules and North Dakota Industrial Commission containment mandates drive state-level procurement patterns. The EU F-Gas Regulation and REACH chemical restrictions influence offshore waste handling standards for operators active in the North Sea. Stakeholders must weigh capital intensity of automated handling against regulatory compliance thresholds when configuring service portfolios for upcoming drilling cycles.
Market Dynamics
Multi-well pad drilling in the Permian Basin is compressing rig-to-disposal transfer cycles and forcing real-time containment system upgrades across North American land operations.
Growth Catalysts
- EPA Subtitle D Solid Waste Rules:Federal disposal standards mandate engineered containment systems for drilling cuttings, compelling onshore operators to replace open pits with steel-framed tank systems.
- Automated Cuttings Conveyance:Vacuum extraction technology reduces worker exposure and accelerates waste transfer, driving capital allocation toward integrated handling workflows.
- North Dakota Industrial Commission Mandates:State-level pit closure rules concentrate demand for polymer-sealed drums and solidification matrices in the Bakken formation.
Market Restraints
- Steel Input Volatility:Fluctuations in hot-rolled coil pricing compress margins for tank system manufacturers serving high-volume drilling programs.
- Remote Location Logistics:Solidification matrix deployment faces transport cost barriers in areas lacking pipeline infrastructure, limiting adoption outside established basins.
- OSHA Workplace Exposure Limits:Respirable silica standards impose equipment retrofit costs on manual collection operations, creating compliance friction for smaller contractors.
Strategic Opportunities
- Texas Railroad Commission Pit Closure Timeline:Accelerated remediation deadlines create replacement demand for closed-loop systems across legacy well sites in the Eagle Ford.
- Digital Waste Tracking Convergence:Integration of IoT sensors with containment hardware enables real-time monitoring services that extend contract duration with exploration firms.
- EU F-Gas Regulation Alignment:North Sea offshore operators require REACH-compliant handling systems, opening export channels for US containment technology providers.
Industry Challenges
- Automated System Integration:Legacy rig infrastructure requires costly retrofitting to accommodate pneumatic cuttings transfer, delaying deployment timelines.
- Specialized Technician Scarcity:Vacuum extraction maintenance and polymer-sealing operations demand certified personnel that drilling contractors struggle to recruit in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Containment and Handling Drilling Waste Management Market |
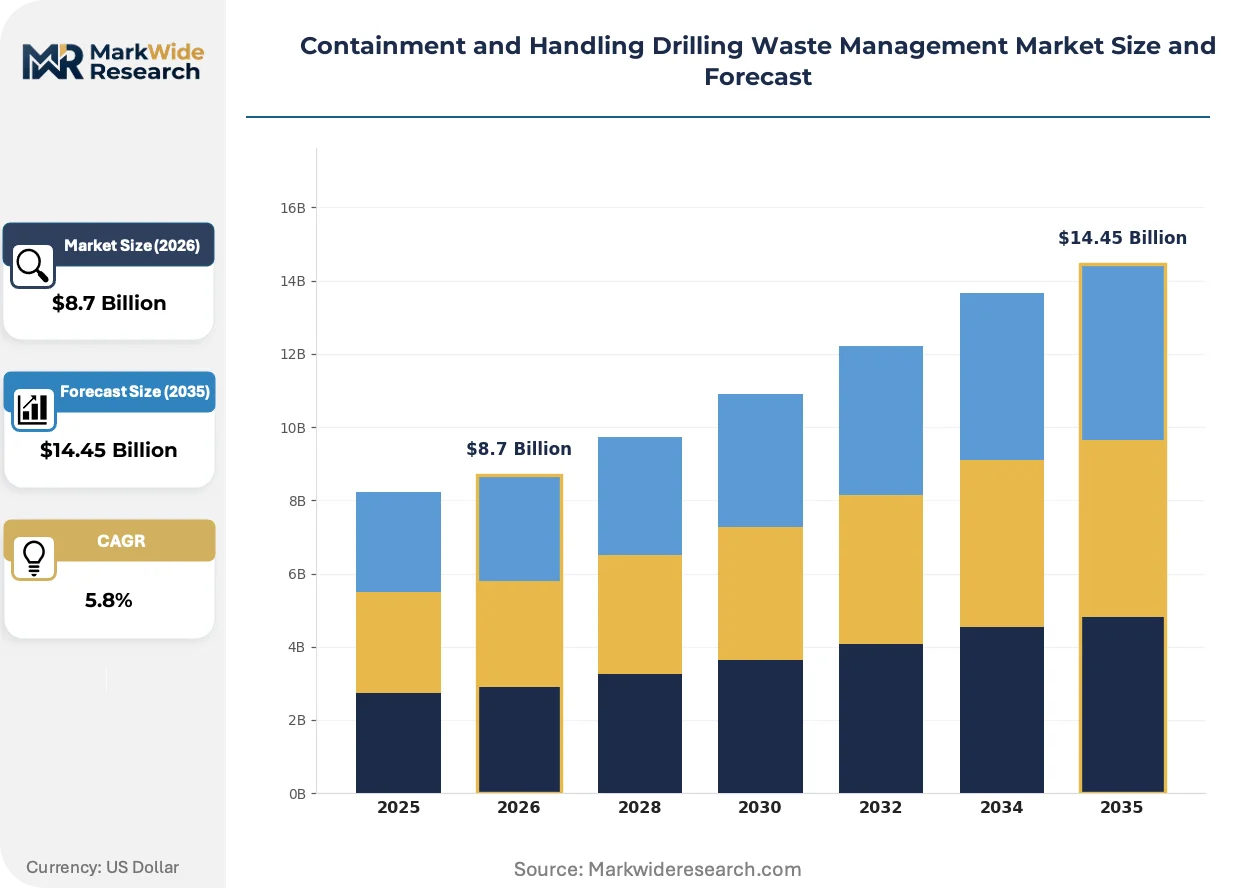
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Containment Method: Drum Storage, Tank Systems, Solidification, Filtration Units, Absorbent Pads Handling Technique: Manual Collection, Mechanical Conveyance, Pneumatic Transfer, Automated Systems, Vacuum Extraction Drilling Waste Type: Cuttings, Mud, Fluids, Barite, Polymers End User Segment: Exploration Firms, Rig Operators, Environmental Contractors, Waste Disposal Companies |
| Companies Covered | Baker Hughes, Halliburton, Schlumberger, Weatherford International, TWMA, Secure Energy Services, GN Solids Control, National Oilwell Varco, Augean, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Containment and Handling Drilling Waste Management Market Trends and Innovations
Containment technology is pivoting toward electrification and digital integration as drilling intensity rises and regulatory scrutiny tightens across major basins.
Electrified vacuum extraction systems are eliminating diesel-powered pneumatic units at multi-well pads. Permian Basin operators are deploying these systems to cut fuel logistics and reduce emissions exposure. This shift is electrifying rig-to-disposal workflows while compressing maintenance intervals and extending equipment lifespan in high-temperature drilling environments.
REACH chemical restrictions are reshaping offshore waste handling specifications for North Sea operations. ECHA substance classifications now limit certain polymer formulations in containment matrices, forcing suppliers to reformulate sealing compounds. Drillship operators in Norwegian and UK waters are accelerating procurement of compliant alternatives ahead of enforcement deadlines.
Integrated service bundling is displacing standalone equipment rentals among onshore drilling contractors. Baker Hughes and Halliburton are anchoring long-term rig contracts through containment-to-treatment workflows that combine tank systems with automated conveyance. This consolidation concentrates procurement authority with integrated service providers in Texas and North Dakota land markets.
Containment and Handling Drilling Waste Management Market Segmentation
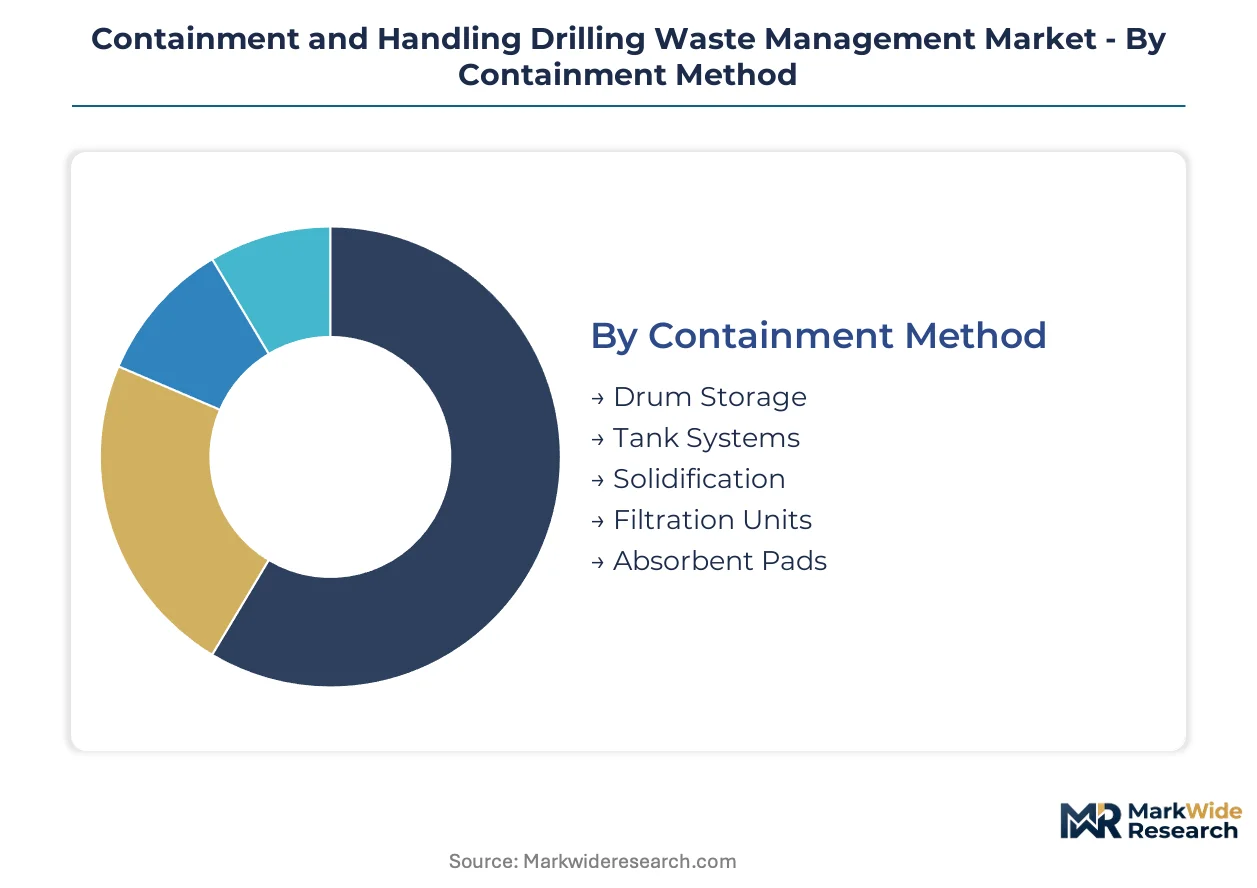
Segmentation in containment and handling drilling waste management reveals how procurement authority consolidates around integrated service providers versus standalone equipment vendors. Equipment specification varies sharply by drilling intensity, regulatory jurisdiction, and waste stream chemistry.
Containment Method:
Tank systems and solidification matrices anchor standalone deployments, while filtration units embed within continuous treatment workflows.
- Tank Systems:Steel-framed modular tanks with polymer liners withstand temperatures exceeding 150°C and pressures above 10,000 psi. Demand clusters in Texas Permian Basin multi-well pads where reusability across drilling programs justifies capital outlay against rental alternatives.
- Solidification:Cementitious and polymer matrices immobilize liquid waste for transport to remote disposal facilities. Bakken formation operators in North Dakota deploy these where pipeline infrastructure remains absent, though transport costs constrain economics beyond 150-mile radii.
- Drum Storage:Polymer-sealed drums serve short-duration projects and legacy site remediation.
- Filtration Units:Centrifuge and press systems integrate with closed-loop mud recovery operations.
- Absorbent Pads:Cellulose and synthetic media capture surface spills during rig maintenance.
Volume placements concentrate in tank systems; the faster expansion belongs to solidification.
Handling Technique:
Cost tiering separates premium automated systems from manual collection, with pneumatic transfer occupying the mid-market efficiency band.
- Vacuum Extraction:Diesel and electrified pneumatic systems eliminate worker exposure to respirable silica while accelerating rig-to-disposal transfer cycles. Permian Basin contractors are electrifying these units to cut fuel logistics and extend maintenance intervals in high-temperature environments.
- Automated Systems:Conveyor and robotic handling reduce non-productive time penalties in high-dayrate drilling contracts. North Dakota rig operators specify these for 24-hour pad drilling where manual collection bottlenecks threaten spud-to-spud schedules.
- Pneumatic Transfer:Compressed-air conveying bridges mid-scale operations seeking throughput gains without full automation.
- Mechanical Conveyance:Auger and belt systems serve established land rigs with predictable waste volumes.
- Manual Collection:Shovel-and-barrel methods persist in low-frequency workover operations and marginal well maintenance.
Capital deployment tilts toward vacuum extraction; steepest expansion trajectory runs through automated systems.
Drilling Waste Type:
Application intensity varies by waste chemistry, with reactive cuttings demanding immediate containment versus inert barite permitting extended storage.
- Cuttings:Rock fragments contaminated with drilling fluids require temperature-resistant containment due to exothermic reactions. Eagle Ford shale operators in Texas prioritize real-time handling to meet Railroad Commission pit closure deadlines.
- Mud:Synthetic and oil-based drilling fluids command closed-loop recovery systems for reuse economics. Gulf Coast offshore platforms specify tank-based containment with integrated filtration for discharge compliance.
- Fluids:Produced water and completion fluids drive demand for corrosion-resistant drum systems.
- Barite:Weighting agent recovery concentrates in high-density drilling programs.
- Polymers:Viscosifier waste faces REACH-compliant handling constraints in North Sea operations.
Cuttings generate the heaviest containment load; polymers are climbing fastest on regulatory compliance spend.
End User Segment:
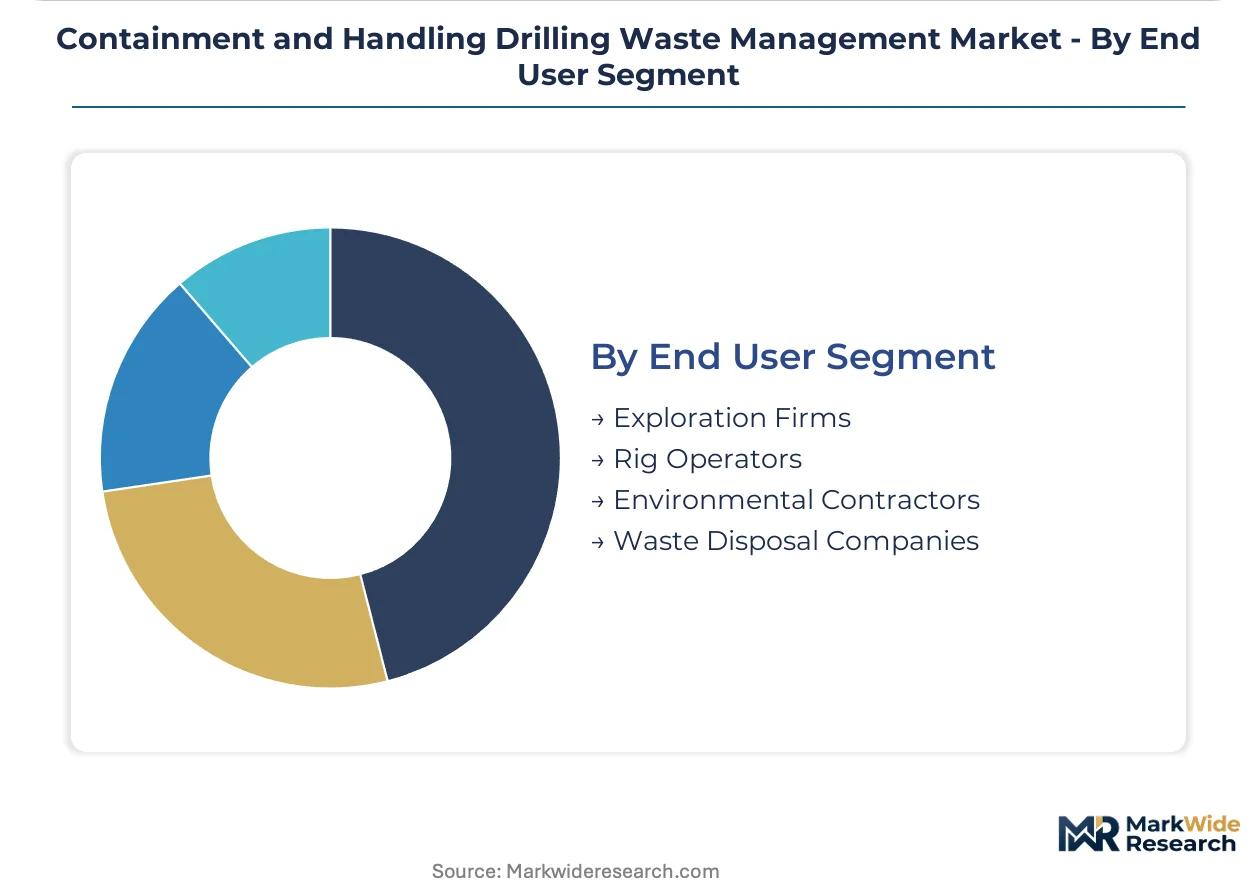
Customer type determines contract structure, with exploration firms bundling services and waste disposal companies purchasing discrete equipment.
- Rig Operators:Drilling contractors specify integrated containment-to-treatment workflows to anchor long-term pad contracts. Texas and North Dakota land markets show procurement authority consolidating with operators capable of real-time waste tracking.
- Environmental Contractors:Remediation specialists acquire solidification matrices and vacuum extraction for legacy site closure. EPA Subtitle D enforcement drives replacement demand as open pit remediation accelerates.
- Exploration Firms:Oil and gas producers outsource full waste management to integrated service providers.
- Waste Disposal Companies:Midstream processors invest in tank systems for temporary storage arbitrage.
Rig operators command the largest equipment volume; environmental contractors are expanding most quickly on regulatory remediation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of engineered containment systems while Norway and China expand manufacturing capacity for high-pressure tank exports. Production clusters concentrate near steel fabrication centers in Houston and Shanghai, with final assembly shifting toward basin-proximate yards in Midland and Daqing to cut logistics costs.
United States
Permian Basin multi-well pad drilling compresses rig-to-disposal transfer cycles and forces real-time containment upgrades. EPA Subtitle D solid waste rules mandate engineered steel-framed tank systems to replace open pits. Eagle Ford operators in South Texas face accelerated Railroad Commission pit closure deadlines driving replacement demand.
Norway
North Sea drillship operators require REACH-compliant handling systems ahead of ECHA enforcement deadlines. ECHA substance classifications limit certain polymer formulations in containment matrices. Stavanger-based offshore contractors are accelerating procurement of reformulated sealing compounds for high-temperature drilling environments.
China
Sinopec and CNPC drilling programs in Sichuan shale basins scale closed-loop containment for high-pressure gas wells. MEE environmental standards tighten disposal protocols for oil-based mud cuttings. Daqing oilfield services cluster is expanding polymer-sealed drum manufacturing for remote western basin deployment.
Canada
Alberta oil sands thermal drilling generates concentrated waste streams requiring temperature-resistant tank systems. Alberta Energy Regulator directives mandate engineered containment for steam-assisted gravity drainage cuttings. Calgary-based environmental contractors are bundling vacuum extraction with solidification services for legacy site remediation.
Saudi Arabia
Aramco unconventional gas drilling in Jafurah Basin is importing high-capacity tank systems for multi-well pad programs. The country's national environmental regulator is aligning disposal standards with EPA Subtitle D frameworks. Dammam industrial zone fabricators are licensing steel-framed modular tank designs from US engineering firms.
Containment and Handling Drilling Waste Management Market Competitive Landscape
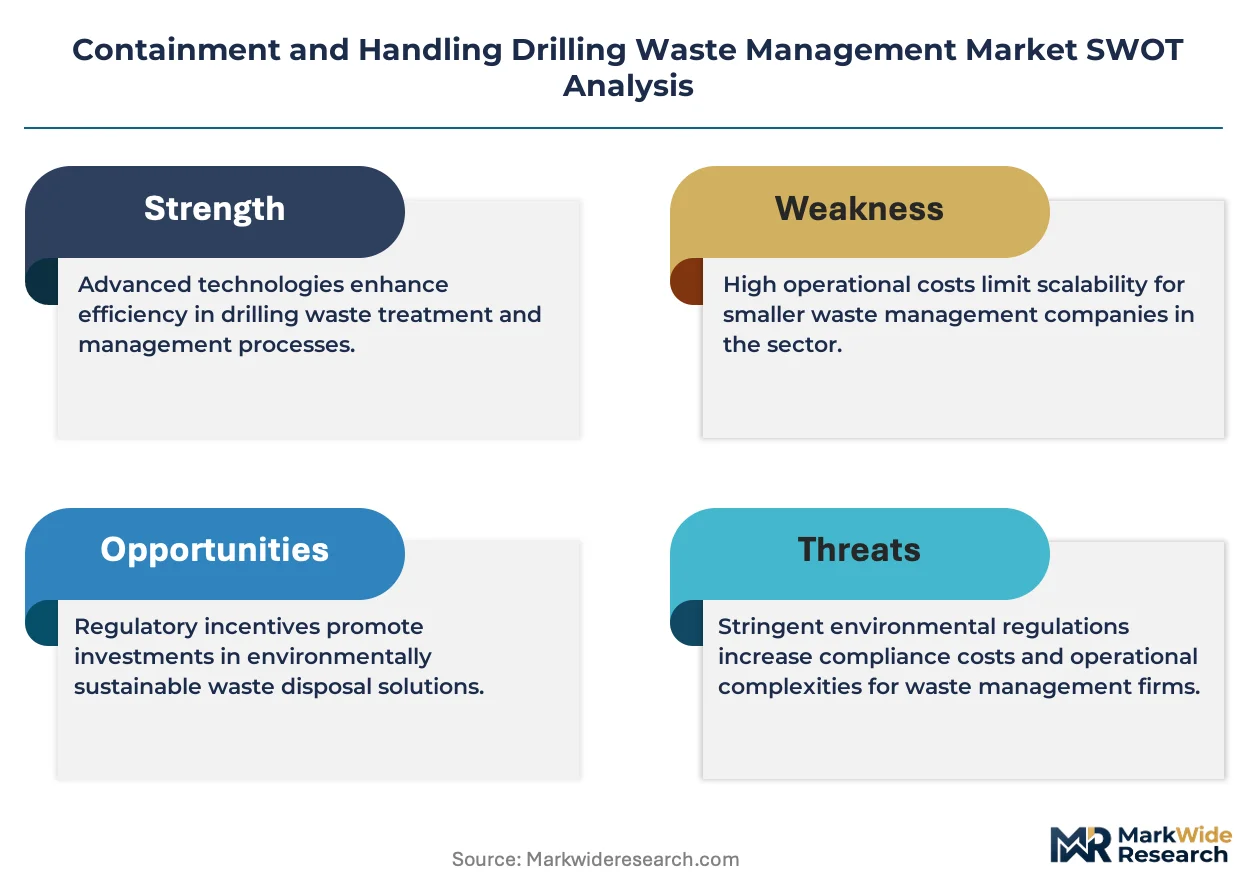
Diversified conglomerates compete with focused pure-play specialists across the containment and handling drilling waste management market. The vendor base shows moderate concentration with three distinct strategic archetypes: integrated oilfield service providers bundling containment-to-treatment workflows, standalone equipment manufacturers supplying modular tank systems, and environmental contractors specializing in legacy site remediation. Competitive moves center on strategic partnerships for technology licensing and geographic expansion into high-growth shale basins.
Within the integrated service provider tier, Baker Hughes, Halliburton, and Schlumberner exemplify the bundling archetype that anchors long-term rig contracts through combined hardware and digital tracking services. These Houston-based corporations occupy positions where procurement authority concentrates among operators seeking single-source accountability for waste compliance. Their market presence reflects the broader industry shift toward outcome-based contracting that transfers regulatory risk from exploration firms to service providers.
| Leading Market Players |
|---|
| Baker Hughes |
| Halliburton |
| Schlumberger |
| Weatherford International |
| TWMA |
| Secure Energy Services |
| GN Solids Control |
| National Oilwell Varco |
| Augean |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between EPA Subtitle D-compliant steel-framed tank systems and non-compliant legacy equipment manifests in pricing premiums exceeding standard commodity hardware while concentrating procurement authority with integrated service providers capable of underwriting regulatory liability. This divergence reshapes supplier economics across North American land drilling markets.
Pricing Analysis
Margin tightening in automated handling equipment reflects steel input volatility and electrification retrofit costs compressing manufacturer returns. Three-tier pricing structure across premium automated systems, mid-market pneumatic units, and economy manual collection segments anchors contract structures. Cost-down pressure accelerates in vacuum extraction systems as hot-rolled coil pricing fluctuates. Environmental contractors show highest price sensitivity due to project-based bidding constraints, while integrated rig operators prioritize compliance assurance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from major drilling contractors mandate qualified suppliers across both Houston steel fabrication clusters and Shanghai manufacturing centers for tank system components. Production draws from hot-rolled coil mills in the US Gulf Coast and Chinese port cities, with polymer liner materials resting on petrochemical feedstock channels. Single-source vulnerability concentrates in specialized sealing compound formulations facing REACH compliance deadlines. Distribution runs through basin-proximate assembly yards in Midland and Williston to compress logistics costs for multi-well pad programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containment and handling drilling waste management functions as a cost-of-compliance market where EPA Subtitle D solid waste rules erect regulatory moats favoring incumbent service providers with established compliance infrastructure and capital reserves.
For Market Incumbents: Lock in long-term rig contracts through bundled containment-to-treatment workflows that transfer regulatory liability from exploration firms. Deepen backward integration into steel-framed tank manufacturing to defend margins against hot-rolled coil price volatility. Prioritize electrified vacuum extraction R&D to outpace OSHA silica exposure standard tightening. For New Entrants and Emerging Players: Enter via environmental contractor channels servicing EPA Subtitle D remediation timelines for legacy open pit closure. Target Bakken formation solidification matrix deployment where pipeline infrastructure gaps create white-space demand. Pursue REACH-compliant polymer reformulation partnerships for North Sea export qualification. For Investors and Strategic Acquirers: Re-rating potential sits with automated handling specialists given electrification mandates and labor scarcity compressing deployment timelines for manual collection alternatives. Long-term viability favors platforms with digital waste tracking capabilities extending contract duration. Watch Texas Railroad Commission enforcement acceleration as inflection signal for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification of Vacuum Extraction Systems | Permian Basin operators deploy electrified units to eliminate diesel logistics and extend maintenance intervals in high-temperature drilling. |
| REACH-Compliant Polymer Reformulation | North Sea drillship procurement accelerates ahead of ECHA enforcement deadlines limiting legacy sealing compounds. |
| Integrated Containment-to-Treatment Bundling | Baker Hughes and Halliburton anchor multi-year rig contracts through combined hardware and digital tracking services. |
| Basin-Proximate Assembly Expansion | Final tank system assembly shifts to Midland and Williston yards cutting transport costs for multi-well pad programs. |
| Digital Waste Tracking Platform Deployment | Schlumberger extends service stickiness with exploration firms through IoT sensor integration with containment hardware. |
Research Methodology
Document review covered EPA enforcement records, state regulatory filings from the Texas Railroad Commission and North Dakota Industrial Commission, and equipment procurement databases, complemented by interviews with drilling contractors, environmental compliance officers, and waste disposal facility operators. Secondary validation drew from SEC 10-K disclosures of integrated service providers, steel industry trade data, and REACH substance classification updates. Bottom-up equipment shipment analysis triangulated against top-down drilling activity metrics.
Segment-level demand outputs across containment method, handling technique, waste type, and end-user categories informed the analytical framework over the projection horizon. CAGRs derived from equipment replacement cycles, regulatory deadline schedules, and drilling intensity projections by basin. Forecast inputs incorporated steel price volatility indices and electrification adoption curves for pneumatic system replacements.
Revisions become necessary when EPA enforcement acceleration, state-level pit closure timeline extensions, or breakthrough solidification chemistry materializes. Deviation in steel input pricing or REACH substance reclassification would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Sucker Rod Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
Asia-Pacific Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market