
 DRAM Market | 2026-2036
DRAM Market Size, Share, and Industry Trends Forecast 2026-2036
DRAM Market Intelligence
The premium DDR5 and commodity DDR4 tiers is rebalancing around divergent margin structures and capacity allocation priorities. Samsung Electronics dominates advanced node wafer starts for high-bandwidth server modules. SK hynix sustains leadership in HBM stack technology for AI accelerators. Micron Technology anchors US-based supply through its Idaho and New York fabrication complexes.
Dynamic random-access memory (DRAM) stores data as electrical charge in capacitors paired with access transistors on silicon wafers, typically fabricated at process nodes below 20nm to maximize bit density per die; its primary purpose is to provide volatile working memory for processors requiring high-speed data retrieval. DDR5 modules command the fastest expansion trajectory as server OEMs refresh platforms for bandwidth-intensive workloads. LPDDR5 tracks mobile device form-factor constraints toward lower-voltage operation. GDDR6 occupies a narrower but profitable niche serving discrete graphics and AI inference cards.
US EPA energy-efficiency standards and South Korea's K-CHIP Act shape fab power consumption targets and subsidy eligibility for new greenfield capacity. REACH chemical restrictions in Europe limit certain etching precursor formulations used in EUV lithography patterning. China's SAMR enforces domestic procurement preferences for state-affiliated data center operators. Stakeholders must monitor how export control classifications on deposition and etching equipment redirect capital expenditure flows across Korean, Taiwanese, and US manufacturing corridors.
Market Dynamics
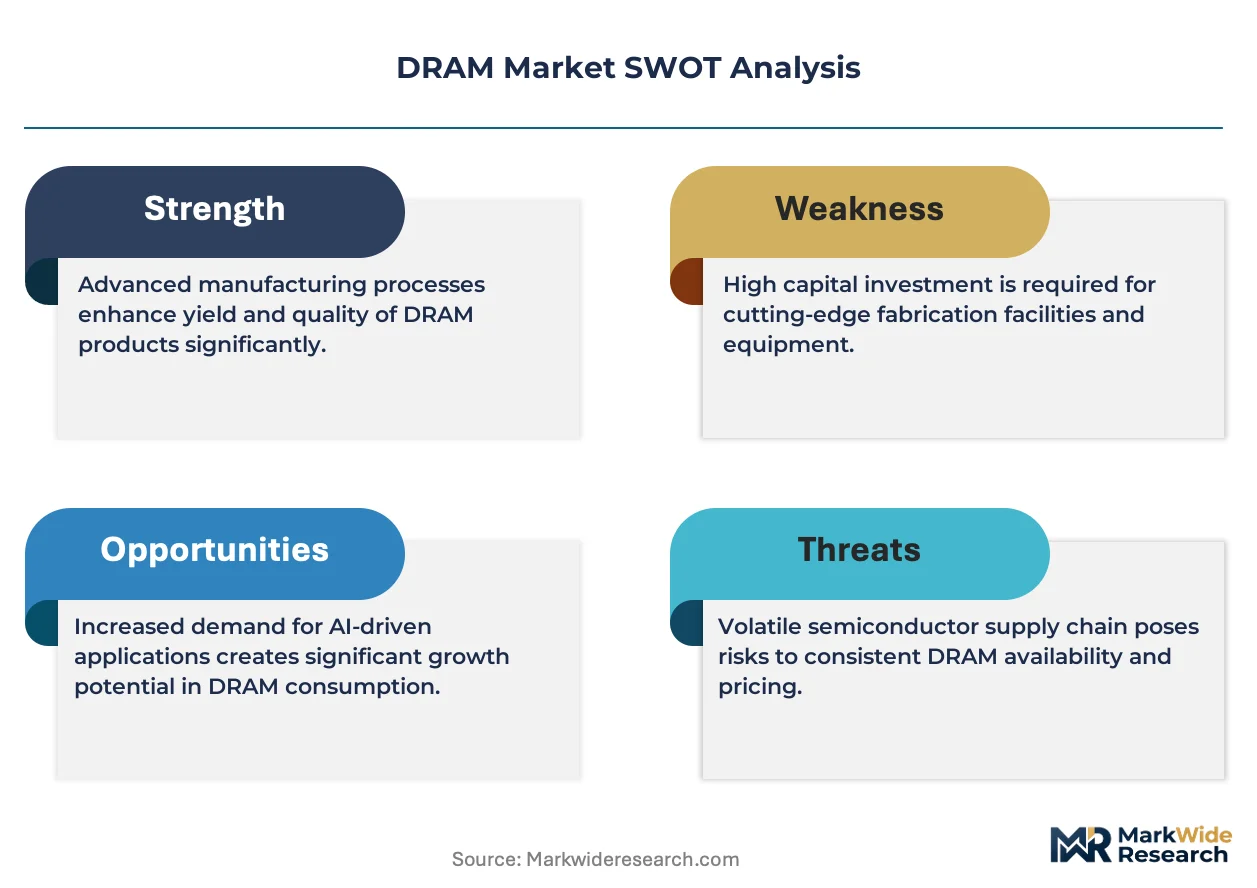
AI training clusters are forcing a fundamental reallocation of wafer capacity toward high-bandwidth memory architectures, compressing commodity DRAM supply and redrawing competitive boundaries between process-node leaders.
Growth Catalysts
- China's MIIT localization mandates:Domestic procurement preferences for state-affiliated data center operators are redirecting captive foundry investment toward DRAM self-sufficiency targets.
- Server platform refresh cycles:Cloud service providers are accelerating DDR5 adoption as bandwidth-intensive AI workloads demand higher data throughput per socket.
- HBM stack technology maturation:Advanced packaging techniques enabling vertical memory integration are unlocking new performance tiers for accelerator cards.
Market Restraints
- Extreme ultraviolet lithography equipment constraints:Deposition and etching tool availability bottlenecks are extending advanced node ramp timelines.
- Fluorinated gas supply volatility:REACH chemical restrictions in Europe are limiting etching precursor formulations critical to sub-20nm patterning.
- Power consumption escalation:US EPA energy-efficiency standards are tightening fab operating cost structures at leading-edge facilities.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Subsidy eligibility for semiconductor assembly and test operations is attracting module packaging investment.
- Automotive edge computing architectures:LPDDR5 adoption in advanced driver-assistance systems is creating new qualification pathways outside traditional server channels.
- South Korea's K-CHIP Act subsidy framework:Greenfield capacity incentives are enabling domestic expansion of HBM-specific cleanroom infrastructure.
Industry Challenges
- EUV technician scarcity:Specialized lithography maintenance and calibration expertise is concentrating at a handful of fabrication complexes.
- Legacy DDR4 inventory absorption:Module manufacturers face margin compression as server OEMs accelerate platform transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DRAM Market |
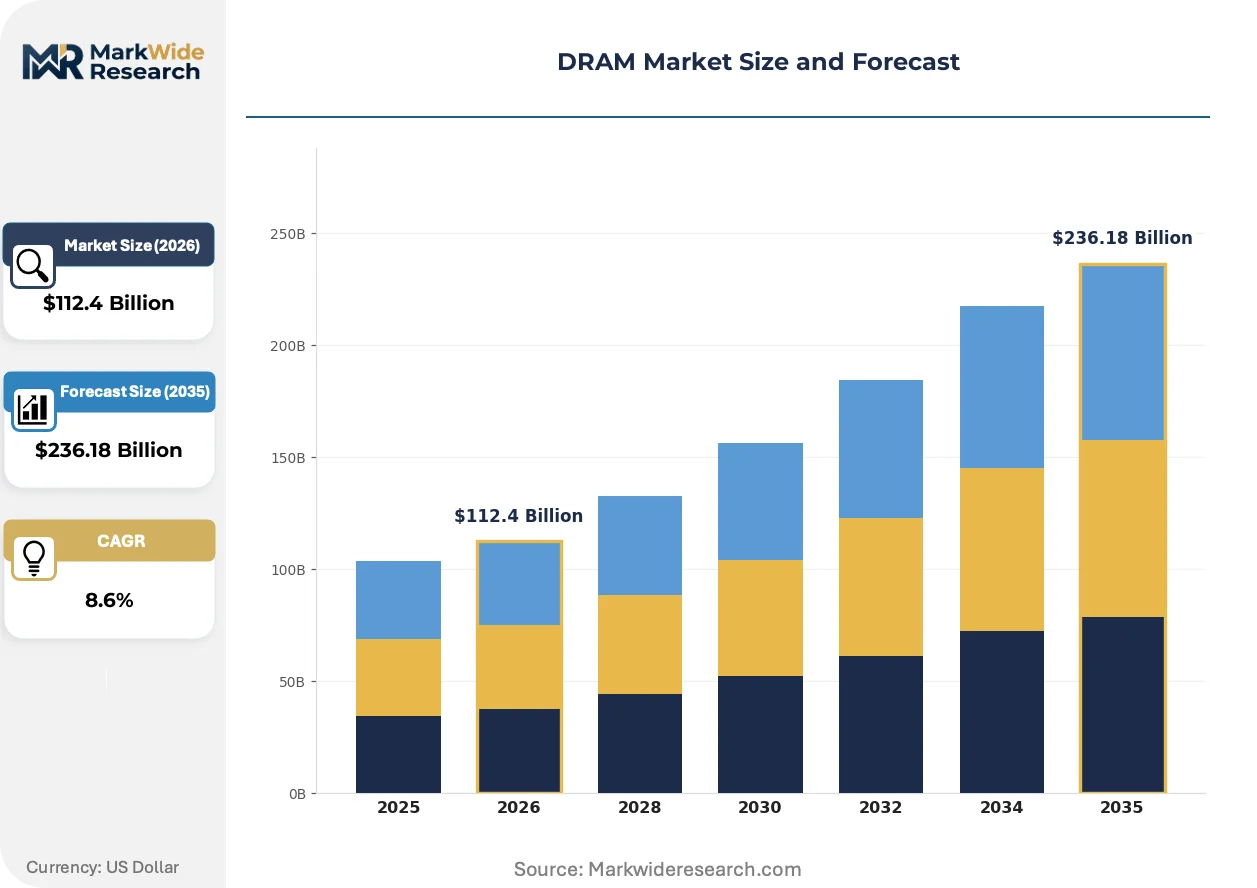
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $236.18 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDR4, DDR5, LPDDR4, LPDDR5, GDDR6 Technology: Synchronous DRAM, Fast Page Mode DRAM, Extended Data Out DRAM, Rambus DRAM, Multibank DRAM Application: Personal Computing, Mobile Devices, Servers, Gaming Consoles, Networking Equipment End User: Original Design Manufacturers, Cloud Service Providers, Data Centers, Telecommunications Firms, Consumer Electronics Brands |
| Companies Covered | ChangXin Memory Technologies, Winbond Electronics, SK hynix, Powerchip Semiconductor Manufacturing, Infineon Technologies, Samsung Electronics, Nanya Technology, UniBetter, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DRAM Market Strategic Shifts & Innovations
Memory architecture specialization is fragmenting the traditional commodity DRAM model, with divergent technical requirements across AI training, inference, and edge deployment creating distinct product-development tracks.
DDR5 interface technology is overtaking DDR4 in server motherboard designs by doubling channel bandwidth and improving power management through on-die voltage regulation. Hyperscale data center operators are standardizing DDR5-4800 and DDR5-5600 speeds for new rack deployments. This transition is compressing DDR4 module pricing and forcing suppliers to accelerate last-time-buy commitments for legacy platforms.
South Korea's K-CHIP Act is channeling subsidy eligibility toward fabs meeting aggressive power consumption targets and domestic content thresholds. Equipment procurement contracts now incorporate energy-efficiency clauses as binding technical specifications. Memory suppliers with existing Korean fabrication footprints are capturing preferential treatment for advanced node expansion relative to greenfield entrants.
Cloud service provider procurement is consolidating around direct supplier relationships, bypassing traditional distribution channels for high-volume server memory contracts. Module vendors are establishing dedicated technical account teams for hyperscale buyers. This disintermediation is most visible in North American and European markets where AWS, Azure, and Google Cloud dominate infrastructure deployment.
DRAM Market Segmentation
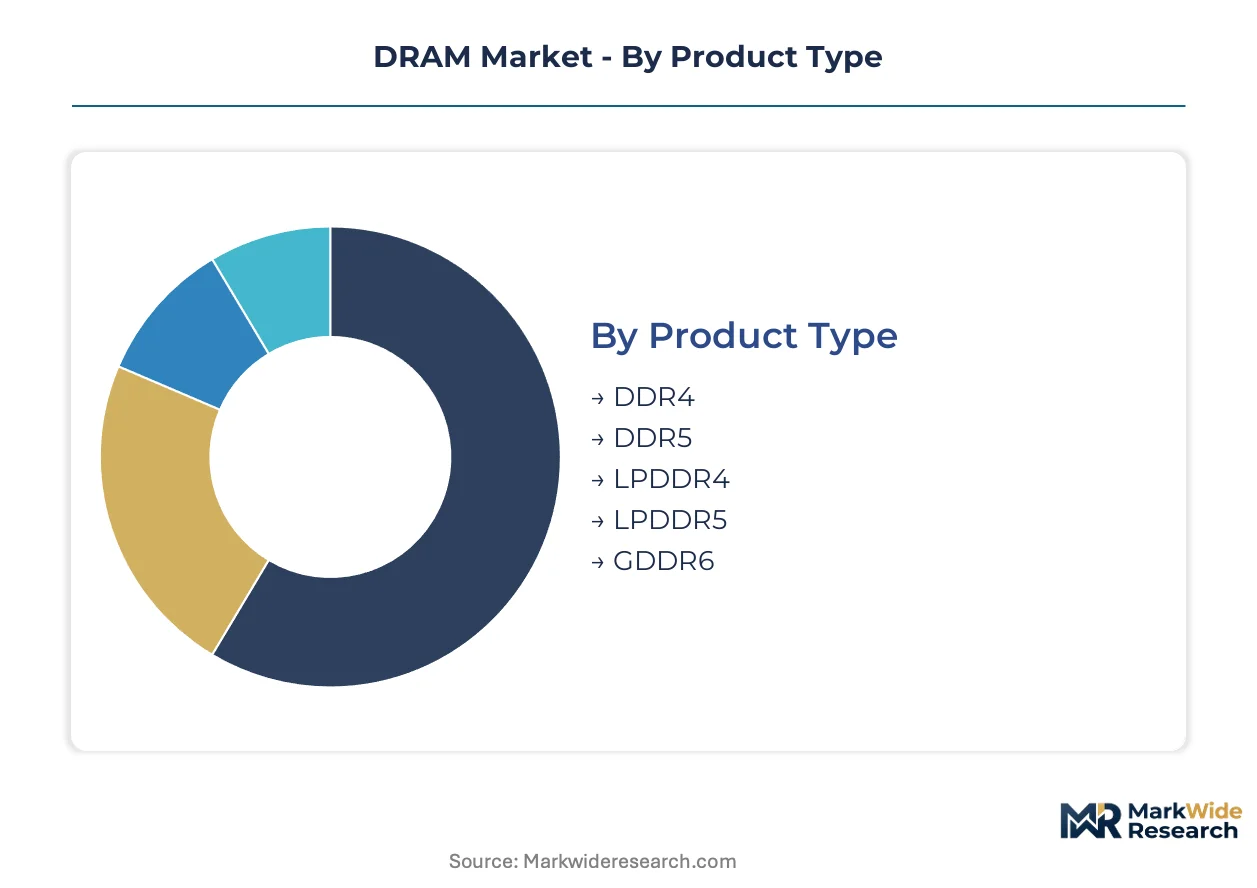
DRAM segmentation reflects divergent technical requirements across computing environments. Voltage specifications, bandwidth architectures, and thermal envelopes create distinct procurement criteria for server farms versus mobile handsets versus graphics accelerators.
Product Type:
Cost tier separates premium bandwidth modules from commodity density products.
- DDR5:Operating at 1.1V with on-die power management, DDR5 doubles channel bandwidth over prior generations. Hyperscale data centers in South Korea and the United States are standardizing DDR5-4800 and DDR5-5600 speeds for AI training clusters, though module premiums compress server OEM margins during platform transitions.
- LPDDR5:Low-voltage operation at 0.5V enables thinner mobile form factors without thermal throttling. Samsung Electronics and SK hynix are prioritizing LPDDR5 wafer allocation for flagship smartphone releases, where battery life constraints override raw bandwidth requirements.
- DDR4:Mature 1.2V interface dominates legacy server refresh cycles and enterprise desktop fleets. Inventory absorption pressures are forcing module manufacturers into last-time-buy negotiations as DDR5 penetration accelerates.
- LPDDR4:Previous-generation mobile standard retains volume in mid-tier handsets and automotive infotainment systems where cost sensitivity exceeds performance demands.
- GDDR6:High-bandwidth graphics memory serves discrete AI inference cards and gaming GPUs. Narrower addressable market sustains pricing premiums relative to commodity DRAM tiers.
Volume sits with DDR4; growth tilts toward DDR5.
Technology:
Maturity curves separate legacy asynchronous architectures from synchronous standards governing modern fabrication.
- Synchronous DRAM:Clock-aligned data transfer enables pipelined memory operations matching processor bus speeds. All contemporary DDR and LPDDR variants derive from this architecture, which commands virtually all wafer capacity at sub-20nm nodes.
- Fast Page Mode DRAM:Page-mode access pattern predates synchronous standards. Retained only in industrial control systems and legacy telecommunications equipment requiring long-term supply continuity.
- Extended Data Out DRAM:Overlapped read cycles provided marginal latency improvements over earlier asynchronous designs. Now confined to replacement markets for obsolete computing hardware.
- Rambus DRAM:Proprietary high-speed interface achieved limited adoption in early 2000s gaming consoles. Patent licensing structures constrain contemporary deployment outside niche embedded applications.
- Multibank DRAM:Interleaved memory banks enable concurrent access patterns. Incorporated into specialized networking silicon rather than general-purpose computing modules.
Production concentrates on Synchronous DRAM; obsolescence risk shadows legacy asynchronous categories.
Application:
Customer scale separates hyperscale procurement from fragmented consumer purchasing.
- Servers:Registered DIMM and load-reduced DIMM configurations support multi-terabyte memory pools per rack. Cloud service providers negotiate direct supplier relationships bypassing distribution, compressing module vendor margins while securing volume commitments.
- Mobile Devices:Package-on-package stacking integrates DRAM directly atop application processors. Form-factor constraints drive LPDDR5 adoption as handset OEMs compete on millimeter thickness specifications.
- Personal Computing:Desktop and notebook segments face demand erosion as enterprise fleets extend replacement cycles. DDR4 inventory overhang persists in channel distribution despite DDR5 motherboard proliferation.
- Gaming Consoles:Unified memory architectures pool DRAM for CPU and GPU access. Console refresh cycles create lumpy demand patterns distinct from steady-state server procurement.
- Networking Equipment:Buffer memory and lookup table storage require deterministic latency characteristics. Telecom infrastructure investment cycles in South Korea and Japan shape regional demand concentration.
Revenue pools deepest in Servers; Mobile Devices claim the steepest expansion trajectory.
End User:
Integration depth separates captive semiconductor operations from merchant market purchasing.
- Cloud Service Providers:AWS, Azure, and Google Cloud negotiate multi-year supply agreements directly with Samsung Electronics and SK hynix. Technical account teams co-develop module specifications matching proprietary server designs.
- Data Centers:Colocation and enterprise facilities procure through integrators rather than direct supplier relationships. China's state-affiliated operators face MIIT domestic procurement preferences redirecting sourcing toward captive foundry output.
- Original Design Manufacturers:Foxconn and Quanta aggregate DRAM demand across multiple brand customers. Volume consolidation enables pricing leverage unavailable to individual electronics brands.
- Telecommunications Firms:5G baseband processing and edge computing nodes create specialized memory requirements. South Korean carriers SK Telecom and KT are expanding edge infrastructure deployment.
- Consumer Electronics Brands:Smartphone and tablet OEMs compete for LPDDR5 allocation during flagship launch windows. Supply allocation disputes concentrate around Apple and Samsung Mobile release calendars.
Procurement gravity centers on Cloud Service Providers; regulatory pressure reshapes Data Center sourcing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors advanced DRAM fabrication through Samsung Electronics and SK hynix operations in the Seoul Capital Area, where HBM-specific cleanroom infrastructure is expanding under South Korea's K-CHIP Act subsidy framework.
South Korea
Cloud service providers and AI training clusters are driving DDR5 and HBM procurement from domestic fabs. The K-CHIP Act ties subsidy eligibility to power consumption targets and domestic content thresholds. Pyeongtaek hosts Samsung Electronics' leading-edge DRAM complex where advanced node wafer starts dominate high-bandwidth server module production.
United States
Hyperscale data center operators including AWS, Azure, and Google Cloud negotiate direct supply agreements bypassing traditional distribution channels. EPA energy-efficiency standards tighten fab operating cost structures at leading-edge facilities. Idaho and New York fabrication complexes anchor US-based supply through Micron Technology's domestic manufacturing footprint.
China
State-affiliated data center operators face MIIT domestic procurement preferences redirecting sourcing toward captive foundry output. SAMR enforces domestic content requirements for memory procurement in government-linked infrastructure. ChangXin Memory Technologies represents the primary domestic DRAM fabricator scaling captive production toward self-sufficiency targets.
Taiwan
Original design manufacturers aggregate DRAM demand across multiple brand customers, consolidating volume for pricing leverage. Powerchip Semiconductor Manufacturing operates foundry services serving fabless memory designers. Hsinchu Science Park hosts concentrated back-end packaging and testing operations supporting regional module assembly.
Japan
Automotive edge computing architectures are creating LPDDR5 qualification pathways for advanced driver-assistance systems. METI industrial policy supports semiconductor material and equipment supplier ecosystems. Yokkaichi retains historical memory fabrication clustering though advanced DRAM production has shifted toward Korean and US competitors.
DRAM Market Key Industry Players
Premium-margin players sit above commodity-margin players across bandwidth-density and packaging-complexity dimensions. The vendor base concentrates around three integrated fabricators controlling advanced node capacity, with second-tier specialists occupying legacy and niche segments. Strategic archetypes include: HBM-stack technology leaders, high-volume commodity producers, and automotive/industrial qualification specialists. Dominant competitive moves center on backward integration into advanced packaging and geographic diversification of cleanroom infrastructure to capture subsidy eligibility.
Among Korean-based fabricators, Samsung Electronics and SK hynix occupy positions defining the premium-tier competitive vector, while Micron Technology represents the US-based scale anchor. Samsung Electronics exemplifies the integrated device manufacturer archetype spanning DDR5 server modules and mobile LPDDR5 allocation. SK hynix sits within the high-bandwidth memory specialization tier. Micron Technology anchors the Western Hemisphere supply security position through its Idaho and New York fabrication complexes.
| Leading Market Players |
|---|
| ChangXin Memory Technologies |
| Winbond Electronics |
| SK hynix |
| Powerchip Semiconductor Manufacturing |
| Infineon Technologies |
| Samsung Electronics |
| Nanya Technology |
| UniBetter |
| Micron Technology |
| Others |
Cost & Logistics Intelligence
EUV lithography equipment depreciation feeds through wafer cost structures into module pricing tiers, with South Korean and US fabs passing capital intensity downstream to hyperscale buyers through long-term offtake contracts.
Pricing Analysis
Bandwidth-per-watt throughput anchors value-based pricing for HBM stacks serving AI training clusters. Three-tier pricing structure across premium HBM, standard DDR5, and economy DDR4 levels separates AI accelerator procurement from legacy server refresh cycles. Cost compression in DDR4 modules is intensifying because server OEMs accelerate platform transitions, compressing margins for module manufacturers holding legacy inventory. Cloud service providers exhibit lowest price sensitivity due to direct supplier relationships, while enterprise data centers face procurement budget constraints.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong coordinate hub-and-spoke logistics for module assembly operations serving Asian electronics manufacturing clusters. Wafer supply concentrates in South Korea, the United States, and Taiwan, with advanced node capacity tethered to deposition and etching tool availability from Dutch and Japanese equipment suppliers. Fluorinated gas precursors and silicon wafer substrates represent critical input dependencies. Single-source vulnerability around EUV lithography systems creates chokepoint exposure. Distribution runs through direct supplier agreements with hyperscale cloud operators, bypassing traditional component distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DDR5 interface technology is displacing DDR4 across server platforms, compressing legacy procurement windows and reallocating capital toward high-bandwidth memory architectures.
For Market Incumbents: Hedge against DDR4 inventory obsolescence by accelerating last-time-buy negotiations with enterprise server OEMs. Prioritize backward integration into advanced packaging capabilities for HBM stack production, as SK hynix's technology leadership threatens margin capture in AI accelerator memory. Channel control through direct technical account teams with AWS, Azure, and Google Cloud remains essential for volume commitment security. For New Entrants and Emerging Players: Automotive LPDDR5 qualification for advanced driver-assistance systems offers a technology-first wedge into memory markets outside hyperscale cloud channels. India's PLI scheme for electronics manufacturing provides subsidy-eligible assembly and test capacity for module packaging operations. Target tier-two automotive electronics suppliers with specialized thermal and reliability specifications distinct from consumer mobile requirements. For Investors and Strategic Acquirers: K-CHIP Act subsidy disbursement timelines are the leading indicator that South Korean fab expansion will accelerate HBM-specific cleanroom infrastructure investment. Long-term viability favors integrated device manufacturers with captive advanced node capacity and established hyperscale customer relationships. Acquisition target archetype: specialty packaging houses with TSV (through-silicon via) expertise for vertical memory integration. Watch for EUV equipment delivery schedules as the inflection signal for capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| HBM Stack Technology Licensing | SK hynix and Samsung Electronics monetize packaging IP through accelerator card partnerships. |
| Greenfield Fab Expansion | Micron Technology's Idaho and New York complexes anchor US supply security under EPA efficiency standards. |
| Direct Supplier Relationship Formation | Cloud service providers bypass distribution to secure volume commitments from Korean fabricators. |
| Automotive Qualification Pathway Development | LPDDR5 suppliers target advanced driver-assistance system certification outside server channels. |
| Backward Integration into Advanced Packaging | Memory vendors capture margin from TSV and interposer production for AI accelerator modules. |
Research Approach
SEC 10-K filings, hyperscaler capital expenditure disclosures, and SAMR procurement policy documents formed the secondary backbone for supply-side capacity and demand trajectory validation. Primary interviews with DRAM procurement leads at cloud service providers, fab operations directors, and module vendor technical account teams combined with secondary triangulation. Bottom-up wafer start projections and top-down server shipment forecasts were reconciled across the analysis window.
Historical trendline analysis of DDR generational transitions informed adoption curve modeling across the projection horizon. Segmentation dimensions included product type, application environment, end-user integration depth, and regional regulatory cluster. CAGRs were derived from installed base refresh cycles and AI training cluster deployment trajectories. Forecast inputs incorporated EUV equipment delivery schedules and MIIT domestic content threshold enforcement patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control escalation or fluorinated gas supply disruption scenarios. Outputs reflect documented assumptions around subsidy disbursement timelines and hyperscale capex continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Japan Flash Memory Market
Memory Chips
Digital RF Memory Market
Memory Chips
Global Standalone Memory Market
Memory Chips
Automotive Memory Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
Memory Market
Memory Chips
Contactless Memory Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
Memory IC Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
China Flash Memory Market
Memory Chips
In-Memory Computing Market