
 NAND-Based Multi-Chip Packages Market | 2026-2036
NAND-Based Multi-Chip Packages Market Size, Share, and Industry Trends Forecast 2026-2036
NAND-Based Multi-Chip Packages Market Analysis
Software-defined storage tiering is expanding how NAND-based multi-chip packages get monetized beyond hardware shipments. Samsung Electronics leverages its captive foundry capacity to anchor vertically integrated supply chains. SK Hynix sustains aggressive R&D intensity in 3D NAND stacking architectures. Micron Technology competes through advanced packaging specialization at its Taiwan and Singapore manufacturing nodes.
NAND-based multi-chip packages integrate multiple flash memory dies within a single substrate using wire bonding or through-silicon via interconnects, achieving storage densities exceeding 1 terabyte in compact form factors for smartphones and enterprise SSDs. Dual Stack and Quad Stack configurations now dominate volume production as manufacturers push layer counts beyond 200 in 3D NAND architectures. Data Centers represent the fastest-growing end-user segment as hyperscale operators demand higher bandwidth-per-watt ratios from storage-class memory deployments.
REACH restrictions on hazardous substances in electronics packaging shape material selection for European-bound shipments, while the EPA oversees chemical emissions from semiconductor fabrication facilities serving U.S. markets. China's MIIT enforces domestic content requirements through GB standards certification for imported memory modules. Stakeholders must monitor how divergent regulatory timelines for per- and polyfluoroalkyl substance bans affect substrate material qualification cycles.
Market Dynamics
Layer-count escalation in 3D NAND architectures is compressing die footprints while amplifying interconnect complexity, forcing substrate designers to rebalance thermal dissipation against signal integrity in multi-chip configurations.
Growth Catalysts
- Hyperscale data center buildouts:Cloud operators in Northern Virginia, Frankfurt, and Singapore are deploying storage-class memory arrays requiring 200+ layer NAND stacks to optimize bandwidth-per-watt ratios.
- REACH substance restrictions:ECHA's evolving hazardous substance framework is accelerating substrate material innovation for European-bound shipments, creating qualification advantages for early-compliant suppliers.
- Wire bonding to TSV migration:Through-silicon via interconnects are penetrating smartphone storage modules as OEMs demand sub-millimeter package heights for foldable device architectures.
Market Restraints
- Fluorinated gas process dependencies:C4F6 and C4F8 etching chemistries face supply volatility from Korean and Japanese specialty gas producers, compressing foundry margin structures during allocation periods.
- Substrate material concentration:Ajinomoto Build-up Film and Mitsubishi Gas Chemical dominate ABF laminate supply, creating single-source vulnerability for advanced package substrates above 10 layers.
- Retention time limitations:Charge trap flash architectures exhibit accelerated electron leakage above 80°C junction temperatures, constraining automotive under-hood deployment without active cooling.
Strategic Opportunities
- India's PLI scheme for electronics:The Modified Incentive Scheme for semiconductor assembly and testing is attracting NAND packaging investments to Gujarat and Karnataka corridors with 25% capital expenditure offsets.
- Automotive zonal storage architectures:Domain controller consolidation in electric vehicles is creating demand for 512GB-1TB embedded multi-chip packages with AEC-Q100 Grade 2 qualification.
- EU Chips Act capacity subsidies:Dresden and Leuven are receiving preferred funding for advanced packaging lines serving European automotive and industrial automation OEMs seeking supply chain proximity.
Industry Challenges
- Substrate warpage control:Coefficient of thermal expansion mismatches between silicon dies and organic substrates exceed 50ppm/°C in quad-stack configurations, requiring finite element modeling capabilities scarce among mid-tier OSATs.
- MIIT certification timelines:China's GB standards for imported memory modules impose 6-9 month qualification cycles that misalign with quarterly product refresh cadences of smartphone OEMs.
- Copper pillar bumping yield:Fine-pitch interconnects below 40μm pitch exhibit bridging defects during reflow, demanding optical inspection investments that strain capital deployment for packaging specialists below $500M annual revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NAND-Based Multi-Chip Packages Market |
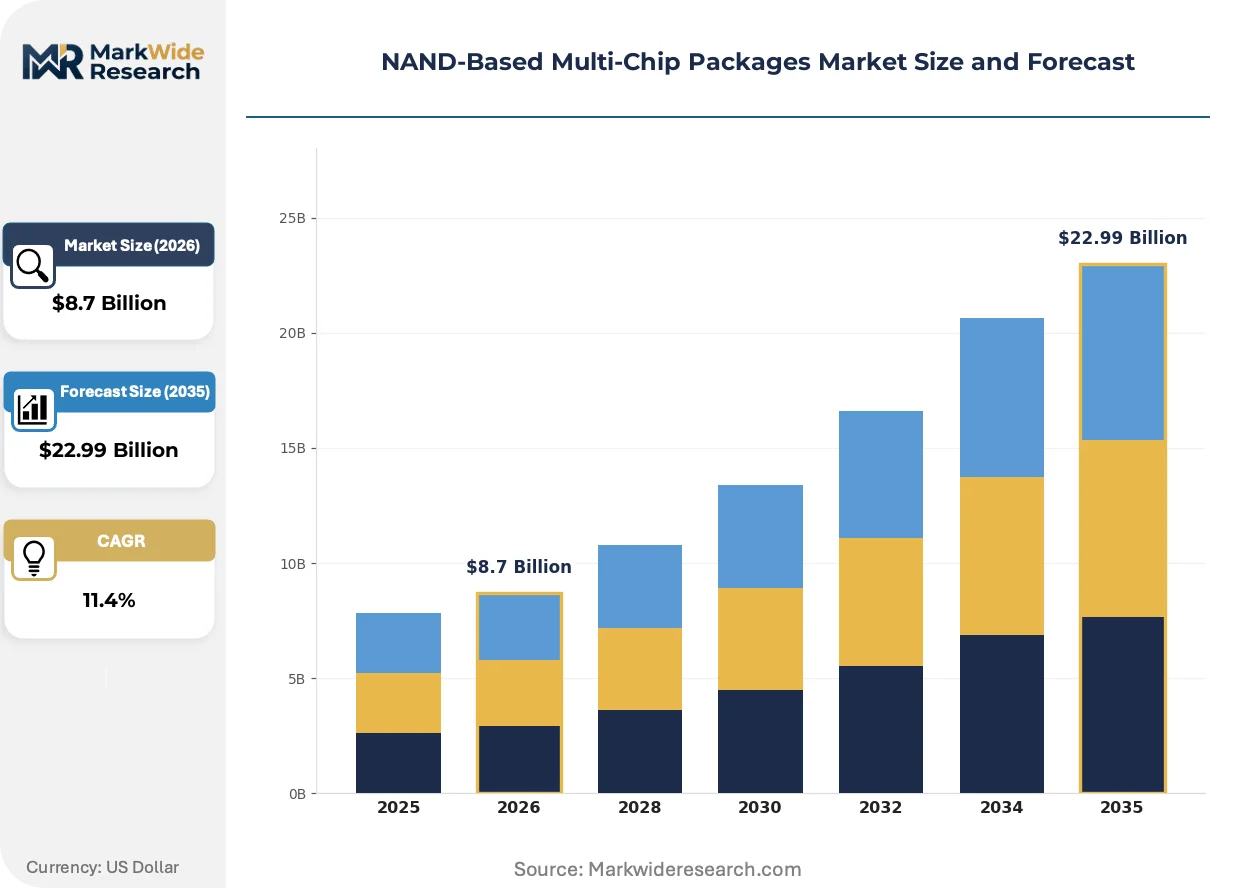
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stack, Dual Stack, Quad Stack, Custom Stack Technology: 3D NAND, 2D NAND, Flash Memory, Hybrid Technology End User: Consumer Electronics, Automotive OEMs, Data Centers, Industrial IoT Packaging Type: Ball Grid Array, Chip-on-Board, Chip-on-Wafer, Others |
| Companies Covered | Western Digital, Infineon Technologies, Samsung Electronics, Winbond Electronics Corporation, Macronix International, Micron Technology, Kioxia Corporation, Kingston Technology, SK Hynix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NAND-Based Multi-Chip Packages Market Emerging Trajectories
Packaging architectures are bifurcating between cost-optimized wire bonding for mainstream smartphones and TSV-based solutions for performance-tier enterprise storage, with hybrid approaches emerging for automotive edge computing nodes.
Hybrid bonding technology is decentralizing the traditional OSAT-foundry boundary by enabling wafer-level die-to-wafer stacking before singulation. Samsung's X-Cube and TSMC's SoIC implementations are penetrating AI accelerator and high-bandwidth memory applications first, with smartphone storage modules following as die thinning reaches 30μm thicknesses. This interconnection method is decentralizing final test and burn-in responsibilities toward wafer-level probing, compressing traditional backend assembly value capture.
ECHA's per- and polyfluoroalkyl substance restriction proposals are forcing substrate laminate suppliers to reformulate fluorinated resin systems used in high-frequency build-up layers. The industrial consequence is extended material qualification cycles overlapping with 3D NAND generation transitions, creating synchronization risk for package designers. European automotive and industrial OEMs are responding by consolidating supplier panels to those with demonstrated PFAS-free roadmaps, privileging Japanese and Taiwanese laminate producers over Korean competitors.
Hyperscale operators are consolidating procurement through direct foundry relationships rather than distributor-mediated component sourcing, compressing channel margins for memory module assemblers. This disintermediation is most visible in North American cloud infrastructure deployments, where Meta, Microsoft, and Amazon negotiate die-level pricing for captive SSD programs. The shift is forcing traditional memory distributors to pivot toward technical services and firmware customization rather than volume-based fulfillment.
NAND-Based Multi-Chip Packages Market Segmentation
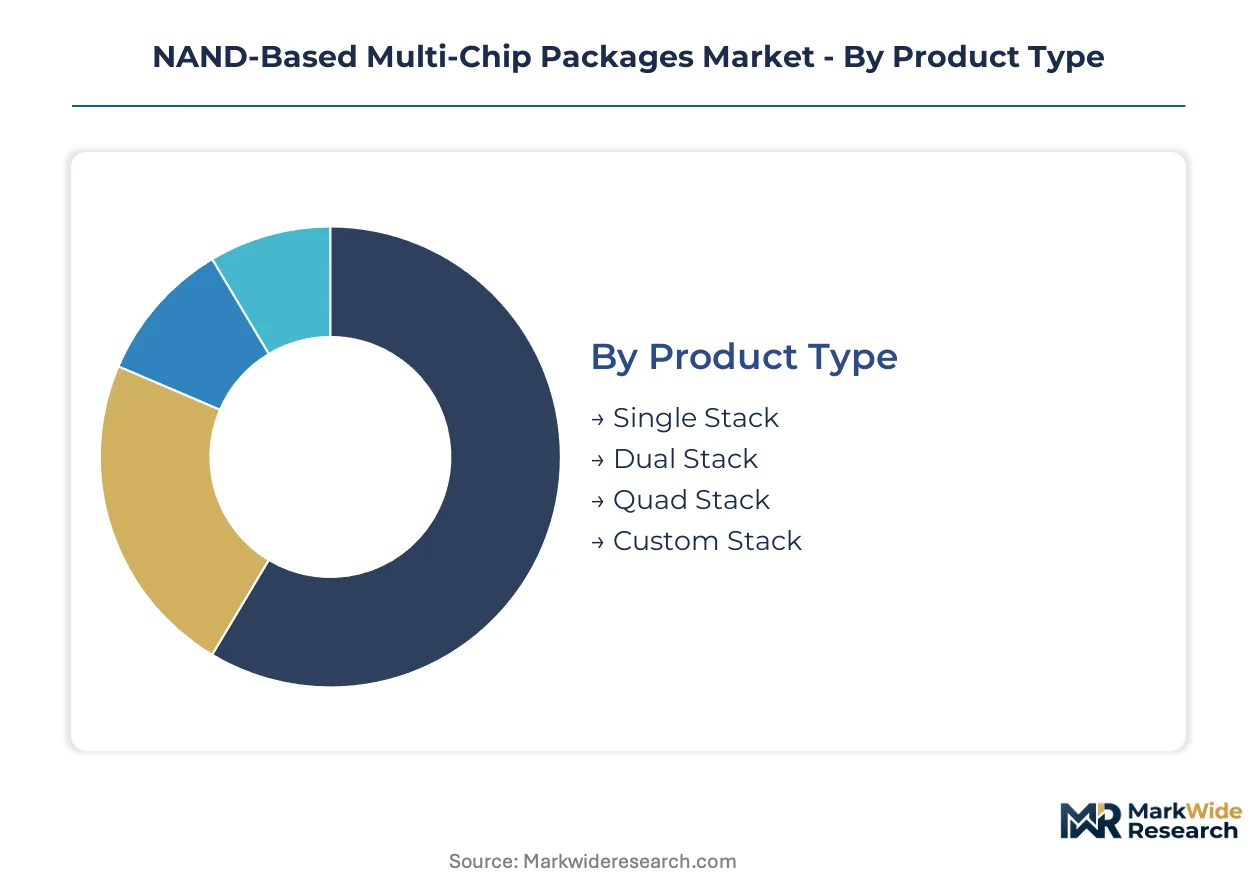
NAND-based multi-chip package configurations vary dramatically in thermal density, interconnect complexity, and integration depth. Segmentation reveals how die-stacking strategies align with end-use power budgets and form-factor constraints.
Product Type:
Single Stack configurations serve discrete storage applications, while Dual and Quad Stack variants embed directly into system-on-chip architectures demanding higher bit density per square millimeter.
- Single Stack:One NAND die mounted on substrate with wire-bond or flip-chip interconnects. Automotive infotainment systems in Germany and Japan specify these for 64-128GB eMMC replacements where thermal headroom is limited.
- Dual Stack:Two thinned dies vertically interconnected through wire bonding or peripheral TSVs. Smartphone OEMs in South Korea and Taiwan dominate procurement for 256-512GB UFS modules in flagship handsets.
- Quad Stack:Four-die configurations achieve 1TB+ capacities in under 1.2mm package heights. Data center SSD controllers and enterprise storage accelerators absorb volumes from Northern Virginia and Frankfurt hyperscale buildouts.
- Custom Stack:Die counts and interconnect topologies tailored to specific thermal or signal-integrity requirements. Niche deployments include aerospace solid-state recorders and medical imaging equipment.
Dual Stack leads volumes today; Quad Stack is gaining share fastest.
Technology:
Process node and cell architecture choices determine cost-per-bit floors and endurance specifications across consumer and enterprise tiers.
- 3D NAND:Vertical charge-trap or floating-gate cells stacked in 176-232 layer configurations. South Korean and Chinese fabs supply the majority of die output for high-density smartphone and SSD applications.
- 2D NAND:Planar cell structures at 1xnm nodes persist in industrial and automotive qualified products where design stability outweighs density requirements.
- Flash Memory:Broad category encompassing NOR and NAND variants for code storage and data retention. Embedded systems in Japanese factory automation equipment specify these for firmware persistence.
- Hybrid Technology:Combinations of SLC cache layers with QLC or TLC main storage arrays. Gaming consoles and workstation SSDs leverage this for performance consistency under sustained write loads.
3D NAND dominates manufacturing output; Hybrid Technology shows the steepest expansion trajectory.
End User:
Application-specific qualification requirements create divergent procurement patterns across reliability grades and temperature ranges.
- Consumer Electronics:Smartphones, tablets, and wearable devices demanding sub-millimeter z-heights and UFS 4.0 interface speeds. Foldable handset introductions are compressing package height specifications below 0.8mm.
- Automotive OEMs:Domain controllers and zonal gateways requiring AEC-Q100 Grade 2 or Grade 1 qualification. Electric vehicle platforms in Germany and California specify 512GB-1TB embedded storage for autonomous driving data logging.
- Data Centers:Hyperscale operators and colocation facilities deploying storage-class memory and NVMe SSD arrays. EMEA and North American cloud regions are prioritizing bandwidth-per-watt metrics in procurement specifications.
- Industrial IoT:Edge computing nodes and predictive maintenance sensors operating in extended temperature ranges. Factory floor deployments in Japan and Germany specify -40°C to 85°C operational windows.
Consumer Electronics absorbs the highest unit volumes; Data Centers command the fastest value expansion.
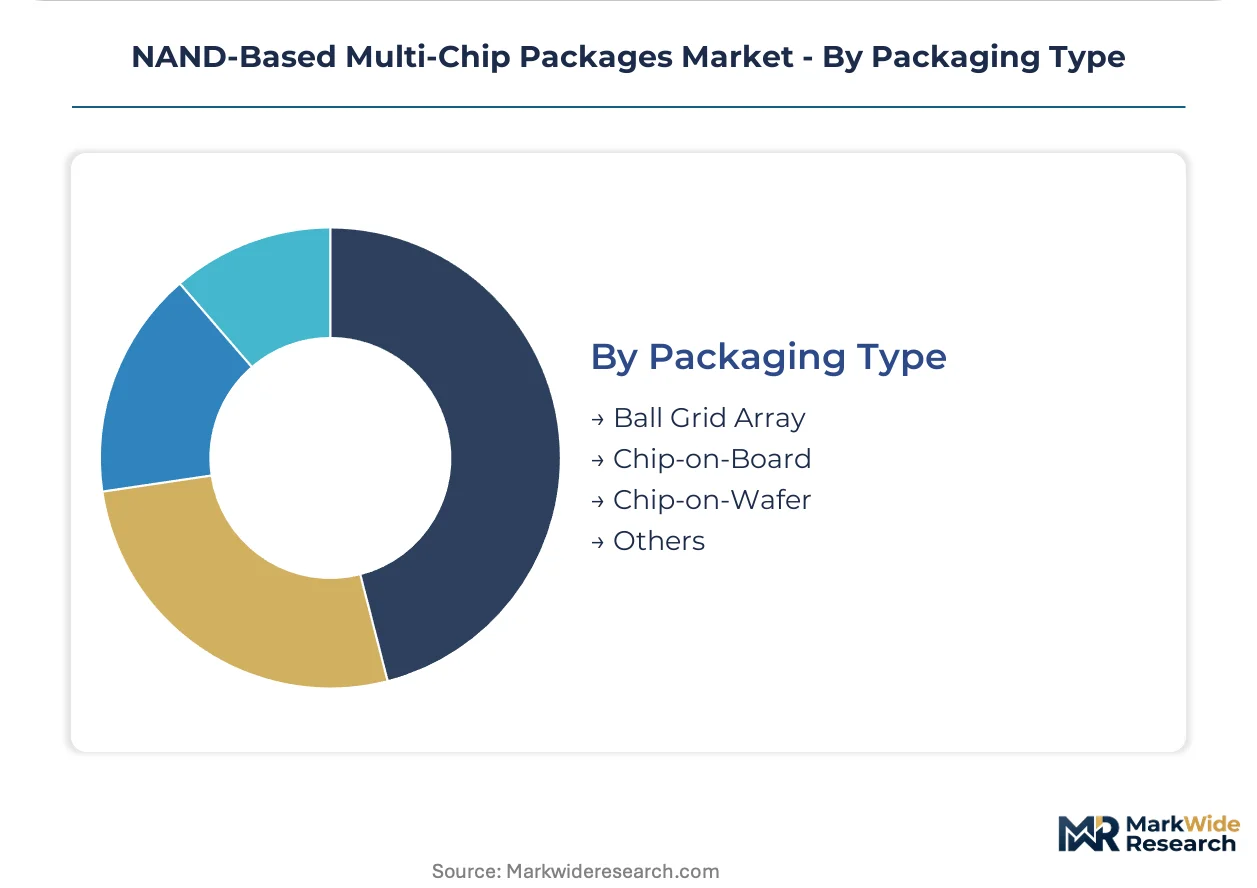
Packaging Type:
Interconnect and substrate choices balance electrical performance against assembly cost and reworkability.
- Ball Grid Array:Solder ball interconnects on organic laminate substrates enabling 0.4-0.8mm pitch densities. Smartphone motherboards and consumer SSDs standardize on FBGA and TBGA outlines.
- Chip-on-Board:Bare die attach directly to system PCB with wire-bond or flip-chip connections. Cost-optimized feature phones and industrial control modules in India and Southeast Asia favor this approach.
- Chip-on-Wafer:Wafer-level integration before singulation, enabling hybrid bonding and die-to-wafer stacking. AI accelerators and high-bandwidth memory applications are piloting this for sub-50μm interconnect pitches.
- Others:Lead-frame packages, QFN outlines, and system-in-package configurations for legacy interface compatibility.
Ball Grid Array maintains volume leadership; Chip-on-Wafer is climbing the fastest as hybrid bonding matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea commands the densest concentration of 3D NAND fabrication, while the United States drives hyperscale data center procurement. Japan maintains critical materials dominance. Taiwan anchors advanced packaging capacity. Germany is emerging as Europe's automotive storage hub.
South Korea
Seoul Capital Area fabs from Samsung Electronics and SK Hynix supply the majority of 176-232 layer NAND die for smartphone and enterprise SSD applications. The Ministry of Trade, Industry and Energy enforces export control frameworks under the Foreign Trade Act for strategic semiconductor technologies. Pyeongtaek and Icheon host the world's highest-density memory fabrication corridors with ongoing expansion into hybrid bonding pilot lines.
United States
Northern Virginia hyperscale operators Meta, Microsoft, and Amazon negotiate die-level pricing for captive SSD programs exceeding 200-layer configurations. The EPA oversees chemical emissions from semiconductor fabrication facilities under the Clean Air Act National Emission Standards. Boise, Idaho and Manassas, Virginia concentrate Micron Technology's domestic manufacturing and R&D operations for advanced packaging specialization.
Japan
Kioxia Corporation and Western Digital joint venture fabs in Yokkaichi and Kitakami produce 3D NAND for global smartphone OEMs and data center integrators. METI coordinates supply chain resilience initiatives under the Economic Security Promotion Act for critical material stockpiling. The Nagoya-Tokyo industrial corridor houses Ajinomoto Build-up Film and Mitsubishi Gas Chemical facilities dominating ABF laminate supply for advanced substrates.
Taiwan
OSATs in Taichung and Kaohsiung manage wire-bond to TSV migration for smartphone storage modules demanding sub-millimeter package heights. The National Development Council administers semiconductor industry subsidies under the Statute for Industrial Innovation. Hsinchu Science Park clusters TSMC's SoIC implementations alongside dedicated memory packaging lines serving AI accelerator and high-bandwidth memory applications.
Germany
BMW, Mercedes-Benz, and Volkswagen specify 512GB-1TB embedded multi-chip packages with AEC-Q100 Grade 2 qualification for zonal storage architectures in electric vehicle platforms. The KBA enforces type approval requirements under UN ECE regulations for automotive electronic systems. Dresden and Leuven receive EU Chips Act preferred funding for advanced packaging lines serving European automotive and industrial automation OEMs seeking supply chain proximity.
NAND-Based Multi-Chip Packages Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive foundry operators commanding premium-tier supply and independent OSATs serving cost-optimized wire-bond volumes. The vendor base concentrates around three strategic archetypes: vertically integrated memory IDMs controlling die supply and packaging, pure-play packaging specialists competing on substrate innovation, and fabless module assemblers sourcing dies through distributor channels. Dominant competitive moves include hybrid bonding technology licensing for wafer-level integration and geographic expansion into India and Southeast Asia to capture PLI scheme benefits.
Within the vertically integrated tier, Samsung Electronics, SK Hynix, and Micron Technology exemplify the IDM archetype by combining captive foundry capacity with in-house advanced packaging operations. Samsung Electronics occupies a position anchoring vertically integrated supply chains through its Pyeongtaek fabrication and packaging co-location. SK Hynix sits within the aggressive R&D intensity segment for 3D NAND stacking architectures. Micron Technology represents the advanced packaging specialization vector at its Taiwan and Singapore manufacturing nodes, distinguishing itself from competitors reliant on third-party OSAT partnerships.
| Leading Market Players |
|---|
| Western Digital |
| Infineon Technologies |
| Samsung Electronics |
| Winbond Electronics Corporation |
| Macronix International |
| Micron Technology |
| Kioxia Corporation |
| Kingston Technology |
| SK Hynix |
| Others |
Supply Flow & Price Mechanics
ABF laminate resin systems from Ajinomoto and Mitsubishi Gas Chemical feed through substrate fabricators to packaging tiers, with fluorinated build-up layer costs cascading differentially across automotive-grade and consumer-grade module pricing.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for 3D NAND die supply, compressing margins for second-tier module assemblers. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive-qualified packages from flagship smartphone UFS modules and cost-optimized wire-bond consumer storage. Price differentiation hinges on certification grade and volume scale, with hyperscale direct procurement eliminating distributor markups. Pricing pressure stems from fluorinated gas allocation volatility, while automotive OEMs exhibit lowest price sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Single-source vulnerability sits with Japanese ABF laminate suppliers dominating substrates above 10 layers. Die fabrication concentrates in South Korea, Taiwan, and the United States, while packaging capacity clusters in Taiwan, China, and emerging India corridors. Raw material dependencies span silicon wafers, high-purity etching gases, and organic substrate laminates. Tariff exposure on Chinese-assembled modules threatens margin structures for US-bound shipments. Distribution runs through direct foundry relationships for hyperscale operators and distributor-mediated channels for industrial and automotive tier-2 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in NAND-based multi-chip packaging rests on hybrid bonding yield improvements and automotive certification premiums offsetting commodity consumer storage erosion.
For Market Incumbents: Extend captive foundry-packaging co-location advantages by qualifying 30μm die thinning for smartphone TSV modules before OSATs achieve comparable yields. Consolidate substrate supplier panels to Japanese and Taiwanese laminate producers with demonstrated PFAS-free roadmaps, locking in ECHA compliance ahead of Korean competitors. Defend against hyperscale disintermediation by embedding firmware customization and technical services into module offerings. For New Entrants and Emerging Players: Automotive tier-2 suppliers in Germany and California present the most penetrable entry point, with 512GB-1TB zonal storage demand outpacing qualified packaging capacity. India's PLI scheme for Gujarat and Karnataka assembly corridors offers capital expenditure offsets for wire-bond capacity targeting cost-optimized smartphone modules. Pursue joint qualification programs with European automotive OEMs seeking supply chain proximity under EU Chips Act subsidies. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier OSATs because substrate warpage control capabilities remain scarce below $500M annual revenue, creating consolidation value in finite element modeling talent and hybrid bonding pilot lines. Target packaging specialists with demonstrated AEC-Q100 Grade 2 qualification timelines under 18 months. Watch for inflection when China's MIIT accelerates GB standards certification cycles to align with quarterly smartphone refresh cadences.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Technology Licensing | Samsung's X-Cube and TSMC's SoIC implementations compress backend assembly value capture toward wafer-level probing. |
| Automotive Certification Investment | AEC-Q100 Grade 2 qualification for 512GB-1TB modules locks in German OEM zonal architecture specifications. |
| India PLI Scheme Capacity Buildout | Gujarat and Karnataka corridors attract 25% capital expenditure offsets for smartphone wire-bond packaging. |
| PFAS-Free Substrate Roadmap | ECHA restriction proposals privilege Japanese and Taiwanese laminate suppliers over Korean competitors in European automotive panels. |
| Hyperscale Direct Procurement | Meta, Microsoft, and Amazon negotiate die-level pricing for captive SSD programs, eliminating traditional distributor margins. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with NAND packaging engineers, substrate procurement leads at OSATs, automotive electronics platform managers, and hyperscale infrastructure sourcing officers with secondary validation. Sources included SEC filings from memory IDMs, ECHA substance restriction proposals, EU Chips Act funding disclosures, and customs data on ABF laminate trade flows. Bottom-up die shipment estimates and top-down module revenue analysis were triangulated against foundry capacity announcements.
Segment-weighting approaches modeled product type, technology node, end-user application, and packaging interconnect complexity across the analysis window. CAGRs were derived from layer-count escalation trajectories, smartphone storage density requirements, and data center bandwidth-per-watt procurement specifications. Forecast inputs incorporated 3D NAND fab expansion timelines, hybrid bonding yield learning curves, and automotive zonal storage architecture adoption patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA PFAS restriction implementation timelines, MIIT certification cycle alignment, and fluorinated gas supply allocation volatility. Forecasts reflect documented assumptions about die thinning feasibility, substrate warpage control scalability, and hyperscale direct procurement penetration rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
ECC Memory Market
Memory Chips
Contactless Memory Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
In-Memory Grid Market
Memory Chips
Digital RF Memory Market
Memory Chips
Japan Semiconductor Memory Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
Static RAM Market
Memory Chips
Memory IC Market
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
Memory Chip Market
Memory Chips
Embedded Non-Volatile Memory Market
Memory Chips
Europe Dynamic Random Access Memory (DRAM) Market
Memory Chips
Japan Flash Memory Market
Memory Chips
DDR SDRAM Market