
 APAC Dynamic Random Access Memory (DRAM) Market | 2026-2036
APAC Dynamic Random Access Memory (DRAM) Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Dynamic Random Access Memory (DRAM) Market Insights
Hyperscale datacenter operators is bifurcating from traditional consumer electronics OEMs as the dominant demand archetype across the APAC DRAM landscape. Samsung Electronics Co. Ltd leverages its vertically integrated Pyeongtaek fabrication complex to anchor supply for server-grade DDR5 modules. SK hynix Inc. competes through advanced packaging leadership in high-bandwidth memory stacks for AI accelerators. ChangXin Memory Technologies specializes in mature-node DDR4 production to capture cost-sensitive enterprise storage demand.
Dynamic Random Access Memory consists of capacitive storage cells arranged in arrays with each bit stored as an electrical charge requiring periodic refresh cycles, typically operating at voltages between 1.1V and 1.5V depending on generation. The technology serves as the primary working memory for computing systems where low-latency random access to active data streams determines system performance. DDR5 modules command premium positioning in server and AI training workloads where bandwidth density per channel determines infrastructure economics. LPDDR4 maintains structural importance in mobile devices where thermal constraints and battery endurance govern design tradeoffs. DIMM and SO-DIMM form factors segment cleanly between rack-mounted enterprise servers and compact consumer laptops.
China's MIIT enforces domestic content requirements through the GB standards framework while South Korea's METI coordinates semiconductor R&D consortia under national strategic technology designations. REACH compliance from Europe-bound exports and Japan's METI export controls on advanced deposition equipment both reshape component sourcing and process technology roadmaps for APAC fabricators. Stakeholders must monitor how dual-use technology restrictions and carbon-border adjustment mechanisms recalibrate capital allocation between leading-edge expansion and mature-node specialization.
Market Dynamics
High-bandwidth memory architectures are bifurcating procurement patterns across APAC, with AI training clusters demanding fundamentally different module specifications than traditional enterprise servers. This divergence concentrates investment in South Korea's advanced packaging corridors while redirecting mature-node capacity toward Chinese system integrators serving cost-sensitive storage arrays.
Growth Catalysts
- AI Accelerator Deployment:Hyperscale datacenter operators in China's Yangtze River Delta are scaling procurement of HBM3E stacks for GPU clusters, creating dedicated demand lanes separate from general-purpose server memory.
- GB Standards Compliance:China's MIIT domestic content mandates are redirecting wafer procurement toward ChangXin Memory Technologies and local packaging houses, insulating regional supply from external disruption.
- DDR5 Server Migration:Cloud service providers across South Korea's Pyeongtaek-Suwon corridor are completing rack refreshes, displacing DDR4 inventories toward secondary enterprise markets.
Market Restraints
- Advanced Deposition Equipment Access:Japan's METI export controls on EUV lithography components constrain South Korean fabricators from sub-10nm node expansion without alternative tool sourcing.
- Fluorinated Gas Supply Concentration:Etching chemistry inputs for 3D NAND and DRAM stack fabrication concentrate among Japanese and Korean chemical suppliers, exposing cost volatility from regional production curtailments.
- Power Density Constraints:HBM2E and HBM3 modules exceed 1.2V thermal envelopes in dense server configurations, limiting deployment in existing air-cooled facilities without liquid cooling retrofit capital.
Strategic Opportunities
- Vietnam Packaging Diversification:Assembly and test capacity in Bac Ninh and Ho Chi Minh City industrial zones offers tariff-advantaged export routes for modules bound for North American OEMs.
- Automotive LPDDR5 Adoption:Advanced driver-assistance systems in Japanese and Korean vehicle platforms are qualifying low-power memory for central compute modules, opening qualification pathways outside datacenter procurement.
- South Korea R&D Consortia:METI-coordinated public-private partnerships fund next-generation interface standards development, reducing private capital burden for interface IP advancement.
Industry Challenges
- Packaging Engineer Scarcity:TSV (through-silicon via) process specialists and thermal simulation experts command premium compensation across Seoul and Hsinchu labor markets, constraining HBM yield ramp schedules.
- Legacy DDR3 EOL Transition:Industrial and networking equipment OEMs face forced redesign cycles as Samsung and SK hynix accelerate last-time-buy notifications for 20nm-class commodity modules.
- Carbon Border Adjustment Alignment:European-bound module exports require embedded emissions documentation that APAC fabricators lack standardized measurement protocols to generate, delaying customs clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Dynamic Random Access Memory (DRAM) Market |
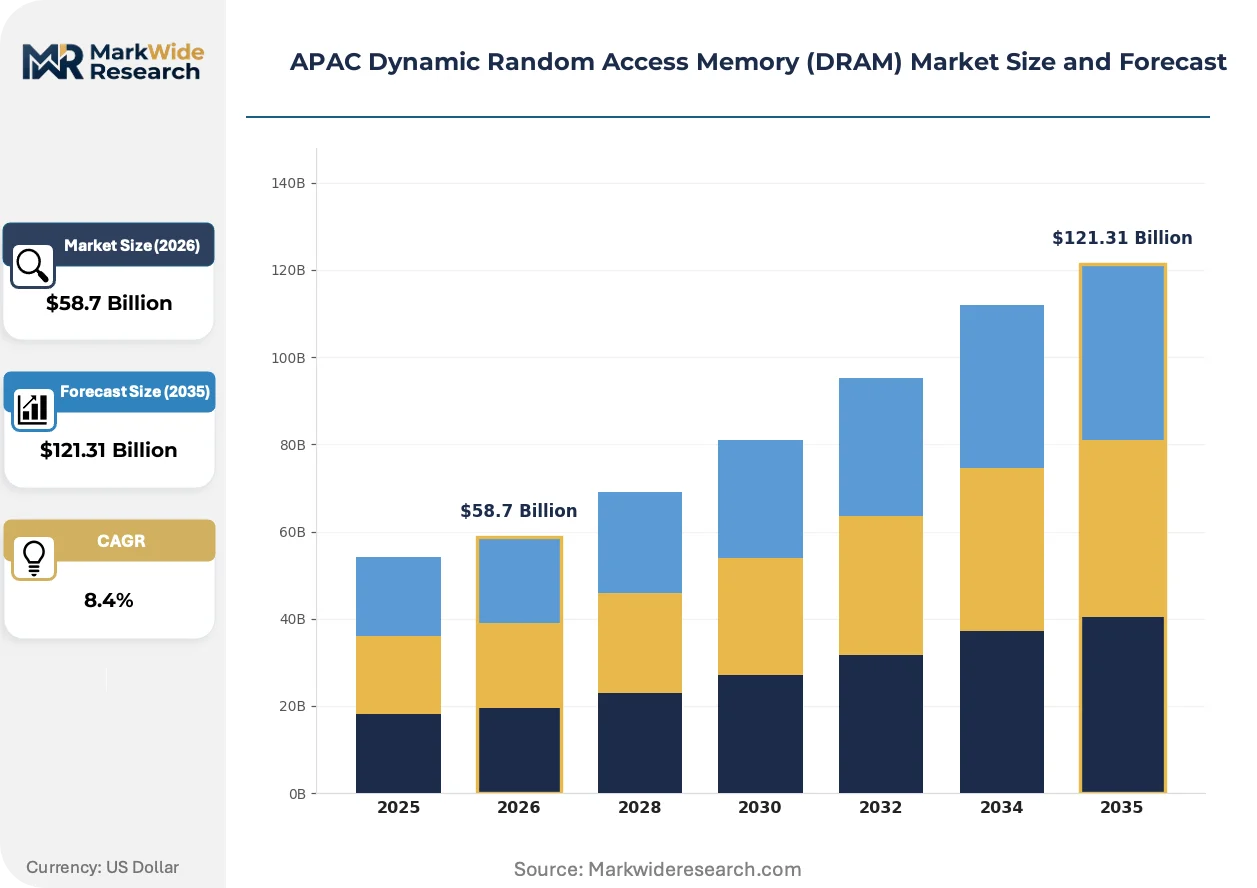
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDR3, DDR4, DDR5, LPDDR4 Application: Consumer Electronics, Servers, Mobile Devices, Automotive Form Factor: SO-DIMM, DIMM, MicroDIMM, LRDIMM End User: OEMs, Retailers, Distributors, Enterprises |
| Companies Covered | Nanya Technology Corporation, Powerchip Technology Corporation, Samsung Electronics Co. Ltd, ChangXin Memory Technologies, Transcend Information, SK hynix Inc., Winbond Electronics Corporation, Kingston Technology, Micron Technology Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Dynamic Random Access Memory (DRAM) Market Trends and Innovations
Interface standard evolution and sovereign supply chain mandates are recalibrating competitive positioning across memory procurement. Module specifications diverge between AI training workloads and general compute, while regulatory pressure on carbon intensity and domestic content reshapes fabrication geography.
High-bandwidth memory is fragmenting the traditional DIMM market into specialized verticals. HBM3E stacks enable 819 GB/s bandwidth per accelerator package for large language model training. Cloud operators in South Korea and Taiwan are qualifying these modules for 100k+ GPU deployments. This bifurcation is fragmenting procurement teams into AI infrastructure specialists separate from general server buyers.
China's dual carbon goals and GB 31241 battery safety standards are extending to semiconductor fabrication energy disclosure. MIIT enforcement requires wafer fabs above 50MW connected load to report Scope 2 emissions quarterly. Memory modules bound for state-owned enterprise procurement must carry third-party carbon footprint verification, favoring Pyeongtaek facilities with captive renewable power purchase agreements.
Hyperscale buyers are consolidating direct sourcing relationships with memory fabricators, bypassing traditional distribution. Alibaba Cloud and Baidu AI have established dedicated supply agreements with SK hynix for HBM allocation, locking capacity outside spot market availability. This channel compression concentrates in China's Yangtze River Delta and South Korea's manufacturing corridor, marginalizing regional distributors from high-margin AI memory segments.
APAC Dynamic Random Access Memory (DRAM) Market Segmentation
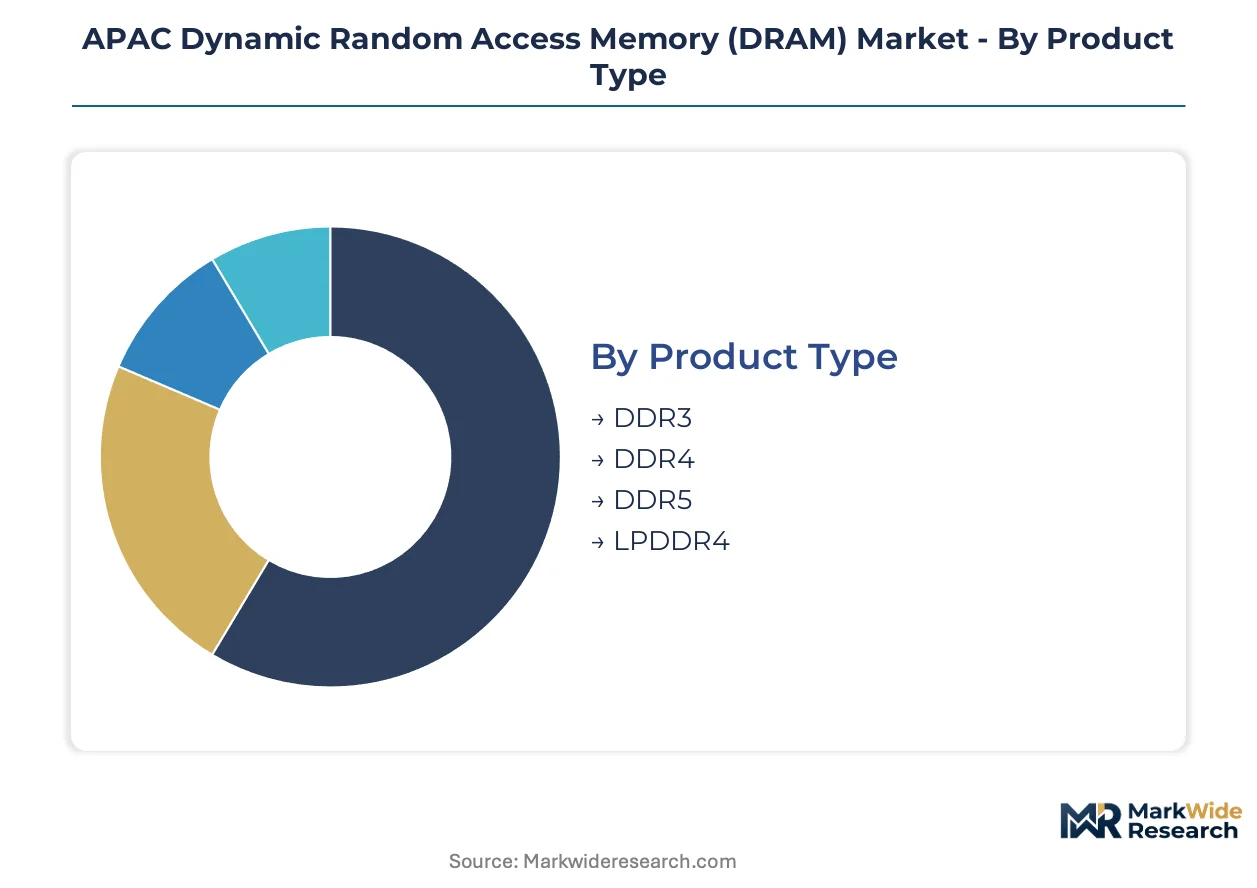
APAC DRAM procurement patterns fragment sharply across interface generations and thermal envelopes. Product roadmaps diverge between AI training clusters demanding HBM-class bandwidth and cost-sensitive enterprise storage arrays. Understanding segment substitution dynamics illuminates where capital redeploys fastest.
Product Type:
DDR5 modules face the strongest substitution pressure as AI infrastructure operators bypass intermediate generations entirely, while mature-node DDR4 absorbs displaced enterprise server demand.
- DDR3:20nm-class planar cells operate at 1.5V with 800-2133 MT/s transfer rates. Industrial automation and legacy networking equipment in China's Pearl River Delta sustain residual procurement despite Samsung's last-time-buy acceleration.
- DDR4:1.2V operating voltage with 2133-3200 MT/s speeds across 4Gb-16Gb densities. Enterprise storage arrays in South Korea's Pangyo technopole absorb rack-refresh displacement from DDR5 server migrations.
- DDR5:Dual 32-bit subchannels enable 4800-6400 MT/s with on-die ECC. Hyperscale datacenters in South Korea's Pyeongtaek-Suwon corridor complete server-grade module qualification for cloud infrastructure.
- LPDDR4:Mobile-optimized 1.1V interface with stacked-package configurations. Smartphone OEMs in Vietnam's Bac Ninh industrial zone qualify modules for 5G handset thermal envelopes.
DDR4 retains volume leadership across APAC enterprise procurement; DDR5 holds the steepest expansion curve as AI training clusters scale.
Application:
Cost tier stratification separates air-cooled enterprise servers from liquid-cooled AI accelerators, with automotive qualification emerging as a margin buffer.
- Consumer Electronics:Notebook and desktop systems in Taiwan's Taoyuan manufacturing cluster specify SO-DIMM configurations with soldered-down LPDDR4 for ultrabook thermal constraints.
- Servers:Rack-mounted DDR5 DIMMs with PMIC onboard regulate voltage at 1.1V. Cloud operators in China's Yangtze River Delta memory cluster lock capacity through direct fabricator agreements.
- Mobile Devices:PoP (package-on-package) stacking dominates smartphone memory subsystems. Korean handset OEMs qualify LPDDR4X variants for flagship 5G models.
- Automotive:AEC-Q100 Grade 2 temperature cycling requirements govern central compute modules. Japanese Tier-1 suppliers qualify LPDDR5 for advanced driver-assistance systems.
Server applications command the highest module ASPs; automotive qualification pathways are climbing fastest as functional safety standards mature.
Form Factor:
Supply concentration in Seoul and Hsinchu packaging corridors determines which form factors achieve yield scale fastest.
- SO-DIMM:72-pin or 260-pin configurations for notebook and compact workstation motherboards. Taiwanese ODMs in Taichung industrial parks specify these for enterprise laptop refresh cycles.
- DIMM:Standard 288-pin DDR5 modules with SPD EEPROM for server motherboards. Samsung's Pyeongtaek fab anchors supply for hyperscale datacenter rack deployments.
- MicroDIMM:214-pin compact format for blade servers and embedded systems. Japanese industrial computing OEMs specify these for factory automation controllers.
- LRDIMM:Buffered architectures with data buffers reduce electrical load for high-capacity server configurations. Chinese cloud operators qualify these for in-memory database workloads.
DIMM form factors retain volume leadership in APAC procurement; LRDIMM adoption is gaining share fastest as memory-per-socket requirements climb.
End User:
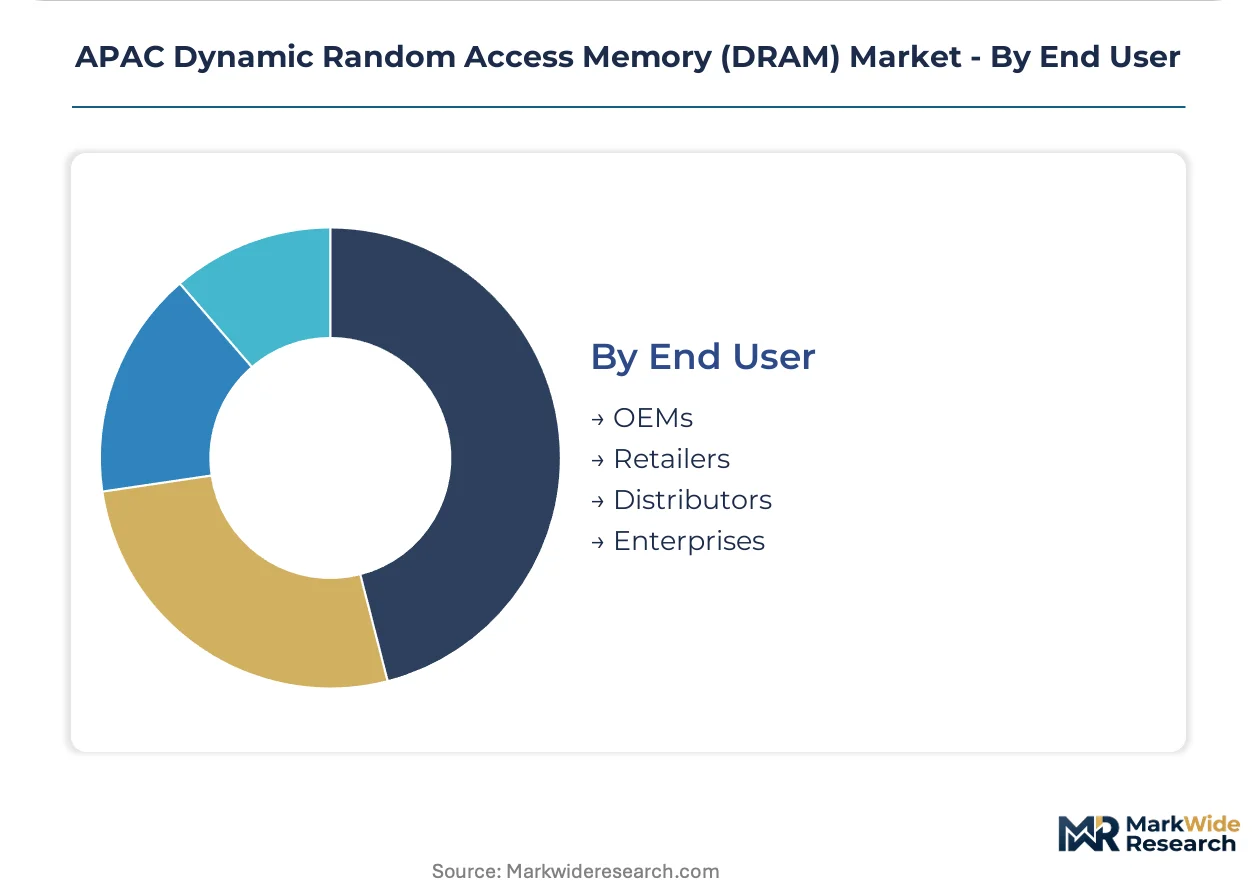
Customer type determines whether procurement flows through distribution or direct fabricator relationships, with channel compression most advanced in AI memory segments.
- OEMs:Server and handset manufacturers in South Korea and Taiwan negotiate annual capacity agreements. Direct sourcing relationships with SK hynix and Samsung bypass traditional distribution for HBM allocation.
- Retailers:Module kit vendors in Shenzhen's Huaqiangbei electronics market serve enthusiast and small-system-builder demand. Price transparency from spot-market DRAM pricing governs inventory turns.
- Distributors:Arrow Electronics and Avnet maintain buffer stock for industrial and networking equipment OEMs. Long-tail DDR3 demand concentrates through these channels as primary fabricators exit.
- Enterprises:State-owned enterprises in China face GB standards domestic content mandates. MIIT enforcement requires carbon footprint verification for memory modules in government procurement.
OEMs retain volume leadership in APAC DRAM offtake; enterprise direct procurement is expanding most quickly as sovereign supply chain mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan anchors South Korea's semiconductor export corridor, handling specialized container flows for memory modules bound for global datacenter operators. This maritime infrastructure underwrites Pyeongtaek-Suwon manufacturing concentration and shapes regional procurement logistics.
China
MIIT domestic content mandates redirect wafer procurement toward ChangXin Memory Technologies for state-owned enterprise memory requirements. The GB standards framework enforces carbon footprint verification for government procurement, favoring Yangtze River Delta fabs with renewable power purchase agreements.
South Korea
METI-coordinated R&D consortia fund next-generation interface standards development for AI accelerator memory stacks. Samsung Electronics and SK hynix anchor supply from vertically integrated Pyeongtaek fabrication complexes serving hyperscale cloud operators.
Japan
METI export controls on advanced deposition equipment constrain sub-10nm node expansion for regional fabricators. Tokyo and Osaka industrial zones concentrate etching chemistry suppliers for 3D NAND and DRAM stack fabrication.
Taiwan
TSMC-adjacent packaging corridors in Hsinchu and Taichung industrial parks supply advanced module assembly for North American OEM qualification. The island's semiconductor equipment ecosystem supports regional memory test and validation infrastructure.
Vietnam
Bac Ninh and Ho Chi Minh City industrial zones offer tariff-advantaged export routes for modules bound for North American markets. Assembly and test capacity expansion attracts secondary packaging investment from Korean memory fabricators.
APAC Dynamic Random Access Memory (DRAM) Market Competitive Landscape
Concentration sits with vertically integrated Korean conglomerates commanding advanced packaging corridors for AI accelerator memory. The vendor base spans three strategic tiers: captive fabricators serving hyperscale direct procurement, independent module assemblers for industrial long-tail demand, and Chinese domestic champions fulfilling MIIT content mandates. Capacity expansion and sovereign supply chain partnerships constitute the dominant competitive vectors reshaping allocation agreements.
Among Korean fabricators, Samsung Electronics Co. Ltd and SK hynix Inc. occupy positions anchoring high-bandwidth memory supply for cloud infrastructure operators. ChangXin Memory Technologies exemplifies the domestic champion archetype capturing state-directed procurement under GB standards enforcement. Nanya Technology Corporation and Powerchip Technology Corporation represent Taiwan-based specialists maintaining module assembly scale for secondary enterprise markets.
| Leading Market Players |
|---|
| Nanya Technology Corporation |
| Powerchip Technology Corporation |
| Samsung Electronics Co. Ltd |
| ChangXin Memory Technologies |
| Transcend Information |
| SK hynix Inc. |
| Winbond Electronics Corporation |
| Kingston Technology |
| Micron Technology Inc. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day wafer fab lead times for DDR5 modules concentrate pricing power with Samsung and SK hynix in South Korea's Pyeongtaek-Suwon corridor, while Chinese system integrators absorbing displaced DDR4 inventories face compressed margins from ChangXin Memory Technologies' cost-positioned output. This inventory-to-pricing feedback loop rewards captive renewable power agreements that lower Scope 2 exposure for European-bound exports.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs module procurement, with HBM3E stacks for AI accelerators commanding premium positioning against commodity DDR4 for enterprise storage. Price differentiation rests on thermal envelope certification and direct fabricator relationships versus spot-market sourcing. Pricing pressure stems from Japan's METI export controls constraining sub-10nm equipment access for leading-edge expansion. Cloud service providers exhibit lowest price sensitivity due to locked capacity agreements, while Shenzhen distributors serving small-system builders face margin compression from transparent spot pricing.
Supply Chain Analysis
Strategic stockpile preferences dominate among hyperscale operators securing HBM allocation through multi-quarter offtake agreements, contrasting with just-in-tight inventory discipline at industrial OEMs managing DDR3 end-of-life transitions. Geographic supply concentration centers on South Korea, Taiwan, and China for wafer fabrication and advanced packaging. Raw material dependencies include fluorinated etching gases from Japanese chemical suppliers and EUV lithography components subject to export controls. Single-source vulnerability concentrates in TSV process equipment for HBM stacking. Distribution runs through direct fabricator relationships for AI memory segments, bypassing traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through China's GB standards and Japan's METI export controls erects structural barriers against new fabrication capacity. Switching costs for hyperscale operators qualifying HBM stacks reinforce incumbent positioning.
For Market Incumbents: Secure captive renewable power purchase agreements for Pyeongtaek facilities to satisfy European carbon border documentation requirements and defend margin position against ChangXin Memory Technologies' state-subsidized cost structure. Deepen backward integration into etching chemistry supply through Korean-Japanese joint ventures to mitigate fluorinated gas concentration risk. For New Entrants and Emerging Players: Anchor in Vietnam's Bac Ninh industrial zone for tariff-advantaged assembly and test capacity serving North American OEM qualification pathways. Target automotive LPDDR5 segments where AEC-Q100 Grade 2 certification requirements create qualification barriers favoring specialized entrants over commodity players. Pursue direct technical partnerships with Japanese Tier-1 suppliers for advanced driver-assistance system integration. For Investors and Strategic Acquirers: Long-term, this sits as a sovereign technology access play because MIIT domestic content mandates and METI export controls fragment global supply into non-substitutable regional blocs. Acquisition target archetype: advanced packaging specialists with TSV process expertise in Hsinchu or Seoul labor markets. Watch for Japan's deposition equipment control list expansion as inflection indicator for Korean fabricator capital allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Vietnam | Bac Ninh assembly zones offer tariff-advantaged export routes for North American OEM qualification. |
| Backward Integration into Etching Chemistry | Korean-Japanese joint ventures reduce fluorinated gas supply concentration vulnerability for 3D stack fabrication. |
| Green Certification Program | Captive renewable PPAs at Pyeongtaek satisfy European carbon border adjustment documentation requirements. |
| Long-term Supply Agreement | Direct HBM allocation contracts with Alibaba Cloud and Baidu AI lock capacity outside spot market volatility. |
| Joint Venture for TSV Process Development | Seoul-Hsinchu packaging corridors address packaging engineer scarcity constraining HBM yield ramps. |
Research Methodology
Desk research of SEC filings from memory fabricators, customs trade databases, and MIIT regulatory notices preceded structured interviews with datacenter procurement officers, semiconductor packaging engineers, and carbon verification specialists. Primary fieldwork with cloud infrastructure operators in China's Yangtze River Delta and South Korea's Pangyo technopole validated secondary demand signals. Bottom-up module shipment analysis triangulated against top-down wafer capacity announcements from Samsung, SK hynix, and ChangXin Memory Technologies.
Variance decomposition across interface generation, thermal envelope, and end-user procurement channel anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, application, form factor, and end-user category, with sovereign supply chain mandate intensity as an industry-specific overlay. CAGRs derived from installed base replacement cycles for DDR4-to-DDR5 server migrations and AI accelerator deployment scaling. Forecast inputs incorporated Japan's METI equipment control list evolution and China's GB standards enforcement trajectory.
Decision-makers should treat outputs as directional under assumptions of continued METI export control stringency and MIIT domestic content mandate expansion; material deviation would warrant model refresh. Revision becomes warranted when fluorinated gas supply disruptions or carbon border adjustment mechanism scope expansion crosses operational thresholds for APAC fabricator cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market
Memory Chips
eMMC Master Control Chip Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
Second-Gen Magneto Resistive RAM (STT MRAM) Market
Memory Chips
China Flash Memory Market
Memory Chips
Memristor Market
Memory Chips
DDR SDRAM Market
Memory Chips
Ferroelectric RAM Market
Memory Chips
Next Generation Memory Market
Memory Chips
MRAM Market
Memory Chips
Automotive Memory Market
Memory Chips
Contactless Memory Market
Memory Chips
Memory IC Market