
 Contactless Memory Market | 2026-2036
Contactless Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Contactless Memory Market Insights
Buyer concentration across automotive OEMs and government ID issuers is rebalancing toward fragmented procurement from healthcare networks and retail chains. NXP Semiconductors leverages its automotive-qualified NFC portfolio to anchor supply relationships with Tier 1 module integrators. STMicroelectronics competes through R&D intensity in secure-element architectures for payment credentials. Samsung Electronics dominates wafer-scale manufacturing capacity for high-volume RFID inlay production.
Contactless memory stores and transmits data via radio-frequency coupling without physical electrical contact, typically operating at 13.56 MHz for NFC or 860–960 MHz for UHF RFID protocols with read ranges from centimeters to tens of meters. The technology enables authentication, tracking, and transaction processing across sealed or moving substrates where connector wear would compromise reliability. Smart Cards command the largest revenue pool due to banking and national ID program volumes, though NFC Tags represent the fastest-expanding segment as smartphone-tap ecosystems proliferate in retail access control. Payment Systems applications concentrate margin in certified secure-element supply, while Inventory Management segments compete on unit cost at billion-tag annual scale.
FCC Part 15 rules in the United States govern unlicensed RF emissions for contactless devices, constraining power levels and spectrum allocation that shape product architecture decisions. ETSI standards in Europe and the EU Cyber Resilience Act impose security-by-design mandates that filter market access for uncertified suppliers. Stakeholders must monitor evolving national digital ID frameworks and automotive cybersecurity regulations to anticipate procurement specification shifts before qualification cycles lock in vendor selections.
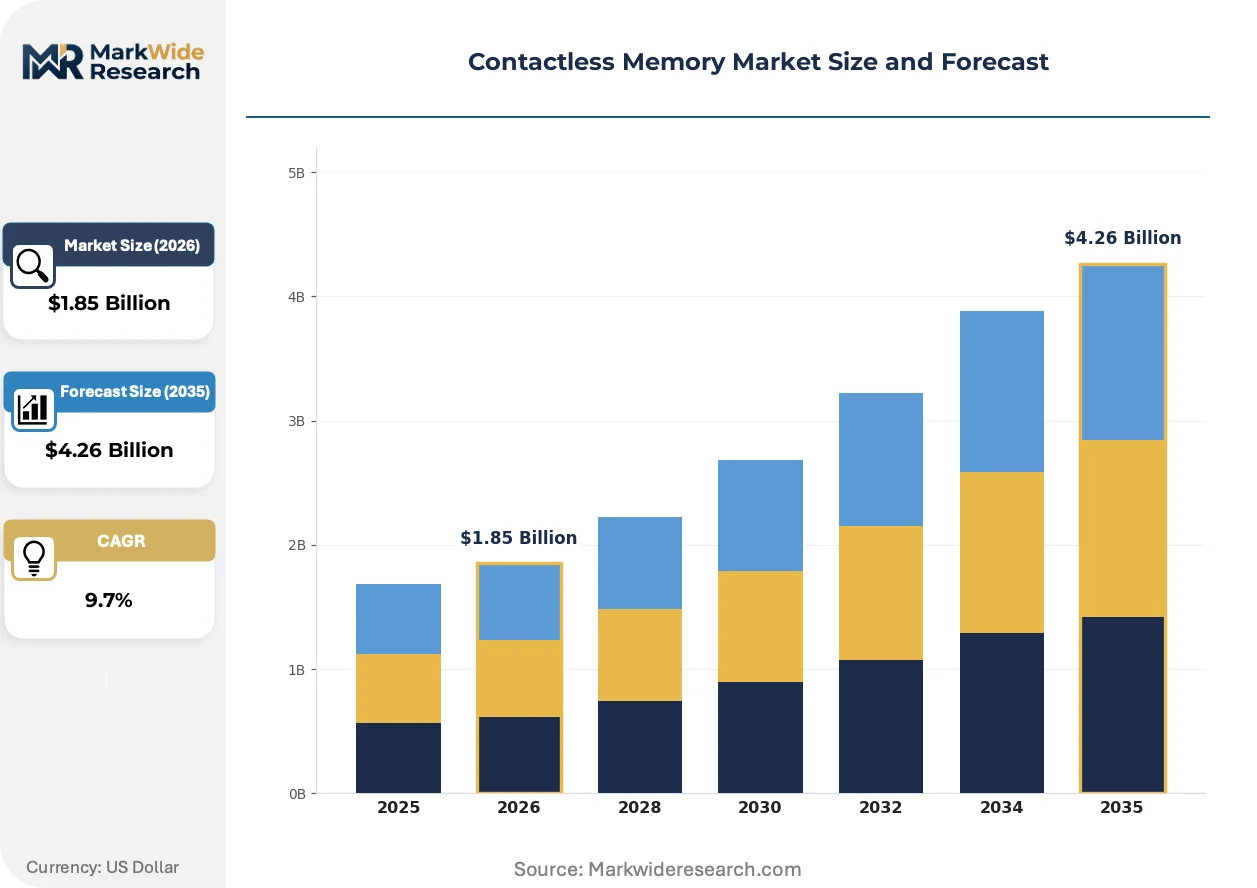
Market Dynamics
Automotive OEMs and government ID issuers are consolidating procurement around certified secure-element suppliers, while EU Cyber Resilience Act mandates force qualification cycles that lock out uncertified vendors before design windows close.
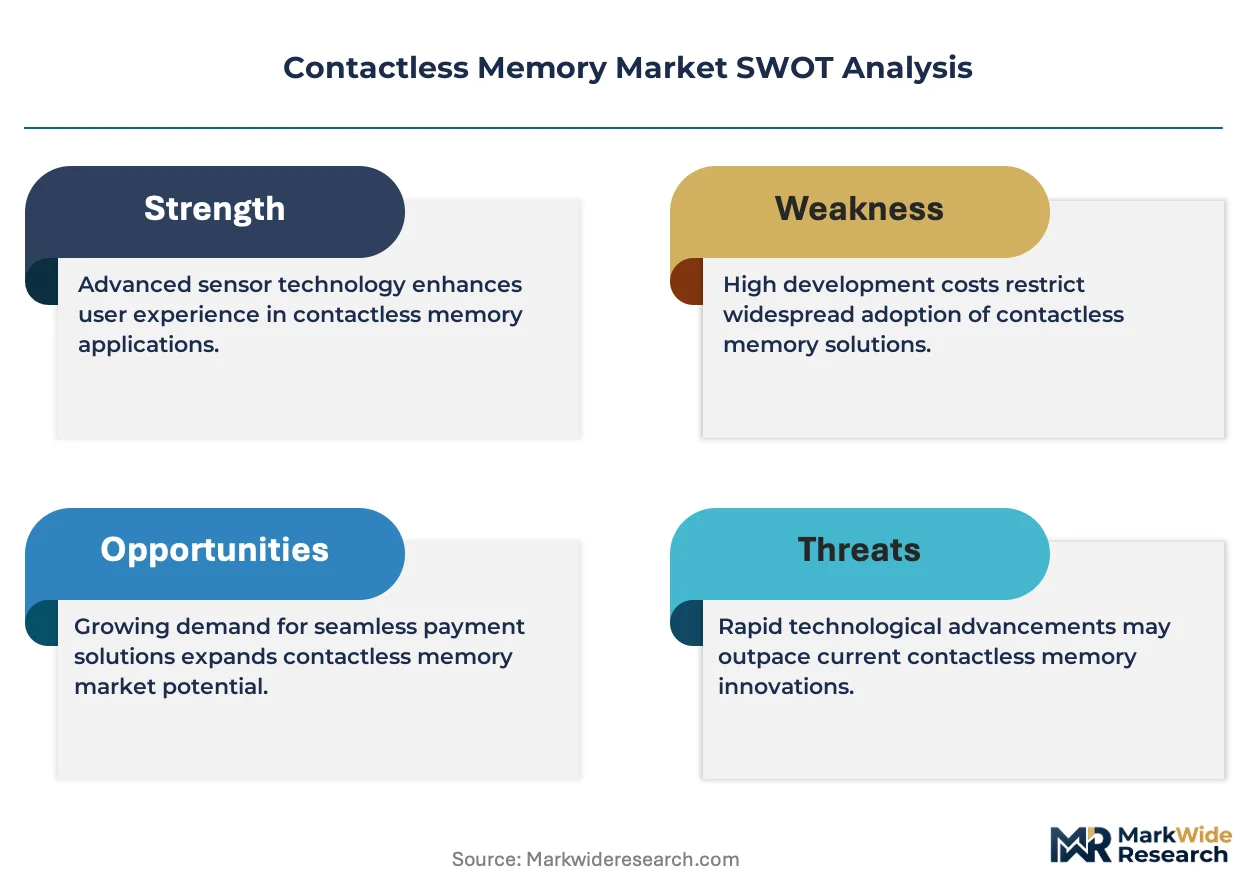
Growth Catalysts
- ETSI EN 303 645 certification:European cybersecurity standards for IoT devices are accelerating demand for tamper-resistant NFC modules in connected automotive and healthcare equipment.
- Automotive keyless entry:German OEMs are embedding UHF RFID transponders into passive entry systems, requiring high-reliability memory qualified to AEC-Q100 stress tests.
- Digital identity credentialing:National e-ID programs across EU member states are mandating contactless smart card deployments with Common Criteria EAL5+ secure elements.
Market Restraints
- Silicon wafer supply concentration:Advanced RFID inlay production depends on 300mm wafer capacity concentrated in East Asian foundry clusters, exposing buyers to allocation risk.
- Secure-element qualification timelines:Common Criteria and EMVCo certification cycles extend 18-24 months, freezing architecture decisions before volume ramps.
- Optical biometric substitution:Facial recognition and fingerprint-on-display systems are displacing contactless card authentication in premium smartphone segments.
Strategic Opportunities
- Healthcare asset tracking:German hospital networks are piloting NFC-enabled surgical instrument sterilization logs, creating demand for high-temperature-resistant memory tags.
- EU Green Deal alignment:Battery passport regulations mandating digital product passports are driving RFID integration into electric vehicle cell packaging for lifecycle traceability.
- Hybrid NFC-UHF convergence:Dual-protocol chips combining 13.56 MHz payment authentication with 865-868 MHz logistics tracking are opening unified retail-supply-chain deployments.
Industry Challenges
- RF analog design talent scarcity:The intersection of antenna matching, power harvesting, and digital protocol stacks requires specialized mixed-signal engineers concentrated in Munich and Eindhoven clusters.
- Legacy POS infrastructure fragmentation:Retail chains operate parallel NFC, magnetic stripe, and QR code acceptance systems, forcing chip vendors to support multi-protocol firmware stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contactless Memory Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NFC Tags, RFID Tags, Smart Cards, Memory Modules Technology: Magnetic Induction, Infrared, Ultrasonic, Electromagnetic Application: Access Control, Payment Systems, Inventory Management, Tracking Solutions End User: Retail, Automotive, Healthcare, Logistics |
| Companies Covered | NXP Semiconductors, Infineon Technologies, STMicroelectronics, Samsung Electronics, Sony Corporation, Microchip Technology, Shanghai Fudan Microelectronics Group, IDEMIA, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contactless Memory Market Trends and Innovations
Energy-harvesting tag architectures and post-quantum cryptographic hardware are compressing the gap between disposable logistics labels and banking-grade secure elements, forcing vendors to recalibrate R&D roadmaps.
Dual-interface EEPROM with RF energy harvesting is electrifying passive sensor applications in industrial predictive maintenance. German automotive suppliers are embedding these chips into rotating shaft monitors where battery replacement is impossible. The technology is electrifying demand for foundry processes that integrate power management with non-volatile storage on single die.
The EU Cyber Resilience Act's security-by-design mandates are filtering market access for connected device components. Manufacturers must demonstrate vulnerability management processes and automatic update capabilities before CE marking. Payment terminal OEMs in France and the Netherlands are restructuring supplier qualification to front-load cryptographic architecture reviews.
Healthcare procurement departments are unbundling tag supply from system integration contracts, directly negotiating volume commitments with semiconductor vendors. This disintermediation compresses margin for traditional RFID inlay converters while rewarding chip suppliers with balance-sheet strength to offer consignment inventory. German hospital procurement associations are piloting this model for implantable device tracking programs.
Contactless Memory Market Segmentation
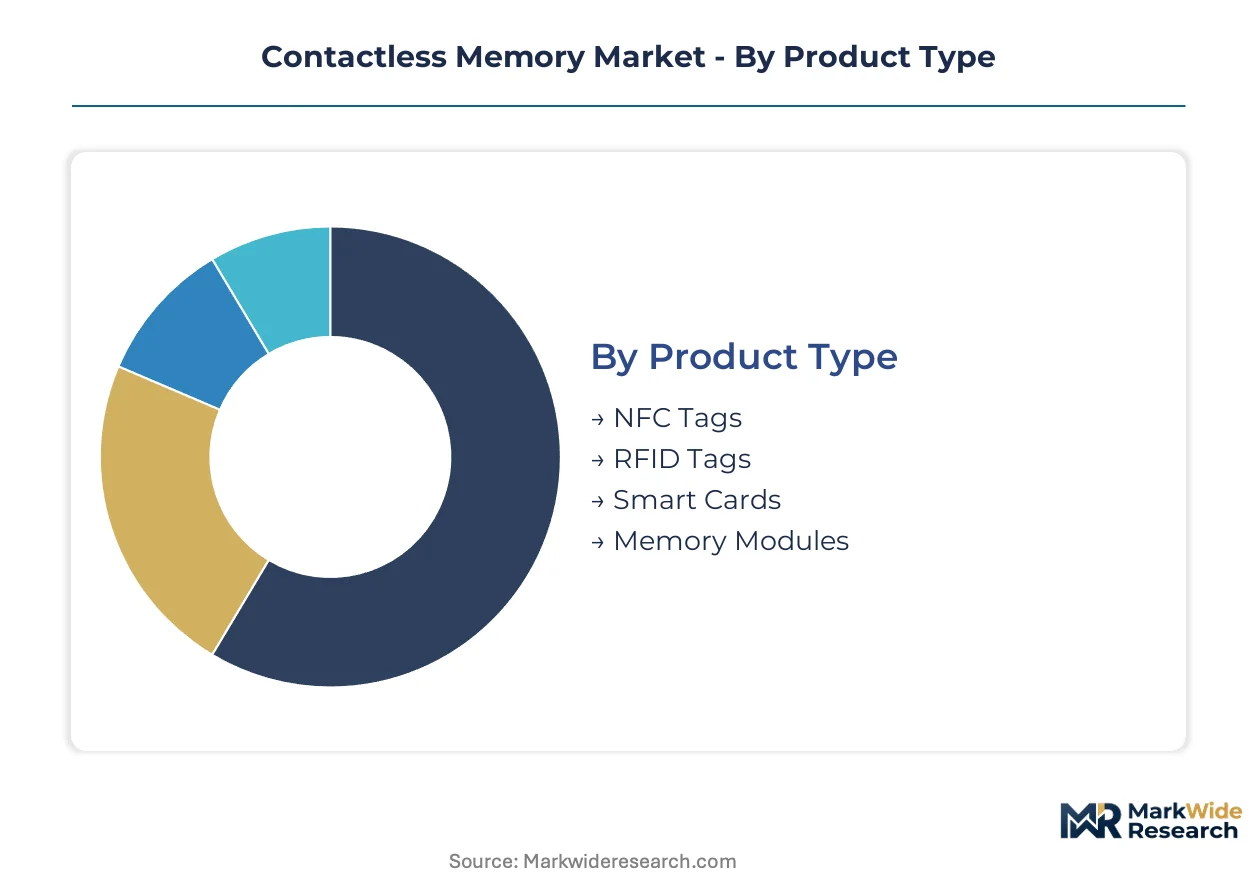
Contactless memory procurement decisions hinge on protocol compatibility, security certification tiers, and environmental durability requirements. Upgrade cycles vary dramatically across segments, from disposable logistics labels replaced annually to banking-grade secure elements with decade-long qualification windows.
Product Type:
Replacement cycles stretch from months for consumable tags to years for embedded automotive modules, forcing vendors to maintain parallel qualification pipelines.
- Smart Cards:Polycarbonate or PVC substrates embed microcontroller-based secure elements with cryptographic coprocessors certified to Common Criteria EAL4+ or higher. National e-ID programs in Germany and France anchor procurement volumes, with EMVCo certification timelines extending 18-24 months before volume deployment.
- NFC Tags:Passive 13.56 MHz devices harvest RF energy to power small EEPROM or FRAM arrays, typically 64 bytes to 32 kB capacity. Retail access control pilots in German hospital networks are accelerating demand for ISO 14443 Type A/B compliant formats.
- RFID Tags:UHF 860-960 MHz inlays with printed antennas dominate logistics serialization at billion-unit annual scale.
- Memory Modules:Industrial-grade contactless storage integrates with PLC and sensor networks in factory automation clusters.
Smart Cards sits at the top of the volume ranking, with NFC Tags climbing the fastest.
Technology:
Cost tiers separate premium authenticated protocols from commodity proximity sensing, with electromagnetic coupling commanding the highest ASPs.
- Electromagnetic:RF field coupling at 13.56 MHz or UHF bands enables passive power transfer and bidirectional data exchange across sealed enclosures. Automotive passive entry systems in German OEM supply chains require AEC-Q100 qualified transponders with -40°C to +125°C operating ranges.
- Magnetic Induction:Near-field coupling through inductive loops powers simple identification tokens without onboard batteries. Access control badges in European corporate campuses concentrate demand for 125 kHz proximity formats despite security limitations.
- Infrared:Line-of-sight optical transmission supports short-range data bursts in controlled lighting environments.
- Ultrasonic:Acoustic wave propagation enables underwater or metallic barrier penetration where RF attenuation blocks electromagnetic alternatives.
Electromagnetic technology captures the dominant revenue share, while Magnetic Induction maintains installed-base dominance in legacy infrastructure.
Application:
Margin structures diverge sharply between certified secure-element supply and commodity tag volumes, with payment authentication commanding 10-20x unit premiums over logistics serialization.
- Payment Systems:EMV contactless and mobile wallet transactions require tamper-resistant secure elements with dynamic cryptogram generation. French and Dutch payment terminal OEMs are restructuring supplier qualification to front-load cryptographic architecture reviews under EU Cyber Resilience Act mandates.
- Inventory Management:UHF RFID item-level tagging at retail and pharmaceutical scale competes on cent-per-unit landed cost. German automotive suppliers embed dual-protocol chips into electric vehicle battery packs for EU Green Deal digital passport compliance.
- Access Control:Physical security credentials for corporate and government facilities balance security tier with user convenience.
- Tracking Solutions:Asset location services combine RFID infrastructure with cloud-based analytics platforms.
Payment Systems generates the highest margin per unit, with Inventory Management expanding most quickly on volume scale.
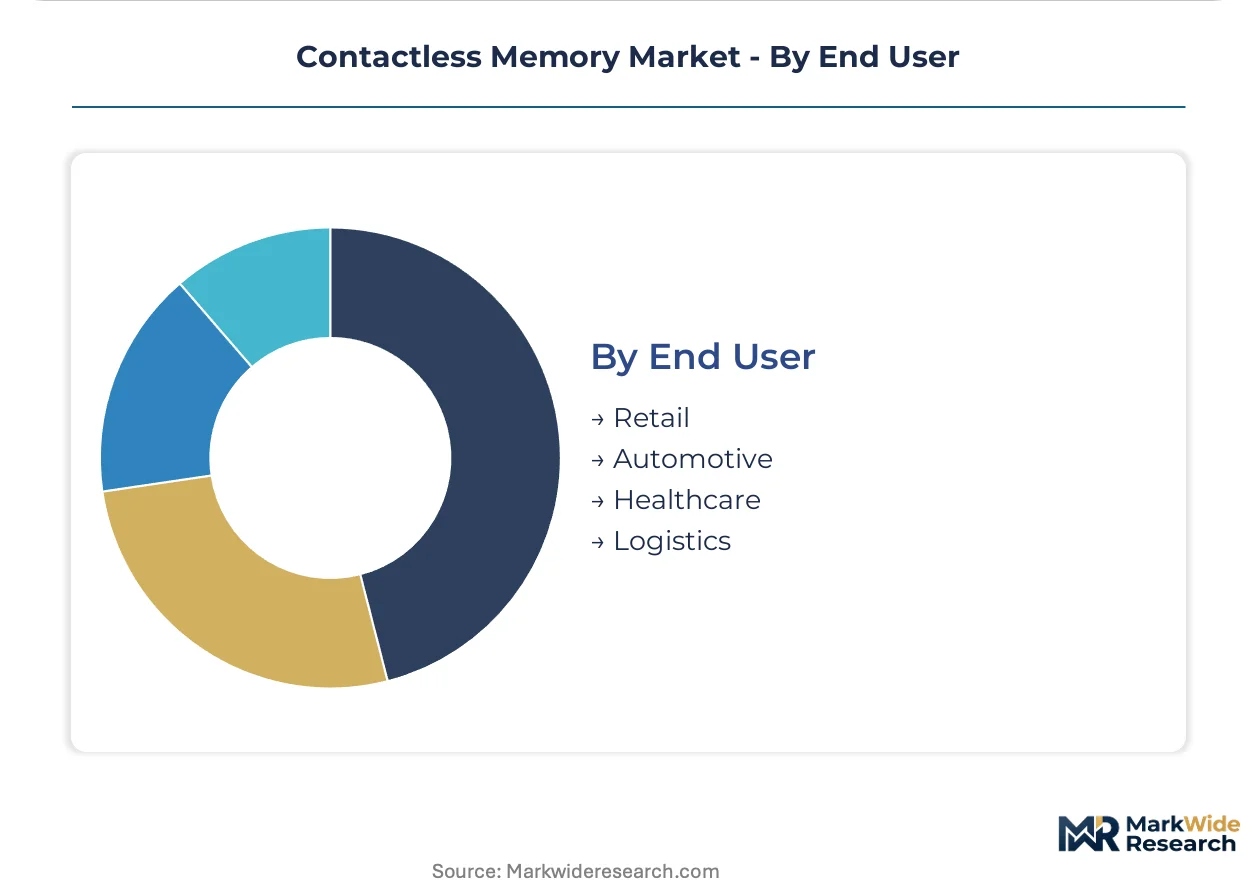
End User:
Customer procurement maturity varies from automotive Tier 1 technical specifications to healthcare network pilot programs still unbundling tag supply from system integration.
- Automotive:Keyless entry and immobilizer systems demand AEC-Q100 qualified components with zero-defect reliability targets. German OEMs anchor procurement volumes for high-frequency memory modules, with KBA type-approval processes gating market access.
- Healthcare:Surgical instrument tracking and patient identification are piloting NFC-enabled sterilization logs requiring high-temperature-resistant memory. German hospital procurement associations are directly negotiating volume commitments with semiconductor vendors, compressing margin for traditional inlay converters.
- Retail:Omnichannel fulfillment drives RFID source tagging mandates from major apparel chains.
- Logistics:Parcel and pallet tracking concentrates demand for disposable UHF inlays at postal and courier scale.
Automotive leads in qualification rigor and contract value, with Healthcare gaining share fastest as procurement models shift toward direct vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates automotive procurement volumes for high-frequency memory modules, while the United States drives payment terminal demand through EMVCo certification mandates. Regulatory divergence between ETSI cybersecurity standards and FCC Part 15 spectrum rules shapes distinct product architectures across these markets.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg anchor procurement for AEC-Q100 qualified transponders in keyless entry systems. KBA type-approval processes gate market access for passive entry components. The Stuttgart and Munich industrial clusters concentrate Tier 1 supplier relationships for high-reliability memory modules.
United States
FCC Part 15 rules constrain unlicensed RF emissions for contactless devices, shaping power levels and spectrum allocation decisions. Payment terminal OEMs in California and Texas drive EMVCo certification demand for secure-element supply. The Silicon Valley and Austin semiconductor corridors concentrate fabless design activity for NFC protocol stacks.
France
National e-ID programs mandate contactless smart card deployments with Common Criteria EAL5+ secure elements. ANSM and CNIL oversight extends to healthcare NFC applications for patient identification. The Paris-Saclay and Grenoble clusters concentrate secure-element architecture R&D for payment credentials.
China
MIIT governs radio frequency allocations for RFID and NFC devices through GB standards compliance requirements. Shanghai Fudan Microelectronics Group anchors domestic supply for smart card microcontroller production. The Yangtze River Delta and Pearl River Delta manufacturing corridors concentrate wafer-scale capacity for high-volume inlay production.
Japan
METI coordinates industrial IoT adoption policies that accelerate NFC-enabled asset tracking in factory automation. JIS standards govern electromagnetic compatibility for contactless devices in automotive and healthcare applications. The Kanto and Kansai metropolitan areas concentrate precision manufacturing for hybrid NFC-UHF dual-protocol chips.
Contactless Memory Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the contactless memory landscape. The market structure concentrates secure-element supply among semiconductor vendors with automotive qualification capabilities, while RFID inlay production fragments across converter networks. Three archetypes dominate: vertically integrated IDM houses with foundry ownership, fabless designers relying on outsourced manufacturing, and module integrators assembling finished credentials. Competitive moves center on Common Criteria certification pre-qualification and consignment inventory arrangements with hospital procurement associations.
Within the diversified semiconductor tier, NXP Semiconductors and Infineon Technologies occupy positions anchored by automotive-qualified NFC portfolios. STMicroelectronics exemplifies the R&D-intensive secure-element specialist model. These European-headquartered vendors represent the premium-tier vector where certification timelines and AEC-Q100 stress test compliance determine contract eligibility. Samsung Electronics sits within the scale-driven manufacturing archetype, leveraging captive wafer capacity for high-volume RFID production.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Infineon Technologies |
| STMicroelectronics |
| Samsung Electronics |
| Sony Corporation |
| Microchip Technology |
| Shanghai Fudan Microelectronics Group |
| IDEMIA |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal digital passport mandates gate qualified supply and premium-tier pricing access for contactless memory vendors serving electric vehicle battery traceability programs. Manufacturers lacking CE marking and AEC-Q100 certification face exclusion from procurement pools where German automotive OEMs anchor volume commitments.
Pricing Analysis
Capacity additions in East Asian foundry clusters are reshaping price floors for UHF RFID inlays while secure-element premiums hold firm. Three-tier pricing structure across certified secure elements, industrial-grade modules, and disposable logistics tags separates EMVCo-qualified supply from commodity proximity formats. Cost compression in UHF segments is intensifying because billion-unit retail serialization demands cent-per-unit landed costs. Healthcare networks exhibit lowest price sensitivity due to sterilization-log reliability requirements, while apparel chains drive hardest unit-cost negotiations.
Supply Chain Analysis
Single-source vulnerability sits with 300mm wafer fabrication concentrated in South Korea, Taiwan, and China. Advanced RFID inlay production draws from silicon wafers, printed antenna substrates, and flip-chip bonding equipment. Tariff exposure on semiconductor equipment imports threatens capacity expansion timelines for European fabless designers. Distribution runs through Tier 1 module integrators for automotive-qualified components and direct hospital procurement for healthcare NFC tags.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The contactless memory market functions as a stable compounder anchored by decade-long automotive qualification cycles that lock in supplier relationships and recurring replacement demand.
For Market Incumbents: Cement automotive supply relationships through AEC-Q100 qualification pipeline investments before KBA type-approval windows close. Deepen backward integration into 300mm wafer capacity to offset allocation risk from East Asian foundry concentration. Optical biometric substitution in premium smartphones threatens card-authentication volumes, demanding counter-positioning through healthcare asset-tracking diversification. For New Entrants and Emerging Players: German hospital procurement associations represent an underserved buyer archetype disintermediating traditional RFID inlay converters. White-space concentration sits with high-temperature-resistant NFC tags for surgical instrument sterilization logs and dual-protocol chips for EU Green Deal battery passport compliance. Direct semiconductor vendor contracting models offer entry without legacy converter relationships. For Investors and Strategic Acquirers: Roll-up economics work for secure-element specialists because Common Criteria certification timelines create moats that scale advantages compound across product lines. Five-to-ten-year viability rests on cryptographic architecture R&D intensity and automotive qualification track records. Watch EMVCo certification queue lengths as inflection indicator for secure-element supply tightness.| Strategic Initiative | Industry Significance |
|---|---|
| Common Criteria EAL5+ Certification Investment | Unlocks national e-ID program procurement in France and Germany under EU Cyber Resilience Act mandates. |
| Dual-Protocol Chip Development | Enables unified retail-supply-chain deployments combining NFC payment with UHF logistics tracking. |
| Healthcare Direct Procurement Partnership | Bypasses traditional inlay converter margins through consignment inventory with German hospital networks. |
| Foundry Capacity Reservation | Secures 300mm wafer allocation for high-volume RFID production amid East Asian supply concentration. |
| Post-Quantum Cryptographic Hardware R&D | Positions banking-grade secure elements against emerging quantum computing threats to legacy protocols. |
Research Methodology
Multiple input streams — semiconductor procurement directors at German automotive Tier 1 suppliers, hospital biomedical engineering leads, payment terminal OEM technical architects, and RFID inlay converter operations managers — were reconciled against SEC 10-K filings, EMVCo certification registries, KBA type-approval databases, and EU Cyber Resilience Act implementation guidance. Secondary validation drew from customs trade data for RFID inlay imports and AEC-Q100 qualification records. Bottom-up tag volume estimates and top-down secure-element revenue triangulation anchored market sizing.
Historical shipment trajectories were cross-referenced against panel input from NFC protocol stack engineers and secure-element architecture specialists. Segmentation modeling spanned product type, certification tier, application margin structure, and end-user procurement maturity. CAGRs were derived from protocol adoption curves and replacement cycle analysis. Forecast inputs incorporated automotive production schedules for keyless entry penetration and national e-ID program deployment timelines.
Underlying measurement precision varies by segment; Smart Cards and Payment Systems carry tighter precision than emerging Healthcare tracking applications. Forecasts reflect assumptions regarding EMVCo certification throughput, foundry capacity allocation, and EU regulatory implementation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
DDR RAM Market
Memory Chips
Mobile DRAM Market
Memory Chips
GDDR6 Market
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
DDR SDRAM Market
Memory Chips
In-Memory Grid Market
Memory Chips
Japan DRAM Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Static RAM Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
Memristor Market
Memory Chips
Automotive DRAM Market
Memory Chips
In-Memory Computing Market
Memory Chips
Memory Module Market