
 Global Dynamic Random Access Memory (DRAM) Market | 2026-2036
Global Dynamic Random Access Memory (DRAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dynamic Random Access Memory (DRAM) Market Foresight
South Korea's Pyeongtaek cluster expansion is reconfiguring global wafer start capacity. Samsung Electronics leverages its vertically integrated foundry-to-module pipeline to anchor supply for high-bandwidth memory stacks. SK hynix sustains process leadership in advanced lithography nodes for server-grade modules. Micron Technology navigates geopolitical licensing constraints while extending its Singapore and Japan manufacturing footprint.
Dynamic Random Access Memory consists of capacitive storage cells arranged in arrays, where each bit resides at the intersection of a word line and bit line; charge leakage necessitates refresh cycles every 64 milliseconds, with contemporary nodes fabricating cells at process geometries below 15 nanometers using extreme ultraviolet lithography. DDR5 and HBM2 command the highest margin pools as data centers and AI accelerators absorb premium bandwidth modules. Low Power DDR and LPDDR4X dominate mobile electronics volume, though Graphics DDR and GDDR6 segments are accelerating with gaming console refresh cycles and autonomous sensor fusion workloads.
REACH restricts fluorinated greenhouse gas emissions from etching chemistries used in DRAM fabrication, while CE marking mandates electromagnetic compatibility for modules sold across Europe. South Korea's Ministry of Trade, Industry and Energy enforces energy efficiency standards for fab operations exceeding designated power thresholds. Stakeholders must monitor export control alignment between the US Commerce Department, Japan's METI, and China's MIIT as equipment licensing rules fragment supply chain predictability.
Market Dynamics
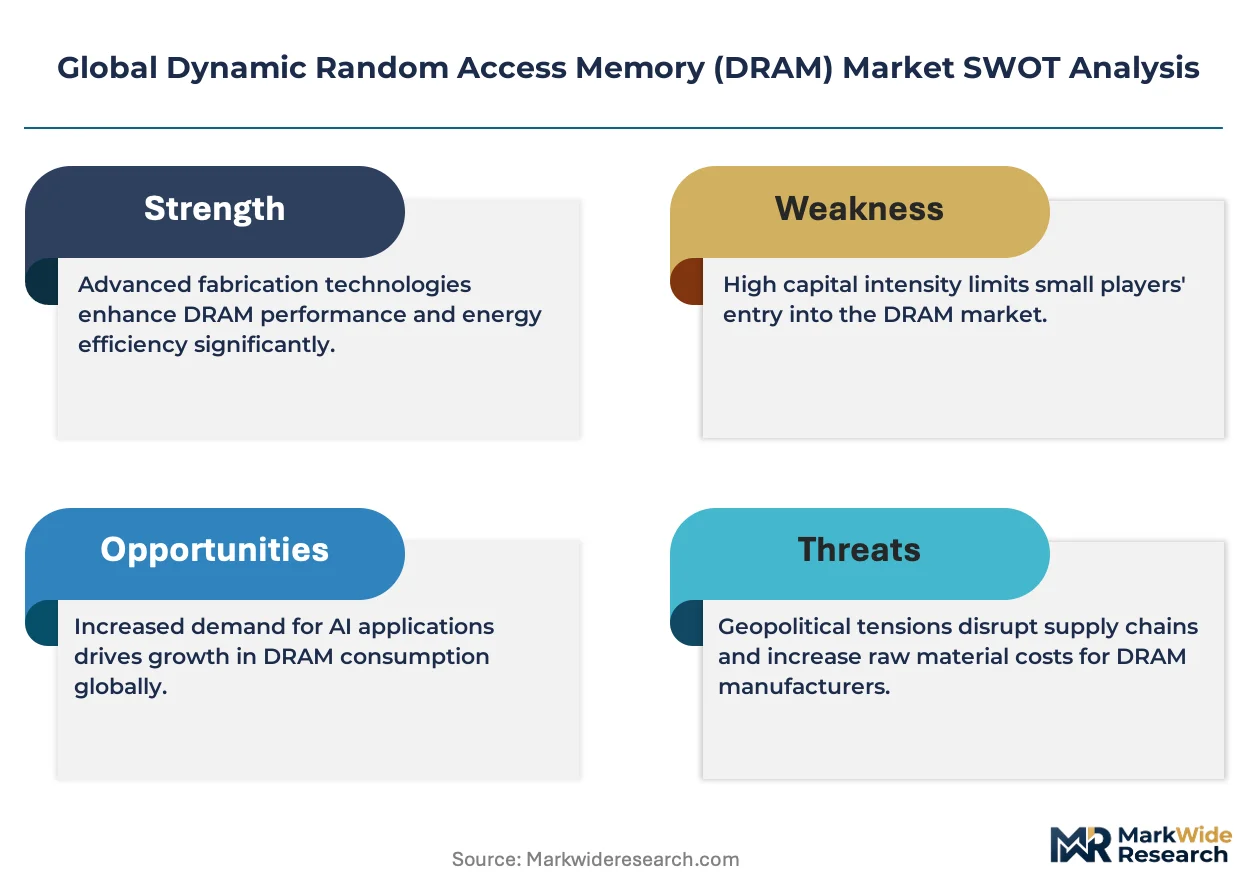
High-bandwidth memory stacks for generative AI training clusters are compressing traditional DDR5 procurement timelines while fabs absorb extreme ultraviolet lithography capex loads exceeding prior node transitions.
Growth Catalysts
- Generative AI Training Clusters:Cloud service providers are expanding memory procurement for large language model infrastructure, pulling advanced node wafer starts toward server-grade HBM2E and HBM3 stacks.
- China's Dual Carbon Mandates:Process efficiency requirements under MIIT directives are accelerating fab energy retrofits and renewable power purchase agreements for semiconductor manufacturing.
- Automotive Sensor Fusion:GDDR6 modules are penetrating autonomous vehicle compute platforms as sensor data throughput requirements multiply frame processing demands.
Market Restraints
- Fluorinated Gas Restrictions:REACH F-Gas Regulation and EU emissions caps are constraining etching chemistry availability, elevating wet process transition costs for European fabs.
- Equipment Licensing Fragmentation:Export control misalignment between US Commerce Department, Japan's METI, and China's MIIT is injecting lead time volatility into lithography tool procurement.
- Charge Leakage Physics:Sub-15 nanometer cell geometries face fundamental retention time degradation, mandating more frequent refresh cycles that degrade effective bandwidth.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor assembly and testing are attracting module packaging investment outside traditional East Asian concentration.
- EU AI Act Compliance:Transparency requirements for high-risk AI systems are creating certified memory traceability demand that premium module suppliers can capture.
- Edge AI Inference:LPDDR5X integration with neural processing units in smartphones and industrial gateways is opening low-power, high-density sockets outside data center concentration.
Industry Challenges
- EUV Photoresist Chemist Shortage:Specialized formulation expertise for extreme ultraviolet layers is concentrated among Japanese and US suppliers, constraining node migration timelines.
- Legacy DDR4 Inventory Absorption:Data center refresh cycles are lagging protocol transition forecasts, trapping working capital in depreciating module stockpiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dynamic Random Access Memory (DRAM) Market |
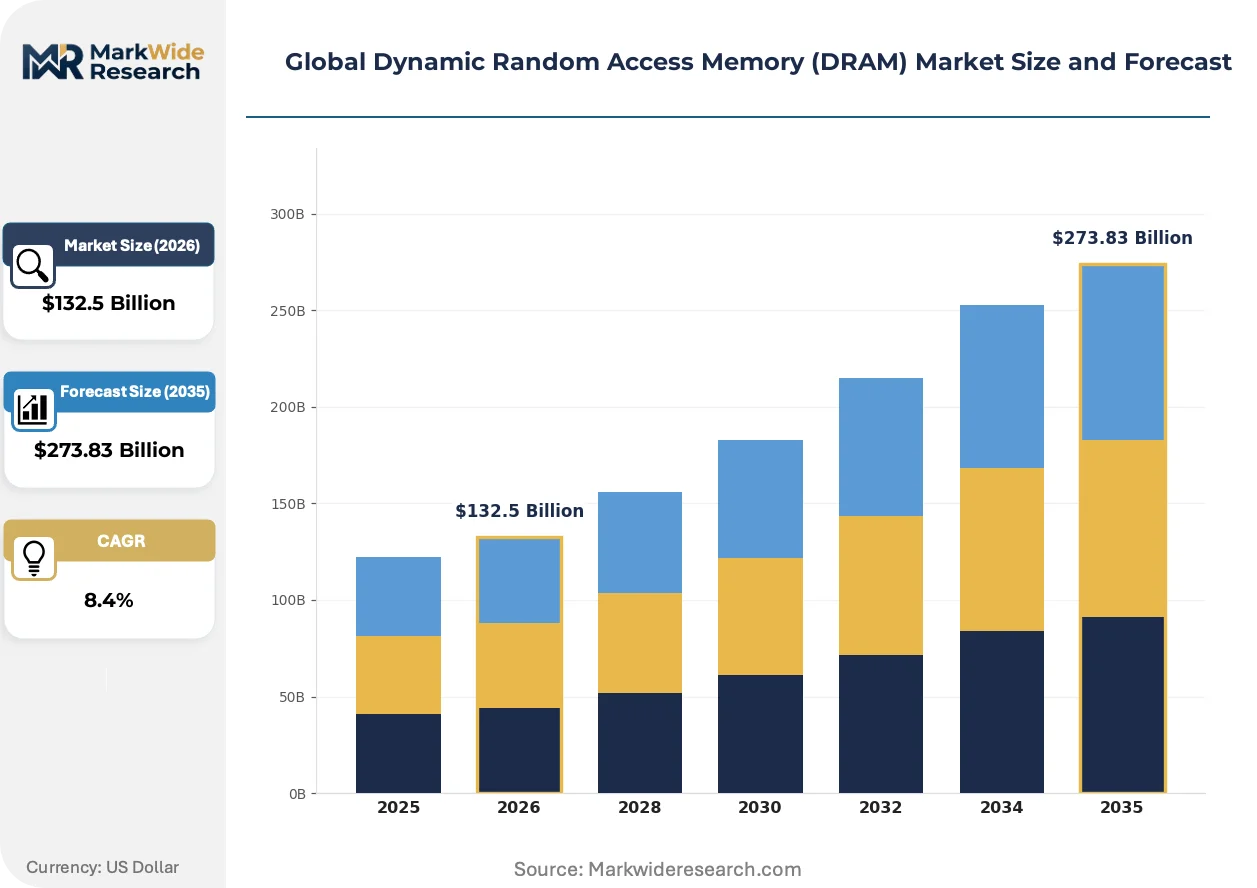
| Market Size in 2026 | $132.5 Billion |
| Market Size in 2035 | $273.83 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synchronous DRAM, Double Data Rate SDRAM, Low Power DDR, Graphics DDR, Rambus DRAM, Wide I/O DRAM Technology: DDR3, DDR4, DDR5, LPDDR4X, GDDR6, HBM2 Application: Desktop Computing, Server Solutions, Mobile Electronics, Networking Equipment, Gaming Consoles, Artificial Intelligence Systems End User: Original Design Manufacturers, Cloud Service Providers, Telecommunications Operators, Data Centers, Consumer Electronics Corporations, Semiconductor Foundries |
| Companies Covered | ChangXin Memory Technologies, Winbond Electronics, SK hynix, Infineon Technologies, Powerchip Semiconductor Manufacturing, Samsung Electronics, Nanya Technology, UniBetter, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dynamic Random Access Memory (DRAM) Market Shifts & Advancements
Process-node compression and regulatory emissions accounting are rewiring competitive advantage sources across wafer fabrication and module assembly stages.
Hybrid bonding die-stacking is collapsing the interconnect pitch between memory layers, enabling 12-high and 16-high HBM configurations. AI accelerator vendors at NVIDIA and AMD are qualifying these stacks for 2024-2025 training cluster deployments. The technology is collapsing the bandwidth-per-watt gap between discrete GDDR and stacked memory architectures.
EU F-Gas Regulation phase-down schedules are forcing etching chemistry substitution toward C4F6 and C5F8 alternatives with lower global warming potential. Korean and Taiwanese fabs are retrofitting abatement systems ahead of 2027 compliance deadlines. Server-grade module production in European-bound supply chains faces elevated process certification burdens.
Hyperscaler direct procurement of raw wafer capacity is displacing traditional distributor-mediated module purchasing. Amazon Web Services and Microsoft Azure are contracting foundry slot years in advance, compressing spot market liquidity for enterprise OEMs. This pattern concentrates most visibly in South Korea's Pyeongtaek and Yongin fab clusters where Samsung and SK hynix anchor supply.
Global Dynamic Random Access Memory (DRAM) Market Segmentation
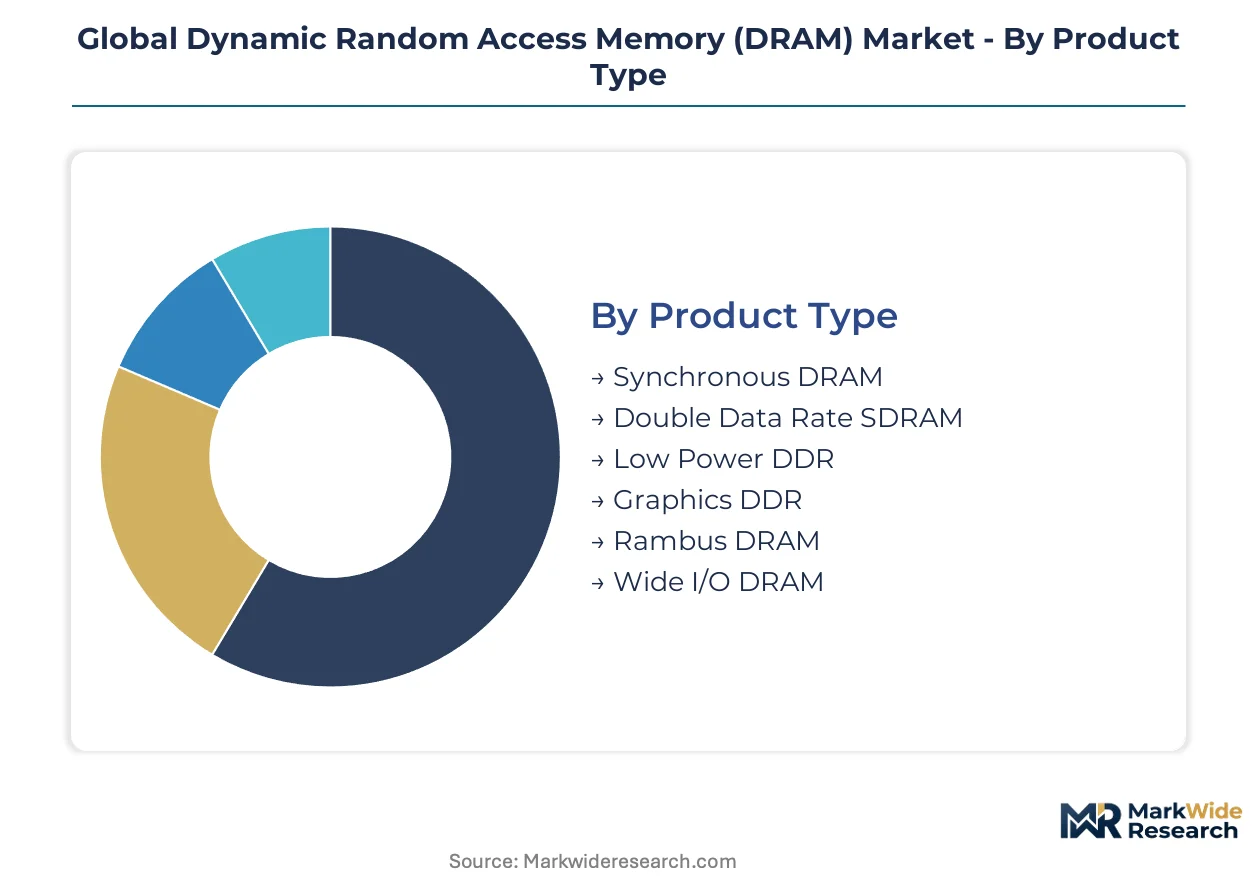
DRAM segmentation reveals divergent replacement cycles across product architectures, with mobile and graphics modules turning over fastest while server infrastructure locks in multi-year refresh windows. Technology node transitions and application-specific bandwidth requirements create distinct procurement rhythms that suppliers must synchronize against foundry allocation schedules.
Product Type:
Cycle times stretch from 18-month smartphone refresh cadences to 5-year server infrastructure lock-ins, compressing margin capture windows for volatile segments while stabilizing long-tail revenue pools.
- Double Data Rate SDRAM:DDR5 modules operate at 4800 MT/s to 8400 MT/s with on-die error correction, channeling demand from data centers in Virginia and Frankfurt where AI training clusters consume terabyte-scale configurations. Supply bottlenecks at extreme ultraviolet lithography nodes constrain die availability for high-density server DIMMs.
- Low Power DDR:LPDDR5X devices achieve 8533 MT/s at sub-1V operating voltage, dominating smartphone BOMs from Samsung Electronics and Apple supply chains in South Korea and China. Mobile OEM procurement cycles align with annual flagship release schedules, creating predictable Q3 demand spikes.
- Synchronous DRAM:Legacy SDRAM persists in industrial control systems and automotive ECUs where certification timelines resist protocol migration.
- Graphics DDR:GDDR6X variants serve discrete GPU attach rates tied to NVIDIA and AMD product ramps, with gaming console refresh cycles from Sony and Microsoft anchoring volume predictability.
- Rambus DRAM:RDRAM architectures retain niche deployment in high-performance computing clusters requiring deterministic latency profiles.
- Wide I/O DRAM:3D-stacked Wide I/O2 interfaces enable 512-bit memory buses for mobile application processors, penetrating premium smartphone tiers in Shenzhen and Taipei design houses.
Double Data Rate SDRAM dominates installed base. Low Power DDR is where expansion concentrates.
Technology:
Cost tiers separate mature-node commodity production from leading-edge premium stacks, with lithography equipment amortization driving 40-60% die cost differentials between DDR4 and HBM generations.
- HBM2:High-bandwidth memory stacks integrate 4 to 8 dies with through-silicon vias, delivering 307 GB/s to 460 GB/s per stack for AI accelerators at Google Cloud and Microsoft Azure. Hybrid bonding advances enable 12-high configurations that collapse interconnect power consumption below 1.2 pJ/bit.
- DDR5:Fifth-generation modules incorporate decision feedback equalization and on-die power management, supporting 128 GB DIMMs for hyperscaler server farms in Singapore and Dublin. Intel Sapphire Rapids and AMD EPYC platform qualifications determine socket penetration velocity.
- DDR4:Mature 1y-nm and 1z-nm production lines in Micron's Singapore fabs service enterprise IT refresh cycles trailing cloud adoption by 18 to 24 months.
- LPDDR4X:Low-power variants at 4266 MT/s saturate mid-tier smartphone and tablet configurations where LPDDR5 penetration remains cost-constrained.
- DDR3:Legacy 20nm-class production continues for automotive infotainment and networking equipment with extended qualification requirements.
- GDDR6:Graphics-focused 16 Gb/s signaling supports ray-tracing workloads in PC gaming and autonomous vehicle sensor fusion platforms.
DDR4 retains volume leadership in shipment terms. HBM2 is climbing the fastest in revenue contribution.
Application:
Volume concentration splits between billion-unit mobile electronics and thousand-unit AI system deployments, with per-socket value spreading across four orders of magnitude from handsets to training clusters.
- Artificial Intelligence Systems:Training clusters deploy HBM2E and HBM3 stacks in 80 GB to 192 GB GPU memory configurations, with NVIDIA DGX systems and Google TPU pods driving foundry slot commitments two years forward. Memory bandwidth, not capacity, limits model scaling at trillion-parameter thresholds.
- Mobile Electronics:Smartphones integrate 8 GB to 16 GB LPDDR5X packages in stacked-package-on-package configurations, with Apple A-series and Qualcomm Snapdragon launches determining quarterly bit demand from SK hynix and Samsung Electronics.
- Server Solutions:General-purpose compute servers absorb DDR5 RDIMMs and LRDIMMs for virtualization workloads, with Amazon Web Services and Microsoft Azure direct procurement displacing distributor channels.
- Gaming Consoles:GDDR6 unified memory architectures in PlayStation 5 and Xbox Series X sustain 16 GB configurations through mid-cycle refreshes.
- Desktop Computing:PC OEM demand channels through DDR4 and DDR5 SO-DIMM and UDIMM modules, with enterprise refresh cycles lagging consumer adoption by 12 to 18 months.
- Networking Equipment:Router and switch buffer memory relies on RLDRAM and reduced-latency DDR variants for packet processing determinism.
Mobile Electronics commands unit volume leadership. Artificial Intelligence Systems is gaining share fastest on value terms.
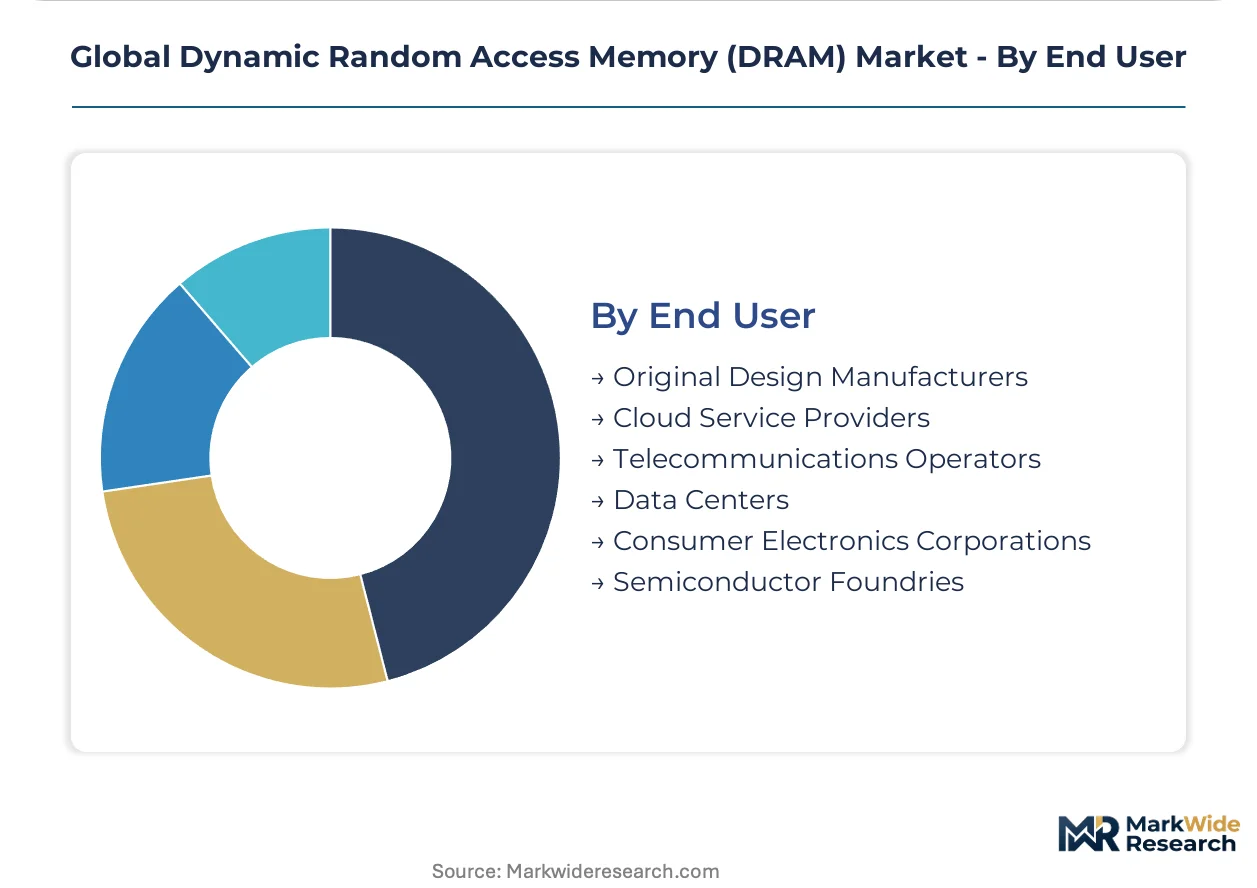
End User:
Customer type determines procurement modality, with cloud service providers contracting wafer-level capacity while consumer electronics corporations purchase finished modules through distribution.
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Google Cloud Platforms negotiate multi-year foundry slot agreements directly with Samsung Electronics and SK hynix, securing HBM2E and DDR5 supply for training cluster buildouts. Spot market participation has collapsed for server-grade modules.
- Data Centers:Enterprise colocation operators and hyperscale self-build facilities procure RDIMMs through integrators like Dell Technologies and HPE, with qualification timelines extending 6 to 9 months for new module suppliers.
- Original Design Manufacturers:Foxconn, Quanta, and Wistron purchase DRAM components for notebook and server assembly, consolidating procurement across multiple OEM customers to achieve volume pricing.
- Consumer Electronics Corporations:Apple, Samsung Mobile, and Xiaomi negotiate LPDDR supply through package-on-package assembly houses in Taiwan and Vietnam.
- Telecommunications Operators:5G baseband unit deployments drive demand for industrial-temperature DDR4 modules with 10-year supply guarantees.
- Semiconductor Foundries:Pure-play foundries including TSMC and GlobalFoundries consume DRAM for test vehicle and process development wafer requirements.
Original Design Manufacturers dominate shipment volume. Cloud Service Providers is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Ministry of Trade, Industry and Energy enforces energy efficiency standards that shape fab operations across the dominant semiconductor belt. National regulators in China, Japan, the United States, and Germany impose distinct emissions and export control frameworks that fragment equipment procurement timelines.
China
MIIT dual carbon mandates accelerate renewable power purchase agreements for fabs in the Yangtze River Delta. The country's national semiconductor regulator enforces process efficiency benchmarks exceeding designated power thresholds. Shanghai and Wuxi clusters absorb extreme ultraviolet lithography capex loads for advanced node migration.
Japan
METI export licensing alignment with US Commerce Department rules constrains lithography tool lead times for memory fabricators. The country's national industrial regulator coordinates fluorinated gas abatement retrofits ahead of 2027 compliance deadlines. Yokohama and Kyoto host specialized photoresist formulation expertise concentrated among domestic suppliers.
United States
US Commerce Department export controls fragment equipment licensing predictability for fabs serving AI training clusters. EPA emissions frameworks intersect with state-level renewable portfolio standards in Arizona and Texas. Intel's New Mexico and Oregon fabs anchor domestic advanced packaging capacity alongside emerging memory module assembly.
Germany
REACH F-Gas Regulation phase-down schedules force etching chemistry substitution toward lower global warming potential alternatives. The country's national chemical regulator enforces electromagnetic compatibility mandates for modules sold across Europe. Dresden's silicon cluster hosts memory test vehicle production for automotive qualification timelines.
Singapore
Enterprise Singapore incentives attract module packaging investment outside traditional East Asian concentration zones. The country's national trade regulator enforces semiconductor assembly standards aligned with ASEAN mutual recognition frameworks. Woodlands and Pasir Ris industrial zones host backend operations for enterprise IT refresh cycles.
Global Dynamic Random Access Memory (DRAM) Market Competitive Landscape
Vertically integrated conglomerates and specialized memory fabricators split the market into distinct capability tiers. The structure concentrates around three players commanding advanced lithography nodes and high-bandwidth memory stacks. Strategic archetypes span captive foundry-to-module pipelines, pure-play memory specialists, and diversified semiconductor conglomerates. Dominant competitive moves include multi-year foundry slot pre-commitments and hybrid bonding die-stacking technology licensing.
Within the vertically integrated tier, Samsung Electronics and SK hynix occupy positions anchoring supply for server-grade configurations. Micron Technology exemplifies the geographically diversified archetype with manufacturing footprint extending beyond the Korean peninsula. ChangXin Memory Technologies represents the emerging domestic champion model within China's semiconductor self-sufficiency framework.
| Leading Market Players |
|---|
| ChangXin Memory Technologies |
| Winbond Electronics |
| SK hynix |
| Infineon Technologies |
| Powerchip Semiconductor Manufacturing |
| Samsung Electronics |
| Nanya Technology |
| UniBetter |
| Micron Technology |
| Others |
Supply & Pricing Matrix
Overcapacity signals from South Korea's Pyeongtaek fab cluster are forcing suppliers into inventory absorption mode while simultaneously defending premium pricing for HBM2E and HBM3 stacks. This utilization tension compresses margins on mature-node DDR4 production while reinforcing pricing power at the advanced lithography frontier.
Pricing Analysis
Geographic price spreads between South Korean contract pricing and spot-market Singapore quotations widen during periods of EUV equipment delivery uncertainty. Three-tier pricing structure across premium HBM stacks, standard DDR5 server modules, and economy DDR4 mobile chips reflects lithography node amortization differentials. Pricing pressure stems from legacy DDR4 inventory overhang as data center refresh cycles lag protocol migration forecasts. Cloud service providers exhibit lowest price sensitivity through multi-year foundry slot commitments, while consumer electronics OEMs negotiate aggressively on LPDDR5X package costs.
Supply Chain Analysis
Tariff exposure between US Commerce Department licensing restrictions and Japan's METI export controls dominates equipment procurement risk for advanced node migration. Supply concentrates in South Korea, Taiwan, and Japan for front-end wafer fabrication, with Singapore and Vietnam hosting backend module assembly. Raw material dependencies include high-purity silicon wafers, extreme ultraviolet photoresists, and fluorinated etching chemistries constrained by REACH F-Gas phase-down schedules. Single-source vulnerability characterizes EUV lithography tool availability. Distribution runs through direct hyperscaler procurement for server-grade modules, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats rooted in switching costs: AI accelerator vendors face multi-year qualification timelines for alternative memory suppliers, locking in incumbent relationships.
For Market Incumbents: Pre-empt emerging Chinese domestic champions by accelerating hybrid bonding die-stacking R&D and securing renewable power purchase agreements ahead of MIIT dual carbon enforcement. Defend HBM2E socket positions at NVIDIA and AMD through captive foundry capacity allocation. Expand Pyeongtaek and Yongin fab utilization to absorb fixed costs while trapping ChangXin Memory Technologies at trailing-edge nodes.
For New Entrants and Emerging Players: Build out India-based module packaging capacity under PLI scheme incentives to capture enterprise IT refresh cycles outside Korean supply concentration. Target automotive sensor fusion applications for GDDR6 modules where qualification barriers remain lower than data center server sockets. Pursue direct relationships with Foxconn and Quanta as ODM procurement consolidators.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud service provider direct procurement contracts with Samsung Electronics and SK hynix. Long-term viability centers on extreme ultraviolet lithography node access and HBM stack yield mastery. Monitor EUV photoresist formulation supplier consolidation as the inflection signal for node migration timeline risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Die-Stacking Scale-Up | Enables 12-high HBM configurations for NVIDIA DGX and Google TPU deployments. |
| Renewable Power Purchase Agreements | Secures MIIT compliance for Pyeongtaek and Yongin fab operations under dual carbon mandates. |
| Direct Hyperscaler Procurement Contracts | Locks multi-year foundry slots with Amazon Web Services and Microsoft Azure. |
| India PLI Scheme Module Assembly Investment | Diversifies backend capacity outside traditional East Asian concentration zones. |
| Photoresist Formulation Supplier Partnerships | Mitigates EUV layer expertise concentration among Japanese and US suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, hyperscaler capex disclosures, and customs trade data. Interviews with DRAM procurement executives at cloud service providers, fab operations directors, and ODM supply chain managers informed capacity utilization and pricing dynamics. Secondary validation drew from equipment supplier order books, foundry slot allocation announcements, and regulatory filings with the US Commerce Department and Japan's METI. Bottom-up die cost modeling and top-down market sizing triangulated volume and value estimates.
Forecast inputs incorporate wafer start capacity by technology node, AI accelerator attach rates for HBM stacks, and mobile OEM flagship release cadences. Segmentation dimensions span product architecture, lithography generation, application workload, and end-user procurement modality. CAGRs derive from foundry capacity expansion schedules against demand elasticity for server-grade and mobile modules. Extreme ultraviolet lithography tool delivery timelines and REACH F-Gas compliance deadlines factor as supply-side constraints.
Sensitivities concentrate around export control alignment between US, Japanese, and Chinese regulators, EUV equipment delivery delays, and charge leakage physics degradation at sub-15 nanometer geometries. Forecasts reflect assumptions on node migration velocity and hyperscaler capital commitment durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
ECC Memory Market
Memory Chips
eMMC Master Control Chip Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
Europe Dynamic Random Access Memory (DRAM) Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
Memristor Market
Memory Chips
Automotive Memory Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
Memory Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
New RAM Market
Memory Chips
Memory Chip Market
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
Static RAM Market