
 Cleanroom Particle Counters Market | 2026-2036
Cleanroom Particle Counters Market Size, Share, and Industry Trends Forecast 2026-2036
Cleanroom Particle Counters Market Insights
The gap between optical sensing and laser diffraction architectures is narrowing as manufacturers converge on multi-wavelength detection platforms. TSI Inc leverages its aerosol science heritage to anchor premium handheld portfolios for biotechnology labs. Lighthouse Worldwide Solutions sustains dominance in continuous monitoring installations across semiconductor cleanrooms. Particle Measuring Systems specializes in regulatory-compliant calibration protocols that pharmaceutical clients require for FDA submissions.
Cleanroom particle counters are precision instruments that detect and quantify airborne particulate contamination using light scattering or laser diffraction principles, with sensitivity thresholds typically spanning 0.1 to 10.0 micrometers to validate ISO 14644-1 classification compliance. These devices serve as critical quality control infrastructure in environments where particulate intrusion risks product sterility, wafer yield, or aerospace component integrity. Continuous monitoring systems command the highest installed base in semiconductor fabrication due to real-time yield protection requirements, while handheld units represent the fastest-expanding category as field audit protocols multiply across pharmaceutical processing. Remote sampling configurations increasingly displace manual methods in biotechnology labs seeking to minimize human-borne contamination during viable particle enumeration.
FDA cGMP guidelines, EMA Annex 1 sterile manufacturing requirements, and ISO 14644-1 cleanroom classification standards collectively dictate instrument sensitivity thresholds, calibration frequencies, and data integrity protocols that shape procurement specifications. The EU AI Act and CSRD reporting frameworks are beginning to influence how particle counter manufacturers document algorithmic transparency in automated classification software. Stakeholders must monitor whether emerging pharmaceutical serialization mandates and semiconductor export controls will redirect capital expenditure toward domestic metrology infrastructure.
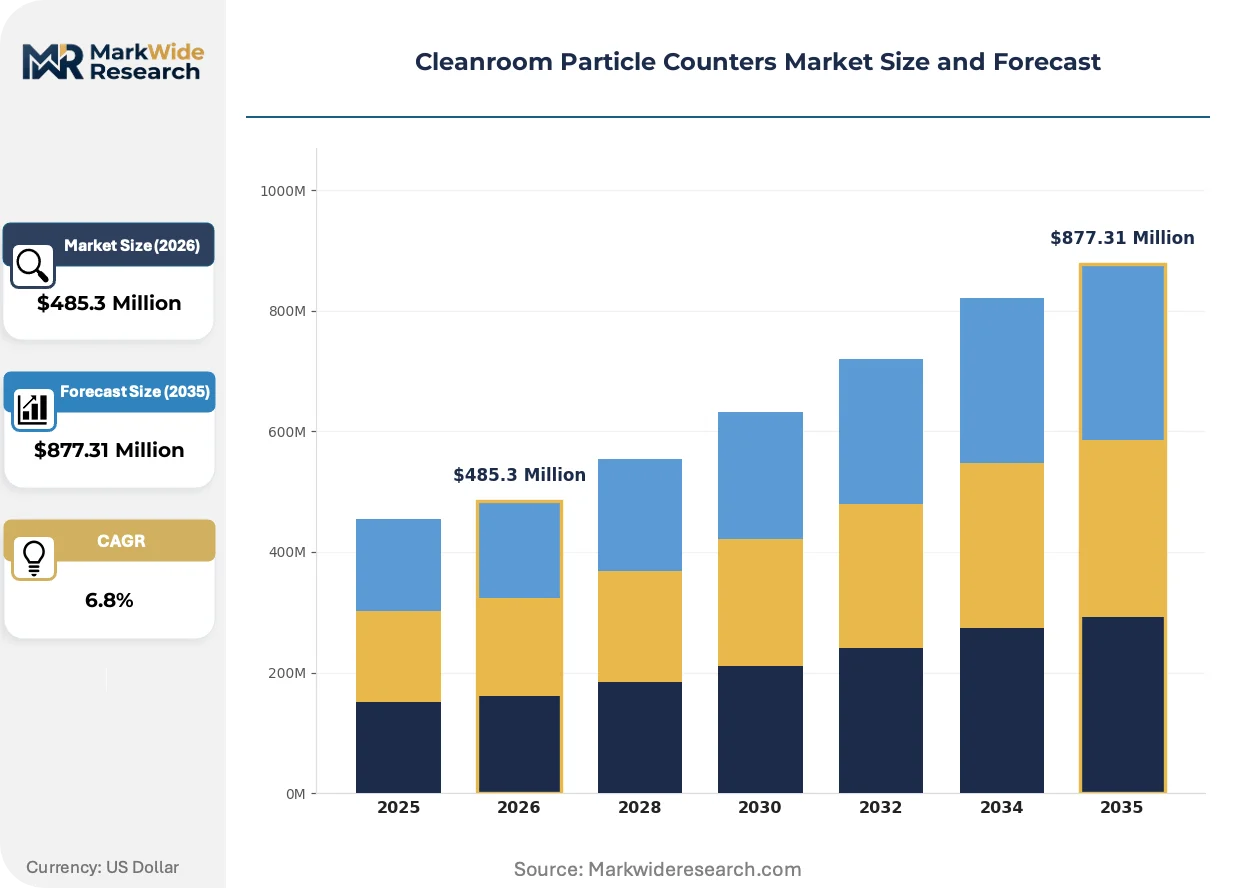
Market Dynamics
The transition to sub-3nm EUV lithography nodes in semiconductor fabrication is compressing permissible particle thresholds by an order of magnitude, forcing metrology infrastructure upgrades across Taiwan, South Korea, and the United States.
Growth Catalysts
- FDA cGMP sterile manufacturing mandates:Tightening particle thresholds in aseptic filling suites are compelling pharmaceutical facilities in New Jersey, North Carolina, and Massachusetts to deploy continuous monitoring architectures.
- EUV node shrinkage:Semiconductor foundries operating below three nanometers require 0.1-micrometer sensitivity thresholds that legacy optical systems cannot satisfy.
- EMA Annex 1 revision:The updated sterile manufacturing guidance mandates real-time viable particle enumeration, displacing manual sampling methods in biotechnology cleanrooms.
Market Restraints
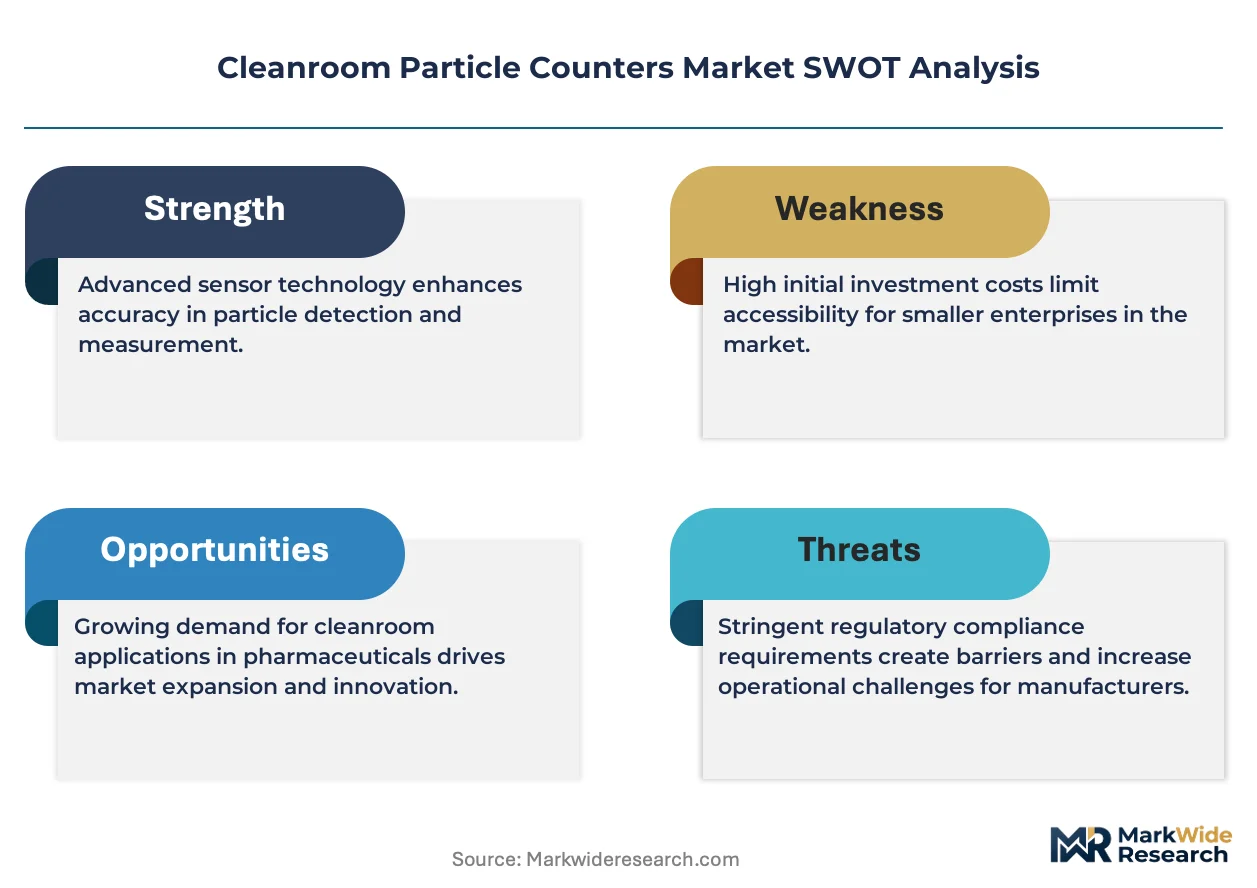
- Helium-neon laser supply concentration:Single-source dependency on Japanese gas laser manufacturers creates vulnerability for diffraction-based particle counter production.
- Calibration infrastructure scarcity:ISO 17025-accredited facilities capable of traceable 0.1-micrometer calibration remain concentrated in Germany, the United States, and Japan.
- Photodetector cost volatility:Avalanche photodiode pricing fluctuates with compound semiconductor wafer allocation priorities in RF communications markets.
Strategic Opportunities
- India pharmaceutical corridor expansion:CDSCO alignment with PIC/S standards is creating demand for regulatory-compliant particle monitoring in Hyderabad and Ahmedabad manufacturing clusters.
- Multi-wavelength convergence:Integration of optical scattering with laser-induced fluorescence enables simultaneous viable and non-viable particle detection in single-instrument platforms.
- EU AI Act algorithmic transparency:Automated classification software documentation requirements favor vendors with established validation protocols for pharmaceutical audit trails.
Industry Challenges
- Metrology talent scarcity:Cross-disciplinary expertise spanning aerosol physics, photonics, and regulatory compliance remains concentrated among a narrow cohort of specialists in Boston, Stuttgart, and Tokyo.
- Legacy system integration friction:BACnet and Modbus protocol mismatches between 1990s-era building management systems and modern particle counter networks extend commissioning timelines in renovated pharmaceutical suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleanroom Particle Counters Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Portable, Continuous Monitoring, Remote Sampling Technology: Light Scattering, Laser Diffraction, Electrostatic, Optical Sensing Application: Pharmaceutical Processing, Semiconductor Fabrication, Aerospace Assembly, Food & Beverage Production End User: Biotechnology Labs, Electronics Manufacturers, Research Institutes, Clean Manufacturing Facilities |
| Companies Covered | TSI Inc, Lighthouse Worldwide Solutions, Rion Co., Ltd, Spectris Plc, Danaher Corporation, Particle Measuring Systems, Met One Instruments, Inc, Particle Plus, Inc, PAMAS Partikelmess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleanroom Particle Counters Market Trends and Innovations
Detection architectures are converging on multi-parameter platforms while regulatory frameworks harden data integrity requirements. Three developments are compressing traditional category boundaries.
Solid-state laser diodes are collapsing the cost-performance gap that historically separated portable handheld units from fixed continuous monitoring installations. Biotechnology field audit teams in Massachusetts and North Carolina are adopting these platforms for viable particle enumeration without sacrificing the sensitivity thresholds previously reserved for semiconductor cleanrooms. The distinction between laboratory-grade and field-deployable instrumentation is dissolving as wavelength stability in compact packages matches legacy gas laser performance.
EMA Annex 1 sterile manufacturing revisions are mandating continuous viable particle monitoring in Grade A and B environments, eliminating manual sampling as a primary compliance method. Pharmaceutical manufacturers in Ireland and Germany are retrofitting aseptic filling lines with remote sampling configurations to minimize human-borne contamination during intervention operations. The regulation is compressing procurement cycles as facilities race to validate new infrastructure before enforcement deadlines.
Service unbundling is fragmenting traditional instrument-vendor relationships as pharmaceutical quality departments seek independent calibration and validation providers. Third-party metrology laboratories in New Jersey and Switzerland are capturing recurring revenue streams that manufacturers previously monopolized through captive service contracts. This pattern is most pronounced among mid-cap biotechnology firms with limited internal metrology capabilities but stringent FDA submission requirements.
Cleanroom Particle Counters Market Segmentation
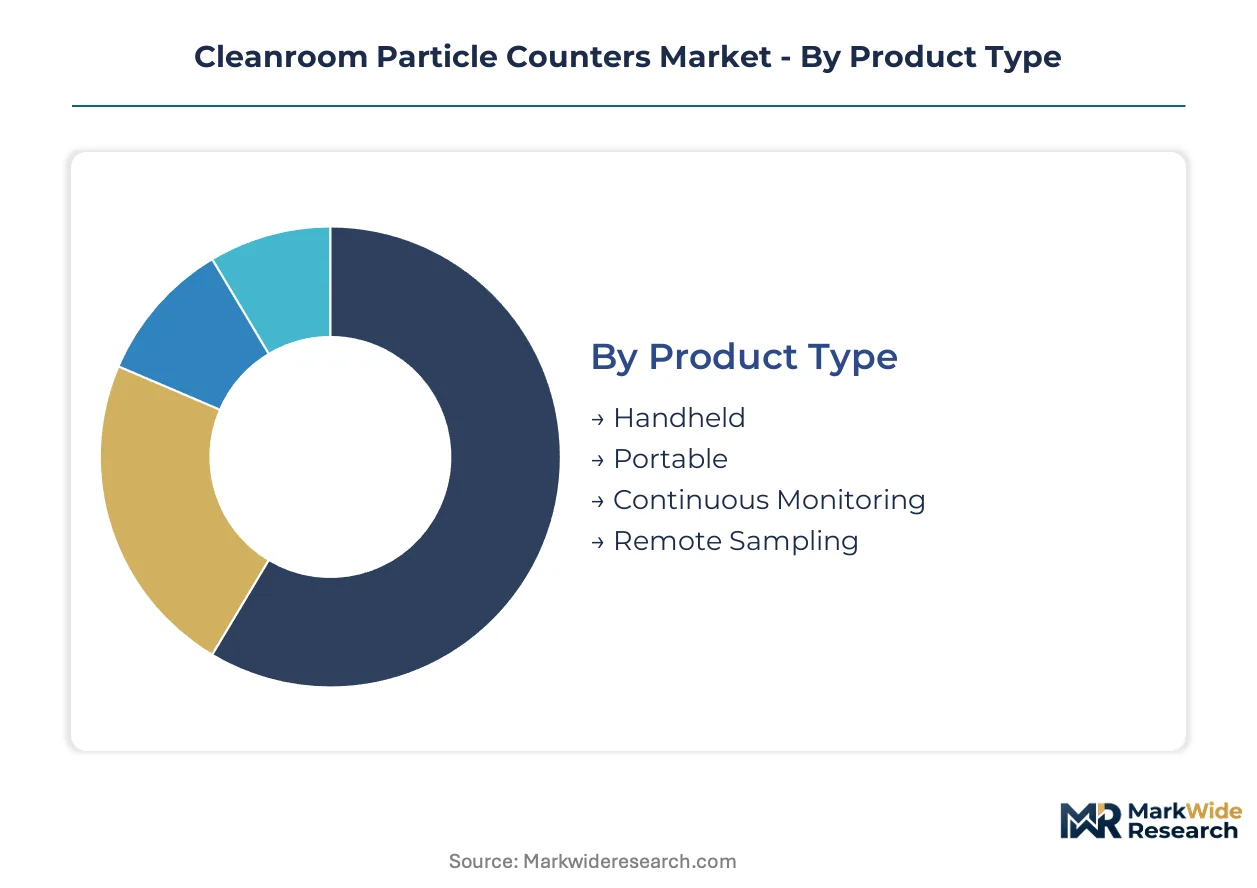
Particle counter procurement patterns diverge sharply across deployment contexts, with semiconductor fabs prioritizing capital-intensive continuous monitoring while pharmaceutical auditors drive handheld replacement cycles. Calibration dependencies and regulatory validation requirements create distinct service revenue profiles for each segment category.
Product Type:
After-sales service intensity varies dramatically across product formats, with continuous monitoring systems generating multi-year calibration contracts while handheld units concentrate replacement demand in field audit teams.
- Continuous Monitoring:Fixed installations integrate with facility building management systems through BACnet or Modbus protocols, requiring quarterly ISO 17025-accredited calibration cycles. Taiwan and South Korea semiconductor foundries deploy these systems at EUV lithography nodes below three nanometers where real-time yield protection justifies premium service contracts.
- Handheld:Battery-operated units with solid-state laser diodes now match laboratory-grade sensitivity thresholds. Massachusetts and North Carolina biotechnology field auditors are replacing legacy optical units for viable particle enumeration during unannounced facility inspections.
- Portable:Mobile carts bridge fixed and handheld applications with wheeled sampling heads. Pharmaceutical suites in New Jersey deploy these for periodic reclassification studies without permanent infrastructure commitment.
- Remote Sampling:Configurations extend particle detection into Grade A aseptic filling environments through isokinetic sampling probes. EMA Annex 1 revisions are mandating these systems to eliminate human-borne contamination during intervention operations.
Continuous monitoring holds the largest share; momentum sits with handheld units.
Technology:
Cost tiers separate mature optical methods from precision laser architectures, with sensitivity thresholds and photodetector specifications determining end-use access.
- Laser Diffraction:Multi-wavelength platforms achieve 0.1-micrometer detection thresholds through avalanche photodiode arrays. Semiconductor fabrication in Taiwan and South Korea depends on these systems for sub-3nm node validation where particle-induced defects destroy wafer yield.
- Light Scattering:Single-wavelength optical detection remains cost-effective for ISO 14644-1 compliance verification in less critical environments. Food and beverage packaging facilities in Germany leverage these systems for HACCP-aligned environmental monitoring.
- Optical Sensing:Compact diode-based architectures are collapsing price-performance gaps between field and laboratory applications. Biotechnology startups in Boston are adopting these for initial cleanroom qualification before scaling to continuous monitoring.
- Electrostatic:Charge-based detection targets specific conductive particle populations in aerospace composite manufacturing. Clean manufacturing facilities in Toulouse and Hamburg deploy these for carbon fiber dust monitoring during layup operations.
Laser diffraction commands premium pricing; optical sensing is climbing the fastest.
Application:
Volume concentration follows regulatory stringency, with sterile manufacturing mandates outpacing general industrial hygiene requirements.
- Pharmaceutical Processing:Aseptic filling suites in New Jersey, North Carolina, and Massachusetts face FDA cGMP particle threshold compression. Continuous viable monitoring is displacing manual sampling methods ahead of enforcement deadline alignment.
- Semiconductor Fabrication:EUV lithography nodes below three nanometers require metrology infrastructure capable of detecting particles at 0.1 micrometers. Taiwan and South Korea foundries are expanding capital budgets for multi-parameter detection platforms.
- Aerospace Assembly:Composite manufacturing cleanrooms monitor conductive dust during carbon fiber layup operations. Toulouse and Hamburg facilities integrate electrostatic detection with standard optical methods.
- Food & Beverage Production:HACCP-aligned environmental monitoring in dairy and beverage packaging uses cost-optimized light scattering systems. German facilities prioritize ISO 14644-1 compliance over sub-micrometer sensitivity.
Pharmaceutical processing holds the largest share; semiconductor fabrication shows steepest expansion trajectory.
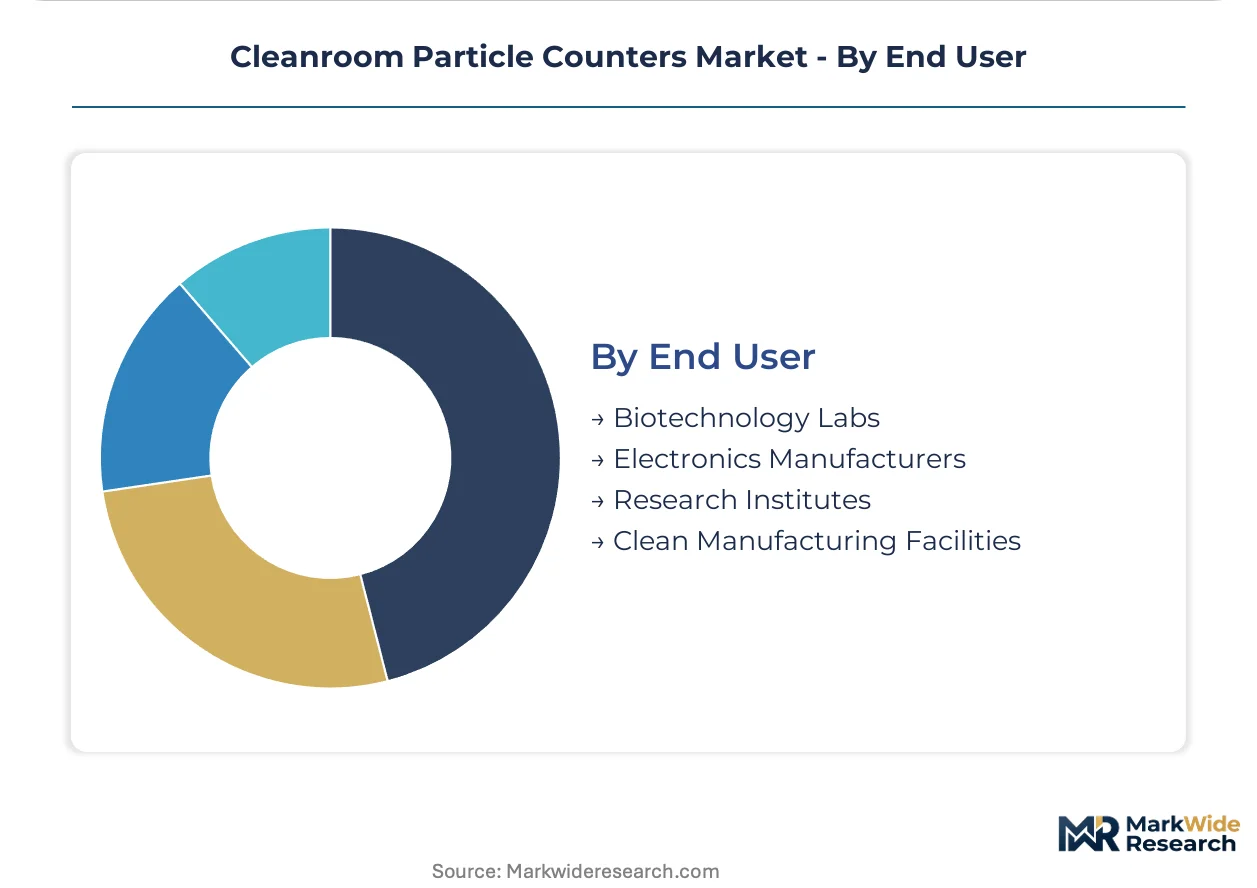
End User:
Customer type determines procurement sophistication, with regulated manufacturers demanding validated calibration protocols that research institutes often bypass.
- Electronics Manufacturers:Taiwan and South Korea semiconductor foundries specify 0.1-micrometer sensitivity with traceable calibration chains. These buyers negotiate multi-year service contracts bundling hardware, software, and ISO 17025-accredited validation.
- Biotechnology Labs:Massachusetts and North Carolina facilities balance field audit flexibility with regulatory submission requirements. Hybrid procurement patterns mix handheld units for intervention sampling with fixed installations for continuous Grade A monitoring.
- Clean Manufacturing Facilities:Aerospace and precision optics producers in Toulouse and Stuttgart prioritize particle classification over viable enumeration. These buyers favor portable systems for periodic reclassification without permanent infrastructure.
- Research Institutes:Academic and government laboratories in Boston and Tokyo prioritize capital cost over calibration traceability. These users drive demand for refurbished instruments and third-party metrology services.
Electronics manufacturers hold the largest share; biotechnology labs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical quality managers in New Jersey and semiconductor yield engineers in Taiwan represent the archetypal buyer profiles. These procurement specialists command budgets shaped by FDA cGMP enforcement and sub-3nm EUV node requirements respectively.
United States
FDA sterile manufacturing mandates are compressing particle thresholds in aseptic filling suites across New Jersey, North Carolina, and Massachusetts. The agency's updated guidance on continuous viable monitoring is displacing manual sampling methods ahead of enforcement deadlines. Boston-area biotechnology labs are retrofitting Grade A environments with remote sampling configurations to minimize human-borne contamination.
Taiwan
Semiconductor foundries operating EUV lithography nodes below three nanometers require 0.1-micrometer sensitivity thresholds that legacy optical systems cannot satisfy. TSMC and associated supply chain partners are expanding metrology capital expenditure to protect wafer yields from particle-induced defects. Hsinchu Science Park facilities anchor the densest concentration of continuous monitoring installations worldwide.
Germany
EMA Annex 1 revisions mandating real-time viable particle enumeration are driving retrofit cycles across pharmaceutical manufacturing in Baden-Württemberg and Bavaria. ISO 17025-accredited calibration infrastructure remains concentrated in Stuttgart and Berlin, creating geographic bottlenecks for traceable validation services. Food and beverage packaging facilities leverage cost-optimized light scattering systems for HACCP-aligned environmental monitoring.
South Korea
Samsung and SK Hynix fabrication complexes are expanding multi-wavelength detection platform procurement as EUV node shrinkage accelerates. MFDS alignment with international pharmaceutical standards is creating secondary demand in biologics manufacturing clusters around Seoul. Pyeongtaek and Hwaseong foundries represent the fastest-expanding capital deployment for metrology infrastructure.
India
CDSCO alignment with PIC/S standards is generating regulatory-compliant particle monitoring demand in Hyderabad and Ahmedabad pharmaceutical corridors. Domestic electronics manufacturing under PLI scheme incentives is creating nascent semiconductor-adjacent requirements. Bangalore biotechnology startups are adopting compact diode-based architectures for initial cleanroom qualification before scaling investments.
Cleanroom Particle Counters Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct procurement contexts. The market structure concentrates around three tiers: premium continuous monitoring providers serving semiconductor fabs, handheld specialists capturing pharmaceutical field audit demand, and calibration service unbundlers disrupting traditional vendor relationships. Strategic moves center on multi-wavelength platform convergence and third-party validation protocol partnerships that pharmaceutical quality departments increasingly require.
Among precision instrumentation specialists, TSI Inc exemplifies the aerosol-science heritage archetype anchoring premium handheld portfolios. Lighthouse Worldwide Solutions occupies a position representing continuous monitoring dominance in semiconductor cleanroom installations. Particle Measuring Systems sits within the regulatory compliance tier, specializing in calibration protocols that pharmaceutical clients require for FDA submission documentation. These three players collectively represent the strategic positioning vectors—field mobility, fixed infrastructure, and validation services—that define competitive differentiation in this market.
| Leading Market Players |
|---|
| TSI Inc |
| Lighthouse Worldwide Solutions |
| Rion Co., Ltd |
| Spectris Plc |
| Danaher Corporation |
| Particle Measuring Systems |
| Met One Instruments, Inc |
| Particle Plus, Inc |
| PAMAS Partikelmess |
| Others |
Pricing and Supply Chain Analysis
Hsinchu Science Park's concentrated metrology component manufacturing feeds downstream pricing power to semiconductor-grade instrument vendors serving Taiwan and South Korea fabrication facilities. Avalanche photodiode allocation priorities in RF communications markets create input cost volatility that compresses margins for mid-tier optical sensing architectures.
Pricing Analysis
Cost-plus contracts with Japanese gas laser manufacturers index helium-neon tube pricing to noble gas commodity benchmarks. Three-tier pricing structure across premium laser diffraction, standard optical sensing, and economy light scattering tiers separates sensitivity thresholds and calibration traceability levels. Pricing pressure stems from solid-state laser diode cost compression collapsing performance gaps between handheld and fixed-installation categories. Biotechnology field audit teams in Massachusetts demonstrate highest price sensitivity, while Taiwan semiconductor foundries absorb premium multi-wavelength platform costs without volume negotiation.
Supply Chain Analysis
Supplier-financing facilities from Japanese photonics component vendors extend 90-day payment terms to qualified instrument assemblers. Manufacturing concentrates in Japan, Germany, and the United States for precision optical subassemblies and ISO 17025-accredited calibration standards. Raw material dependencies include helium-neon laser tubes, avalanche photodiode arrays, and synthetic sapphire optical windows. Single-source vulnerability sits with Japanese gas laser manufacturers for diffraction-based detection platforms. Distribution runs through authorized metrology distributors serving pharmaceutical corridors and direct OEM relationships with semiconductor fabrication equipment integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from ISO 17025-accredited calibration contracts expands faster than hardware unit sales as pharmaceutical quality departments unbundle validation from captive vendor relationships. Third-party metrology laboratories in New Jersey and Switzerland capture recurring revenue streams previously monopolized by instrument manufacturers.
For Market Incumbents: Pre-empt service unbundling by acquiring independent calibration laboratories in Stuttgart and Berlin to secure geographic bottlenecks for traceable 0.1-micrometer validation. Deepen backward integration into avalanche photodiode sourcing through compound semiconductor wafer allocation agreements with RF communications foundries. Lock in multi-year service contracts with Taiwan semiconductor foundries before solid-state laser diodes erode premium positioning for continuous monitoring installations. For New Entrants and Emerging Players: Establish a beachhead in India pharmaceutical corridor expansion by aligning CDSCO-compliant calibration protocols with Hyderabad and Ahmedabad manufacturing clusters. Target mid-cap biotechnology firms in North Carolina lacking internal metrology capabilities but facing FDA submission deadlines for viable particle enumeration. Lead with compact diode-based optical sensing platforms priced below TSI Inc handheld portfolios while matching sensitivity thresholds for field audit applications. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors calibration service specialists with ISO 17025 accreditation in regulatory-constrained geographies over hardware manufacturers facing solid-state laser commoditization. Five-to-ten year viability rests on recurring revenue durability from pharmaceutical validation contracts rather than capital equipment replacement cycles. Watch for EMA Annex 1 enforcement deadline alignment as inflection indicator for remote sampling configuration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Acquisition | Captures recurring revenue from pharmaceutical quality departments unbundling validation from hardware vendors. |
| Multi-Wavelength Platform Launch | Enables simultaneous viable and non-viable particle detection for EMA Annex 1 compliance in Grade A suites. |
| India Regulatory Alignment | Positions CDSCO-compliant instruments for PIC/S standard convergence in Hyderabad pharmaceutical corridors. |
| Backward Integration into Photonics | Secures avalanche photodiode allocation priority amid RF communications market compound semiconductor competition. |
| Remote Sampling Configuration Partnership | Minimizes human-borne contamination risks during aseptic filling interventions ahead of enforcement deadlines. |
Research Methodology
A spread of perspectives from semiconductor yield engineers, pharmaceutical quality managers, metrology laboratory directors, and calibration service technicians converged on the working assumptions. Primary interviews across Taiwan, South Korea, Germany, and the United States combined with secondary validation from FDA cGMP guidance documents, EMA Annex 1 revisions, ISO 14644-1 classification standards, and SEC filings from precision instrumentation conglomerates. Bottom-up unit shipment estimates by product category and top-down market sizing through installed base analysis were triangulated for convergence.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling particle counter procurement against semiconductor fabrication capacity expansion and pharmaceutical sterile manufacturing retrofit cycles. Segmentation dimensions included product type, detection technology, application vertical, and end-user sophistication tier. CAGRs derived from regression analysis against EUV lithography node transition timelines and regulatory enforcement deadline schedules. Industry-specific forecast inputs incorporated TSMC and Samsung capital expenditure disclosures and MFDS pharmaceutical alignment announcements.
Stress conditions across helium-neon laser supply disruption, avalanche photodiode price volatility, and EMA enforcement timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about sub-3nm EUV node adoption rates and sterile manufacturing guideline implementation. Macroeconomic contraction, semiconductor export control expansion, or pharmaceutical serialization mandate redirection would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Micro Balances Market
Analytical Instruments
Microplate Absorbance Reader Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
Global Fluorescence Spectrophotometer Market
Analytical Instruments
Logic Analyzer Market
Analytical Instruments
Microplate Instrumentation and Systems Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Global Particle Counters Market
Analytical Instruments
Flashpoint Analyzer Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
High-Sensitivity Luminometers Market
Analytical Instruments
Discrete Analyzers Market
Analytical Instruments
Portable Particle Counter Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market