
 Australia Forklift Market | 2026-2036
Australia Forklift Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Forklift Market Insights
Aftermarket service revenue is fragmenting across dealer networks and independent service providers as fleet owners extend equipment lifecycles. Toyota Material Handling leverages its national parts distribution network to capture recurring maintenance contracts. Crown Equipment differentiates through battery and charger vertical integration, sustaining higher attachment rates on full-service agreements.
A forklift is a powered industrial truck featuring dual fork arms mounted on a mast, designed to lift, lower, and transport palletized loads typically weighing between one and fifty tonnes across horizontal distances. Counterbalance forklifts anchor the installed base across Australian manufacturing and bulk logistics, though reach trucks are gaining share in Melbourne and Sydney distribution centers where vertical storage density is rising. Electric units are displacing LPG in retail and food logistics end uses as warehouse operators prioritize indoor air quality compliance and lower total energy costs.
TGA workplace safety directives intersect with Safe Work Australia's material handling codes to mandate operator certification, periodic inspection intervals, and load-rating compliance documentation. The Australian Competition and Consumer Commission monitors aftermarket parts accessibility, influencing manufacturer warranty and servicing policies. Stakeholders must weigh battery-electric transition timelines against Queensland and Western Australia mining corridor requirements for high-heat, high-dust diesel performance.
Market Dynamics
The Australian forklift market is undergoing a fundamental powertrain transition as lithium-ion battery chemistry and fast-charging infrastructure mature, compressing the operational cost gap against internal combustion alternatives in high-utilization warehouse environments.
Growth Catalysts
- Safe Work Australia's proposed emissions guidelines:Indoor air quality mandates are accelerating electric forklift procurement among Sydney and Melbourne third-party logistics operators ahead of formal enforcement timelines.
- Vertical storage density expansion:Melbourne and Sydney distribution centers are deploying reach trucks and very narrow aisle equipment to maximize cubic meter utilization in constrained urban logistics real estate.
- Queensland mining corridor manufacturing:Heavy-duty diesel and hybrid unit demand concentrates in Gladstone and Mackay, where bulk material handling requires high-heat, high-dust operational capability.
Market Restraints
- Lithium and cobalt price volatility:Battery raw material cost swings compress electric forklift margin structures and extend payback period calculations for fleet conversions.
- Dealer network consolidation:National distributor concentration in parts distribution limits independent service provider access to proprietary diagnostic software and OEM-approved components.
- LPG infrastructure lock-in:Existing cylinder exchange networks and on-site storage investments create switching friction for operators with mid-life internal combustion fleets.
Strategic Opportunities
- Western Australia mining logistics:Pilbara iron ore and lithium extraction operations present untapped demand for autonomous hauling and remote-operated rough-terrain forklifts in extreme climate conditions.
- TGA-Safe Work Australia certification convergence:Unified operator competency frameworks reduce training duplication costs and open cross-sector labor mobility between warehousing and manufacturing.
- Telematics and predictive maintenance integration:Fleet management platforms combining usage data with battery health monitoring enable outcome-based service contracting and uptime guarantees.
Industry Challenges
- High-voltage technician certification pipeline:Electric forklift maintenance requires specialized electrical safety competencies that current vocational training programs are not producing at replacement rates.
- Multi-site fleet standardization complexity:National operators struggle to harmonize equipment specifications across state-based procurement teams with divergent capital approval processes and local supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Forklift Market |
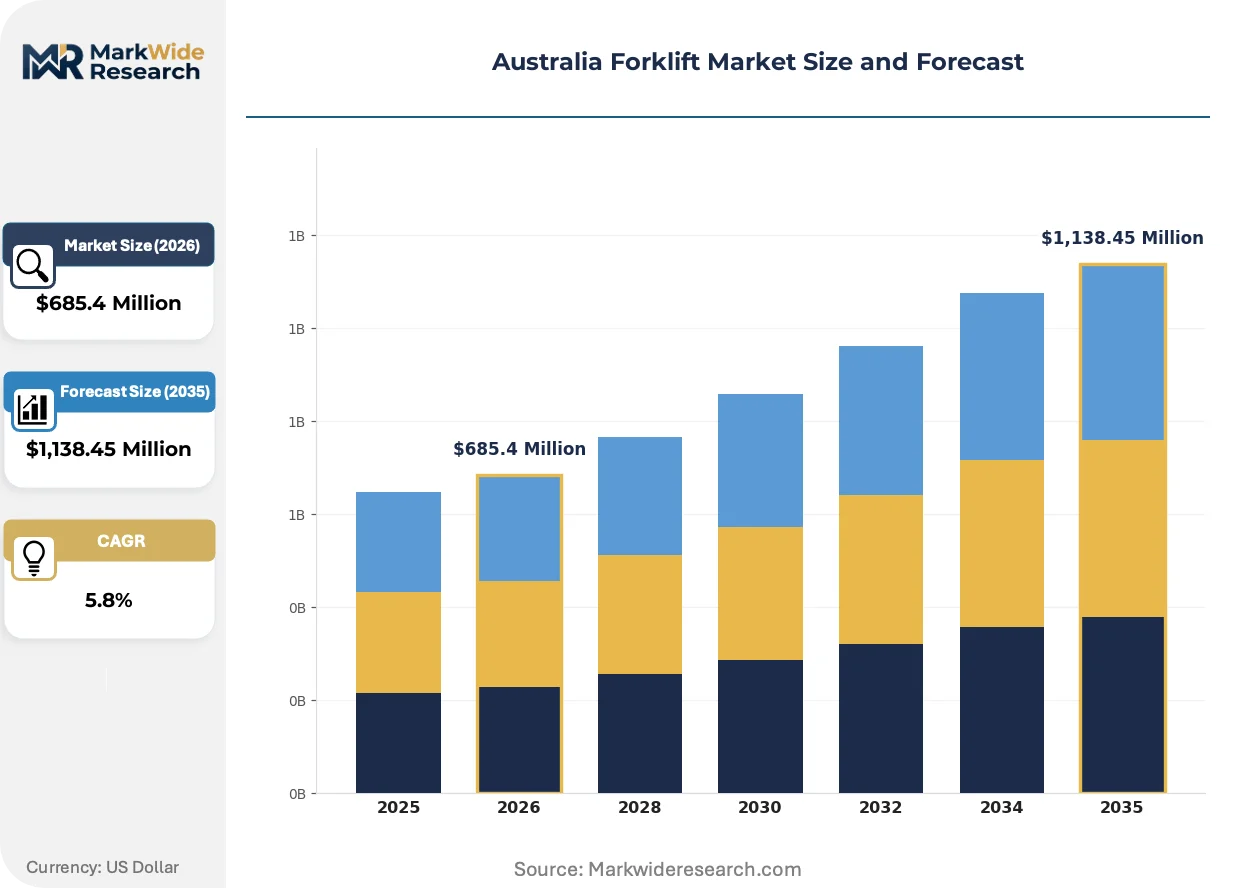
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Counterbalance Forklifts, Pallet Jacks, Reach Trucks, Order Pickers End User: Manufacturing, Logistics, Retail, Construction Fuel Type: Electric, Diesel, LPG, Hybrid Technology: Automated Guided Vehicles, Advanced Telemetry, Telematics, Driver Assistance Systems |
| Companies Covered | Toyota Material Handling, Crown Equipment, Hyster-Yale Materials Handling, Inc., CLARK, Komatsu Ltd., Jungheinrich AG, Doosan Corporation, Hangcha, Linde Material Handling, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Forklift Market Trends and Innovations
Battery chemistry advances and autonomous navigation systems are restructuring equipment procurement criteria, shifting buyer evaluation from upfront capital cost toward total cost of ownership and operational flexibility metrics.
Lithium-iron-phosphate battery packs with opportunity charging capability are rendering obsolete the traditional battery room infrastructure and eight-hour shift-change protocols that dominated electric forklift operations. Major grocery and pharmaceutical distributors in Sydney's southwestern logistics corridor are retrofitting existing fleets with fast-charging systems during scheduled maintenance windows. The elimination of dedicated battery exchange staff and floor space reallocation is compressing facility operating costs and accelerating electric penetration in multi-shift environments.
Safe Work Australia's harmonized material handling codes intersect with TGA workplace safety directives to mandate documented load-rating compliance and periodic inspection intervals with digital record-keeping requirements. Equipment lessors and fleet operators must now maintain centralized certification databases accessible to regulatory auditors. Food processing and pharmaceutical manufacturing facilities in Victoria are prioritizing suppliers with integrated compliance documentation systems to reduce audit preparation labor.
Flexible leasing structures with embedded maintenance and battery replacement clauses are displacing traditional capital purchase models among mid-sized warehousing operators. Third-party logistics providers in Brisbane's trade coast zone are consolidating equipment decisions with facility management contracts to reduce vendor relationship overhead. This bundling trend favors national lessors with integrated service networks over regional equipment distributors lacking geographic coverage depth.
Australia Forklift Market Segmentation
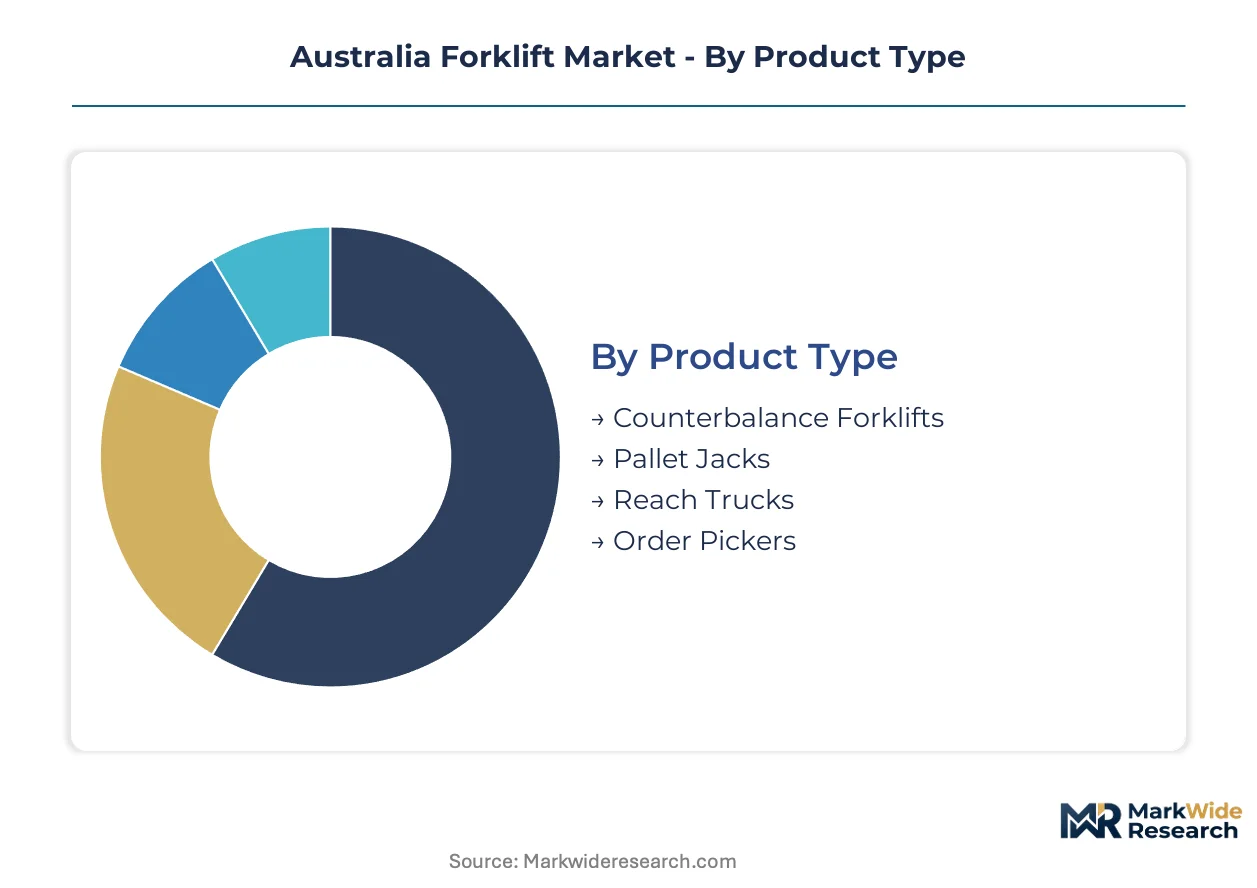
Powertrain transition and warehouse automation are fragmenting procurement criteria across Australian material handling operations. Fleet managers now evaluate segments through total cost of ownership lenses rather than upfront capital expenditure alone.
Product Type:
Equipment configuration determines facility layout economics and labor productivity ceilings across Australian distribution networks.
- Counterbalance Forklifts:Dual-front-wheel design with rear-mounted counterweight enables unrestricted outdoor operation and standard aisle width navigation. Manufacturing plants in Geelong and Adelaide's northern suburbs maintain dense fleets for inbound raw material handling and finished goods dispatch, though vertical storage limitations constrain cubic utilization in greenfield Sydney logistics facilities.
- Reach Trucks:Pantograph mast mechanism extends load carriage forward while chassis remains stationary, enabling 12-meter rack height access in aisles under 2.7 meters wide. Melbourne's Port of Melbourne hinterland distribution centers are deploying triple-mast configurations to maximize land value as industrial rents climb across Victoria's western suburbs.
- Pallet Jacks:Manual and electric walk-behind units handle ground-level pallet movement with minimal capital outlay. Food retail distribution in Brisbane's trade coast relies on high-frequency low-lift cycles for cross-dock operations.
- Order Pickers:Elevating operator platform enables piece-pick fulfillment at height. E-commerce fulfillment centers in Sydney's southwestern logistics corridor are scaling man-up equipment to support same-day delivery service levels.
Counterbalance forklifts hold installed capacity across Australian manufacturing. Reach trucks are rotating up the share rankings in metropolitan distribution centers.
End User:
Application intensity and shift patterns create divergent equipment utilization profiles across Australian industry verticals.
- Logistics:Third-party operators in Sydney and Melbourne run 20-hour utilization cycles across multi-client facilities. Fleet standardization pressure intensifies as national 3PL contracts consolidate with operators possessing cross-dock network density.
- Manufacturing:Discrete production scheduling generates intermittent demand spikes synchronized with inbound supplier windows and outbound shipping cutoffs. Automotive component suppliers in Adelaide maintain dedicated forklift pools aligned with just-in-sequence delivery commitments to Holden and Toyota assembly operations.
- Retail:Seasonal volume surges around promotional calendars drive short-term rental demand. Supermarket distribution centers in Queensland's southeast corridor are extending electric fleet penetration to meet corporate sustainability disclosure requirements.
- Construction:Rough-terrain capability and weather resistance dominate specification criteria. Western Australia civil infrastructure projects around Perth's metropolitan expansion generate demand for all-terrain telehandler variants.
Logistics commands the steepest expansion trajectory as e-commerce fulfillment infrastructure scales. Manufacturing maintains equipment density but faces capital allocation competition from automation investments.
Fuel Type:
Energy source selection now hinges on duty cycle intensity, indoor air quality compliance, and charging infrastructure availability rather than historical preference patterns.
- Electric:Lithium-ion battery packs with opportunity charging capability eliminate battery room infrastructure and enable continuous multi-shift operation. Pharmaceutical manufacturing in Victoria's Latrobe Valley is mandating zero-emission indoor fleets ahead of TGA facility inspection protocols.
- Diesel:High-torque internal combustion engines sustain performance in extreme temperature and particulate environments. Queensland mining logistics corridors around Gladstone specify heavy-duty diesel units for bulk material handling in unenclosed bulk terminals.
- LPG:Liquid petroleum gas offers faster refueling than battery exchange and lower particulate emissions than diesel. Established cylinder exchange networks in Perth's industrial estates create switching friction for mid-life fleet operators.
- Hybrid:Dual powertrain configurations optimize energy consumption across variable duty cycles. Limited deployment in Australian conditions reflects technology cost premiums against single-source alternatives.
Electric captures the fastest-growing trajectory as lithium-ion economics improve. Diesel retains entrenched position in Queensland and Western Australia extractive industries.
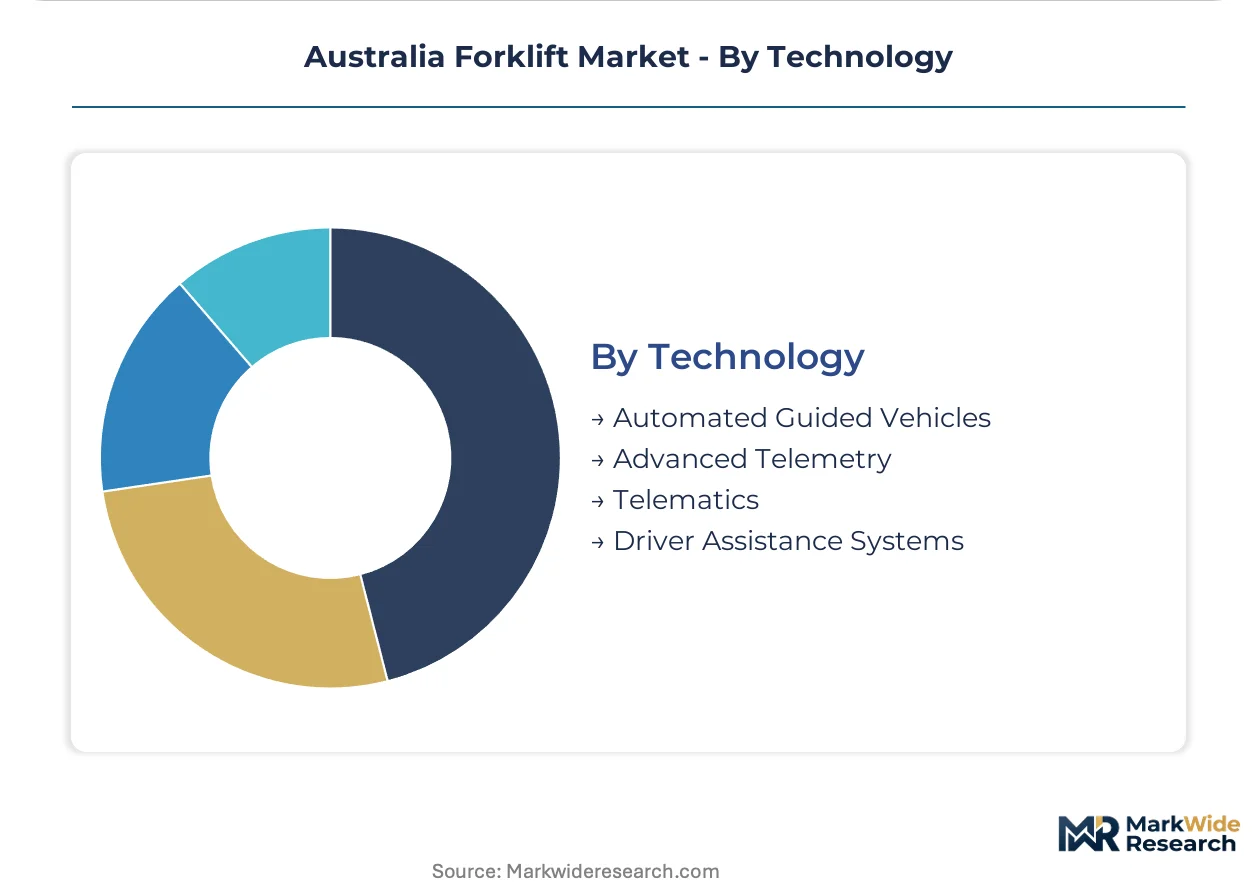
Technology:
Digital capability layers are restructuring service revenue models and equipment residual value calculations across Australian forklift fleets.
- Telematics:GPS-enabled usage tracking and impact detection systems generate fleet optimization data. National lessors are embedding telemetry hardware as standard equipment to enable outcome-based uptime contracting.
- Driver Assistance Systems:Proximity sensors and automatic speed reduction in confined zones reduce incident frequency. Safe Work Australia's proposed material handling codes are accelerating specification of pedestrian detection capability in high-traffic Sydney warehouse environments.
- Advanced Telemetry:Battery health monitoring and predictive maintenance algorithms extend component replacement intervals. Crown Equipment's vertical integration of charger and battery management systems sustains higher attachment rates on full-service agreements.
- Automated Guided Vehicles:Laser and vision-guided navigation enables unmanned horizontal transport in structured warehouse environments. Woolworths' distribution automation programs in Melbourne's west are piloting AGV integration with manual forklift operations for hybrid fulfillment workflows.
Telematics holds installed capacity across fleet management platforms. Automated guided vehicles are rotating up the share rankings as labor availability tightens in major metropolitan logistics corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian forklift deployment patterns diverge sharply between coastal logistics corridors and inland extractive zones, with eastern seaboard warehouses prioritizing electric fleet transitions while Queensland and Western Australia mining hubs sustain diesel-heavy equipment profiles.
New South Wales
Sydney's southwestern logistics corridor drives electric reach truck demand as third-party operators expand multi-client fulfillment centers. Safe Work Australia's proposed indoor emissions guidelines are accelerating procurement timelines ahead of formal enforcement. The Port Botany hinterland concentrates high-density warehousing where vertical storage maximization commands premium equipment specifications.
Victoria
Melbourne's Port of Melbourne hinterland distribution centers deploy triple-mast reach trucks to exploit climbing industrial land values across the western suburbs. TGA workplace safety directives intersect with state-level occupational health codes to mandate digital certification record-keeping. Pharmaceutical manufacturing in the Latrobe Valley is mandating zero-emission indoor fleets ahead of facility inspection protocols.
Queensland
Gladstone and Mackay mining corridors generate concentrated demand for heavy-duty diesel and hybrid units capable of high-heat, high-dust bulk material handling. The state's natural resources sector maintains equipment specifications that prioritize torque performance over emissions compliance in unenclosed terminal environments. Brisbane's trade coast third-party logistics providers are consolidating equipment decisions with bundled facility management contracts.
Western Australia
Pilbara iron ore and lithium extraction operations present emerging demand for autonomous hauling and remote-operated rough-terrain forklifts in extreme climate conditions. Perth's metropolitan civil infrastructure expansion generates demand for all-terrain telehandler variants with weather resistance specifications. Established LPG cylinder exchange networks in Perth's industrial estates create switching friction for mid-life fleet operators considering electric conversion.
South Australia
Adelaide's northern suburbs automotive component suppliers maintain dedicated forklift pools aligned with just-in-sequence delivery commitments to remaining assembly operations. The state's manufacturing equipment density faces capital allocation competition from automation investments. Geelong-connected manufacturing plants sustain counterbalance forklift fleets for inbound raw material handling and finished goods dispatch.
Australia Forklift Market Competitive Landscape
Capability concentration sits with integrated service networks; scale advantage sits with diversified industrial conglomerates. The Australian forklift market structures around three tiers: national distributors with captive parts distribution, regional lessors with embedded maintenance contracts, and specialized autonomous equipment developers. Strategic moves center on telematics platform integration and battery-charger vertical integration to capture recurring service revenue.
Among Japanese industrial conglomerates, Toyota Material Handling anchors the national parts distribution tier. Crown Equipment exemplifies battery and charger vertical integration specialists. Hyster-Yale Materials Handling, Inc. occupies a position within the diversified materials handling group. These three represent distinct competitive archetypes: captive infrastructure, component integration, and portfolio breadth.
| Leading Market Players |
|---|
| Toyota Material Handling |
| Crown Equipment |
| Hyster-Yale Materials Handling, Inc. |
| CLARK |
| Komatsu Ltd. |
| Jungheinrich AG |
| Doosan Corporation |
| Hangcha |
| Linde Material Handling |
| Others |
Pricing and Supply Chain Analysis
Melbourne's western suburbs logistics cluster concentrates national warehousing capacity, and this geographic density grants incumbent lessors pricing power through embedded service network coverage that regional distributors cannot replicate. Fleet operators face cost compression as lithium-ion battery raw material volatility feeds into equipment lease rate calculations.
Pricing Analysis
Long-term equipment lease contracts dominate procurement in Sydney and Melbourne distribution centers, with flexible term structures displacing outright purchase for mid-sized operators. Three-tier pricing structure across premium, standard, and economy levels separates full-service bundled agreements from bare-metal rentals and used-equipment repositioning. Pricing pressure stems from lithium and cobalt cost swings compressing electric forklift margin structures. Third-party logistics providers exhibit highest price sensitivity due to multi-client facility economics, while pharmaceutical manufacturers prioritize uptime guarantees over rate minimization.
Supply Chain Analysis
Contract manufacturing concentration for lithium-ion battery packs sits with Chinese and South Korean cell producers, with final assembly and chassis integration occurring in Australian distributor facilities. Supply chains draw from Japanese engine and transmission specialists for diesel powertrain components, and from German sensor manufacturers for telematics hardware. Single-source vulnerability concentrates in battery management system semiconductors. Distribution runs through national lessor networks with captive parts depots rather than independent dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian forklift market positioning rests on regulatory entrenchment as TGA and Safe Work Australia certification requirements create switching costs that lock fleet operators into established service relationships.
For Market Incumbents: Pre-empt lithium-ion battery standardization by securing exclusive supply agreements with cell producers before chemistry specifications consolidate. Capture high-voltage technician certification pipeline capacity to defend service revenue against independent providers. Battery-charger vertical integration and telematics platform control represent priority defensive levers as outcome-based contracting displaces transactional service models. For New Entrants and Emerging Players: Western Australia's Pilbara mining corridor presents underpenetrated demand for autonomous rough-terrain equipment in extreme climate conditions. Remote-operated forklift capability for lithium extraction operations offers a technical differentiation wedge against established diesel-heavy incumbents. Partner with Western Australia civil infrastructure contractors for telehandler fleet trials to build reference accounts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among national lessors with embedded maintenance contracts and battery replacement clauses. Long-term viability favors integrated service networks over pure equipment distributors as procurement shifts toward total cost of ownership metrics. Monitor Safe Work Australia enforcement timeline acceleration as inflection signal for electric fleet conversion capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Charger Vertical Integration | Crown Equipment's captive supply of power electronics sustains premium attachment rates on full-service agreements. |
| Telematics Platform Integration | Toyota Material Handling embeds GPS-enabled usage tracking to enable outcome-based uptime contracting with national 3PLs. |
| High-Voltage Technician Certification Investment | Specialized electrical safety competency pipelines address replacement rate shortfalls in electric forklift maintenance. |
| Autonomous Equipment Development | Woolworths' Melbourne distribution pilots validate hybrid AGV-manual forklift workflows for labor-constrained facilities. |
| Flexible Lease Structure Innovation | Brisbane trade coast 3PLs consolidate equipment decisions with facility management contracts to reduce vendor overhead. |
Research Methodology
A spread of perspectives from fleet maintenance directors, warehouse operations managers, OEM procurement teams, and aftermarket service heads converged on the working assumptions for equipment utilization profiles and replacement cycles. Secondary validation drew from Safe Work Australia regulatory filings, Australian Bureau of Statistics industrial equipment import data, TGA workplace safety directives, and SEC 10-K disclosures from listed materials handling conglomerates. Bottom-up equipment unit economics triangulated against top-down market size estimates across powertrain and product type segmentations.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning fuel type, product configuration, end-use vertical, and technology tier. CAGRs derived from equipment shipment trajectories, fleet age distribution analysis, and replacement cycle compression factors. Industry-specific forecast inputs included lithium-ion battery cost curve assumptions and Safe Work Australia enforcement probability weightings.
Practitioners should monitor lithium and cobalt commodity price movements, TGA-Safe Work Australia certification convergence timelines, and high-voltage technician training graduation rates for early signals of forecast revision triggers. Quarterly review of electric forklift penetration rates in Sydney and Melbourne warehousing, and diesel equipment order flows from Queensland mining corridors, is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Global Submersible Slurry Pumps Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
Industrial Girth Gear Market
Material Handling Equipment
Spring Shackles Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Industrial Wood Chipper Market
Material Handling Equipment
Portable Forklift Ramps Market