
 US Forklift Market | 2026-2036
US Forklift Market Size, Share, and Industry Trends Forecast 2026-2036
US Forklift Market Insights
OSHA forklift operator certification is reorganizing competitive access across the US material handling sector. Toyota Material Handling leverages its vertically integrated manufacturing footprint to sustain pricing discipline in electric lift trucks. Hyster-Yale Materials Handling anchors its position through deep specialization in heavy-capacity models for port and lumber applications. Crown Equipment Corporation differentiates via direct-to-customer service networks that bypass traditional dealer channels.
A forklift is a powered industrial truck equipped with hydraulic lifting mechanisms and fork attachments designed to raise, lower, and transport palletized loads typically ranging from one to seven tons. Its primary commercial purpose centers on vertical storage optimization and horizontal material movement within warehouses, distribution centers, and manufacturing floors. Electric forklifts now command the fastest expansion trajectory as battery energy density improvements and lithium-ion chemistry advances displace internal combustion alternatives in indoor environments. The warehousing end-user segment generates the densest margin pools due to fleet standardization contracts and multi-shift utilization rates that accelerate replacement cycles.
OSHA mandates operator training and equipment inspection protocols that directly shape fleet procurement timelines and safety feature requirements. EPA Tier 4 Final emissions standards constrain diesel forklift deployments in non-attainment zones, redirecting capital toward electric and LPG alternatives. The Department of Energy's industrial efficiency guidelines further influence battery charging infrastructure investments. Stakeholders must monitor state-level zero-emission warehouse mandates and utility rebate programs that could abruptly alter total cost of ownership calculations.
Market Dynamics
EPA Tier 4 Final emissions standards are compressing diesel forklift deployment timelines and redirecting capital toward electric alternatives, fundamentally restructuring fleet procurement patterns across US manufacturing and logistics operations.
Growth Catalysts
- E-commerce fulfillment density:Multi-shift warehouse operations in Texas and Ohio logistics corridors are accelerating replacement cycles as uptime requirements intensify.
- OSHA workplace safety mandates:Operator certification requirements and equipment inspection protocols are driving upgrades to models with enhanced stability control and collision avoidance systems.
- Lithium-ion battery chemistry:Energy density improvements are enabling single-battery multi-shift operation, eliminating battery changeout infrastructure in indoor environments.
Market Restraints
- Copper and lithium price volatility:Raw material cost swings for electric forklift powertrains are compressing margin predictability for fleet operators.
- Charging infrastructure capex:High-voltage electrical upgrades required for fast-charging fleets create capital barriers for smaller warehousing operations.
- LPG fueling network concentration:Geographic gaps in propane distribution infrastructure limit internal combustion alternatives in rural Great Lakes manufacturing zones.
Strategic Opportunities
- State-level zero-emission warehouse mandates:California and New York regulatory trajectories are creating first-mover advantages for electric fleet specialists.
- Automated guided vehicle convergence:Integration of autonomous navigation with traditional forklift chassis is opening new application spaces in high-throughput distribution.
- Direct service network expansion:Bypassing traditional dealer channels through captive technician deployment is capturing margin pools in fleet standardization contracts.
Industry Challenges
- Certified technician scarcity:OSHA-mandated operator training and lithium-ion battery maintenance specializations are outpacing vocational pipeline output.
- Legacy fleet integration complexity:Mixed-voltage charging infrastructure and telematics platform incompatibility are extending deployment timelines for hybrid fleet transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Forklift Market |
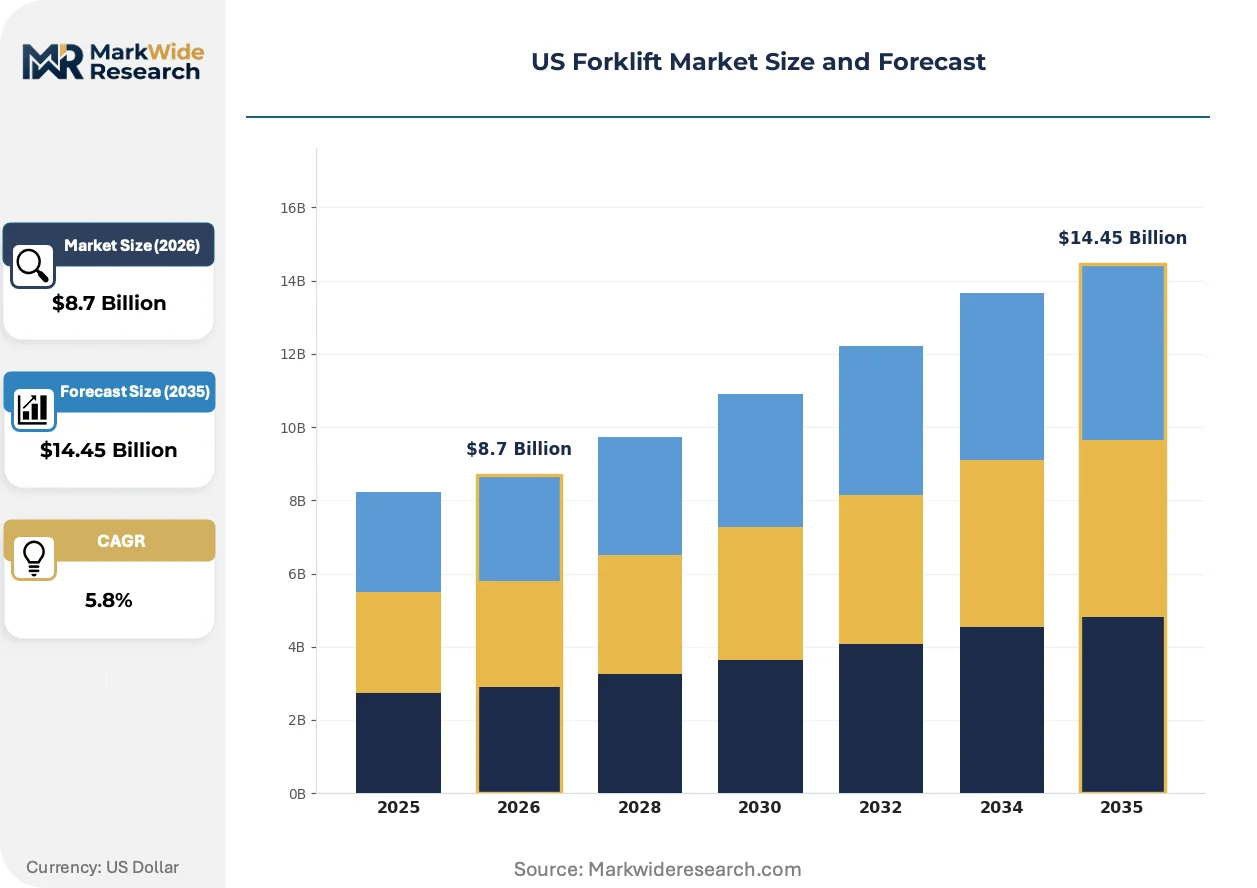
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Forklifts, Diesel Forklifts, LPG Forklifts, Pallet Jacks End User: Retail, Manufacturing, Warehousing, Construction Capacity: 1-3 Tons, 3-5 Tons, 5-7 Tons, Above 7 Tons Technology: Automated, Manual, Semi-Automated, IoT-Enabled |
| Companies Covered | Crown Equipment Corporation, Toyota Material Handling, Hyster-Yale Materials Handling, KION North America, Mitsubishi Logisnext Americas, Clark Material Handling Company, Komatsu Ltd., HELI America Inc., Hangcha Forklift America, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Forklift Market Trends and Innovations
Electrification trajectories and automation convergence are redefining equipment specifications and service delivery models across US material handling operations, with regulatory pressure accelerating technology substitution timelines.
Lithium-ion forklift powertrains are fragmenting the traditional battery market by enabling opportunity charging and eliminating dedicated battery rooms. Third-party logistics operators in California and Texas are adopting these systems fastest, drawn by reduced floor space requirements and elimination of acid-handling protocols. The technology is fragmenting capital deployment patterns as customers shift from battery asset ownership to energy-as-a-service arrangements with equipment financiers.
EPA non-attainment zone designations are constraining diesel forklift eligibility in industrial counties across California, Texas, and the Northeast. The regulation is forcing fleet operators to front-load electric conversion timelines or absorb higher LPG fuel costs. Port and lumber applications in Pacific Northwest and Gulf Coast corridors face the steepest compliance cliffs, driving demand for heavy-capacity electric alternatives previously dominated by internal combustion.
Telematics-enabled usage-based service contracts are displacing traditional time-and-materials maintenance arrangements. Large retail distribution operators are unbundling equipment purchase from service provision, selecting providers based on uptime guarantees rather than initial capital cost. The shift is most visible in Great Lakes automotive parts distribution and Southeast grocery warehousing, where multi-shift intensity maximizes value capture from predictive maintenance algorithms.
US Forklift Market Segmentation
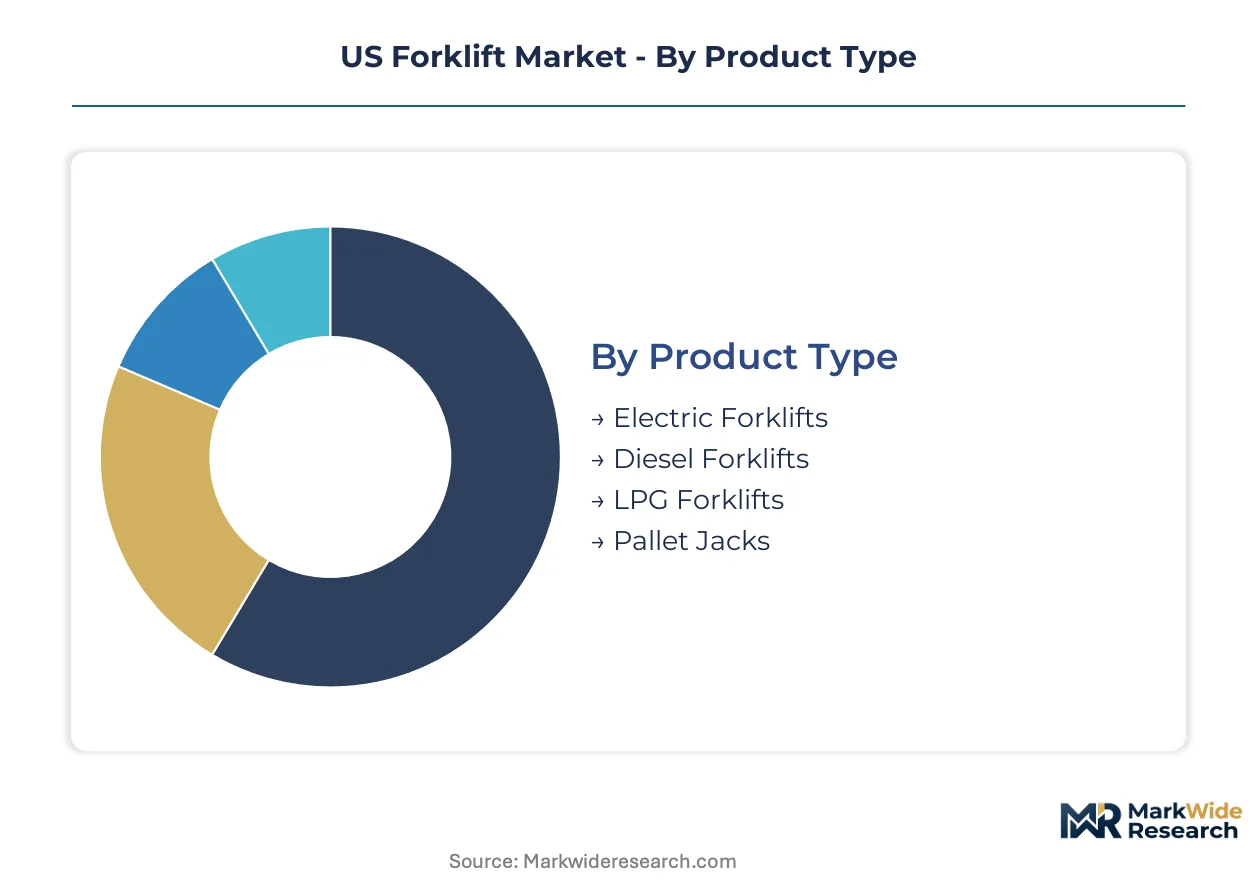
Forklift procurement patterns diverge sharply across product types and end-use environments. Fleet operators select specifications based on duty cycle intensity, indoor air quality constraints, and vertical racking requirements.
Product Type:
Equipment financing channels favor electric models for warehouse deployments, while diesel and LPG variants flow through industrial machinery dealers serving outdoor yards.
- Electric Forklifts:Battery-powered units with zero tailpipe emissions and regenerative braking systems. Demand concentrates in California and Texas e-commerce fulfillment centers where EPA non-attainment designations restrict combustion alternatives. OSHA indoor air quality mandates accelerate substitution in multi-shift operations.
- Diesel Forklifts:Internal combustion engines delivering high torque for outdoor container handling and lumber yards. Procurement compresses in Great Lakes manufacturing corridors as Tier 4 Final compliance costs erode total cost of ownership advantages against electric alternatives.
- LPG Forklifts:Liquid propane gas powertrains offering indoor-outdoor flexibility with lower particulate output than diesel. Rural Texas logistics hubs and Pacific Northwest timber operations sustain demand despite fueling infrastructure gaps.
- Pallet Jacks:Manual and electric walk-behind units for ground-level load transport. Retail distribution centers in Ohio and Pennsylvania standardize on these for dock-to-rack workflows.
By volume, pallet jacks lead. By growth pace, electric forklifts are climbing the fastest.
End User:
Margin profiles vary dramatically across customer types, with warehousing commanding premium pricing for uptime guarantees while construction purchases emphasize acquisition cost.
- Retail:Big-box distribution networks in Southeast grocery and Midwest home improvement chains. Fleet standardization contracts consolidate procurement through national lessors.
- Manufacturing:Automotive parts suppliers along the Great Lakes corridor and Gulf Coast petrochemical processors. Just-in-time production lines demand 24/7 equipment availability.
- Warehousing:Third-party logistics operators in California's Inland Empire and Dallas-Fort Worth metroplex. Multi-shift intensity maximizes lithium-ion battery utilization rates.
- Construction:Residential builders and commercial contractors in Florida and Arizona growth markets. Seasonal demand patterns favor rental over ownership.
Warehouse deployments generate the densest margin pools. Construction exhibits the most volatile replacement cycles.
Capacity:
Heavy-capacity segments concentrate specialized dealer networks, while light-duty models distribute through equipment rental chains.
- 1-3 Tons:Compact electric units for narrow-aisle retail and pharmaceutical distribution. California cold storage facilities drive specification toward corrosion-resistant mast designs.
- 3-5 Tons:General-purpose workhorses dominating manufacturing floor operations. Texas automotive assembly plants specify these for line-side parts delivery.
- 5-7 Tons:Heavy-duty electric and LPG models replacing diesel in lumber and steel service centers. Pacific Northwest port operators test battery alternatives for container stuffing.
- Above 7 Tons:Specialized port handlers and steel coil movers. Gulf Coast heavy industry sustains limited demand as electric alternatives penetrate slowly.
The 3-5 ton bracket dominates unit shipments. Above-7-ton electric conversions are gaining share fastest.
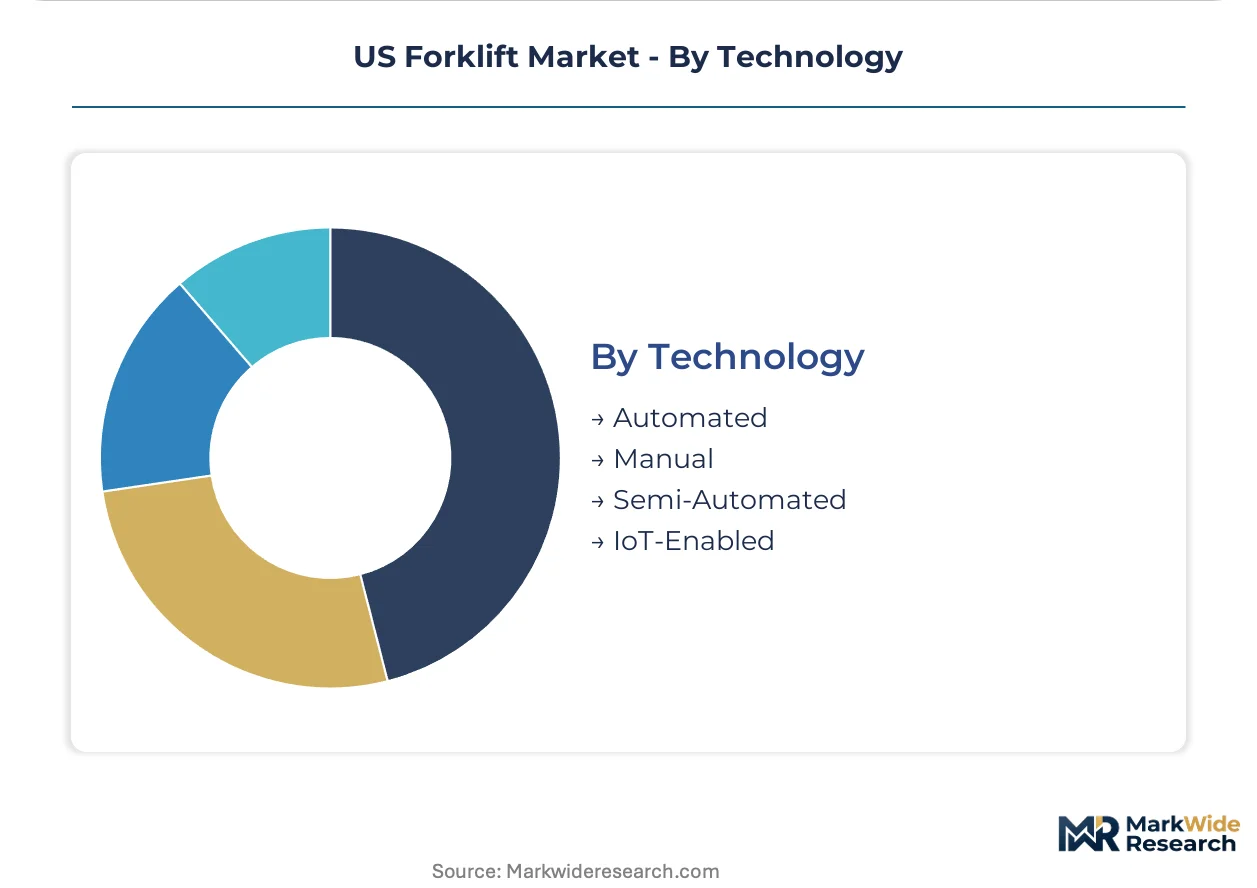
Technology:
Technology tier determines service contract structure, with automated systems requiring systems integrator partnerships rather than traditional dealer maintenance.
- Automated:Autonomous guided vehicles with LiDAR navigation for high-throughput distribution. Amazon and Walmart fulfillment networks in Arizona and Pennsylvania deploy these for pallet transport.
- Manual:Operator-controlled equipment with basic hydraulic systems. Small Midwest manufacturers and independent warehousing operations sustain this segment.
- Semi-Automated:Assisted steering and load-height optimization without full autonomy. Food and beverage distributors in Georgia and North Carolina adopt these for operator productivity gains.
- IoT-Enabled:Telematics-equipped units transmitting usage data for predictive maintenance. Large retail fleets in Illinois and Ohio unbundle equipment purchase from uptime-guaranteed service contracts.
Manual equipment retains the largest installed base. IoT-enabled models show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety mandates and EPA emissions standards are redirecting procurement capital toward electric alternatives across distinct US industrial corridors, with state-level zero-emission warehouse rules accelerating conversion timelines in coastal and Great Lakes manufacturing zones.
California
Third-party logistics operators in the Inland Empire and Central Valley are deploying lithium-ion fleets to comply with CARB warehouse emissions rules. The state's zero-emission forklift mandate for large facilities drives battery infrastructure investments in Fontana and Stockton distribution hubs. Cold storage facilities in the Central Valley specify corrosion-resistant mast designs for multi-shift frozen food operations.
Texas
Dallas-Fort Worth metroplex fulfillment centers are compressing replacement cycles to sustain e-commerce uptime requirements. The Texas Commission on Environmental Quality enforces emissions standards that redirect capital toward LPG and electric alternatives in Houston petrochemical corridors. Port operators in Corpus Christi test heavy-capacity electric models for container stuffing applications previously served by diesel.
Ohio
Automotive parts suppliers along the I-75 corridor demand 24/7 equipment availability for just-in-time production lines. OSHA's operator certification requirements drive upgrades to stability-enhanced models in Toledo and Dayton manufacturing plants. Retail distribution centers in Columbus standardize on pallet jacks for dock-to-rack workflows with fleet standardization contracts.
Illinois
Chicago-area warehousing operations unbundle equipment purchase from uptime-guaranteed service contracts enabled by telematics platforms. The Illinois EPA enforces non-attainment designations that constrain diesel eligibility in Cook County industrial zones. Food and beverage distributors in Rockford adopt semi-automated steering systems for operator productivity gains in high-throughput environments.
Pennsylvania
Southeast grocery warehousing networks deploy IoT-enabled units transmitting usage data for predictive maintenance algorithms. The Pennsylvania Department of Environmental Protection enforces emissions protocols that accelerate electric conversion in Philadelphia port operations. Steel service centers in Pittsburgh test 5-7 ton electric alternatives for coil handling previously dominated by internal combustion.
US Forklift Market Competitive Landscape
Player mix skews toward integrated manufacturers with captive component production and direct service networks. The market structure consolidates around three strategic tiers: vertically integrated full-line suppliers, specialized heavy-capacity fabricators, and direct-to-customer service specialists. Dominant competitive moves include backward integration into battery and mast manufacturing, and geographic expansion of captive technician deployment networks to bypass traditional dealer channels.
Among US-based equipment specialists, Crown Equipment Corporation exemplifies the direct-service archetype through technician networks that capture margin pools in fleet standardization contracts. Toyota Material Handling anchors the integrated-manufacturing tier with in-house production of electric powertrain components. Hyster-Yale Materials Handling occupies a position in heavy-capacity specialization for port and lumber applications where diesel displacement creates equipment specification gaps.
| Leading Market Players |
|---|
| Crown Equipment Corporation |
| Toyota Material Handling |
| Hyster-Yale Materials Handling |
| KION North America |
| Mitsubishi Logisnext Americas |
| Clark Material Handling Company |
| Komatsu Ltd. |
| HELI America Inc. |
| Hangcha Forklift America |
| Others |
Pricing and Supply Chain Analysis
OSHA operator certification requirements gate both supplier qualification and price differentiation simultaneously, as fleet operators pay premiums for equipment bundled with compliant training programs while uncertified dealers get pushed toward commodity segments. EPA Tier 4 Final compliance costs and lithium-ion battery chemistry advances are compressing margin structures for diesel-dependent fabricators and rewarding electric specialists with pricing power in multi-shift warehousing contracts.
Pricing Analysis
Certification level creates the primary spread across the US forklift market, with OSHA-compliant training bundles commanding substantial premiums over bare equipment transactions. Three-tier pricing structure across premium, standard, and economy levels segments buyers by fleet scale and uptime requirements, with third-party logistics operators in California and Texas showing lowest price sensitivity due to energy-as-a-service financing shifts. Cost compression in the diesel-equipment tier is intensifying because Tier 4 Final after-treatment systems erode total cost of ownership advantages against electric alternatives in EPA non-attainment zones.
Supply Chain Analysis
Lithium carbonate processing concentration in Chile, Australia, and China anchors battery cost volatility for electric forklift powertrains. Copper winding supplies from Chile and the Democratic Republic of Congo feed motor fabrication, while Japanese and South Korean electronics houses supply battery management systems. Single-source vulnerability in lithium hydroxide refining creates exposure to export restriction shocks. Distribution runs through captive technician networks for premium fleet contracts and industrial machinery dealers for standard equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics platform interoperability is reconfiguring the US forklift market toward ecosystem economics, as usage-based service contracts unbundle equipment ownership from uptime guarantees and reward providers with integrated data-analytics capabilities.
For Market Incumbents: Fortify position through backward integration into lithium-ion battery cell production and captive mast fabrication, neutralizing raw material cost volatility that threatens margin stability. Deepen certification investment in OSHA-mandated operator training programs to lock in fleet standardization contracts against emerging electric specialists. Priority defensive moves center on acquiring regional service networks in Texas and California logistics corridors where replacement cycles compress fastest. For New Entrants and Emerging Players: Lead with heavy-capacity electric models for Pacific Northwest port and lumber applications, where diesel displacement creates specification gaps that Hyster-Yale and Toyota have not fully addressed. Target 5-7 ton capacity segments in Gulf Coast steel service centers and Great Lakes manufacturing zones where incumbent electric portfolios remain thin. Go-to-market angle should emphasize opportunity-charging infrastructure partnerships that eliminate battery room capex for mid-size warehousing operations. For Investors and Strategic Acquirers: EPA non-attainment zone expansion reshapes the acquisition landscape toward electric fleet specialists with proven lithium-ion deployment track records in California and Texas corridors. Long-term viability favors providers with captive technician networks and telematics-enabled service contract portfolios over pure manufacturing plays. Acquisition target archetype: regional electric specialists with 500+ unit deployed base and direct-service footprint. Signal to watch: state-level zero-emission warehouse mandate adoption beyond California and New York.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Captive lithium-ion supply secures margin stability against Chile-Australia price volatility. |
| Direct Service Network Expansion | Bypassing dealer channels captures uptime-guaranteed contract pools in Ohio automotive corridors. |
| Telematics Platform Integration | Usage-based maintenance contracts unbundle equipment from service in Illinois retail distribution. |
| Heavy-Capacity Electric Portfolio Buildout | 5-7 ton models address diesel displacement gaps in Pacific Northwest port operations. |
| OSHA Certification Program Investment | Operator training bundling locks in fleet standardization contracts against price competition. |
Research Methodology
A spread of perspectives from fleet maintenance directors, plant engineers at automotive parts suppliers, OEM procurement teams, aftermarket service heads, and third-party logistics operators converged on the working assumptions. Primary fieldwork combined structured interviews with equipment financing specialists and warehouse operations managers with secondary validation through OSHA enforcement data, EPA emissions compliance filings, SEC 10-K disclosures from listed manufacturers, and utility rebate program databases. Bottom-up unit deployment estimates triangulated against top-down market value reconstructions.
Segmentation dimensions modeled include powertrain type, capacity tier, end-use environment, technology integration level, and regional regulatory cluster across the analysis window. CAGRs derived from fitted growth curves applied to historical shipment data, adjusted for lithium-ion substitution trajectories and state-level mandate adoption curves. Industry-specific forecast inputs encompassed battery energy density improvement curves and charging infrastructure deployment rates.
Forecasts assume regulatory continuity in EPA Tier 4 Final enforcement and OSHA certification mandates; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as copper-lithium price volatility and state zero-emission warehouse rule expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Linear Slide Units Market