
 Sand Washing Machine Market | 2026-2036
Sand Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Sand Washing Machine Market Analytics
Buyer concentration among large-scale construction aggregates producers is realigning procurement patterns across the sand washing machine supply base. Gongyi Forui Machinery leverages its Henan manufacturing base to dominate domestic Chinese quarry retrofits. Nesans anchors its position through specialized hydrocyclone integration for Indian mining operators. LZZG Machine competes on modular skid-mounted systems that reduce civil works for mid-size sand plants.
A sand washing machine removes fines, clay, and organic contaminants from quarried or dredged sand through mechanical agitation, water injection, and particle classification, typically processing 50-500 tonnes per hour to meet concrete and asphalt grading specifications. Screw washer configurations sustain the largest installed base due to lower capital outlay and simpler maintenance access, though hydrocyclone technology leads growth in high-capacity mining applications where water recovery rates exceed eighty percent. Bucket wheel washers occupy the premium tier in European markets where CE marking and REACH compliance elevate certification costs.
China's MEE enforces wastewater discharge limits that compel quarry operators toward closed-loop sand washing circuits with zero liquid discharge. India's CEA and state pollution control boards are tightening groundwater extraction rules for sand processing, pushing demand toward water-efficient pneumatic classification systems. Stakeholders must monitor how evolving silica dust exposure standards from OSHA and China's GB occupational health frameworks reshape equipment enclosure and ventilation design requirements.
Market Dynamics
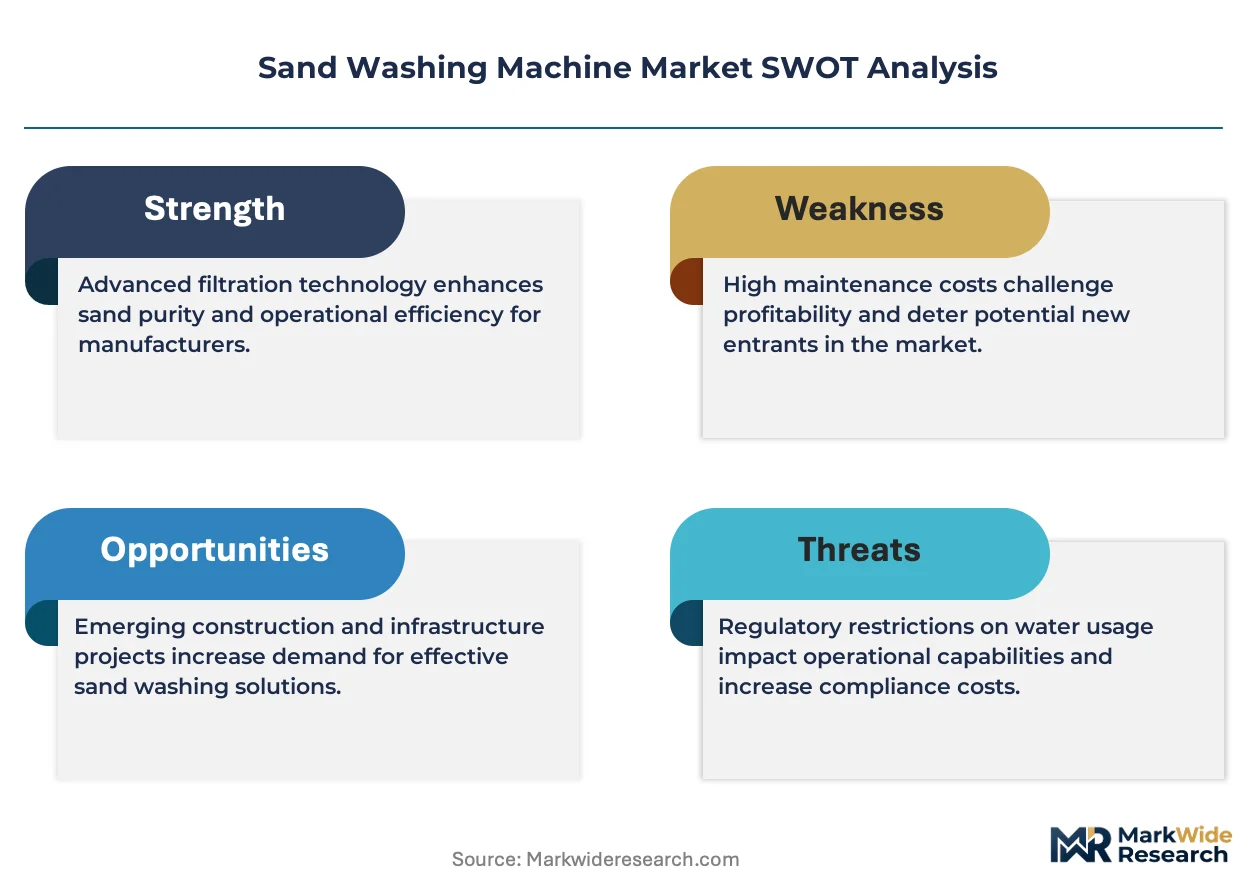
Closed-loop water recovery mandates from China's MEE and Germany's quarry runoff regulations are compressing replacement cycles and forcing capital redeployment toward hydrocyclone-based systems with zero liquid discharge capability.
Growth Catalysts
- Hydrocyclone integration:Mining operators in India are retrofitting screw washer fleets with hydrocyclone arrays to achieve eighty-plus percent water recovery rates under CEA groundwater extraction rules.
- Germany's quarry runoff standards:Stricter federal water protection laws mandate closed-loop circuits for aggregate producers, accelerating equipment replacement in Bavaria and North Rhine-Westphalia.
- Western India infrastructure surge:Maharashtra and Gujarat state governments are expanding highway and port construction, concentrating sand processing demand in coastal quarry clusters.
Market Restraints
- High-grade steel input volatility:Abrasion-resistant plate and alloy screw flights constitute forty percent of bill-of-materials cost, exposing manufacturers to nickel and manganese price swings.
- Henan manufacturing concentration:Domestic Chinese supply clusters around Zhengzhou-Gongyi corridor, creating geographic vulnerability to logistics disruptions and regional power rationing.
- REACH compliance friction:CE marking and chemical substance registration for European markets adds eighteen-to-twenty-four month certification timelines that exclude smaller fabricators.
Strategic Opportunities
- Modular skid-mounted deployment:Mid-size sand plants in Southeast Asia are bypassing civil works through containerized washing circuits that install within seventy-two hours.
- Silica dust enclosure retrofit:OSHA's pending crystalline silica rulemaking for construction materials processing creates aftermarket demand for sealed classifier housings and negative-pressure ventilation.
- Remote condition monitoring:Vibration sensors and oil analysis telemetry are penetrating Indian mining contracts through annual subscription models that unbundle hardware from service revenue.
Industry Challenges
- Hydrocyclone sizing expertise scarcity:Proper vortex finder and spigot diameter selection for variable feed grades requires specialized process engineering talent concentrated with original equipment vendors.
- Legacy screw washer integration:Retrofitting closed-loop water circuits onto existing concrete foundations demands custom chute work and pump sizing that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sand Washing Machine Market |
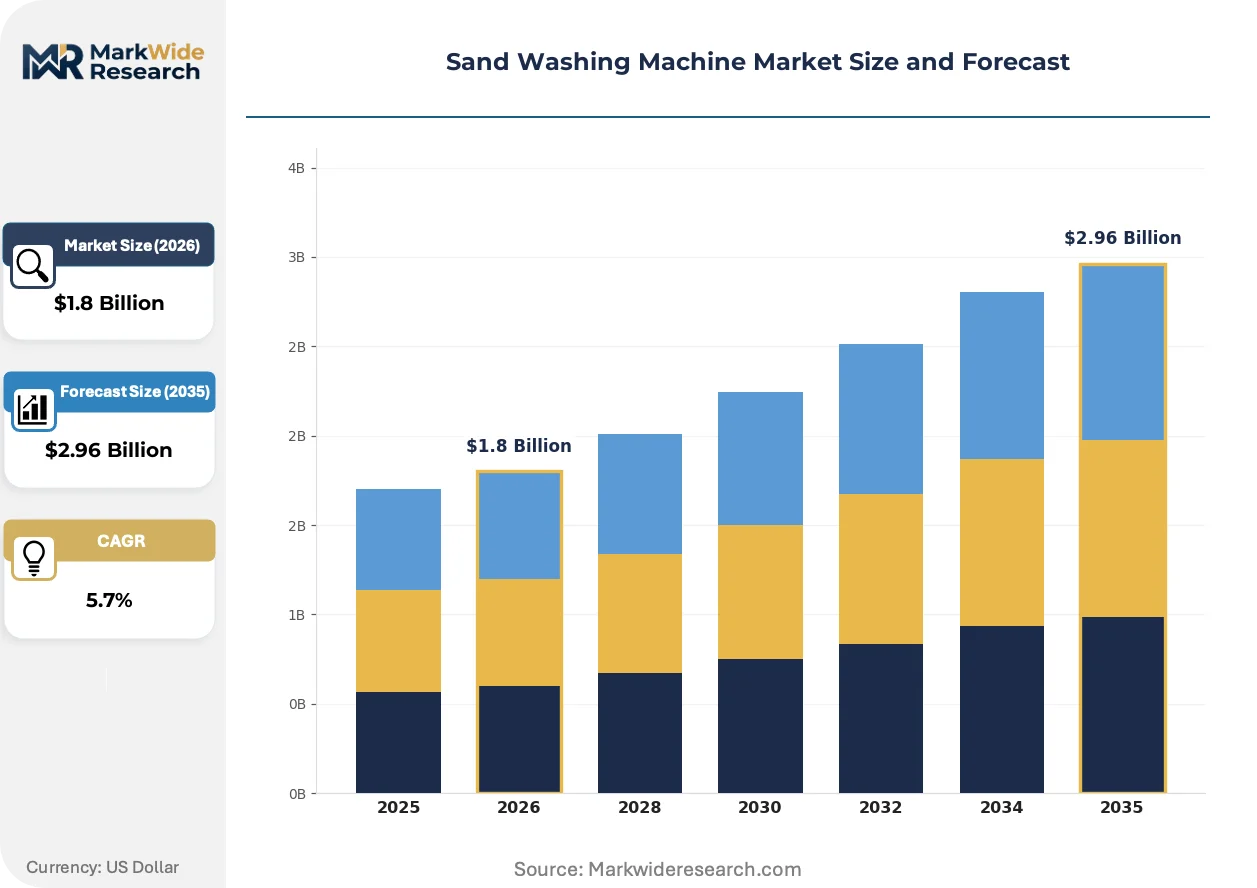
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Washer, Bucket Wheel Washer, Sand Classifier, Hydrocyclone Technology: Mechanical, Hydraulic, Pneumatic, Eco-friendly End User: Construction, Mining, Recycling, Agriculture Installation: Stationary, Mobile, Modular, Fixed |
| Companies Covered | Gongyi Forui Machinery, Nesans, LZZG Machine, Rockman Equipments, FABO Stone Crusher Machines, Shibang Industry and Technology, Shiroli MIDC, Shanghai Kinglink Industry, Zxcrusher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sand Washing Machine Market Evolving Landscape
Automation of particle classification and real-time moisture sensing is compressing operator headcount requirements while elevating process consistency in high-throughput mining applications.
Sensor-based feed control is automating the adjustment of water injection rates and classifier speed based on real-time particle size distribution data. Large-scale aggregates producers in Australia and Brazil are deploying these systems at greenfield sites. This capability is automating the elimination of manual sampling and laboratory testing delays that previously required four-to-six hour feedback loops.
China's GB occupational health frameworks are tightening permissible exposure limits for respirable crystalline silica in quarry environments. Equipment manufacturers must now engineer sealed enclosures with HEPA filtration and negative-pressure maintenance access panels. Bucket wheel washer suppliers serving European markets are leveraging this regulatory convergence to standardize dust-tight designs across export portfolios.
Lifecycle service contracting is displacing transactional spare parts purchasing among Indian mining operators. Annual tonnage-based agreements covering wear component replacement and process optimization are capturing multi-year revenue streams. This shift is most visible in Gujarat's limestone quarry clusters where contractor-operated sand plants dominate supply to ready-mix concrete networks.
Sand Washing Machine Market Segmentation
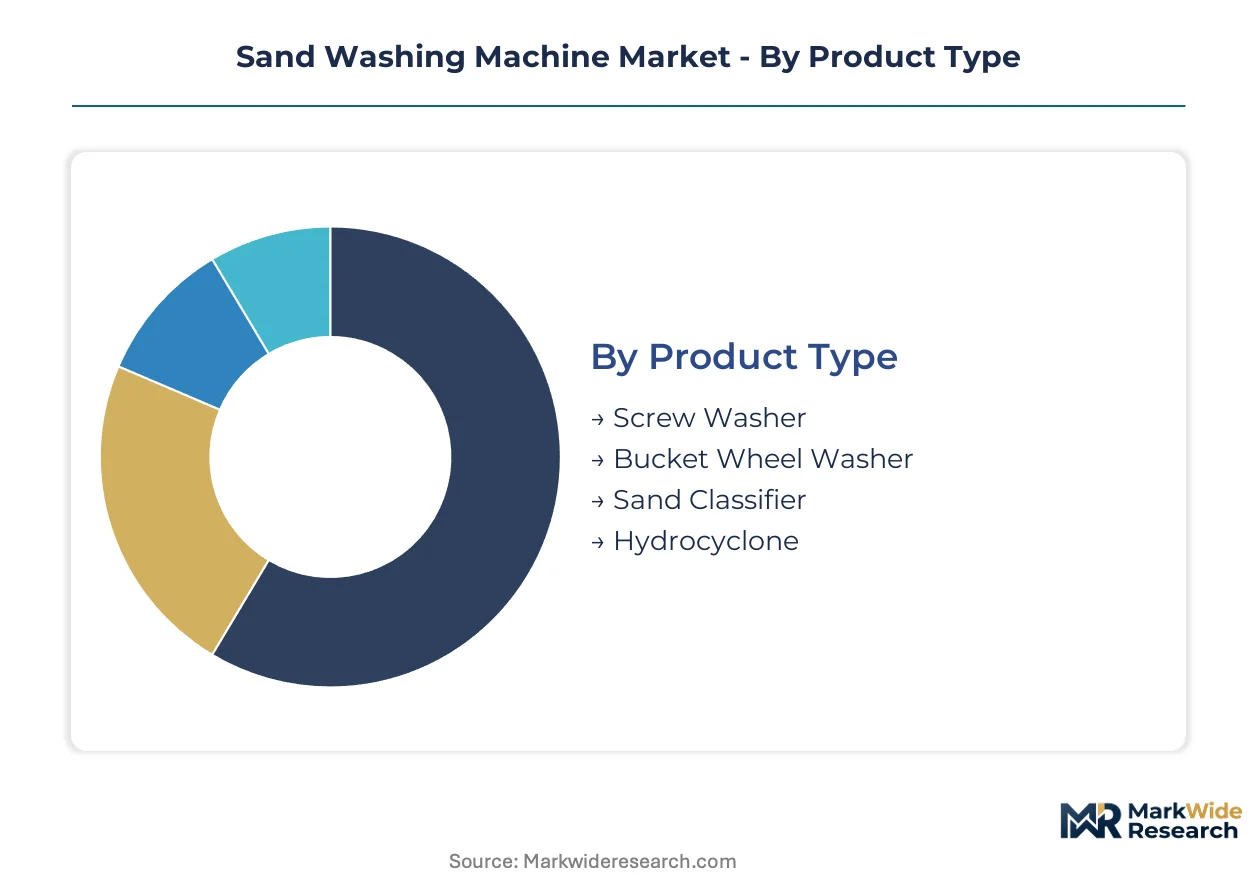
Sand washing machine procurement hinges on water recovery mandates, throughput requirements, and civil works constraints. Buyers prioritize technology configurations that balance capital efficiency against regulatory compliance in their specific operating jurisdictions.
Product Type:
Capital outlay and maintenance accessibility drive equipment selection across quarry and mining operations.
- Screw Washer:Spiral blade assemblies agitate sand slurry through an inclined trough to remove fines and clay. India's western state quarry clusters favor these units for their mechanical simplicity and lower spare parts inventory burden under CEA groundwater extraction constraints.
- Hydrocyclone:Centrifugal force separates particles by size through vortex classification without moving parts. Mining operators in Australia and Brazil deploy hydrocyclone arrays at greenfield sites to achieve eighty-plus percent water recovery rates, displacing legacy screw washer fleets.
- Bucket Wheel Washer:Rotating bucket wheels lift and dewater sand in continuous circuits. European aggregate producers specify these for CE-marked installations where REACH compliance elevates certification thresholds.
- Sand Classifier:Settling tanks with overflow weirs separate particle sizes by differential sedimentation. Smaller concrete batching plants in Southeast Asia specify these for their minimal power draw and containerized transportability.
Volume sits with Screw Washer; growth tilts toward Hydrocyclone.
Technology:
Water consumption intensity and energy efficiency differentiate procurement tiers across regulatory environments.
- Mechanical:Motor-driven agitation and conveyor systems dominate installed base economics. Germany's quarry runoff standards are compressing replacement cycles for mechanical-only circuits lacking closed-loop integration.
- Pneumatic:Air classification replaces water-intensive washing for specific feed gradations. India's state pollution control boards are tightening groundwater extraction rules that push pneumatic adoption in water-stressed districts of Maharashtra and Gujarat.
- Hydraulic:Pressurized water jets augment particle separation in high-capacity configurations. Brazilian iron ore sand processing operations specify hydraulic-assisted units for laterite feedstocks with elevated clay content.
- Eco-friendly:Zero-liquid-discharge circuits with full water recycling and solar power integration. China's MEE wastewater discharge limits compel quarry operators toward these configurations in Shandong and Henan provinces.
Mechanical technology holds current volume leadership; Eco-friendly systems are climbing the fastest as MEE and REACH mandates harden.
End User:
Feedstock variability and output specifications shape equipment configuration requirements.
- Construction:Ready-mix concrete and asphalt producers require consistent grading for structural applications. Western India's highway expansion is concentrating demand in coastal quarry clusters serving Mumbai-Ahmedabad infrastructure corridors.
- Mining:Mineral sands and aggregate operations process high tonnages with variable ore grades. Australian mineral sands producers automate classification with real-time particle size distribution sensors to eliminate laboratory testing delays.
- Recycling:Construction and demolition waste processors recover sand from crushed concrete. European circular economy directives are expanding feedstock availability for specialized washing circuits in Germany and France.
- Agriculture:Silica sand for glass manufacturing and specialized soil amendments. Limited adoption outside specific regional glassmaking clusters in China and India.
Construction commands current procurement volume; Mining is gaining share fastest through automation adoption.
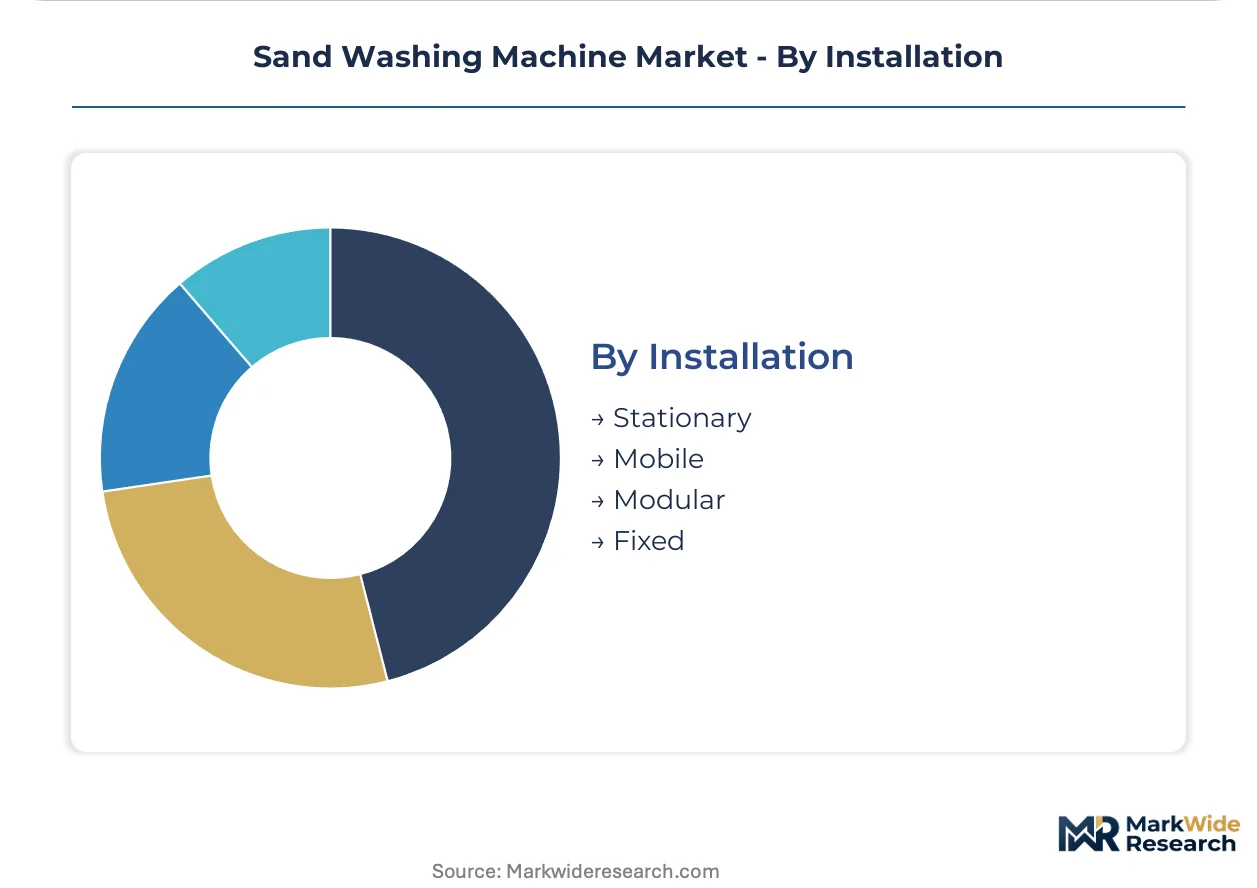
Installation:
Civil works capacity and site tenure determine capital deployment structure.
- Modular:Skid-mounted or containerized systems install without poured foundations. Southeast Asian mid-size sand plants bypass civil works through these configurations that commission within seventy-two hours.
- Mobile:Trailer-mounted units relocate between extraction faces. Indian contractor-operated quarry fleets favor mobile installations for limestone sand supply to ready-mix concrete networks in Gujarat.
- Stationary:Fixed foundations support permanent high-capacity operations. Large-scale Brazilian and Australian greenfield mining sites specify stationary configurations for twenty-plus year asset life.
- Fixed:Integrated concrete structures for dedicated processing lines. European aggregate producers in Bavaria and North Rhine-Westphalia deploy fixed installations under federal water protection law compliance timelines.
Stationary installations retain volume dominance; Modular systems show steepest expansion trajectory in Southeast Asian greenfield development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement clusters concentrate where infrastructure investment intersects with water scarcity regulations. Quarry operators in Germany, China, India, Australia, and Brazil face distinct compliance timelines that reshape equipment replacement priorities.
Germany
Bavaria and North Rhine-Westphalia aggregate producers accelerate fleet replacement under federal water protection laws mandating closed-loop circuits. Stricter quarry runoff standards compress capital deployment timelines toward hydrocyclone-based zero liquid discharge systems. Equipment certification costs elevate as CE marking and REACH compliance thresholds exclude smaller fabricators from procurement shortlists.
China
Shandong and Henan province quarry operators retrofit screw washer installations after MEE wastewater discharge limits took effect. The Zhengzhou-Gongyi manufacturing corridor dominates domestic supply but creates geographic vulnerability to regional power rationing. Closed-loop water recovery mandates force capital redeployment toward eco-friendly configurations with full recycling circuits.
India
Maharashtra and Gujarat state governments expand highway and port construction, concentrating sand processing demand in coastal quarry clusters. CEA groundwater extraction rules push mining operators toward water-efficient pneumatic classification systems. Contractor-operated limestone sand plants in Gujarat increasingly specify mobile installations for ready-mix concrete network supply.
Australia
Mineral sands producers automate classification with real-time particle size distribution sensors to eliminate laboratory testing delays. Greenfield sites deploy hydrocyclone arrays achieving eighty-plus percent water recovery rates. Western Australian operations lead automation adoption through sensor-based feed control systems that compress operator headcount requirements.
Brazil
Iron ore sand processing operations specify hydraulic-assisted units for laterite feedstocks with elevated clay content. Large-scale greenfield mining sites deploy stationary configurations for twenty-plus year asset life. Southeast Brazilian aggregates producers balance capital efficiency against throughput requirements in equipment selection decisions.
Sand Washing Machine Market Competitive Landscape
Chinese producers anchor the volume tier through manufacturing concentration in the Zhengzhou-Gongyi corridor; Indian and Turkish specialists hold differentiated positions in regional retrofit markets. Market structure tilts toward geographic fragmentation with tiered competitive positioning across certification-grade boundaries. Three archetypes dominate: integrated machinery conglomerates with captive foundry capacity, hydrocyclone-focused process engineering specialists, and modular skid-mounted system fabricators serving rapid-deployment segments. Capacity expansion and technology licensing constitute the dominant competitive moves as players respond to water recovery mandate timelines.
Among Chinese fabricators, Gongyi Forui Machinery and LZZG Machine exemplify the manufacturing-scale archetype, leveraging proximity to quarry retrofit demand in Henan and Shandong provinces. Nesans occupies a position within the process engineering specialist tier, anchoring hydrocyclone integration capabilities for Indian mining operators. Shanghai Kinglink Industry and Shibang Industry and Technology represent the integrated machinery conglomerate model with cross-border equipment portfolios. These named entities illustrate how geographic origin and corporate structure align with distinct strategic positioning vectors rather than converging on uniform competitive approaches.
| Leading Market Players |
|---|
| Gongyi Forui Machinery |
| Nesans |
| LZZG Machine |
| Rockman Equipments |
| FABO Stone Crusher Machines |
| Shibang Industry and Technology |
| Shiroli MIDC |
| Shanghai Kinglink Industry |
| Zxcrusher |
| Others |
Value Network & Pricing Analysis
Hydrocyclone integration into legacy screw washer fleets simultaneously compresses capital recovery timelines and concentrates procurement leverage among process engineering specialists with vortex sizing expertise. China's MEE zero-liquid-discharge mandates and Germany's quarry runoff standards are forcing buyers toward premium-tier configurations, fragmenting price architecture across certification-grade boundaries.
Pricing Analysis
Volume sits with mechanical screw washers while margins concentrate in hydrocyclone arrays and eco-friendly zero-liquid-discharge systems. Three-tier pricing structure across CE-marked European configurations, CEA-compliant Indian installations, and unstandardized Chinese domestic units reflects REACH certification costs and water recovery performance tiers. Cost compression in the mechanical tier intensifies because Henan manufacturing concentration exposes fabricators to nickel and manganese alloy price swings. Contractor-operated quarry fleets in Gujarat exhibit highest price sensitivity, while Australian mineral sands producers prioritize automation-enabled process consistency over capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining operator demand in Australia and Brazil, while distributor networks serve mid-size Southeast Asian sand plants through modular skid-mounted configurations. Manufacturing gravity centers on China's Zhengzhou-Gongyi corridor, with secondary supply clusters in India's Pune-Nashik industrial belt and Turkey's Ankara-based fabrication base. Abrasion-resistant plate, alloy screw flights, and hydrocyclone polyurethane liners constitute critical input dependencies. Single-source vulnerability concentrates in Henan province where regional power rationing and logistics disruptions threaten delivery timelines. Distribution runs through equipment leasing consortia and EPC contractors for greenfield mining sites, with aftermarket parts flowing through regional service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sand washing machine sector is executing a technology-transition phase as sensor-based feed control and real-time particle classification displace manual sampling and laboratory testing delays. Hydrocyclone-based water recovery circuits are supplanting legacy screw washer fleets under tightening groundwater extraction and wastewater discharge mandates.
For Market Incumbents: Anchor hydrocyclone sizing expertise through captive process engineering talent pools to defend against modular skid-mounted entrants penetrating Southeast Asian rapid-deployment segments. Deepen backward integration into abrasion-resistant alloy foundry capacity to buffer nickel and manganese price volatility eroding mechanical tier margins. Prioritize REACH and CE marking certification maintenance to exclude smaller fabricators from European procurement shortlists. For New Entrants and Emerging Players: Digital-channel route through remote condition monitoring subscription models offers lowest-friction entry into Indian mining operator contracts seeking to unbundle hardware from service revenue. Target Gujarat limestone quarry clusters where contractor-operated sand plants dominate ready-mix concrete supply and mobile installation demand outstocks stationary configurations. Pursue pneumatic classification white-space in water-stressed Maharashtra districts under CEA groundwater extraction tightening. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated machinery conglomerates seeking hydrocyclone process engineering capabilities to complete closed-loop water recovery portfolios. Long-term viability favors specialists with demonstrated vortex finder and spigot diameter selection expertise for variable feed grades. Watch OSHA crystalline silica rulemaking progression as inflection indicator for sealed enclosure and negative-pressure ventilation retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocyclone Technology Licensing | Enables rapid capability acquisition for screw washer incumbents facing MEE compliance deadlines in Shandong. |
| Modular Skid-Mounted Expansion | Addresses Southeast Asian demand for seventy-two-hour commissioning without poured foundations. |
| Remote Condition Monitoring Launch | Captures Indian mining subscription revenue through vibration sensors and oil analysis telemetry unbundling. |
| Silica Dust Enclosure Retrofit Program | Positions suppliers for OSHA crystalline silica rulemaking in construction materials processing. |
| Backward Integration Into Alloy Foundry | Secures captive supply of abrasion-resistant screw flights against nickel price volatility. |
Research Methodology
Independent corroboration across quarry operator maintenance directors, aggregate producer procurement teams, hydrocyclone process engineers, and aftermarket service heads underwrites the qualitative findings. Primary interviews with OEM sales directors and EPC contractor equipment specialists combined with secondary validation from customs trade data, MEE wastewater discharge filings, CEA groundwater extraction notifications, and SEC equipment manufacturer disclosures. Bottom-up installation tracking and top-down aggregate demand modeling triangulate volume estimates.
Comparable-period anchoring to historical replacement cycle data and regulatory compliance timeline announcements structures the projection horizon. The analytical framework models technology type, water recovery performance tier, installation mobility class, and end-use application across the analysis window. CAGRs derive from segment-level demand elasticity and capital redeployment pattern analysis. Forecast inputs include infrastructure investment pipeline tracking for western Indian highway expansion and greenfield mining project development databases for Australian mineral sands and Brazilian iron ore operations.
The model holds under stable regulatory enforcement intensity and alloy input price corridors; deviation in MEE discharge limit tightening velocity or nickel supply disruption magnitude would shift replacement cycle assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Cable Duct Market
Material Handling Equipment
Autonomous Material Handling Equipment Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
Rotary Breaker Market
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Flux Spraying Machine Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Industrial Counterweights Market
Material Handling Equipment
Europe Forklift Truck Market
Material Handling Equipment
United States Conveyor Belt Market