
 High Pressure Grinding Rollers Market | 2026-2036
High Pressure Grinding Rollers Market Size, Share, and Industry Trends Forecast 2026-2036
High Pressure Grinding Rollers Market Intelligence
The push for decarbonization in heavy industry, guided by frameworks like the EU Green Deal and China's dual carbon goals, is restructuring demand for energy-efficient comminution equipment. Metso Outotec Corporation leverages its extensive installed base and service network in the global mining sector. thyssenkrupp Industrial Solutions AG specializes in large-scale unit designs for high-tonnage operations. Meanwhile, FLSmidth & Co. A/S positions itself with integrated plant solutions for cement producers.
High Pressure Grinding Rollers are comminution machines that crush material between two counter-rotating rollers under immense force. This process, applying pressures often exceeding 100 MPa, induces efficient inter-particle breakage for mineral liberation. Mining applications, specifically for hard rock mineral processing, represent the largest demand segment over cement production. In terms of technology, systems with advanced control solutions and hydraulic pressure are displacing older mechanical press designs due to superior performance and energy savings.
Equipment design and market access are shaped by regulations from bodies like the US EPA and China's Ministry of Ecology and Environment (MEE) targeting energy use and particulate emissions. Worker safety standards, enforced by agencies like the US OSHA and Safe Work Australia, also dictate machine guarding and operational protocols. The critical decision for end-users centers on balancing the high initial capital investment against the long-term operational cost savings and environmental compliance benefits.
Market Dynamics
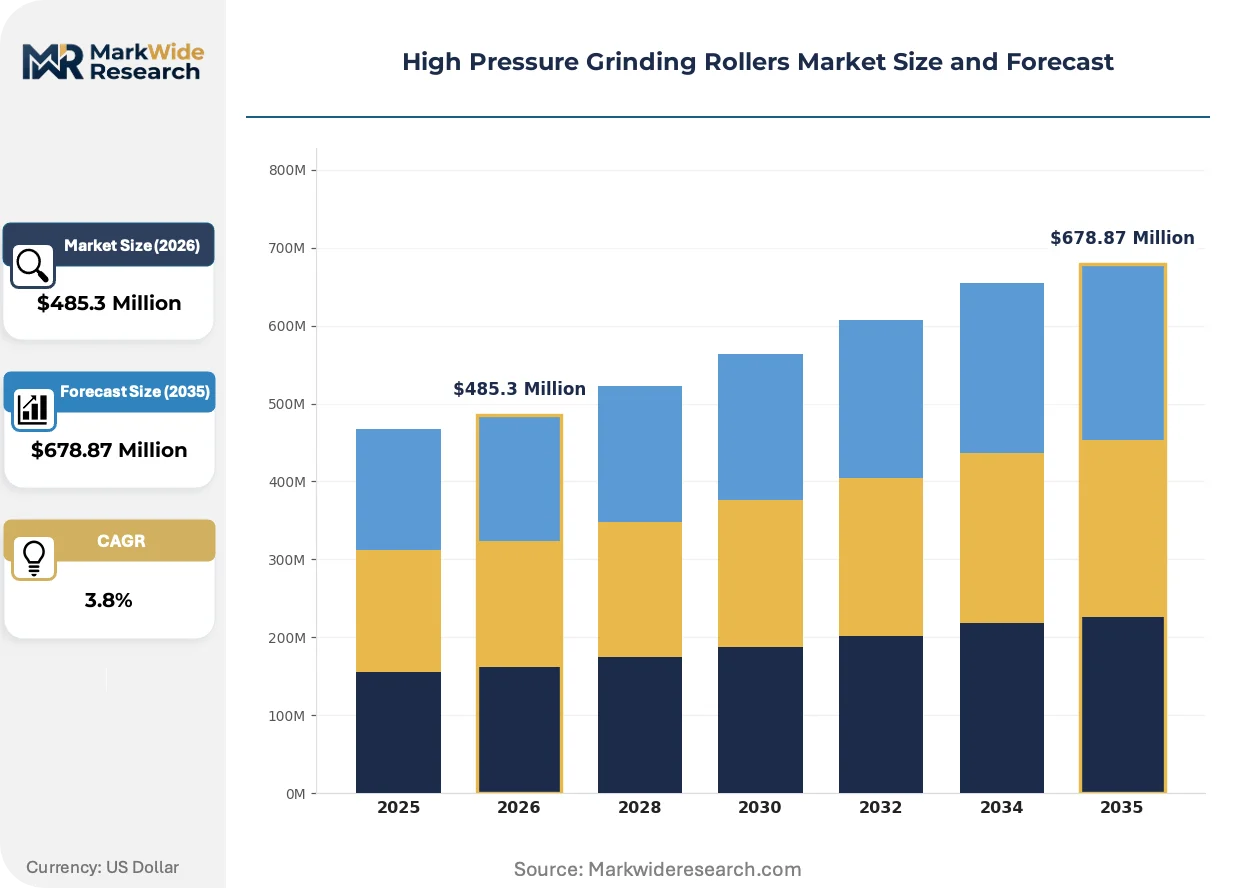
The central dynamic shaping the High Pressure Grinding Rollers market is the drive for comminution efficiency. This forces a direct trade-off between the high initial capital outlay for HPGR units and the substantial long-term operational savings in energy and media consumption compared to traditional milling circuits.
Growth Catalysts
- Decarbonization Policies:Frameworks like China's dual carbon goals and the EU Green Deal incentivize energy efficiency in heavy industry, favoring the adoption of HPGR technology over energy-intensive conventional grinding mills in both mining and cement sectors.
- Ore Grade Decline:As mining targets harder, more complex, and lower-grade ore bodies, the superior liberation and micro-cracking capability of HPGRs becomes essential for achieving viable recovery rates and downstream processing efficiency.
- Concentrated Mining Investment:Significant capital expenditure on new mining projects and brownfield expansions in resource-rich jurisdictions, particularly for copper and iron ore in Australia and Chile, directly fuels demand for high-capacity comminution equipment.
Market Restraints
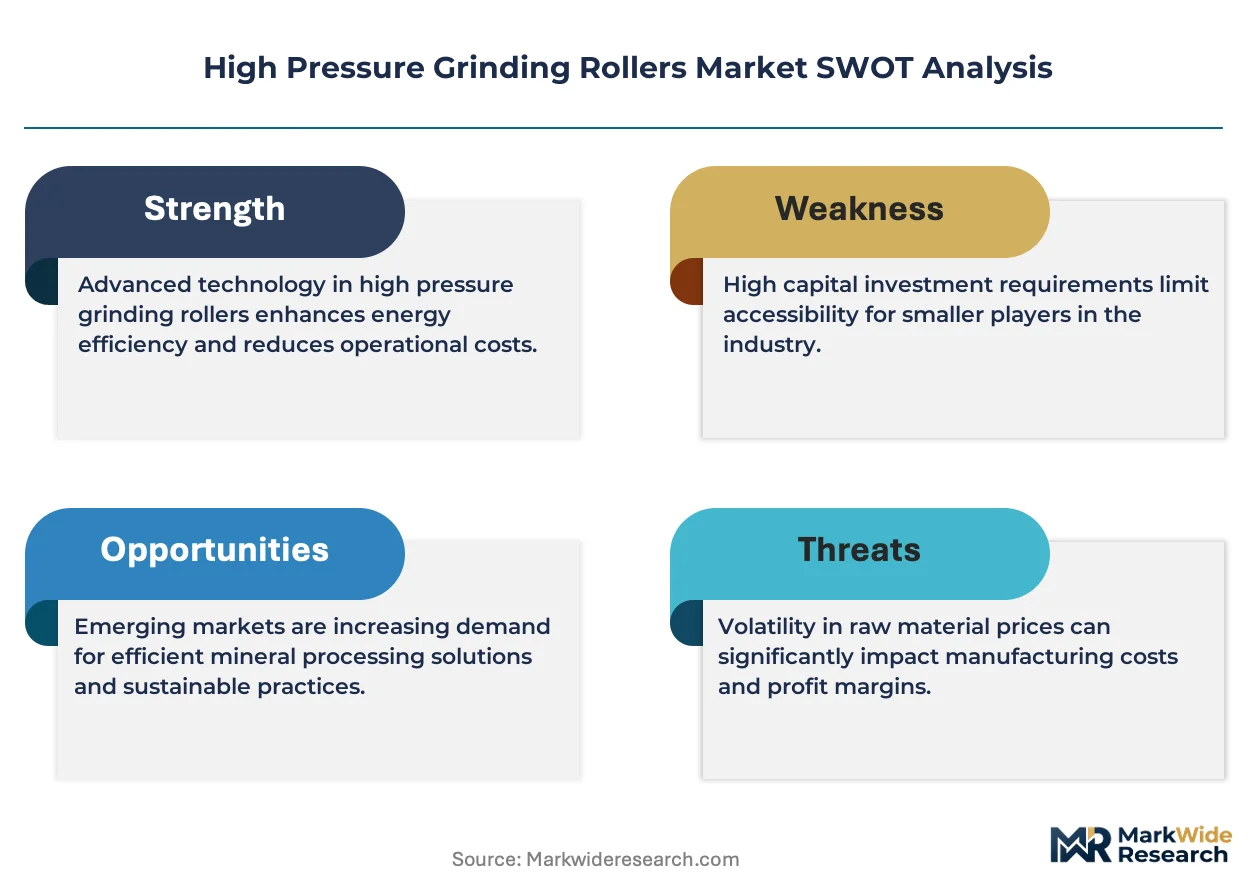
- High Capital Expenditure:The significant upfront investment required for HPGR units compared to conventional crushers and mills remains a primary barrier, particularly for junior miners or smaller-scale cement producers with limited capital budgets.
- Feed Material Sensitivity:HPGR performance is highly sensitive to variations in feed moisture, size distribution, and clay content, which can lead to operational instability and require sophisticated upstream process control to mitigate. -
- Alternative Technology Competition:In certain applications, advanced and highly optimized semi-autogenous grinding (SAG) and ball mill circuits can present a competitive alternative, especially where project economics prioritize lower initial capex over long-term energy savings.
Strategic Opportunities
- Industrial Minerals Processing:There is an opportunity to expand HPGR applications beyond primary mining into industrial minerals like limestone, bauxite, and slag grinding, where energy efficiency and precise particle size control offer a competitive advantage.
- Service and Aftermarket Expansion:Manufacturers can develop comprehensive service packages, including remote monitoring, predictive maintenance, and wear part management, creating recurring revenue streams and deepening customer relationships beyond the initial equipment sale.
- Retrofit and Hybrid Circuits:A significant opportunity exists in retrofitting HPGR units into existing comminution circuits. This allows operators to debottleneck plants and increase throughput without a complete greenfield investment.
Industry Challenges
- Skilled Labor Scarcity:A shortage of metallurgists and maintenance technicians with the specialized expertise to operate, optimize, and service advanced HPGR systems constrains effective deployment and can impact long-term equipment performance.
- Wear Component Supply Chain:The long lead times and logistical complexity associated with manufacturing and supplying critical wear components, such as tires and studs, pose a risk to operational continuity for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Pressure Grinding Rollers Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $678.87 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Mill, Grinding Roller, Machinery Components, Wear Parts Application: Cement Production, Mining, Aggregates, Metallurgical Processing End User: Cement Manufacturers, Mining Companies, Construction Firms, Industrial Processors Technology: Mechanical Pressing, Hydraulic Pressure, Energy-Efficient Systems, Advanced Control Solutions |
| Companies Covered | CITIC Heavy Industries Co. Ltd., Maschinenfabrik Köppern GmbH & Co. KG, FLSmidth & Co. A/S, SGS S.A., The Weir Group PLC, Metso Outotec Corporation, thyssenkrupp Industrial Solutions AG, TAKRAF GmbH, KHD Humboldt Wedag International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Pressure Grinding Rollers Market Strategic Shifts & Innovations
The evolution of High Pressure Grinding Rollers is defined by the integration of digital intelligence with mechanical force. This trend moves beyond raw crushing power, focusing on data-driven optimization to meet stringent energy and environmental performance standards demanded by modern industrial operators.
Advanced process control is a key product evolution. These systems use sensors to monitor roller pressure, gap, and motor power, adjusting parameters in real-time to optimize energy consumption and product size distribution. Mining operators processing hard rock ores are the primary adopters, seeking to maximize mineral liberation. This advanced automation is converging with AI-driven predictive analytics, enabling comminution circuits to self-optimize and preemptively schedule maintenance.
European Union industrial policies, specifically directives tied to the EU Green Deal, are mandating stricter energy consumption and emissions reporting for heavy industries. This regulatory pressure directly impacts the operational licenses of cement producers and mineral processors, forcing them to invest in more efficient equipment. The cement sector, especially in Germany and France, is most affected, accelerating the replacement of legacy ball mills with HPGR technology to meet compliance targets.
A shift from transactional equipment sales to performance-based service contracts is altering buyer behavior. This model disrupts the traditional upfront purchase by bundling multi-year maintenance, wear part supply, and operational support into a single agreement. End-users in major mining regions like Australia and Chile increasingly favor these arrangements, as they transfer technical risk to the manufacturer and align costs with production outcomes.
High Pressure Grinding Rollers Market Segmentation
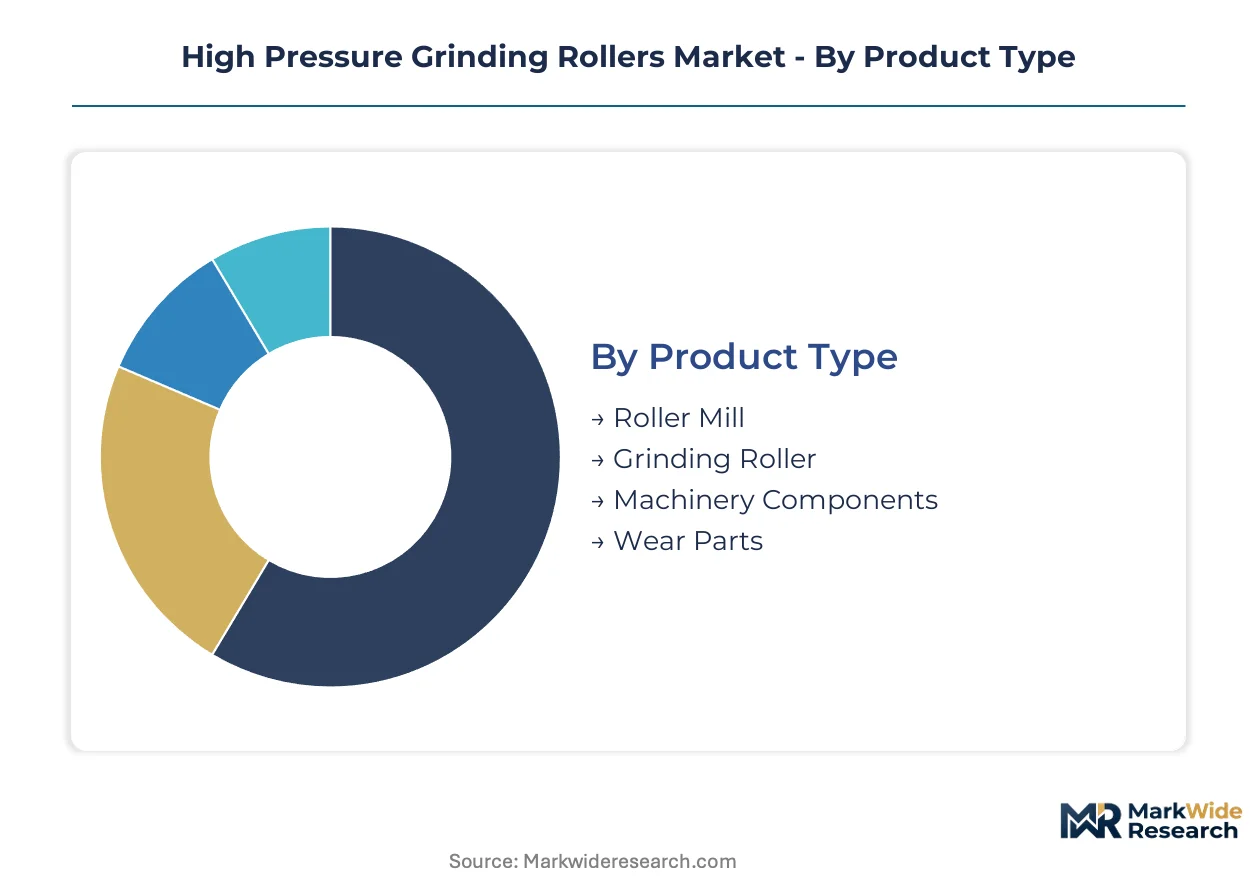
The segmentation analysis illuminates the diverse components, applications, and technological advancements driving the High Pressure Grinding Rollers market. Understanding these distinct segments provides clarity on demand patterns and the strategic focus areas for manufacturers. This granular view reveals where investment and innovation are most concentrated.
Product Type:
The upgrade and replacement cycle for High Pressure Grinding Rollers significantly influences demand across various product types. End-users evaluate the longevity and performance of individual components when planning capital expenditures.
- Grinding Roller:These are the core elements of an HPGR unit, comprising the rotating cylinders that apply immense pressure to material. Demand concentrates in hard rock mining operations in Australia and Chile, driven by the need for efficient comminution of increasingly complex ore bodies.
- Wear Parts:These consumable components, such as tires and studs, require regular replacement due to abrasive forces during operation. Mining companies and cement producers globally prioritize reliable supply chains for these critical parts to ensure operational continuity and minimize downtime.
- Roller Mill:Complete HPGR machines, including the frame, drive system, and grinding rollers, are procured for new plant installations or major capacity expansions.
- Machinery Components:This segment includes ancillary parts like bearings, hydraulic systems, and motors that support the primary grinding function of HPGR units.
Grinding Roller sits at the top of the volume ranking, with Wear Parts climbing the fastest.
Application:
The diverse applications for High Pressure Grinding Rollers reflect their versatility in processing various raw materials. Each application presents unique requirements for material throughput, particle size distribution, and energy efficiency.
- Mining:HPGRs are indispensable in hard rock mining for pre-grinding and comminution of ores like copper, iron, and gold. Mining operations in regions such as Australia and Chile are heavily investing in this technology to enhance mineral liberation and reduce energy consumption.
- Cement Production:In the cement industry, HPGRs are used for clinker grinding, significantly reducing the energy required compared to traditional ball mills. European cement producers, particularly in Germany and France, adopt HPGRs to meet stringent decarbonization targets.
- Aggregates:HPGR technology finds use in the production of construction aggregates, offering improved particle shape and reduced fines compared to conventional crushers.
- Metallurgical Processing:This application involves using HPGRs for specific comminution stages in metallurgical plants to prepare material for further refining processes.
Mining applications command the largest share, with Cement Production expanding most quickly due to efficiency mandates.
End User:
The end-user landscape for High Pressure Grinding Rollers is shaped by the scale of operations and the specific processing needs of different industrial sectors. Procurement decisions are influenced by capital availability and long-term operational cost benefits.
- Mining Companies:These entities operate large-scale mineral extraction and processing facilities, requiring high-capacity and energy-efficient comminution equipment. Major global mining groups are primary purchasers, seeking to optimize recovery rates from lower-grade ores.
- Cement Manufacturers:Producers of cement utilize HPGRs to reduce energy consumption in clinker grinding and improve product quality. Companies in Europe and Asia are upgrading their facilities to comply with environmental regulations and reduce operational expenses.
- Construction Firms:While not direct primary users, large construction firms may indirectly drive demand through their requirements for high-quality aggregates and specialized processed materials.
- Industrial Processors:This broad category encompasses various industries that require fine grinding of bulk materials, such as industrial minerals, where precise particle size control is critical.
Mining Companies represents the fastest-growing segment, while Cement Manufacturers are increasingly adopting HPGR technology to meet sustainability goals.
Technology:
The technological evolution within High Pressure Grinding Rollers focuses on enhancing performance, energy efficiency, and operational control. Innovations are consistently introduced to address the complex challenges of material comminution.
- Hydraulic Pressure:Modern HPGR systems primarily utilize hydraulic cylinders to apply and maintain the immense grinding force between the rollers. This technology allows for precise pressure control and overload protection, crucial for processing varied feed materials.
- Advanced Control Solutions:These systems integrate sensors and software to monitor operational parameters like roller gap, pressure, and motor power, enabling real-time adjustments for optimized energy use and product quality. Mining operators globally leverage these solutions for predictive maintenance and process optimization.
- Mechanical Pressing:Older generation HPGRs relied more on mechanical springs or fixed gaps for pressure application, offering less flexibility and control compared to hydraulic systems.
- Energy-Efficient Systems:This segment includes design features and operational modes aimed at minimizing power consumption per ton of processed material, aligning with global decarbonization efforts.
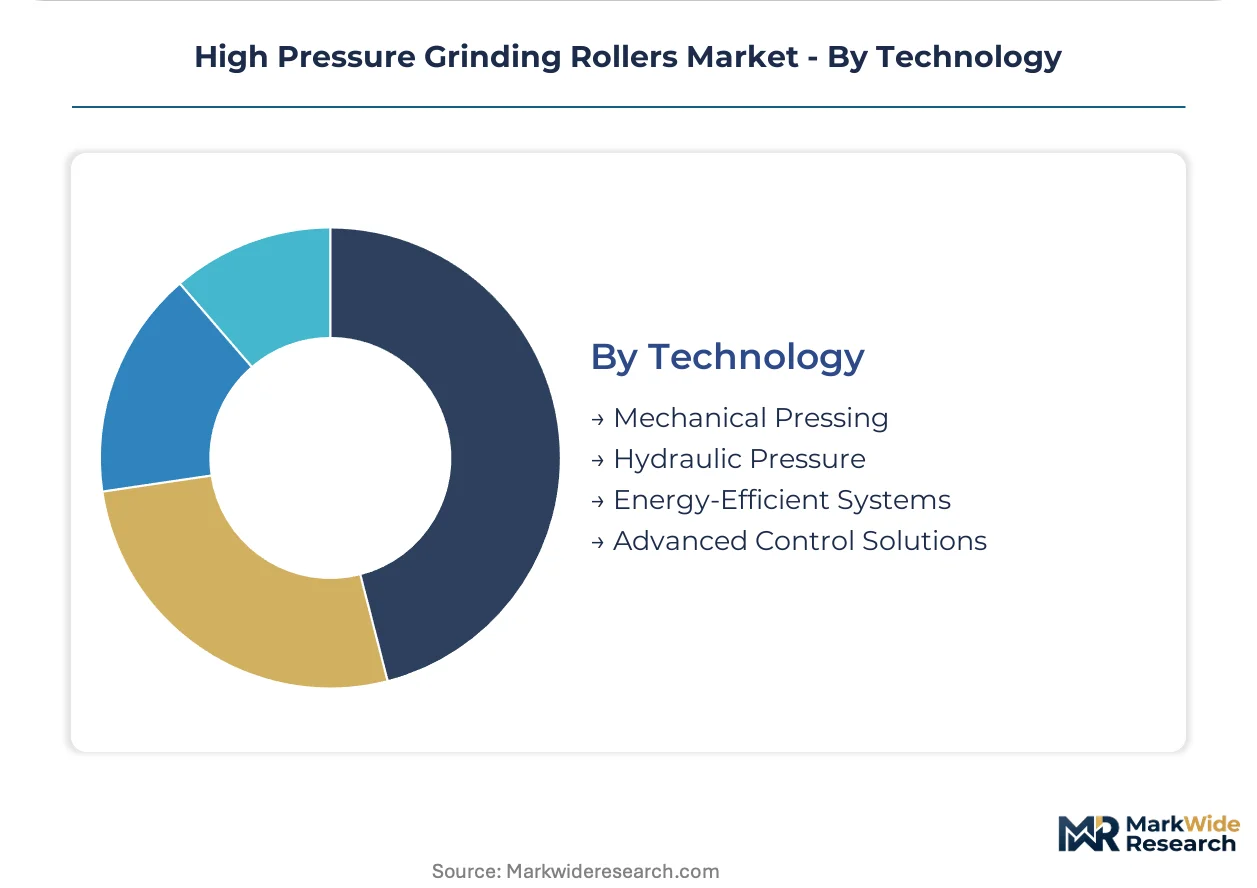
Hydraulic Pressure technology dominates the market, with Advanced Control Solutions exhibiting the steepest expansion trajectory as operators seek greater automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled engineering workforce anchors the High Pressure Grinding Rollers market across key mining and industrial regions. These specialized teams drive innovation and operational excellence for comminution technologies. Strategic investments in advanced processing capabilities are evident from these concentrations.
Australia
Demand for High Pressure Grinding Rollers in Australia stems from extensive iron ore and copper mining operations. The Australian government's critical minerals strategy promotes efficient processing technologies. Western Australia's Pilbara region, a major iron ore hub, sees continuous investment in high-capacity comminution equipment. Mining companies there prioritize HPGR adoption for energy efficiency.
Chile
Chile's vast copper reserves drive significant demand for HPGR units, particularly for processing lower-grade porphyry ores. The country's environmental regulations, enforced by the Ministry of Environment, encourage energy-efficient mineral processing. Antofagasta, a key mining region, hosts numerous large-scale operations upgrading their comminution circuits. These facilities leverage HPGRs to enhance mineral liberation and reduce water consumption.
China
Rapid industrialization and a focus on resource efficiency fuel HPGR adoption in China for both mining and cement production. China's dual carbon goals, overseen by the MEE, mandate energy consumption reductions in heavy industries. The Yangtze River Delta region, with its dense industrial base, observes significant investment in HPGR technology. Cement manufacturers and mining companies in this area are modernizing their plants.
Germany
Germany's advanced manufacturing sector and stringent environmental standards contribute to the demand for high-efficiency HPGRs in cement and industrial minerals. The EU Green Deal and national regulations push for lower carbon footprints in industrial processes. North Rhine-Westphalia, a traditional industrial heartland, sees cement producers investing in HPGR technology. These companies aim for superior clinker grinding efficiency.
United States
The United States market for HPGRs is influenced by its diverse mining operations and growing industrial minerals sector. The US EPA regulations on energy efficiency and emissions drive adoption of advanced comminution solutions. Nevada, a major gold mining state, features operations integrating HPGRs for improved ore processing. Industrial processors across the Midwest also utilize HPGRs for fine grinding applications.
High Pressure Grinding Rollers Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in the High Pressure Grinding Rollers sector. This market features a tiered structure, with established industrial giants alongside specialized technology providers. Strategic archetypes include vertically integrated manufacturers, component specialists, and engineering firms offering integrated solutions. Competitive moves primarily involve strategic partnerships to expand service networks and continuous portfolio diversification into new applications.
Among established industrial giants, Metso Outotec Corporation, a Finland-based company, represents a comprehensive provider of mineral processing equipment. Germany-based thyssenkrupp Industrial Solutions AG exemplifies large-scale engineering capabilities for heavy machinery, including HPGR units. Denmark-based FLSmidth & Co. A/S occupies a position as a specialist in integrated plant solutions, particularly for the cement industry. These entities anchor the premium segment, offering advanced technologies and extensive global service networks. Their market presence is characterized by deep customer relationships and a focus on long-term operational support. Such firms often engage in strategic alliances to enhance their technological offerings and expand geographic reach.
| Leading Market Players |
|---|
| CITIC Heavy Industries Co. Ltd. |
| Maschinenfabrik Köppern GmbH & Co. KG |
| FLSmidth & Co. A/S |
| SGS S.A. |
| The Weir Group PLC |
| Metso Outotec Corporation |
| thyssenkrupp Industrial Solutions AG |
| TAKRAF GmbH |
| KHD Humboldt Wedag International AG |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and publicly traded industrial giants collectively influence the High Pressure Grinding Rollers market. This ownership structure directly impacts long-term investment in wear part manufacturing and pricing strategies for integrated solutions.
Pricing Analysis
Bundled service contracts versus unbundled equipment sales define the pricing landscape for High Pressure Grinding Rollers. This market primarily utilizes a project-based pricing model for new installations, often incorporating long-term service agreements. Price differentiation stems from after-sales service quality, customization levels for specific ore bodies, and manufacturer brand premium. Pricing pressure stems from the need for operators to balance high initial capital outlay against long-term operational savings. Major mining groups are less price-sensitive, prioritizing performance and uptime, while smaller cement producers exhibit higher price sensitivity.
Supply Chain Analysis
China's domestic content mandates for heavy machinery are reshaping sourcing patterns for High Pressure Grinding Rollers. The supply chain for HPGR units and their critical wear parts concentrates in Germany, China, and Finland, leveraging specialized engineering and manufacturing capabilities. Raw material dependencies include specialized steel alloys for grinding rollers and high-strength hydraulic components. Long lead times for manufacturing and supplying critical wear components, such as tires and studs, pose a significant supply chain risk. Distribution runs through direct sales channels from equipment manufacturers to end-users, supplemented by regional service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The High Pressure Grinding Rollers market represents a late-cycle quality story, driven by a demand shift towards premium specifications for energy-efficient comminution. Mining companies increasingly seek advanced control solutions to optimize mineral liberation from complex ore bodies.
For Market Incumbents: Lock in long-term service contracts, especially for existing installed bases in Australia and Chile. Incumbents face a threat from alternative comminution technologies and specialized component manufacturers. Investment in R&D for advanced control systems and predictive maintenance platforms can enhance existing product lines. Expanding global service networks ensures prompt delivery of wear parts, mitigating operational downtime for key clients.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for new entrants offering energy-efficient HPGR solutions to cement producers. White-space targets include industrial minerals processing, such as bauxite and limestone, where precise particle size control is valued. A compelling go-to-market angle involves offering performance-based contracts that align manufacturer incentives with customer operational savings. Targeting smaller-scale cement producers and regional aggregate firms in emerging markets can provide initial traction.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized component manufacturers and service providers with strong intellectual property. The long-term viability of the HPGR market is robust, supported by global decarbonization efforts and declining ore grades. Acquisition targets should focus on firms developing advanced control software or specialized wear-resistant materials. The signal to watch is the increasing share of HPGR units in new mining project tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Service Network in Australia | Ensures critical wear part availability for major iron ore and copper mining operations. |
| Invest in AI-driven Predictive Maintenance | Optimizes HPGR uptime and reduces operational costs for end-users like Metso Outotec Corporation. |
| Develop HPGRs for Industrial Minerals | Diversifies application base beyond mining and cement into sectors like limestone and bauxite processing. |
| Form Strategic Partnerships for Retrofits | Accelerates HPGR integration into existing comminution circuits, offering efficiency gains to operators. |
| Enhance Wear Part Material Science | Extends component lifespan, directly addressing a key operational challenge for thyssenkrupp Industrial Solutions AG. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a comprehensive market view. This involved primary research with plant managers, metallurgists, procurement leads, and R&D directors across mining and cement sectors. Secondary validation utilized mining association reports, company annual reports, regulatory filings with the US EPA, and patent databases. A bottom-up approach informed market sizing, while top-down analysis validated overall market trends.
The segment-weighting approach was applied to project market growth across the analysis window. This framework modeled market dynamics based on product type, application, end-user, technology, and regional mining intensity. Compound annual growth rates were derived from historical data and projected future demand drivers, such as global ore grade decline rates. Key industry-specific forecast inputs included anticipated capital expenditure in major mining jurisdictions and energy efficiency mandates from China's MEE.
Revisions become necessary when significant shifts in commodity prices or geopolitical instability impacting mining investment materialize. Forecasts reflect assumptions regarding technological advancements and regulatory frameworks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Low Clearance Loaders Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Loader Bucket Attachments Market
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Industrial Wood Chipper Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Global Linear Guide Market
Material Handling Equipment
Mobile Conveyor Market