
 Middle East Conveyor Belts Market | 2026-2036
Middle East Conveyor Belts Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Conveyor Belts Market Outlook
Heavy-duty specification upgrades across oil-resistant and heat-stable grades is bifurcating the Middle East conveyor belts landscape. Continental AG leverages captive compound development to sustain premium positioning in Saudi mining contracts. Bridgestone Corporation anchors its regional footprint through localized splicing services and technical support centers. Fenner Dunlop Conveyor Belting differentiates via Kevlar-reinforced carcass designs purpose-built for Gulf bulk terminals.
Conveyor belts are continuous transport surfaces engineered from multi-ply fabric carcasses impregnated with nitrile, PVC, or polyurethane compounds, rated for tensile strengths exceeding 800 N/mm in heavy-duty configurations; they move bulk solids and unit loads through integrated production and distribution systems. Rubber belts dominate mining procurement across Oman and Qatar due to abrasion resistance and repairability in remote installations. Modular plastic belts represent the fastest-growing product category within food processing and pharmaceutical clean rooms across the UAE, where sanitation protocols and quick-change requirements command margin premiums over commodity alternatives.
Gulf Standardization Organization harmonization with ISO 14890 and DIN 22102 governs tensile rating and flame-resistance benchmarks across member states, while Saudi Standards, Metrology and Quality Organization enforces local conformity assessment for mining safety applications. The UAE's Ministry of Industry and Advanced Technology aligns industrial equipment codes with EU machinery directives to facilitate re-export positioning. Stakeholders must monitor evolving carbon-border adjustment mechanisms affecting European-bound petrochemical exports and their associated material handling infrastructure requirements.
Market Dynamics
Heat-resistant compound formulations are displacing standard rubber grades across Gulf Cooperation Council mining sites, forcing compound suppliers to recalibrate R&D pipelines and pricing architectures around thermal performance benchmarks rather than commodity tensile ratings.
Growth Catalysts
- Phosphate extraction expansion:Saudi Arabia's mining operators are scaling belt procurement for Ma'aden's Waad Al-Shamal complex, creating sustained demand for abrasion-resistant carcass designs rated above 1000 N/mm.
- GSO-ISO 14890 harmonization:The Gulf Standardization Organization's alignment with international tensile and flame-resistance benchmarks is eliminating technical barriers to cross-border procurement across member states.
- Jebel Ali logistics corridor concentration:UAE's port modernization and automated container handling retrofits are generating replacement cycles for modular plastic belt systems in high-throughput distribution centers.
Market Restraints
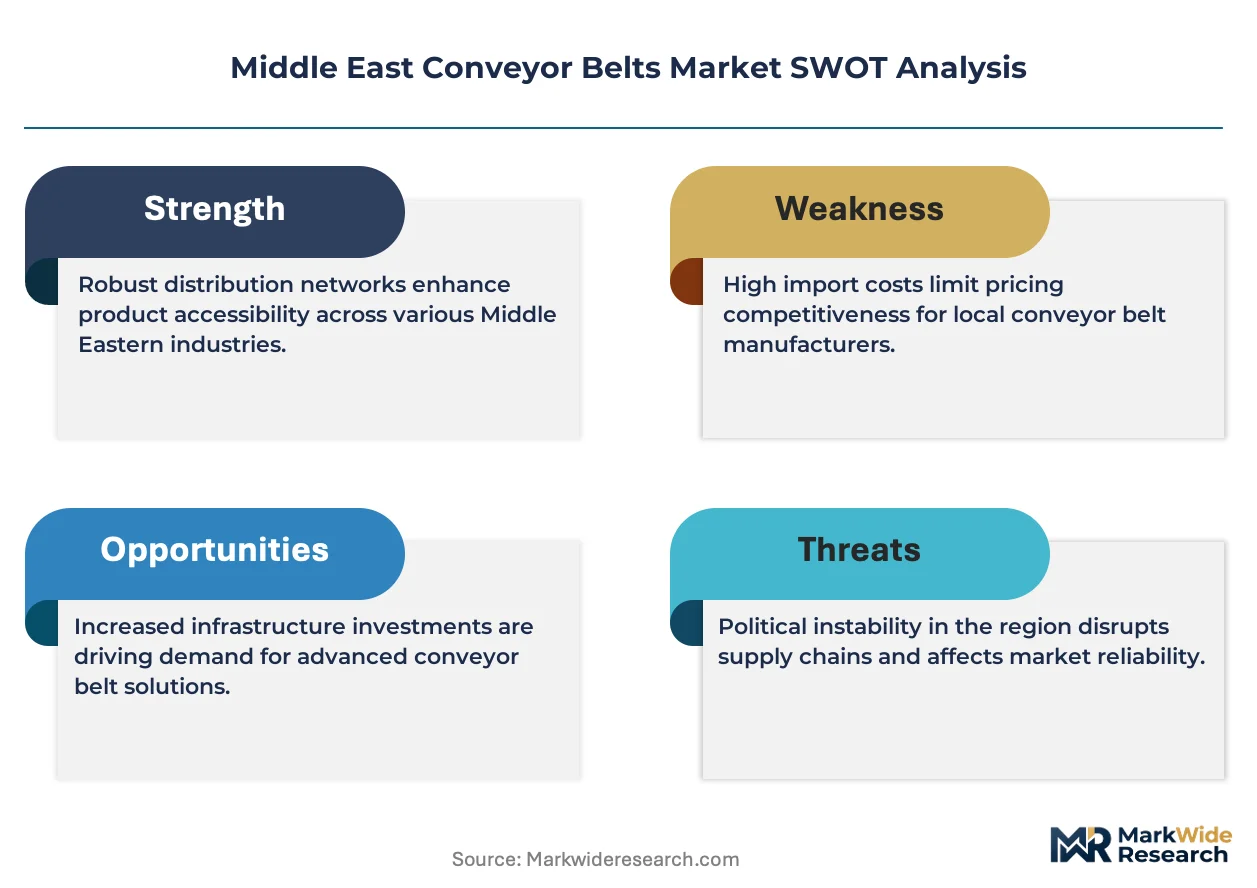
- Natural rubber price volatility:Feedstock cost swings tied to Southeast Asian supply disruptions compress margin predictability for compound-dependent manufacturers serving GCC contracts.
- Specialized splicing technician scarcity:The shallow regional talent pool for hot vulcanization and mechanical fastening expertise extends installation timelines and inflates service premiums.
- Steel cord import dependency:Limited domestic production of high-tensile reinforcement cables concentrates supply risk with East Asian mill sources.
Strategic Opportunities
- Oman mining greenfield development:Untapped copper and chromite extraction projects in the Al Batinah region present first-mover positioning for heat-stable belt suppliers.
- Food-grade modular plastic convergence:Quick-release sanitation designs are penetrating pharmaceutical clean rooms across Dubai's Jebel Ali Free Zone, displacing woven fabric alternatives.
- Saudi Vision 2030 localization mandates:Domestic content requirements for mining safety equipment are incentivizing joint venture formation between international belt manufacturers and Saudi industrial partners.
Industry Challenges
- SASO conformity assessment timelines:Saudi Standards, Metrology and Quality Organization certification bottlenecks for mining safety applications delay contract execution by 8-14 weeks.
- Legacy vulcanization equipment incompatibility:New-generation polyurethane compounds require press retrofits that many regional service depots have deferred.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Conveyor Belts Market |
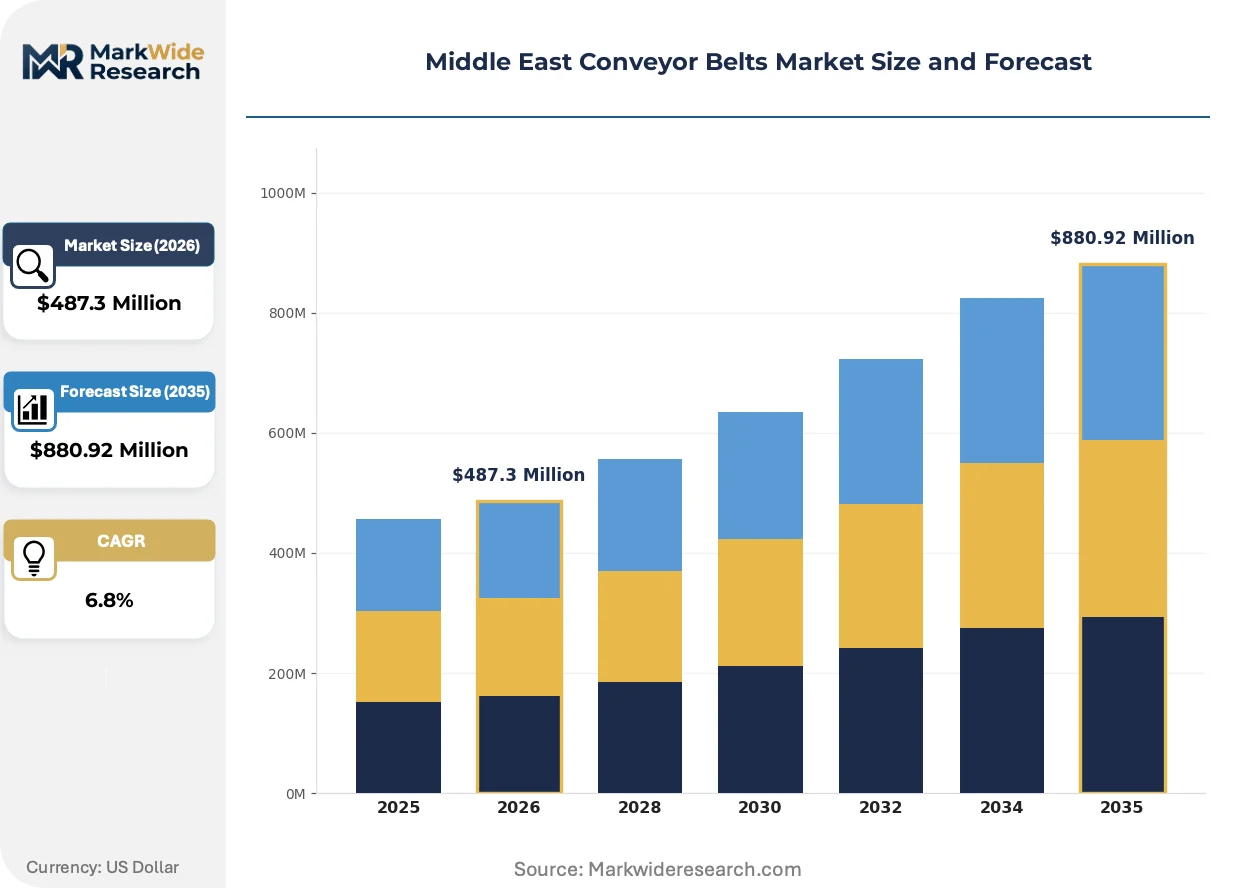
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Belts, Rubber Belts, PVC Belts, Metal Belts End User: Mining, Manufacturing, Food Processing, Logistics Installation Type: Fixed, Mobile, Automated, Semi-Automated Application: Material Handling, Packaging, Transport, Assembly |
| Companies Covered | Al Kuwaiti Industrial Solutions, Ziligen A.S., Arabian Universal, Semperit AG Holding, Habasit AG, Continental AG, Bridgestone Corporation, Fenner Dunlop Conveyor Belting, Phoenix Conveyor Belt Systems GmbH, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Conveyor Belts Market Strategic Shifts
Compound chemistry advances and regulatory harmonization are compressing product lifecycles while elevating performance specifications across Middle East material handling infrastructure.
Aramid fiber-reinforced carcass constructions are supplanting traditional polyester-nylon plies in high-impact mining applications. Saudi phosphate and bauxite operators are specifying Kevlar-based tensile members for their superior tear propagation resistance. This shift is compressing the addressable market for commodity-grade multi-ply designs while expanding premium compound development budgets.
Gulf Standardization Organization alignment with DIN 22102 flame-resistance protocols is mandating self-extinguishing cover grades across all member state mining procurement. Industrial consequence includes accelerated obsolescence of non-compliant inventory held by regional distributors. UAE-based bulk terminal operators are responding by front-loading replacement schedules to preempt enforcement deadlines.
Maintenance contracting is unbundling from original equipment supply across UAE logistics corridors. Third-party service providers are capturing splice and repair work previously bundled with belt sales, compressing manufacturer margin capture. This pattern is most visible in Dubai's Jebel Ali port cluster where specialized splicing contractors now hold multi-year framework agreements independent of belt procurement decisions.
Middle East Conveyor Belts Market Segmentation
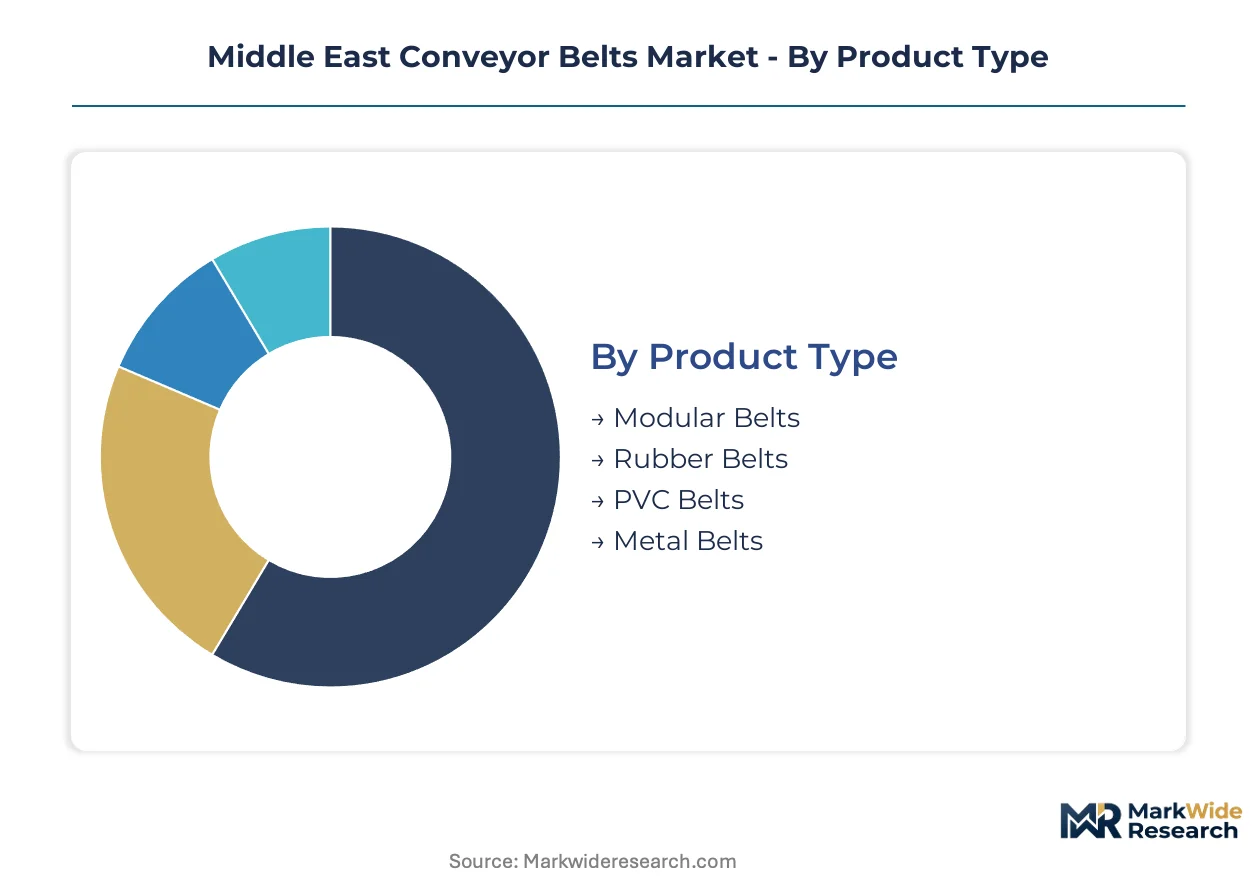
Conveyor belt procurement across the Middle East fragments sharply between export-oriented bulk terminals and domestically anchored manufacturing lines. Segment selection determines compound specification, regulatory compliance pathway, and service infrastructure requirements.
Product Type:
Rubber belts and modular systems concentrate in Saudi Arabia's mining corridors and the UAE's re-export hubs respectively, while PVC and metal alternatives serve more localized industrial niches.
- Rubber Belts:Multi-ply fabric carcasses impregnated with nitrile or SBR compounds, rated for tensile strengths exceeding 800 N/mm in heavy-duty configurations. Saudi phosphate and bauxite extraction at Ma'aden's Waad Al-Shamal complex drives specification upgrades toward heat-resistant formulations displacing standard grades.
- Modular Belts:Interlocking plastic segments engineered for quick-release sanitation and tool-free changeover. Dubai's Jebel Ali Free Zone food processing and pharmaceutical clean rooms command margin premiums over commodity alternatives due to stringent hygiene protocols.
- PVC Belts:Lightweight thermoplastic constructions dominate light manufacturing and assembly lines across UAE industrial zones where capital constraints limit heavy-duty procurement.
- Metal Belts:Stainless steel or carbon steel link designs specified for extreme temperature environments in Saudi petrochemical processing and high-heat curing applications.
Rubber belts hold the largest share; momentum sits with modular belts gaining share fastest in food-grade and pharmaceutical installations.
End User:
Cost tier differentiation separates premium-specification mining procurement from price-sensitive manufacturing segments, with logistics operators occupying a mid-tier performance band.
- Mining:Abrasion-resistant carcass designs rated above 1000 N/mm specified for phosphate, bauxite, and emerging copper extraction across Saudi Arabia's Eastern Province and Oman's Al Batinah region. SASO conformity assessment bottlenecks delay contract execution by 8-14 weeks.
- Logistics:High-throughput distribution centers in Jebel Ali and Saudi port modernization projects generate replacement cycles for automated handling systems. Third-party splicing contractors now capture maintenance work previously bundled with belt sales.
- Manufacturing:Standard multi-ply fabric belts serve automotive and construction material plants across UAE and Qatar where procurement prioritizes total cost of ownership over performance specifications.
- Food Processing:Modular plastic belt penetration accelerates in Dubai's free zones where quick-change sanitation designs displace woven fabric alternatives in clean room environments.
Mining commands the premium tier by specification intensity; food processing climbs fastest on regulatory sanitation mandates.
Installation Type:
Volume concentration favors fixed infrastructure in established extraction and port complexes, while mobility requirements emerge in greenfield mining development.
- Fixed:Permanent conveyor structures dominate Saudi mining installations and UAE bulk terminals where throughput predictability justifies capital-intensive foundation work. GSO-ISO 14890 harmonization eliminates technical barriers to cross-border procurement for these long-life assets.
- Automated:Sensor-integrated drive systems and predictive maintenance modules penetrate Jebel Ali logistics corridors where labor cost arbitrage and throughput optimization drive retrofit decisions.
- Mobile:Skid-mounted or crawler-based systems serve Oman's untapped copper and chromite greenfield projects where deposit geometry shifts frequently during exploration phases.
- Semi-Automated:Hybrid configurations bridge manual oversight and automated control in mid-scale manufacturing plants across Qatar and Kuwait where capital deployment remains cautious.
Fixed installations retain the dominant volume position; automated systems expand most quickly in UAE port modernization programs.
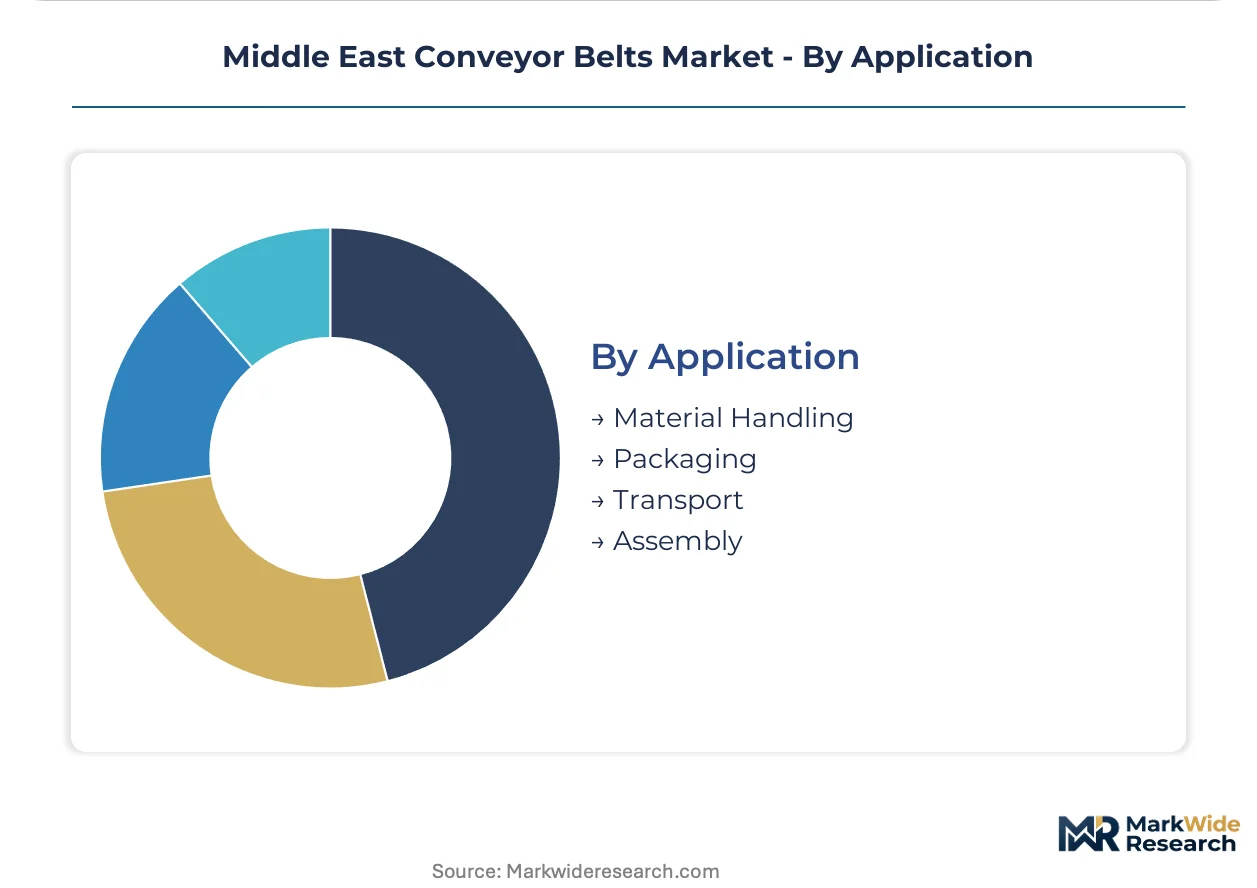
Application:
Application selection correlates directly with belt construction complexity, with material handling demanding the most sophisticated compound and carcass engineering.
- Material Handling:Bulk solid transport through integrated production systems requires Kevlar-reinforced carcass designs purpose-built for Gulf terminal impact conditions. Aramid fiber constructions are supplanting traditional polyester-nylon plies in high-impact mining applications.
- Transport:Unit load movement across distribution networks specifies modular plastic systems in UAE logistics hubs where sanitation protocols and quick-change requirements dominate selection criteria.
- Packaging:End-of-line accumulation and sortation belts in manufacturing facilities utilize lightweight PVC constructions where speed and precision outweigh durability demands.
- Assembly:Precision positioning applications in automotive and electronics manufacturing across Saudi industrial cities employ specialized timing belts and accumulation conveyors.
Material handling captures the greatest specification intensity; transport applications gain momentum on logistics automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across the Middle East. Saudi mining operators prioritize performance specifications over unit cost, while manufacturing buyers in smaller Gulf states negotiate aggressively on total landed cost.
Saudi Arabia
Ma'aden's Waad Al-Shamal phosphate complex and bauxite expansion in the Eastern Province drive specification upgrades toward heat-resistant formulations. SASO enforces conformity assessment bottlenecks that delay mining safety contracts by 8-14 weeks. The Eastern Province industrial cluster concentrates demand for abrasion-resistant carcass designs rated above 1000 N/mm.
United Arab Emirates
Jebel Ali port modernization and automated container handling retrofits generate replacement cycles for modular plastic belt systems. MOHAP sanitation protocols for pharmaceutical clean rooms in Dubai's free zones command margin premiums over commodity alternatives. Third-party splicing contractors now capture maintenance work previously bundled with belt sales across the logistics corridor.
Oman
Untapped copper and chromite extraction projects in the Al Batinah region present first-mover positioning for heat-stable belt suppliers. The country's national mining regulator oversees greenfield development permits for mobile conveyor installations where deposit geometry shifts frequently. Skid-mounted systems serve exploration phases before fixed infrastructure commitments.
Qatar
Construction material plants and mid-scale manufacturing facilities prioritize total cost of ownership over performance specifications. The central infrastructure planning authority channels procurement through framework agreements that favor established Gulf suppliers. Doha industrial zones exhibit cautious capital deployment favoring semi-automated hybrid configurations.
Kuwait
Petrochemical processing and high-heat curing applications specify metal belt constructions for extreme temperature environments. The national standards body aligns equipment codes with Gulf Standardization Organization harmonization to facilitate cross-border procurement. Domestic manufacturing remains limited, concentrating demand with regional distributors holding Saudi and UAE inventory.
Middle East Conveyor Belts Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Middle East conveyor belts landscape. Premium compound development and localized splicing services define the upper tier, while commodity trading houses compete on landed cost for standard multi-ply fabric grades. Two strategic archetypes dominate: integrated manufacturers with captive R&D pipelines, and regional distributors leveraging inventory positioning near Jebel Ali and Dammam port complexes. Competitive moves concentrate on joint venture formation with Saudi industrial partners and service infrastructure expansion.
Within the integrated manufacturer tier, Continental AG and Bridgestone Corporation exemplify divergent regional strategies. Continental leverages captive compound development to sustain premium positioning in Saudi mining contracts. Bridgestone anchors its footprint through localized splicing services and technical support centers. Among specialists in reinforced carcass designs, Fenner Dunlop Conveyor Belting occupies a position purpose-built for Gulf bulk terminal impact conditions. Regional distributors including Al Kuwaiti Industrial Solutions and Arabian Universal sit within the trading-house archetype, competing on logistics proximity rather than technical specification depth.
| Leading Market Players |
|---|
| Al Kuwaiti Industrial Solutions |
| Ziligen A.S. |
| Arabian Universal |
| Semperit AG Holding |
| Habasit AG |
| Continental AG |
| Bridgestone Corporation |
| Fenner Dunlop Conveyor Belting |
| Phoenix Conveyor Belt Systems GmbH |
| Others |
Value Chain & Pricing Dynamics
Ninety-day compound inventory buffers at Jebel Ali distributors concentrate pricing leverage with regional trading houses while compressing margin capture for manufacturers serving spot procurement in smaller Gulf states. This lead-time asymmetry rewards inventory positioning near Saudi Arabia's Eastern Province industrial cluster and the UAE's logistics corridor, penalizing distant suppliers on total landed cost.
Pricing Analysis
After-sales service revenue from hot vulcanization contracts and mechanical fastening support drives lifetime value capture for integrated manufacturers serving Saudi mining operators. Three-tier pricing structure across premium aramid-reinforced grades, standard multi-ply fabric constructions, and economy PVC alternatives stratifies procurement decisions by end-use intensity. Cost compression in commodity rubber belts is intensifying because Southeast Asian natural rubber feedstock volatility compresses compound-dependent manufacturer margins. Manufacturing buyers in Qatar and Kuwait exhibit the highest price sensitivity, while phosphate and bauxite extraction operators in Saudi Arabia prioritize heat-resistant performance specifications over unit cost.
Supply Chain Analysis
Regional distributors maintain sixty-day safety stocks of DIN 22102-compliant cover grades to preempt Gulf Standardization Organization enforcement deadlines across member states. Manufacturing concentration in Germany, Japan, and South Korea supplies high-tensile steel cord reinforcements and specialized compound formulations to Middle East assembly points. Supply chain risk centers on single-source dependency for aramid fiber tensile members from East Asian mill sources. Distribution runs through Jebel Ali and Dammam port complexes where regional trading houses hold inventory positions for rapid deployment to Saudi mining sites and UAE logistics terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through SASO conformity assessment and GSO-ISO 14890 harmonization creates sticky relationships between certified suppliers and mining operators. Switching costs compound through specialized splicing technician scarcity and hot vulcanization equipment compatibility requirements.
For Market Incumbents: Consolidate service infrastructure around Jebel Ali and Dammam corridors to capture third-party splicing work unbundling from original equipment supply. Deepen backward integration into captive compound development for heat-resistant formulations displacing standard rubber grades, defending premium positioning against emerging regional distributors competing on logistics proximity rather than technical specification depth.
For New Entrants and Emerging Players: Specialized splicing technician scarcity in Oman and Qatar presents white-space positioning for mobile vulcanization service providers unbundled from belt procurement decisions. Target food-grade modular plastic penetration in Dubai's Jebel Ali Free Zone pharmaceutical clean rooms where MOHAP sanitation protocols command margin premiums and quick-change requirements displace incumbent woven fabric alternatives.
For Investors and Strategic Acquirers: Long-term, this sits as a compound-chemistry consolidation play because thermal performance benchmarks are displacing commodity tensile ratings as the primary procurement criterion across Gulf mining sites. Acquisition targets should display captive R&D pipelines for heat-stable formulations and established SASO certification pathways. The signal to watch is Saudi Vision 2030 localization mandate enforcement intensity driving joint venture formation between international manufacturers and Saudi industrial partners.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | Saudi Vision 2030 localization mandates incentivize partnerships with domestic industrial partners for mining safety equipment procurement. |
| Service Infrastructure Expansion | Third-party splicing contractors capture maintenance work unbundled from belt sales across UAE logistics corridors. |
| Compound Development Investment | Heat-resistant formulations displace standard rubber grades across Gulf Cooperation Council phosphate and bauxite extraction sites. |
| Certification Pathway Acceleration | SASO conformity assessment bottlenecks delay contract execution, rewarding pre-certified inventory positions. |
| Regional Distribution Positioning | Inventory concentration at Jebel Ali and Dammam port complexes compresses lead times for Saudi Eastern Province demand. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, Gulf Standardization Organization regulatory filings, and mining operator procurement records across the analysis window. Primary interviews engaged maintenance directors at Saudi phosphate extraction facilities, procurement leads at UAE bulk terminal operators, aftermarket service heads at regional distributors, and technical R&D directors at compound formulation specialists. Bottom-up demand estimation from end-use installation data triangulates against top-down supply-side capacity assessments from manufacturer disclosures.
Segmentation dimensions modeled include product type, end user industry, installation configuration, and application intensity across the projection horizon. CAGRs derive from regression analysis of historical procurement patterns against announced mining expansion timelines and port modernization investment schedules. Industry-specific forecast inputs incorporate Ma'aden Waad Al-Shamal complex development phases and Jebel Ali automation retrofit cycles.
Forecasts assume regulatory continuity in Saudi Standards, Metrology and Quality Organization and Gulf Standardization Organization regimes; material policy shifts would require re-modeling around revised flame-resistance or tensile rating mandates. Revision becomes warranted when natural rubber feedstock volatility crosses thresholds that force compound supplier pricing architecture recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Low-Level Order Picker Pallet Truck Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Hook Loader Market
Material Handling Equipment
Material Rack Correction Machine Market
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Hydraulic Hose and Fittings Market