
 Decoiler Machine Market | 2026-2036
Decoiler Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Decoiler Machine Market Analysis
A shift from single-source to multi-source procurement of coil handling equipment is realigning how automotive stampers and metal service centers evaluate decoiler vendors. AMADA leverages its integrated press line expertise to bundle decoilers with servo feeds and straighteners. Dallas Industries anchors its position through deep specialization in heavy-duty models for North American steel processors. The Formtek Group competes by controlling distribution through a network of regional rebuild and service centers.
A decoiler machine is an industrial material handling device that unwinds coiled metal strip or wire under controlled tension, typically accommodating coil weights from 500 kg to over 30 tonnes and widths up to 2,000 mm, feeding continuous processing lines in stamping, roll forming, and cut-to-length operations. Its primary purpose is to maintain consistent strip payoff speed and flatness while preventing coil collapse or telescoping during high-speed production. Powered decoilers occupy the largest installed base across mature manufacturing economies, while automatic decoilers with integrated coil cars and threading mechanisms represent the fastest-growing product category as labor costs rise and throughput targets tighten. Electric decoiler technology leads in new installations for light-gauge applications, whereas hydraulic systems dominate heavy-gauge coil handling where torque requirements exceed 50,000 Nm.
The EU Machinery Directive and CE marking requirements enforce safety interlocks and emergency stop protocols on decoilers sold across Europe, while China's GB standards mandate structural load testing and operator guarding specifications enforced by SAMR. OSHA lockout/tagout rules in the US shape maintenance access design and hydraulic system isolation requirements. Stakeholders must monitor how evolving carbon accounting under the EU Green Deal and China's dual carbon goals will reshape material sourcing and energy efficiency specifications for new coil handling equipment procurements.
Market Dynamics
Automotive stampers in Germany and Japan are consolidating coil handling equipment procurement around integrated press line solutions, compressing vendor selection criteria from standalone specifications to full-line performance guarantees. This concentration of buying power is forcing decoiler specialists to bundle servo feeds, straighteners, and controls or exit tier-one supplier status entirely.
Growth Catalysts
- EU Green Deal carbon accounting:Steel processors in Germany and France face Scope 3 disclosure mandates that favor electric decoiler retrofits over hydraulic systems for energy traceability.
- China's eastern manufacturing clusters:Jiangsu and Zhejiang provinces host dense automotive supply chain networks generating sustained demand for automatic threading systems.
- Powered decoiler technology:Light-gauge stamping lines across mature economies are replacing manual payoff systems to achieve consistent tension control at higher throughput speeds.
Market Restraints
- Structural steel input volatility:Coil car and mandrel fabrication depends on normalized steel plate pricing that fluctuates with scrap and billet markets.
- Certification timeline friction:China's SAMR enforcement of GB standards for industrial equipment safety extends type-approval cycles by four to six months for imported systems.
- Hydraulic system substitution pressure:Electric servo drives are displacing torque-dense hydraulic power units in coil handling applications below 30,000 Nm.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic stamping capacity expansion under production-linked incentives creates first-mover positioning for automatic decoiler vendors.
- Servo-electric and IoT convergence:Integrated condition monitoring and predictive maintenance capabilities differentiate premium system offerings.
- Rebuild and service channel innovation:Regional refurbishment networks in North America capture aftermarket revenue from installed base obsolescence cycles.
Industry Challenges
- Mechatronics skill scarcity:Maintenance of automatic decoiler systems requires technicians proficient in both hydraulic troubleshooting and servo drive programming.
- Legacy press line integration complexity:Retrofit projects face mechanical interface mismatches and control architecture incompatibilities with 1990s-era stamping equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decoiler Machine Market |
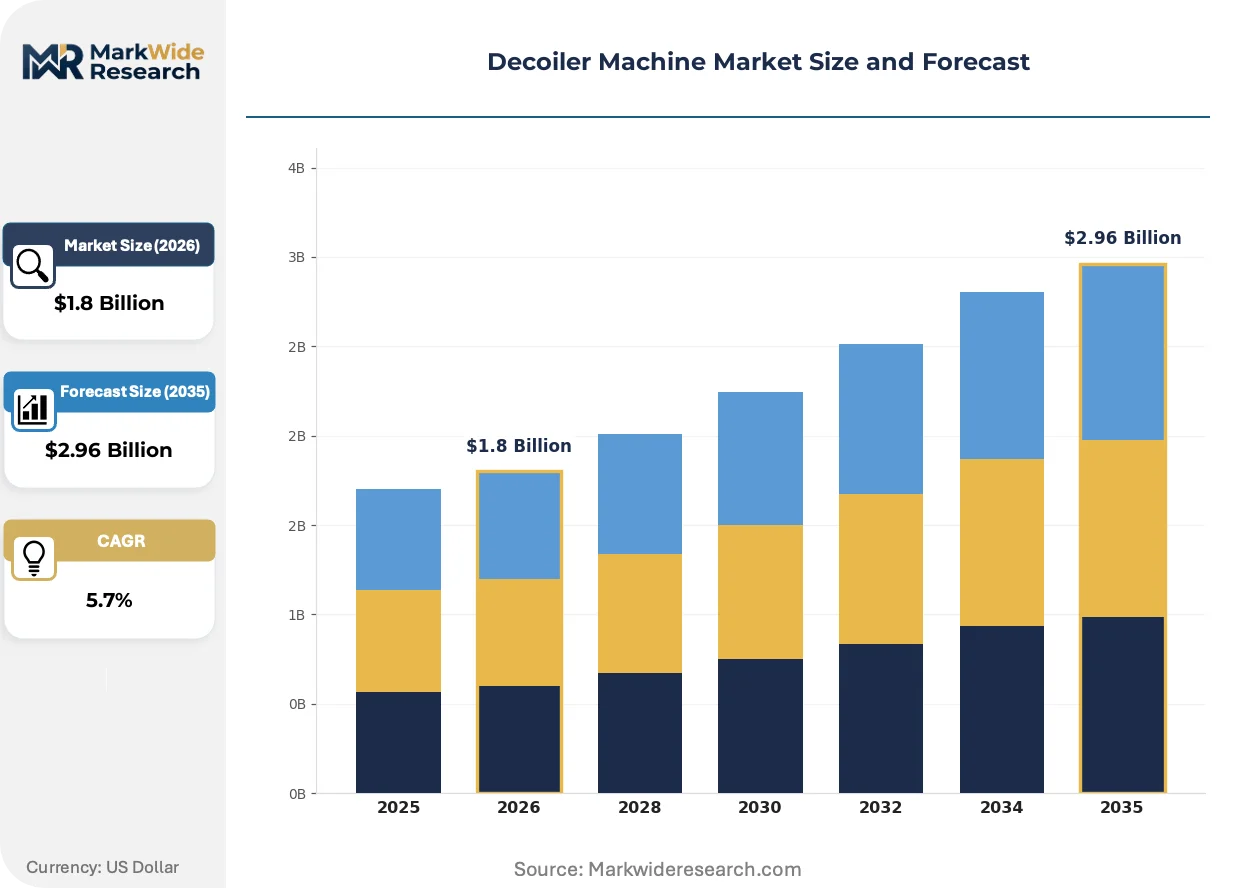
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
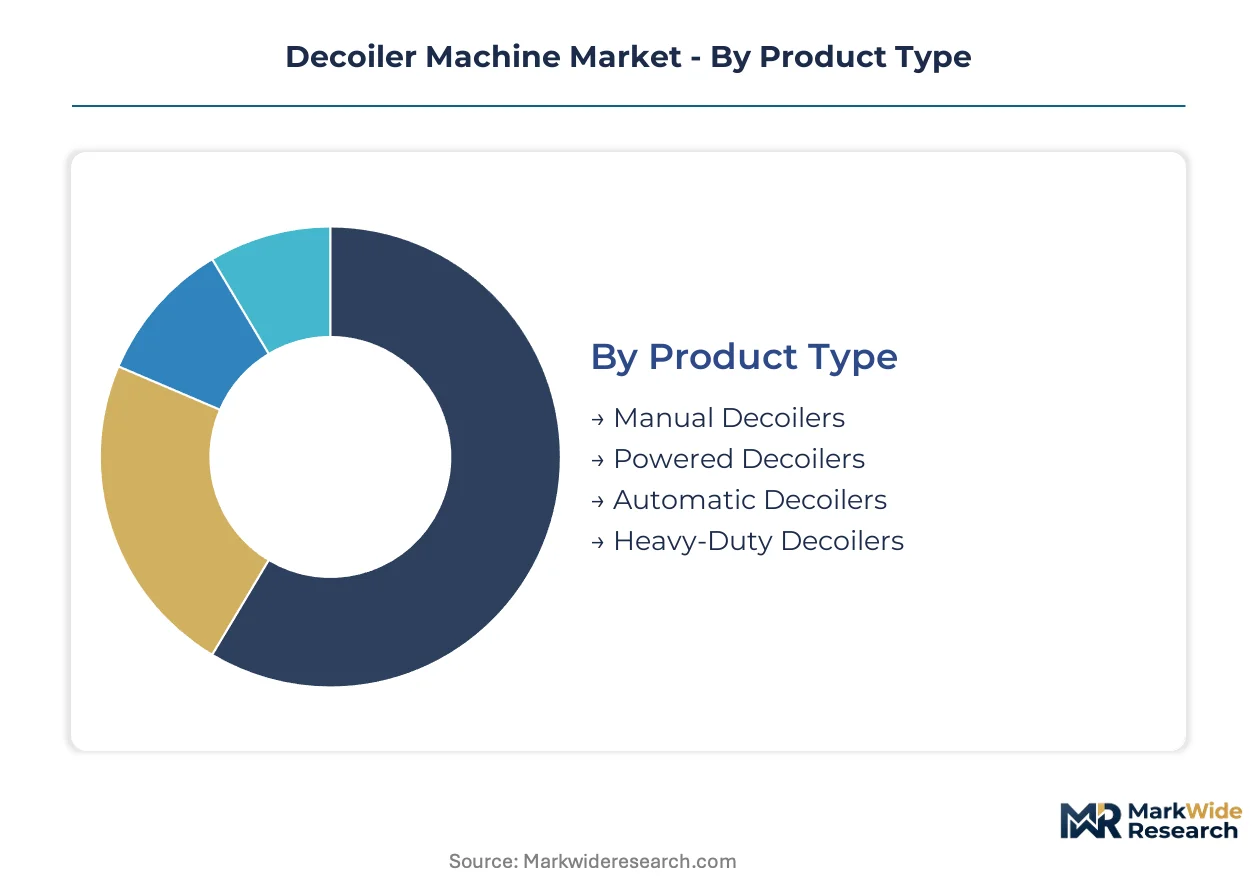
| Segmentation | Product Type: Manual Decoilers, Powered Decoilers, Automatic Decoilers, Heavy-Duty Decoilers End User: Construction, Manufacturing, Automotive Parts, Metal Fabrication Technology: Electric Decoilers, Pneumatic Decoilers, Hydraulic Decoilers, Mechanical Decoilers Application: Sheet Metal Processing, Wire Forming, Coil Handling, Assembly Lines |
| Companies Covered | Coe Press Equipment, AMADA, Dallas Industries, Acier Equipment, Wuxi Zhenqun Machinery Manufacture Co., Ltd., The Formtek Group, ARKU Maschinenbau GmbH, Bradbury Group, Vaspo Vamberk, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decoiler Machine Market Emerging Trajectories
Decoiler system architecture is fragmenting from centralized hydraulic power distribution toward distributed electric drive nodes. This shift compresses maintenance access requirements while enabling modular capacity scaling.
Edge-mounted servo motor arrays are decentralizing torque generation in light-gauge decoiler designs. Japanese automotive stampers adopted this configuration fastest, with European metal service centers following within eighteen months. The topology eliminates centralized hydraulic power units and reduces energy recovery losses by locating drive electronics adjacent to payoff mandrels.
REACH substance restrictions and the EU F-Gas Regulation are phasing out hydraulic fluids with high global warming potential in coil handling equipment. Equipment OEMs must reformulate seal materials and lubricant specifications to maintain CE marking compliance. German steel processors are responding by specifying biodegradable synthetic fluids or migrating to dry-running electric alternatives.
Buyer consolidation among tier-one automotive stampers is compressing vendor qualification cycles and unbundling after-sales service contracts. North American OEMs now separate maintenance agreements from initial equipment procurement, forcing decoiler specialists to compete with independent service providers. This disintermediation is most pronounced in Michigan and Ontario automotive corridors where multi-plant operators standardize on single-source service providers.
Decoiler Machine Market Segmentation
Decoiler procurement patterns diverge sharply across product configurations, end-use requirements, and drive technologies. Buyers evaluate segments through distinct certification lenses—CE marking for EU-bound automotive lines, GB standards for Chinese steel processors, and OSHA compliance for North American metal service centers. Understanding these segmentation boundaries clarifies where specification premiums concentrate and where commoditization pressure dominates.
Product Type:
CE marking under the EU Machinery Directive imposes emergency stop and interlock requirements most stringently on automatic and heavy-duty configurations, while manual decoilers face lighter conformity assessment burdens. GB standards administered by SAMR mandate structural load testing across all powered variants entering Chinese eastern manufacturing provinces.
- Powered Decoilers:Motor-driven mandrel systems with torque-controlled payoff dominate mature manufacturing economies where consistent tension control replaces manual operator judgment. German automotive stampers and Japanese tier-one suppliers anchor demand, driven by press line integration requirements and throughput guarantees that hydraulic alternatives cannot match at lighter gauges.
- Automatic Decoilers:Integrated coil cars, threading mechanisms, and servo feed synchronization command premium positioning as labor costs rise in Jiangsu and Zhejiang steel processing clusters. These systems require the most extensive certification documentation under both EU Machinery Directive and China's GB standards, extending type-approval timelines.
- Manual Decoilers:Hand-cranked or gravity-payoff systems persist in low-volume metal fabrication shops and developing market entry points.
- Heavy-Duty Decoilers:30-tonne-plus coil capacity configurations serve North American steel processors and European metal service centers handling hot-rolled structural grades.
Powered Decoilers sits at the top of the volume ranking, with Automatic Decoilers climbing the fastest.
End User:
Cost tier stratification separates capital-intensive automotive stampers—specifying full-line performance guarantees—from price-sensitive construction contractors purchasing standalone manual units. Metal fabrication shops occupy the mid-tier, balancing retrofit compatibility against throughput targets.
- Automotive Parts:Tier-one stampers in Germany, Japan, and China's eastern provinces consolidate procurement around integrated press line solutions. These buyers demand bundled servo feeds, straighteners, and controls with decoiler hardware, compressing standalone vendor margins while elevating system integrator value capture.
- Metal Fabrication:Independent job shops and regional steel service centers across Michigan, Ontario, and France drive aftermarket rebuild demand. Their procurement separates equipment purchase from maintenance contracts, opening service channel competition to independent providers.
- Construction:Project-based contractors prioritize portable manual and light-powered units for on-site rebar and structural steel processing.
- Manufacturing:General industrial users span appliance, HVAC, and consumer goods producers with moderate throughput requirements.
Automotive Parts commands the highest specification premiums, while Metal Fabrication delivers the steepest expansion trajectory through aftermarket service disaggregation.
Technology:
Application severity dictates drive selection—light-gauge sheet metal favors electric precision, while heavy-gauge coil handling sustains hydraulic dominance where torque requirements exceed 50,000 Nm. EU Green Deal carbon accounting is reshaping technology mix in German and French steel processing.
- Electric Decoilers:Servo motor arrays with distributed drive electronics deliver energy traceability advantages under Scope 3 disclosure mandates. Japanese automotive stampers adopted edge-mounted configurations fastest, with European metal service centers following within eighteen months as REACH and F-Gas restrictions phase out high-GWP hydraulic fluids.
- Hydraulic Decoilers:Torque-dense power units retain installed base dominance above 30,000 Nm in heavy-gauge applications. German processors are responding to regulatory pressure by specifying biodegradable synthetic fluids or migrating to dry-running alternatives where coil weights permit.
- Pneumatic Decoilers:Compressed-air drive systems serve niche applications requiring explosion-proof operation or rapid cycling in wire forming.
- Mechanical Decoilers:Direct mechanical linkage designs persist in legacy press line retrofits where control architecture compatibility constrains modernization paths.
Hydraulic Decoilers retains volume leadership in heavy-gauge segments, with Electric Decoilers gaining share fastest in light-gauge automotive stamping.
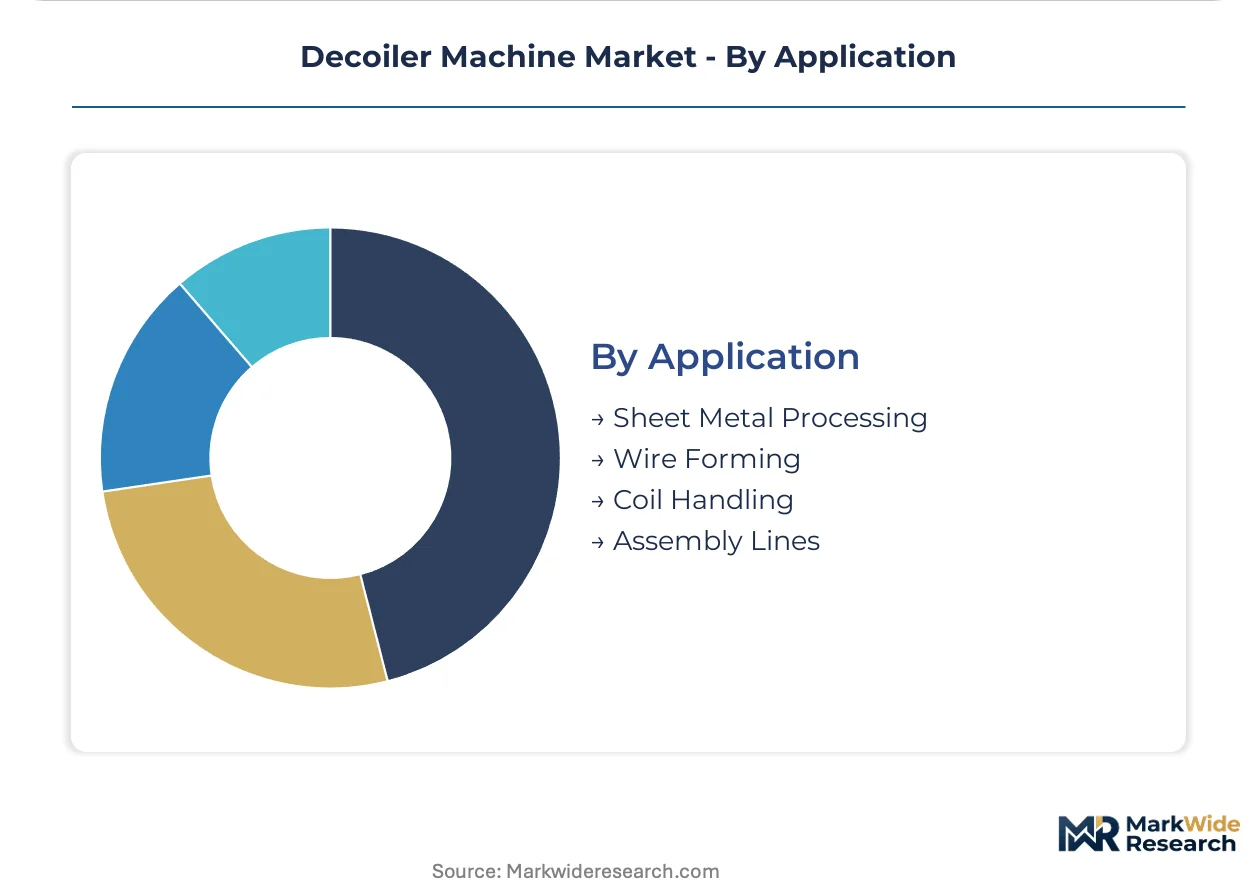
Application:
Customer type concentration varies by process—sheet metal processing clusters in China's automotive supply chains, wire forming specialists in precision component manufacturing, and coil handling generalists serving distributed metal service networks.
- Sheet Metal Processing:Continuous feed operations in stamping, roll forming, and cut-to-length lines demand synchronized decoiler-straightener-feeder integration. Jiangsu and Zhejiang automotive supply chain density sustains automatic threading system demand, while German stampers prioritize full-line performance guarantees.
- Coil Handling:General-purpose material flow applications span steel service centers, distribution facilities, and intermediate processing points with variable coil specifications.
- Wire Forming:Precision payoff control for spring manufacturing, fastener production, and specialty wire products requires tension accuracy distinct from flat strip handling.
- Assembly Lines:Discrete manufacturing integration points where decoilers feed progressive or transfer press operations in appliance and consumer goods production.
Sheet Metal Processing anchors volume demand, with Coil Handling expanding most quickly through metal service center capacity additions in India's PLI-supported auto component corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting decoiler procurement toward jurisdictions where CE marking and GB standard compliance costs diverge. German automotive stampers absorb stricter EU Machinery Directive enforcement while Chinese eastern provinces exploit faster type-approval pathways for domestic equipment.
China
Jiangsu and Zhejiang steel processing clusters generate concentrated demand for automatic threading systems feeding automotive supply chains. SAMR enforcement of GB standards extends import approval cycles, favoring domestic Wuxi-based fabricators over European suppliers. Ningbo and Suzhou metal service centers are retrofitting powered decoilers to meet dual carbon goals energy efficiency specifications.
Germany
Tier-one automotive stampers in Bavaria and Baden-Württemberg consolidate procurement around integrated press line performance guarantees. KBA and EU Machinery Directive compliance costs compress standalone decoiler vendor margins. Stuttgart and Munich industrial corridors are specifying electric servo retrofits to satisfy EU Green Deal Scope 3 carbon accounting mandates.
United States
Michigan and Ontario automotive corridors drive aftermarket service disaggregation as multi-plant operators unbundle maintenance from initial procurement. OSHA lockout/tagout rules shape hydraulic system isolation requirements for legacy press line retrofits. Detroit-area metal service centers are expanding heavy-duty coil handling capacity for structural steel processing.
Japan
Kanto and Chubu automotive suppliers anchor demand for edge-mounted servo motor arrays with distributed drive electronics. METI industrial efficiency guidelines accelerate displacement of centralized hydraulic power units in light-gauge applications. Toyota City and Nagoya stamping clusters adopted automatic decoiler configurations eighteen months ahead of European adoption curves.
India
Maharashtra and Tamil Nadu auto component corridors expand stamping capacity under PLI scheme production-linked incentives. BIS certification requirements for industrial equipment safety create first-mover positioning opportunities for automatic system vendors. Pune and Chennai manufacturing belts are integrating decoiler-straightener-feeder synchronization for continuous sheet metal processing lines.
Decoiler Machine Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue servo-electric and IoT convergence as differentiation vectors. The vendor base stratifies across three maturity tiers: integrated press line specialists bundling full-line controls, standalone decoiler fabricators defending position through heavy-duty specialization, and regional rebuild operators capturing aftermarket service revenue. Consolidation pressure concentrates among tier-one automotive stampers demanding full-line performance guarantees. Dominant competitive moves include backward integration into servo drive electronics and geographic expansion through regional refurbishment networks.
Within the integrated systems tier, AMADA and The Formtek Group exemplify bundling strategies that compress standalone component margins. ARKU Maschinenbau GmbH anchors German precision positioning for CE-marked automotive line integration. Among North American fabricators, Dallas Industries and Coe Press Equipment occupy positions shaped by heavy-duty specialization for steel service center applications. Wuxi Zhenqun Machinery Manufacture Co., Ltd. represents Chinese domestic supply advantages under SAMR accelerated approval pathways.
| Leading Market Players |
|---|
| Coe Press Equipment |
| AMADA |
| Dallas Industries |
| Acier Equipment |
| Wuxi Zhenqun Machinery Manufacture Co., Ltd. |
| The Formtek Group |
| ARKU Maschinenbau GmbH |
| Bradbury Group |
| Vaspo Vamberk, Ltd. |
| Others |
Supply Flow & Price Mechanics
Tier-one automotive stampers in Germany and Japan now dominate procurement volumes, compressing vendor margins through consolidated multi-year performance contracts while elevating specification premiums for integrated press line solutions.
Pricing Analysis
Distributor markups of 12-18% separate OEM-direct pricing from metal service center procurement channels. Three-tier pricing structure across premium automatic systems, standard powered configurations, and economy manual units stratifies by certification burden and after-sales bundling. Cost compression in the standard tier is intensifying as Chinese domestic fabricators exploit SAMR accelerated approval pathways. Metal fabrication shops exhibit highest price sensitivity, while automotive stampers absorb premium positioning for full-line integration guarantees.
Supply Chain Analysis
Dual-sourcing qualification requirements now mandate approved vendor lists spanning German servo drive specialists, Chinese structural steel fabricators, and Japanese control electronics suppliers. Coil car and mandrel fabrication draws from normalized steel plate feedstock anchored in Chinese mills and European distributors. Single-source vulnerability concentrates in precision servo motor arrays where Japanese producers retain technical leadership. Distribution runs through regional rebuild centers in North America and direct OEM relationships in automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where buyer consolidation toward automatic threading systems with integrated coil cars justifies specification premiums over commodity powered alternatives.
For Market Incumbents: Acquire regional service network assets to capture aftermarket revenue as multi-plant operators unbundle maintenance contracts. Defend margin position by backward integration into servo drive electronics and predictive maintenance software stacks. Electric servo substitution threatens hydraulic system incumbents below 30,000 Nm torque thresholds. For New Entrants and Emerging Players: India's PLI-supported auto component corridors offer the most penetrable white-space for automatic decoiler-straightener-feeder bundles. Target tier-two metal fabrication shops in Maharashtra and Tamil Nadu with certification-light configurations. Pursue channel partnerships with existing press line integrators rather than direct OEM confrontation. For Investors and Strategic Acquirers: Integrated press line specialists are the most active acquirer in this space, seeking decoiler technology to complete full-line bundling capabilities. Five-to-ten year viability hinges on servo-electric and IoT convergence differentiation. Watch for BIS certification timeline acceleration in India as inflection signal for first-mover positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Electronics | Captures margin compression from Japanese motor suppliers in light-gauge applications. |
| Regional Refurbishment Network Expansion | Locks aftermarket revenue as North American buyers disaggregate service contracts. |
| GB Standards Pre-Certification Investment | Accelerates SAMR approval timelines for Jiangsu and Zhejiang market penetration. |
| Biodegradable Hydraulic Fluid Formulation | Maintains CE marking compliance under REACH and EU F-Gas phase-out schedules. |
| IoT-Enabled Predictive Maintenance Platform | Differentiates premium offerings for automotive stamper throughput guarantee requirements. |
Methodological Framework
Multiple input streams — structured interviews with plant engineers and maintenance directors, OEM procurement team surveys, and aftermarket service head consultations — were reconciled against customs records, SEC equipment supplier filings, and automotive production databases. Secondary validation drew from SAMR type-approval registries, EU Machinery Directive conformity databases, and metal service center capacity announcements. Bottom-up unit demand estimates and top-down equipment spending allocations were triangulated for convergence.
Data-stream reconciliation across product configuration, drive technology, and end-use intensity dimensions anchored the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate differentials applied to base-year value distributions. Forecast inputs incorporated PLI scheme disbursement timelines, EU Green Deal carbon accounting implementation pace, and hydraulic-to-electric substitution curves.
Underlying measurement precision varies by segment; powered decoiler estimates carry tighter precision than emerging automatic system projections due to installed base visibility. Forecasts reflect assumptions on certification timeline friction, raw material input stability, and buyer consolidation trajectories. Deviation in India's PLI scheme execution or EU F-Gas regulatory acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Metal Plain Washer Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Vertical Lift Module (VLM) Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Cam and Groove Fittings Market
Material Handling Equipment
Flux Spraying Machine Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
Sifter Fitment Market