
 BOPP Packaging Tapes Market | 2026-2036
BOPP Packaging Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
BOPP Packaging Tapes Market Outlook
Asset-light leasing models for coating and slitting equipment are rewriting competitive entry barriers in BOPP tape manufacturing. 3M Company leverages its captive resin compounding capabilities to sustain margin control across adhesive formulations. Youyi Group anchors its position through vertical integration into film extrusion, while Intertape Polymer Group competes via North American distribution density.
Biaxially oriented polypropylene packaging tape consists of oriented PP film coated with pressure-sensitive adhesive, typically 20–50 microns thick, engineered for tensile strength above 30 N/cm in machine direction. Hot melt adhesive tapes dominate volume throughput in automated fulfillment lines, whereas water-based acrylic formulations are gaining share in food-contact applications where FDA compliance is mandatory. The electronics end-user segment concentrates demand for low-outgassing printed tapes with static-dissipative properties.
FDA food-contact regulations and EPA volatile organic compound limits constrain solvent-based adhesive formulations in US manufacturing. China's GB standards and MEE emissions protocols are accelerating converter migration to water-based systems. REACH compliance in Europe adds testing burdens for imported tape shipments. Stakeholders must monitor adhesive chemistry transitions and regional certification divergence when allocating capital across coating capacity.
Market Dynamics
Water-based adhesive chemistry migration is compressing solvent-based capacity economics while automated fulfillment infrastructure concentrates tape specification power among e-commerce platform operators and third-party logistics providers.
Growth Catalysts
- E-commerce fulfillment automation:Automated carton sealing lines in North American and European distribution centers specify hot melt adhesive tapes for throughput speeds above 200 cartons per minute.
- China's dual carbon goals:MEE emissions protocols and GB standards are mandating water-based acrylic formulations, forcing converter retooling and creating certified-supplier premiums.
- Southeast Asian manufacturing clusters:Vietnam and Indonesia are attracting electronics assembly and consumer goods production, concentrating demand for low-outgassing static-dissipative tape grades.
Market Restraints
- Propylene monomer volatility:BOPP film extrusion depends on naphtha-cracker propylene supply, with Asian petrochemical pricing swings compressing integrated margin visibility.
- Adhesive raw material concentration:Hydrogenated hydrocarbon resin supply for hot melt formulations clusters with Korean and Japanese specialty chemical producers, creating single-source vulnerability.
- REACH compliance burden:ECHA substance-of-very-high-concern listings for certain tackifier classes are extending EU import testing timelines and documentation costs.
Strategic Opportunities
- India packaging modernization:FSSAI food-contact compliance requirements and organized retail expansion are displacing unbranded kraft tape with certified acrylic systems.
- Printed tape brand security:QR-code and holographic authentication features on carton sealing tapes are penetrating pharmaceutical and luxury goods distribution.
- Asset-light equipment leasing:Coating and slitting line leasing models are lowering Southeast Asian converter entry barriers without balance-sheet-heavy capex commitments.
Industry Challenges
- Adhesive formulation chemist scarcity:Water-based acrylic expertise sits concentrated with aging technical workforces in Germany and Japan, constraining rapid converter migration.
- Multi-certification stacking:Simultaneous FDA, EU 10/2011, and GB compliance for food-contact tapes extends product development cycles and testing expenditure.
- Legacy solvent line stranded assets:Converters with recent solvent-based capacity investments face accelerated obsolescence risk under tightening VOC regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BOPP Packaging Tapes Market |
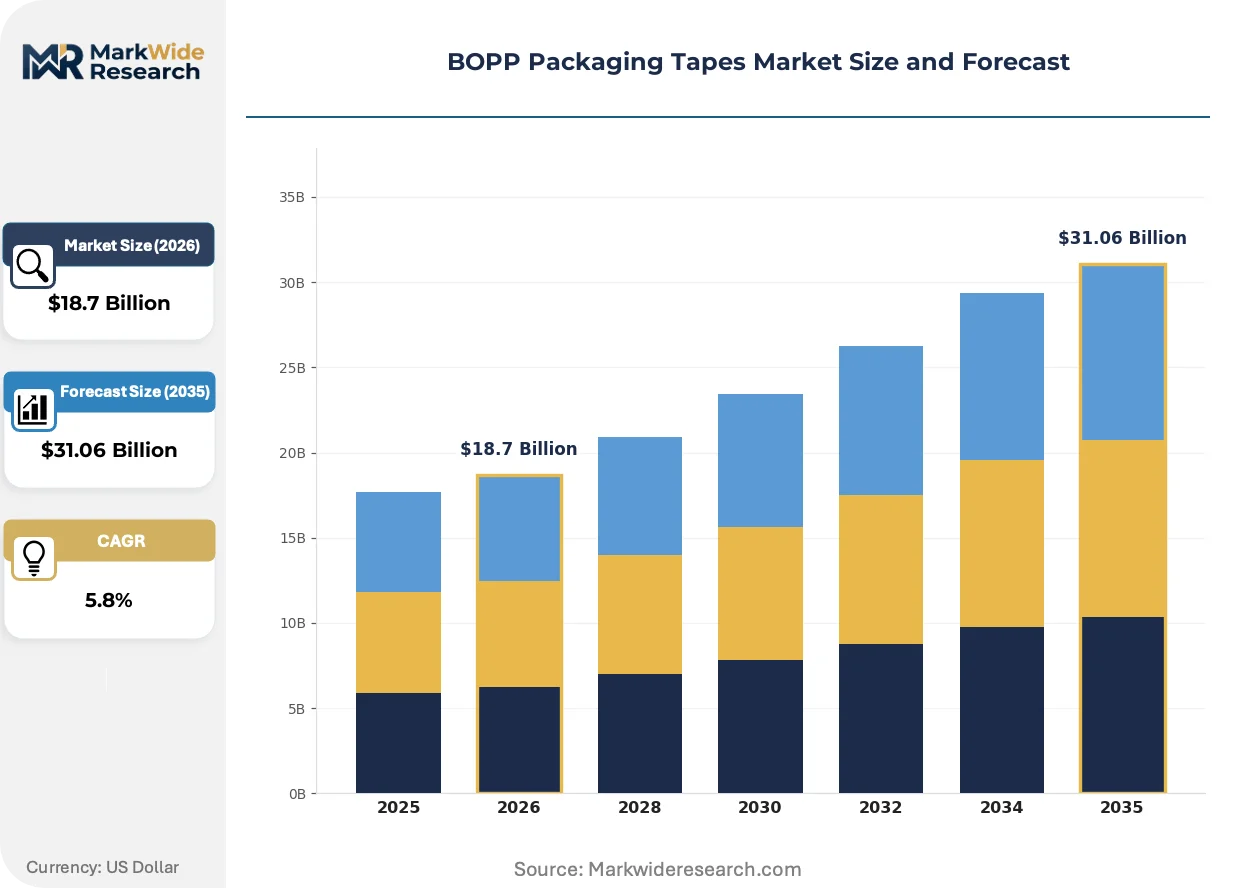
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Tapes, Printed Tapes, Masking Tapes, Double-Sided Tapes Adhesive Type: Hot Melt, Water-Based, Solvent-Based, Acrylic End User: Food & Beverage, Electronics, Consumer Goods, Pharmaceuticals Thickness: General Purpose, Heavy-Duty, Extra Thick, Standard |
| Companies Covered | tesa SE, Youyi Group, 3M Company, Avery Dennison Corporation, Vibac Group, Intertape Polymer Group, Shurtape Technologies, Shanghai Yongguan Adhesive Products, Nitto Denko Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BOPP Packaging Tapes Market Strategic Shifts
Digital printing integration and bio-based feedstock substitution are fragmenting the traditional commodity tape specification model while raising performance segmentation across end-use verticals.
Water-based acrylic adhesive systems with enhanced shear resistance are rendering obsolete solvent-based natural rubber formulations in ambient-temperature carton sealing. European grocery retailers and North American pharmaceutical distributors are specifying these systems for FDA and EU 10/2011 compliance without throughput sacrifice. The shift is compressing solvent-based capacity valuations and redirecting R&D spend toward emulsion polymerization process control.
REACH SVHC disclosure requirements and ECHA restriction proposals on certain rosin ester tackifiers are forcing adhesive reformulation across imported tape shipments. European converters are accelerating qualification of hydrogenated hydrocarbon alternatives and bio-based terpene resins. Food-contact and cosmetics packaging segments bear the highest compliance burden, with some suppliers exiting EU market participation rather than absorbing testing costs.
Direct platform procurement by e-commerce operators is disintermediating traditional distribution channels for standard-grade carton sealing tapes. Amazon, Alibaba, and regional logistics platforms are consolidating specification authority and pushing private-label sourcing. This concentration is most visible in North American and Chinese fulfillment networks, where tape has become a captive supply category with annual tender cycles and volume-commitment pricing.
BOPP Packaging Tapes Market Segmentation
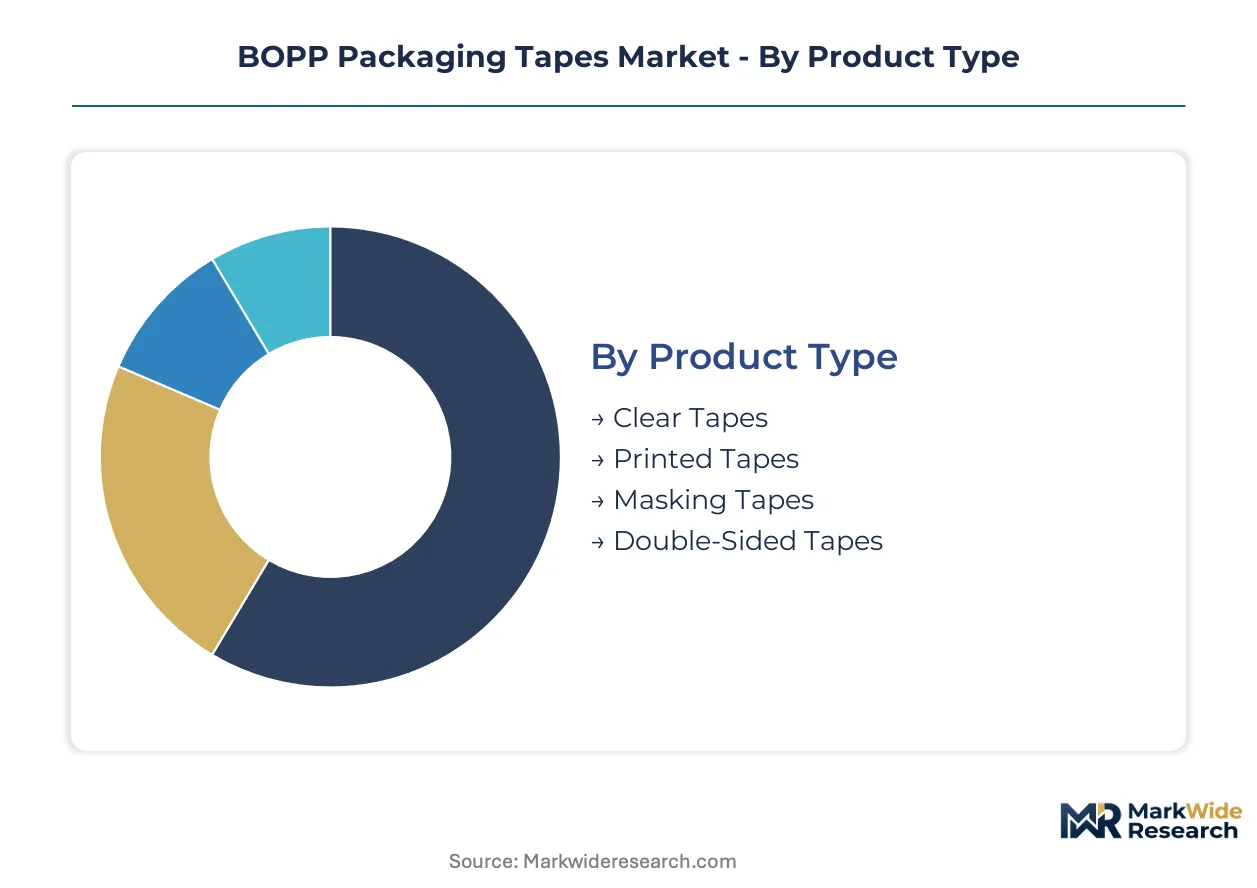
Segmentation in BOPP packaging tapes reveals divergent margin structures and specification cycles. Tape buyers sort by adhesive chemistry for regulatory compliance, by thickness for load-bearing requirements, and by print capability for brand authentication. Understanding these splits exposes where converter capital earns returns versus where commoditization erodes pricing power.
Product Type:
Cycle times vary dramatically: clear tapes turn inventory weekly in high-velocity fulfillment centers, while printed tapes carry 6–8 week lead times for plate setup and color matching. Masking tapes for industrial painting applications exhibit seasonal demand spikes that strain slitting capacity.
- Clear Tapes:Unprinted biaxially oriented polypropylene film with hot melt or water-based adhesive, optimized for optical clarity and unwind consistency. Amazon fulfillment centers and Alibaba logistics hubs specify these for automated carton sealing lines running above 200 units per minute. Demand concentrates in Chinese and North American e-commerce infrastructure where throughput speed governs procurement decisions.
- Printed Tapes:Custom graphics, QR codes, or holographic elements applied via flexographic or digital printing for brand security and handling instructions. Pharmaceutical distributors in Germany and luxury goods shippers in Italy specify these for tamper-evidence and authentication. FDA and EU 10/2011 compliance requirements extend qualification timelines and support pricing premiums over commodity grades.
- Masking Tapes:Crepe paper or flatback paper backing with rubber-based adhesive for temporary surface protection in painting and finishing operations.
- Double-Sided Tapes:Adhesive coating on both film faces for bonding applications in electronics assembly and display mounting.
Clear tapes dominate installed base volume. Printed tapes are where expansion concentrates as brand security requirements penetrate pharmaceutical and cosmetics distribution.
Adhesive Type:
Cost tiers separate sharply: hot melt formulations run lowest on per-meter adhesive cost, while water-based acrylics command premiums for food-contact certification. Solvent-based systems face stranded asset risk as MEE emissions protocols tighten in China and EPA VOC limits constrain US manufacturing.
- Hot Melt:Synthetic rubber and hydrogenated hydrocarbon resin formulations applied molten and cooled to tack. Automated fulfillment lines in US and German distribution centers specify these for shear strength and instant bond formation at ambient temperatures. Propylene monomer volatility and Korean/Japanese resin supply concentration create margin visibility challenges for converters.
- Water-Based:Acrylic emulsion polymers dispersed in water, curing through evaporation. China's GB standards and MEE emissions mandates are accelerating converter migration from solvent systems. European grocery retailers and North American food distributors specify these for FDA and EU 10/2011 compliance without sacrificing line speed.
- Solvent-Based:Natural rubber or synthetic elastomers dissolved in organic solvents, delivering aggressive tack and plasticizer resistance.
- Acrylic:Solvent-borne or emulsion acrylic polymers offering UV stability and aging resistance for outdoor and long-term applications.
Hot melt adhesive capacity represents the largest installed base. Water-based systems are climbing the fastest as regulatory pressure and food-contact demand reshape formulation preferences.
End User:
Application requirements fragment specification authority: electronics assemblers demand static-dissipative and low-outgassing properties, while food packagers prioritize FDA and FSSAI compliance documentation. Pharmaceutical distributors impose the most rigorous multi-certification stacking.
- Food & Beverage:Carton sealing for ambient and refrigerated supply chains with mandatory FDA, EU 10/2011, or FSSAI food-contact compliance. India's organized retail expansion and FSSAI enforcement are displacing unbranded kraft tape with certified acrylic systems in Mumbai and Delhi distribution networks.
- Electronics:Cleanroom-compatible tapes with low ionic contamination and static-dissipative properties for PCB handling and component packaging. Vietnam and Indonesia manufacturing clusters concentrate demand as assembly shifts from China.
- Consumer Goods:General-purpose carton sealing for retail distribution with moderate performance requirements and price-sensitive procurement.
- Pharmaceuticals:Tamper-evident sealing with batch tracking, temperature indicators, and authentication features for cold chain integrity.
Food and beverage applications anchor volume throughput. Electronics segment is gaining share fastest as Southeast Asian assembly clusters expand cleanroom tape specifications.
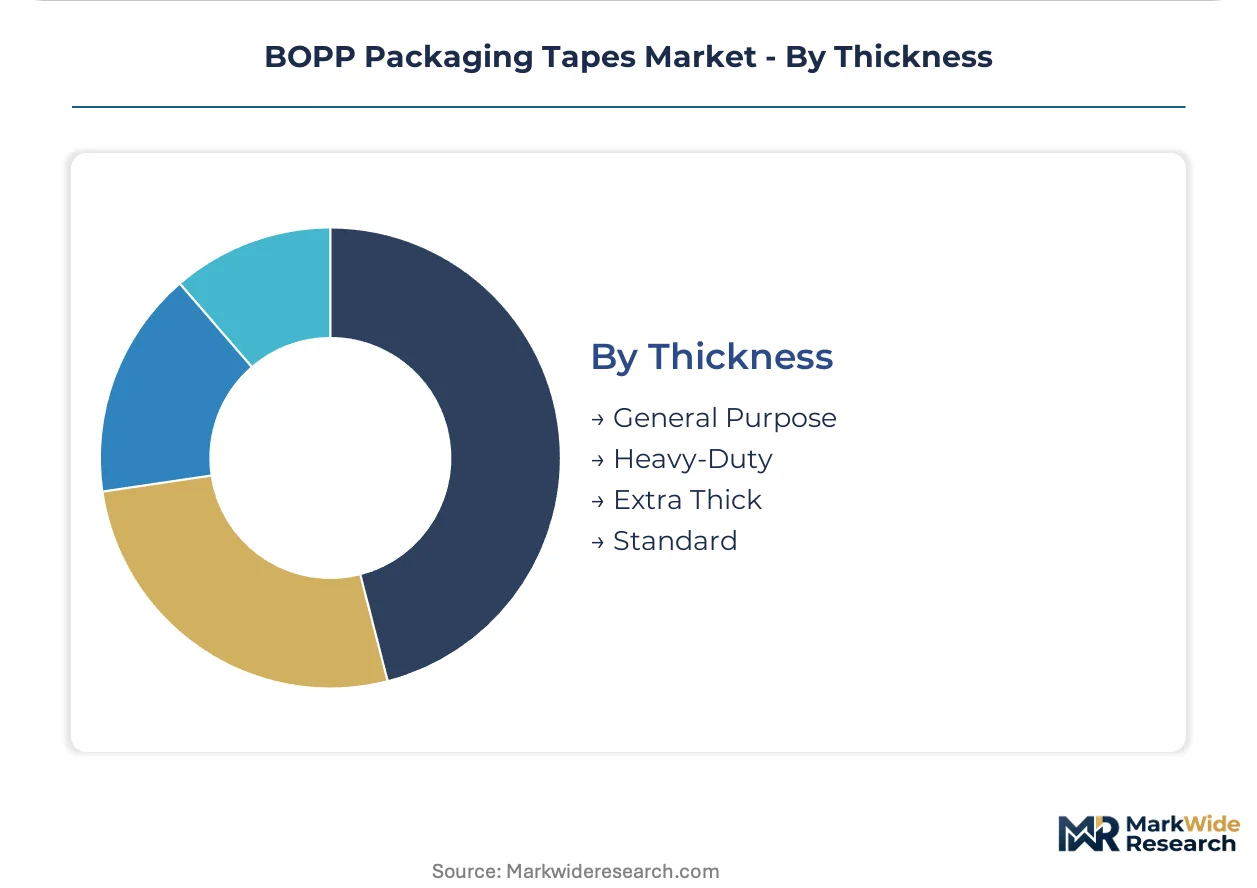
Thickness:
Volume scale concentrates in general-purpose and standard grades, while heavy-duty specifications capture margin in export logistics and bulk material handling. Extra-thick tapes serve niche applications where puncture resistance governs performance.
- General Purpose:20–35 micron film thickness for lightweight carton sealing in e-commerce and retail distribution. Fulfillment automation in US and Chinese logistics platforms drives specification standardization and annual tender-based procurement.
- Heavy-Duty:40–50 micron construction with elevated tensile strength above 40 N/cm for export shipping and palletized loads. German automotive parts exporters and Japanese machinery shippers specify these for ocean container integrity across extended transit times.
- Extra Thick:Above 50 micron film for extreme load securing and metal coil strapping protection.
- Standard:35–40 micron intermediate grade bridging general-purpose economy and heavy-duty performance.
General-purpose thickness holds the broadest installed base. Heavy-duty grades are where specification premiums concentrate as export logistics demand escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and MEE emissions protocols are redirecting converter investment toward water-based adhesive capacity. Vietnam and Indonesia electronics clusters concentrate demand for cleanroom-compatible tape grades. India's FSSAI enforcement and organized retail expansion displace unbranded alternatives with certified systems.
China
GB standards and MEE emissions mandates accelerate solvent-to-water-based adhesive migration across converter networks. The Yangtze River Delta hosts the densest concentration of tape manufacturing infrastructure undergoing regulatory retooling. Shanghai and Suzhou converters command certified-supplier premiums for food-contact compliant acrylic systems.
United States
FDA food-contact regulations and EPA VOC limits constrain solvent-based formulation economics in domestic manufacturing. Automated fulfillment infrastructure in Chicago and Dallas distribution centers specifies hot melt adhesive tapes for throughput above 200 cartons per minute. Amazon and regional logistics platforms consolidate procurement authority through annual tender cycles.
Germany
REACH SVHC disclosure requirements and ECHA restriction proposals on rosin ester tackifiers extend import testing timelines for tape shipments. The Rhine-Ruhr industrial corridor anchors European demand for pharmaceutical-grade printed tapes with batch-tracking features. Stuttgart automotive parts exporters specify heavy-duty 40–50 micron grades for ocean container integrity.
Vietnam
Electronics assembly relocation from China concentrates cleanroom tape demand in Bac Ninh and Hai Phong manufacturing zones. Low-outgassing and static-dissipative specifications govern procurement for PCB handling applications. Korean and Japanese component suppliers drive quality standards for imported adhesive systems.
India
FSSAI food-contact compliance requirements displace unbranded kraft tape in Mumbai and Delhi organized retail distribution networks. Maharashtra and Gujarat packaging converters expand water-based acrylic capacity to serve modern trade expansion. E-commerce platform procurement is standardizing specifications across fulfillment center networks.
BOPP Packaging Tapes Market Competitive Environment
On the supply side, the industry is consolidating around integrated film producers and specialized adhesive compounders with regulatory certification depth. Tier-one players control captive resin compounding and extrusion capacity. Tier-two regional converters compete through distribution density and asset-light equipment leasing. Dominant competitive moves include backward integration into film extrusion and geographic expansion through Southeast Asian coating capacity.
Within the integrated-manufacturer tier, Youyi Group exemplifies upstream control over film extrusion and adhesive formulation. 3M Company occupies a position anchored by captive resin compounding capabilities that sustain margin control across chemistry transitions. Intertape Polymer Group represents North American distribution density strategies competing against vertically integrated Asian producers.
| Leading Market Players |
|---|
| tesa SE |
| Youyi Group |
| 3M Company |
| Avery Dennison Corporation |
| Vibac Group |
| Intertape Polymer Group |
| Shurtape Technologies |
| Shanghai Yongguan Adhesive Products |
| Nitto Denko Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese water-based adhesive coating lines is compressing margin visibility for converters while simultaneously accelerating procurement consolidation among e-commerce platform operators. Utilization rates below 70% in Yangtze River Delta facilities are forcing suppliers into extended payment terms and volume-commitment pricing to secure offtake.
Pricing Analysis
Certification level creates the primary spread across BOPP tape quotations, with FDA and EU 10/2011 food-contact grades commanding premiums over general-purpose hot melt formulations. Three-tier pricing structure separates pharmaceutical authentication tapes from standard clear grades from unbranded economy products. Price erosion runs through general-purpose segments as Amazon and Alibaba consolidate annual tender authority. Food and beverage distributors exhibit lowest price sensitivity due to compliance documentation requirements, while consumer goods procurement teams drive aggressive cost compression.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are emerging as competitive weapons among Korean and Japanese hydrogenated hydrocarbon resin suppliers serving hot melt formulation networks. BOPP film extrusion draws from propylene supply concentrated in China, South Korea, and Saudi Arabia. Single-source vulnerability clusters around specialty tackifier classes subject to ECHA restriction proposals. Distribution runs through converter networks with coating and slitting capacity leased on asset-light terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-commerce platform procurement centralization is transforming BOPP tape from a distributed commodity into a captive supply category with interoperability demands around automated line specification.
For Market Incumbents: Harden certification depth against regulatory divergence by securing simultaneous FDA, EU 10/2011, and GB compliance for food-contact acrylic systems. Defend margin position through backward integration into film extrusion rather than relying on merchant BOPP supply. Water-based adhesive expertise scarcity in aging German and Japanese technical workforces represents a defendable capability moat. For New Entrants and Emerging Players: India's FSSAI enforcement gap in secondary cities represents the most penetrable entry point for certified acrylic tape displacement of unbranded kraft alternatives. Vietnam electronics assembly clusters offer white-space demand for low-outgassing static-dissipative grades as Korean component suppliers qualify new adhesive sources. Asset-light equipment leasing models enable Southeast Asian coating capacity without balance-sheet-heavy capex. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across water-based adhesive coating as standardized emulsion polymerization equipment proliferates. Acquisition targets should prioritize converters with stacked multi-certification capabilities rather than single-market specialists. Monitor ECHA restriction proposals on rosin ester tackifiers as signal for adhesive chemistry transition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Youyi Group's captive BOPP supply insulates margin from propylene volatility. |
| Water-Based Adhesive Capacity Expansion | China's MEE emissions protocols are accelerating solvent line obsolescence risk. |
| Multi-Certification Stacking Investment | Simultaneous FDA and EU 10/2011 compliance captures pharmaceutical distributor premiums. |
| Asset-Light Equipment Leasing Models | Southeast Asian converters enter without balance-sheet-heavy coating line commitments. |
| Printed Tape Authentication Features | QR-code and holographic elements penetrate pharmaceutical and luxury goods distribution. |
Study Parameters
A spread of perspectives from coating line operators, adhesive formulation chemists, e-commerce procurement directors, and logistics platform engineers converged on the working assumptions. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of listed packaging converters, and GB standards documentation. Bottom-up capacity assessments triangulated against top-down demand modeling from fulfillment center automation deployment rates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include adhesive chemistry type, film thickness grade, end-use vertical, and regional regulatory cluster. CAGRs derived from capacity utilization trajectories and substitution elasticity between solvent and water-based systems. Forecast inputs incorporated propylene monomer pricing volatility and e-commerce fulfillment line automation penetration curves.
Practitioners should monitor ECHA SVHC listing announcements and China's MEE enforcement intensity for early signals. Forecasts reflect assumptions around regulatory transition timelines and platform procurement consolidation velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Coding Foils and Tapes Market
Tapes
Pouch Tapes Market
Tapes
Pressure Sensitive Tapes and Labels Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Hand Wrappers Market
Tapes
Paper Masking Tapes Market
Tapes
Tape and Label Adhesives Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Sealing and Strapping Packaging Tapes Market
Tapes
Washi Tapes Market
Tapes
Masking Tape Market
Tapes
Labels, Tapes and Films Market
Tapes
Paper Packaging Tapes Market
Tapes
Aerospace Tapes Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Kraft Paper Tapes Market