
 Tapes Market | 2026-2036
Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Tapes Market Analytics
China's Yangtze River Delta manufacturing cluster is rewriting regional supply dynamics for pressure-sensitive materials. 3M Company leverages its fluoropolymer and acrylic chemistry portfolio to sustain premium positioning across electronics and automotive bonding applications. Nitto Denko Corporation anchors East Asian supply chains through specialized optical and semiconductor tapes. tesa SE competes in European industrial channels with precision die-cut solutions for surface protection.
Tapes are flexible substrates coated with adhesive formulations, typically acrylic, rubber, or silicone-based, engineered to bond, seal, insulate, or protect surfaces across industrial and consumer applications; thickness ranges from micrometers for electronics to millimeters for heavy-duty construction, with peel adhesion and shear strength as critical performance parameters. Adhesive tapes occupy the largest value share due to universal applicability across packaging and assembly workflows, while double-sided tapes represent the fastest-expanding category as device miniaturization in electronics demands invisible bonding without mechanical fasteners. Plastic substrates dominate material consumption given polyester and polypropylene versatility, though fabric backings sustain niche demand in high-temperature automotive harness wrapping.
China's SAMR enforces GB standards limiting volatile organic compound emissions in tape manufacturing, while the EU REACH regulation restricts phthalate plasticizers in adhesive formulations, compelling reformulation investments across export-oriented producers. Japan's METI promotes JIS-certified industrial tapes through quality infrastructure programs that shape procurement specifications for precision assembly. Stakeholders must monitor divergence between China's domestic environmental targets and evolving EU chemical restrictions to anticipate compliance-driven product redesign cycles.
Market Dynamics
Electronics miniaturization is compressing bonding tolerances across consumer devices and automotive modules, forcing substrate and adhesive chemistries to evolve in parallel with semiconductor packaging roadmaps.
Growth Catalysts
- China's dual carbon goals:Manufacturers are reformulating solvent-based adhesives to waterborne systems to meet MEE emission ceilings, accelerating premium tape adoption in export-oriented electronics.
- Die-attach films in advanced packaging:Flip-chip and fan-out wafer-level packaging processes now specify ultra-thin dicing tapes with controlled adhesive release properties.
- Yangtze River Delta concentration:Tape converters cluster within 200 kilometers of Shanghai port infrastructure, reducing logistics friction for just-in-time electronics assembly.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and polyester film prices fluctuate with naphtha cracking economics, squeezing converter margins unpredictably.
- East Asian supply concentration:Specialty silicone adhesives for high-temperature automotive harnesses depend on Japanese and South Korean resin producers, creating single-source vulnerability.
- EU REACH phthalate restrictions:Legacy plasticizer formulations face authorization sunset dates, requiring costly adhesive reformulation for European-bound shipments.
Strategic Opportunities
- India's PLI scheme for electronics:Smartphone and component manufacturing incentives are attracting tape converters to Gujarat and Tamil Nadu industrial corridors.
- Thermal interface materials convergence:Pressure-sensitive adhesives are integrating with boron nitride and graphene fillers to serve power electronics cooling modules.
- Direct-to-plant distribution:Automotive OEMs are bypassing traditional industrial distributors, creating margin capture potential for specialized tape formulators.
Industry Challenges
- Adhesive formulator talent scarcity:Cross-disciplinary expertise spanning polymer chemistry, rheology, and electronics reliability testing remains concentrated among aging technical specialists in Japan and Germany.
- Cleanroom certification timelines:ISO Class 7 and 8 validation for semiconductor-grade tape slitting operations extends facility commissioning by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tapes Market |
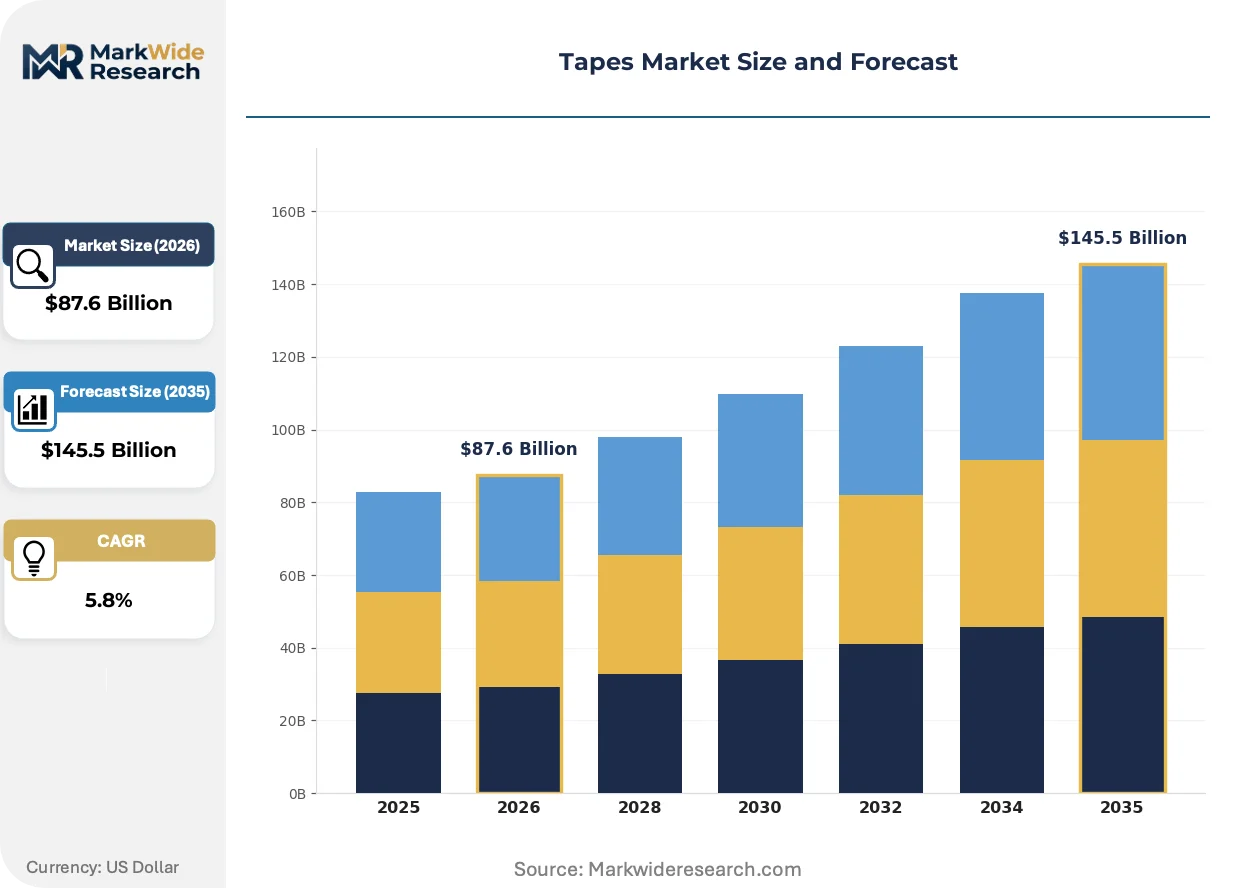
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $145.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Tapes, Double-Sided Tapes, Masking Tapes, Electrical Tapes End User: Construction, Automotive, Electronics, Packaging Material: Plastic, Paper, Fabric, Foam Application: Insulation, Bonding, Surface Protection, Labeling |
| Companies Covered | 3M Company, Nitto Denko Corporation, tesa SE, Avery Dennison Corporation, Lintec Corporation, Intertape Polymer Group, Scapa Group PLC, Berry Global Inc., Shurtape Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tapes Market Evolving Landscape
Active material substitution and regulatory chemistry bans are forcing concurrent innovation across adhesive platforms, substrate films, and release liner systems without transitional grace periods.
Silicone pressure-sensitive adhesives are migrating from traditional thermal-cure systems to UV-curable formulations in electronics bonding applications. Display manufacturers in South Korea and Taiwan now specify UV silicones for optical bonding to compress cycle times. This chemistry shift is migrating from high-margin display assembly into mainstream consumer electronics, compressing the performance premium historically commanded by thermal-cure grades.
REACH authorization requirements for phthalate plasticizers in adhesive formulations are tightening through ECHA sunset date enforcement. European tape producers face reformulation mandates for legacy PVC electrical tapes and masking products. Automotive harness suppliers serving EU-27 markets are accelerating validation of bio-based plasticizer alternatives, with German OEMs specifying compliance in supplier quality agreements.
Component manufacturers now consolidate adhesive specification authority at central engineering centers, displacing plant-level procurement autonomy. Electronics EMS providers in Vietnam and Mexico report purchasing decisions migrating to headquarters technical teams in Shenzhen and San Jose. This concentration pattern is most visible in smartphone and notebook supply chains, where bonding failure liability costs exceed regional sourcing savings.
Tapes Market Segmentation
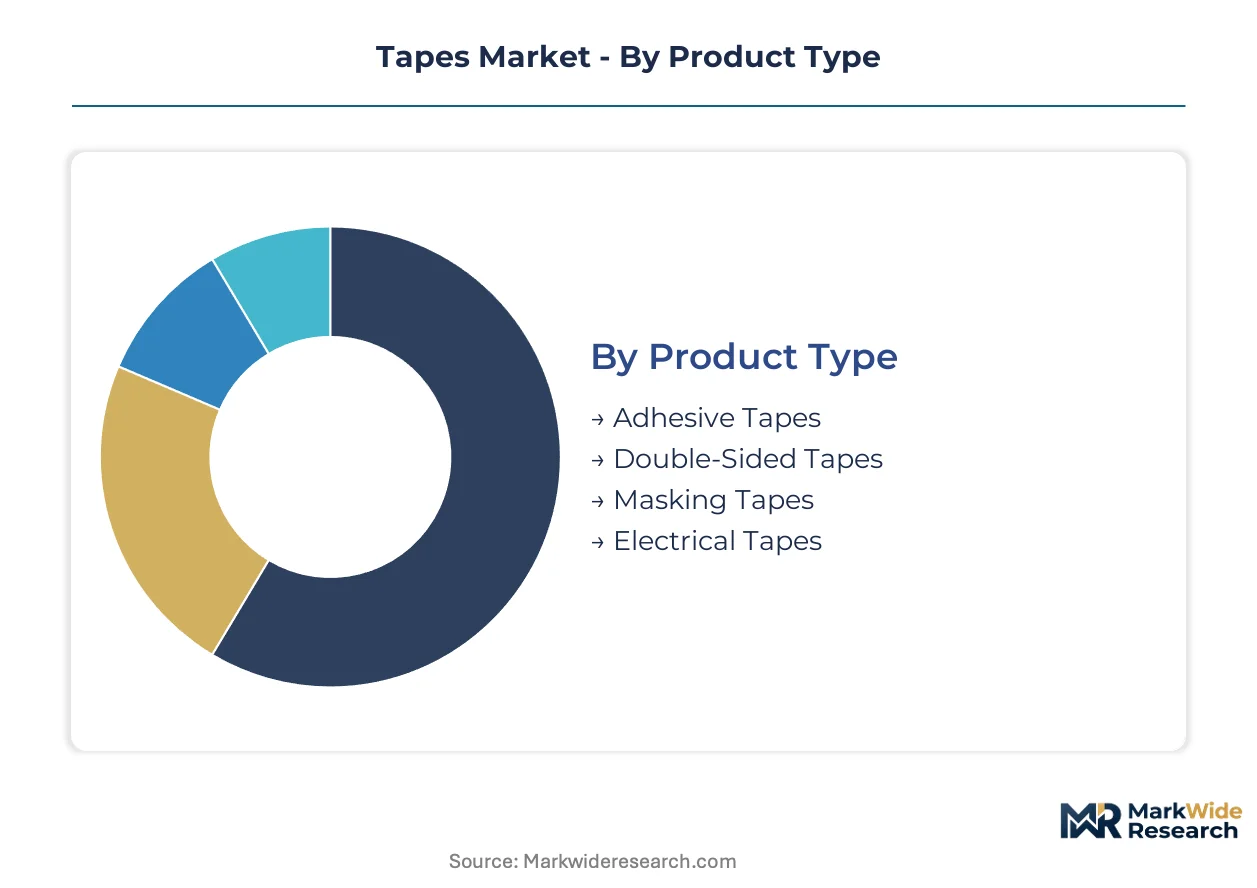
Segmentation in the tapes market reveals distinct performance requirements across adhesive chemistry, substrate material, and end-use specifications. Each dimension carries different margin profiles and regulatory exposure, shaping converter investment priorities and formulation roadmaps.
Product Type:
Cost tier differentiation separates commodity packaging grades from precision-engineered bonding solutions serving semiconductor and automotive assembly.
- Adhesive Tapes:Acrylic, rubber, or silicone formulations coated on flexible substrates ranging from micrometer electronics grades to millimeter construction thicknesses. Demand concentrates in China's eastern manufacturing corridor where export-oriented electronics producers specify peel adhesion and shear strength parameters under GB standards and dual carbon compliance frameworks.
- Double-Sided Tapes:Pressure-sensitive adhesive layers on both substrate faces enable invisible bonding without mechanical fasteners. Device miniaturization across South Korean and Taiwanese display manufacturers accelerates specification of ultra-thin die-attach films with controlled release properties for flip-chip packaging processes.
- Masking Tapes:Crepe paper or film backings with controlled tack for temporary surface protection during painting and coating operations.
- Electrical Tapes:PVC or rubber-based insulation grades facing REACH phthalate reformulation mandates for EU-bound shipments.
Adhesive Tapes holds installed capacity. Double-Sided Tapes is rotating up the share rankings.
End User:
Application maturity varies sharply across customer industries, with electronics and automotive driving specification intensity while construction and packaging operate on volume economics.
- Electronics:Miniaturization compresses bonding tolerances across consumer devices and semiconductor packaging, forcing substrate and adhesive chemistries to evolve with wafer-level processing roadmaps. UV-curable silicone formulations displace thermal-cure systems in optical bonding applications.
- Automotive:High-temperature harness wrapping and power electronics cooling modules specify silicone adhesives and thermal interface materials with boron nitride fillers. German OEMs enforce bio-based plasticizer compliance in supplier quality agreements under REACH authorization timelines.
- Construction:Heavy-duty bonding and sealing applications favor thicker tape constructions with weather-resistant acrylic formulations.
- Packaging:Carton sealing and logistics protection dominate volume consumption with commodity-grade hot-melt and waterborne acrylic systems.
Packaging commands volume throughput. Electronics is expanding most quickly through specification migration to headquarters engineering teams.
Material:
Substrate selection determines thermal stability, conformability, and cost structure across application environments from cleanroom electronics to outdoor construction exposure.
- Plastic:Polyester and polypropylene films dominate material consumption given versatility across temperature ranges and dielectric properties. China's Yangtze River Delta converters process plastic substrates within 200 kilometers of Shanghai port infrastructure for just-in-time electronics assembly.
- Fabric:Woven and non-woven backings sustain niche demand in high-temperature automotive harness wrapping where tear resistance and conformability to irregular surfaces outweigh film substrate economics.
- Paper:Crepe and flatback grades serve masking and general-purpose bonding with lower cost structures than film alternatives.
- Foam:Polyethylene and polyurethane cores provide gap-filling and vibration damping in automotive trim attachment and electronics gasketing.
Plastic holds installed capacity. Fabric is rotating up the share rankings on automotive electrification demand.
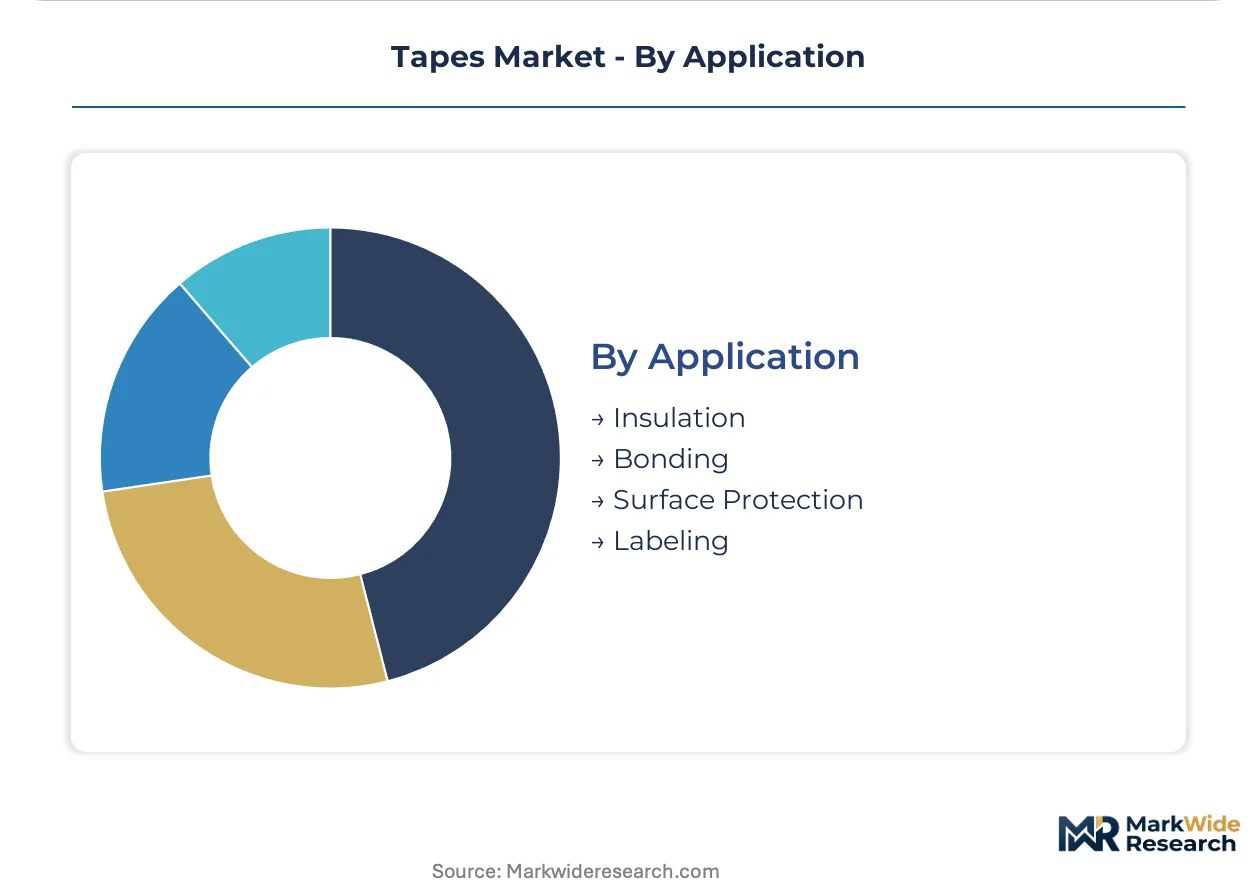
Application:
Functional requirement determines adhesive chemistry family and certification burden, with insulation and bonding carrying stricter validation protocols than surface protection or labeling.
- Bonding:Structural and semi-structural attachment applications specify shear strength, creep resistance, and environmental aging performance. Die-attach films in advanced packaging represent the steepest expansion trajectory as fan-out wafer-level processes proliferate.
- Insulation:Electrical and thermal barrier functions require dielectric strength validation and flammability ratings under JIS-certified programs promoted by Japan's METI for precision assembly procurement.
- Surface Protection:Temporary guarding of finishes and sensitive components during manufacturing and transit emphasizes clean removal without residue.
- Labeling:Printable facestocks with permanent or removable adhesives for identification and tracking across logistics and retail environments.
Surface Protection holds installed capacity. Bonding is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangshan deep-water port anchors Asia-Pacific tape logistics, handling specialized adhesive substrate imports for electronics manufacturing clusters within 200 kilometers of the terminal. The port's automated container handling compresses customs clearance for just-in-time assembly lines serving export markets.
China
Electronics contract manufacturers in Suzhou and Kunshan specify GB-certified tapes for smartphone and notebook assembly under SAMR emission ceilings. MEE enforcement of dual carbon goals is forcing solvent-to-waterborne adhesive conversions at Yangtze River Delta coating facilities. Tape converters cluster within the Shanghai-Nanjing-Hangzhou triangle to minimize logistics friction for semiconductor packaging customers.
Japan
Automotive harness suppliers in Aichi Prefecture demand JIS-certified silicone tapes for high-temperature electrification applications. METI quality infrastructure programs shape procurement specifications for precision assembly across domestic OEM supply chains. Nagoya-area resin producers supply specialty silicone adhesives that Korean and Taiwanese converters depend on for automotive-grade production.
Germany
REACH authorization timelines for phthalate plasticizers are compelling adhesive reformulation at tape plants serving EU-27 automotive markets. ECHA sunset date enforcement affects legacy PVC electrical tape formulations exported from Bavarian industrial zones. Stuttgart-based OEMs specify bio-based plasticizer compliance in supplier quality agreements for harness wrapping applications.
South Korea
Display manufacturers in Gyeonggi Province specify UV-curable silicone tapes for optical bonding to compress cycle times against thermal-cure alternatives. MFDS chemical registration requirements affect imported adhesive raw materials used in consumer electronics assembly. Suwon and Hwaseong industrial corridors concentrate tape slitting operations for Samsung and LG supply chains.
United States
EPA VOC regulations under the Clean Air Act shape adhesive formulation requirements for tape converters supplying automotive assembly plants in Michigan and Ohio. Electronics packaging demand in Austin and Phoenix drives specification of ultra-thin die-attach films for semiconductor testing operations. Midwestern distributors maintain inventory positions for just-in-time delivery to Detroit-area OEMs.
Tapes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in adhesive chemistry and substrate manufacturing. The tapes market structures around three tiers: multinational conglomerates with diversified materials portfolios, regional converters with die-cutting and slitting capabilities, and specialized formulators focused on single chemistry families. Competitive dynamics center on M&A activity consolidating converter networks and capacity expansion in Asian electronics corridors.
Within the multinational tier, 3M Company, Nitto Denko Corporation, and tesa SE exemplify divergent geographic anchoring and chemistry specialization. 3M represents the diversified materials conglomerate archetype with fluoropolymer and acrylic capabilities spanning industrial and consumer channels. Nitto Denko occupies a position as the East Asian optical and semiconductor tape specialist with supply chain integration into display manufacturing clusters. tesa SE exemplifies European precision die-cutting expertise serving automotive surface protection and industrial bonding applications.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corporation |
| tesa SE |
| Avery Dennison Corporation |
| Lintec Corporation |
| Intertape Polymer Group |
| Scapa Group PLC |
| Berry Global Inc. |
| Shurtape Technologies |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility determines both pricing tier spreads and supply chain shape across adhesive tape manufacturing, with acrylic monomer and polyester film costs compressing converter margins unpredictably while forcing tiered pricing stratification across premium, standard, and economy levels.
Pricing Analysis
Volume-discount tiering separates three-tier pricing structure across premium, standard, and economy levels, with certification grade under JIS and GB standards and volume scale as the primary differentiation drivers. Cost compression in standard-grade packaging tapes is intensifying because of naphtha cracking economics, while specialty electronics grades maintain pricing power. Automotive OEMs exhibit the least price sensitivity due to liability costs from bonding failures, with commodity packaging buyers most responsive to per-unit fluctuations.
Supply Chain Analysis
Upstream acrylic monomer and silicone resin feedstock draws from Japanese and South Korean petrochemical complexes, with polyester film substrate anchored in Chinese and Taiwanese manufacturing. Specialty silicone adhesives for high-temperature automotive applications rest on Nagoya-area resin producers, creating single-source vulnerability for automotive harness suppliers. Distribution runs through Yangtze River Delta converters clustered within 200 kilometers of Shanghai port infrastructure for just-in-time electronics assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronics miniaturization represents an early-cycle expansion story, with die-attach films in advanced packaging driving specification intensity as flip-chip and fan-out wafer-level processes proliferate across semiconductor manufacturing.
For Market Incumbents: Build formulation IP moats around UV-curable silicone chemistry to defend against thermal-cure displacement in optical bonding applications. Deepen backward integration into acrylic monomer supply through captive production or long-term offtake agreements with naphtha crackers. Accelerate cleanroom certification investments to capture semiconductor-grade tape slitting demand.
For New Entrants and Emerging Players: Pursue India's PLI scheme corridors in Gujarat and Tamil Nadu as white-space targets for smartphone component manufacturing tape conversion. Target thermal interface materials convergence with boron nitride fillers as the most penetrable application segment. Establish direct-to-plant distribution relationships with automotive OEMs bypassing traditional industrial distributors.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors specialized formulators with JIS and GB certification infrastructure over commodity converters. Long-term viability hinges on regulatory chemistry adaptation capability across REACH and dual carbon compliance frameworks. Watch for ECHA sunset date enforcement on phthalate plasticizers as the inflection indicator forcing consolidation among legacy PVC electrical tape producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Captive feedstock secures margin stability against naphtha cracking volatility for Yangtze River Delta coaters. |
| UV-Curable Silicone Formulation Investment | Cycle time compression in South Korean display manufacturing displaces thermal-cure incumbent positions. |
| Cleanroom Certification for ISO Class 7/8 Slitting | Semiconductor-grade validation extends facility commissioning timelines but locks in premium pricing tiers. |
| Direct-to-Plant Distribution Partnership | Automotive OEM bypass of industrial distributors captures margin for specialized tape formulators in Stuttgart supply chains. |
| Waterborne Adhesive Conversion Investment | MEE emission ceiling compliance under China's dual carbon goals enables continued access to export-oriented electronics corridors. |
Research Methodology
A standing panel of adhesive formulators, automotive harness procurement managers, electronics EMS technical directors, and tape slitting facility operators provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings from materials conglomerates, Japan Chemical Industry Association reports, and ECHA authorization databases. Bottom-up capacity assessments triangulated against top-down demand modeling from end-use industry production forecasts.
Scenario-bracketing anchored the analytical framework across the modeling period, with adhesive chemistry family, substrate material tier, end-use industry vertical, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from unit consumption trajectories in semiconductor packaging and automotive electrification applications, cross-referenced against substrate film production capacity expansion announcements and resin producer utilization rates.
Sensitivities concentrate around REACH authorization timeline shifts and MEE enforcement intensity under China's dual carbon framework. Forecasts reflect assumptions on solvent-to-waterborne conversion pace and UV-curable silicone adoption curves in display manufacturing. Material shifts in ECHA sunset date enforcement or GB standard emission ceiling adjustments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Sealing and Strapping Packaging Tapes Market
Tapes
Glue Tape Market
Tapes
Adhesive Transfer Tape Market
Tapes
Foam Tape Market
Tapes
Duct Tapes Market
Tapes
Global Adhesive Tapes Market
Tapes
Galley Tapes Market
Tapes
Tissue Tapes Market
Tapes
Pressure Sensitive Tapes and Labels Market
Tapes
Tear Tape Dispenser Market
Tapes
Pre-Printed Tape Market
Tapes
Invisible Tapes Market
Tapes
Pipe Anti-Corrosion Tape Market
Tapes
Global Non Woven Tape Market
Tapes
Metal Foil Tapes Market
Tapes
Unsupported Single Coated Tape Market