
 Carbon Tapes Market | 2026-2036
Carbon Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Tapes Market Outlook
REACH is realigning the cost-of-entry calculus for carbon tape suppliers serving European aerospace and automotive clients. Toray Industries leverages its upstream PAN precursor capacity to sustain margin control across the value chain. Hexcel Corporation anchors North American defense and commercial aviation demand through qualified material specifications. SGL Carbon specializes in thermoplastic tape formats that compete with traditional thermoset prepregs in automotive structural applications.
Carbon tapes are unidirectional or bidirectional strips of carbon fiber reinforcement, typically 25-300 mm wide, impregnated with thermoset or thermoplastic resin matrices and designed for automated fiber placement or tape laying processes. Prepreg tapes currently dominate aerospace structural applications where out-of-autoclave processing reduces cycle time and energy consumption. Non-prepreg dry tape formats are gaining traction in automotive components as OEMs seek to eliminate refrigeration costs and shorten supply lead times. Medical devices represent a concentrated margin pool where biocompatible thermoplastic tapes command premium positioning for orthopedic and surgical instrument applications.
The FAA certifies carbon tape structures under updated composite damage tolerance guidelines that extend qualification timelines but lock in incumbent supplier relationships. EASA harmonizes with FAA standards while adding EU-specific sustainability disclosure requirements through the CSRD framework. BASF and Mitsubishi Chemical navigate divergent regulatory pathways as they scale thermoplastic tape capacity for automotive OEMs. Stakeholders must monitor evolving recyclability mandates that could disadvantage thermoset-dominant product lines against thermoplastic alternatives.
Market Dynamics
Automated fiber placement systems are compressing production cycle times for aerospace primary structures, forcing tape suppliers to synchronize format specifications with equipment OEMs or face qualification exclusion.
Growth Catalysts
- EU Green Deal embodied carbon rules:Import restrictions on high-carbon composite materials are redirecting procurement toward European-qualified tape suppliers serving Stuttgart's automotive supplier corridor.
- Out-of-autoclave processing:Aerospace manufacturers are specifying prepreg tapes that cure without autoclave cycles, cutting energy consumption and floor space requirements for wing and fuselage components.
- Thermoplastic tape formats:Automotive OEMs are adopting non-prepreg dry tapes to eliminate refrigerated transport and extend material shelf life beyond thermoset limitations.
Market Restraints
- PAN precursor supply concentration:Acrylonitrile feedstock volatility and limited qualified precursor suppliers in Japan and the United States create margin pressure for downstream tape manufacturers.
- REACH compliance costs:ECHA chemical registration requirements for epoxy and thermoplastic resin systems impose six-figure entry costs that exclude regional compounders from European aerospace qualification.
- Aluminum-lithium substitution:Next-generation aerospace alloys are reclaiming secondary structure applications where carbon tapes had penetrated for weight reduction.
Strategic Opportunities
- Medical device biocompatibility:Orthopedic implant manufacturers are qualifying PEEK-based carbon tapes for spinal cages and surgical instruments at 40-60% premium pricing over industrial grades.
- Wind blade spar caps:Turbine OEMs are transitioning from fiberglass to carbon tape reinforcement for blades exceeding 80 meters, opening volume demand outside traditional aerospace and automotive channels.
- CSRD sustainability disclosure:EU corporate reporting mandates are creating preference for tape suppliers with verified lifecycle carbon data and end-of-life recyclability pathways.
Industry Challenges
- Automated fiber placement technician scarcity:Aerospace and automotive manufacturers compete for operators trained on AFP/ATL equipment, inflating labor costs and extending commissioning timelines for new production lines.
- FAA-EASA harmonization gaps:Divergent damage tolerance certification requirements force tape suppliers to maintain parallel qualification dossiers, doubling engineering overhead for dual-market products.
- Thermoplastic tape welding standardization:Absence of unified induction welding parameters across automotive OEMs prevents scale economies for structural battery enclosure applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Tapes Market |
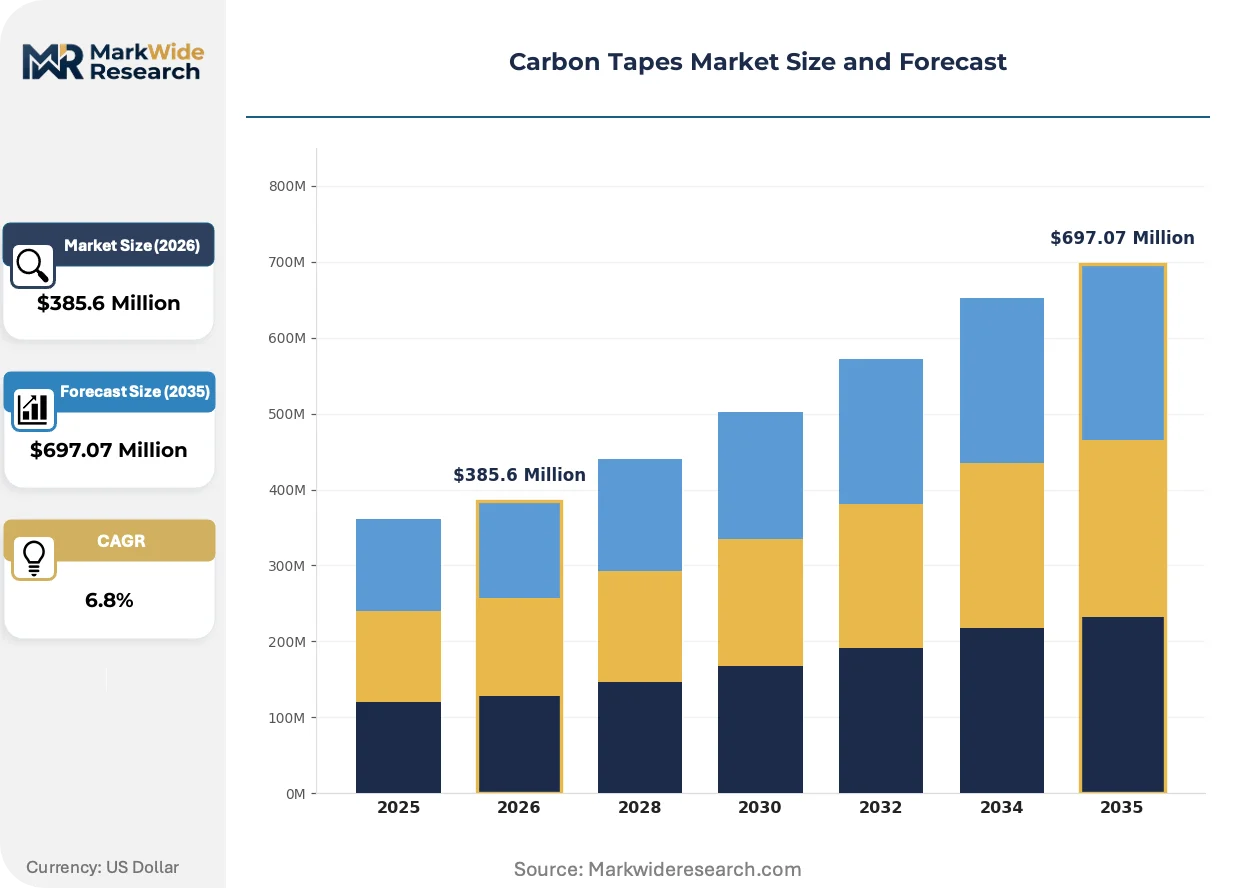
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepregs, Non-Prepregs, Adhesive Bonds, Thermal Interface Materials Application: Aerospace, Automotive Components, Medical Devices, Sports Equipment End User: Aerospace Manufacturers, Automotive OEMs, Healthcare Providers, Consumer Electronics Distribution Channel: Online Retailers, Direct Sales, Distributors, Resellers |
| Companies Covered | Toray Industries, Hexcel Corporation, Teijin Limited, SGL Carbon, Solvay, SABIC, Mitsubishi Chemical, Evonik Industries, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Tapes Market Strategic Shifts
Thermoplastic unidirectional tapes are absorbing investment and technical attention as equipment makers and material suppliers converge on in-situ consolidation processes that bypass autoclave bottlenecks entirely.
Continuous fiber-reinforced thermoplastic (CFRTP) tape technology is absorbing development resources from major resin compounders and machinery builders. Automotive tier-one suppliers in Germany are trialing in-situ AFP systems that consolidate PEEK and PPS-based tapes during placement. This processing shift is absorbing the capital that previously flowed toward thermoset prepreg capacity expansions, compressing the addressable market for traditional epoxy systems in non-aerospace applications.
REACH chemical restriction proposals under ECHA review are absorbing compliance planning cycles for tape formulators using bisphenol-A derived epoxies. The restriction roadmap threatens disqualification of qualified aerospace prepreg systems unless alternative resin platforms achieve equivalent mechanical properties and flame resistance. North American suppliers serving European aerospace OEMs are absorbing dual-registration costs to maintain market access under diverging regulatory timelines.
Consolidated procurement through tier-one system integrators is absorbing direct supplier relationships that previously connected tape manufacturers with airframers and automotive OEMs. Airbus and Boeing are directing composite structures procurement through Spirit AeroSystems and GKN Aerospace, compressing the qualified supplier base for raw tape materials. This channel compression is absorbing margin from independent tape converters and redirecting volume toward vertically integrated compounders with in-house AFP equipment partnerships.
Carbon Tapes Market Segmentation
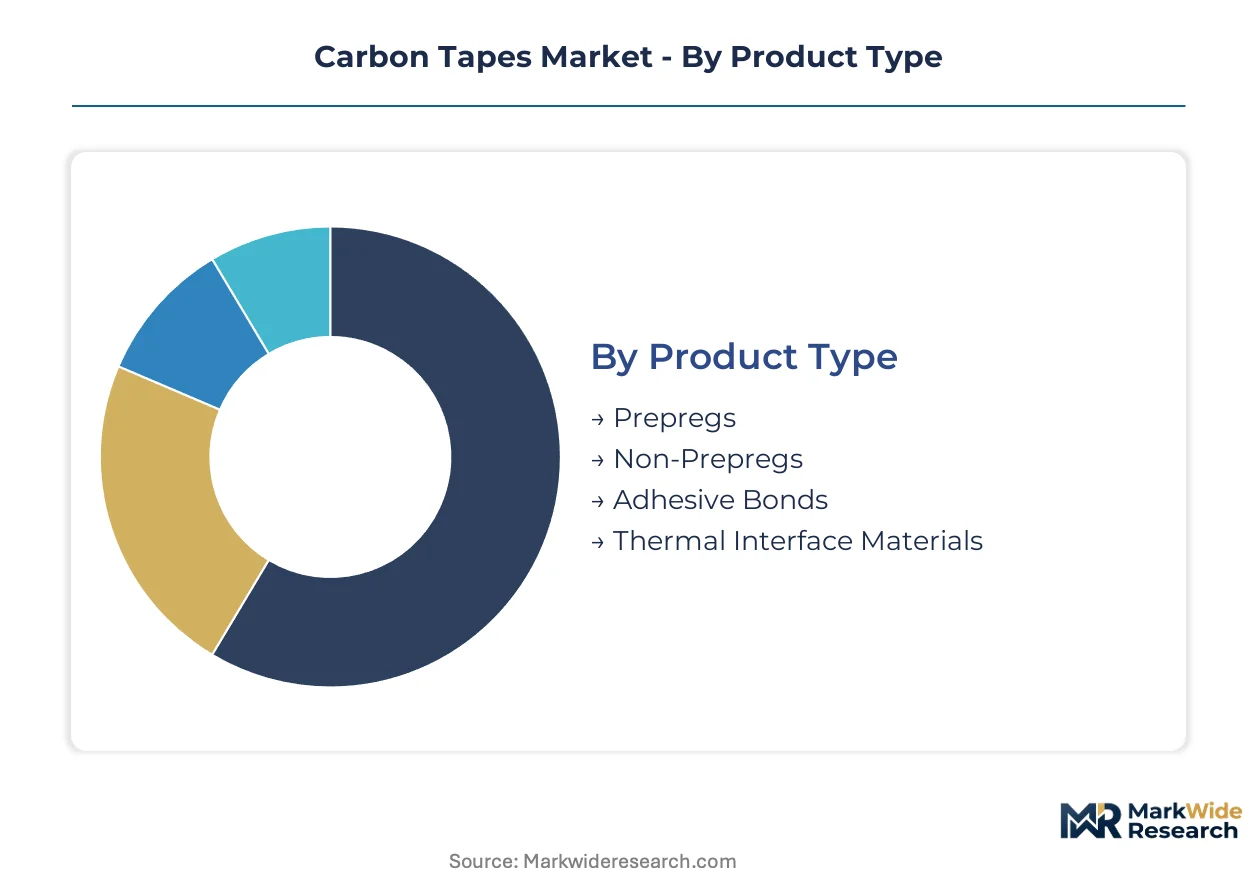
Carbon tape procurement patterns diverge sharply across product formats and end-use specifications. Aerospace qualification protocols favor prepreg systems with frozen-chain logistics, while automotive buyers prioritize shelf-stable formats that bypass refrigeration infrastructure.
Product Type:
Equipment refresh cycles and processing technology shifts are resegmenting demand across tape formats, with thermoplastic-capable AFP systems displacing legacy thermoset workflows.
- Prepregs:Resin-impregnated carbon fiber tapes requiring frozen storage and out-of-autoclave or autoclave curing. Demand concentrates in Airbus and Boeing primary structures where FAA damage tolerance guidelines mandate qualified material systems.
- Non-Prepregs:Dry carbon fiber tapes without resin matrix, enabling in-situ thermoplastic consolidation during automated fiber placement. Stuttgart's automotive supplier corridor is adopting PEEK and PPS-based formats to eliminate refrigerated transport costs.
- Adhesive Bonds:Tapes with pressure-sensitive or heat-activated adhesive layers for secondary bonding applications. Medical device manufacturers specify biocompatible variants for surgical instrument reinforcement.
- Thermal Interface Materials:Carbon-filled tapes engineered for heat dissipation in electronics enclosures. Consumer electronics OEMs integrate these into smartphone and laptop thermal management stacks.
Volume placements concentrate in Prepregs; the faster expansion belongs to Non-Prepregs.
Application:
Cost tier stratification separates aerospace-grade specifications from industrial commodity formats, with certification overhead creating pricing chasms between segments.
- Aerospace:Primary and secondary structural applications including wing spars, fuselage panels, and control surfaces. Wing structures absorb the largest tape volumes as OEMs replace aluminum in high-load paths.
- Automotive Components:Structural battery enclosures, body-in-white reinforcements, and crash-critical members. Germany's OEMs lead thermoplastic tape adoption for electric vehicle platform standardization.
- Medical Devices:Orthopedic implants, surgical instruments, and diagnostic equipment housings. PEEK-based tapes command premium positioning for spinal cage applications requiring biocompatibility certification.
- Sports Equipment:Bicycle frames, hockey sticks, and racing equipment where weight reduction justifies material cost premiums. European cycling component manufacturers specify high-modulus tapes for performance differentiation.
Revenue concentration sits with Aerospace; Automotive Components are climbing the fastest.
End User:
Customer procurement maturity separates qualified aerospace buyers with multi-year qualification cycles from automotive OEMs demanding rapid format flexibility.
- Aerospace Manufacturers:Airframers and tier-one structures suppliers with formalized material qualification programs. Spirit AeroSystems and GKN Aerospace consolidate procurement, compressing direct supplier access.
- Automotive OEMs:Volume manufacturers integrating carbon tapes into platform architectures. BMW and Porsche anchor demand in Stuttgart's supplier corridor.
- Healthcare Providers:Hospital systems and device manufacturers specifying biocompatible formats. FDA and EMA regulatory pathways dictate resin system selection.
- Consumer Electronics:Smartphone, laptop, and wearable device manufacturers seeking thermal and structural performance. Asian electronics assemblers drive commodity-grade carbon tape consumption.
Contract value aggregates with Aerospace Manufacturers; Healthcare Providers deliver the steepest margin expansion.
Distribution Channel:
Supply chain configuration separates qualified material systems requiring technical support from commodity formats moving through efficient logistics networks.
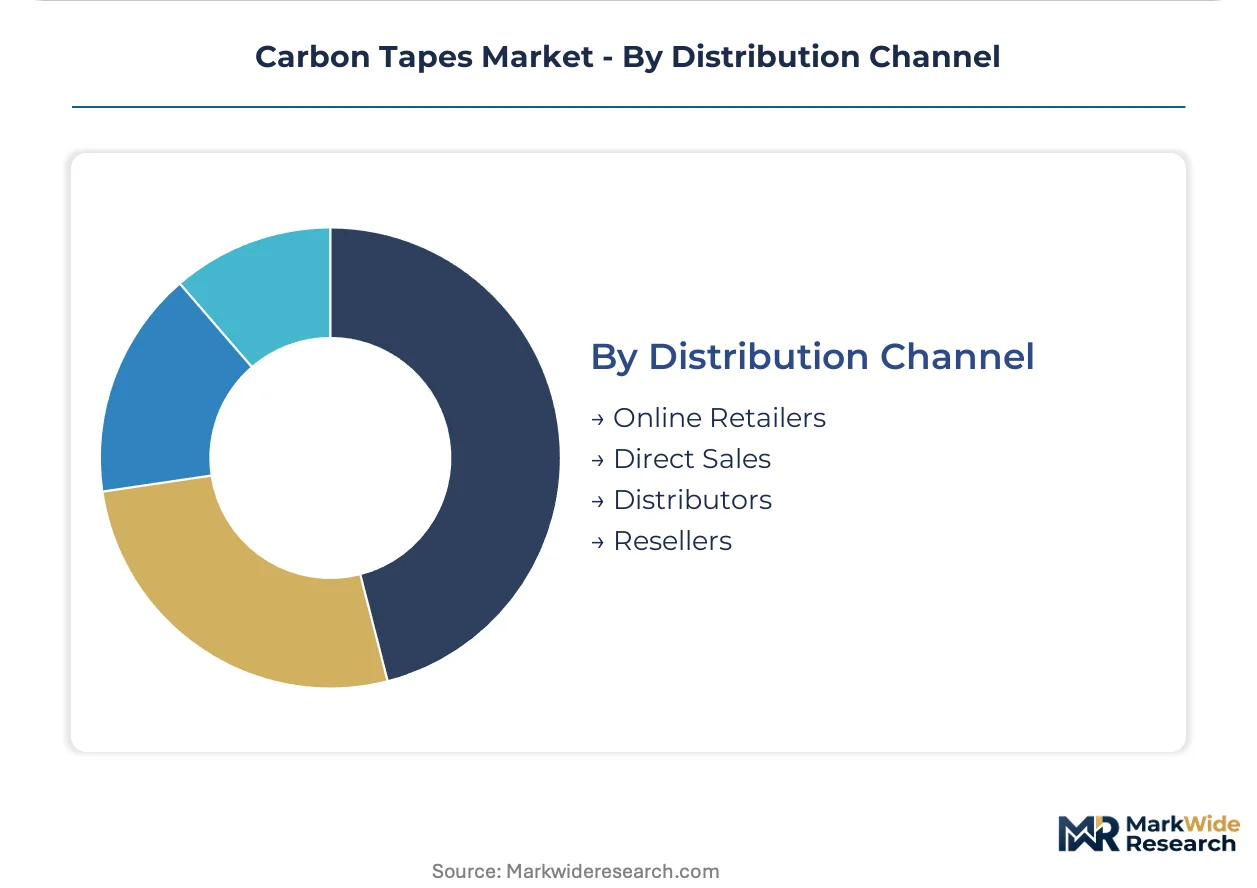
- Online Retailers:E-commerce platforms serving prototype builders, research institutions, and small manufacturers. Standard-width rolls and cut-to-length formats dominate this channel.
- Direct Sales:Manufacturer-to-OEM relationships for qualified aerospace and automotive programs. Field application engineering support accompanies high-volume contracts.
- Distributors:Regional stocking partners providing inventory buffering and technical service. European distributors navigate REACH compliance documentation for resin system shipments.
- Resellers:Secondary market channels for excess inventory and discontinued specifications. Price-sensitive buyers source through this channel for non-critical applications.
Transaction volume flows through Direct Sales; Online Retailers are gaining share fastest among emerging applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier corridor around Stuttgart operates as a concentrated demand zone for thermoplastic tape formats, with BMW and Porsche qualifying materials for electric vehicle platforms under EU Green Deal embodied carbon rules.
Germany
Stuttgart anchors European automotive carbon tape procurement as tier-one suppliers adopt PEEK-based formats for battery enclosures. ECHA REACH compliance requirements filter qualified resin systems, elevating compounders with registered chemical dossiers. Bavaria's industrial belt hosts machinery builders developing in-situ consolidation equipment for thermoplastic AFP processes.
United States
FAA damage tolerance guidelines extend qualification timelines for aerospace prepreg tapes, locking Spirit AeroSystems and Boeing into incumbent supplier relationships. Department of Defense procurement sustains demand for qualified material specifications across multiple airframe programs. Washington state's aerospace cluster concentrates composite structures manufacturing with integrated tape placement capabilities.
Japan
Toray Industries leverages captive PAN precursor capacity to control margins across the carbon tape value chain. METI industrial policy supports advanced materials R&D through designated strategic innovation programs. Nagoya's aerospace manufacturing hub supplies qualified prepreg systems for commercial aviation export markets.
China
MIIT dual carbon goals accelerate domestic carbon fiber capacity expansion to reduce import dependency for wind blade and automotive applications. NMPA medical device registration creates parallel pathways for biocompatible tape formats in orthopedic implant manufacturing. Yangtze River Delta industrial zones concentrate thermoplastic composite processing equipment development.
France
Airbus procurement consolidation through tier-one structures suppliers compresses direct access for independent tape converters. ANSM medical device regulations align with EMA pathways for PEEK-based implant materials. Toulouse's aerospace cluster maintains qualified prepreg supply chains for A350 wing and fuselage programs.
Carbon Tapes Market Competitive Environment
Japanese and German producers anchor the upstream precursor and resin-compounding tier; North American specialists hold qualified aerospace positions. Market structure concentrates around vertically integrated compounders with in-house PAN production and those with captive AFP equipment partnerships. Three archetypes dominate: integrated chemical conglomerates controlling precursor-to-tape value chains, aerospace-qualified specialists with frozen-chain logistics capabilities, and thermoplastic-focused compounders serving automotive consolidation trends. Capacity expansion and strategic equipment partnerships constitute the primary competitive vectors as suppliers synchronize format specifications with AFP system OEMs.
Among Japanese chemical conglomerates, Toray Industries and Teijin Limited exemplify the integrated precursor-to-tape archetype with captive supply chain control. Mitsubishi Chemical occupies a position within the thermoplastic resin and tape specialization tier. SGL Carbon represents the European automotive-focused model with emphasis on thermoplastic formats. Hexcel Corporation anchors North American aerospace qualification protocols. Solvay, SABIC, Evonik Industries, and BASF each sit within distinct chemical-compounder archetypes spanning epoxy systems, high-performance thermoplastics, and specialty resin platforms.
| Leading Market Players |
|---|
| Toray Industries |
| Hexcel Corporation |
| Teijin Limited |
| SGL Carbon |
| Solvay |
| SABIC |
| Mitsubishi Chemical |
| Evonik Industries |
| BASF |
| Others |
Value Chain & Pricing Dynamics
Tier-one aerospace structures suppliers consolidate procurement through Spirit AeroSystems and GKN Aerospace, compressing direct supplier access and anchoring contract-based long-term offtake pricing with frozen-chain logistics premiums.
Pricing Analysis
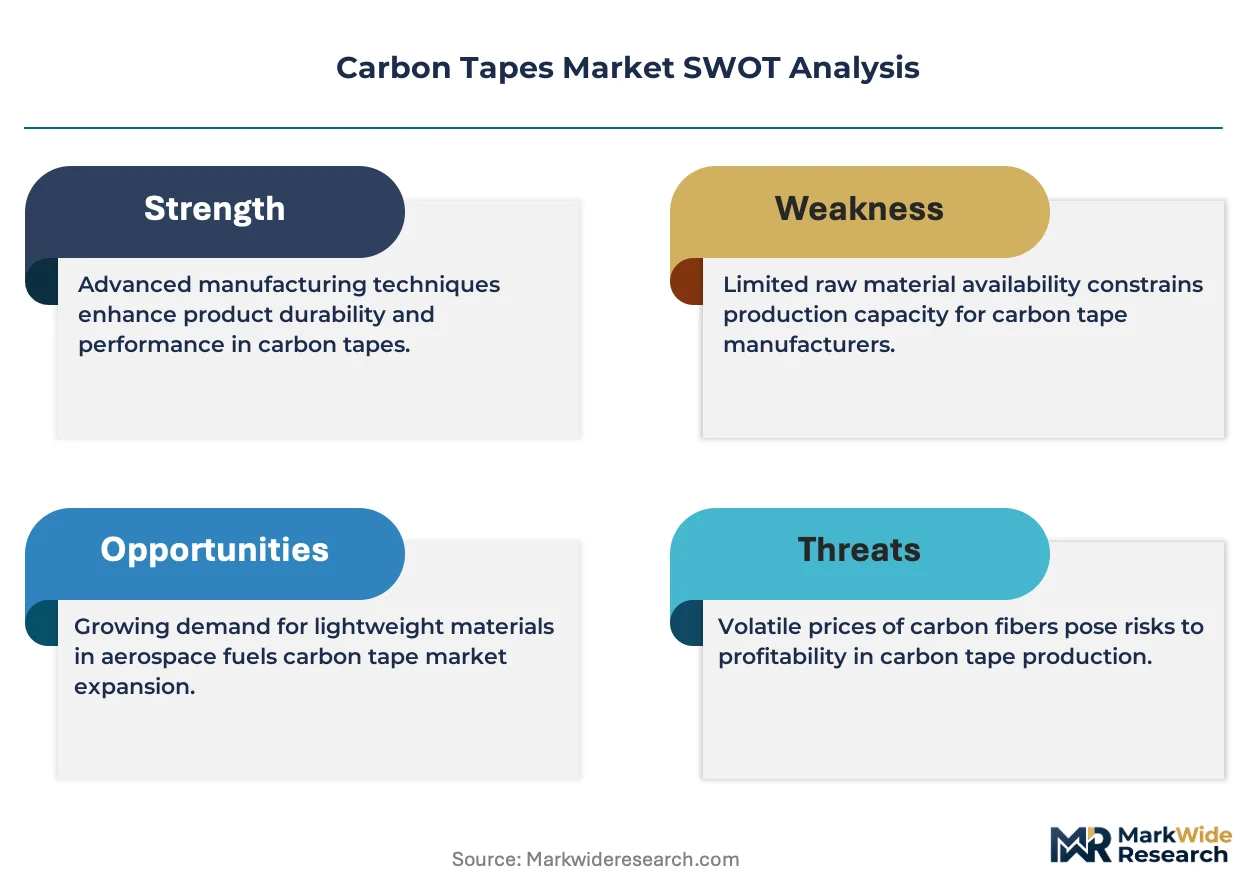
Short-lead-time spot inventory commands substantial premiums over qualified material systems with standard aerospace procurement cycles. Three-tier pricing structure across aerospace-qualified, automotive-industrial, and commodity research-grade separates segments by certification overhead and volume scale. Pricing pressure stems from aluminum-lithium alloy substitution reclaiming secondary structure applications. Automotive OEMs exhibit highest price sensitivity as they benchmark thermoplastic tapes against steel cost baselines.
Supply Chain Analysis
Domestic-content mandates under China's MIIT dual carbon goals and EU Green Deal embodied carbon rules are reshaping sourcing patterns toward qualified regional suppliers. PAN precursor production concentrates in Japan, the United States, and emerging Chinese capacity. Acrylonitrile feedstock, qualified resin systems, and AFP equipment components constitute critical input dependencies. Single-source vulnerability runs through Toray Industries' captive precursor-to-tape value chain. Distribution runs through tier-one system integrators with direct sales for qualified programs and regional distributors for industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs and FAA-EASA qualification overhead are forcing weaker compounders without registered chemical dossiers or dual-market certifications toward exit or acquisition.
For Market Incumbents: Anticipate thermoplastic format displacement by securing in-situ consolidation equipment partnerships with machinery builders in Germany and Japan. Backward integration into PAN precursor capacity defends margin control against acrylonitrile volatility. Prioritize CSRD-compliant lifecycle carbon data to capture EU corporate procurement preference. For New Entrants and Emerging Players: E-commerce platforms serving prototype builders and research institutions offer the most penetrable route around consolidated tier-one procurement channels. Target medical device biocompatibility certification as a premium segment with lower qualification barriers than aerospace. Pursue direct digital sales of standard-width PEEK-based tapes to orthopedic implant manufacturers. For Investors and Strategic Acquirers: Distressed-cycle entries favor thermoplastic-focused compounders with automotive OEM qualifications in Germany's Stuttgart corridor over legacy thermoset specialists. Five-to-ten year viability hinges on format flexibility across resin platforms. Monitor ECHA bisphenol-A restriction timelines as inflection signal for alternative epoxy system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Toray Industries' captive supply secures margin control against acrylonitrile price volatility. |
| Thermoplastic Capacity Expansion | SGL Carbon's PEEK-based formats capture BMW and Porsche electric vehicle platform demand. |
| In-Situ Consolidation Equipment Partnership | Machinery builders in Bavaria enable automotive OEMs to bypass autoclave bottlenecks entirely. |
| CSRD Sustainability Certification | Verified lifecycle carbon data unlocks EU corporate procurement preference under Green Deal rules. |
| Medical Device Biocompatibility Pathway | PEEK-based spinal cage qualifications command 40-60% premiums over industrial tape grades. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this carbon tapes analysis. Primary interviews with AFP equipment operators, automotive tier-one procurement leads, aerospace material qualification engineers, and resin compounder technical directors combined with ECHA registration databases, FAA certification records, and EU customs import data. Bottom-up tape volume estimates triangulated against top-down aerospace and automotive composite demand projections.
Granularity-level modeling operated at product format, end-use application, and regional manufacturing cluster dimensions across the analysis window. Prepreg and non-prepreg segments, aerospace versus automotive qualification tiers, and country-specific regulatory clusters were modeled separately. CAGRs derived from segment-level volume trajectories weighted by value-per-kilogram differentials. PAN precursor capacity expansion timelines and AFP equipment installation rates informed supply-side constraints.
Inputs from ECHA chemical registration databases and FAA certification timelines were available through the study window; gaps in proprietary OEM procurement data introduce uncertainty bands around tier-one supplier volume allocations. Forecasts reflect documented assumptions regarding thermoplastic adoption rates and REACH restriction implementation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Global Non-Conductive Water Blocking Tape Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Masking Tape Market
Tapes
India Masking Tapes Market
Tapes
Hydrocolloid Tapes Market
Tapes
Self-Fusing Silicone Tapes Market
Tapes
Breathable Tape Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Filament Tapes Market
Tapes
Tabbing Tapes Market
Tapes
Carton Sealing Tape Market
Tapes
Kraft Paper Tapes Market
Tapes
Global Construction Tape Market
Tapes
North America Packaging Tapes Market