
 Coding Foils and Tapes Market | 2026-2036
Coding Foils and Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Coding Foils and Tapes Market Outlook
Specialty distributor networks serving pharmaceutical and food packaging converters is reconfiguring as direct procurement from foil and tape manufacturers expands. 3M leverages its materials science portfolio to sustain premium positioning in thermal transfer ribbon formulations. KURZ Group anchors European supply for hot stamping foils through integrated pigment and carrier film production. Avery Dennison Corporation competes across labeling applications with extended adhesive and print-receptive coating capabilities.
Coding foils and tapes comprise thin substrate layers—typically polyester or cellulose acetate films coated with wax-resin, resin-only, or metallic pigment formulations—engineered to transfer alphanumeric codes, barcodes, and traceability data onto packaging surfaces via thermal, pressure, or digital activation. Thermal transfer ribbons dominate pharmaceutical serialization workflows where legibility under harsh storage conditions remains non-negotiable, while security tapes command margin premiums in anti-counterfeiting deployments across consumer goods. Flexographic and gravure printing technologies retain scale advantages in high-volume food and beverage labeling, though digital printing segments accelerate in short-run personalization and regional compliance variants.
FDA serialization mandates under the Drug Supply Chain Security Act shape pharmaceutical demand for permanent, tamper-evident coding substrates. REACH and the EU Green Deal restrict volatile organic compound migration in food-contact foils, compelling reformulation of thermal transfer coatings. China's GB standards and NMPA traceability rules extend comparable technical requirements across domestic pharmaceutical packaging. Stakeholders must monitor evolving substrate compliance thresholds and printing speed compatibility as automation investments outpace legacy ribbon specifications.
Market Dynamics
Pharmaceutical serialization mandates across Germany, China, and the United States are compressing procurement cycles for thermal transfer ribbons as converters race to upgrade legacy packaging lines before compliance deadlines. This regulatory pressure is reshaping supplier relationships and coating formulation priorities.
Growth Catalysts
- Drug Supply Chain Security Act:FDA serialization requirements mandate permanent, tamper-evident coding substrates across US pharmaceutical packaging, forcing wholesale ribbon specification upgrades.
- Hot stamping foil demand:Food and beverage converters in Germany are expanding security tape procurement to combat counterfeiting in premium spirits and organic product lines.
- GB standards alignment:China's NMPA traceability rules extend technical requirements for thermal transfer legibility under harsh storage conditions, matching EU pharmaceutical benchmarks.
Market Restraints
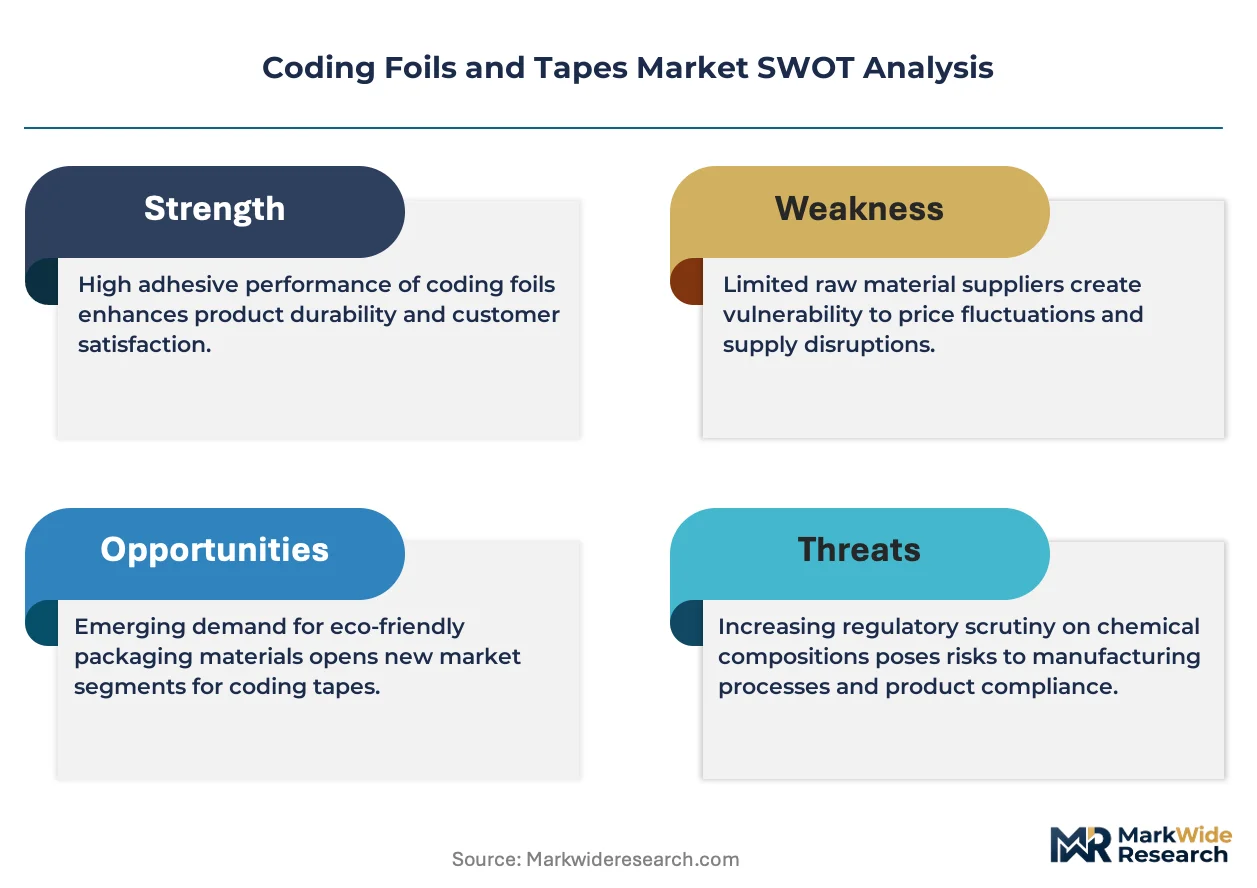
- Resin-wax input volatility:Petrochemical feedstock fluctuations destabilize thermal transfer ribbon coating costs, squeezing converter margins on fixed-price pharmaceutical contracts.
- Pigment supply concentration:Metallic pigment production for security foils clusters in southern Germany, creating single-source vulnerability for European hot stamping supply.
- Migration testing bottlenecks:REACH compliance timelines for low-migration ink reformulation delay new product launches by 8-14 months.
Strategic Opportunities
- India pharmaceutical expansion:CDSCO serialization rollout lags US and EU phases by 3-4 years, opening first-mover positioning for compliant ribbon suppliers.
- Digital-overprint integration:Convergence of thermal transfer base layers with inkjet personalization enables short-run regional compliance variants without plate changes.
- Direct manufacturer procurement:Pharmaceutical converters are bypassing specialty distributors to secure volume commitments and technical co-development access.
Industry Challenges
- Coating chemist scarcity:Formulation expertise for low-migration, high-speed thermal transfer coatings concentrates at legacy European suppliers, constraining new market entry.
- Legacy line incompatibility:High-speed pharmaceutical automation outpaces ribbon specification ranges, forcing costly printhead and tension system retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coding Foils and Tapes Market |
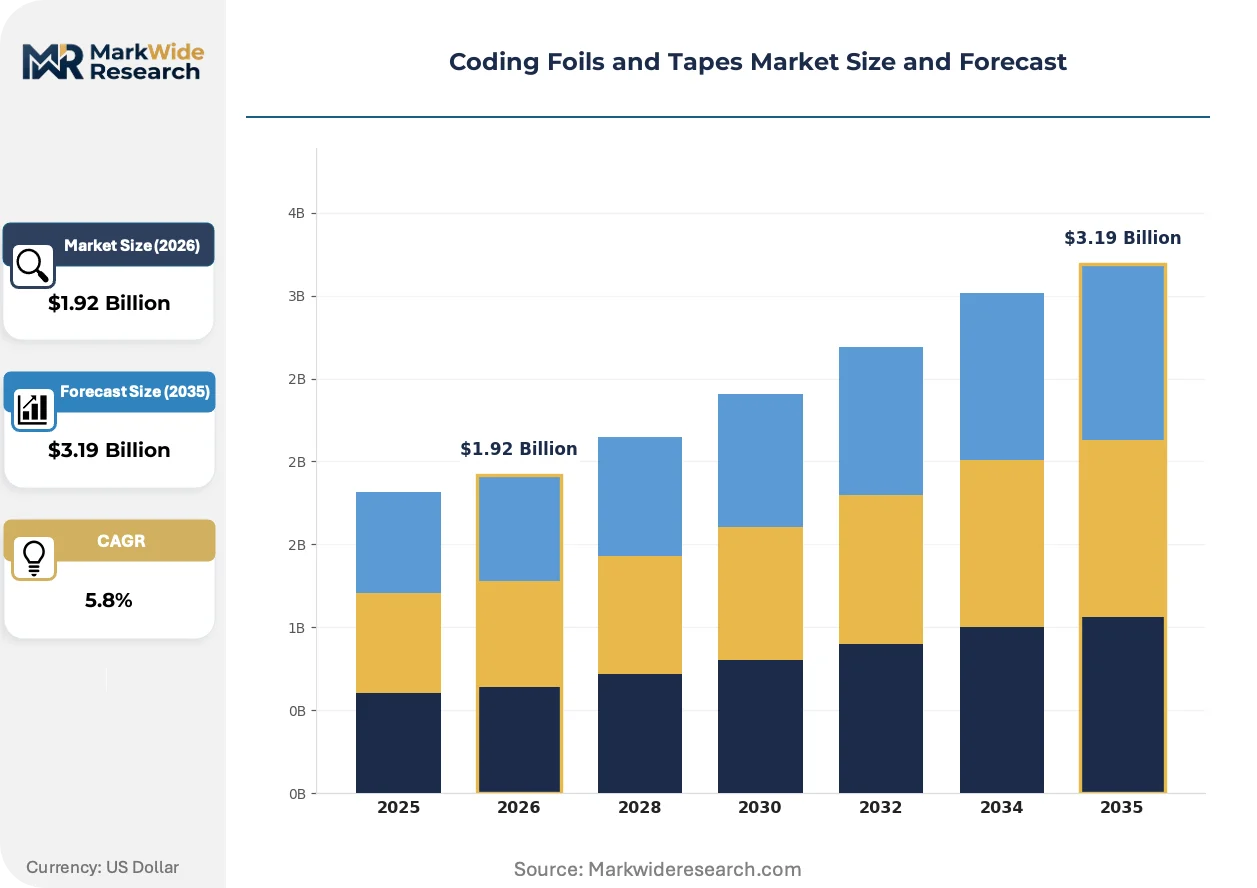
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.19 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Stamping Foils, Thermal Transfer Ribbons, Printing Tapes, Security Tapes Application: Packaging, Labeling, Product Marking, Security Printing End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Technology: Digital Printing, Flexographic Printing, Gravure Printing, Offset Printing |
| Companies Covered | 3M, Saint-Gobain, Avery Dennison Corporation, KURZ Group, Nitto Denko Corporation, tesa SE, ITW Foils, DIC Corporation, AG Foil s.r.o., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coding Foils and Tapes Market Strategic Shifts
Formulation chemistry and procurement architecture are undergoing simultaneous transformation as regulatory thresholds tighten and buyer concentration accelerates. These shifts are compressing traditional supplier hierarchies.
Near-edge thermal transfer ribbons with wax-resin hybrid coatings are collapsing the performance gap between economy and premium formulations. Pharmaceutical converters in the United States are adopting these mid-tier specifications at twice the pace of food packaging buyers. This compression is eliminating historical three-tier pricing stratification in favor of performance-certified single grades.
REACH restrictions on volatile organic compound migration in food-contact substrates are compelling coating reformulation across EU converter operations. ECHA enforcement timelines are tightening substrate chemistry documentation requirements beyond existing self-certification. German food packaging lines are responding by consolidating supplier bases to capture technical audit efficiencies.
Buyer concentration among multinational pharmaceutical contract packagers is compressing supplier negotiation cycles from annual to quarterly frameworks. Direct sourcing teams at three major US-based converters now specify thermal transfer products by performance band rather than brand. This shift is most visible in New Jersey and North Carolina pharmaceutical packaging clusters where automation investment rates exceed national averages.
Coding Foils and Tapes Market Segmentation
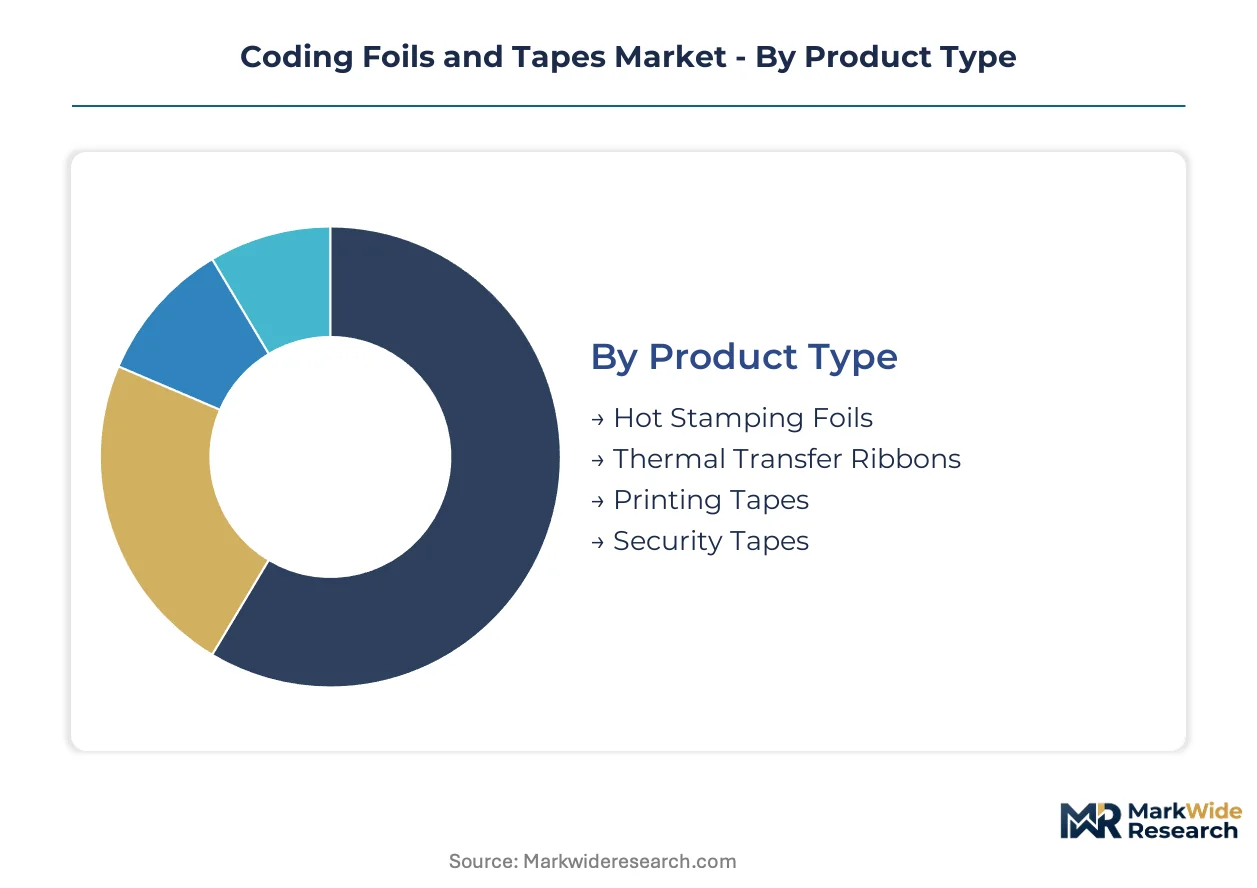
Segmentation in coding foils and tapes reveals how technical specifications, regulatory exposure, and automation intensity fragment procurement patterns across converter operations. Each dimension carries distinct margin profiles and compliance burdens that reshape supplier relationships.
Product Type:
After-sales service intensity varies sharply across product categories, with thermal transfer ribbons demanding printhead compatibility troubleshooting and hot stamping foils requiring die alignment calibration support.
- Hot Stamping Foils:Metallic pigment layers deposited on polyester or cellulose acetate carriers transfer under heat and pressure onto rigid substrates. Premium spirits packaging in Germany drives security-grade procurement as distillers combat counterfeiting in organic product lines. REACH documentation requirements for pigment chemistry extend service obligations to 14-month compliance windows.
- Thermal Transfer Ribbons:Wax-resin or resin-only coatings engineered for thermal printhead activation dominate pharmaceutical serialization where legibility under cold-chain storage is mandatory. FDA serialization mandates under the Drug Supply Chain Security Act compress specification upgrade cycles across US contract packagers.
- Printing Tapes:Pressure-sensitive adhesive substrates with print-receptive surfaces serve short-run labeling applications in regional food processing.
- Security Tapes:Tamper-evident formulations with holographic or void-release features command margin premiums in anti-counterfeiting deployments.
Thermal transfer ribbons hold the largest share; momentum sits with security tapes as brand protection budgets expand.
Application:
Application segmentation tracks how regulatory exposure concentrates demand in packaging versus the customization intensity of security printing.
- Packaging:Primary and secondary packaging surfaces receive batch codes, expiration dates, and traceability data through thermal or pressure transfer methods. Food and beverage lines in China scale procurement to match GB standards alignment for domestic distribution.
- Labeling:Adhesive-backed substrates with pre-printed or on-demand variable data serve logistics and retail compliance requirements.
- Product Marking:Direct surface coding on electronics housings and consumer goods demands abrasion-resistant resin formulations.
- Security Printing:Covert and overt authentication features integrate into tax stamps, certificates, and high-value product verification systems.
Packaging commands volume leadership; security printing is climbing the fastest as authentication mandates proliferate.
End User:
End user segmentation reflects divergent automation speeds and compliance stringency across vertical markets.
- Food & Beverage:High-speed filling lines in Germany operate at 600+ packages per minute, requiring ribbon formulations that minimize printhead wear. EU Green Deal restrictions on volatile organic compound migration compel coating reformulation with 8-14 month testing bottlenecks.
- Pharmaceuticals:Serialization mandates in the United States, Germany, and China enforce permanent, tamper-evident coding substrates with machine-readable permanence under harsh storage. NMPA traceability rules match EU technical benchmarks for thermal transfer legibility.
- Consumer Goods:Cosmetic and personal care packaging favors aesthetic hot stamping for premium positioning.
- Electronics:Component and device marking requires heat-resistant substrates for reflow soldering compatibility.
Pharmaceuticals dominates value capture; food and beverage shows steepest expansion trajectory as emerging market processing capacity scales.
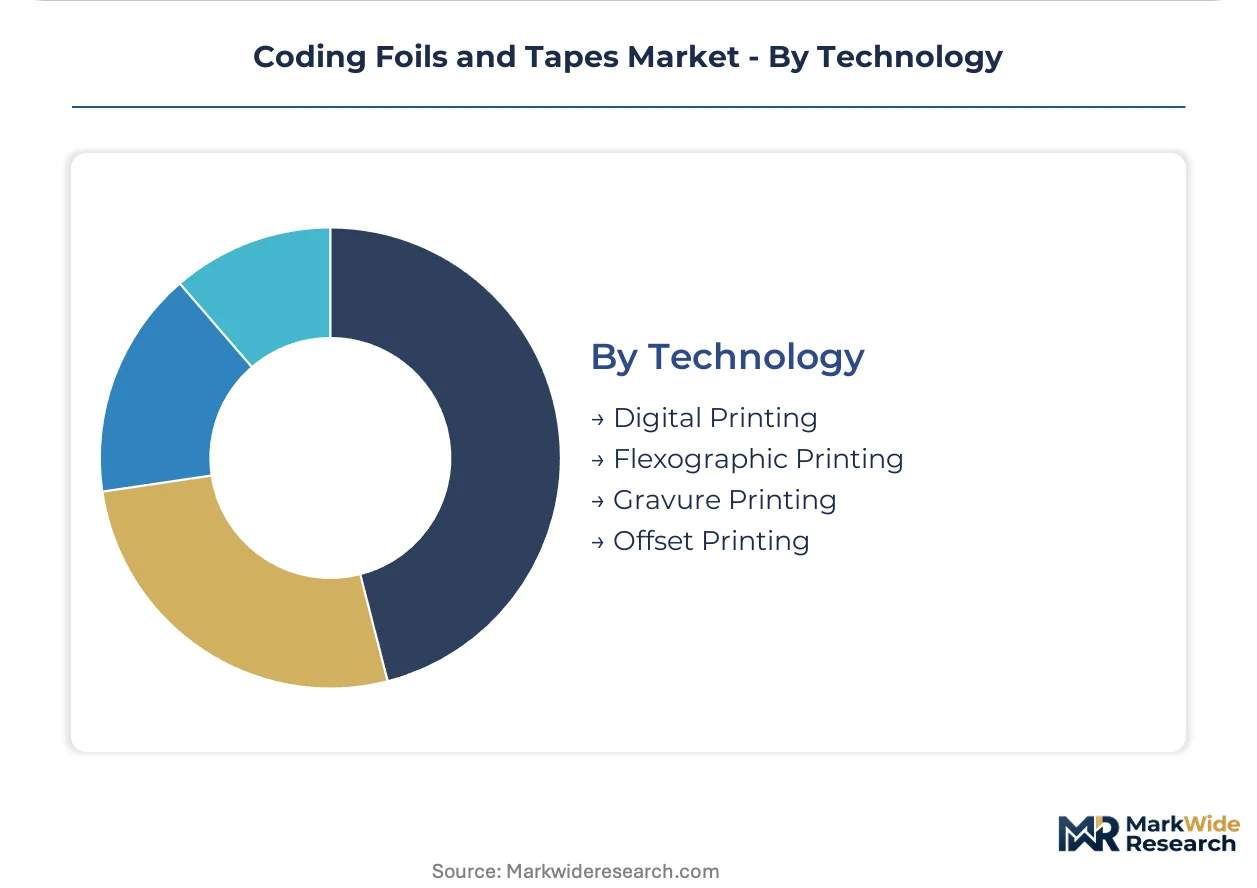
Technology:
Technology segmentation maps the tension between scale economies in analog methods and flexibility demands in digital workflows.
- Digital Printing:Inkjet and toner-based variable data systems enable short-run regional compliance without plate changes. Pharmaceutical converters in the United States adopt digital-overprint integration with thermal transfer base layers for personalization at scale.
- Flexographic Printing:Rotary relief plates with anilox roller metering retain cost advantages in high-volume food and beverage label production.
- Gravure Printing:Intaglio cylinder engraving delivers consistent ink film weights for long-run security printing applications.
- Offset Printing:Lithographic transfer from plate to blanket to substrate serves premium graphic packaging with precise color registration.
Flexographic printing maintains installed base dominance; digital printing is gaining share fastest as lot size fragmentation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premium multiples over Chinese thermal transfer ribbon benchmarks, reflecting formulation compliance costs and pigment supply concentration. This asymmetry reshapes procurement arbitrage strategies across converter networks.
United States
Pharmaceutical contract packagers in New Jersey and North Carolina drive thermal transfer ribbon demand as FDA serialization deadlines compress upgrade cycles. The Drug Supply Chain Security Act mandates permanent, tamper-evident coding substrates. Automation investment rates in these Atlantic seaboard clusters exceed national averages by a significant margin.
Germany
Hot stamping foil procurement for premium spirits packaging accelerates as distillers combat counterfeiting in organic product lines. REACH documentation requirements for metallic pigment chemistry extend supplier service obligations to 14-month compliance windows. Southern German pigment production concentration creates single-source vulnerability for European security foil supply.
China
Domestic pharmaceutical packaging lines scale thermal transfer ribbon procurement to match NMPA traceability rules under GB standards alignment. The national medical products regulator extends technical requirements for legibility under harsh storage conditions. Yangtze River Delta converter clusters absorb the bulk of compliance-driven specification upgrades.
India
CDSCO serialization rollout lags US and EU implementation phases by 3-4 years, opening first-mover positioning for compliant ribbon suppliers. The national pharmaceutical regulator's phased mandate approach creates windowed procurement surges. Maharashtra and Gujarat pharmaceutical packaging corridors concentrate early automation investments.
Japan
Electronics component marking demands heat-resistant substrates compatible with reflow soldering processes. METI industrial standards shape substrate performance specifications for device traceability. Kanto and Kansai manufacturing belts host dense concentrations of precision electronics assemblers.
Coding Foils and Tapes Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with formulation chemistry and carrier film production. The vendor base organizes around three strategic archetypes: diversified materials conglomerates with adhesive science portfolios, integrated foil specialists with captive pigment operations, and regional coating converters serving price-sensitive packaging segments. Consolidation pressure concentrates among mid-tier European coating houses facing REACH compliance cost escalation. Dominant competitive moves include direct procurement channel expansion bypassing specialty distributors and technical co-development partnerships with high-volume pharmaceutical packagers.
Among diversified materials conglomerates, 3M and Avery Dennison Corporation exemplify platform-scale positioning through extended adhesive and print-receptive coating capabilities. KURZ Group anchors the integrated foil specialist archetype with European supply chain density. These three entities represent distinct competitive vectors: materials science breadth, labeling application convergence, and vertical pigment-carrier integration.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| Avery Dennison Corporation |
| KURZ Group |
| Nitto Denko Corporation |
| tesa SE |
| ITW Foils |
| DIC Corporation |
| AG Foil s.r.o. |
| Others |
Value Chain & Pricing Dynamics
Single-source pigment concentration in southern Germany compresses margin buffers across European security foil tiers while simultaneously forcing converter procurement teams toward multi-country sourcing architectures. REACH compliance documentation costs propagate through coating reformulation cycles, widening the spread between certified premium formulations and uncertified economy grades.
Pricing Analysis
Configured-to-order pricing for REACH-compliant thermal transfer ribbons commands spreads of 40-60% above standard wax-resin formulations. The dominant pricing structure stratifies across premium, standard, and economy tiers, with certification level (ECHA-registered vs self-declared) and volume scale as primary differentiation drivers. Pricing pressure stems from resin-wax feedstock volatility squeezing converter margins on fixed-price pharmaceutical contracts. Small-batch food processors exhibit highest price sensitivity; pharmaceutical contract packagers prioritize performance certification over unit cost.
Supply Chain Analysis
Petrochemical feedstock supply for polyester carriers and wax-resin coatings concentrates in Germany, China, and the United States. Raw material dependencies span petroleum-derived polyester films, metallic pigments from southern German producers, and resin formulations from specialized chemical suppliers. Single-source vulnerability in European pigment production creates structural risk for security foil availability. Distribution runs through specialty distributor networks, though direct manufacturer procurement is displacing traditional channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, EMA, and NMPA compliance timelines fragments demand into discrete procurement windows, creating niche positioning opportunities for formulation specialists.
For Market Incumbents: Pre-empt coating chemist scarcity by securing exclusive technical talent arrangements with legacy European suppliers before CDSCO serialization accelerates Indian demand. Establish captive resin formulation capability to defend against petrochemical margin compression. Anchor supply security through backward integration into polyester carrier film production or long-term offtake agreements with southern German pigment producers.
For New Entrants and Emerging Players: Build out digital-overprint integration capabilities serving pharmaceutical converters seeking short-run regional compliance without plate changes. Target Maharashtra and Gujarat pharmaceutical packaging corridors where CDSCO implementation lags create first-mover windows. Lead with technical co-development partnerships offering printhead compatibility optimization rather than commodity ribbon supply.
For Investors and Strategic Acquirers: The market sits at a regulatory-compliance phase that favors integrated coating specialists with captive pigment operations and ECHA-registered formulation libraries. Long-term viability hinges on REACH adaptation capacity and pharmaceutical certification depth. Acquisition focus should center on mid-tier European coating houses facing compliance cost escalation. Watch NMPA enforcement intensity in Yangtze River Delta clusters as inflection indicator for Chinese demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Production | Captive metallic pigment supply eliminates single-source vulnerability for European security foil manufacturers. |
| REACH Compliance Certification Program | ECHA-registered coating formulations unlock premium pricing tiers in German food packaging procurement. |
| Digital-Overprint Technology Partnership | Inkjet personalization integration enables pharmaceutical converters to serve regional compliance variants at scale. |
| Direct Procurement Channel Expansion | Bypassing specialty distributors captures margin compression from buyer concentration among multinational packagers. |
| Technical Co-Development Agreement | Embedded R&D relationships with high-volume pharmaceutical packagers lock in specification-setting influence. |
Study Parameters
Cross-validation between primary fieldwork with coating formulators and secondary validation through regulatory filing databases anchors the qualitative findings. Conversations with pharmaceutical packaging procurement directors, thermal transfer printhead engineers, ECHA compliance consultants, and food converter operations managers informed demand-side dynamics. Secondary sources include FDA Drug Supply Chain Security Act guidance documents, ECHA REACH substance registration databases, NMPA traceability rule filings, and customs trade data for polyester film and metallic pigment flows. Bottom-up volume estimates from converter capacity installations triangulate against top-down market sizing from raw material consumption patterns.
Calibration against historical specification upgrade cycles shapes the analytical framework across the analysis window. Segmentation dimensions span product type (thermal transfer ribbon, hot stamping foil, security tape), end-use vertical (pharmaceutical, food and beverage, consumer goods), and technology (digital, flexographic, gravure). CAGRs derive from regression analysis of procurement intensity against regulatory deadline proximity. Industry-specific forecast inputs include pharmaceutical serialization mandate phase-in schedules and REACH enforcement timeline acceleration.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified materials conglomerates would shift competitive outcomes. Cross-checking against ECHA substance registration velocity and CDSCO implementation announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Reflective Tape Market
Tapes
Global Seam Sealing Tapes Market
Tapes
Paper Masking Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
India Reflective Tapes Market
Tapes
Mastic Tapes Market
Tapes
Double Sided Tape Market
Tapes
BOPP Packaging Tapes Market
Tapes
Dry Wall Tapes Market
Tapes
Industrial Tapes Market
Tapes
Wing Walk Tapes Market
Tapes
Utility Grade Duct Tapes Market
Tapes
Void Pattern Tamper-Evident Tapes Market
Tapes
Invisible Tapes Market
Tapes
Heat Sealing Tape Market
Tapes
Correction Tapes Market