
 Conductive Bags Market | 2026-2036
Conductive Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Bags Market Outlook
Electronics OEMs are gaining procurement share as defense contractors scale back orders, and demand between these buyer archetypes is bifurcating. Greif, Inc. leverages its integrated resin-to-bag manufacturing network across North American resin corridors. Berry Global Group, Inc. sustains R&D intensity in multilayer coextrusion for surface resistivity control. Mondi plc anchors European supply through kraft-based conductive laminates that serve pharmaceutical serialization requirements.
Conductive bags are engineered packaging structures incorporating carbon-loaded or metallized films to maintain surface resistivity between 10^3 and 10^11 ohms per square, dissipating electrostatic discharge that would otherwise destroy sensitive components. Flat bags dominate electronics component shipping due to standardized form factors and vacuum-seal compatibility, while custom bags capture margin pools from aerospace kitting operations that require part-specific dimensions and military-grade traceability. Polyethylene formulations lead volume production for their cost-efficient extrusion and broad chemical compatibility, though polyester substrates are displacing them in pharmaceutical cold-chain applications where dimensional stability across temperature swings matters more than unit cost.
The EPA regulates volatile organic compound emissions from adhesive lamination processes used in conductive bag assembly, while FDA 21 CFR Part 211 governs pharmaceutical contact materials that constrain substrate selection for drug-device combination packaging. ISO 61340-5-1 establishes electrostatic protected area requirements that OEMs cascade onto their packaging suppliers as conditional purchase terms. Stakeholders must monitor how the EU AI Act's supply chain traceability mandates could extend to packaging data carriers, forcing decisions on whether to embed RFID or printed electronics directly into conductive bag structures.
Market Dynamics
Semiconductor node shrinkage below 7nm is forcing fabs to reject standard packaging in favor of static-dissipative solutions with tighter surface resistivity tolerances, compressing converter margins while elevating technical qualification barriers.
Growth Catalysts
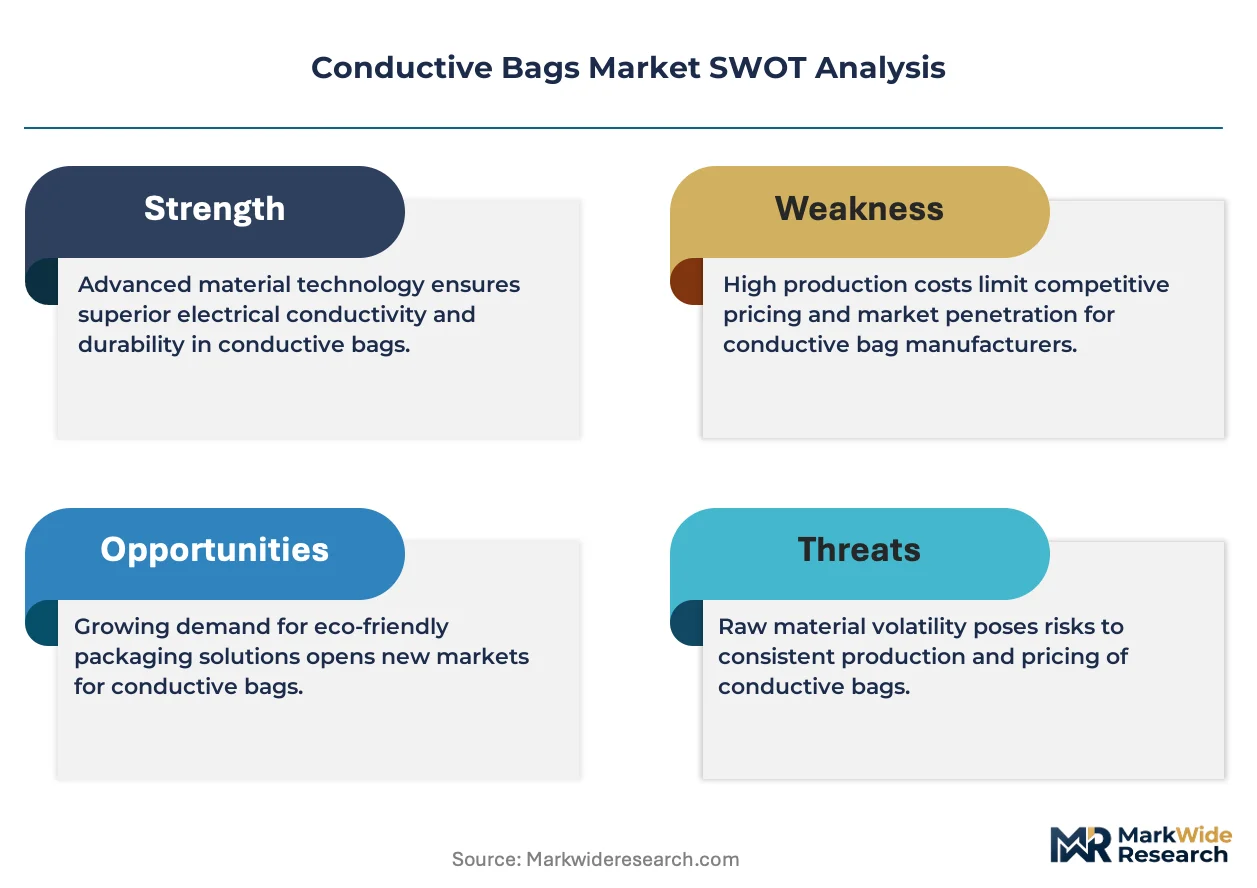
- REACH chemical restrictions:The EU's additive bans are accelerating compliant conductive formulation R&D, opening premium pricing tiers for certified converters.
- Wafer-level packaging expansion:Taiwan and South Korea fabs are mandating ESD-safe transport for bare die shipments, pulling demand for multilayer film structures.
- Carbon nanotube loading:This conductive filler technology enables thinner film gauges without resistivity degradation, reducing resin consumption per bag.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin accounts for majority material cost, and naphtha-cracker output swings in the US Gulf Coast directly compress converter margins.
- Carbon black supply concentration:Three suppliers control furnace-grade conductive pigment, creating single-source risk for mid-tier bag producers.
- Metallized film substitution ceiling:Aluminum-sputtered substrates achieve lower resistivity but fail flex-cracking tests for aerospace kitting, limiting addressable market.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme subsidies for semiconductor assembly are creating first-mover advantage for ESD packaging suppliers establishing local extrusion.
- RFID-embedded traceability:EU AI Act supply chain mandates are converging with conductive bag structures, enabling premium smart packaging tiers.
- Cold-chain pharmaceutical serialization:Polyester-based conductive laminates with dimensional stability are capturing temperature-controlled biologics distribution.
Industry Challenges
- ISO 61340-5-1 auditor scarcity:Certification backlog delays supplier qualification for electrostatic protected area compliance, stretching OEM onboarding timelines.
- Multilayer coextrusion capex:Seven-layer blown film lines require capital deployment that mid-cap converters cannot access, consolidating supply among resin-integrated majors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Bags Market |
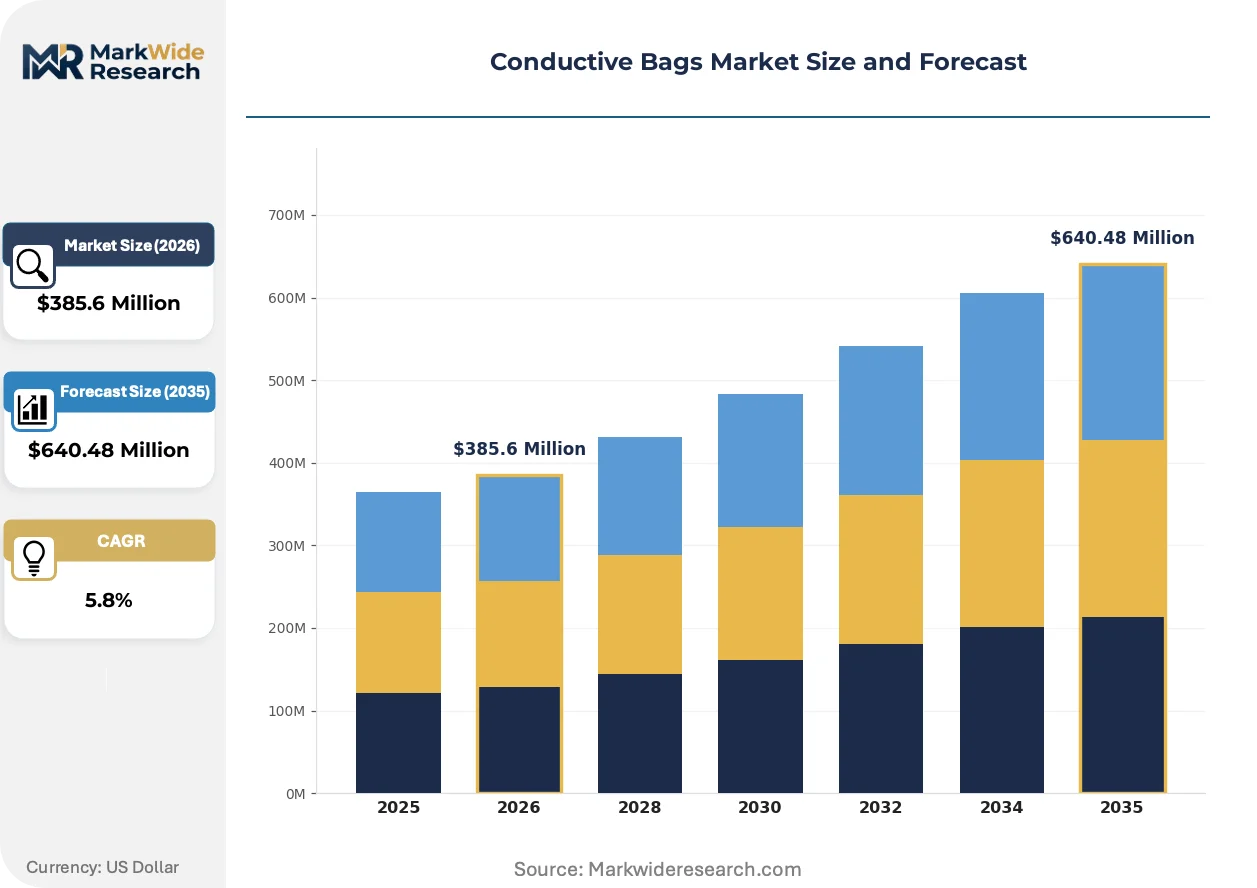
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Zipper Bags, Custom Bags, Resealable Bags Material: Polyethylene, Polyester, Nylon, Paper End User: Electronics, Pharmaceuticals, Aerospace, Defense Packaging Type: Bulk Packaging, Retail Packaging, Carton Packaging, Pallet Packaging |
| Companies Covered | Greif, Inc., Berry Global Group, Inc., Mondi plc, LC Packaging, BAG Corp, SAMOA FIBC GmbH, Flexi-tuff, Conitex Sonoco, Rishi FIBC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Bags Market Strategic Shifts
Active material science breakthroughs are splitting the market between commodity polyethylene formulations and engineered multilayer structures, while regulatory traceability mandates are embedding digital identity directly into packaging substrates.
Multilayer coextrusion with discrete conductive and barrier layers is fragmenting the traditional monolayer bag market. Pharmaceutical cold-chain distributors are specifying these structures for temperature-stable ESD protection. The technology is fragmenting procurement categories, forcing buyers to maintain dual supplier bases for standard and premium applications.
REACH restrictions on phthalate plasticizers and heavy-metal pigments are eliminating legacy conductive masterbatch formulations. European converters are reformulating with bio-based carbon blacks and compliant polymer carriers. Medical device packaging lines in Germany and France face the steepest reformulation timelines, with some OEMs pre-qualifying alternative suppliers six months ahead of enforcement.
Direct mill relationships are replacing distributor intermediaries for high-volume electronics OEMs. Taiwan-based semiconductor houses now contract extruders on annual resin-indexed terms, bypassing regional packaging distributors entirely. This channel compression is most advanced in East Asian manufacturing clusters, where logistics integration favors landed-cost optimization over local inventory holding.
Conductive Bags Market Segmentation
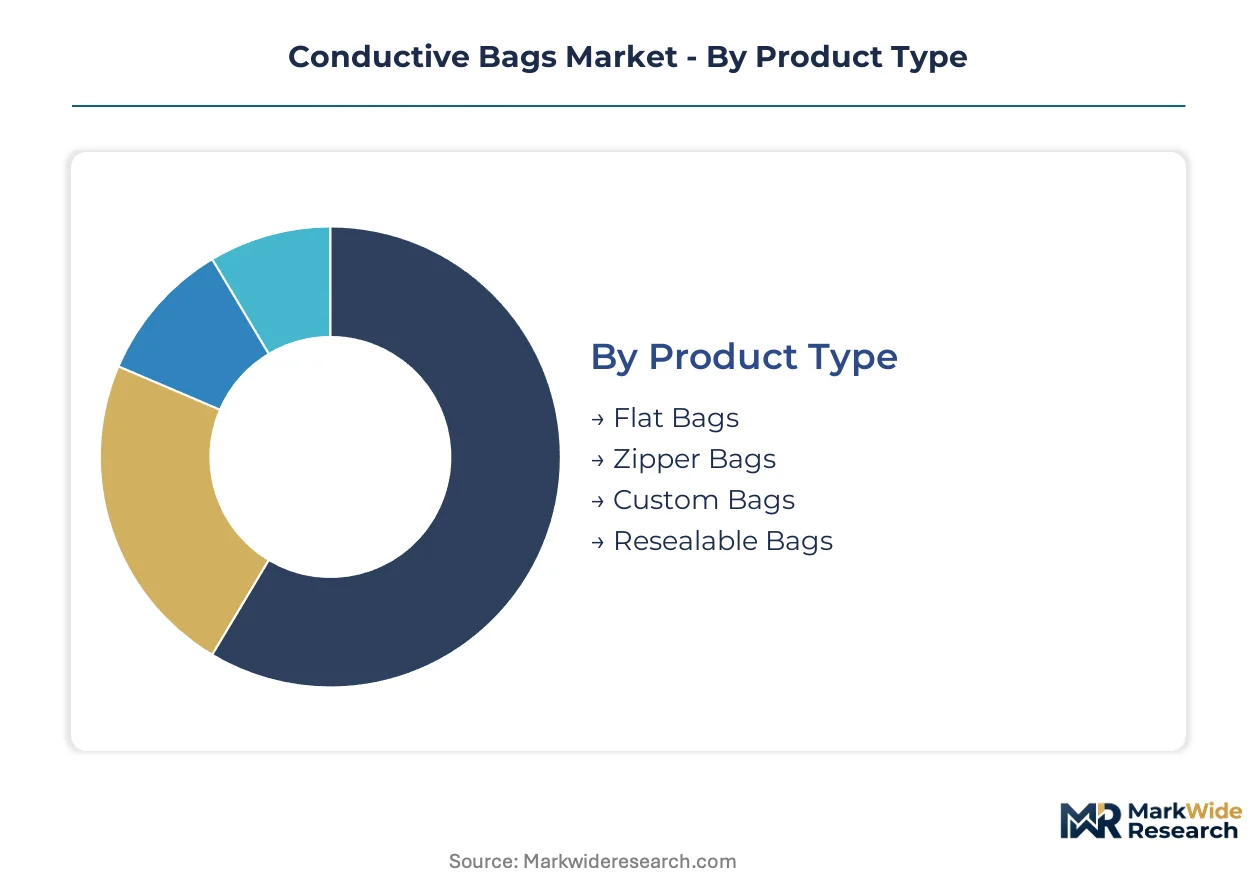
Conductive bag procurement splits sharply between domestic electronics manufacturing and export-driven pharmaceutical distribution. Segment selection determines resin formulation, barrier layer complexity, and compliance documentation burdens.
Product Type:
Flat bags and zipper bags serve primarily domestic electronics assembly lines, while custom bags ship to export-heavy aerospace kitting operations in Taiwan and South Korea.
- Flat Bags:Monolayer polyethylene structures with carbon-loaded films maintain surface resistivity between 10^3 and 10^11 ohms per square. Electronics OEMs in Taiwan and South Korea specify these for standardized component shipping, driven by wafer-level packaging expansion and vacuum-seal compatibility requirements.
- Custom Bags:Engineered multilayer coextrusions with part-specific dimensions and military-grade traceability serve aerospace kitting. Demand concentrates in South Korean defense supply chains and Taiwanese semiconductor fabs, constrained by ISO 61340-5-1 auditor scarcity stretching qualification timelines.
- Zipper Bags:Resealable closures add contamination control for pharmaceutical sampling operations.
- Resealable Bags:Adhesive strip variants dominate electronics rework stations requiring repeated access.
Flat bags command the established base. The steepest expansion runs through custom bags.
Material:
Cost tiers separate commodity polyethylene from engineered polyester, with nylon occupying mid-range performance positioning and paper serving regulatory-niche pharmaceutical serialization.
- Polyethylene:Cost-efficient extrusion and broad chemical compatibility sustain volume leadership. Electronics manufacturers in Taiwan specify these for bare die transport, though ethylene feedstock volatility from US Gulf Coast naphtha crackers compresses converter margins.
- Polyester:Dimensional stability across temperature swings displaces polyethylene in pharmaceutical cold-chain applications. German and French medical device packaging lines pre-qualify these structures six months ahead of REACH enforcement deadlines.
- Nylon:Superior puncture resistance serves aerospace hardware with sharp-edged components.
- Paper:Kraft-based conductive laminates from Mondi plc anchor European pharmaceutical serialization requirements.
Polyethylene retains volume dominance. Polyester gains share fastest in temperature-controlled biologics distribution.
End User:
Customer type determines certification intensity, with defense contractors demanding military-grade traceability and electronics OEMs prioritizing landed-cost optimization.
- Electronics:Semiconductor fabs below 7nm nodes reject standard packaging for static-dissipative solutions with tighter resistivity tolerances. Taiwan-based houses now contract extruders directly on annual resin-indexed terms, bypassing regional distributors.
- Pharmaceuticals:Cold-chain distributors specify multilayer polyester laminates for temperature-stable ESD protection. EU AI Act supply chain traceability mandates are converging with conductive bag structures, enabling premium smart packaging tiers.
- Aerospace:Part-specific kitting operations require custom dimensions and flex-crack resistance that metallized films fail.
- Defense:Military-grade traceability documentation and serialized inventory control add procurement overhead.
Electronics anchors procurement volume. Pharmaceuticals shows the steepest margin expansion trajectory.
Packaging Type:
Volume scale separates bulk shipments to fab loading docks from retail units distributed through pharmaceutical channels.
- Bulk Packaging:Large-format conductive liners for semiconductor wafer cassettes ship directly to Taiwan and South Korean fab loading docks. Carbon nanotube loading enables thinner film gauges without resistivity degradation, reducing resin consumption per shipment.
- Retail Packaging:Unit-dose formats for pharmaceutical counter sales require printed lot codes and tamper-evident closures. Indian PLI scheme subsidies for semiconductor assembly are creating first-mover advantage for ESD packaging suppliers establishing local extrusion.
- Carton Packaging:Intermediate aggregation for electronics distributors balances protection with cube efficiency.
- Pallet Packaging:Stretch-wrap conductive films for aerospace logistics consolidation.
Bulk packaging commands the established base. Retail packaging climbs the fastest as pharmaceutical serialization requirements deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung-Taichung industrial corridor anchors East Asian electronics manufacturing, with dedicated container terminals at Kaohsiung Port handling semiconductor packaging materials bound for wafer fabs across Taiwan and South Korea.
United States
Semiconductor fabrication plants in Arizona and Texas are expanding procurement of static-dissipative packaging as domestic chip manufacturing reshoring accelerates. EPA regulations on volatile organic compound emissions from adhesive lamination processes constrain converter operations in the US Gulf Coast resin corridor. Electronics OEMs in Austin and Phoenix now contract extruders directly on annual resin-indexed terms.
Germany
Medical device packaging lines in Bavaria and Baden-Württemberg face steep reformulation timelines as ECHA REACH restrictions on phthalate plasticizers eliminate legacy conductive masterbatch formulations. The country's national pharmaceutical regulator enforces strict compliance documentation for temperature-controlled biologics distribution. Stuttgart-based converters are pre-qualifying polyester-based conductive laminates six months ahead of enforcement deadlines.
Taiwan
Wafer-level packaging expansion at Hsinchu Science Park and Tainan Technology Industrial Park is mandating ESD-safe transport for bare die shipments. The country's industrial standards bureau cascades ISO 61340-5-1 electrostatic protected area requirements onto packaging suppliers as conditional purchase terms. Semiconductor houses in Hsinchu now bypass regional distributors entirely, contracting extruders on landed-cost optimization terms.
South Korea
Defense supply chains and semiconductor fabs in Gyeonggi Province are driving demand for custom bags with military-grade traceability and part-specific dimensions. The Ministry of Trade, Industry and Energy oversees PLI scheme subsidies for semiconductor assembly that pull ESD packaging demand. Pyeongtaek-Dangjin port complexes handle bulk conductive liner shipments for fab loading docks.
India
Electronics manufacturing clusters in Karnataka and Tamil Nadu are emerging as procurement growth zones as PLI scheme subsidies for semiconductor assembly create first-mover advantage for ESD packaging suppliers. The Bureau of Indian Standards monitors compliance for pharmaceutical contact materials in temperature-controlled distribution. Chennai and Bengaluru extrusion facilities are establishing local resin-to-bag manufacturing to serve domestic electronics OEMs.
Conductive Bags Market Competitive Environment
Listed leaders compete with private specialists across resin integration and qualification intensity. The vendor base splits between resin-integrated majors with captive polyethylene supply and mid-cap converters dependent on spot resin markets. Three archetypes dominate: integrated resin-to-bag manufacturers, multilayer coextrusion specialists, and regional distributors losing share to direct mill relationships. Competitive moves center on backward integration into resin corridors and ISO 61340-5-1 certification stacking to stretch OEM onboarding timelines.
Among North American resin-integrated players, Greif, Inc. and Berry Global Group, Inc. exemplify the scale-driven archetype with captive supply networks. Mondi plc occupies a position within the European kraft-based laminate segment, representing the specialty materials tier that serves pharmaceutical serialization requirements. These three companies anchor the competitive structure without exhausting the field, as private specialists and regional converters fill gaps in custom dimensions and local logistics.
| Leading Market Players |
|---|
| Greif, Inc. |
| Berry Global Group, Inc. |
| Mondi plc |
| LC Packaging |
| BAG Corp |
| SAMOA FIBC GmbH |
| Flexi-tuff |
| Conitex Sonoco |
| Rishi FIBC |
| Others |
Value Chain & Pricing Dynamics
Sixty-day resin-indexed contract windows now dominate Taiwan and South Korean procurement, compressing spot-market arbitrage and anchoring pricing power with integrated resin-to-bag manufacturers rather than distributor intermediaries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 61340-5-1 certified multilayer structures from commodity monolayer polyethylene bags. Price differentiation hinges on certification grade and volume scale, with semiconductor fabs below 7nm nodes accepting premium tiers for tighter resistivity tolerances. Cost compression in standard polyethylene tiers is intensifying because ethylene feedstock volatility from US Gulf Coast naphtha crackers squeezes converter margins. Electronics OEMs in Taiwan exhibit highest price sensitivity through annual resin-indexed terms, while pharmaceutical cold-chain distributors show lowest sensitivity due to serialization compliance requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites carbon black feedstock flows from furnace-grade pigment suppliers in India and China to extrusion facilities across East Asia. Geographic supply concentration centers on Taiwan, South Korea, and the US Gulf Coast for resin production and bag conversion. Raw material dependencies rest on polyethylene resin, conductive carbon black, and metallized film substrates. Single-source vulnerability from three suppliers controlling furnace-grade conductive pigment creates chokepoint risk for mid-tier bag producers. Distribution runs through direct mill relationships replacing regional distributors, with semiconductor houses in Hsinchu and Gyeonggi Province contracting extruders on landed-cost optimization terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor node shrinkage and REACH reformulation timelines are fragmenting procurement categories, creating white-space niches for specialists between resin-integrated majors and commodity converters.
For Market Incumbents: Secure backward integration into North American resin corridors to defend against ethylene feedstock volatility compressing converter margins. Stack ISO 61340-5-1 certification investments to stretch OEM onboarding timelines and lock out mid-cap competitors lacking auditor access. Prioritize captive supply of carbon-loaded masterbatch formulations to offset single-source pigment concentration risk. For New Entrants and Emerging Players: Lead with polyester-based conductive laminates for Indian pharmaceutical cold-chain expansion under PLI scheme subsidies, where local extrusion capacity remains underdeveloped. Target Karnataka and Tamil Nadu electronics manufacturing clusters with temperature-stable ESD protection solutions. Position through direct mill relationships bypassing distributor intermediaries that dominate legacy procurement channels. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because multilayer coextrusion capex requirements and auditor scarcity are structurally consolidating supply among resin-integrated majors with certification depth. Acquisition target archetype: mid-cap converters with established ISO 61340-5-1 qualifications and regional logistics integration in East Asian manufacturing clusters. Signal to watch: EU AI Act supply chain traceability mandate enforcement accelerating RFID-embedded smart packaging tier adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Greif and Berry Global anchor North American supply through captive polyethylene production corridors. |
| Multilayer Coextrusion Capacity Expansion | Seven-layer blown film lines enable thinner carbon nanotube-loaded gauges without resistivity degradation. |
| ISO 61340-5-1 Certification Stacking | Auditor scarcity stretches OEM qualification timelines, locking preferred supplier status for certified converters. |
| RFID-Embedded Smart Packaging Development | EU AI Act traceability mandates converge with conductive substrates for pharmaceutical serialization tiers. |
| Direct Mill Relationship Establishment | Taiwan semiconductor houses bypass distributors entirely for annual resin-indexed contract terms. |
Study Parameters
Initial hypotheses were tested against primary input from packaging procurement managers at semiconductor fabs, converter plant managers in Taiwan and South Korea, pharmaceutical supply chain directors, and resin trading desk analysts, and refined through secondary validation against customs trade data, SEC 10-K filings from listed packaging manufacturers, ECHA REACH regulatory filings, and ISO certification registry databases. Bottom-up demand modeling from wafer-level packaging expansion and top-down market sizing from resin consumption patterns were triangulated to cross-validate volume estimates.
Variance-decomposition framing separated volume drivers by product type, material substrate, end-use industry, and regional manufacturing cluster across the analysis window. CAGRs were derived from segmented growth rate assumptions applied to baseline consumption estimates, with semiconductor node shrinkage timelines and REACH enforcement deadlines as key forecast inputs. Pharmaceutical cold-chain expansion and Indian PLI scheme subsidy uptake were modeled as scenario-weighted demand accelerators.
The analysis sits within stated boundaries; outcomes outside sustained ethylene feedstock price stability, ECHA additive ban enforcement timelines, or ISO auditor availability expansion would require recalibration. Forecasts reflect documented assumptions about wafer-level packaging adoption rates and conductive formulation R&D progress. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bag-In-Box Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Multiwall Bags Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Pre-Made Bags Market
Bags and Containers
North America Retail Bags Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
Cassava Bags Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Drum Liners Market
Bags and Containers
Vacuum Shrink Bags Market
Bags and Containers
Global High Abuse Shrink Bags Market