
 Differential Tapes Market | 2026-2036
Differential Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Differential Tapes Market Outlook
Multi-source procurement toward captive polymer supply is realigning how converters secure acrylic adhesive feedstocks. 3M Company anchors North American capacity through in-house resin synthesis at its Minnesota complex. Nitto Denko Corporation dominates Asian electronics-grade output with proprietary solvent-free coating lines. Henkel AG & Co. KGaA extends European reach via regional toll manufacturing partnerships that reduce cross-border logistics exposure.
Differential tapes are pressure-sensitive adhesive constructions with dissimilar facestocks—typically polyester, polyimide, or aluminum foil bonded to foam or paper carriers—engineered to deliver asymmetric peel strength, thermal conductivity, or electrical isolation across joined substrates. Double-sided products command the widest specification range, serving structural bonding in electric vehicle battery modules where dielectric strength and thermal cycling resistance prove critical. Conductive variants occupy narrow but high-margin niches in electromagnetic interference shielding for telecommunications hardware, while heat-resistant grades sustain adhesive integrity above 150°C in aerospace engine compartment applications.
FDA migration limits and EPA volatile organic compound rules constrain solvent-based adhesive formulations in US medical and industrial end uses, pushing demand toward UV-cured and hot-melt alternatives. ECHA REACH substance restrictions and EU F-Gas Regulation phase-down schedules further reshape European material selection, particularly for fluorinated release liners and blowing agents in foam carriers. Stakeholders must monitor evolving substance ban timelines and qualify alternative chemistries before existing formulations lose market access.
Market Dynamics
Automotive adhesive bonding programs are displacing mechanical fasteners in electric vehicle assembly, redirecting specification authority from tier-two component suppliers directly to OEM engineering teams and compressing qualification timelines for tape converters.
Growth Catalysts
- EV Battery Module Bonding:Dielectric differential tapes secure cell-to-cell isolation in lithium-ion packs, with thermal cycling resistance specifications tightening across German and Chinese automotive programs.
- REACH Substance Restrictions:ECHA's expanding SVHC list accelerates reformulation toward solvent-free acrylics, opening specification windows for converters with qualified UV-cured alternatives.
- Bavarian Precision Assembly:Industrial automation clusters in Baden-Württemberg consume specialized bonding solutions for miniaturized electronics, concentrating demand for sub-50-micron tolerance tapes.
Market Restraints
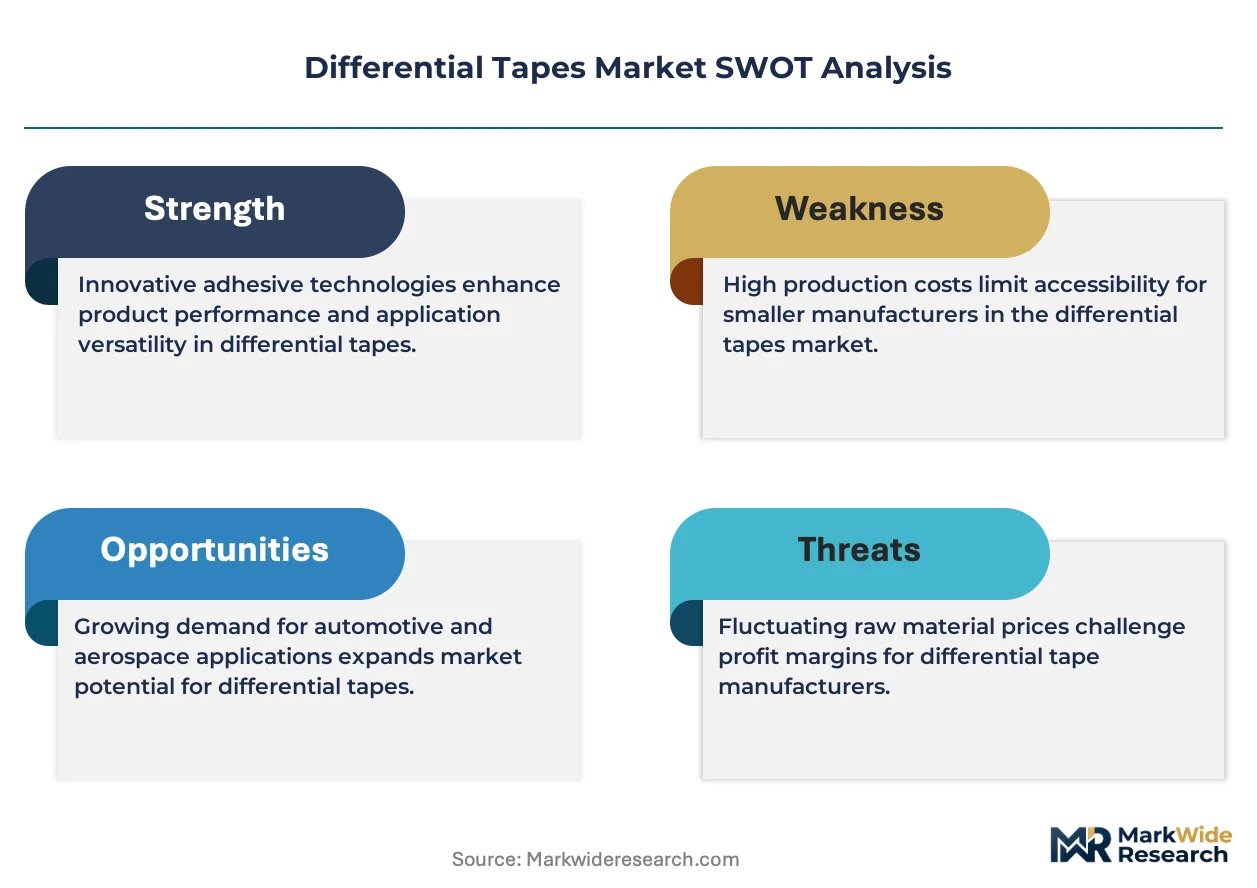
- Acrylic Monomer Volatility:Crude-linked feedstock costs for 2-ethylhexyl acrylate swing tape gross margins without contract pass-through mechanisms.
- Asian Electronics-Grade Concentration:Solvent-free coating capacity clusters in Japan and Korea, exposing European automotive buyers to extended lead times and currency exposure.
- Mechanical Fastener Residual Preference:Aerospace structural joints retain bolted connections for traceability, capping tape penetration in primary load-bearing applications.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme subsidies for mobile device assembly create first-mover advantage for tape converters establishing local slitting and die-cutting operations.
- 5G Infrastructure Shielding:Conductive differential tapes for electromagnetic interference suppression in base station antennas represent uncontracted demand as telecom capital expenditure accelerates.
- F-Gas Phase-Down Alignment:EU Regulation 517/2014 drives fluorinated release liner substitution, rewarding converters with bio-based silicone alternatives already qualified under ECHA protocols.
Industry Challenges
- Adhesive Formulation Chemist Scarcity:Solvent-to-UV conversion expertise concentrates among retiring specialists, extending R&D cycle times for next-generation products.
- Multi-Jurisdiction Certification Overlap:Simultaneous FDA migration limits, EPA VOC rules, and REACH substance restrictions demand parallel qualification tracks, straining regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Differential Tapes Market |
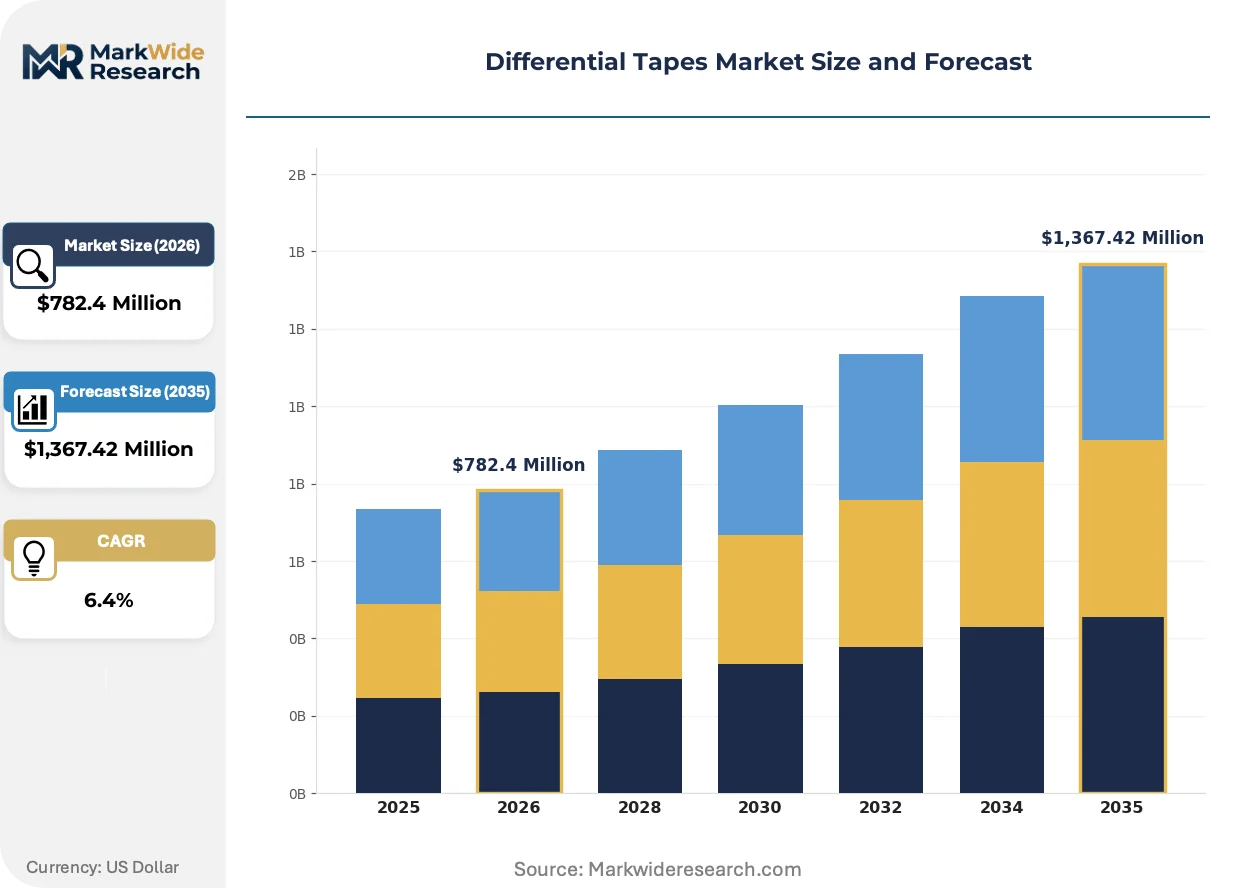
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,367.42 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Conductive, Heat-Resistant Application: Automotive, Electronics, Construction, Aerospace Material: Polymer, Foam, Paper, Aluminum End User: Manufacturers, DIY Enthusiasts, Contractors, Engineers |
| Companies Covered | 3M Company, Nitto Denko Corporation, tesa SE, Avery Dennison Corporation, Saint-Gobain Performance Plastics, Scapa Group plc, Intertape Polymer Group, Shurtape Technologies, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Differential Tapes Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to reshape how differential tapes are formulated, coated, and specified across automotive, electronics, and medical end uses.
Solvent-free UV-curable acrylic adhesives are decentralizing coating operations away from centralized chemical plants toward regional toll manufacturing hubs. German automotive suppliers now specify UV-cured constructions for battery module assembly, eliminating solvent recovery infrastructure. This technology is decentralizing supply chain risk by enabling smaller-batch regional production with 72-hour turnaround versus six-week ocean freight dependency.
ECHA's REACH authorization requirements for diisocyanates entered full enforcement for industrial users in August 2023, forcing polyurethane adhesive converters toward aliphatic epoxy alternatives. Industrial consequence includes accelerated qualification of polyester-silicone hybrid chemistries previously sidelined by cost. Medical device tape applications in Germany and France face the tightest substitution timelines, with notified body review queues extending certification cycles.
Specification authority migration from tier suppliers to OEM engineering teams is compressing converter sales cycles and fragmenting order volumes. Automotive buyers in Stuttgart and Wolfsburg now demand lot-level thermal cycling data, displacing historical certificate-of-analysis acceptance. This pattern is most visible in German premium EV programs, where adhesive bonding responsibility shifted from body-in-white suppliers to battery pack integrators.
Differential Tapes Market Segmentation
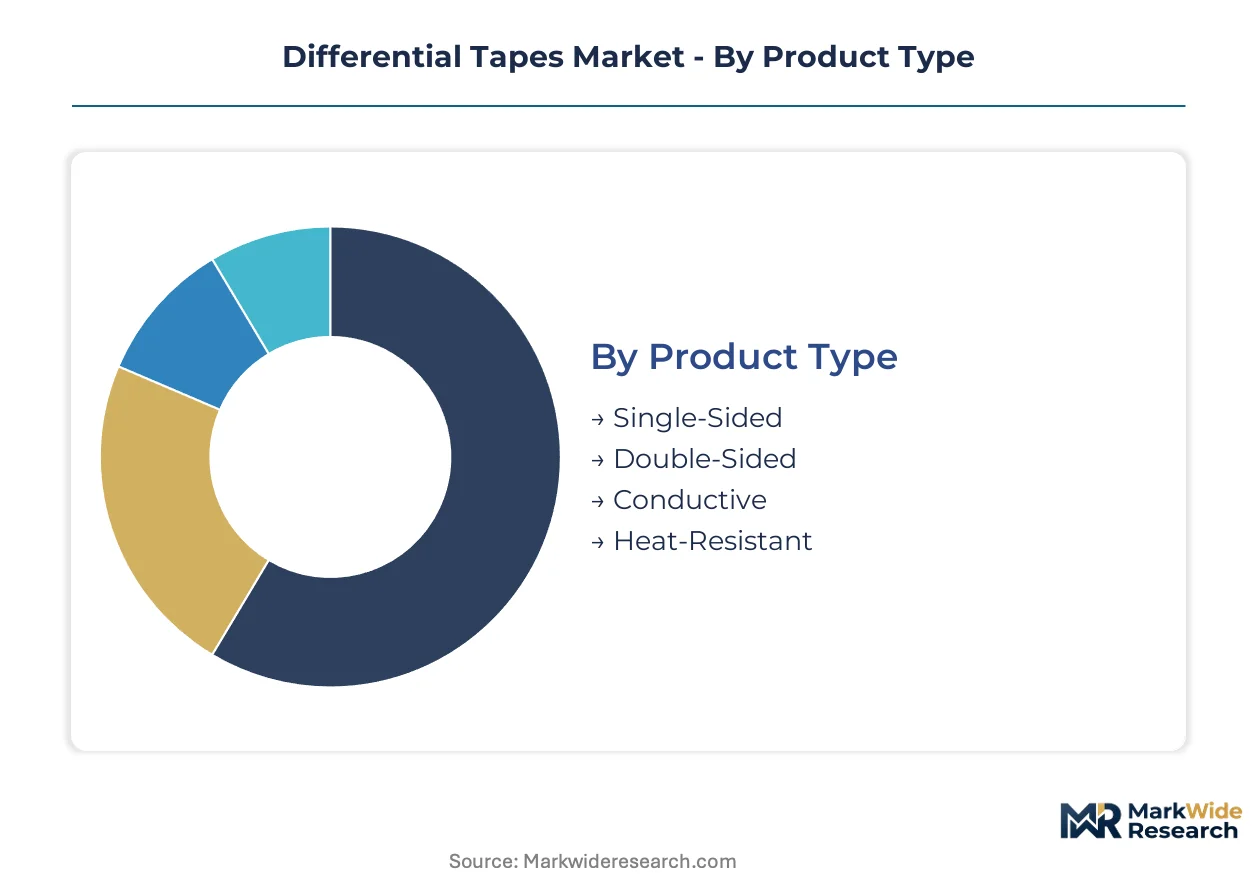
Differential tapes fragment across four intersecting dimensions that dictate specification authority and margin capture. Product type determines coating complexity and capital intensity, while application end-uses concentrate demand in automotive and electronics clusters with divergent qualification timelines.
Product Type:
Coating capacity for solvent-free acrylics concentrates among Japanese and Korean converters, locking specification windows for high-performance constructions.
- Double-Sided:Asymmetric adhesive constructions bond dissimilar substrates—polyester to aluminum, polyimide to foam—with differential peel strength engineered per joint. Demand concentrates in German EV battery module assembly, where dielectric isolation and thermal cycling resistance specifications tightened after OEM engineering teams assumed direct qualification authority from tier suppliers.
- Conductive:Metal-filled adhesive matrices deliver electromagnetic interference shielding with controlled impedance. Bavarian precision electronics clusters in Baden-Württemberg consume sub-50-micron tolerance grades for miniaturized telecommunications hardware, though volumes remain narrow relative to structural bonding segments.
- Single-Sided:One adhesive face with release liner protection serves masking and temporary holding applications in industrial painting operations.
- Heat-Resistant:Silicone-modified acrylics sustain adhesive integrity above 150°C for aerospace engine compartment gasketing and exhaust shielding.
Today's leader: Double-Sided. Tomorrow's challenger: Conductive.
Application:
End-use concentration in automotive and electronics creates divergent procurement patterns—OEM direct specification versus tier-supplier delegation.
- Automotive:Adhesive bonding programs displace mechanical fasteners in Stuttgart and Wolfsburg EV assembly lines, compressing converter sales cycles and fragmenting order volumes. Battery pack integrators now demand lot-level thermal cycling data, displacing historical certificate-of-analysis acceptance.
- Electronics:Miniaturized device assembly in Bavarian automation clusters consumes specialized bonding solutions with sub-50-micron placement tolerance. REACH substance restrictions on diisocyanates force polyurethane converters toward aliphatic epoxy alternatives, extending notified body review queues.
- Construction:Weatherproofing membranes and vapor barrier sealing employ heavy-duty foam carriers with UV-stabilized facestocks.
- Aerospace:Primary structural joints retain bolted connections for traceability, capping tape penetration to secondary sealing and interior panel bonding.
Automotive commands current volume. Electronics shows steepest expansion trajectory as device miniaturization accelerates.
Material:
Raw material selection determines thermal performance ceiling and compliance pathway under evolving chemical content thresholds.
- Polymer:Polyester and polyimide films provide dimensional stability with dielectric strength for electrical isolation applications. ECHA REACH SVHC list expansion accelerates reformulation toward solvent-free acrylics, opening specification windows for converters with qualified UV-cured alternatives.
- Foam:Closed-cell polyethylene and polyurethane carriers absorb shock and fill gap tolerances in automotive trim attachment. EU F-Gas Regulation phase-down schedules reshape blowing agent selection, rewarding early adopters of hydrocarbon-blown alternatives.
- Paper:Saturated kraft facestocks serve cost-sensitive masking and splicing applications with limited durability requirements.
- Aluminum:Foil constructions deliver thermal conductivity and moisture barrier properties for HVAC duct sealing and electronics shielding.
Polymer dominates specification complexity. Foam faces regulatory substitution pressure.
End User:
Customer type segmentation reveals bifurcated procurement—volume contract manufacturing versus fragmented spot purchasing.
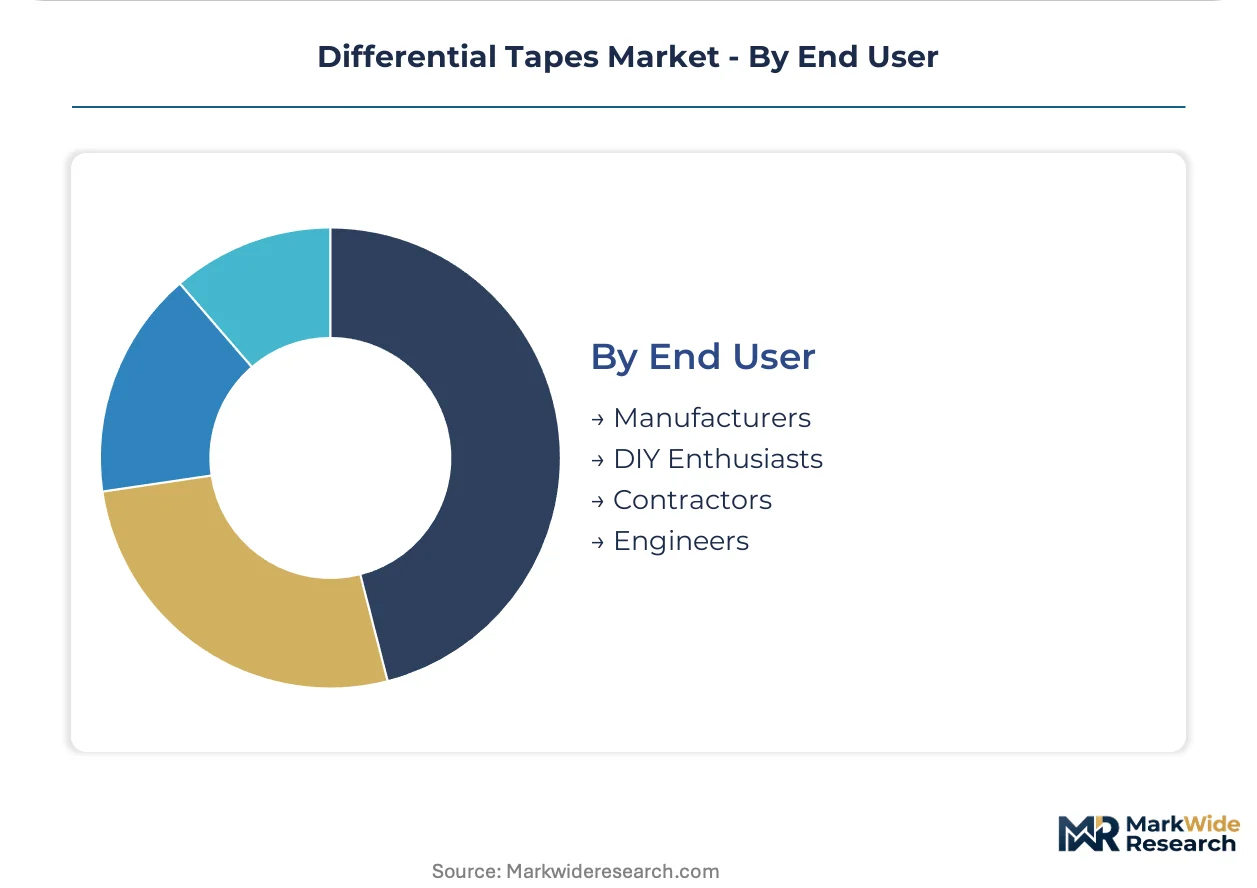
- Manufacturers:Tier-one automotive and electronics OEMs negotiate multi-year supply agreements with embedded price pass-through mechanisms for acrylic monomer volatility. Direct specification authority migration from component suppliers to OEM engineering teams concentrates order consolidation risk.
- Contractors:Construction and MRO channels purchase through distributor networks with 72-hour regional fulfillment expectations, favoring converters with toll manufacturing partnerships that reduce cross-border logistics exposure.
- Engineers:Prototyping and R&D procurement emphasizes specification flexibility and rapid sample turnaround over unit cost minimization.
- DIY Enthusiasts:Retail channel demand concentrates in general-purpose double-sided constructions with consumer-packaged dimensions.
Manufacturers control margin structure. Contractors determine regional fulfillment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision assembly clusters anchor differential tape consumption for miniaturized electronics and automotive bonding applications. Specification authority has migrated from tier suppliers to OEM engineering teams across Stuttgart and Wolfsburg. Regional procurement patterns now demand lot-level thermal cycling data and 72-hour regional fulfillment windows.
Germany
EV battery module assembly in Stuttgart and Wolfsburg consumes dielectric differential tapes with tightening thermal cycling specifications. ECHA REACH authorization requirements for diisocyanates entered full enforcement in August 2023, forcing polyurethane converters toward aliphatic epoxy alternatives. Bavarian automation clusters in Baden-Württemberg specialize in sub-50-micron tolerance tapes for miniaturized electronics.
United States
Automotive adhesive bonding programs in Detroit and Tennessee displace mechanical fasteners in electric vehicle assembly lines. FDA migration limits and EPA volatile organic compound rules constrain solvent-based adhesive formulations in medical and industrial end uses. Minnesota hosts in-house resin synthesis operations that anchor North American acrylic adhesive feedstock security.
China
Electronics-grade differential tape demand concentrates in Shenzhen and Dongguan for mobile device and telecommunications hardware assembly. MIIT standards and GB certification requirements shape material selection for domestic battery manufacturers. Yangtze River Delta clusters consume specialized bonding solutions for 5G infrastructure electromagnetic interference shielding.
Japan
Solvent-free coating capacity concentrates among Japanese converters serving precision electronics and automotive export markets. METI industrial standards govern adhesive performance specifications for domestic OEM qualification programs. Nagoya and Osaka industrial corridors supply high-performance constructions to German and Chinese automotive programs.
India
PLI scheme subsidies for mobile device assembly create procurement windows for tape converters establishing local slitting operations. BIS certification requirements and DGFT import regulations shape material qualification timelines for electronics manufacturers. Karnataka and Tamil Nadu electronics manufacturing clusters drive demand for specialized die-cutting and regional fulfillment capabilities.
Differential Tapes Market Competitive Environment
Global majors compete with regional champions across coating technology and geographic proximity to automotive OEM engineering teams. Market structure tilts toward consolidated capacity among Japanese and Korean electronics-grade specialists, with fragmented regional toll manufacturing serving European automotive qualification requirements. Three archetypes dominate: vertically integrated resin synthesizers with captive polymer supply, solvent-free coating specialists with proprietary equipment, and regional toll manufacturers with cross-border logistics reduction capabilities. Competitive moves center on backward integration into acrylic monomer supply and strategic partnerships with battery pack integrators seeking lot-level traceability.
Within the integrated-resin tier, 3M Company exemplifies North American capacity anchored through in-house operations. Nitto Denko Corporation occupies a position among solvent-free coating specialists with Asian electronics-grade output. Henkel AG & Co. KGaA represents European regional reach through toll manufacturing partnerships that reduce logistics exposure. These three entities illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corporation |
| tesa SE |
| Avery Dennison Corporation |
| Saint-Gobain Performance Plastics |
| Scapa Group plc |
| Intertape Polymer Group |
| Shurtape Technologies |
| Henkel AG & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
REACH authorization requirements for diisocyanates gate both qualified supply and premium-tier pricing access, as converters without ECHA-compliant alternatives face exclusion from German automotive programs while those with qualified aliphatic epoxy formulations command specification premiums.
Pricing Analysis
Input-cost pass-through mechanisms for 2-ethylhexyl acrylate swing gross margins without contract protection, forcing converters toward long-term offtake agreements with embedded monomer price adjustments. Price differentiation centers on REACH SVHC compliance tier and thermal cycling certification grade, with OEM-direct specifications least sensitive and spot-purchasing contractors most vulnerable. Cost compression in standard-grade constructions intensifies as Asian electronics-grade capacity floods commodity segments.
Supply Chain Analysis
Reverse-logistics flows for fluorinated release liners face mounting friction under EU F-Gas Regulation phase-down schedules, accelerating converter qualification of bio-based silicone alternatives. Solvent-free coating capacity concentrates in Japan, South Korea, and Germany, drawing from acrylic monomer feedstocks anchored in Saudi Arabian and U.S. Gulf Coast petrochemical complexes. Single-source vulnerability runs through Japanese electronics-grade specialists serving Bavarian automation clusters. Distribution runs through regional toll manufacturing partnerships that compress cross-border lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German REACH compliance costs run 40% above U.S. EPA thresholds, creating arbitrage windows for converters with dual-qualified formulations serving both regulatory environments.
For Market Incumbents: Acquire solvent-free UV coating assets to defend specification authority as OEM engineering teams compress qualification timelines. Secure captive acrylic monomer supply through backward integration into 2-ethylhexyl acrylate production. Invest in ECHA pre-registration for aliphatic epoxy alternatives before diisocyanate authorization deadlines harden substitution windows. For New Entrants and Emerging Players: UV-curable adhesive platforms offer the most penetrable wedge for battery module assembly qualifications shifting away from solvent-based formulations. Target Indian electronics manufacturing clusters under PLI scheme subsidies where local slitting capacity remains undersupplied. Lead with 72-hour regional fulfillment guarantees rather than price competition. For Investors and Strategic Acquirers: Roll-up economics work for regional toll manufacturers because automotive OEMs fragment order volumes across multiple qualified suppliers. Five-to-ten year viability hinges on converters with existing ECHA registration portfolios. Monitor EU F-Gas Regulation enforcement intensity as the signal for fluorinated release liner substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Captive feedstock security insulates margins from crude-linked volatility at 2-ethylhexyl acrylate plants. |
| Solvent-Free UV Coating Capacity Expansion | Eliminates solvent recovery infrastructure while qualifying for German automotive battery module specifications. |
| ECHA REACH Pre-Registration Investment | Secures market access before SVHC list expansion triggers formulation bans. |
| Regional Toll Manufacturing Partnership | Reduces cross-border logistics exposure for 72-hour fulfillment windows demanded by Stuttgart OEMs. |
| Aliphatic Epoxy Alternative Qualification | Substitutes diisocyanate-based polyurethanes before August 2023 authorization enforcement hardens. |
Study Parameters
Bottom-up automotive and electronics end-use modeling reconciled against top-down coating capacity tracking forms the analytical core. Primary interviews with adhesive formulation chemists, OEM platform engineers, tier-one procurement leads, and toll manufacturing operators combined with secondary validation from ECHA SVHC notifications, EPA VOC rulemaking dockets, SEC 10-K resin segment disclosures, and customs trade flow data. Triangulation across these sources calibrated segment-level volume estimates.
Input-output matrices mapped acrylic monomer consumption to tape coating throughput across product type, application, material, and end-user dimensions over the projection horizon. CAGRs derived from regression analysis of historical qualification cycle compression and OEM direct-specification migration patterns. Industry-specific forecast inputs included EV battery pack production schedules and 5G infrastructure capital expenditure trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance restriction timelines and MIIT standard revisions in China. Practitioners should monitor diisocyanate authorization enforcement intensity and F-Gas Regulation phase-down acceleration for early signals of formulation substitution velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Pipe Marking Tape Market
Tapes
Invisible Tapes Market
Tapes
Tabbing Tapes Market
Tapes
Application Tapes Market
Tapes
Thermal Release Tapes Market
Tapes
Global Electrical Tapes Market
Tapes
Replica Tapes Market
Tapes
Dicing Tapes Market
Tapes
Sealing and Strapping Packaging Tapes Market
Tapes
Tape and Label Adhesives Market
Tapes
Mastic Tapes Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Pouch Tapes Market
Tapes
Global Construction Tape Market
Tapes
Hand Wrappers Market
Tapes
Fine Line Striping Tape Market