
 Replica Tapes Market | 2026-2036
Replica Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Replica Tapes Market Outlook
Aftermarket service revenue for legacy format maintenance is tilting toward specialty refurbishment and archival-grade reconditioning. 3M Company leverages its materials science heritage to dominate high-resolution substrate supply. Shurtape Technologies anchors North American distribution through direct studio relationships. Nitto Denko Corp specializes in precision coating technologies that sustain extended archival lifespans.
Replica tapes are magnetically coated polyester or acetate substrates engineered to exacting surface smoothness specifications, typically measured in nanometer-scale roughness profiles, for faithful analog signal reproduction in professional audio and motion picture applications. The product type dimension shows high-resolution formats commanding premium margins while specialty variants capture fastest growth from niche restoration workflows. Film production end users drive volume demand, though archival storage channels exhibit superior price realization per unit as institutions prioritize longevity over per-foot cost.
EPA regulations on volatile organic compound emissions constrain solvent-based adhesive manufacturing processes in the United States, while REACH chemical registration requirements in Europe elevate compliance costs for imported coated substrates. ISO 18923 archival durability standards shape procurement specifications for institutional buyers across both jurisdictions. Stakeholders must monitor evolving chemical restriction schedules and digitization subsidy programs that could abruptly redirect demand between preservation-grade physical media and digital migration services.
Market Dynamics
The Replica Tapes Market faces intensifying pressure from solvent-free adhesive mandates under the EU Green Deal, forcing reformulation investments while broadcast digitization programs sustain demand for premium archival substrates.
Growth Catalysts
- Heritage Digitization Mandates:German broadcast infrastructure upgrades and film restoration projects are accelerating procurement of high-resolution formats for archival preservation.
- REACH Chemical Registration:Elevated compliance requirements in Europe are filtering out low-grade imports, consolidating demand around certified archival-grade suppliers.
- Acetate Substrate Engineering:Advances in nanometer-scale surface smoothness specifications are expanding addressable applications in professional motion picture workflows.
Market Restraints
- Petrochemical Feedstock Volatility:Polyester base film production depends on purified terephthalic acid supply chains concentrated in East Asian refining clusters.
- Coating Equipment Concentration:Precision magnetic coating lines are concentrated among a limited set of Japanese and German capital equipment suppliers.
- Digital Migration Substitution:Cloud-based digital preservation archives are displacing physical tape procurement for secondary backup tiers in institutional buyers.
Strategic Opportunities
- Restoration Workflow Specialization:Niche film laboratories in Italy and Spain are creating demand for specialty variant formats with extended temperature stability.
- Solvent-Free Adhesive Innovation:EU Green Deal chemical restriction schedules are creating first-mover advantages for manufacturers with water-based coating capabilities.
- Archival Reconditioning Services:Direct studio relationships are enabling aftermarket service revenue through refurbishment and extended-warranty programs.
Industry Challenges
- Magnetic Particle Engineering Talent:Specialized coating chemists with expertise in iron oxide dispersion protocols are scarce across European manufacturing bases.
- ISO 18923 Certification Timelines:Archival durability testing cycles extend 18-24 months, delaying new product introductions and locking in incumbent formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Replica Tapes Market |
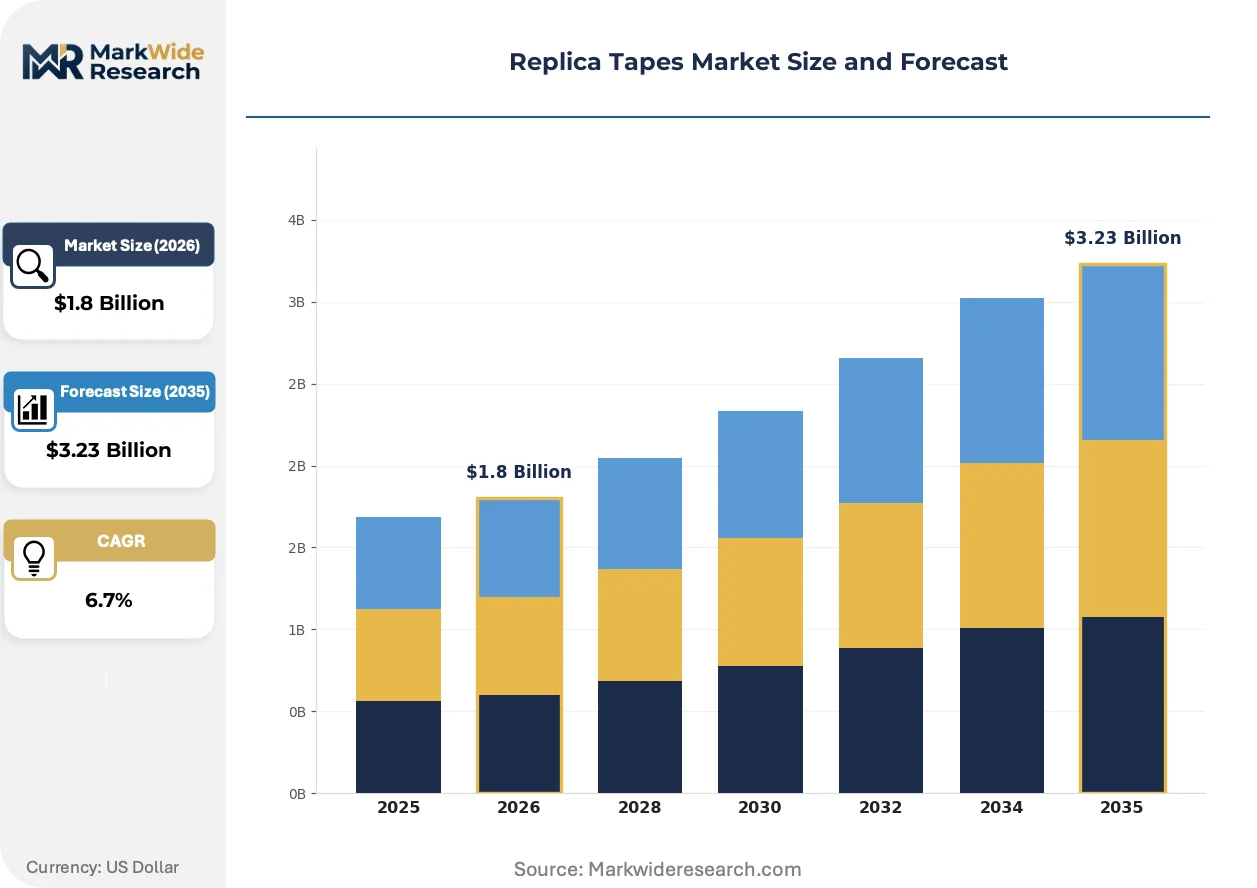
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Resolution, Low-Noise, Standard, Specialty End User: Film Production, Audio Recording, Broadcasting, Archival Storage Application: Sound Engineering, Film Restoration, Document Preservation, Music Distribution Distribution Channel: Online Retailers, Physical Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Shurtape Technologies, Intertape Polymer Group, 3M Company, Saint-Gobain, Scapa Group PLC, Nitto Denko Corp, Berry Global, Advance Tapes International Ltd, Beiersdorf AG (Tesa), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Replica Tapes Market Strategic Shifts
Coating technology convergence with nanomaterials science is compressing product development cycles while regulatory chemistry restrictions are redrawing competitive boundaries. Three developments are restructuring supply-side capabilities.
Ultrafine barium ferrite magnetic particles are enabling higher linear recording densities without substrate thickness increases. Motion picture post-production facilities in Los Angeles and London are adopting these formulations for 4K film mastering workflows at accelerated replacement cycles. The technology is rendering obsolete traditional acicular iron oxide coatings in premium archival segments.
EPA volatile organic compound emission limits are constraining solvent-based adhesive manufacturing processes in the United States. Coating operations in Ohio and California are retrofitting production lines with thermal oxidizer systems or migrating to water-based chemistries. Small-batch heritage restoration suppliers face disproportionate compliance burdens relative to volume manufacturers.
Studio procurement departments are consolidating vendor lists around integrated substrate-coating-service providers. Independent tape distributors in North America are losing shelf space to direct manufacturer relationships with major film production houses. This concentration is most visible in California, where studio technical standards departments now mandate single-source accountability for archival longevity claims.
Replica Tapes Market Segmentation
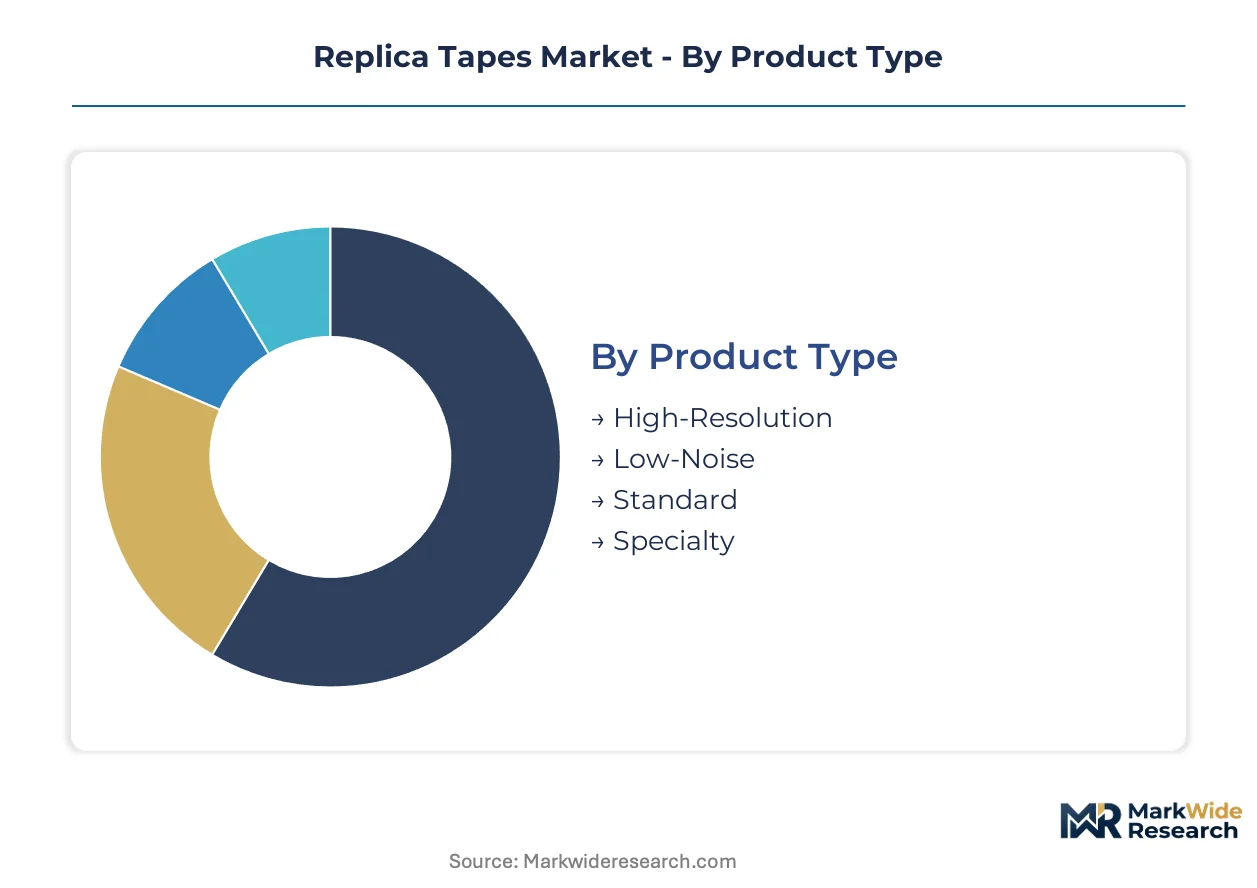
Replica tape manufacturers face divergent technical specifications across professional workflows. Product differentiation maps directly to signal fidelity requirements and archival longevity mandates. Procurement patterns vary sharply between commercial production houses and institutional preservation programs.
Product Type:
Cost tier stratification separates premium archival formulations from commodity studio stock. Each tier commands distinct coating chemistries and substrate engineering investments.
- High-Resolution:Ultrafine barium ferrite magnetic particles enable nanometer-scale surface smoothness specifications for 4K film mastering workflows. German broadcast infrastructure upgrades and heritage digitization programs sustain premium consumption of these formulations despite per-foot cost premiums.
- Low-Noise:Specialized iron oxide dispersions with reduced surface asperity profiles minimize signal dropouts in critical audio recording sessions. Los Angeles post-production facilities specify these substrates for orchestral scoring and dialogue replacement workflows where noise floor specifications are non-negotiable.
- Standard:Acicular iron oxide coatings on polyester base film serve routine production budgets in commercial advertising and television programming.
- Specialty:Extended temperature stability variants address niche restoration workflows in Italian and Spanish film laboratories.
High-Resolution commands the established base. The steepest expansion runs through Specialty variants.
End User:
Customer type determines whether procurement prioritizes per-foot economy or century-scale durability. Institutional buyers accept substantial cost premiums for certified archival performance.
- Film Production:Volume consumption concentrates in California studio technical standards departments. These buyers now mandate single-source accountability for archival longevity claims, consolidating vendor relationships around integrated substrate-coating-service providers.
- Audio Recording:Professional music studios in London and Nashville drive replacement cycles for mastering-grade formulations. Cloud-based digital preservation archives are displacing physical tape procurement for secondary backup tiers in this segment.
- Broadcasting:German public broadcasters anchor demand through infrastructure upgrade programs. REACH chemical registration requirements filter procurement toward certified archival-grade suppliers.
- Archival Storage:Museums and national film archives exhibit superior price realization per unit as longevity specifications override per-foot cost considerations. ISO 18923 certification shapes procurement decisions across European and North American institutions.
Film Production captures the volume base. Archival Storage delivers the margin expansion.
Application:
Application context dictates surface engineering specifications and adhesive chemistry requirements. Each use case imposes distinct environmental stress profiles on coated substrates.
- Sound Engineering:Multi-track recording workflows demand consistent magnetic particle dispersion across extended tape lengths. Ohio and California coating operations supply these specifications under EPA volatile organic compound emission constraints.
- Film Restoration:Heritage laboratories require acetate substrate compatibility with legacy playback equipment. EU Green Deal solvent-free adhesive mandates are pressuring manufacturers toward water-based coating capabilities for this application.
- Document Preservation:Government archives specify polyester base films with enhanced humidity resistance for climate-uncontrolled storage environments.
- Music Distribution:Limited vinyl-complementary releases create intermittent demand for analog mastering stock in boutique pressing operations.
Sound Engineering anchors current procurement volumes. Film Restoration is gaining share fastest as heritage digitization accelerates.
Distribution Channel:
Supply concentration shapes how manufacturers reach end users. Channel selection reflects order scale, technical support requirements, and geographic proximity to coating operations.
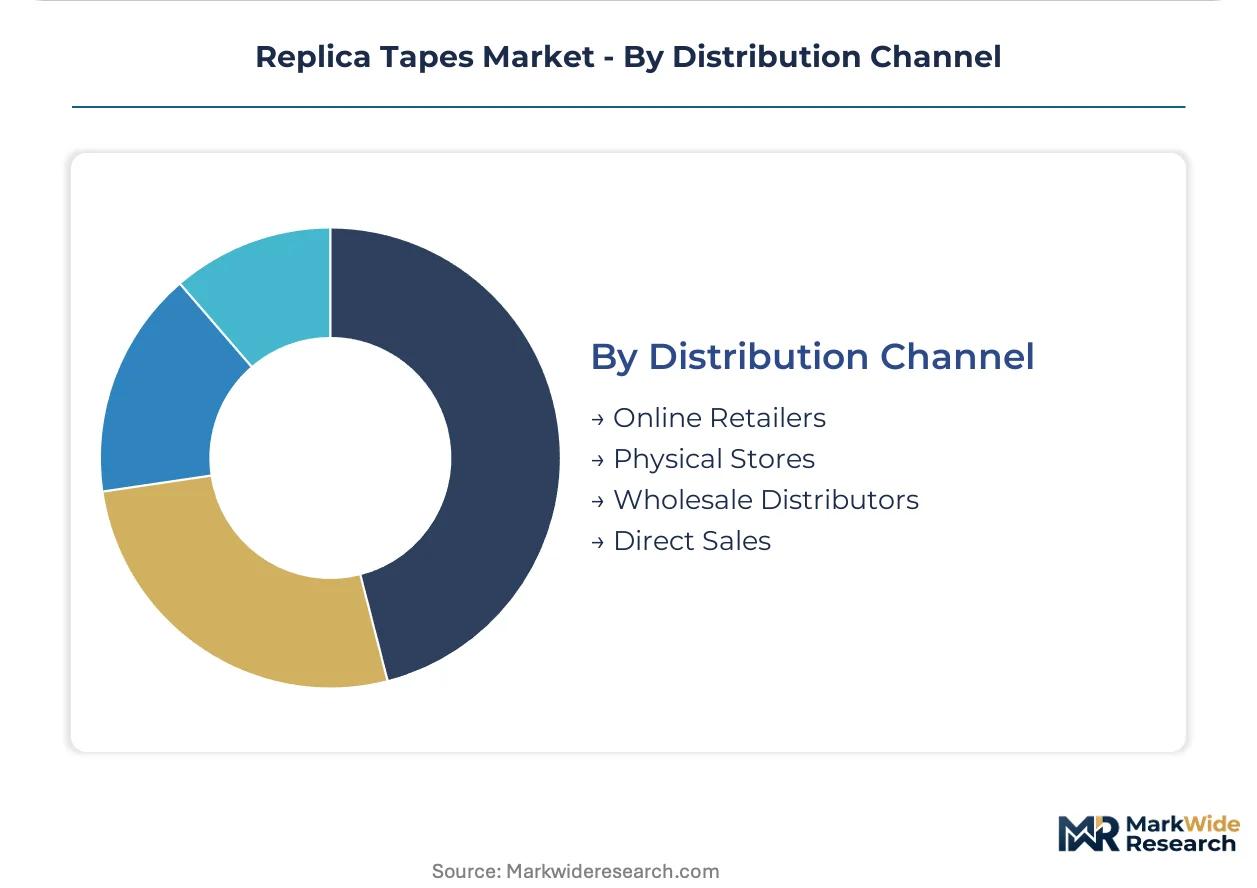
- Online Retailers:Small-batch heritage restoration suppliers and independent studios source specialty formats through digital procurement platforms. These buyers face disproportionate compliance burdens relative to volume manufacturers under evolving chemical restriction schedules.
- Physical Stores:Regional audio-visual equipment dealers in Los Angeles and London maintain inventory for immediate production needs. Proximity to post-production clusters determines store viability.
- Wholesale Distributors:Independent tape distributors in North America are losing shelf space to direct manufacturer relationships as studio procurement departments consolidate vendor lists.
- Direct Sales:Major film production houses now mandate single-source accountability through captive supply arrangements with coating manufacturers. Shurtape Technologies anchors this channel through direct studio relationships.
Wholesale Distributors retain the legacy volume position. Direct Sales is climbing the fastest as studio consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Institutional buyers in Germany absorb substantial per-foot premiums for certified archival longevity, while commercial studios in the United States prioritize per-unit economy in high-volume production workflows.
Germany
Public broadcaster infrastructure upgrades and heritage film digitization programs sustain premium consumption of high-resolution formats. EU Green Deal chemical substance restrictions under REACH registration requirements filter procurement toward certified archival-grade suppliers with solvent-free coating capabilities. Berlin and Munich host concentrated restoration laboratory clusters where extended-temperature stability variants command fastest adoption.
United States
California studio technical standards departments drive volume demand through consolidated vendor relationships and single-source accountability mandates. EPA volatile organic compound emission limits constrain solvent-based adhesive manufacturing processes, forcing Ohio and California coating operations toward thermal oxidizer retrofits or water-based chemistry migrations. Los Angeles post-production facilities anchor 4K film mastering workflows with accelerated replacement cycles for ultrafine barium ferrite formulations.
Japan
Precision magnetic coating equipment suppliers and iron oxide dispersion protocol specialists concentrate technical expertise in Kanto and Kansai industrial corridors. METI industrial standards shape domestic procurement specifications for archival durability testing cycles. Tokyo-based capital equipment manufacturers supply precision coating lines to European and North American tape producers under technology licensing arrangements.
United Kingdom
London post-production clusters specify low-noise formulations for orchestral scoring and dialogue replacement workflows where noise floor specifications are non-negotiable. REACH chemical registration requirements elevate compliance costs for imported coated substrates, consolidating demand around established suppliers with EU certification. British film archives participate in cross-border heritage digitization initiatives with German and French institutions.
Italy
Niche film laboratories in Rome and Milan create specialized demand for acetate substrate compatibility with legacy playback equipment. EU Green Deal solvent-free adhesive mandates pressure manufacturers toward water-based coating capabilities for restoration-specific applications. Italian heritage restoration suppliers face disproportionate compliance burdens relative to volume manufacturers under evolving chemical restriction schedules.
Replica Tapes Market Competitive Environment
Capability concentration sits with coating technology specialists; scale advantage sits with integrated materials conglomerates. The vendor base separates into distinct tiers based on substrate engineering depth versus distribution breadth. Three strategic archetypes dominate: precision coating specialists with archival certification expertise, diversified adhesive manufacturers leveraging materials science heritage, and regional distributors anchoring direct studio relationships. Competitive moves center on coating chemistry reformulation investments and captive supply arrangements with major production houses.
Among diversified materials science conglomerates, 3M Company exemplifies the capability-driven archetype through its substrate engineering heritage. Shurtape Technologies occupies a position within the direct-relationship tier, anchoring North American studio supply chains. Nitto Denko Corp represents the precision-specialist archetype, with Japanese coating technology expertise concentrated in extended archival lifespan applications.
| Leading Market Players |
|---|
| Shurtape Technologies |
| Intertape Polymer Group |
| 3M Company |
| Saint-Gobain |
| Scapa Group PLC |
| Nitto Denko Corp |
| Berry Global |
| Advance Tapes International Ltd |
| Beiersdorf AG (Tesa) |
| Others |
Value Chain & Pricing Dynamics
Kanto industrial corridor coating equipment manufacturers command disproportionate leverage over downstream tape pricing through precision line scarcity and technology licensing arrangements. Their capacity allocation decisions ripple directly into substrate cost structures for European and North American converters serving archival storage and film production buyers.
Pricing Analysis
Aftermarket refurbishment and extended-warranty service contracts generate lifetime value multiples exceeding initial substrate sales. Three-tier pricing structure across premium archival, standard production, and economy broadcast tiers separates ISO 18923-certified formulations from uncertified studio stock. Cost compression in the standard tier intensifies as cloud-based digital archives displace physical procurement for secondary backup workflows. Film production studios in California exhibit lowest price sensitivity, accepting substantial per-foot premiums for single-source accountability mandates.
Supply Chain Analysis
Tokyo-based capital equipment manufacturers and Kansai precision coating specialists hold concentrated contract-manufacturing capacity for magnetic particle dispersion lines. Raw material flows draw from German purified terephthalic acid refiners, Japanese iron oxide pigment specialists, and Belgian adhesive resin suppliers. Single-source vulnerability concentrates in precision coating equipment where replacement timelines extend 18-24 months. Distribution runs through direct manufacturer relationships with major film production houses, bypassing traditional wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities multiply as heritage digitization mandates splinter demand across specialty restoration workflows, solvent-free adhesive reformulations, and archival reconditioning services. Niche technical requirements create defensible pockets for specialists unburdened by volume-manufacturing scale constraints.
For Market Incumbents: Harden archival certification moats through accelerated ISO 18923 testing investments and captive supply arrangements with German public broadcasters. Vertical integration into acetate substrate engineering insulates against East Asian petrochemical feedstock volatility. Shurtape Technologies demonstrates channel control leverage through direct studio relationships that independent distributors cannot replicate. For New Entrants and Emerging Players: Build out water-based coating capabilities to capture EU Green Deal first-mover advantages as REACH chemical restrictions filter out solvent-dependent competitors. Italian and Spanish film restoration laboratories represent the most penetrable segment, with extended-temperature stability variants commanding premium realization absent from commoditized studio stock. Technical partnership routes with heritage digitization program contractors bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision coating specialists with magnetic particle engineering talent and archival durability certification expertise. Long-term viability hinges on digitization subsidy program durability and physical preservation mandate persistence. Watch for abrupt demand redirection between preservation-grade media and digital migration services as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Adhesive Reformulation | EU Green Deal REACH compliance creates first-mover licensing advantages for water-based coating patent holders. |
| Heritage Digitization Partnership | German public broadcaster infrastructure upgrades anchor multi-year offtake commitments for high-resolution formats. |
| Precision Coating Equipment Acquisition | Tokyo capital equipment manufacturers supply scarce magnetic dispersion lines under exclusive technology licensing. |
| Archival Reconditioning Service Launch | Aftermarket refurbishment extends customer lifetime value beyond substrate replacement cycles for institutional buyers. |
| Direct Studio Relationship Consolidation | California technical standards departments mandate single-source accountability, eliminating independent distributor intermediaries. |
Study Parameters
Desk research of SEC 10-K filings, customs trade databases, and ISO archival standards documentation preceded structured interviews with magnetic coating chemists, film laboratory technical directors, and broadcast procurement officers. Primary fieldwork with German heritage digitization program administrators and California studio technical standards departments was cross-validated against ECHA REACH registration databases and EPA emission compliance records. Bottom-up volume estimates from coating line capacity utilization were triangulated against top-down heritage preservation budget allocations.
Assumptions around EU Green Deal chemical restriction implementation timelines, digitization subsidy program continuity, and polyester base film feedstock cost trajectories were held fixed across the projection horizon. Segmentation modeling incorporated product type tiers, end-user procurement patterns, application environmental stress profiles, and distribution channel concentration. CAGRs were derived from archival storage institution budget growth rates and commercial production house replacement cycle compression.
Stress conditions across REACH registration fee escalations, purified terephthalic acid supply disruptions, and cloud-based digital archive substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of German public broadcaster procurement announcements and EPA solvent emission enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Strapping Tapes Market
Tapes
Freezer Tape Market
Tapes
United States End-Of-Line Packaging Tape Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Custom Printed Tape Market
Tapes
Acoustic Tape Market
Tapes
Spacer Tapes Market
Tapes
Seam Tapes Market
Tapes
Tabletop Tape Dispensers Market
Tapes
Gaffers Tape Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Shipping Tapes Market
Tapes
UV Tapes Market
Tapes
Tissue Tapes Market
Tapes
Automotive Tapes Market
Tapes
Flocking Tape Market