
 Tablet Bottle Market | 2026-2036
Tablet Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Tablet Bottle Market Analytics
REACH compliance is decoupling low-cost Asian suppliers from European pharmaceutical clients. Gerresheimer AG leverages its German glassmaking heritage to sustain premium positioning in compliance-heavy markets. Berry Global competes through scale-driven plastic bottle operations across North American nutraceutical channels. Silgan Holdings anchors its position via in-house resin and closure manufacturing that insulates margin pools from raw material volatility.
Tablet bottles are rigid primary containers engineered from HDPE, PET, or borosilicate glass with neck finishes standardized to ISO 8362, designed to protect solid oral dosage forms from moisture ingress and light degradation. Plastic dominates volume due to cost efficiency and child-resistant closure compatibility, while glass retains preference for moisture-sensitive formulations where inert contact surfaces matter. The pharmaceuticals end user segment leads absolute demand but nutraceuticals generates faster growth as supplement brands pursue differentiated shelf presence. Tamper-evident closures command margin premiums over standard screw caps as liability exposure drives brand owner specification upgrades.
The FDA enforces 21 CFR Part 211 cGMP requirements that dictate container closure system validation for all domestic drug packaging. EMA's Annex 1 revision tightens particulate and bioburden standards that push European buyers toward certified cleanroom manufacturing partners. India's CDSCO aligns with WHO prequalification norms that enable export-oriented tablet bottle suppliers to serve regulated markets. Stakeholders must weigh compliance investment against volume concentration in emerging supply bases where regulatory convergence remains incomplete.
Market Dynamics
Serialized track-and-trace mandates are forcing pharmaceutical contract manufacturers to requalify their entire packaging supply chains, concentrating procurement power among suppliers capable of integrated coding, aggregation, and verification systems.
Growth Catalysts
- WHO Prequalification Alignment:India's CDSCO adoption of WHO norms enables domestic tablet bottle suppliers to access regulated export markets without redundant certification cycles.
- Nutraceutical Shelf Differentiation:Supplement brands specify custom neck finishes and opaque colorants to secure retail visibility, pulling HDPE and PET bottle volumes beyond pharmaceutical baselines.
- Child-Resistant Closure Mandates:Poison Prevention Packaging Act requirements in the US drive specification upgrades across over-the-counter and prescription solid-dosage categories.
Market Restraints
- REACH Compliance Cost Escalation:ECHA substance-of-very-high-concern listings force reformulation of plasticizers and stabilizers used in pharmaceutical-grade HDPE, compressing margins for non-European suppliers.
- Glass Supply Concentration:Borosilicate pharmaceutical tubing production clusters in Germany and India, creating vulnerability to energy-cost shocks and logistics disruption.
- Resin Price Volatility:Ethylene and propylene feedstock exposure in PET and HDPE bottles transfers crude-oil indexation directly to converter cost structures.
Strategic Opportunities
- Biopharma Cold-Chain Extension:Lyophilized tablet and orally disintegrating formats require moisture-barrier packaging with desiccant integration, opening premium-price segments beyond conventional bottles.
- Direct-to-Patient Pharmacy Channels:Mail-order and subscription supplement distribution favors lightweight, shatter-resistant PET configurations over glass for last-mile durability.
- EU Green Deal Packaging Rules:Recycled-content mandates and extended-producer-responsibility frameworks reward converters with certified post-consumer resin streams and closed-loop collection infrastructure.
Industry Challenges
- Serialization Integration Complexity:Line-speed matching between blow-molding, labeling, and aggregation stations requires capex-heavy retrofitting of legacy filling equipment.
- Cleanroom Certification Backlogs:EMA Annex 1 revision tightens particulate limits, extending audit timelines for contract manufacturers seeking ISO 14644-1 Class 7 or 8 qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablet Bottle Market |
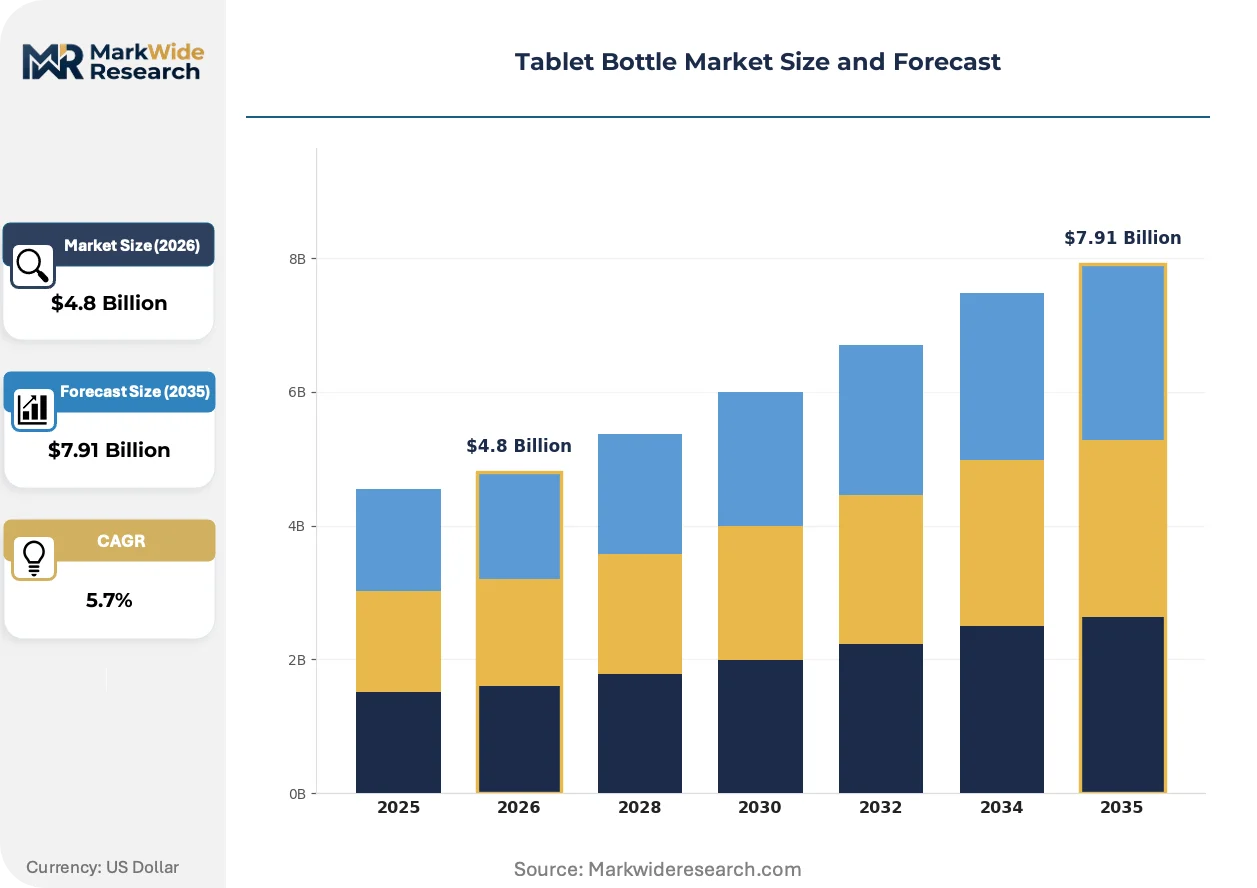
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Bio-based End User: Pharmaceuticals, Nutraceuticals, Cosmetics, Food Industry Capacity: 30ml, 60ml, 100ml, 200ml Closure Type: Screw Cap, Flip Top, Push Down, Tamper Evident |
| Companies Covered | Gerresheimer AG, Berlin Packaging, Amcor plc, Berry Global, Inc., AptarGroup, Inc., Stoelzle Glass Group, Kaufman Container, Silgan Holdings Inc., WestRock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablet Bottle Market Evolving Landscape
Active and intelligent packaging functionalities are migrating from premium biologics into mainstream oral solid dosage formats, rewiring supplier R&D priorities and buyer specification templates.
Multilayer co-extruded barrier bottles are expanding into moisture-sensitive generic portfolios previously reserved for glass or aluminum blister alternatives. Indian and Chinese contract manufacturers now specify ethylene vinyl alcohol copolymer intermediate layers for hygroscopic statins and antihypertensives. This expansion is compressing the traditional glass-or-plastic material selection logic into a more nuanced performance-based procurement calculus.
EMA's Annex 1 revision on sterile manufacturing has tightened particulate and bioburden standards for primary packaging supplied to European fill-finish operations. Cleanroom manufacturing partnerships now dominate supplier qualification workflows, disqualifying converters without ISO 14644-1 certified environments. Oral solid dosage packaging for EU export markets is consolidating toward a narrower base of certified cleanroom operators in Germany, Switzerland, and selected Indian clusters.
Brand-owner buying committees now integrate sustainability scorecards into packaging RFPs alongside unit-cost and lead-time metrics. Nutraceutical marketers in North American and Western European channels specify post-consumer recycled content thresholds and carbon-footprint disclosures as gate criteria. Supplier selection in these geographies increasingly hinges on verified life-cycle-assessment documentation rather than purely technical compliance.
Tablet Bottle Market Segmentation
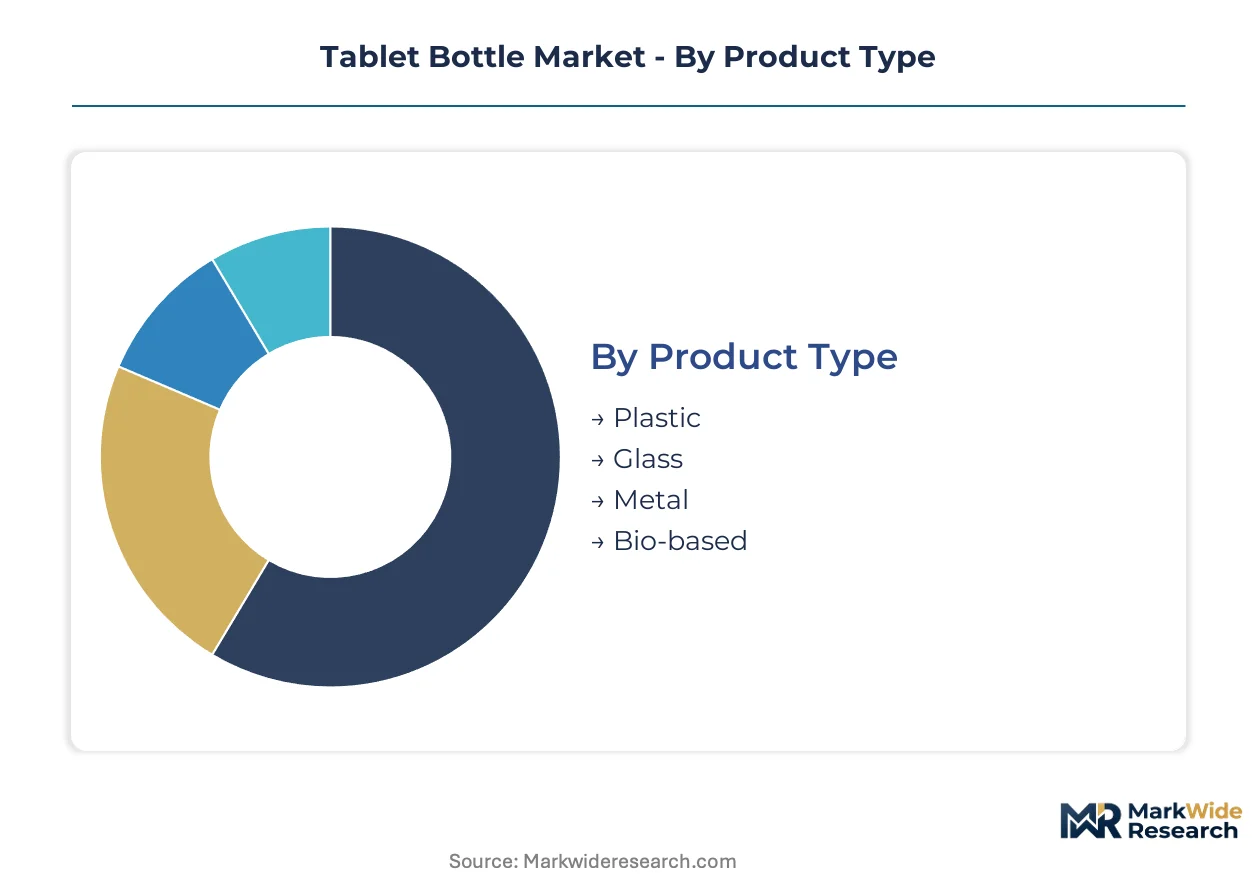
Tablet bottle procurement decisions hinge on material-performance tradeoffs, regulatory compliance burdens, and end-use shelf-life requirements. Buyers segment supply bases across four intersecting dimensions that determine unit economics, qualification timelines, and geographic sourcing feasibility.
Product Type:
Material selection governs barrier performance, serialization compatibility, and compliance pathway costs across pharmaceutical and nutraceutical channels.
- Plastic:HDPE and PET dominate volume through blow-molding efficiency and child-resistant closure compatibility. Indian generic manufacturers concentrate procurement here for cost-sensitive export portfolios serving WHO-prequalified markets.
- Glass:Borosilicate tubing delivers inert contact surfaces for moisture-sensitive formulations. German and Indian tubing clusters supply European fill-finish operations facing EMA Annex 1 particulate limits.
- Metal:Aluminum bottles serve niche effervescent and hygroscopic tablet formats requiring absolute light and moisture exclusion. Limited adoption outside premium pharmaceutical lines.
- Bio-based:PLA and bio-PET variants attract nutraceutical brands targeting EU Green Deal recycled-content mandates. Supply remains constrained by certification backlogs and performance gaps against conventional resins.
Plastic leads on scale; bio-based leads on momentum.
End User:
Demand concentration varies sharply across customer types, with regulatory intensity and specification flexibility diverging between life-science and consumer-product buyers.
- Pharmaceuticals:Solid oral dosage manufacturers enforce ISO 8362 neck-finish standards and serialized track-and-trace integration. FDA 21 CFR Part 211 cGMP requirements dominate North American procurement specifications.
- Nutraceuticals:Supplement brands prioritize shelf differentiation through custom colorants and opaque barriers. Direct-to-patient subscription channels favor lightweight PET configurations for last-mile durability.
- Cosmetics:Tablet-format beauty supplements drive demand for premium aesthetic finishes and travel-size capacities. Specification discipline lags pharmaceutical tiers.
- Food Industry:Functional food tablets and mints require food-grade resin certifications with lower barrier performance thresholds. Price sensitivity exceeds pharmaceutical baselines significantly.
Pharmaceuticals anchor absolute volume; nutraceuticals climb the fastest.
Capacity:
Volume segmentation aligns with dosing regimen duration, retail channel format, and patient compliance packaging trends.
- 30ml:Compact trial sizes and travel retail formats. Nutraceutical subscription services specify this capacity for sample-to-full-size conversion funnels.
- 60ml:Standard one-month prescription supply for chronic medications. Indian CDSCO-aligned exporters target this segment for regulated market entry.
- 100ml:Extended-supply formats for mail-order pharmacy and 90-day prescription fills. Serialized aggregation complexity increases at this scale.
- 200ml:Institutional and hospital dispensing formats. Bulk packaging economics compete against blister alternatives for high-volume generic portfolios.
60ml commands procurement concentration; 100ml gains share fastest in mail-order channels.
Closure Type:
Closure selection determines child-resistance certification, tamper evidence, and line-speed compatibility in contract manufacturing environments.
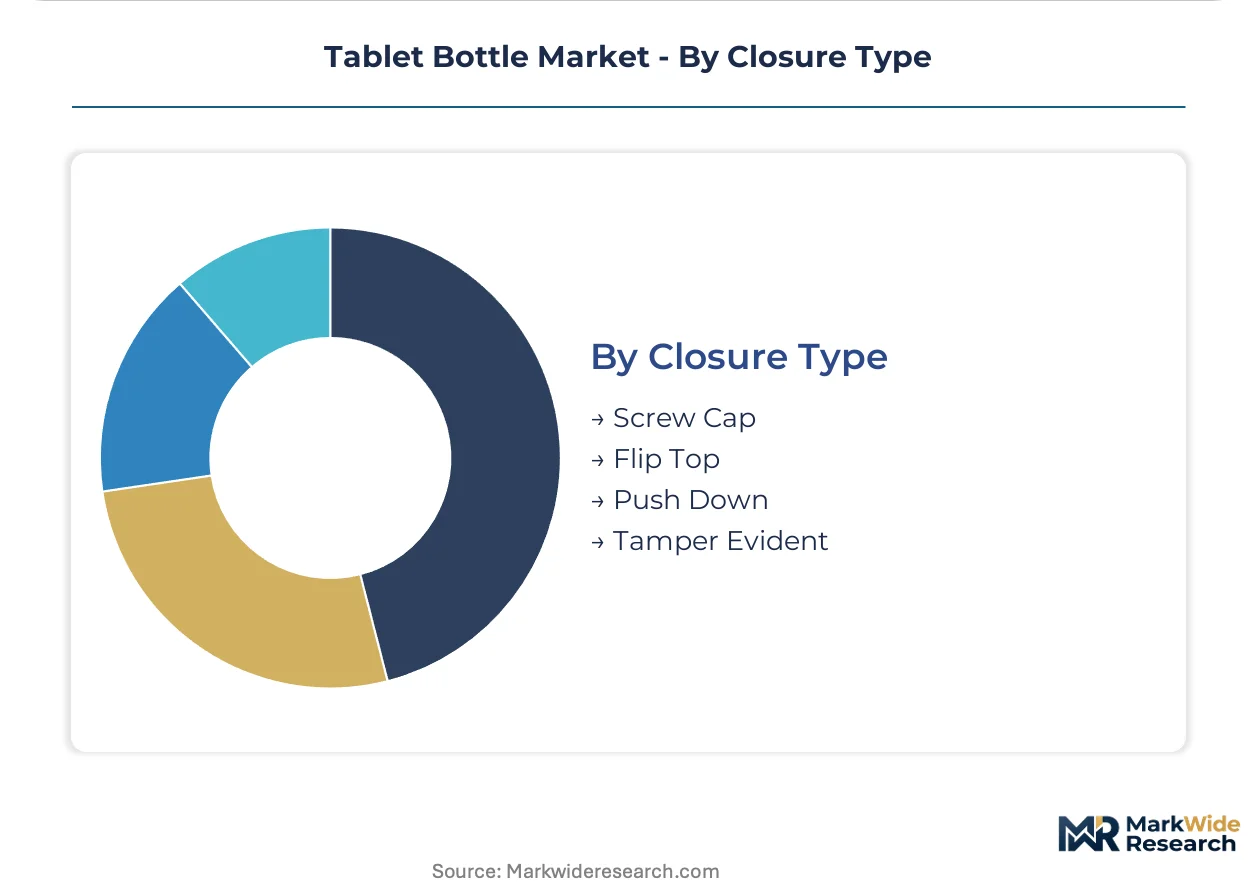
- Screw Cap:Baseline configuration for non-prescription and low-risk categories. Cost efficiency sustains volume in emerging market supply chains.
- Flip Top:Convenience-driven adoption in nutraceutical and food applications. Elder-accessible designs expand addressable patient demographics.
- Push Down:Poison Prevention Packaging Act compliance for US prescription and over-the-counter categories. Child-resistant certification adds qualification overhead.
- Tamper Evident:Ring-break and shrink-band variants command margin premiums. Liability exposure drives brand-owner specification upgrades across all regulated end uses.
Screw cap leads on unit volume; tamper evident leads on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and pharmaceutical manufacturing specialists cluster in Germany, India, and the United States, anchoring the industry's geographic talent base and driving regional specialization in compliance-heavy production environments.
United States
Contract pharmaceutical manufacturers in New Jersey and North Carolina drive demand for serialized track-and-trace compatible bottles. FDA 21 CFR Part 211 cGMP requirements enforce container closure system validation standards across domestic packaging procurement. The Research Triangle Park cluster concentrates blow-molding operations serving mail-order pharmacy channels.
Germany
Borosilicate glass tubing production for moisture-sensitive formulations centers on Bavarian and Hessian manufacturing corridors. EMA Annex 1 revision tightens particulate limits, pushing European buyers toward ISO 14644-1 certified cleanroom partners. Gerresheimer AG leverages its German glassmaking heritage to sustain premium positioning in REACH-regulated markets.
India
Domestic generic drug output and government-backed PLI scheme incentives draw fresh packaging investment to Gujarat and Maharashtra. CDSCO alignment with WHO prequalification norms enables export-oriented suppliers to serve regulated markets without redundant certification cycles. Hyderabad and Ahmedabad clusters specialize in HDPE bottle production for cost-sensitive WHO-prequalified portfolios.
Switzerland
Specialty pharmaceutical fill-finish operations in Basel and Zurich demand high-barrier packaging for hygroscopic formulations. Swissmedic regulations align with EMA standards, requiring certified cleanroom manufacturing partnerships for primary packaging supply. The Basel pharmaceutical corridor concentrates procurement power among converters with integrated serialization capabilities.
China
Domestic pharmaceutical contract manufacturing expansion in Jiangsu and Zhejiang provinces drives PET and HDPE bottle volume growth. NMPA serialization mandates tighten packaging supply chain qualification requirements for export-oriented producers. The Yangtze River Delta cluster integrates blow-molding operations with active pharmaceutical ingredient manufacturing hubs.
Tablet Bottle Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated material-converter hybrids controlling resin and closure production, compliance-focused specialists certifying cleanroom environments for European export markets, and scale-driven plastic converters serving high-volume nutraceutical channels. Competitive moves concentrate on backward integration into resin supply and strategic partnerships with contract manufacturers seeking single-source packaging solutions.
Among Germany-based specialists, Gerresheimer AG and Stoelzle Glass Group exemplify the compliance-focused archetype serving EMA-regulated European markets. Silgan Holdings occupies a position within the integrated material-converter tier through captive resin and closure manufacturing. Berry Global represents scale-driven plastic operations across North American nutraceutical distribution channels.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Berlin Packaging |
| Amcor plc |
| Berry Global, Inc. |
| AptarGroup, Inc. |
| Stoelzle Glass Group |
| Kaufman Container |
| Silgan Holdings Inc. |
| WestRock |
| Others |
Value Network & Pricing Analysis
Ethylene and propylene price indices cascade directly through HDPE and PET converter cost structures, stratifying tablet bottle procurement into three performance tiers that align with certification burden and geographic sourcing risk. Buyers in REACH-regulated European markets absorb premium pricing for EMA Annex 1 compliant cleanroom production, while Indian CDSCO-aligned suppliers compete on cost efficiency for WHO-prequalified export volumes.
Pricing Analysis
Bundled serialization and aggregation services command substantial premiums over unbundled bottle-only supply, with integrated track-and-trace qualification adding significant cost layers to European and North American procurement. Three-tier pricing structure separates EMA-certified cleanroom glass from FDA-validated plastic configurations and cost-optimized Indian HDPE for emerging markets. Pricing pressure stems from REACH compliance cost escalation forcing reformulation of plasticizers and stabilizers, compressing margins for non-European resin converters. Nutraceutical subscription channels exhibit highest price sensitivity due to direct-to-patient last-mile economics, while Swiss biopharma fill-finish operations show lowest sensitivity given hygroscopic formulation requirements.
Supply Chain Analysis
Dual-sourcing requirements from major pharmaceutical contract manufacturers mandate multi-supplier qualification across at least two geographic clusters, preventing single-source dependency even at qualification cost. Supply concentrates in Germany for borosilicate glass tubing, India for HDPE blow-molding, and China for PET resin and conversion equipment. Raw material dependencies center on ethylene and propylene feedstocks, pharmaceutical-grade colorants, and desiccant integration components. Single-source vulnerability in German glass tubing production creates exposure to energy-cost shocks and logistics disruption. Distribution runs through contract manufacturing organizations and direct procurement by generic drug manufacturers, with serialization-capable suppliers capturing consolidated volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-regulated European production with compliance premiums and Indian CDSCO-aligned supply benefiting from government PLI scheme incentives and WHO prequalification access.
For Market Incumbents: Lock in serialization-integrated supply partnerships with top-tier contract manufacturers before EMA Annex 1 revision deadlines harden qualification backlogs. Defensive consolidation through backward integration into resin compounding insulates margin pools from ethylene price volatility, while certification investment in ISO 14644-1 cleanroom expansion captures European export volumes fleeing non-compliant Asian suppliers.
For New Entrants and Emerging Players: Regional Indian generic manufacturers with PLI scheme backing represent the most penetrable buyer archetype for cost-optimized HDPE bottle supply. White-space targets include bio-based PLA variants for EU Green Deal compliance and lightweight PET configurations for North American nutraceutical subscription channels. Go-to-market positioning as WHO-prequalified serialization partners enables regulated market access without redundant certification cycles.
For Investors and Strategic Acquirers: Asymmetric upside sits with compliance-focused specialists certifying cleanroom environments for European export markets, given EMA Annex 1 revision tailwinds and consolidation pressure on uncertified converters. Long-term viability over the next decade hinges on serialization integration capabilities and post-consumer resin certification infrastructure. The signal to watch is CDSCO enforcement tightening on domestic Indian suppliers, which would accelerate qualification demand for export-oriented cleanroom operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive HDPE supply insulates margin pools from ethylene price volatility indexed to crude oil benchmarks. |
| Cleanroom Certification Expansion | ISO 14644-1 Class 7 qualification unlocks EMA-regulated European fill-finish procurement volumes. |
| Serialization Partnership Development | Integrated track-and-trace capabilities meet FDA 21 CFR Part 211 mandates for contract manufacturers. |
| Post-Consumer Resin Certification | Verified PCR streams satisfy EU Green Deal recycled-content thresholds for nutraceutical RFPs. |
| Desiccant Integration Capability | Moisture-barrier packaging with active protection commands premium pricing for lyophilized tablet formats. |
Research Methodology
Multiple input streams — primary interviews with packaging procurement directors, regulatory affairs leads at contract manufacturers, and blow-molding operations managers; secondary validation through FDA 483 inspection databases, EMA GMP certification registries, and Indian CDSCO manufacturing facility listings; plus customs trade data on pharmaceutical packaging imports — were reconciled through bottom-up volume triangulation against top-down market sizing. Primary fieldwork captured specification trends across German glass tubing converters, Indian HDPE specialists in Gujarat and Maharashtra, and North American nutraceutical packaging distributors.
Data-stream reconciliation applied across the modeling period linked material-grade segmentation by barrier performance, capacity-tier distribution aligned with prescription duration norms, and closure-type procurement patterns to derive volume and value trajectories. Segmentation dimensions modeled included material type, end-user regulatory intensity, geographic compliance cluster, and serialization integration level. CAGRs were computed from annualized growth rates applied to base-year estimates, with forecast inputs incorporating REACH substance restriction timelines and PLI scheme incentive phase-outs.
Underlying measurement precision varies by segment; EMA-certified cleanroom glass and FDA-validated plastic configurations carry tighter precision than emerging bio-based variants where certification backlogs create data gaps. Forecasts reflect documented assumptions on regulatory convergence pace and resin price index trajectories. Deviation in CDSCO enforcement tightening or ethylene feedstock supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
Polymer Vials Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Vaccine Packaging Market