
 Custom Printed Tape Market | 2026-2036
Custom Printed Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Printed Tape Market Outlook
Asset-light leasing models for flexographic printing equipment are narrowing the capital barrier for mid-size tape converters. 3M Company leverages captive resin supply to sustain margin control across polypropylene substrates. Avery Dennison Corporation anchors its position through digital printing integration that shortens order cycles for e-commerce clients. Intertape Polymer Group competes on geographic density of its North American distribution footprint.
Custom printed tape comprises pressure-sensitive adhesive substrates—typically polypropylene, PVC, or paper backing between 25–50 microns—bearing logos, barcodes, handling instructions, or decorative motifs via flexographic, digital, gravure, or offset processes; its primary function is brand communication combined with carton sealing security in transit. Packaging tape occupies the dominant volume position due to omnichannel fulfillment expansion, while biodegradable materials represent the fastest-growing margin pool as sustainability procurement criteria harden across European retail chains. Digital printing technology is displacing gravure for short-run customized orders by eliminating plate costs and enabling variable-data graphics.
REACH compliance in Europe governs adhesive chemical composition, while FDA indirect food-contact rules shape tape selection for packaged goods distribution in the United States. The EU Packaging and Packaging Waste Regulation is forcing converters to document recyclability pathways, redirecting R&D spend toward biodegradable and paper-based formulations. Stakeholders must decide whether to absorb compliance costs or pass them through in a market where procurement teams increasingly weight total cost of ownership against unit price.
Market Dynamics
Digital printing adoption is compressing order minimums and collapsing lead times, forcing converters to rebuild workflows around variable-data production rather than static plate-based runs.
Growth Catalysts
- E-commerce fulfillment expansion:Third-party logistics operators in Germany's industrial corridor are mandating branded sealing tape for outbound parcel identity, pulling volume from generic alternatives.
- REACH chemical compliance:Adhesive reformulation to eliminate restricted phthalates and heavy metals is opening premium positioning for certified converters serving European retail chains.
- Biodegradable substrate R&D:Paper backing and plant-derived adhesives are capturing sustainability procurement tenders previously closed to petroleum-based tapes.
Market Restraints
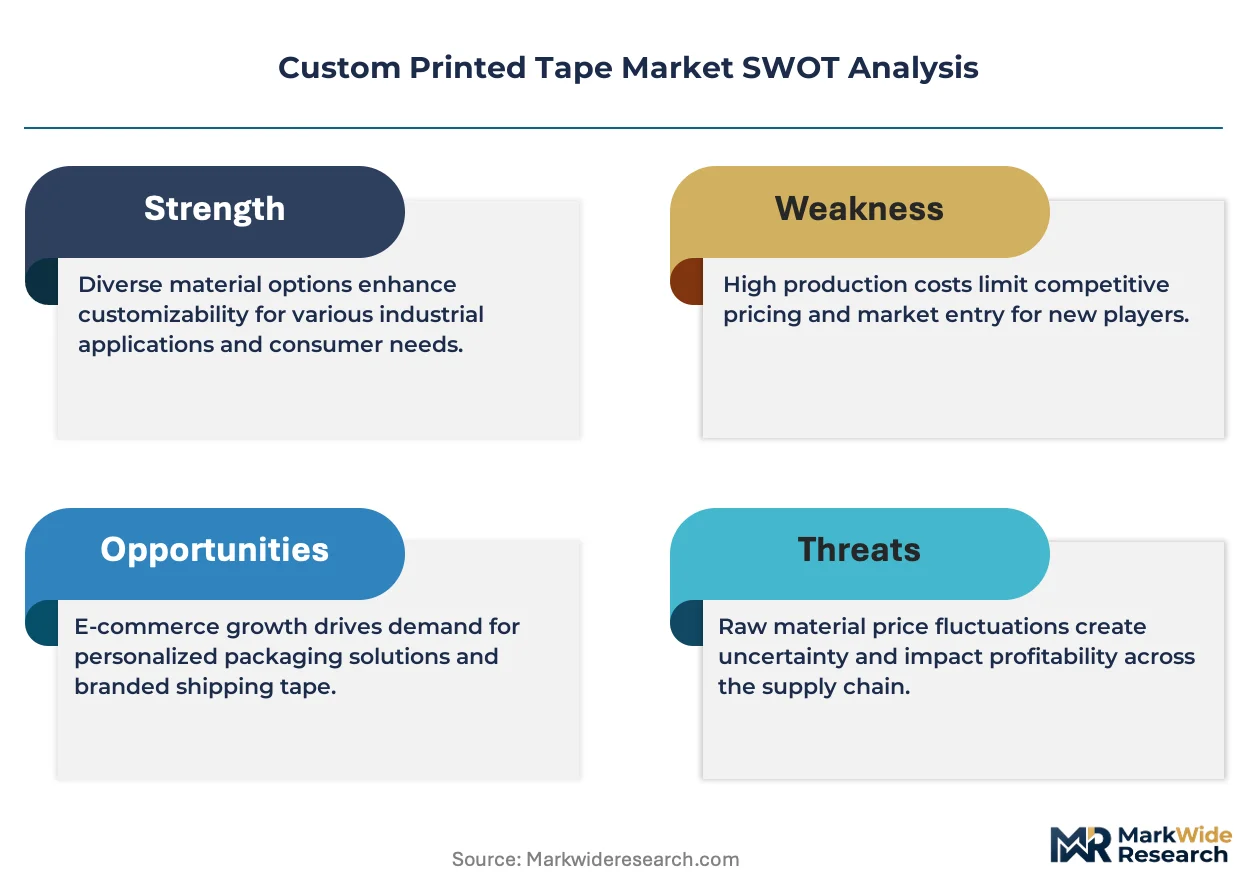
- Petrochemical feedstock volatility:Polypropylene resin prices track naphtha and propylene monomer swings, squeezing margin predictability for non-integrated converters.
- Gravure plate cost rigidity:Traditional cylinder engraving for long-run orders requires capital-intensive preproduction that digital-native competitors bypass entirely.
- EU Packaging and Packaging Waste Regulation documentation burden:Recyclability pathway verification is extending quoting cycles and raising compliance overhead for cross-border shipments.
Strategic Opportunities
- India's organized retail buildout:Modern trade expansion in Maharashtra and Gujarat is creating first-time branded packaging demand among domestic consumer goods manufacturers.
- Smart tape integration:RFID inlays and QR-embedded graphics are converging physical sealing with supply chain traceability, commanding price premiums in pharmaceutical distribution.
- Asset-light equipment leasing:Flexographic press rental models are lowering entry barriers for mid-size converters seeking short-run capabilities without balance-sheet commitment.
Industry Challenges
- Flexographic operator scarcity:Skilled press technicians capable of managing anilox roller selection and ink viscosity control are concentrating at established converters, constraining capacity expansion.
- Color consistency across substrate batches:Polypropylene surface energy variation demands real-time corona treatment adjustment, complicating quality assurance for multi-shift operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Printed Tape Market |
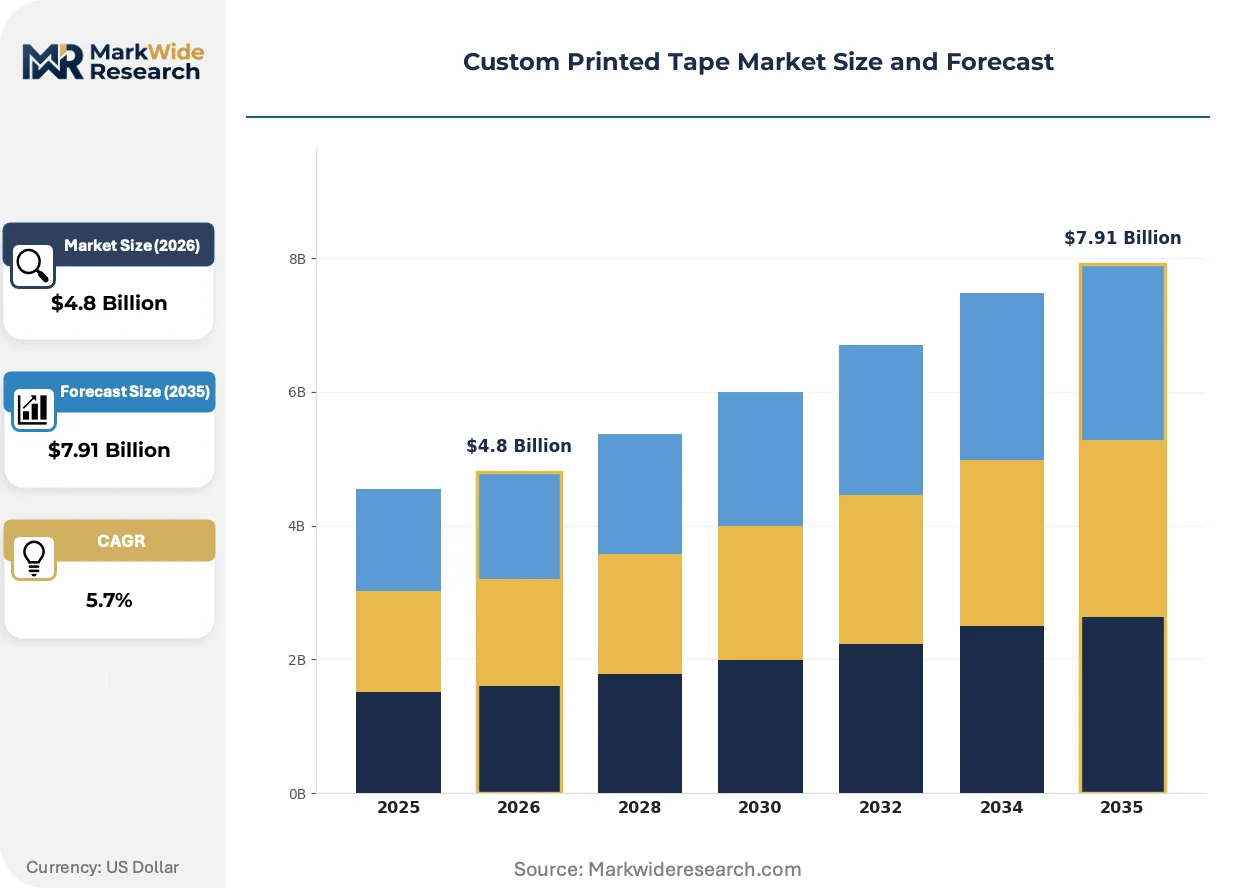
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packaging Tape, Decorative Tape, Warning Tape, Logo Tape Material: Polypropylene, PVC, Paper, Biodegradable End User: E-commerce, Retail, Manufacturing, Logistics Printing Technology: Flexographic, Digital, Gravure, Offset |
| Companies Covered | 3M Company, Avery Dennison Corporation, Intertape Polymer Group, Shurtape Technologies, Uline, UPM Raflatac, Can-Do National Tape, Tape Jungle, CS Hyde Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Printed Tape Market Strategic Shifts
Water-based ink systems and inline spectrophotometry are redefining print quality benchmarks while collapsing the traditional trade-off between speed and customization flexibility.
Single-pass inkjet arrays are rendering obsolete the gravure-digital hybrid workflows that dominated short-run customization for the past decade. E-commerce fulfillment centers in the Netherlands and Belgium are adopting these systems for same-day branded tape production. The elimination of physical plates is compressing order turnaround from weeks to hours, forcing legacy converters to absorb stranded cylinder inventory.
REACH Annex XVII restrictions on adhesive plasticizers are redirecting formulation R&D toward bio-based tackifiers and solvent-free acrylic emulsions. Converters serving French and German food-contact applications are submitting updated safety data sheets to ECHA ahead of 2025 compliance deadlines. Paper-backed alternatives with certified compostability are capturing shelf-ready packaging contracts previously held by PVC tapes.
Direct procurement relationships between brand owners and tape converters are displacing the distributor-mediated model that governed fragmented volume allocation. Major German automotive suppliers are establishing approved vendor lists with technical qualification requirements, bypassing traditional packaging wholesalers. This consolidation of buying influence is visible across industrial corridors in Bavaria and Baden-Württemberg, where specification authority has shifted from logistics managers to brand marketing teams.
Custom Printed Tape Market Segmentation
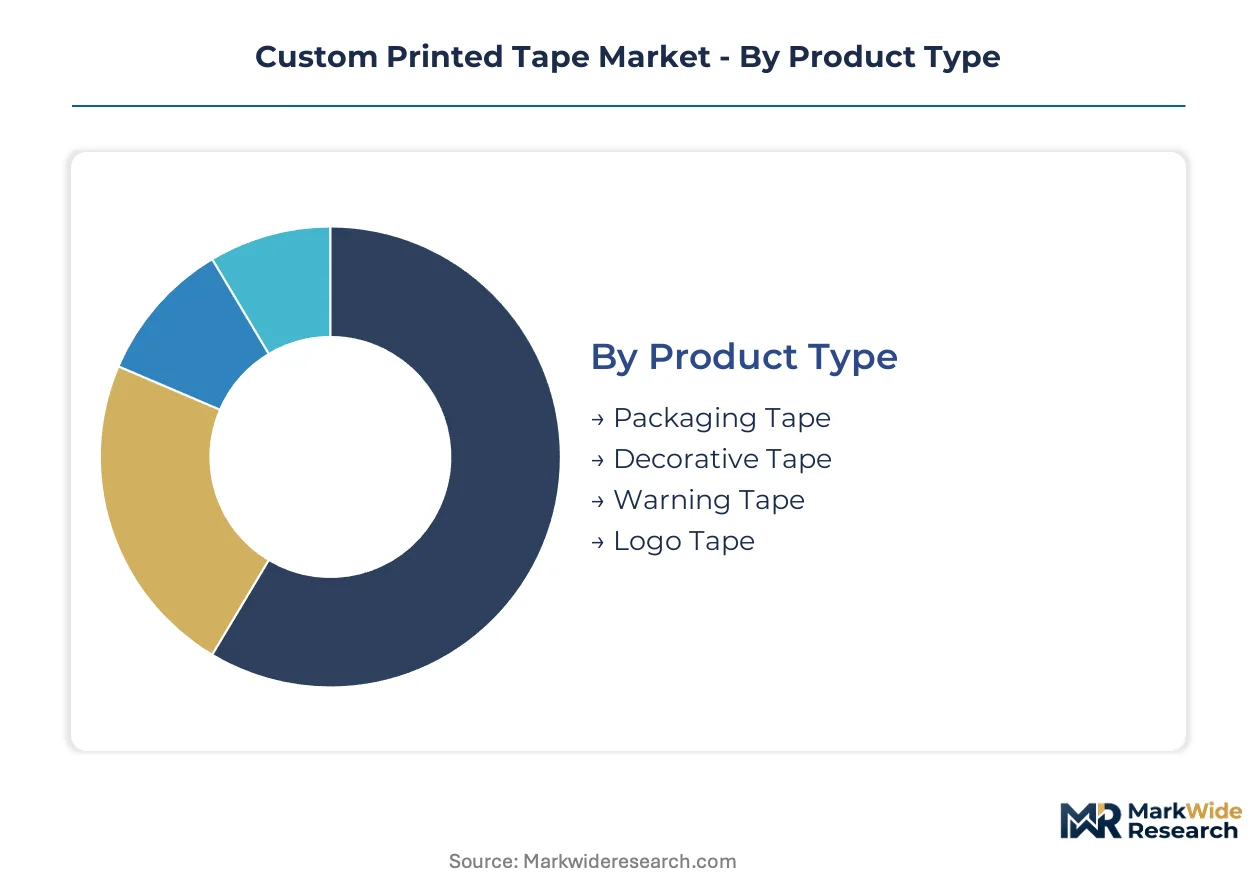
Segmentation in custom printed tape reveals how substrate choices, print methods, and end-use requirements fragment procurement patterns. Each dimension carries distinct margin profiles and compliance burdens that reshape converter specialization.
Product Type:
Mature carton-sealing applications coexist with emerging decorative and functional variants that command premium positioning.
- Packaging Tape:Polypropylene or PVC substrates with one- to four-color flexographic or digital printing serve omnichannel fulfillment and industrial shipping. E-commerce fulfillment centers in Germany's industrial corridor are mandating branded sealing tape for outbound parcel identity, pulling volume from generic alternatives.
- Decorative Tape:Multi-color gravure or offset printing on specialty backings delivers aesthetic packaging enhancement for premium consumer goods. Retail chains in France and Germany are specifying decorative tape for shelf-ready packaging to differentiate private-label lines.
- Warning Tape:High-visibility color combinations and standardized hazard symbols serve OSHA compliance in US industrial facilities and REACH-aligned chemical handling protocols in European warehouses.
- Logo Tape:Simplified single-color branding on economy-grade substrates addresses cost-conscious bulk procurement from third-party logistics operators.
Packaging Tape retains volume leadership; Biodegradable materials hold the steepest expansion curve.
Material:
Cost tiers separate petroleum-derived substrates from emerging bio-based alternatives that capture sustainability procurement tenders.
- Polypropylene:Biaxially oriented film with hot-melt or solvent acrylic adhesives dominates high-volume carton sealing. Surface energy variation demands real-time corona treatment adjustment, complicating quality assurance for multi-shift operations.
- PVC:Calendered vinyl backing with rubber-based adhesives offers conformability to irregular surfaces in cold-chain logistics. REACH Annex XVII restrictions on plasticizers are redirecting formulation R&D toward compliant alternatives.
- Paper:Kraft or crepe backing with water-activated or pressure-sensitive adhesives serves corrugated box sealing with certified recyclability. EU Packaging and Packaging Waste Regulation documentation requirements favor paper-backed alternatives.
- Biodegradable:Plant-derived films and bio-based tackifiers target compostability certification for European retail sustainability mandates. Paper-backed alternatives with certified compostability are capturing shelf-ready packaging contracts previously held by PVC tapes.
Polypropylene retains volume leadership; Biodegradable materials hold the steepest expansion curve.
End User:
Customer type determines order scale, customization depth, and technical qualification requirements.
- E-commerce:Third-party logistics operators and direct-to-consumer brands require variable-data printing for seasonal campaigns and regional fulfillment. Digital printing adoption is compressing order minimums and collapsing lead times.
- Retail:Shelf-ready packaging specifications from French and German chains mandate color consistency and food-contact safety documentation. Direct procurement relationships are displacing distributor-mediated volume allocation.
- Manufacturing:Automotive and industrial equipment producers specify tamper-evident sealing with barcode traceability for warranty protection.
- Logistics:Freight forwarders and parcel carriers prioritize tensile strength and adhesive shear resistance over branding complexity for cross-border shipment security.
E-commerce retains volume leadership; Retail holds the steepest expansion curve.
Printing Technology:
Volume scale and customization depth dictate technology selection, with digital processes disrupting traditional plate-based workflows.
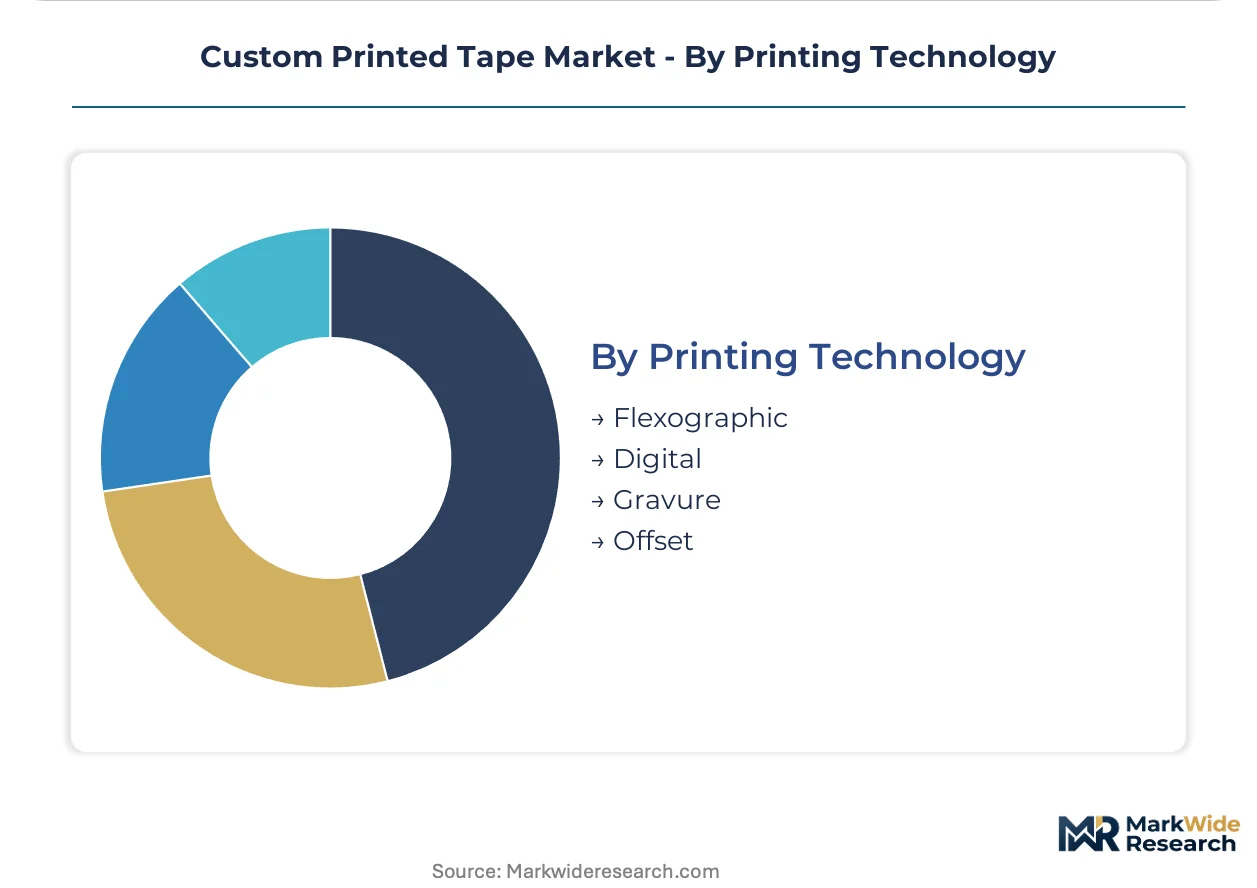
- Flexographic:Rotary letterpress with photopolymer plates and anilox roller ink metering dominates long-run orders with static graphics. Skilled press technicians capable of managing anilox roller selection and ink viscosity control are concentrating at established converters.
- Digital:Single-pass inkjet or toner-based systems enable variable-data graphics and same-day production for short-run orders. E-commerce fulfillment centers in the Netherlands and Belgium are adopting these systems for same-day branded tape production.
- Gravure:Cylinder engraving with electro-mechanical or laser etching delivers high-resolution reproduction for decorative and premium applications. Capital-intensive preproduction requirements expose gravure operators to digital-native competition.
- Offset:Lithographic transfer with rubber blanket cylinders serves paper-backed tape applications requiring fine detail reproduction.
Flexographic retains volume leadership; Digital holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation documentation requirements are redirecting procurement patterns toward certified converters with established recyclability pathways. Germany's industrial corridor anchors European demand, while e-commerce fulfillment expansion in the Netherlands and Belgium accelerates digital printing adoption.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg mandate tamper-evident branded tape with barcode traceability for warranty protection. ECHA REACH Annex XVII compliance on adhesive plasticizers forces reformulation toward bio-based tackifiers. Fulfillment centers in the Rhine-Ruhr metropolitan region specify color-consistent polypropylene sealing tape for outbound parcel identity.
United States
FDA indirect food-contact rules shape tape selection for packaged goods distribution through third-party logistics networks. OSHA hazard communication standards drive warning tape procurement for industrial facilities in Texas and Ohio. E-commerce fulfillment hubs in the Midwest and Southeast prioritize tensile strength specifications over branding complexity for cross-border shipment security.
Netherlands
Single-pass inkjet adoption compresses order turnaround from weeks to hours at fulfillment centers serving Benelux e-commerce corridors. EU Green Deal sustainability targets accelerate biodegradable substrate tenders from Rotterdam-based retail distributors. Same-day branded tape production capabilities concentrate in Eindhoven's advanced manufacturing cluster.
China
Dual carbon goals under MIIT guidance redirect substrate R&D toward plant-derived films and water-based ink systems. Export-oriented manufacturers in the Yangtze River Delta face documentation burdens for EU-bound shipments requiring recyclability verification. Zhejiang and Jiangsu province converters invest in digital printing to capture short-run customization demand from cross-border e-commerce platforms.
India
PLI scheme incentives for organized retail buildout create first-time branded packaging demand among Maharashtra and Gujarat consumer goods manufacturers. BIS certification requirements for adhesive chemical composition raise entry barriers for unorganized sector suppliers. Modern trade expansion in Mumbai and Ahmedabad concentrates specification authority with brand marketing teams rather than logistics managers.
Custom Printed Tape Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. Integrated resin producers with captive polypropylene supply sustain margin predictability against non-integrated converters exposed to naphtha price swings. Three archetypes dominate: multinational adhesive substrate manufacturers with backward integration into resin production, regional digital-native converters exploiting plateless workflows, and specialized decorative tape fabricators serving premium consumer goods. Competitive moves concentrate on M&A to capture geographic density and technology licensing to bypass stranded gravure cylinder investments.
Within the multinational integrated tier, 3M Company and Avery Dennison Corporation exemplify resin-captive positioning that insulates margin structures from petrochemical feedstock volatility. Among North American distribution-focused players, Intertape Polymer Group occupies a position emphasizing geographic density of fulfillment infrastructure. These three entities represent contrasting strategic anchors: integrated chemical-adhesive manufacturing, digital printing workflow leadership, and logistics network coverage respectively.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Intertape Polymer Group |
| Shurtape Technologies |
| Uline |
| UPM Raflatac |
| Can-Do National Tape |
| Tape Jungle |
| CS Hyde Company |
| Others |
Value Chain & Pricing Dynamics
Zhejiang province's converter cluster capacity expansion is compressing margins for European mid-tier players while granting pricing power to resin-integrated multinationals serving REACH-compliant tenders. Cost pass-through mechanics diverge sharply between petroleum-dependent substrates and certified biodegradable alternatives.
Pricing Analysis
Certification level (REACH/FDA-grade) creates the primary spread between premium and standard tiers, with bio-based tackifier formulations commanding substantial markups over conventional solvent acrylics. Three-tier pricing structure across premium, standard, and economy levels reflects adhesive chemistry grade, volume scale, and documentation depth. Cost compression in economy-grade polypropylene is intensifying because naphtha-linked resin volatility squeezes non-integrated converters. Third-party logistics operators exhibit highest price sensitivity, while pharmaceutical distributors prioritize compliance documentation over unit cost.
Supply Chain Analysis
EU dual-use export controls on advanced inkjet printhead technology limit single-pass array availability to Chinese converters, constraining digital capacity expansion in the Yangtze River Delta. Raw material flows center on Saudi propylene monomer, South Korean biaxially oriented film, and German anilox roller equipment. Single-source vulnerability concentrates in photopolymer plate engraving services for flexographic workflows. Distribution runs through Rotterdam-based master distributors serving Benelux fulfillment corridors, with direct procurement bypassing wholesale channels in Germany's automotive supply base.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where REACH documentation depth and ECHA pre-registration create switching costs that lock in certified converters against price-based competition.
For Market Incumbents: Build certification moats by accelerating bio-based tackifier R&D ahead of Annex XVII plasticizer restrictions and capturing approved vendor status with Bavarian automotive suppliers. Capacity addition in Eindhoven's manufacturing cluster secures same-day production capabilities that digital-native competitors cannot replicate. Threat substitution from RFID-embedded smart tape demands companion technology licensing to avoid stranded flexographic investments.
For New Entrants and Emerging Players: Pursue Maharashtra's organized retail buildout as the most penetrable white-space, where PLI scheme incentives and BIS certification gaps create first-mover windows among domestic consumer goods manufacturers. Asset-light equipment leasing for short-run digital capability bypasses gravure cylinder capital requirements. Go-to-market angle centers on seasonal campaign velocity for direct-to-consumer brands underserved by plate-based workflows.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because geographic density advantages in North American distribution and captive resin supply predictability favor scaled operators over fragmented regional converters. Acquisition target archetype: digital-native converters with established same-day production workflows in Benelux corridors. Signal to watch: ECHA enforcement intensity on adhesive plasticizer documentation as inflection indicator for premium tier margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive polypropylene supply insulates 3M and Avery Dennison from naphtha volatility affecting non-integrated competitors. |
| Digital Printing Workflow Migration | Single-pass inkjet adoption at Netherlands fulfillment centers collapses order turnaround from plate-based weeks to hours. |
| Biodegradable Substrate Certification | Compostability credentials from TÜV or OK Compost unlock European retail tenders previously closed to petroleum-based tapes. |
| Direct Procurement Channel Development | Bypassing distributor intermediaries with German automotive suppliers concentrates specification authority and pricing power. |
| Smart Tape Technology Licensing | RFID inlay integration with pharmaceutical distributors commands traceability premiums and locks in long-term supply contracts. |
Study Parameters
Cross-validation between executive interviews at tape converters and customs trade data anchors the qualitative findings on substrate flow patterns. Primary discussions with flexographic press operators, adhesive formulation chemists, e-commerce fulfillment procurement leads, and retail packaging specification managers combined with secondary validation from ECHA substance registrations, EU Packaging and Packaging Waste Regulation guidance documents, and SEC 10-K disclosures from listed adhesive substrate manufacturers. Bottom-up capacity assessments at Zhejiang and Jiangsu province facilities triangulate against top-down demand modeling from omnichannel fulfillment expansion metrics.
Calibration against historical price elasticity during propylene monomer spike periods informs volume and value outputs across the projection horizon. Segmentation dimensions modeled include substrate material tier, print technology type, end-use industry vertical, and regional regulatory cluster. CAGRs derive from adhesive consumption intensity ratios tied to parcel shipment growth indices. Industry-specific forecast inputs incorporate REACH Annex XVII enforcement timelines and EU Green Deal biodegradable procurement mandates.
Macroeconomic conditions sit as an overlay; deviation in naphtha pricing spreads or euro-dollar exchange volatility would shift the trajectory for import-dependent European converters. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity between digital and flexographic workflows. Material shifts in ECHA substance restriction scope or breakthroughs in plant-derived adhesive performance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tape Unwinder Market
Tapes
Automotive Tapes Market
Tapes
Kraft Paper Tapes Market
Tapes
Protective Films Tapes Market
Tapes
Tape Dispenser Market
Tapes
Electrical Shielding Tape Market
Tapes
Release Tape Market
Tapes
Double Sided Tape Market
Tapes
Paper Masking Tapes Market
Tapes
Freezer Tape Market
Tapes
Nano Tapes Market
Tapes
Europe Packaging Tapes Market
Tapes
Sterilization Tape Market
Tapes
Paper Tapes Market
Tapes
Tape and Label Adhesives Market
Tapes
Adhesive Transfer Tape Market