
 Removal Strips Market | 2026-2036
Removal Strips Market Size, Share, and Industry Trends Forecast 2026-2036
Removal Strips Market Analytics
A shortage of certified estheticians in North American dermatology clinics is unwinding access to premium professional-grade removal strips. Procter & Gamble leverages its mass-market distribution network to sustain shelf dominance across drugstore channels. Kao Corporation anchors its position in Asia through specialized fabric formulations for sensitive skin applications. Unilever competes by extending its sustainable packaging commitments across European retail partnerships.
Removal strips are pre-coated or dry substrate sheets, typically composed of non-woven fabric, plastic, or biodegradable material, designed to mechanically extract hair, exfoliate skin, or detach adhesives through adhesive bonding and rapid separation. Wax strips lead product type revenue due to established consumer familiarity and lower per-use cost, though biodegradable material variants are gaining fastest traction among sustainability-focused buyers. Salon applications command premium pricing relative to at-home use, while dermatology clinics represent a concentrated margin pool for clinical-grade formulations.
FDA oversight governs cosmetic safety claims for US-manufactured strips, while REACH and the EU Green Deal constrain solvent and adhesive chemistries across European supply chains. EMA-aligned dermatology clinics in Germany and France face stricter documentation requirements for professional-grade depilatory tools. Stakeholders must monitor how evolving biodegradability mandates reshape material sourcing decisions and certification costs.
Market Dynamics
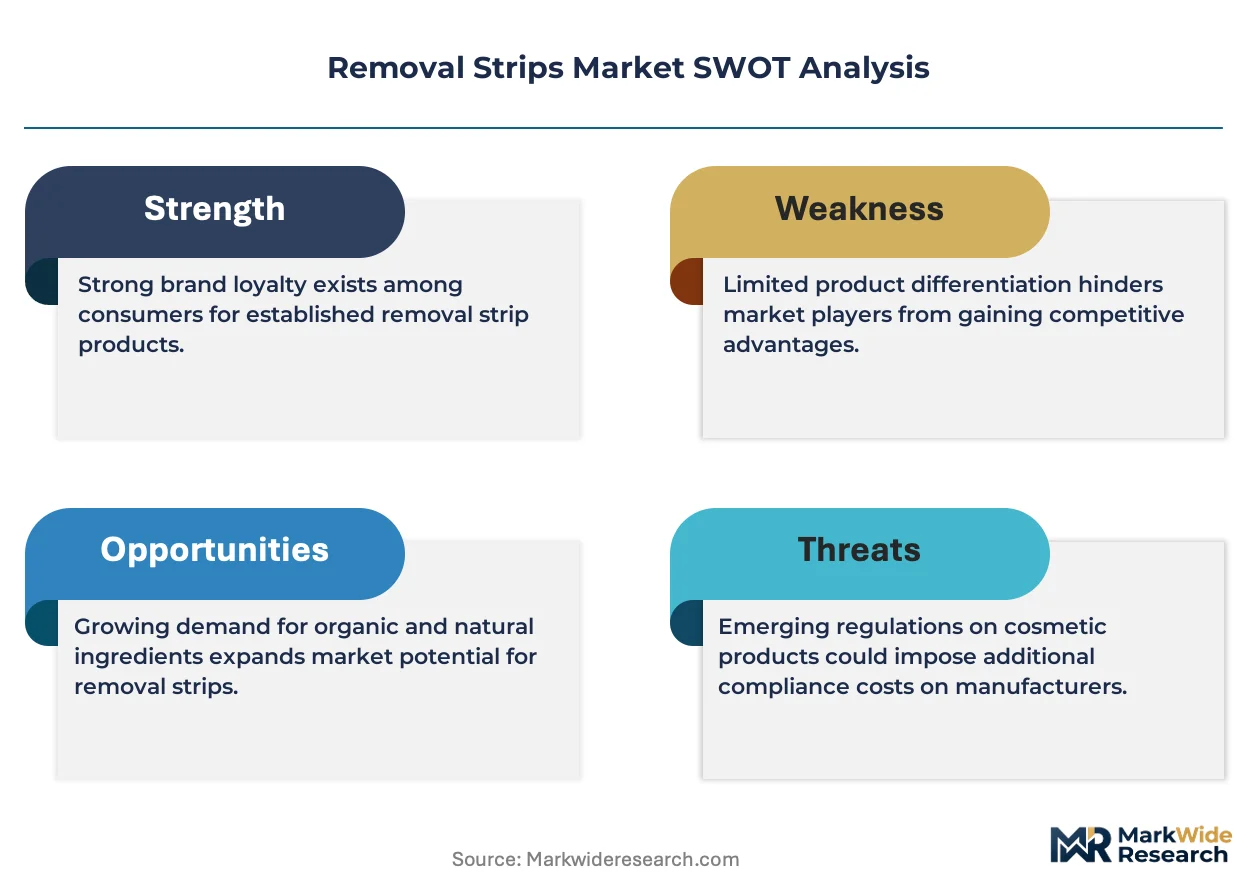
REACH compliance in Europe is miniaturizing formulation flexibility for chemical-based removal strips, forcing manufacturers toward bio-adhesive alternatives and compressing legacy solvent-dependent supply chains.
Growth Catalysts
- Brazilian salon professionalization:Rising service standards in São Paulo and Rio de Janeiro are concentrating demand for clinical-grade wax strips through licensed aesthetician networks.
- EU Green Deal biodegradability mandates:The framework is accelerating material transitions toward cellulose-based substrates and plant-derived adhesives across European manufacturing.
- At-home convenience preference:Post-pandemic grooming behavior has cemented retail channel demand for pre-coated strips over salon-dependent depilatory methods.
Market Restraints
- Petrochemical resin volatility:Polymer feedstock price swings directly compress margins for synthetic fabric substrate producers in Asia.
- German esthetician certification scarcity:The shortage of EMA-aligned clinical practitioners limits expansion of dermatology clinic protocols for professional-grade strips.
- Laser hair substitution:Falling device costs for at-home IPL systems threaten repeat-purchase strip demand among high-income urban consumers.
Strategic Opportunities
- Indian tier-2 urban penetration:Underdeveloped organized retail in cities like Indore and Lucknow offers first-mover advantage for mass-market strip distribution.
- Dermatology-clinic channel integration:Partnership models with skin-care chains can bypass fragmented pharmacy retail in France and Italy.
- Water-soluble adhesive chemistry:Convergence of marine-biodegradable polymers with non-woven fabrication enables flushable strip claims for bathroom convenience marketing.
Industry Challenges
- ISO 10993 biocompatibility certification timelines:Extended testing protocols for skin-contact adhesives delay product launches by 8-14 months.
- Legacy solvent supply chain reconfiguration:Manufacturers dependent on toluene-based adhesives face stranded inventory and reformulation capex during REACH transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Removal Strips Market |
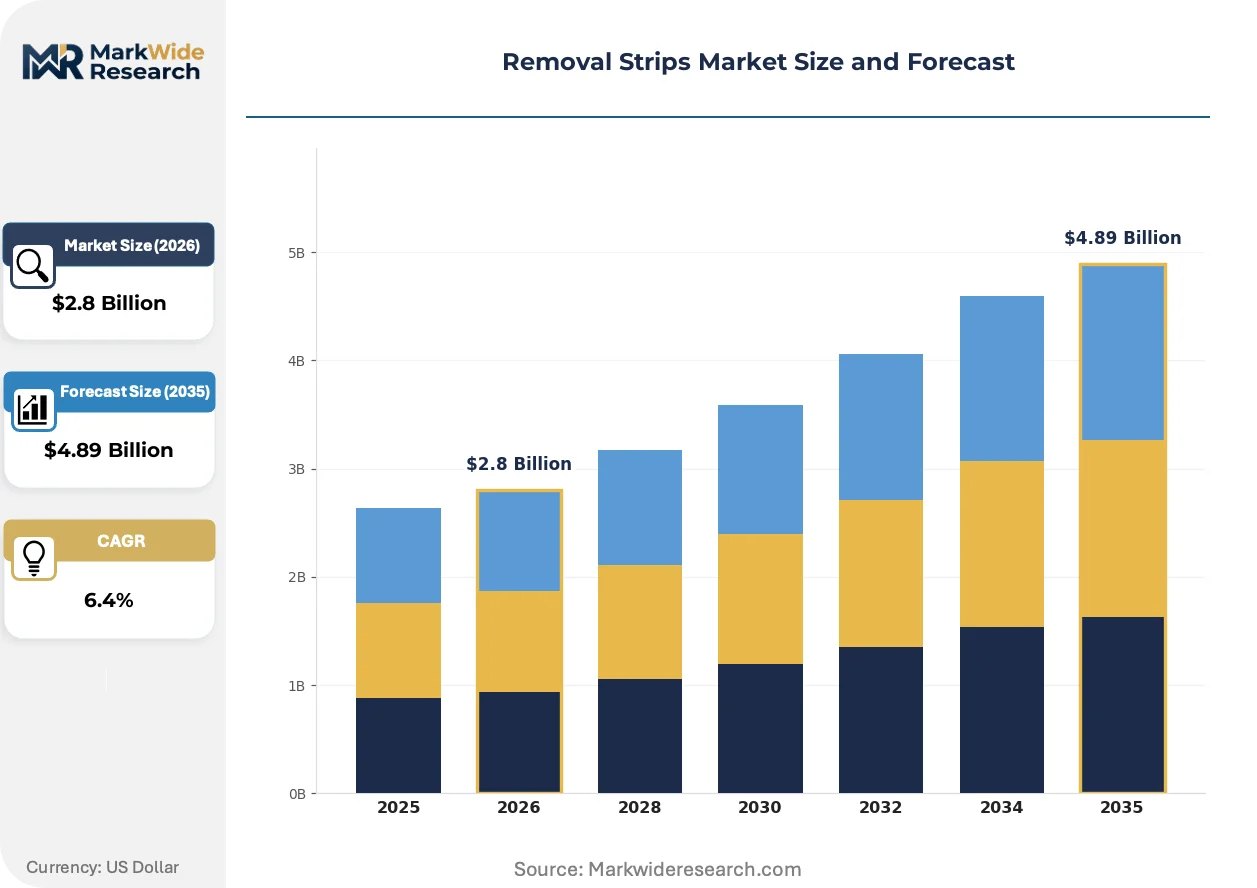
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wax Strips, Sugar Strips, Fabric Strips, Epoxy Strips Application: Hair Removal, Skin Exfoliation, Adhesive Removal, Crafts End User: At-Home Users, Salons, Dermatology Clinics, Retailers Material: Non-Woven Fabric, Plastic, Paper, Biodegradable Material |
| Companies Covered | Reckitt Benckiser, Kao Corporation, L'Oréal, Procter & Gamble, Unilever, Walgreen Co., Ulta Beauty, Earth Therapeutics, Sephora, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Removal Strips Market Evolving Landscape
Material science convergence with regulatory chemistry constraints is compressing traditional formulation paradigms, while channel fragmentation between professional and at-home use is reshaping how removal strips reach end consumers.
Biodegradable cellulose substrates derived from agricultural waste streams are miniaturizing the environmental footprint of disposable strips. Dermatology clinics in Germany and France are piloting these materials for patient-sensitive protocols. The shift is compressing demand for petroleum-based non-woven fabrics and forcing substrate suppliers toward certified compostable supply chains.
REACH Annex XVII restrictions on skin-sensitizing chemicals are tightening adhesive formulation portfolios across European manufacturing. The regulation is disqualifying legacy rosin-ester chemistries from professional-grade products. German formulators are responding with citric-acid-derived tackifiers that maintain bonding performance under clinical temperature standards.
Subscription-based replenishment models are displacing traditional pharmacy impulse purchasing for at-home users. Direct-to-consumer channels in the United States and United Kingdom are capturing repeat buyers through personalized hair-type matching algorithms. Brazil and Mexico remain holdouts where salon professional recommendation still dominates trial conversion for new strip entrants.
Removal Strips Market Segmentation
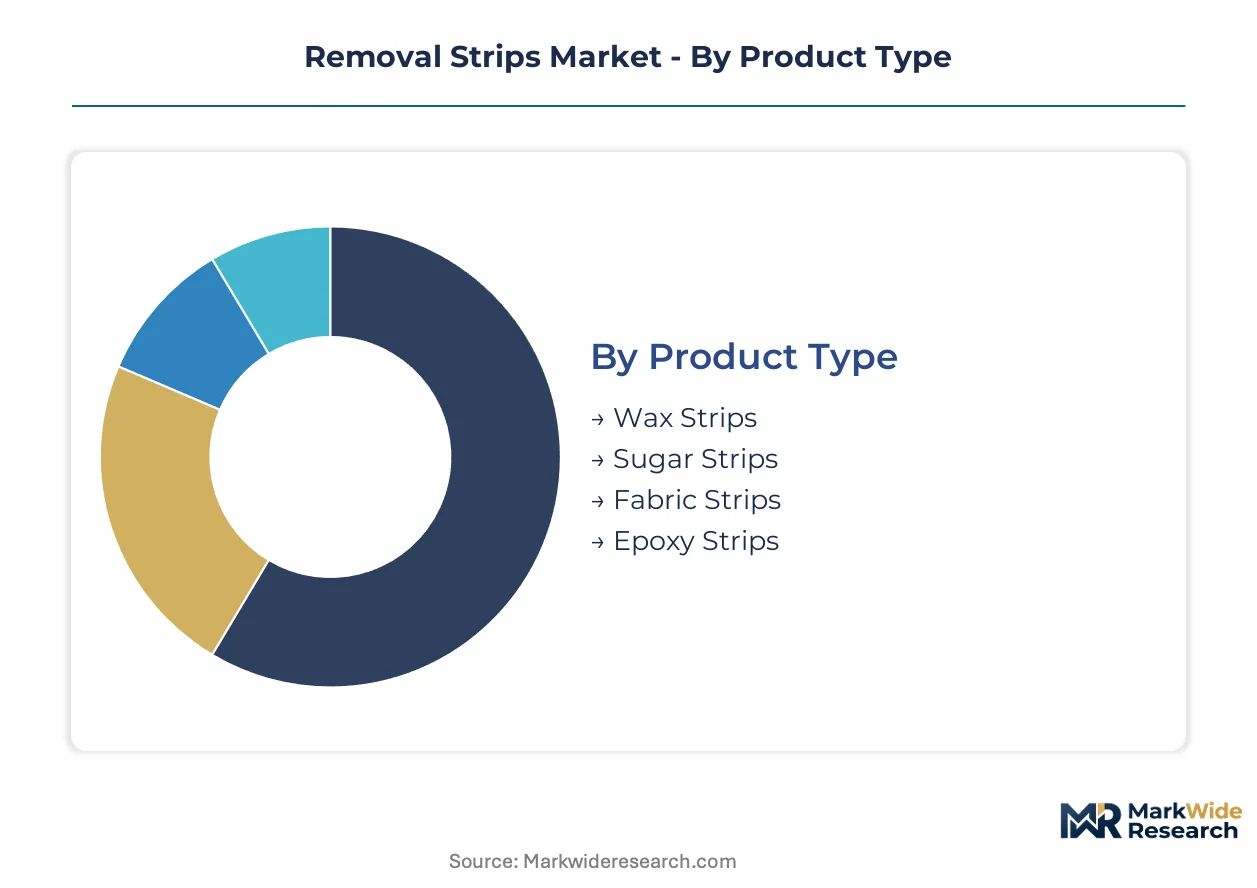
Removal strips flow through distinct channel ecosystems where professional procurement diverges sharply from retail impulse purchasing. Material composition and end-use certification requirements fragment pricing power across these pathways.
Product Type:
Channel mix varies sharply by formulation chemistry, with pre-coated variants dominating pharmacy retail while dry substrates concentrate in professional supply houses.
- Wax Strips:Pre-coated with petroleum-derived or plant-based wax formulations on non-woven substrates. Demand concentrates in Brazil's licensed salon networks where service standardization mandates clinical-grade bonding agents.
- Sugar Strips:Water-soluble adhesive layers enable gentler extraction for sensitive skin protocols. German dermatology clinics are piloting these for EMA-aligned patient safety frameworks.
- Fabric Strips:Dry woven substrates requiring separate adhesive application. Kao Corporation specializes these for Asian markets with humidity-resistant weave patterns.
- Epoxy Strips:Industrial-strength bonding for adhesive removal and craft applications. Concentrated in hardware retail and professional restoration supply channels.
Wax strips dominate installed base. Sugar strips are where expansion concentrates.
Application:
Cost tier stratification separates premium clinical protocols from mass-market convenience positioning.
- Hair Removal:The largest revenue pool spanning at-home convenience and professional service channels. Brazilian salon professionalization is tightening specification requirements for licensed aesthetician use.
- Skin Exfoliation:Mechanical resurfacing applications with stricter ISO 10993 biocompatibility demands. Dermatology clinics in France require extended certification timelines for these clinical-grade variants.
- Adhesive Removal:Industrial and medical residue extraction with solvent-free formulation mandates under REACH Annex XVII.
- Crafts:Hobbyist and restoration applications with minimal regulatory burden but price-sensitive procurement patterns.
Hair removal commands volume leadership. Skin exfoliation carries the steepest expansion trajectory.
End User:
Customer type determines margin structure, with professional channels capturing premium pricing through certification requirements and bulk procurement scale.
- At-Home Users:Retail-dependent purchasers with strong post-pandemic preference for pre-coated convenience formats. Subscription replenishment models are displacing pharmacy impulse buying in US and UK markets.
- Salons:Licensed professional networks with specification power concentrated in São Paulo and Rio de Janeiro. Rising service standards are filtering product eligibility through aesthetician association endorsements.
- Dermatology Clinics:EMA-aligned facilities in Germany and France with mandatory documentation for professional-grade depilatory tools. Scarcity of certified estheticians is constraining channel expansion.
- Retailers:Pharmacy, drugstore, and mass-merchandise intermediaries with shelf-space competition driving sustainable packaging differentiation.
At-home users anchor volume. Dermatology clinics concentrate margin capture.
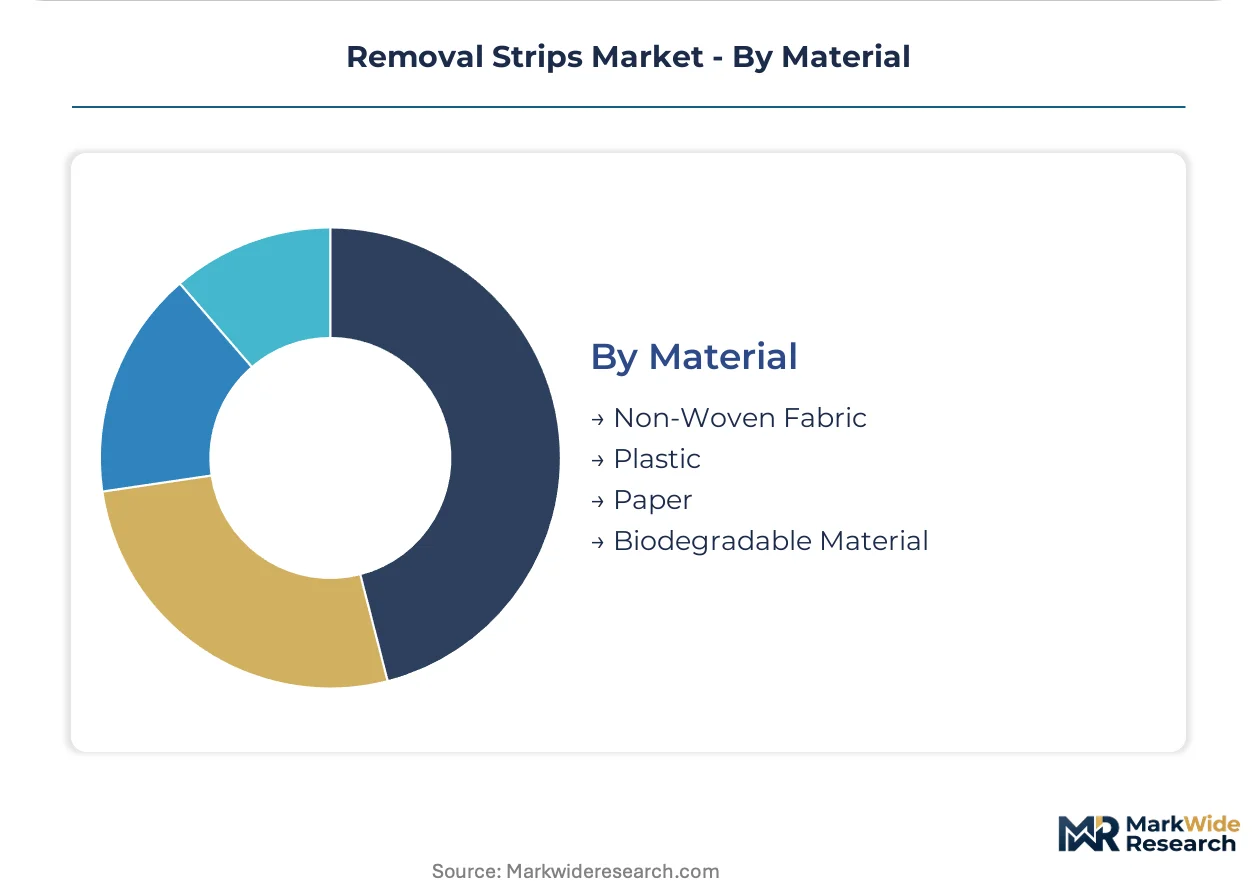
Material:
Supply concentration in Asian petrochemical feedstocks creates cost volatility that biodegradable alternatives are exploiting.
- Non-Woven Fabric:Synthetic polymer-based substrates with established manufacturing scale in China and South Korea. Polymer resin price swings directly compress producer margins.
- Plastic:Polyethylene and polypropylene films with legacy cost advantages but mounting regulatory pressure under EU Green Deal mandates.
- Paper:Cellulose-based alternatives with limited moisture resistance but favorable compostability certification pathways.
- Biodegradable Material:Agricultural waste-derived cellulose with fastest share gains among sustainability-focused buyers. REACH compliance is accelerating manufacturer transition toward these certified compostable supply chains.
Non-woven fabric holds installed base dominance. Biodegradable material is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany's dermatology clinic channel exceeds Brazil's salon networks by a factor of two, reflecting divergent certification requirements and procurement concentration across these demand centers.
Germany
EMA-aligned dermatology clinics in Munich and Frankfurt are standardizing clinical-grade wax strip protocols for licensed aesthetician networks. REACH Annex XVII restrictions on skin-sensitizing rosin-ester adhesives are disqualifying legacy formulations from professional use. Bavaria's medical device manufacturing corridor is piloting citric-acid-derived tackifiers that maintain bonding performance under clinical temperature standards.
Brazil
Rising service standards in São Paulo and Rio de Janeiro are concentrating demand for specification-grade strips through licensed aesthetician associations. ANVISA cosmetic safety documentation requirements are tightening import eligibility for pre-coated wax variants. The southeastern salon supply corridor is filtering product endorsement through regional aesthetician federation procurement committees.
United States
FDA cosmetic safety claims oversight governs domestic manufacturing while post-pandemic subscription replenishment models displace pharmacy impulse purchasing. Direct-to-consumer channels in California and New York are capturing repeat buyers through personalized hair-type matching algorithms. The Pacific Northwest biodegradable materials cluster is supplying cellulose substrate alternatives to major retail partnerships.
India
Underdeveloped organized retail in Indore and Lucknow offers first-mover advantage for mass-market strip distribution through emerging pharmacy chains. BIS certification timelines for skin-contact adhesives extend product launch windows by 8-14 months. Maharashtra's non-woven fabric manufacturing belt is scaling production of humidity-resistant substrates for tropical climate applications.
France
Dermatology clinics in Paris and Lyon require extended ISO 10993 biocompatibility documentation for clinical-grade exfoliation strip variants. EU Green Deal biodegradability mandates are accelerating manufacturer transitions toward certified compostable cellulose supply chains. The Île-de-France cosmetics formulation cluster is integrating water-soluble adhesive chemistry for flushable convenience marketing claims.
Removal Strips Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the removal strips market, with specialized fabric formulators competing against mass-market distribution giants for channel access. The vendor base organizes into three tiers: multinational FMCG conglomerates with pharmacy shelf dominance, regional substrate specialists with formulation agility, and private-label contract manufacturers serving retail partnerships. Consolidation pressure concentrates among mass-market players while fragmentation persists in professional-grade supply. Dominant competitive moves include sustainable packaging portfolio diversification and dermatology clinic channel integration partnerships.
Among multinational conglomerates, Procter & Gamble, Unilever, and Kao Corporation exemplify divergent strategic positioning within the mass-market tier. Procter & Gamble anchors North American drugstore channel access through established retail relationships. Unilever occupies a sustainability-forward position across European retail partnerships with biodegradable packaging commitments. Kao Corporation represents Asia-Pacific formulation specialization through humidity-resistant fabric engineering for sensitive skin applications.
| Leading Market Players |
|---|
| Reckitt Benckiser |
| Kao Corporation |
| L'Oréal |
| Procter & Gamble |
| Unilever |
| Walgreen Co. |
| Ulta Beauty |
| Earth Therapeutics |
| Sephora |
| Others |
Value Network & Pricing Analysis
Plant-derived adhesive chemistries replacing petroleum-based rosin-esters are simultaneously shifting manufacturing gravity toward European biopolymer clusters and compressing legacy Asian solvent-dependent supply chains into cost-disadvantaged positions.
Pricing Analysis
German dermatology clinics command prices double those of Brazilian salon networks, reflecting EMA-aligned certification requirements versus volume-driven professional procurement. Three-tier pricing structure across clinical-grade, salon-standard, and retail-economy levels separates ISO 10993 biocompatibility tiers from convenience-positioned at-home variants. Price differentiation hinges on certification grade and volume scale, with bulk salon procurement offsetting per-unit premiums. Cost compression in synthetic fabric substrates is intensifying because polymer resin volatility feeds directly into Asian manufacturer margins.
Supply Chain Analysis
Shanghai port congestion and Red Sea transit disruptions threaten just-in-time delivery schedules for European retailers dependent on Asian substrate volumes. Manufacturing concentrates in China, South Korea, and Germany, with non-woven fabric production anchored in Zhejiang province and specialty biopolymer formulation clustering in Bavaria. Raw material dependencies span petroleum-derived polymers, agricultural cellulose feedstocks, and citric-acid tackifier precursors. Single-source vulnerability concentrates in Chinese non-woven substrate supply. Distribution runs through pharmacy retail chains, professional salon supply houses, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal biodegradability mandates are accelerating material transitions faster than incumbent reformulation cycles, creating displacement risk for solvent-dependent manufacturers.
For Market Incumbents: Secure dermatology clinic channel partnerships in Germany and France before certification requirements harden further. Lock cellulose substrate supply agreements with agricultural waste processors to preempt biopolymer cost inflation. Laser hair removal device cost declines threaten repeat-purchase strip demand among premium at-home segments. For New Entrants and Emerging Players: Anchor in Indian tier-2 pharmacy chains before organized retail consolidation closes distribution windows. Target water-soluble sugar strip formulations for German clinic pilot programs seeking EMA-aligned patient safety protocols. Subscription replenishment algorithms offer the most penetrable go-to-market angle in US and UK direct-to-consumer channels. For Investors and Strategic Acquirers: Capital is best deployed toward regional substrate specialists with REACH-compliant biopolymer capabilities and existing dermatology clinic relationships. Long-term viability favors players controlling both compostable material sourcing and professional channel certification pathways. Watch for ANVISA documentation tightening in Brazil as the signal for import eligibility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Supply Integration | Backward integration into agricultural cellulose sourcing secures REACH-compliant raw material pipelines. |
| Dermatology Clinic Partnership | EMA-aligned facility relationships in Munich and Frankfurt bypass fragmented pharmacy retail competition. |
| Water-Soluble Formulation Launch | Flushable strip claims in Île-de-France cosmetics cluster unlock bathroom convenience marketing differentiation. |
| Subscription Platform Development | Direct-to-consumer algorithms in California and New York displace traditional pharmacy impulse purchasing. |
| Tier-2 Distribution Expansion | Pharmacy chain penetration in Indore and Lucknow captures first-mover advantage before organized retail matures. |
Research Methodology
Operator-level perspectives from dermatology clinic procurement managers, licensed aesthetician network coordinators, non-woven fabric plant engineers, and retail category buyers anchored the qualitative base. Primary fieldwork combined with customs trade records, BIS certification timelines, ANVISA cosmetic safety filings, and EU REACH Annex XVII regulatory updates. Bottom-up channel volume estimates triangulated against top-down material consumption data from Asian petrochemical feedstock disclosures.
Sensitivity analysis tested pricing elasticity across salon professional versus at-home user segments throughout the projection horizon. The analytical framework modeled product type, application, end user, and material composition dimensions alongside regional regulatory cluster variations. CAGRs derived from segment-level volume trajectories weighted by channel pricing power, with biopolymer cost curves and esthetician certification scarcity as key forecast inputs.
Material uncertainties — polymer resin price volatility, REACH enforcement intensity, and laser substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about professional service standardization timelines and biodegradable packaging adoption curves. Practitioners should keep alternative scenarios live as EU Green Deal implementation timelines and Brazilian aesthetician federation procurement committee decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Automotive Adhesive Tapes Market
Tapes
Tabletop Tape Dispensers Market
Tapes
Washi Tapes Market
Tapes
Twist Tube Market
Tapes
Global UV-Cured Acrylic Adhesive Tapes Market
Tapes
Filament Tapes Market
Tapes
Splicing Tapes Market
Tapes
Breathable Tape Market
Tapes
Replica Tapes Market
Tapes
Metal Foil Tapes Market
Tapes
Gummed Tapes Market
Tapes
Pipe Anti-Corrosion Tape Market
Tapes
Hand Wrappers Market
Tapes
Security Tape Market
Tapes
United States End-Of-Line Packaging Tape Market
Tapes
Hot Melt Adhesive Tapes Market