
 Dolomite Mining Market | 2026-2036
Dolomite Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Dolomite Mining Market Intelligence
Aftermarket refractory service revenue is narrowing as original equipment manufacturers push longer-life dolomite brick formulations. Imerys SA leverages its vertical integration from quarry to finished refractory to capture margin that once flowed to third-party rebuilders. RHI Magnesita sustains dominance in steel-lining solutions through dense R&D networks across Central Europe. Sibelco anchors its position in glass-grade dolomite through controlled access to low-iron deposits in Belgium and France.
Dolomite mining extracts calcium magnesium carbonate rock, typically containing 45-55% magnesium carbonate and 54-58% calcium carbonate, through open-pit blasting and haulage for processing into industrial feedstocks. The material serves primarily as a flux in steelmaking, a refractory lining component, and a magnesium source for chemical and agricultural applications. Crushed stone commands the largest volume share across construction and road base applications, while refractory dolomite carries the highest per-tonne value due to strict chemistry and density specifications for steel-lining duty. Powdered dolomite for soil amendment and glass production represents the fastest-growing product format, driven by precision agriculture adoption and container glass capacity expansion in Southeast Asia.
EPA mining waste standards in the United States, REACH chemical registration in Europe, and India's CEA environmental clearances for limestone and dolomite extraction collectively raise compliance costs while favoring operators with capital for tailings management and dust suppression systems. The EU F-Gas Regulation indirectly pressures refractory performance standards, as tighter furnace insulation requirements extend dolomite brick replacement cycles. Stakeholders must monitor how carbon border mechanisms reshape competitive access for imported versus domestically sourced dolomite in key steel-producing jurisdictions.
Market Dynamics
Steelmakers in Asia-Pacific are consolidating dolomite procurement around captive quarry networks, compressing spot market liquidity and forcing merchant miners to reposition toward glass and agricultural offtake.
Growth Catalysts
- EU Green Deal carbon border adjustments:European steel producers face escalating import tariffs on carbon-intensive inputs, accelerating calcination efficiency investments that favor local dolomite with lower transport emissions.
- Container glass capacity expansion:Southeast Asian glass manufacturers are commissioning new float lines requiring low-iron dolomite flux, creating dedicated supply contracts with Belgian and French deposit operators.
- Precision agriculture adoption:Soil amendment applications are expanding as variable-rate spreading technology enables targeted magnesium supplementation in row-crop farming across the US Corn Belt.
Market Restraints
- Refractory brick lifespan extension:Dense dolomite formulations now achieve 18-24 month campaign lives in basic oxygen furnaces, compressing replacement cycles and reducing raw material pull from integrated steel plants.
- Energy cost volatility:Natural gas and electricity account for 35-45% of calcined dolomite production costs, exposing merchant producers to margin erosion during price spikes.
- Magnesium oxide substitution:Seawater-derived MgO and synthetic periclase are capturing share in chemical applications where dolomite once dominated as the magnesium feedstock.
Strategic Opportunities
- India's eastern mining belt consolidation:Captive quarry integration with integrated steel plants creates template for backward-linked supply models that merchant miners can replicate in Odisha and Jharkhand.
- Refractory service bundling:Original equipment manufacturers are capturing rebuild revenue through performance-based lining contracts, displacing independent aftermarket service providers.
- EU F-Gas Regulation insulation mandates:Tighter furnace envelope standards extend refractory duty cycles while creating demand for higher-density dolomite brick with superior thermal shock resistance.
Industry Challenges
- Environmental clearance timelines:India's CEA permitting process for limestone and dolomite extraction now averages 24-36 months, delaying greenfield quarry development and capacity expansion.
- Tailings management capex:EPA mining waste standards and state-level groundwater protection rules require sediment pond retrofits and dust suppression infrastructure that strain mid-tier operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dolomite Mining Market |
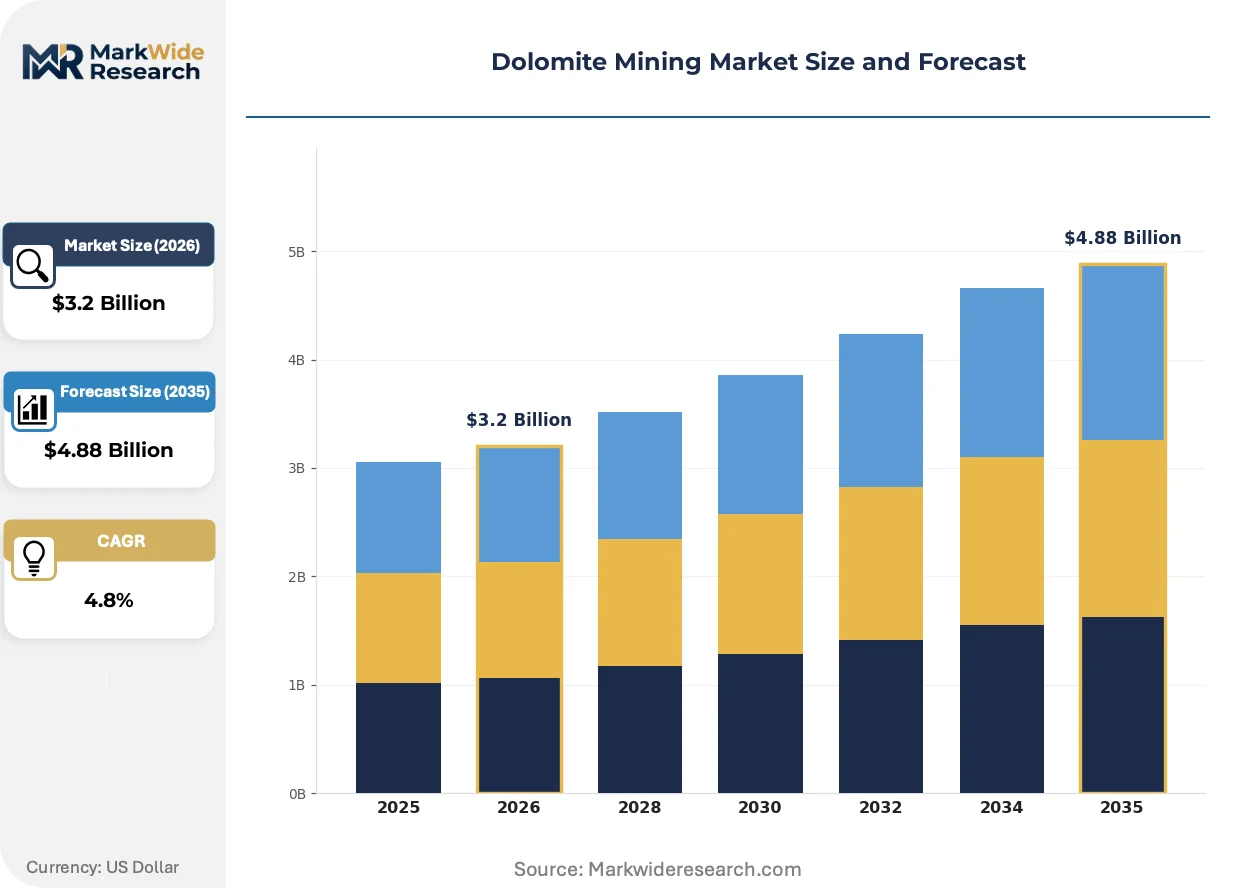
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.88 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Stone, Dolomitic Limestone, Powdered Dolomite, Refractory Dolomite End User: Construction, Agriculture, Glass Manufacturing, Iron & Steel Application: Soil Amendment, Flux in Steelmaking, Glass Production, Cement Industry Processing Technology: Crushing, Grinding, Calcination, Aggregation |
| Companies Covered | Imerys SA, Sibelco, RHI Magnesita, Lhoist Group, Carmeuse, Omya AG, Calcinor SA, Essel Mining & Industries Ltd, JFE Mineral Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dolomite Mining Market Strategic Shifts & Innovations
Calcination technology and furnace control systems are reshaping how dolomite processors extract value from ore chemistry, while regulatory pressure on carbon intensity reconfigures competitive access in key steel-producing jurisdictions.
Flash calcination systems are migrating from rotary kiln dominance in European refractory dolomite production. RHI Magnesita and Imerys SA have installed fluidized-bed reactors at Belgian and Austrian facilities, cutting fuel consumption per tonne by enabling shorter residence times at higher temperatures. This technology is migrating from premium refractory applications toward standard-grade construction dolomite as equipment costs decline and emissions accounting tightens.
REACH chemical registration in Europe now requires full supply chain disclosure for dolomite destined for pharmaceutical and food-contact applications. ECHA's expanded substance evaluation program has forced Belgian processors to segregate quarry output by trace element content, creating parallel handling streams that raise logistics complexity. Glass-grade dolomite producers are responding by certifying deposits under ISO 22000 food safety management to preempt regulatory friction.
Steelmakers are unbundling refractory procurement from installation services, awarding separate contracts for material supply and lining campaigns. This pattern concentrates volume with dolomite miners capable of guaranteeing chemistry consistency across multi-year agreements, while specialized contractors absorb the operational risk of furnace turnaround timing. The shift is most visible in India's eastern steel corridor, where Tata Steel and JSW have separated refractory material procurement from rebuild execution.
Dolomite Mining Market Segmentation
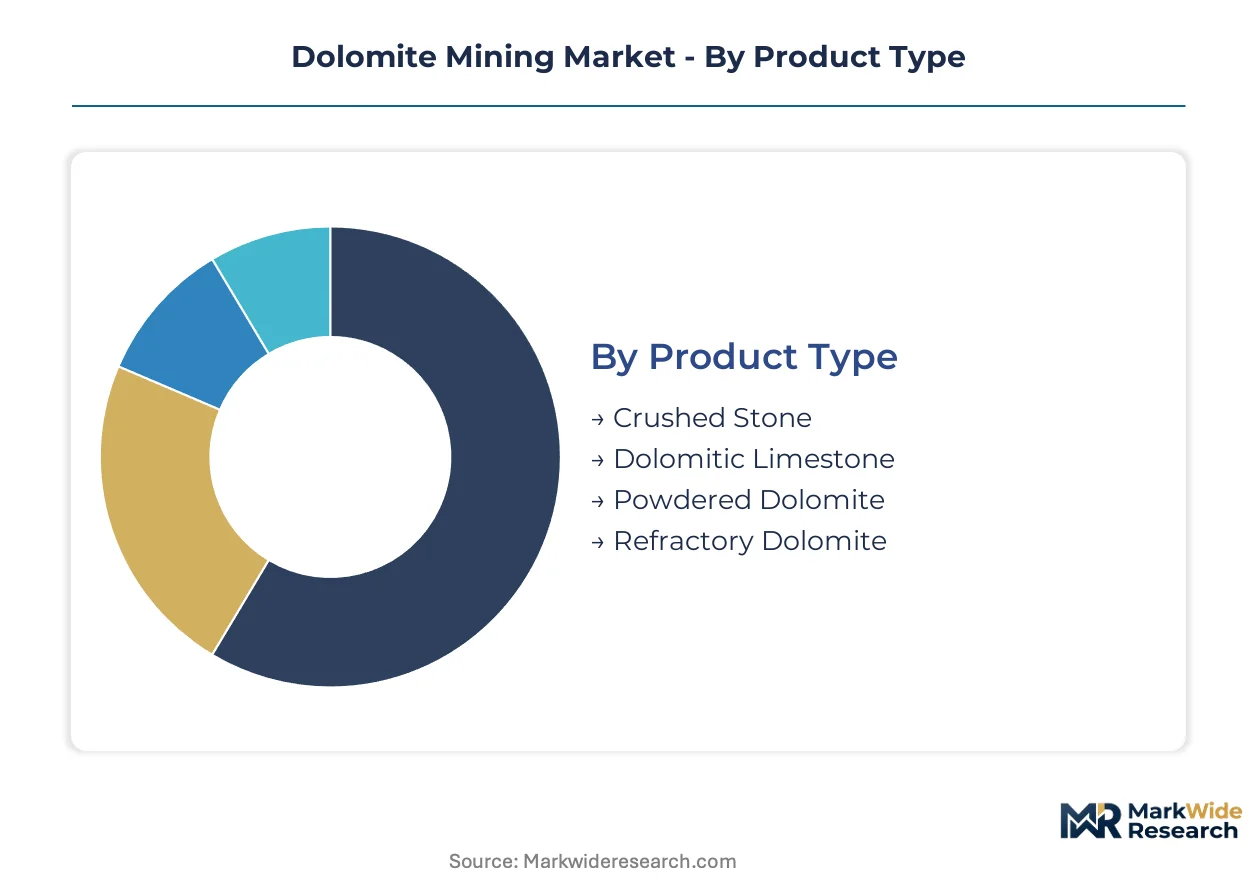
Dolomite mining operators configure product portfolios around distinct chemistry and density specifications that dictate downstream pricing power. Segment boundaries reflect calcination intensity, particle size distribution, and impurity thresholds rather than simple geological classification.
Product Type:
After-sales service intensity varies sharply across product tiers, with refractory dolomite demanding technical support through furnace campaign planning while crushed stone requires minimal post-delivery engagement.
- Refractory Dolomite:High-density sintered material meeting strict MgO/CaO ratios and porosity limits for steel-lining duty. Demand concentrates in India's eastern steel corridor where Tata Steel and JSW commission long-term supply contracts tied to campaign life guarantees.
- Powdered Dolomite:Finely milled product with controlled particle size for chemical reactivity and soil dispersion. Glass manufacturers in Southeast Asia are expanding offtake for container glass flux applications requiring low-iron chemistry.
- Crushed Stone:Coarse aggregate for construction and road base with minimal processing beyond primary crushing. Infrastructure projects across the US Corn Belt drive seasonal demand patterns.
- Dolomitic Limestone:Intermediate carbonate rock blended for cement kiln feed and agricultural lime. Cement producers in Belgium and France source from Sibelco's controlled low-iron deposits.
Crushed stone holds the largest share; momentum sits with powdered dolomite.
End User:
Customer concentration shapes contract structures, with iron and steel producers consolidating procurement around captive quarries while agriculture maintains fragmented spot purchasing.
- Iron & Steel:Integrated mills consume calcined refractory dolomite for basic oxygen furnace and electric arc furnace linings. Asian steelmakers are backward-integrating into quarry ownership, compressing merchant miner access.
- Glass Manufacturing:Float glass and container glass producers require low-iron dolomite flux with strict particle size distribution. Belgian deposit operators are certifying output under ISO 22000 to preempt REACH registration friction.
- Construction:Road base and concrete aggregate applications consume high-volume, lower-specification material. State-level infrastructure budgets in the United States drive regional demand volatility.
- Agriculture:Soil amendment applications leverage magnesium content for crop nutrition. Variable-rate spreading technology adoption across the US Corn Belt is expanding precision application demand.
Iron and steel dominates volume; agriculture is expanding most quickly.
Application:
Application-specific chemistry requirements create distinct supply chain configurations, with steel flux demanding thermal shock resistance and glass production prioritizing optical clarity.
- Flux in Steelmaking:Dolomite reduces slag viscosity and protects refractory linings from chemical attack. EU Green Deal carbon border adjustments are favoring local calcined material over imported alternatives.
- Glass Production:Low-iron dolomite prevents coloration in clear container and float glass. Southeast Asian capacity expansion is creating dedicated supply contracts with European deposit operators.
- Soil Amendment:Magnesium supplementation for row-crop farming addresses deficiency in coarse-textured soils. Precision agriculture technology enables targeted application rates.
- Cement Industry:Dolomitic limestone serves as kiln feed and corrective material for clinker chemistry. Energy cost volatility is pressuring margins on calcined products.
Steelmaking flux holds the largest share; glass production shows steepest expansion trajectory.
Processing Technology:
Capital intensity and energy exposure differentiate processing tiers, with calcination requiring sustained fuel investment while crushing operates at lower fixed cost.
- Calcination:Thermal processing at 900-1100°C drives off carbon dioxide to produce reactive oxide forms. Flash calcination systems at Belgian and Austrian facilities are cutting fuel consumption through fluidized-bed reactor technology.
- Grinding:Milling to specified particle size distributions for powder applications. Glass-grade producers are segregating quarry output by trace element content to meet REACH disclosure requirements.
- Crushing:Primary and secondary size reduction for aggregate markets. Open-pit blasting and haulage economics favor proximity to construction demand centers.
- Aggregation:Pelletizing and briquetting for bulk handling and controlled dissolution. Agricultural applications are adopting pelletized forms for compatibility with precision spreading equipment.
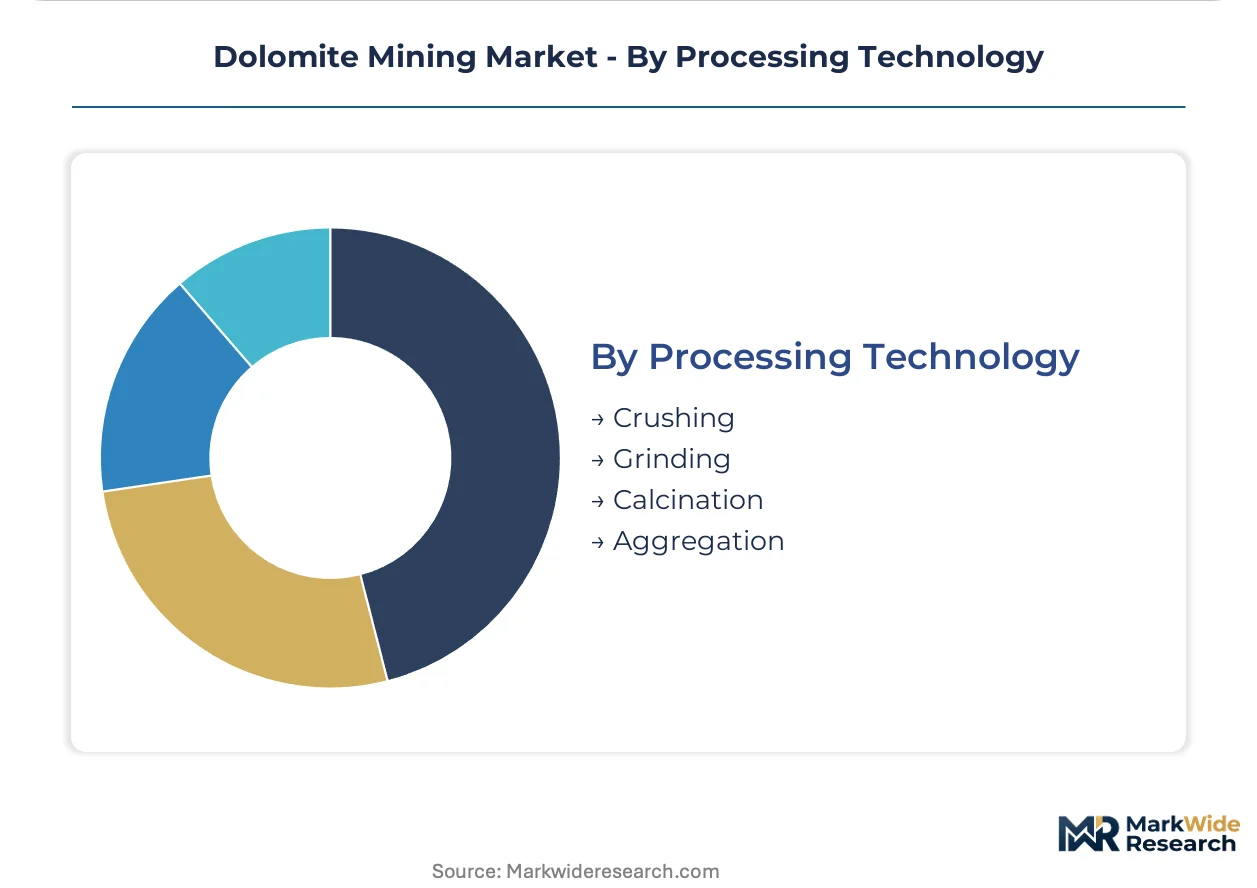
Crushing holds the largest share; calcination is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes raw dolomite primarily for steel refractory linings, while European buyers favor calcined material for glass flux and environmental compliance. Belgium and France supply low-iron deposits to Southeast Asian glassmakers. The United States distributes material across agricultural and construction channels with minimal captive quarry integration.
India
Steelmakers in Odisha and Jharkhand dominate consumption through captive quarry networks feeding integrated plants. India's CEA environmental clearances now average 24-36 months, delaying greenfield capacity. The eastern mining belt around Jamshedpur and Rourkela concentrates backward-linked supply models that compress merchant miner access.
Belgium
Glass-grade dolomite exports to Southeast Asian float glass lines drive specialized production. REACH chemical registration forces full supply chain disclosure for pharmaceutical and food-contact applications. Sibelco controls access to low-iron deposits in the Wallonia region, certifying output under ISO 22000 to preempt regulatory friction.
United States
Construction aggregate and soil amendment applications fragment demand across state-level infrastructure budgets and precision agriculture adoption. EPA mining waste standards require sediment pond retrofits and dust suppression systems that strain mid-tier operators. The US Corn Belt expands magnesium supplementation through variable-rate spreading technology.
China
Basic oxygen furnace and electric arc furnace lining demand anchors refractory consumption, though synthetic periclase substitution pressures chemical-grade offtake. The country's dual carbon goals accelerate calcination efficiency investments at coastal processors. Shandong Peninsula facilities upgrade fluidized-bed reactor technology to cut fuel intensity per tonne.
Austria
Flash calcination systems at RHI Magnesita facilities demonstrate fuel consumption reductions through shorter residence times at higher temperatures. The EU F-Gas Regulation's tighter furnace insulation requirements extend dolomite brick replacement cycles while demanding superior thermal shock resistance. Central European R&D networks sustain dominance in steel-lining solutions.
Dolomite Mining Market Key Industry Players
Capability concentration sits with integrated refractory specialists; scale advantage sits with diversified mineral processors. The market structures around three tiers: captive quarry operators serving single steelmakers, merchant miners supplying fragmented construction and agriculture channels, and vertically integrated processors controlling quarry-to-finished-product chains. Two competitive moves dominate: backward integration into captive quarry ownership by steelmakers, and calcination technology licensing to reduce energy exposure.
Among European-based processors, Imerys SA and RHI Magnesita occupy positions exemplifying the integrated refractory archetype, while Sibelco anchors the specialized glass-grade segment. These three represent contrasting strategic postures—mineral-to-finished-product control versus deposit-specific chemistry management—within a market where merchant miners face narrowing spot market liquidity.
| Leading Market Players |
|---|
| Imerys SA |
| Sibelco |
| RHI Magnesita |
| Lhoist Group |
| Carmeuse |
| Omya AG |
| Calcinor SA |
| Essel Mining & Industries Ltd |
| JFE Mineral Co Ltd |
| Others |
Cost & Logistics Intelligence
EU Green Deal carbon border adjustment exposure compresses pricing spreads between imported calcined dolomite and domestic European material while simultaneously forcing supply chain reconfiguration toward shorter-haul sourcing. This tariff-equivalent mechanism widens the premium commanded by Belgian and Austrian kiln operators over Asian merchant exporters while accelerating captive quarry consolidation among steelmakers seeking emission-accounting certainty.
Pricing Analysis
Long-term offtake contracts dominate refractory-grade transactions, with Tata Steel and JSW locking multi-year supply agreements tied to campaign life guarantees that insulate against spot volatility. Price differentiation rests on calcination intensity and trace element certification, with ISO 22000 food-safety tiering separating glass-grade premiums from construction aggregate. Cost compression in standard-grade construction material is intensifying because merchant miners compete for fragmented road-base demand against vertically integrated quarry operators. Agriculture buyers exhibit highest price sensitivity due to seasonal purchasing and variable-rate spreading equipment compatibility requirements.
Supply Chain Analysis
Export-control regimes on flash calcination reactor technology limit fluidized-bed system proliferation outside RHI Magnesita and Imerys SA's Central European facilities, constraining supply chain upgrade velocity. Geographic concentration centers on India's eastern mining belt, Belgium's Wallonia region, and Austria's refractory corridor, with raw material flows drawing from captive Odisha quarries, Sibelco's low-iron deposits, and Shandong Peninsula processors. Single-source vulnerability concentrates in glass-grade dolomite where REACH registration compliance creates switching costs. Distribution runs through dedicated bulk terminals for steel-lining contracts and construction aggregate yards for seasonal road-base demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dolomite procurement platforms are consolidating around integrated steelmaker ecosystems, with furnace performance data interoperability between lining suppliers and plant engineers creating network effects that disadvantage standalone merchant miners.
For Market Incumbents: Build captive quarry ownership moats through backward integration into Jamshedpur and Rourkela belt deposits, securing emission-accounting advantages under EU carbon border mechanisms. Consolidate calcination capacity around fluidized-bed technology licensing to cut fuel exposure per tonne. Synthetic periclase substitution in chemical applications threatens merchant-grade offtake; defend through R&D investment in dense refractory formulations extending campaign lives beyond 24 months. For New Entrants and Emerging Players: Agricultural precision application in the US Corn Belt offers the most penetrable white space, with variable-rate spreading technology adoption outpacing dedicated dolomite pellet supply. Target glass-grade certification under ISO 22000 to preempt REACH friction in Southeast Asian float glass expansion. Go-to-market leverage rests on pelletized product compatibility with precision agriculture equipment OEM distribution channels. For Investors and Strategic Acquirers: EU F-Gas Regulation furnace insulation mandates reshape the acquisition landscape toward higher-density dolomite brick specialists with thermal shock resistance IP. Long-term viability favors processors controlling quarry-to-finished-product chains in carbon-accounting jurisdictions. Watch for CEA environmental clearance timeline compression in India as the signal indicating greenfield capacity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Quarry Integration | Backward-linked supply models at Odisha steel corridors compress merchant miner spot market access. |
| Flash Calcination Licensing | Fluidized-bed reactor technology transfer cuts fuel intensity per tonne at Austrian and Belgian facilities. |
| ISO 22000 Certification | Food-safety management certification preempts REACH disclosure friction for pharmaceutical-grade output. |
| Precision Agriculture Pelletization | Pelletized dolomite compatibility with variable-rate spreaders expands US Corn Belt magnesium supplementation. |
| Performance-Based Lining Contracts | Refractory service bundling displaces independent aftermarket providers through campaign life guarantees. |
Research Approach
A spread of perspectives from steel plant procurement directors, refractory R&D leads, glass manufacturer technical buyers, and agricultural equipment OEMs converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with quarry operators and calcination plant managers against secondary validation through EU ECHA substance evaluation filings, Indian CEA environmental clearance records, and SEC disclosures from listed mineral processors. Bottom-up shipment data from construction aggregate distributors triangulated against top-down steel production forecasts across the analysis window.
Demand-supply balance modeling anchored volume projections, with segmentation across refractory grade, powdered chemical grade, and crushed construction aggregate tiers. End-use splits incorporated iron and steel flux requirements, container glass capacity expansion trajectories, and precision agriculture adoption curves. CAGRs derived from historical shipment elasticities to steel output and glass tonnage, stress-tested against energy cost volatility scenarios and synthetic periclase substitution rates.
The forecast holds incumbent behavior within observed patterns; aggressive captive quarry acquisition by Asian steelmakers or rapid flash calcination technology licensing would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Talc Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Mineral Wool Material Market
Industrial Minerals
Nepheline Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Limestone Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Global Commercial Perlite Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Barite Mining Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Global and US Inorganic Salt Market