
 High Purity Magnesium Citrate Market | 2026-2036
High Purity Magnesium Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Magnesium Citrate Market Insights
Direct-to-practitioner distribution is reshaping how high purity magnesium citrate reaches end-users in the nutraceutical channel. Jungbunzlauer leverages its fermentation-derived platform to sustain supply security across European and North American markets. Gadot Biochemical Industries anchors Dead Sea brine extraction capabilities that differentiate its cost position. Dr. Paul Lohmann specializes in custom mineral salts for pharmaceutical customers, occupying a premium tier in the value chain.
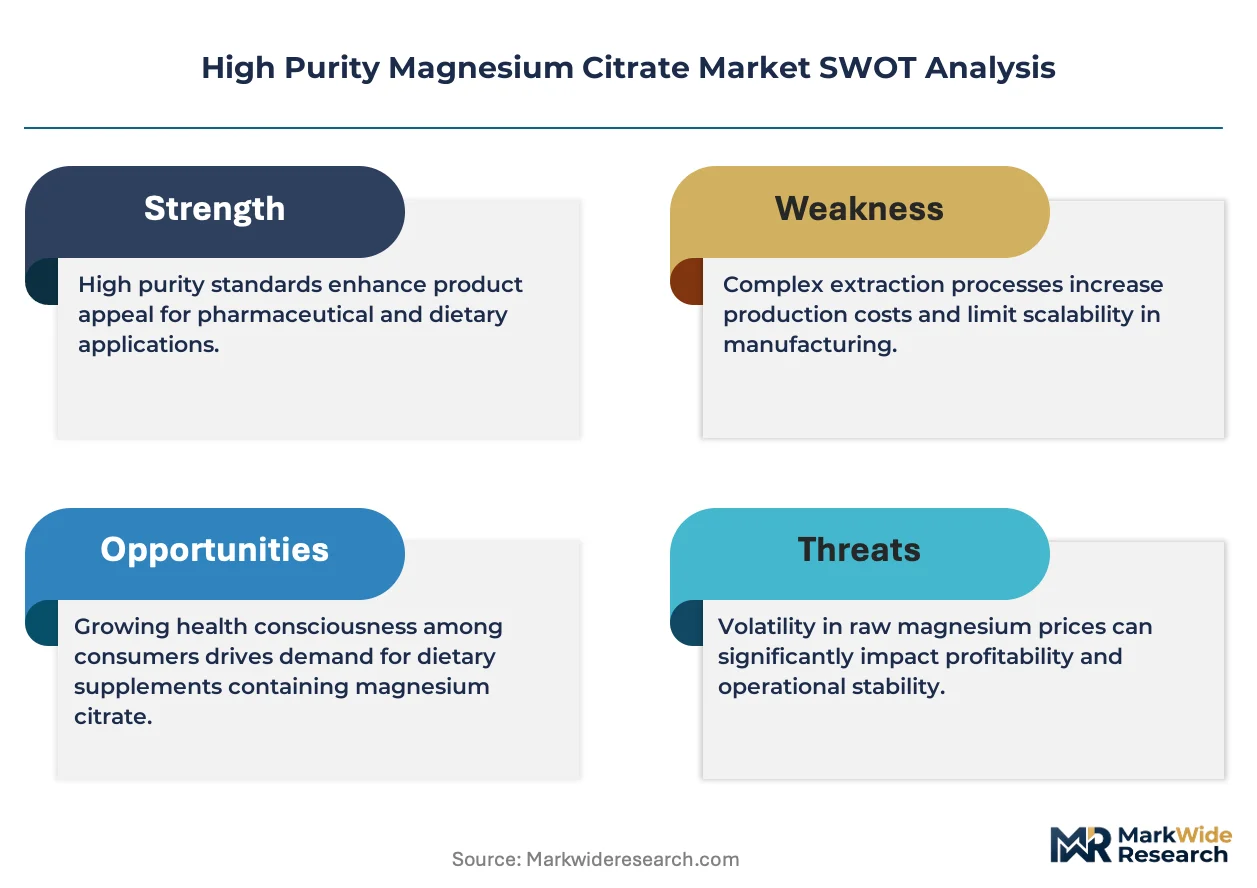
High purity magnesium citrate is a magnesium salt of citric acid, typically manufactured to exceed 99% purity through controlled neutralization and crystallization processes, and functions primarily as a bioavailable mineral source in oral dosage forms. The powder and crystal forms dominate production volumes due to their versatility in downstream tableting and encapsulation operations. Pharmaceutical-grade material commands the widest margin pool, while dietary supplements represent the fastest-expanding application segment as consumers shift toward verified-purity mineral products.
The US FDA enforces Current Good Manufacturing Practice standards for mineral excipients, while the European EMA and REACH framework govern impurity thresholds and chemical safety documentation across EU member states. These regulatory architectures elevate compliance costs for smaller producers and channel volume toward certified manufacturers with established quality management systems. Stakeholders must monitor evolving pharmacopeial monograph revisions and incoming EU packaging sustainability mandates to anticipate specification shifts and qualification requirements.
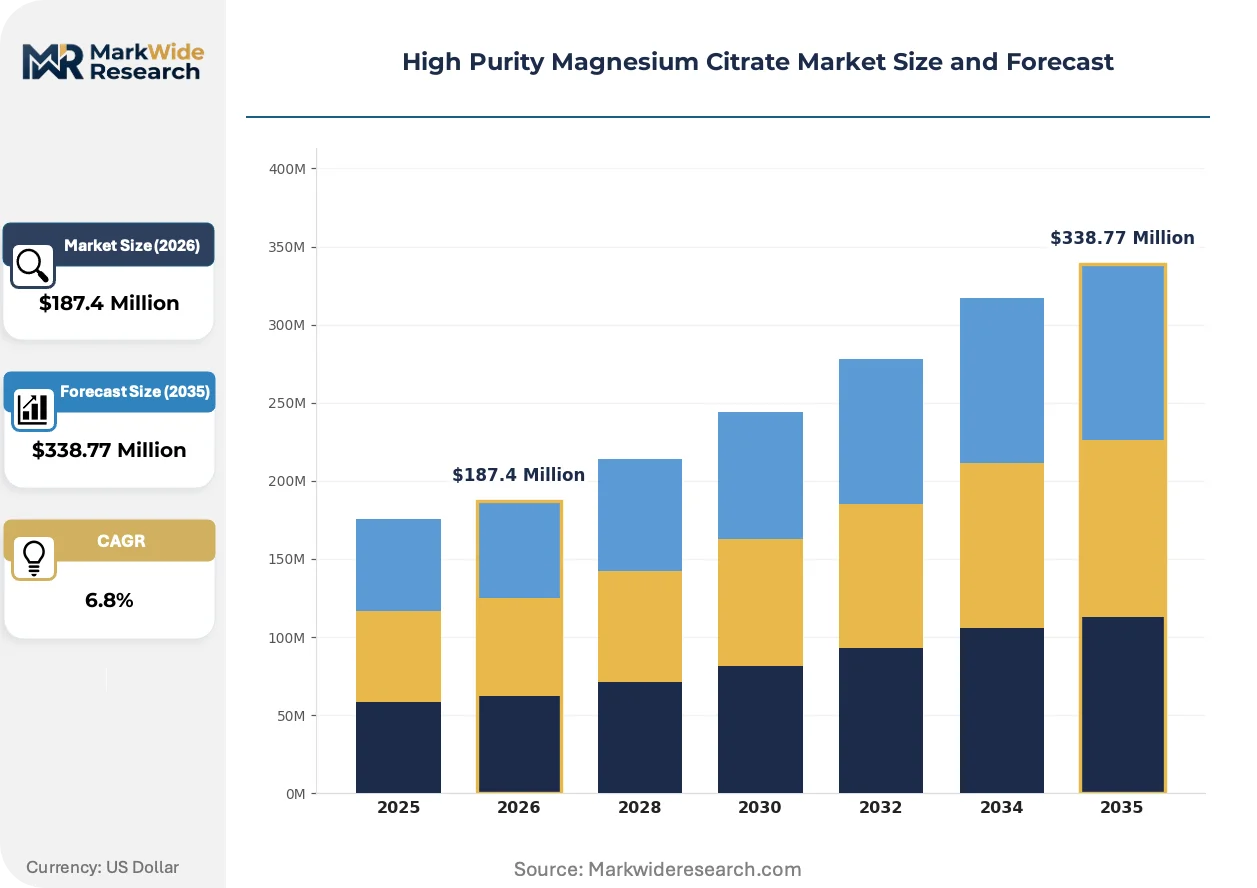
Market Dynamics
Pharmaceutical-grade purity mandates from the US FDA and European EMA are compressing supplier qualification timelines while concentrating volume toward certified manufacturers with established quality management systems.
Growth Catalysts
- REACH and EMA Purity Standards:Tightened impurity thresholds for mineral salts in nutraceuticals are disqualifying uncertified producers and redirecting contract manufacturing volume toward qualified suppliers.
- Dietary Supplement Channel:Consumer preference for verified-purity mineral products is expanding addressable demand for pharmaceutical-grade magnesium citrate in direct-to-practitioner distribution.
- Dead Sea Brine Extraction:Israel-based production clusters leverage unique mineral composition to secure cost-advantaged feedstock positions for high-purity citrate manufacturing.
Market Restraints
- Magnesium Oxide Feedstock Volatility:Energy-intensive calcination processes for magnesium oxide precursors expose producers to natural gas price swings and carbon cost pass-throughs.
- European Supply Concentration:Fermentation-derived citric acid capacity clusters in Western Europe, creating single-source dependency risks for North American formulators.
- Synthetic Magnesium Chloride Substitution:Lower-cost chloride salts compete in laxative and industrial applications, pressuring citrate pricing in non-pharmaceutical segments.
Strategic Opportunities
- India Nutraceutical Manufacturing:CDSCO and FSSAI alignment with USP monographs is enabling Indian contract manufacturers to capture overflow demand from Western qualification backlogs.
- Sustained-Release Formulation Convergence:Combination with liposomal encapsulation technologies opens prescription magnesium replacement therapy markets previously served by intravenous delivery.
- EU Packaging Sustainability Mandates:Incoming requirements for recyclable pharmaceutical packaging create first-mover advantages for suppliers with biodegradable film-compatible powder grades.
Industry Challenges
- Analytical Chemistry Talent Scarcity:ICP-MS and ion chromatography expertise for heavy metal and citrate ratio validation remains concentrated among legacy pharmaceutical service providers.
- Multi-Pharmacopeia Qualification Timelines:Simultaneous USP, EP, and JP monograph compliance extends new supplier onboarding to 18-24 months, freezing spot-market participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Magnesium Citrate Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Crystals, Tablets, Capsules Purity Grade: Pharmaceutical, Food Grade, Cosmetic, Industrial Grade Application: Dietary Supplements, Pharmaceuticals, Personal Care, Agriculture Packaging Type: Glass Bottles, Plastic Containers, Blister Packs, Pouches |
| Companies Covered | Jungbunzlauer, Gadot Biochemical Industries, Dr. Paul Lohmann, BASF, Corbion, Global Calcium, Adani Pharmachem Private Limited, Foodchem International Corporation, American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Magnesium Citrate Market Trends and Innovations
Continuous crystallization and real-time process analytical technology are displacing batch neutralization methods, compressing cycle times while tightening purity coefficient of variation.
Fermentation-derived citric acid is migrating from traditional Aspergillus niger batch processing to continuous cell-culture systems with automated metabolite feedback controls. Japanese and Korean nutraceutical formulators are adopting these feedstocks for traceability advantages. This migration from batch to continuous bioprocessing is collapsing lot-to-lot variability premiums and enabling just-in-time raw material contracts.
EMA's revised excipient risk assessment guidelines now require elemental impurity data for all mineral salts in oral dosage forms. Manufacturers must submit ICH Q3D-compliant risk assessments covering twenty-four specified elements. Dietary supplement contract manufacturers in Germany and the Netherlands are consolidating supplier panels to pre-qualified vendors with existing documentation packages.
Direct-to-clinic sampling programs are replacing traditional distributor intermediation for practitioner-channel magnesium citrate. Functional medicine networks in the United States and Canada now source verified-purity powders through platform-based procurement with certificate-of-analysis transparency. This channel compression is most advanced in California and Ontario, where integrative health practice density supports minimum order consolidation.
High Purity Magnesium Citrate Market Segmentation
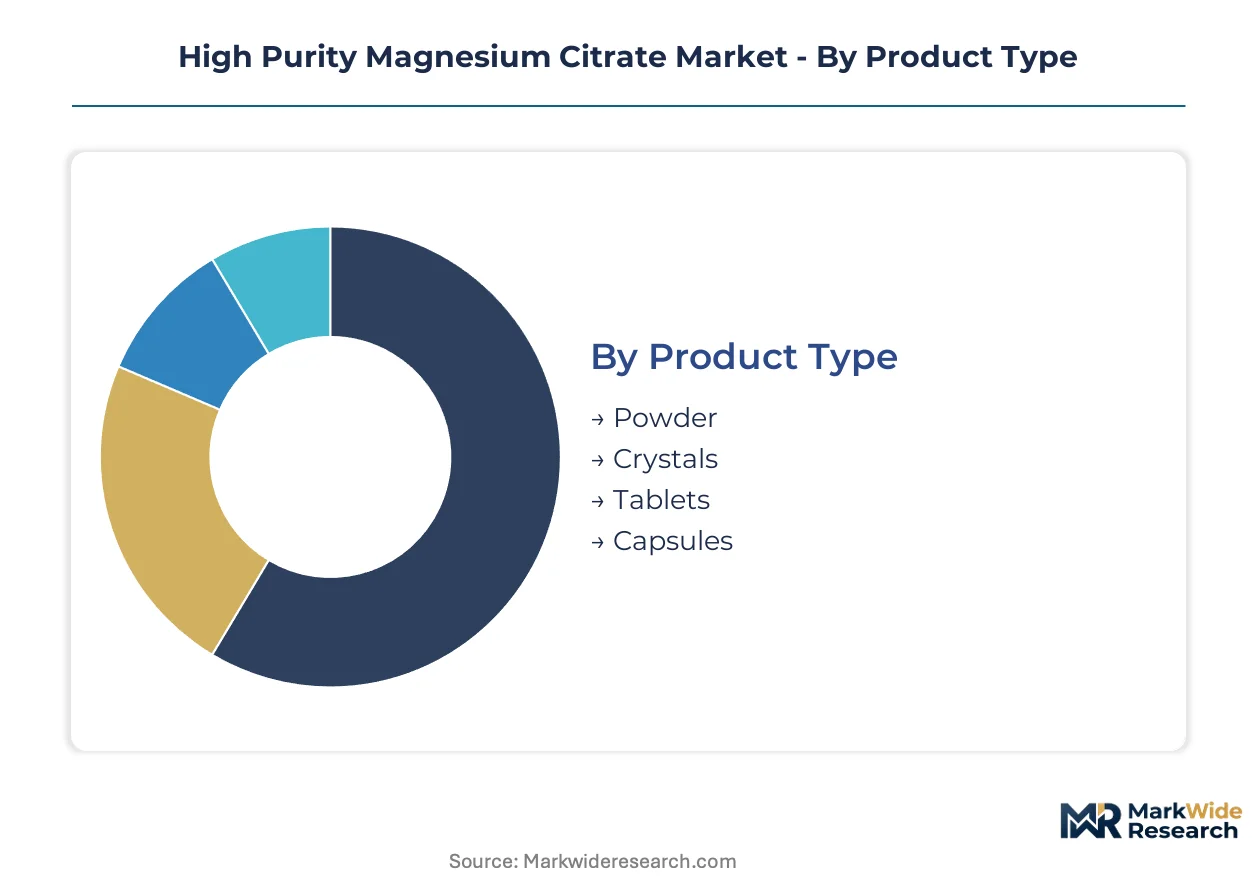
High purity magnesium citrate serves divergent end-use specifications that demand distinct physical forms, purity thresholds, and packaging configurations. Segmentation reveals how pharmaceutical-grade powder commands premium positioning while dietary supplement capsules drive volume expansion. Understanding these category boundaries enables suppliers to align production assets with qualification requirements and margin structures.
Product Type:
Powder and crystal formats anchor pharmaceutical manufacturing, while tablets and capsules address finished dosage convenience in consumer channels.
- Powder:Free-flowing granular material with controlled particle size distribution serves bulk pharmaceutical compounding and contract manufacturing operations. US FDA Current Good Manufacturing Practice standards for mineral excipients concentrate procurement toward certified powder suppliers with established quality management systems.
- Crystals:Recrystallized magnesium citrate with defined morphology and dissolution profile supports sustained-release formulation development. European EMA pharmacopeial monograph compliance requirements channel crystal demand toward manufacturers with ICH Q3D elemental impurity documentation.
- Tablets:Direct-compression ready granules enable high-speed tableting for practitioner-channel mineral supplements.
- Capsules:Pre-milled powder with uniform bulk density facilitates encapsulation in vegetarian and gelatin shell formats.
Established volume favors powder; emerging adoption favors capsules.
Purity Grade:
Regulatory jurisdiction determines acceptable impurity thresholds, creating tiered qualification barriers that stratify supplier access.
- Pharmaceutical:Material exceeding USP and EP monograph specifications with validated heavy metal and microbial limits supports prescription and OTC oral dosage forms. REACH and EMA tightened impurity thresholds for mineral salts disqualify uncertified producers and redirect contract manufacturing volume toward qualified suppliers.
- Food Grade:Compliant with FSSAI and national food safety codes for fortified beverages and functional foods.
- Cosmetic:Low-irritant specification for topical magnesium therapy and personal care formulations.
- Industrial Grade:Technical specification for chemical synthesis and non-consumable applications.
Pharmaceutical commands margin concentration; food grade exhibits steepest expansion trajectory.
Application:
End-use differentiation separates verified-purity nutraceutical demand from commodity mineral salt substitution.
- Dietary Supplements:Bioavailable magnesium source in direct-to-practitioner distribution and platform-based procurement channels. Consumer preference for verified-purity mineral products is expanding addressable demand for pharmaceutical-grade material in functional medicine networks.
- Pharmaceuticals:Active pharmaceutical ingredient and excipient in oral magnesium replacement therapies.
- Personal Care:Transdermal and bath product applications leveraging citrate solubility.
- Agriculture:Foliar feed and soil amendment applications with lower purity tolerance.
Dietary supplements gain share fastest; pharmaceuticals defend premium positioning.
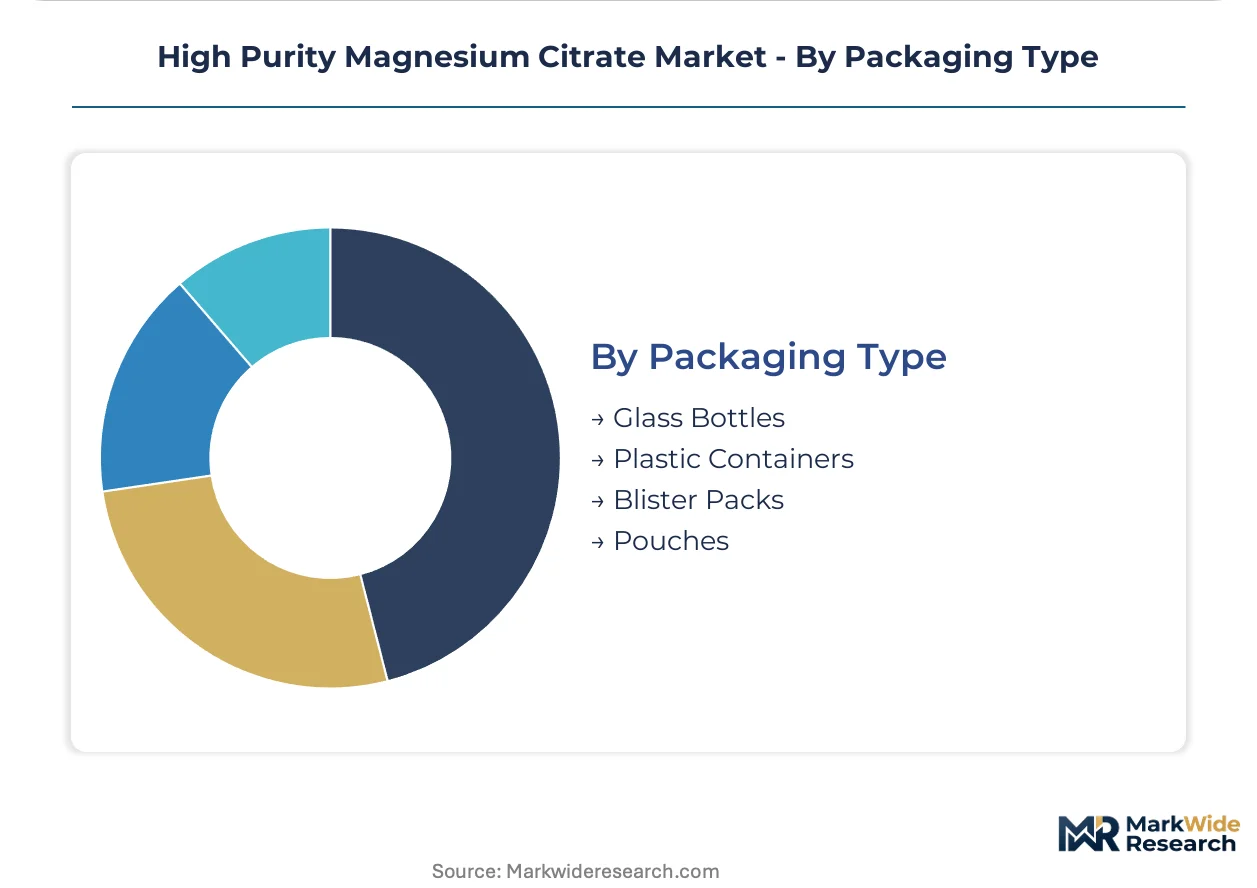
Packaging Type:
Material selection balances chemical stability, regulatory compliance, and incoming sustainability mandates.
- Glass Bottles:Inert barrier protection for hygroscopic powder in pharmaceutical and laboratory settings.
- Plastic Containers:HDPE and PET formats for bulk supplement powder with child-resistant closure options.
- Blister Packs:Unit-dose aluminum-PVC configurations for clinical trial materials and practitioner sampling programs.
- Pouches:Flexible film with moisture barrier for single-serve and travel-format magnesium products.
Glass dominates qualification-sensitive supply; pouches climb fastest in direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Western Europe's dominance in citric acid feedstock logistics, while the Houston Ship Channel anchors North American import dependency for magnesium oxide precursors.
United States
Functional medicine networks in California and Ontario drive practitioner-channel demand for verified-purity powders. The FDA enforces Current Good Manufacturing Practice standards for mineral excipients, compressing supplier qualification timelines. New Jersey and Pennsylvania host contract manufacturing clusters where platform-based procurement with certificate-of-analysis transparency is replacing traditional distributor intermediation.
Germany
Dietary supplement contract manufacturers in Germany consolidate supplier panels to pre-qualified vendors with existing ICH Q3D documentation packages. The EMA's revised excipient risk assessment guidelines now require elemental impurity data for all mineral salts in oral dosage forms. The Cologne-Düsseldorf corridor anchors fermentation-derived citric acid capacity serving pharmaceutical-grade magnesium citrate production.
Israel
Dead Sea brine extraction capabilities differentiate cost positions for high-purity citrate manufacturing in the nutraceutical channel. The country's national pharmaceutical regulator aligns with USP and EP monograph specifications for export markets. Production clusters near the Dead Sea leverage unique mineral composition to secure feedstock advantages for contract manufacturing hubs in North America.
India
CDSCO and FSSAI alignment with USP monographs enables Indian contract manufacturers to capture overflow demand from Western qualification backlogs. The country's food safety regulator enforces national food safety codes for fortified beverages and functional foods. Maharashtra and Gujarat host emerging nutraceutical manufacturing capacity targeting direct-to-practitioner distribution channels in North America.
Japan
Japanese nutraceutical formulators adopt continuous cell-culture citric acid feedstocks for traceability advantages in premium mineral salt applications. The PMDA governs pharmaceutical-grade material specifications for oral dosage forms. The Kanto region around Tokyo anchors demand for sustained-release formulation development combining magnesium citrate with liposomal encapsulation technologies.
High Purity Magnesium Citrate Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain, supplying certified mineral salts to finished dosage manufacturers. The market structure concentrates around fermentation-derived citric acid platforms and brine extraction specialists, with tiered qualification barriers stratifying supplier access. Three archetypes dominate: integrated bioprocessors controlling citric acid-to-citrate conversion, Dead Sea mineral extractors leveraging geographic feedstock advantages, and custom mineral salt houses serving pharmaceutical customers. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure backward integration into citric acid supply.
Within the integrated bioprocessor tier, Jungbunzlauer and Corbion occupy positions exemplifying fermentation-derived platform sustainability across European and North American markets. Among brine extraction specialists, Gadot Biochemical Industries anchors geographic differentiation through Dead Sea mineral capabilities. On the custom pharmaceutical tier, Dr. Paul Lohmann represents premium mineral salt specialization for validated customer applications. These three companies illustrate how feedstock control, geographic endowment, and customer intimacy define competitive positioning in high-purity magnesium citrate supply.
| Leading Market Players |
|---|
| Jungbunzlauer |
| Gadot Biochemical Industries |
| Dr. Paul Lohmann |
| BASF |
| Corbion |
| Global Calcium |
| Adani Pharmachem Private Limited |
| Foodchem International Corporation |
| American Elements |
| Others |
Pricing and Supply Chain Analysis
The Port of Rotterdam's chemical handling infrastructure anchors European citric acid feedstock logistics, and its freight cost dynamics concentrate supply-side power among fermentation-derived platform operators while forcing three-tier price differentiation across pharmaceutical, food-grade, and industrial customer tiers.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade material commanding premium positioning from food-grade and industrial specifications. Price differentiation rests on USP/EP certification status and lot-to-lot variability guarantees, with certified suppliers extracting margin premiums from contract manufacturers facing FDA and EMA qualification mandates. Cost compression in industrial-grade segments intensifies because synthetic magnesium chloride substitutes erode citrate pricing power outside pharmaceutical applications. Dietary supplement contract manufacturers exhibit highest price sensitivity due to platform-based procurement transparency, while prescription drug formulators prioritize supply security over unit economics.
Supply Chain Analysis
Extended payment terms from Dead Sea brine extractors and fermentation platform operators compress working capital cycles for downstream formulators. Geographic supply concentrates in Germany, Israel, and India, with citric acid feedstock drawing from Western European fermentation capacity and magnesium oxide precursors sourcing from Chinese and Turkish calcination operations. Single-source vulnerability runs through the Cologne-Düsseldorf citric acid corridor, where Aspergillus niger and continuous cell-culture capacity clusters expose North American formulators to transatlantic logistics disruption. Distribution runs through direct-to-practitioner platforms in California and Ontario, bypassing traditional mineral salt distributors for verified-purity procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous crystallization and real-time process analytical technology disruption collapses batch neutralization economics, while EMA's revised ICH Q3D elemental impurity mandates compress supplier qualification timelines to 18-24 months.
For Market Incumbents: Pre-empt synthetic magnesium chloride substitution in laxative applications by securing backward integration into Dead Sea brine extraction or fermentation-derived citric acid platforms. Defend pharmaceutical-grade margin pools through ICH Q3D documentation package pre-positioning ahead of EMA excipient risk assessment enforcement. Capacity addition in India captures overflow demand from Western qualification backlogs. For New Entrants and Emerging Players: Build out liposomal encapsulation technology partnerships to access sustained-release magnesium replacement therapy markets previously served by intravenous delivery. White-space concentration sits with Indian contract manufacturers achieving CDSCO-FSSAI alignment with USP monographs. Direct-to-practitioner platform integration offers the most penetrable go-to-market angle in California functional medicine networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized mineral salt divisions lacking pharmaceutical certification infrastructure. Long-term viability frames around feedstock control and pharmacopeia qualification moats rather than commodity scale. Watch for sustained-release formulation convergence with prescription magnesium therapies as inflection signal toward premium mineral salt demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citric Acid Supply | Fermentation platform control secures supply security against European single-source concentration risks. |
| ICH Q3D Documentation Package Investment | Pre-qualified vendor status captures EMA-mandated contract manufacturing consolidation in Germany and Netherlands. |
| Direct-to-Practitioner Platform Partnership | Certificate-of-analysis transparency aligns with California and Ontario integrative health procurement patterns. |
| Liposomal Encapsulation Technology Licensing | Sustained-release convergence opens prescription magnesium therapy markets beyond intravenous delivery. |
| India Manufacturing Footprint Expansion | CDSCO-FSSAI alignment with USP monographs enables capture of Western qualification backlog overflow. |
Research Methodology
A standing panel of mineral salt procurement managers, pharmaceutical quality assurance directors, contract manufacturing executives, and functional medicine practitioners provided ongoing calibration across primary interview cycles and secondary source validation. Stakeholder input combined with FDA 483 inspection observations, EMA excipient risk assessment guidelines, USP and EP monograph revisions, customs trade data for citric acid and magnesium oxide flows, and SEC filings from disclosed mineral salt suppliers. Bottom-up volume modeling and top-down value triangulation cross-validated segment-level outputs.
Scenario-bracketing framed demand projections across pharmaceutical-grade, food-grade, and industrial purity tiers, with powder, crystal, tablet, and capsule form factors modeled separately. The analytical framework incorporated end-use segmentation across dietary supplements, pharmaceuticals, personal care, and agriculture, with regional regulatory clusters distinguishing US FDA, European EMA, Indian CDSCO-FSSAI, and Japanese PMDA compliance pathways. CAGRs derived from elasticity-adjusted volume buildups and price trajectory assumptions anchored in feedstock cost dynamics.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Dead Sea brine extractors or rapid Indian contract manufacturing scale-up would shift outcomes beyond modeled ranges. Macroeconomic volatility in natural gas pricing for magnesium oxide calcination, pharmacopeial monograph revision timing, or technological substitution toward magnesium chloride would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High Purity Benzenethiol Market
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market
High-Value Chemicals
Ultra-High Purity Materials Market
High-Value Chemicals
Global High Temperature Thermoplastics (Htts) Market
High-Value Chemicals
High Purity Aluminum Hydroxide Market
High-Value Chemicals
Hydroxyethyl Urea Market
High-Value Chemicals
Global High Potency Apis /HPAPI Market
High-Value Chemicals
Hydroxylamine Sulfate Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
High-Silica Zeolite Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
Hydroxycarboxylic Acids Market
High-Value Chemicals
High Molecular Weight Polyisobutylene Market
High-Value Chemicals
Sodium Methyl P-Hydroxybenzoate Market
High-Value Chemicals
Global Epichlorohydrin (ECH) Market
High-Value Chemicals
Asia-Pacific Hydrogen Bromide Market