
 Calcined Anthracite Market | 2026-2036
Calcined Anthracite Market Size, Share, and Industry Trends Forecast 2026-2036
Calcined Anthracite Market Intelligence
The EU Carbon Border Adjustment Mechanism is realigning the cost-of-entry calculus for calcined anthracite suppliers exporting into European steel and aluminum sectors. Asbury Carbons leverages its North American mining and calcination infrastructure to sustain long-term supply contracts with electrode manufacturers. Elkem ASA anchors its competitive position through integrated operations spanning Norwegian anthracite sourcing to specialized carbon product finishing.
Calcined anthracite consists of anthracite coal thermally treated at temperatures exceeding 1,200°C to drive off volatile matter, yielding a fixed carbon content typically above 90% with minimal ash and sulfur residues. This material serves primarily as a carbon raiser in steelmaking, a recarburizing agent in foundries, and a filler component in electrode paste and cathode block formulations for aluminum smelting. Granular and powder grades dominate volume flows into electrode manufacturing, where structural demand ties directly to global aluminum smelter expansion schedules. Steel production applications command mature, stable offtake with thinner margin pools, while aluminum smelting segments offer faster growth trajectories linked to Middle Eastern and Southeast Asian greenfield smelter projects.
EPA emissions standards under the Clean Air Act shape domestic calciner operating permits and stack compliance costs in the United States, while REACH registration requirements govern chemical safety documentation for European material imports. China's MEE enforces dual carbon goals that constrain high-emission anthracite calcination capacity additions in Shanxi and Ningxia provinces. Stakeholders must monitor regulatory divergence between carbon-intensity accounting methodologies in Brussels and Beijing, as mismatching compliance frameworks threaten to fragment tradable supply zones and reroute bulk material flows across alternative corridors.
Market Dynamics
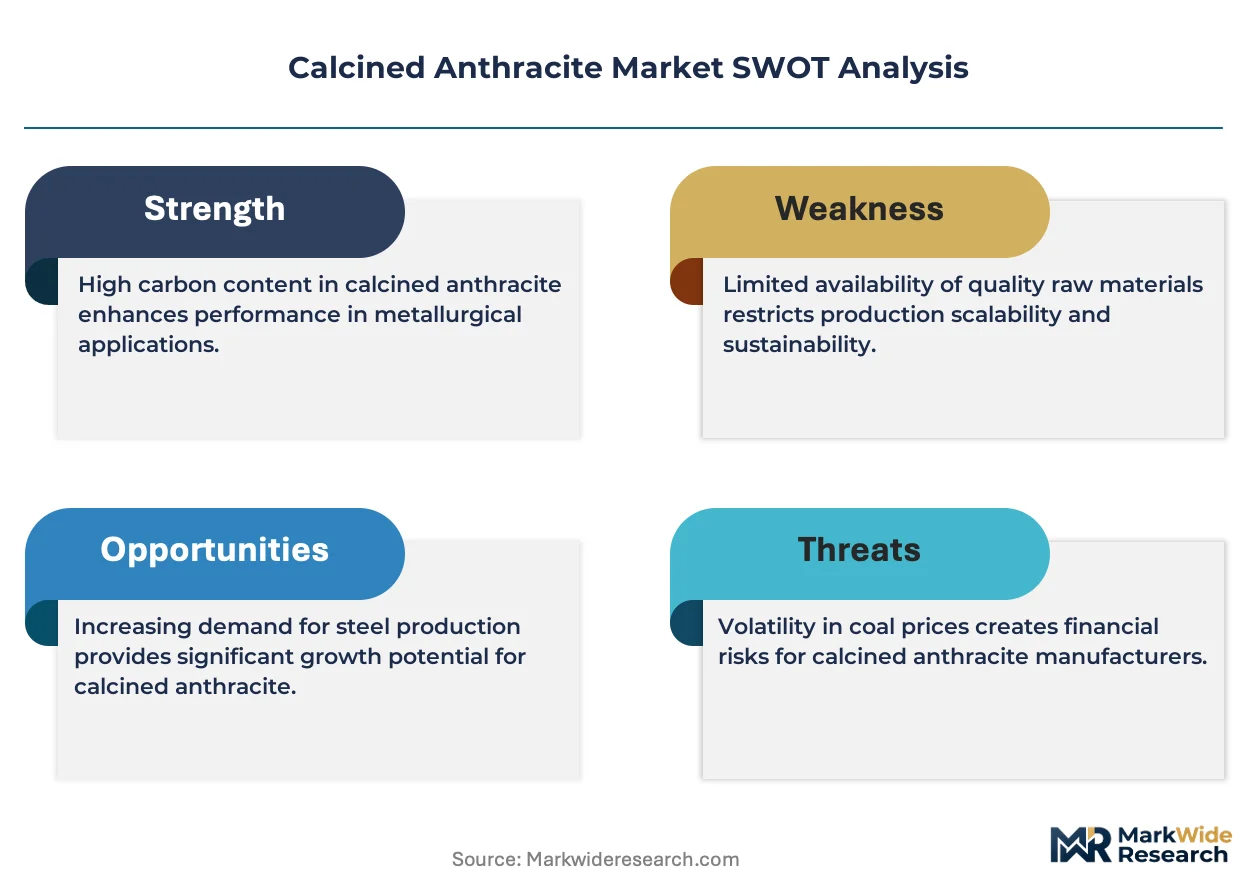
Electric arc furnace capacity expansions in steel-producing clusters are restructuring procurement volumes for high-purity carbon reductants, while regulatory carbon-accounting frameworks fragment cross-border trade corridors.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Import compliance costs for carbon-intensive materials are redirecting supply contracts toward verified low-emission calciners in North America and Scandinavia.
- Yangtze River Delta industrial cluster:Concentrated aluminum smelter and specialty steel investments in this Chinese corridor sustain granular-grade offtake for electrode paste formulations.
- Petroleum coke substitution:Volatile sulfur content in delayed coke is accelerating foundry switching to low-sulfur calcined anthracite for ductile iron production.
Market Restraints
- Anthracite feedstock concentration:Premium low-volatile seam deposits concentrate in northeastern Pennsylvania and Vietnam, exposing calciners to single-source geological risk.
- Energy cost asymmetry:Natural gas and electricity price differentials between North American and European calcination facilities compress margin parity for EU-based suppliers.
- Graphitized petroleum coke competition:Higher-carbon alternatives in ultra-high-power electrode applications displace standard calcined anthracite in premium smelter segments.
Strategic Opportunities
- India PLI scheme for specialty steel:Domestic capacity incentives for electric arc furnace producers create captive demand for imported carbon raisers with certified traceability.
- Middle Eastern greenfield smelters:Aluminum electrolysis projects in Saudi Arabia and the UAE require cathode block fillers with specific thermal expansion profiles.
- Biocarbon blending R&D:Torrefied biomass co-calcination with anthracite is expanding into pilot-scale production for scope-3 emissions reduction claims.
Industry Challenges
- REACH registration timelines:European chemical safety dossier preparation for imported carbon materials extends supplier qualification cycles by 18-24 months.
- Rotary kiln refractory degradation:High-temperature calcination above 1,300°C accelerates lining replacement frequency, forcing unplanned maintenance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcined Anthracite Market |
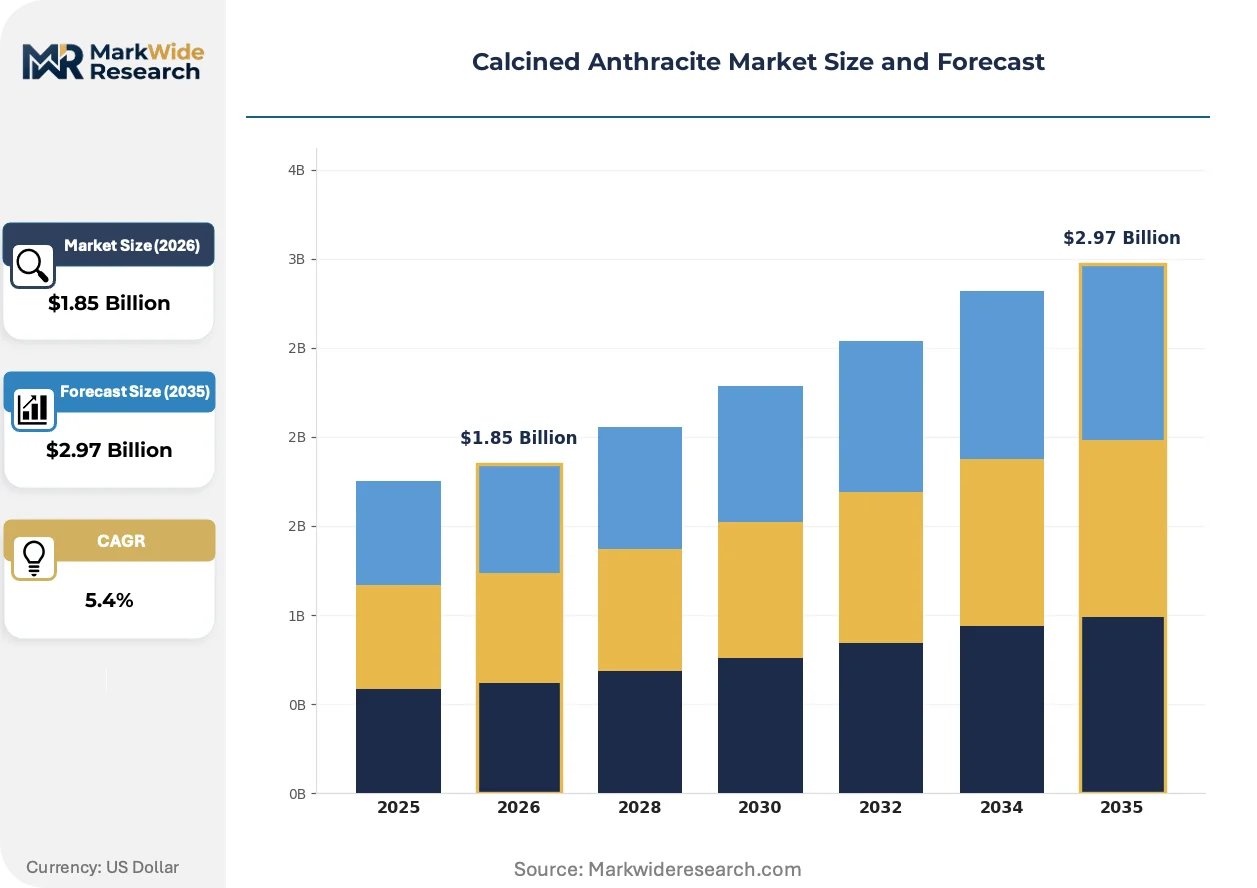
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Lumps, Micronized Application: Electrode Manufacturing, Steel Production, Aluminum Smelting, Water Treatment End User: Metal Industry, Chemical Industry, Cement Industry, Energy Sector Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | RESORBENT s.r.o., Henan Star Metallurgy Material Co. Ltd, Asbury Carbons, Dev Technofab Ltd., Kingstone Group, Elkem ASA, Black Diamond, Sojitz JECT Corporation, Rheinfelden Carbon Products GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcined Anthracite Market Strategic Shifts & Innovations
Carbon intensity verification protocols and alternative reductant R&D are compressing traditional specification boundaries while opening premium tiers for traceable supply chains.
Flash calcination systems using plasma arc heating are expanding into commercial-scale deployment for anthracite upgrading. German electrode manufacturers pilot these units to achieve sub-0.5% volatile matter residuals in half the residence time of rotary kiln methods. The technology is expanding into retrofit opportunities at existing Shanxi Province facilities facing MEE emissions intensity targets.
China's MEE dual carbon enforcement is tightening operating permits for calcination capacity additions in Ningxia and Shanxi provinces. Stack monitoring requirements and carbon intensity benchmarks now condition license renewals on verified renewable energy procurement or co-generation heat recovery installation. Domestic suppliers are responding by consolidating operations at integrated mine-calciner complexes with captive power generation.
Long-term offtake contracting with fixed carbon purity bands is displacing spot-market purchasing for aluminum smelter cathode block programs. Smelters in the Ruhr industrial region and Emirates Global Aluminum now specify multi-year supply agreements with quarterly carbon footprint reporting. This pattern is most visible in Middle Eastern and German aluminum corridors where scope-3 disclosure requirements flow downstream from automotive OEM sustainability mandates.
Calcined Anthracite Market Segmentation
Calcined anthracite procurement decisions hinge on carbon purity thresholds, thermal expansion coefficients, and sulfur content limits that vary sharply across electrode manufacturing, steel recarburization, and aluminum smelting applications. Specification mismatches between granular grades for cathode blocks and powder grades for electrode paste trigger costly reformulation failures.
Product Type:
Buyers prioritize particle size distribution and fixed carbon consistency when selecting calcined anthracite grades for specific furnace operations.
- Granular:Sized between 1-10mm with fixed carbon content exceeding 90%, this grade dominates cathode block formulations for aluminum smelters. Demand concentrates in the Yangtze River Delta industrial cluster where Emirates Global Aluminum and domestic Chinese smelters specify thermal expansion profiles below 2.5% at 1000°C. The EU Carbon Border Adjustment Mechanism is redirecting procurement toward verified low-emission calciners in Norway and Pennsylvania.
- Powder:Finely ground below 0.5mm for electrode paste binder systems, this segment serves electric arc furnace electrode manufacturing. German and Chinese electrode producers in the Ruhr industrial region and Shanxi Province account for concentrated offtake. Flash calcination systems using plasma arc heating are penetrating this segment to achieve sub-0.5% volatile matter residuals.
- Lumps:Retains natural anthracite structure for high-temperature furnace lining applications where mechanical stability matters.
- Micronized:Ultra-fine grinding below 50 microns serves specialty carbon products and precision filler applications in advanced materials.
Volume sits with Granular; growth tilts toward Powder.
Application:
End-use specifications determine sulfur tolerance, ash limits, and carbon recovery rates that calciners must certify before contract execution.
- Electrode Manufacturing:Ultra-high-power graphite electrodes require low-ash calcined anthracite below 8% ash content for steelmaking arc furnaces. Middle Eastern greenfield smelter projects in Saudi Arabia and the UAE are expanding cathode block programs with multi-year offtake agreements. REACH registration timelines extend supplier qualification cycles by 18-24 months for European electrode producers.
- Steel Production:Recarburizing applications in electric arc furnaces and foundries demand rapid dissolution rates and predictable carbon pickup. India's PLI scheme for specialty steel is stimulating domestic capacity incentives that pull imported carbon raisers with certified traceability into Mumbai-Pune and Jamshedpur industrial corridors.
- Aluminum Smelting:Cathode block fillers require specific thermal expansion profiles and electrical resistivity specifications for electrolysis cell longevity.
- Water Treatment:Activated carbon precursor applications utilize calcined anthracite porosity for contaminant adsorption in municipal filtration systems.
Steel Production commands mature volume positions; Aluminum Smelting offers the steepest expansion trajectory.
End User:
Industry-specific carbon intensity disclosure requirements are fragmenting procurement channels across vertically integrated and merchant supply models.
- Metal Industry:Steelmakers and aluminum smelters constitute the dominant demand pool, with procurement patterns shifting toward scope-3 emissions reporting. German automotive OEM sustainability mandates flow downstream to Ruhr region smelters requiring quarterly carbon footprint documentation from calcined anthracite suppliers.
- Chemical Industry:Carbon black and specialty chemical producers utilize calcined anthracite as feedstock for high-purity carbon derivatives.
- Cement Industry:Kiln fuel substitution applications exploit anthracite's high calorific value and low volatile content for clinker production.
- Energy Sector:Battery anode material R&D programs are piloting biocarbon-anthracite blends for lithium-ion cell applications.
Procurement scale concentrates with Metal Industry; sustainability certification urgency climbs fastest in Energy Sector pilot programs.
Distribution Channel:
Supply chain configuration determines price realization and technical service intensity available to end users.
- Direct Sales:Long-term offtake contracts with fixed carbon purity bands dominate aluminum smelter and electrode manufacturer procurement. Asbury Carbons and Elkem ASA leverage integrated mine-calciner infrastructure to sustain direct relationships with specification-sensitive buyers.
- Distributors:Regional stocking points serve foundries and smaller steel producers requiring just-in-time delivery flexibility.
- Online Sales:Digital procurement platforms are penetrating standardized grade transactions for spot-market purchasers.
- Retail:Small-volume packaging serves research institutions and specialty chemical laboratories.
Contract value aggregates through Direct Sales; channel diversification accelerates through Distributors serving fragmented foundry demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for calcined anthracite clusters in steel and aluminum production corridors across China, India, and Germany, with procurement patterns increasingly shaped by carbon border regulations and smelter expansion schedules.
China
Electric arc furnace capacity additions and aluminum smelter investments in the Yangtze River Delta sustain granular-grade offtake for electrode paste formulations. The MEE enforces dual carbon goals that constrain high-emission calcination capacity additions in Shanxi and Ningxia provinces. Domestic suppliers consolidate operations at integrated mine-calciner complexes with captive power generation to meet stack monitoring requirements.
India
The PLI scheme for specialty steel stimulates domestic capacity incentives for electric arc furnace producers, pulling imported carbon raisers into Mumbai-Pune and Jamshedpur industrial corridors. BIS certification requirements govern chemical safety documentation for carbon material imports. Procurement concentrates in these western and eastern industrial belts where steelmakers specify certified traceability for scope-3 emissions reporting.
Germany
Automotive OEM sustainability mandates flow downstream to Ruhr region aluminum smelters requiring quarterly carbon footprint documentation from suppliers. REACH registration requirements extend supplier qualification cycles by 18-24 months for European electrode producers. The Ruhr industrial region anchors concentrated demand for powder-grade material in electrode manufacturing.
United States
EPA emissions standards under the Clean Air Act shape domestic calciner operating permits and stack compliance costs, particularly for facilities serving electrode manufacturers. Premium low-volatile anthracite seam deposits in northeastern Pennsylvania expose calciners to single-source geological risk. Asbury Carbons leverages North American mining and calcination infrastructure to sustain long-term supply contracts.
United Arab Emirates
Greenfield aluminum smelter projects in Saudi Arabia and the UAE require cathode block fillers with specific thermal expansion profiles. Emirates Global Aluminum specifies multi-year supply agreements with quarterly carbon footprint reporting. Demand concentrates in these Gulf smelter corridors where scope-3 disclosure requirements flow downstream from European automotive OEM mandates.
Calcined Anthracite Market Key Industry Players
North American producers anchor one tier; European and Asian specialists hold differentiated positions in purity-grade segments. The vendor base spans integrated mining-calcination operators and merchant processors serving specification-sensitive electrode manufacturers. Two strategic archetypes dominate: vertically integrated resource owners with captive anthracite supply, and toll calciners optimizing rotary kiln throughput for spot-market purchasers. Competitive moves center on backward integration into premium seam deposits and flash calcination technology licensing for emissions compliance.
Among North American resource owners, Asbury Carbons exemplifies the integrated archetype with Pennsylvania-based mining infrastructure. European specialists include Elkem ASA, which occupies a position spanning Norwegian sourcing to specialized carbon finishing. Rheinfelden Carbon Products GmbH represents the German precision-processing tier serving Ruhr region electrode manufacturers. Chinese merchant operators such as Henan Star Metallurgy Material Co. Ltd and Kingstone Group sit within the volume-driven export segment supplying Yangtze River Delta smelters.
| Leading Market Players |
|---|
| RESORBENT s.r.o. |
| Henan Star Metallurgy Material Co. Ltd |
| Asbury Carbons |
| Dev Technofab Ltd. |
| Kingstone Group |
| Elkem ASA |
| Black Diamond |
| Sojitz JECT Corporation |
| Rheinfelden Carbon Products GmbH |
| Others |
Cost & Logistics Intelligence
Specialized kiln operator concentrations in Shanxi Province and Pennsylvania's Wyoming Valley feed labor-cost differentials into a three-tier pricing structure across premium, standard, and economy levels. Carbon intensity certification premiums now separate Norwegian and North American supply from unverified Asian material, compressing margin parity for merchant calciners without captive seam access.
Pricing Analysis
Volume concentrates in long-term offtake contracts for aluminum smelter cathode block programs, while margins concentrate in powder-grade electrode paste formulations with sub-0.5% volatile matter specifications. Price differentiation hinges on fixed carbon purity bands above 90% and verified scope-3 emissions documentation, with EU Carbon Border Adjustment Mechanism compliance adding qualification premiums for European buyers. Pricing pressure stems from energy cost asymmetry between natural gas-fired North American calciners and coal-dependent Chinese facilities. Foundry recarburizing applications show highest price sensitivity due to petroleum coke substitution elasticity, whereas aluminum smelters absorb premiums for thermal expansion profile consistency.
Supply Chain Analysis
India's PLI scheme for specialty steel and Saudi Arabia's smelter localization mandates are reshaping sourcing patterns toward domestic-content-qualified suppliers. Geographic supply concentration centers on China, the United States, and Vietnam, with premium low-volatile anthracite feedstock drawing from northeastern Pennsylvania and Quang Ninh province deposits. Raw material dependencies rest on metallurgical anthracite seam access, natural gas or coal for calcination energy, and refractory linings for rotary kiln maintenance. Single-source geological risk in premium seam deposits exposes calciners to supply disruption. Distribution runs through direct sales relationships for specification-sensitive electrode manufacturers, with regional distributors serving fragmented foundry demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcined anthracite sector is becoming a vertical-integration race, with upstream control over premium Pennsylvania and Vietnamese anthracite seams emerging as the decisive margin lever.
For Market Incumbents: Cement market position through backward integration into captive mine-calciner complexes with renewable energy procurement, insulating against MEE dual carbon enforcement in Shanxi and Ningxia. Secure multi-year offtake agreements with Emirates Global Aluminum and Ruhr region smelters before REACH registration timelines extend supplier qualification windows. Flash calcination technology licensing offers a defensive moat against graphitized petroleum coke displacement in ultra-high-power electrode segments. For New Entrants and Emerging Players: EU Carbon Border Adjustment Mechanism in Europe opens a window for verified low-emission calciners with Pennsylvania or Norwegian feedstock access to capture redirecting procurement from carbon-intensive Asian supply. Target India's PLI-stimulated electric arc furnace capacity in Mumbai-Pune and Jamshedpur corridors, where BIS certification requirements have thinned qualified supplier rosters. Biocarbon blending R&D partnerships with battery anode material programs provide a differentiated entry angle against incumbent carbon raiser positioning. For Investors and Strategic Acquirers: Re-rating potential sits with integrated mine-calciner operators given carbon intensity verification protocol adoption across European and Middle Eastern aluminum corridors. Long-term viability favors resource owners with 15-20 year seam reserves and captive power generation assets over toll calciners exposed to spot anthracite volatility. Watch for MEE operating permit revocation waves in Shanxi as the inflection signal for supply consolidation and price recovery in granular-grade cathode block material.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Anthracite Mining | Secures premium low-volatile seam access in Pennsylvania and Vietnam against geological concentration risk. |
| Flash Calcination Technology Licensing | Enables sub-0.5% volatile matter production for German electrode manufacturers facing MEE emissions targets. |
| Long-term Supply Agreement with Aluminum Smelters | Locks in quarterly carbon footprint reporting commitments with Emirates Global Aluminum and Ruhr region buyers. |
| Biocarbon Blending R&D Partnership | Develops torrefied biomass co-calcination for scope-3 emissions reduction claims in battery anode applications. |
| Renewable Energy Procurement for Calcination | Satisfies MEE dual carbon license renewal conditions for Shanxi and Ningxia facility operations. |
Research Approach
Document review covered SEC filings from carbon material producers, ECHA REACH registration databases, and MEE environmental compliance disclosures, complemented by interviews with rotary kiln plant managers, electrode manufacturer procurement leads, aluminum smelter technical directors, and specialty steel foundry operations heads. Secondary validation drew from U.S. Geological Survey mineral commodity summaries, Chinese customs trade statistics, and European carbon border adjustment implementation guidance. Bottom-up capacity modeling and top-down end-use demand triangulation anchored volume estimates.
Cross-referencing historical price series against expert panel input shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type granularity, application-specific purity thresholds, end-user industry carbon disclosure requirements, and direct versus distributor channel configuration. CAGRs derived from fitted growth curves applied to aluminum smelter expansion schedules and electric arc furnace capacity buildouts. Industry-specific inputs incorporated flash calcination technology adoption curves and biocarbon blend ratio pilot results.
Caveats apply where MEE permit revocation intensity, EU Carbon Border Adjustment Mechanism enforcement timing, or petroleum coke sulfur price spreads could materially shift the outlook. Forecasts reflect assumptions about seamless supply chain adaptation to dual carbon compliance and sustained aluminum smelter investment in Middle Eastern corridors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Talc Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Seaweed Derived Minerals Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Fluorspar Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
Pyrophyllite Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Mineral Sand Market
Industrial Minerals
Slate Market
Industrial Minerals
North America Limestone Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Solar Salt Market
Industrial Minerals
Unexpanded Perlite Market