
 Anhydrite Market | 2026-2036
Anhydrite Market Size, Share, and Industry Trends Forecast 2026-2036
Anhydrite Market Analysis
The anhydrite trade is consolidating around a widening gulf between premium white anhydrite for chemical manufacturing and commodity-grade material bound for cement kilns. Saint-Gobain SA leverages its synthetic production network to supply high-purity grades for specialty chemical clients. Knauf Gips KG anchors Central European construction demand through integrated plasterboard and screed operations. OCP Group dominates North African supply corridors with phosphate-coproduct anhydrite streams.
Anhydrite denotes the anhydrous calcium sulfate mineral (CaSO₄), formed when gypsum loses crystalline water above 150°C; its 29.4% calcium oxide equivalent and near-zero moisture content make it prized as a set-controlling additive in Portland cement and as a sulfur feedstock in chemical synthesis. Natural anhydrite retains cost advantages in bulk cement applications where grinding energy is offset by raw material savings, while synthetic anhydrite from flue-gas desulfurization is gaining share in chemical manufacturing as mercury and heavy-metal specifications tighten. Construction materials applications occupy the largest volume position, though soil stabilization in highway and mining remediation projects represents the fastest-growing demand node.
EPA coal combustion residual rules and REACH chemical registration requirements in Europe are elevating trace-element testing burdens for synthetic anhydrite destined for agricultural and food-adjacent uses. China's MIIT has issued updated GB standards for industrial by-product gypsum utilization, directly shaping synthetic anhydrite qualification protocols for domestic cement producers. Stakeholders must monitor regulatory divergence between sulfur-recovery credit schemes and contaminant thresholds, as these will determine which production routes retain cost-competitive market access.
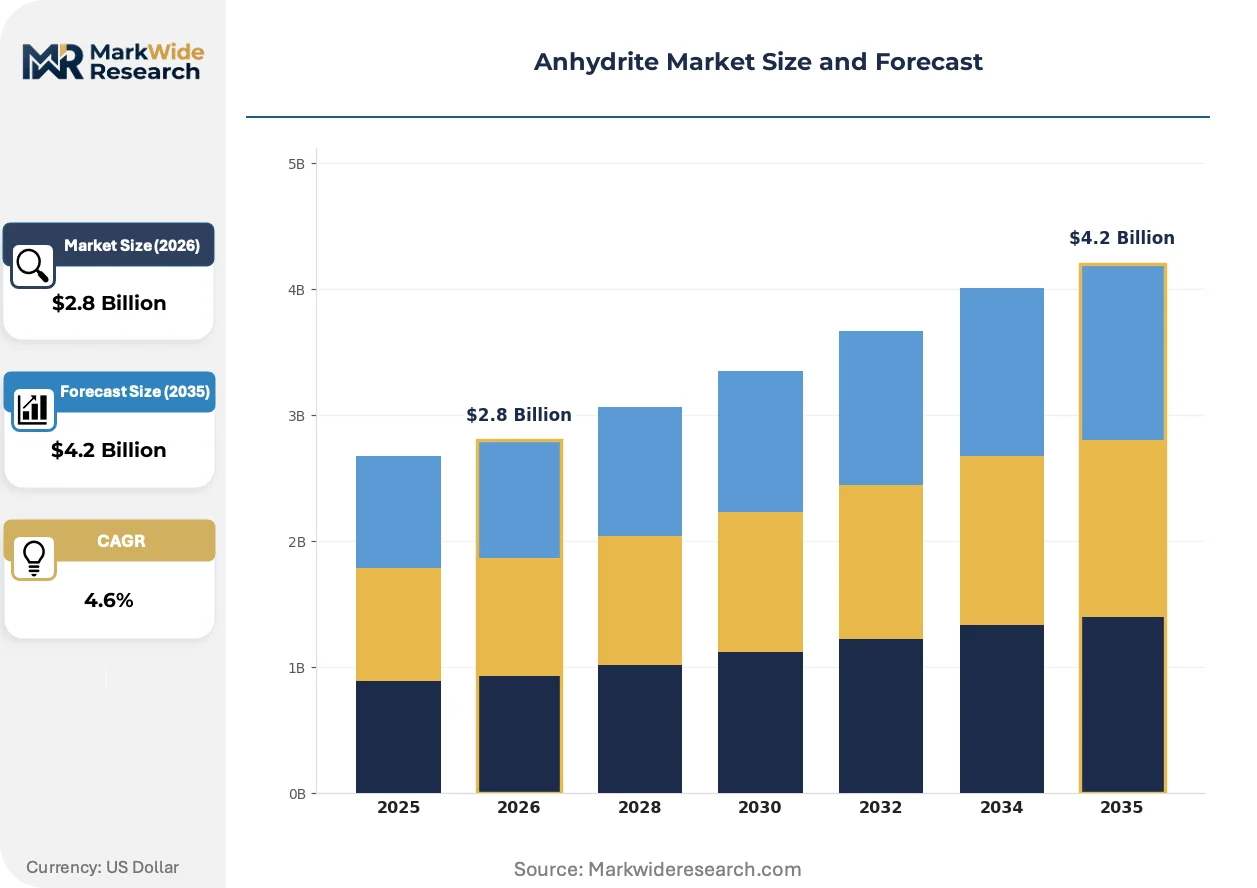
Market Dynamics
Synthetic anhydrite from flue-gas desulfurization operations is displacing natural deposits as cement producers confront tightening mercury and heavy-metal specifications in industrial feedstocks. This feedstock transition concentrates procurement power among integrated power-chemical complexes that control both sulfur recovery and anhydrite qualification.
Growth Catalysts
- REACH chemical registration:ECHA's tightening contaminant thresholds for synthetic gypsum derivatives are accelerating qualification of high-purity anhydrite streams for specialty chemical manufacturing.
- Soil stabilization demand:Highway remediation and mining reclamation projects in Australia's Pilbara and Queensland are absorbing commodity-grade anhydrite for geotechnical binding applications.
- Dual carbon goals:China's MEE sulfur-recovery credit schemes are incentivizing cement-chemical complexes to source synthetic anhydrite from captive flue-gas operations.
Market Restraints
- Natural gas price volatility:Synthetic anhydrite production depends on energy-intensive desulfurization; European gas price spikes compress margins at FGD-dependent facilities.
- Phosphate-coproduct concentration:North African supply corridors dominate merchant-grade availability, creating single-source exposure for Mediterranean cement producers.
- Natural gypsum substitution:Unfired gypsum retains cost advantages in plasterboard manufacturing where moisture tolerance permits, limiting anhydrite penetration in construction materials.
Strategic Opportunities
- India's cement expansion:BIS standards for industrial by-product utilization are opening qualification pathways for synthetic anhydrite at new clinker facilities in Rajasthan and Madhya Pradesh.
- Lithium processing feedstock:Battery-grade lithium sulfate production is testing anhydrite-derived sulfuric acid as a lower-impurity alternative to smelter acid.
- Carbon capture integration:Amine-based CO₂ capture at coal plants is converging with FGD operations to produce certified-low-carbon anhydrite for green cement claims.
Industry Challenges
- Mercury speciation expertise:FGD-derived anhydrite requires specialized analytical chemists to validate oxidation-state compliance under EPA coal combustion residual rules.
- Legacy grinding circuit retrofit:Natural anhydrite's higher grindability demands different mill configurations than gypsum, complicating feedstock switching at older cement plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anhydrite Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Anhydrite, Synthetic Anhydrite, White Anhydrite, Colored Anhydrite Application: Cement Production, Soil Stabilization, Construction Materials, Chemical Manufacturing End User: Construction Industry, Agriculture, Chemical Industry, Mining Sector Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Saint-Gobain SA, American Rock Salt Company LLC, Solvay, OCP Group, Anhydritec, USG Corporation, Holcim Group, Imerys S.A., Knauf Gips KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anhydrite Market Emerging Trajectories
Process intensification in sulfur recovery is collapsing the distinction between emissions compliance and feedstock production. Technology providers are engineering integrated FGD-anhydrite systems that convert regulatory liability into qualified chemical supply.
Flash calcination technology is consolidating control over anhydrite phase purity. This rapid thermal processing method converts FGD gypsum to soluble anhydrite in under 30 seconds, preserving reactivity for chemical synthesis. Specialty chemical manufacturers in Germany's Rhine-Ruhr cluster are adopting flash-calcined material to meet EFSA food-contact specifications. The technology is consolidating procurement around suppliers with captive calcination capacity, squeezing merchant traders.
EPA's updated coal combustion residual rules are forcing trace-element testing at the point of generation rather than destination. This shifts compliance burden to power plant operators who must certify anhydrite streams before transfer. Cement producers in the US Midwest are responding by negotiating long-term offtake agreements with utilities that have invested in inline XRF monitoring systems.
Long-term contracting is displacing spot purchasing among major cement-chemical complexes. Buyers in China's Shandong province are locking in five-year synthetic anhydrite supply with price collars tied to sulfur indexation. This behavior compresses merchant market liquidity and concentrates volume through direct utility-producer linkages. The shift is most visible in integrated industrial parks where FGD, cement kiln, and chemical acid plants share pipeline infrastructure.
Anhydrite Market Segmentation
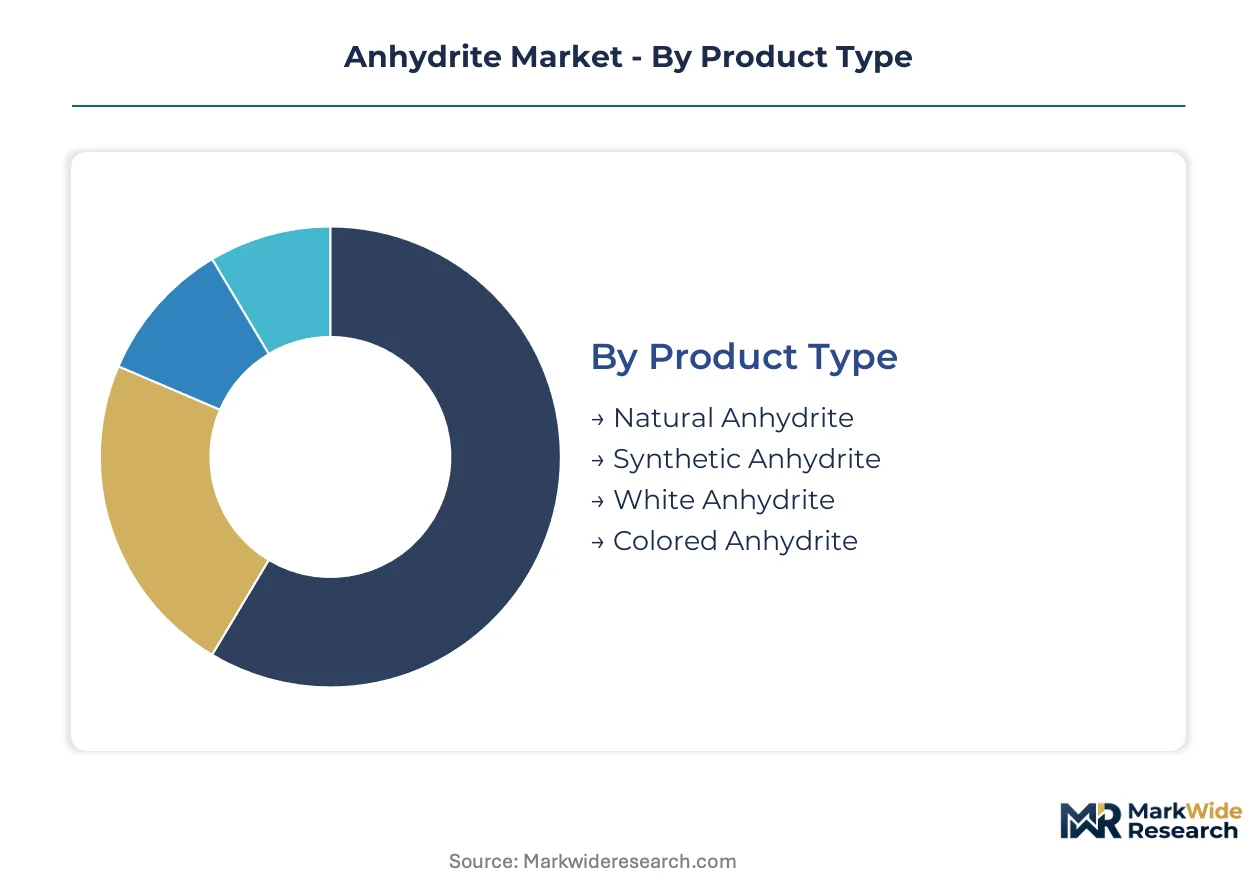
Anhydrite demand fragments across crystalline purity grades and industrial origin pathways. Specification thresholds for sulfur content, mercury limits, and grindability create distinct procurement tiers that cement producers, chemical manufacturers, and geotechnical contractors navigate differently.
Product Type:
Calcination temperature and feedstock chemistry determine phase stability, reactivity, and contaminant profiles across the four product grades.
- Natural Anhydrite:Geological deposits of anhydrous calcium sulfate formed through ancient evaporite processes retain cost advantages in bulk cement applications. China's Shandong province hosts the largest integrated mining-grinding operations supplying domestic clinker producers.
- Synthetic Anhydrite:Flue-gas desulfurization by-product streams are displacing natural deposits as EPA mercury speciation rules tighten. Power-chemical complexes in Germany's Rhine-Ruhr cluster and China's Hebei province control qualification capacity for high-purity chemical manufacturing.
- White Anhydrite:Ultra-low iron content suits specialty plaster and food-contact applications requiring EFSA compliance.
- Colored Anhydrite:Trace mineral inclusions from phosphate coproduction serve decorative aggregate and non-critical construction uses.
Mature deployment sits with Natural Anhydrite. Newer deployment is concentrated in Synthetic Anhydrite.
Application:
End-use specifications range from tolerance for trace contaminants in geotechnical binding to stringent heavy-metal ceilings in chemical synthesis.
- Cement Production:Portland cement manufacturers deploy anhydrite as a set-controlling additive replacing natural gypsum. The 29.4% calcium oxide equivalent and near-zero moisture content reduce kiln energy consumption compared to dihydrate feedstocks.
- Soil Stabilization:Highway remediation and mining reclamation projects in Australia's Pilbara absorb commodity-grade material for geotechnical binding. Volume is climbing the fastest as iron ore tailings rehabilitation expands.
- Construction Materials:Plasterboard and floor screed formulations favor unfired gypsum where moisture tolerance permits, limiting anhydrite penetration.
- Chemical Manufacturing:Sulfuric acid and lithium sulfate producers source flash-calcined synthetic grades to meet battery-grade purity specifications.
Volume leadership belongs to Cement Production. Specification intensity peaks in Chemical Manufacturing.
End User:
Procurement sophistication varies from spot purchasing by agricultural distributors to five-year offtake agreements negotiated by integrated cement-chemical complexes.
- Construction Industry:Plasterboard manufacturers and specialty screed formulators drive demand for white anhydrite grades with controlled particle size distribution.
- Agriculture:Soil amendment applications require sulfur recovery certification under China's MEE credit schemes.
- Chemical Industry:Battery-grade lithium sulfate producers are testing anhydrite-derived sulfuric acid as a lower-impurity alternative to smelter acid, with qualification protocols established in Germany.
- Mining Sector:Tailings stabilization and paste backfill operations in Western Australia source commodity-grade material through direct utility linkages.
Contract maturity is highest in Chemical Industry. Spot market liquidity concentrates in Agriculture.
Distribution Channel:
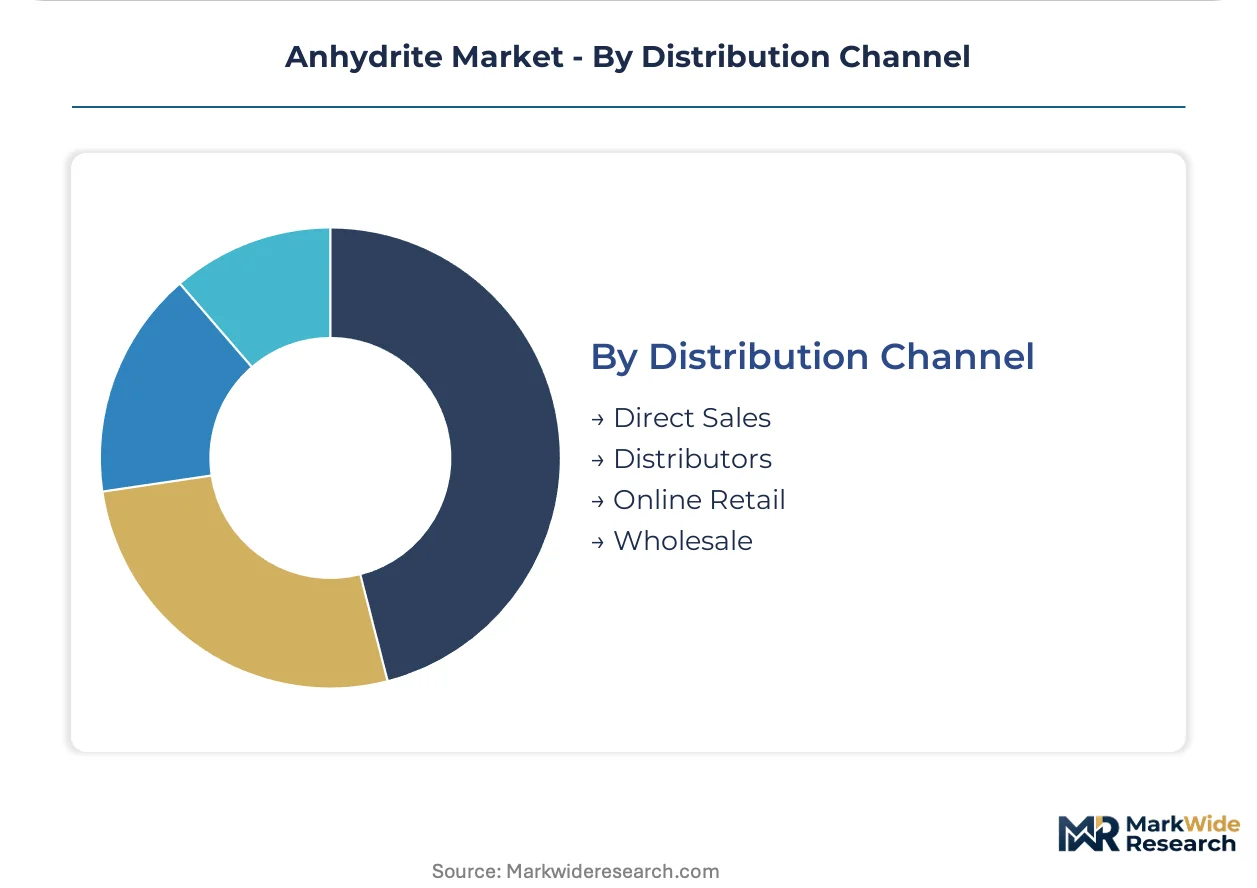
Channel selection tracks shipment scale, certification burden, and the need for technical service support in feedstock switching.
- Direct Sales:Integrated industrial parks with shared pipeline infrastructure between FGD, cement kiln, and chemical acid plants bypass intermediaries entirely. China's Shandong province exemplifies this configuration.
- Distributors:Regional merchants handle smaller lot sizes for agricultural and construction customers lacking bulk handling infrastructure.
- Online Retail:Specialty grades for laboratory and artisan plaster applications move through digital channels with certificate of analysis documentation.
- Wholesale:Bulk commodity grades for soil stabilization and mining backfill consolidate through construction material wholesalers in Queensland and Western Australia.
Pipeline-integrated Direct Sales command the largest volume flows. Distributors retain relevance in fragmented agricultural and small-scale construction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province's cement-chemical corridor anchors synthetic anhydrite procurement, with integrated FGD-utility complexes supplying clinker producers across the Bohai Rim. Procurement patterns concentrate in industrial parks where pipeline infrastructure eliminates bulk handling costs.
China
Hebei province's steel-power clusters generate synthetic anhydrite streams feeding cement kilns in Tangshan and Qinhuangdao. MIIT's updated GB standards for industrial by-product gypsum utilization mandate mercury speciation testing before transfer. Shandong's Weifang and Zibo chemical parks host flash-calcination capacity serving battery-grade sulfuric acid producers.
Germany
Rhine-Ruhr industrial complexes convert FGD residues from lignite power stations into REACH-qualified anhydrite for specialty chemical manufacturing. ECHA's tightening contaminant thresholds for synthetic gypsum derivatives accelerate qualification protocols. Leverkusen and Dormagen chemical parks source flash-calcined material for EFSA-compliant food-contact applications.
United States
Midwest cement producers in Ohio and Indiana negotiate long-term offtake agreements with utilities operating inline XRF monitoring systems. EPA's updated coal combustion residual rules shift trace-element testing burden to power plant operators at generation point. Powder River Basin coal complexes in Wyoming supply merchant-grade streams for soil stabilization contractors.
Australia
Pilbara iron ore operators absorb commodity-grade anhydrite for tailings rehabilitation and paste backfill operations. Queensland's highway remediation projects drive geotechnical binding demand through construction material wholesalers. Western Australia's mining sector sources material through direct utility linkages bypassing distributor networks.
Morocco
Khouribga and Youssoufia phosphate mining complexes dominate North African merchant-grade supply corridors with phosphate-coproduct anhydrite streams. Mediterranean cement producers face single-source exposure as OCP Group controls export logistics. Jorf Lasfar industrial port consolidates bulk shipments for European clinker manufacturers.
Anhydrite Market Vendor Landscape
Capital-heavy producers compete with asset-light traders across a market consolidating around synthetic qualification capacity. Integrated power-chemical complexes capture procurement power through captive FGD operations and inline certification systems. Three archetypes dominate: utility-linked producers with pipeline infrastructure, merchant traders dependent on spot liquidity, and specialty chemical suppliers with flash-calcination technology. Competitive moves center on backward integration into sulfur recovery assets and long-term offtake contracting that locks in volume.
Among European diversified materials groups, Saint-Gobain SA and Solvay occupy positions anchored by synthetic production networks. Knauf Gips KG exemplifies the construction-integrated archetype through captive plasterboard and screed operations. OCP Group represents the resource-extraction model with phosphate-coproduct supply dominance across North African corridors.
| Leading Market Players |
|---|
| Saint-Gobain SA |
| American Rock Salt Company LLC |
| Solvay |
| OCP Group |
| Anhydritec |
| USG Corporation |
| Holcim Group |
| Imerys S.A. |
| Knauf Gips KG |
| Others |
Supply Flow & Price Mechanics
EPA coal combustion residual rules and REACH chemical registration requirements in Europe are gating qualified supply and premium-tier pricing access for synthetic anhydrite streams. Cement producers and chemical manufacturers must secure certified-low-contaminant material to command sulfur-recovery credits and specialty chemical premiums.
Pricing Analysis
Value-based pricing anchored to sulfur-recovery credit yields and battery-grade purity specifications dominates synthetic anhydrite transactions. Three-tier pricing structure across premium, standard, and economy levels separates flash-calcined chemical grades from commodity cement feedstocks and unprocessed FGD residues. Cost compression in standard-grade material is intensifying because European natural gas price spikes erode margins at energy-intensive desulfurization facilities. Agricultural distributors exhibit the highest price sensitivity, while battery-grade lithium sulfate producers accept substantial premiums for EFSA-compliant certification.
Supply Chain Analysis
Single-source vulnerability sits with North African phosphate-coproduct corridors controlled by OCP Group, creating exposure for Mediterranean cement producers. Geographic supply concentration centers on China, Germany, and Morocco, with China's Hebei and Shandong provinces hosting integrated FGD-cement-chemical complexes. Raw material dependencies rest on flue-gas desulfurization residues, phosphate mining coproducts, and natural evaporite deposits. Regulatory restriction risk emerges from divergent mercury speciation standards across EPA, REACH, and China's MIIT frameworks. Distribution runs through pipeline-integrated direct sales in industrial parks, supplemented by construction material wholesalers for geotechnical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a consolidation play as synthetic qualification capacity and inline certification systems force merchant traders and natural deposit operators toward acquisition or exit.
For Market Incumbents: Acquire captive flue-gas desulfurization assets and inline XRF monitoring systems to lock in qualified supply streams before EPA trace-element testing rules harden. Cement-chemical complexes in China's Shandong province demonstrate how pipeline infrastructure eliminates bulk handling costs and secures five-year offtake pricing. Natural anhydrite miners face substitution threat from synthetic streams; defensive consolidation into flash-calcination technology preserves access to battery-grade sulfuric acid markets. For New Entrants and Emerging Players: Digital-channel routes for specialty laboratory and artisan plaster grades offer low-capital entry with certificate-of-analysis documentation requirements. Australia's Pilbara mining remediation sector presents the most penetrable white-space target, with commodity-grade demand climbing fastest for tailings stabilization and paste backfill operations. Partner with construction material wholesalers in Queensland and Western Australia to bypass established utility-producer linkages. For Investors and Strategic Acquirers: Long-term contracting displacement of spot purchasing is the leading indicator that merchant market liquidity will compress further, favoring integrated power-chemical complex ownership over trading archetypes. Target acquisition candidates with captive FGD operations and REACH qualification protocols already established. Watch for EPA enforcement actions on coal combustion residual compliance as the inflection signal for synthetic anhydrite supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into FGD Assets | Captive sulfur recovery secures qualified supply streams under tightening EPA mercury rules. |
| Flash Calcination Capacity Expansion | Rapid thermal processing preserves reactivity for EFSA-compliant battery-grade applications. |
| Long-term Offtake Agreement Structuring | Five-year contracts with sulfur indexation lock in volume through direct utility linkages. |
| Inline XRF Monitoring Deployment | Point-of-generation certification shifts compliance burden to power plant operators. |
| Pipeline Infrastructure Integration | Shared industrial park configuration eliminates bulk handling costs in China's Shandong corridor. |
Methodological Framework
Multi-period observation of synthetic anhydrite procurement volumes, sulfur-recovery credit pricing, and flash-calcination capacity deployment anchored the trend analysis, supplemented by interviews with cement plant managers, chemical procurement leads at specialty sulfate producers, FGD operations engineers, and construction material wholesalers. Secondary validation drew from EPA coal combustion residual filings, ECHA REACH registration databases, China's MIIT GB standard updates, and customs trade data for calcium sulfate derivatives. Bottom-up volume modeling triangulated against top-down industry capacity assessments.
Segment-weighting across product type, application, and end-user dimensions structured the analytical framework across the projection horizon. Crystalline purity grades, industrial origin pathways, and distribution channel configurations formed the core segmentation axes. CAGRs were derived from trend extrapolation of qualification protocol adoption rates and sulfur-recovery incentive program expansions. Forecast inputs incorporated natural gas price volatility assumptions and regulatory enforcement intensity scenarios for mercury speciation compliance.
The model holds under stable regulatory enforcement and continued dual carbon goal implementation in China; deviation in EPA rulemaking timelines or European energy price shocks would shift supply cost structures and qualification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Europe Limestone Market
Industrial Minerals
Potash Ores Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Inorganic Salts Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Kyanite Market
Industrial Minerals
Perlite Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
Europe Feed Minerals Market