
 United States Feed Minerals Market | 2026-2036
United States Feed Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
United States Feed Minerals Market Outlook
Modular mineral premix bundling is pivoting buyer choice away from single-ingredient purchases toward integrated nutrition packages. Cargill Inc. leverages its captive supply of base ingredients to control cost structures across the value chain. Alltech, Inc. differentiates through yeast-based mineral delivery technologies that improve bioavailability in ruminant diets. Phibro Animal Health Corporation anchors its position in trace mineral specialization for poultry and swine segments.
United States feed minerals comprise inorganic and organic compounds including calcium, phosphorus, magnesium, zinc, copper, and selenium, formulated to correct nutritional deficiencies in livestock diets and typically manufactured through crystallization, drying, and chelation processes to achieve specified particle sizes and purity grades for species-specific absorption. Macro minerals sustain the largest volume position due to baseline requirements across all livestock categories, while chelated minerals represent the fastest-expanding segment as producers seek improved mineral uptake efficiency. Trace minerals concentrate margin pools in poultry and swine applications where precise dosing delivers measurable feed conversion improvements.
The FDA enforces current Good Manufacturing Practices for animal food under FSMA, while the USDA monitors residue limits and the Association of American Feed Control Officials establishes ingredient definitions and labeling standards that collectively determine product compliance costs and market access conditions. State-level departments of agriculture in Iowa, Texas, and California administer additional inspection and licensing requirements that create localized regulatory variation. Stakeholders must monitor evolving organic mineral approval pathways and state nutrition labeling harmonization to anticipate compliance investments and positioning advantages.
Market Dynamics
Modular mineral premix bundling is consolidating buyer procurement patterns across concentrated animal feeding operations, compressing single-ingredient spot purchasing into integrated nutrition contracts that reshape supplier margin structures and inventory turnover economics.
Growth Catalysts
- FSMA Animal Food Safety Rules:The FDA's current Good Manufacturing Practices mandate standardized mineral formulation protocols, forcing feed mills to upgrade quality systems and creating pull-through demand for certified premix suppliers.
- Dairy Cattle Operations:High-producing herds in Wisconsin and California require precision mineral balancing to sustain milk yield and reproductive performance, driving consistent replenishment cycles for calcium, phosphorus, and trace mineral blends.
- Corn Belt Concentration:Iowa, Illinois, and Nebraska host the densest networks of beef feedlots and swine finishing operations, generating geographic clustering that reduces logistics costs and enables just-in-time mineral delivery models.
Market Restraints
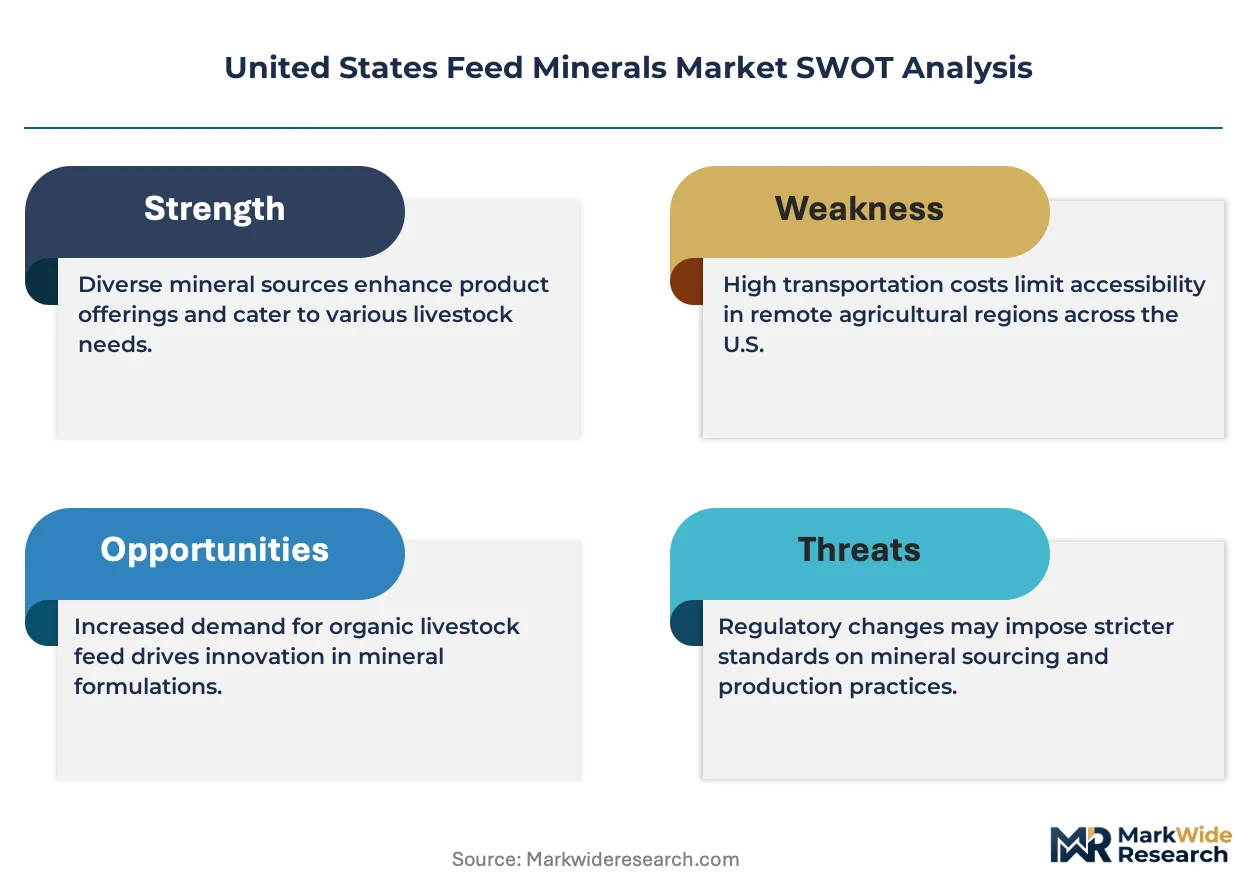
- Sulfate and Oxide Input Volatility:Copper sulfate and zinc oxide prices fluctuate with mining output and smelter capacity, compressing premix margins when base mineral costs spike without corresponding feed price adjustments.
- Midwest Production Concentration:Bulk mineral processing facilities cluster in Indiana and Ohio, creating single-source dependency risks for regional distributors when weather or labor disruptions idle production lines.
- Chelated Mineral Cost Premium:Organic mineral forms carry 40-60% price premiums over inorganic equivalents, limiting adoption in cost-sensitive poultry operations despite documented bioavailability advantages in peer-reviewed trials.
Strategic Opportunities
- Texas Panhandle Feedlot Expansion:Cattle-on-feed numbers in the Texas-Oklahoma corridor continue climbing, creating underpenetrated demand for custom mineral programs tailored to high-roughage finishing diets.
- Association of American Feed Control Officials Labeling Harmonization:Pending standardization of organic mineral ingredient definitions would reduce state-by-state registration burdens and accelerate new product commercialization timelines.
- Precision Livestock Convergence:Integration of real-time mineral intake monitoring with automated feed delivery systems enables dynamic ration adjustment, opening subscription-based mineral management service models.
Industry Challenges
- Formulation Chemist Talent Scarcity:The specialized knowledge required for species-specific mineral antagonism management—particularly copper-molybdenum-sulfur interactions in ruminants—outpaces university training program output.
- State Licensing Fragmentation:California's Department of Food and Agriculture maintains distinct mineral product registration requirements that add 90-120 day approval delays compared to neighboring states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Feed Minerals Market |
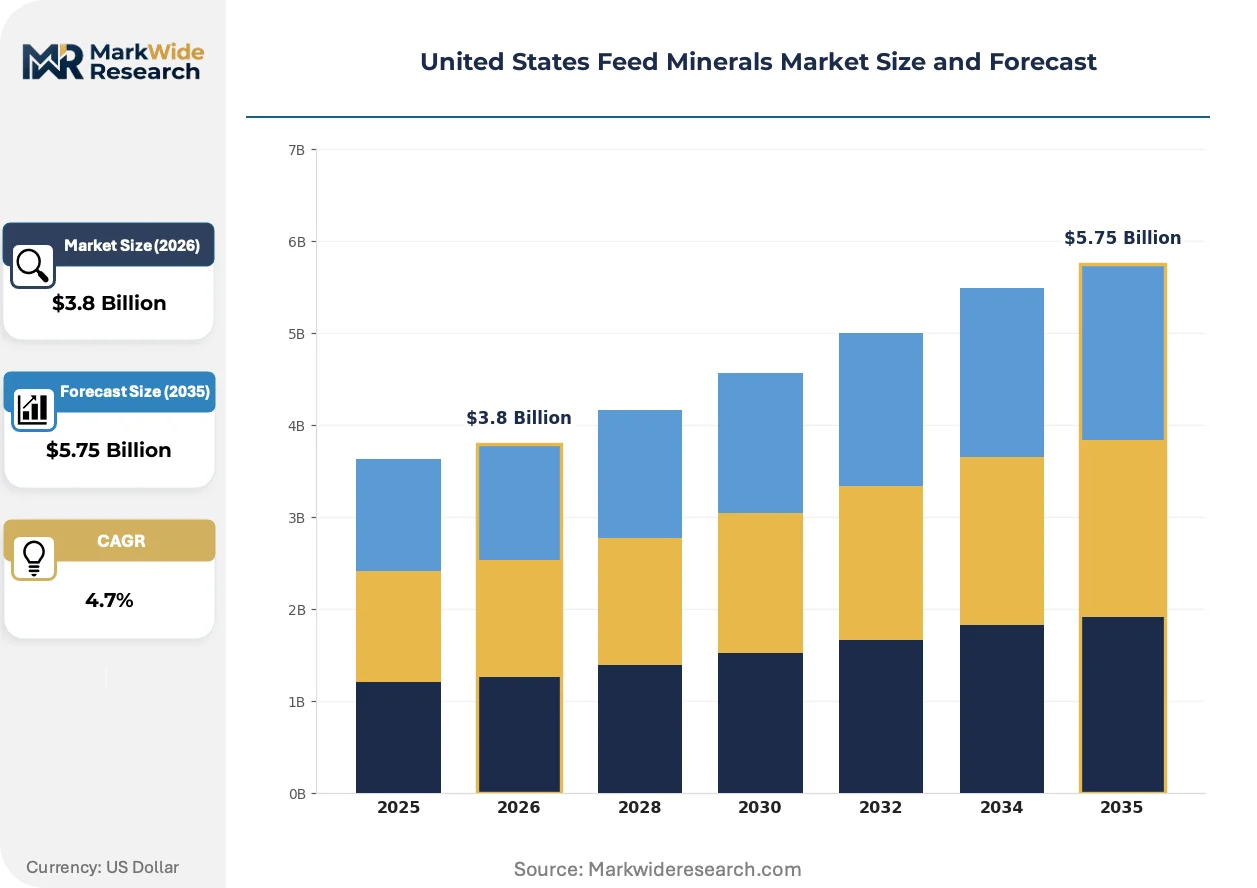
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Premixes, Trace Minerals, Macro Minerals, Chelated Minerals End Use: Poultry, Ruminants, Swine, Aquaculture Form: Granular, Powder, Liquid, Block Distribution Channel: Direct Sales, Online Retail, Distributors, Agricultural Stores |
| Companies Covered | Land O'Lakes, Inc., Alltech, Inc., Phibro Animal Health Corporation, Solvay S.A., Nutreco NV, Cargill Inc., Archer Daniels Midland Co., BASF SE, Kemin Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Feed Minerals Market Strategic Shifts
Yeast-encapsulated mineral delivery systems and blockchain-enabled ingredient provenance tracking are redefining how livestock producers evaluate mineral supplement value, shifting purchasing criteria from price-per-unit toward measurable performance outcomes and supply chain transparency.
Hydroxy trace minerals—zinc, copper, and manganese bound to hydroxide groups rather than sulfates—are rewriting absorption efficiency benchmarks in swine and poultry nutrition. Large integrators in North Carolina and Arkansas have adopted these forms at scale over the past eighteen months. The technology is compressing inclusion rate requirements and reducing environmental mineral excretion loads, forcing traditional sulfate suppliers to defend position on cost rather than efficacy.
The FDA's Veterinary Feed Directive enforcement tightening restricts medically important antimicrobial use in mineral premixes, redirecting formulation priorities toward mineral-biocide synergies for gut health management. Feed mills must now document mineral-medication separation protocols and revise mixing sequences. Poultry operations in the Southeast have responded fastest, reconfiguring premix specifications to eliminate therapeutic overlaps.
Buyer concentration among the top twenty beef packers and dairy cooperatives has compressed mineral supplier negotiation leverage, with procurement teams demanding volume-tiered pricing and extended payment terms. Independent feed distributors in the Upper Midwest are losing share to direct manufacturer relationships. This consolidation is most visible in Nebraska and Kansas, where three beef packers now control mineral specification authority for over sixty percent of finished cattle.
United States Feed Minerals Market Segmentation
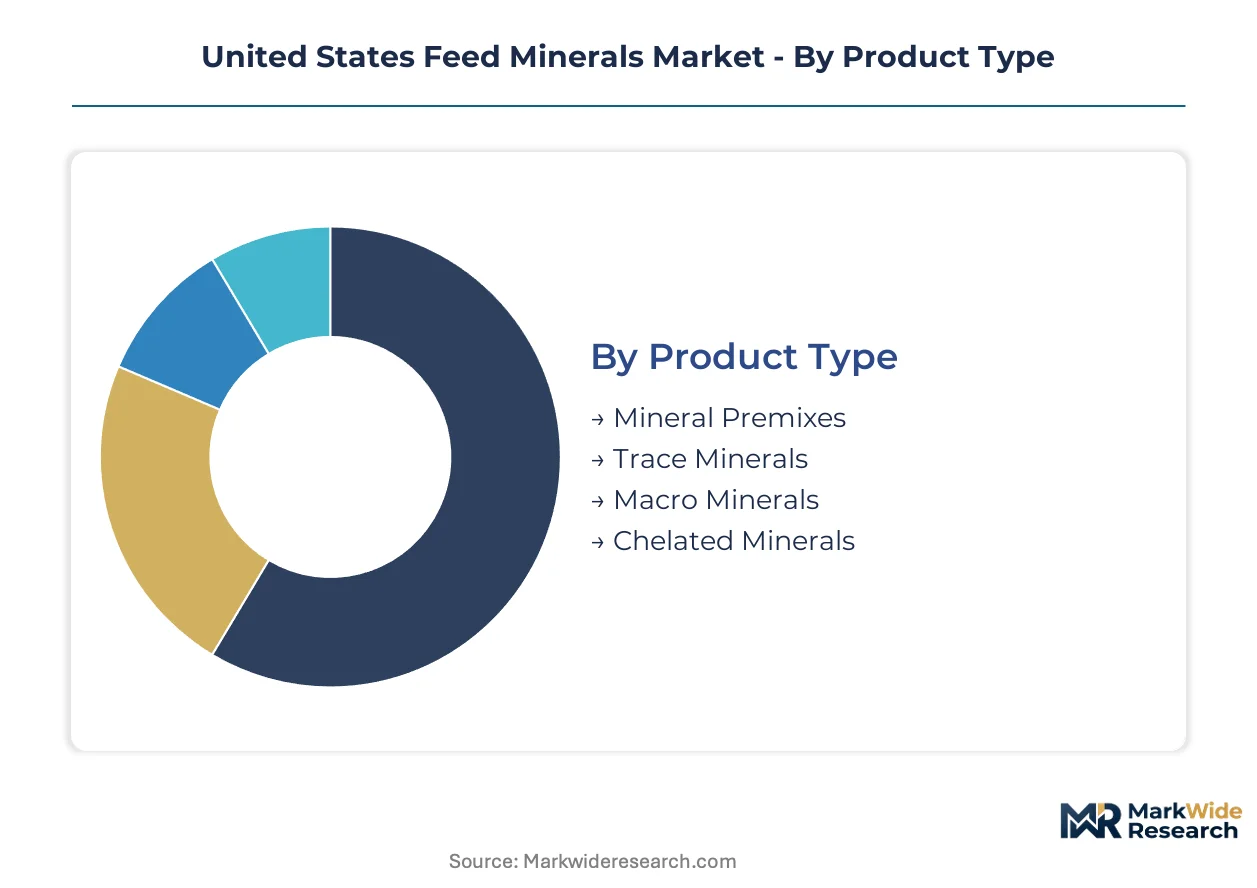
Feed mineral suppliers configure product portfolios around species-specific absorption kinetics and regional logistics constraints. Segmentation discipline determines which formulation investments capture margin pools versus commodity volume positions.
Product Type:
Supply concentration in mineral premix manufacturing clusters around captive ingredient sourcing and toll-milling relationships that lock in cost positions.
- Mineral Premixes:Blended formulations combining macro and trace minerals at specified inclusion rates for species-specific diets. Iowa and Nebraska feed mills drive procurement consolidation through integrated nutrition contracts that compress single-ingredient spot purchasing.
- Chelated Minerals:Organic mineral forms bound to amino acids or proteinates for enhanced bioavailability in ruminant and swine absorption. Wisconsin dairy cooperatives and North Carolina poultry integrators absorb capacity despite 40-60% price premiums over inorganic equivalents.
- Trace Minerals:Copper, zinc, manganese, and selenium compounds dosed at parts-per-million levels for metabolic enzyme function.
- Macro Minerals:Calcium, phosphorus, and magnesium compounds meeting baseline structural and physiological requirements across all livestock categories.
Mineral premixes absorb the bulk of installed capacity; chelated minerals are expanding most quickly.
End Use:
Application-driven formulation requirements split manufacturing capacity between species with divergent mineral antagonism profiles and delivery system preferences.
- Ruminants:Cattle operations in the Corn Belt and Texas Panhandle require precision copper-molybdenum-sulfur balancing to prevent thiomolybdate toxicity that depresses reproductive performance. Dairy herds in California and Wisconsin sustain replenishment cycles for calcium-phosphorus blends supporting high milk yields.
- Poultry:Broiler and layer operations in the Southeast and Mid-Atlantic demand hydroxy trace mineral forms that reduce environmental excretion loads while maintaining feed conversion ratios. Georgia and Arkansas integrators have adopted these technologies at scale.
- Swine:Finishing operations in Iowa and North Carolina utilize zinc oxide and copper sulfate for growth promotion within FDA Veterinary Feed Directive constraints.
- Aquaculture:Catfish farms in the Mississippi Delta and salmonid operations in the Pacific Northwest require water-stable mineral coatings for feed pellet integrity.
Ruminant applications dominate current formulation capacity; poultry is climbing the fastest on hydroxy mineral conversion.
Form:
Physical delivery formats align with feed mill equipment specifications and on-farm handling infrastructure that varies by operation scale.
- Granular:Sized particles for pneumatic conveying and uniform mixing in centralized feed mills serving concentrated animal feeding operations. Indiana and Ohio processing facilities specialize in flowable granules for high-throughput systems.
- Powder:Fine-ground minerals for inclusion in mash feeds and on-farm mixing by smaller livestock producers. Dust control requirements add handling costs that limit adoption in large integrator contracts.
- Liquid:Suspended mineral solutions for water medication systems and automated delivery in swine finishing barns.
- Block:Compressed mineral supplements for pasture-based beef cattle operations in the Western range states.
Granular forms hold the largest share of production assets; liquid delivery is gaining share fastest in automated swine facilities.
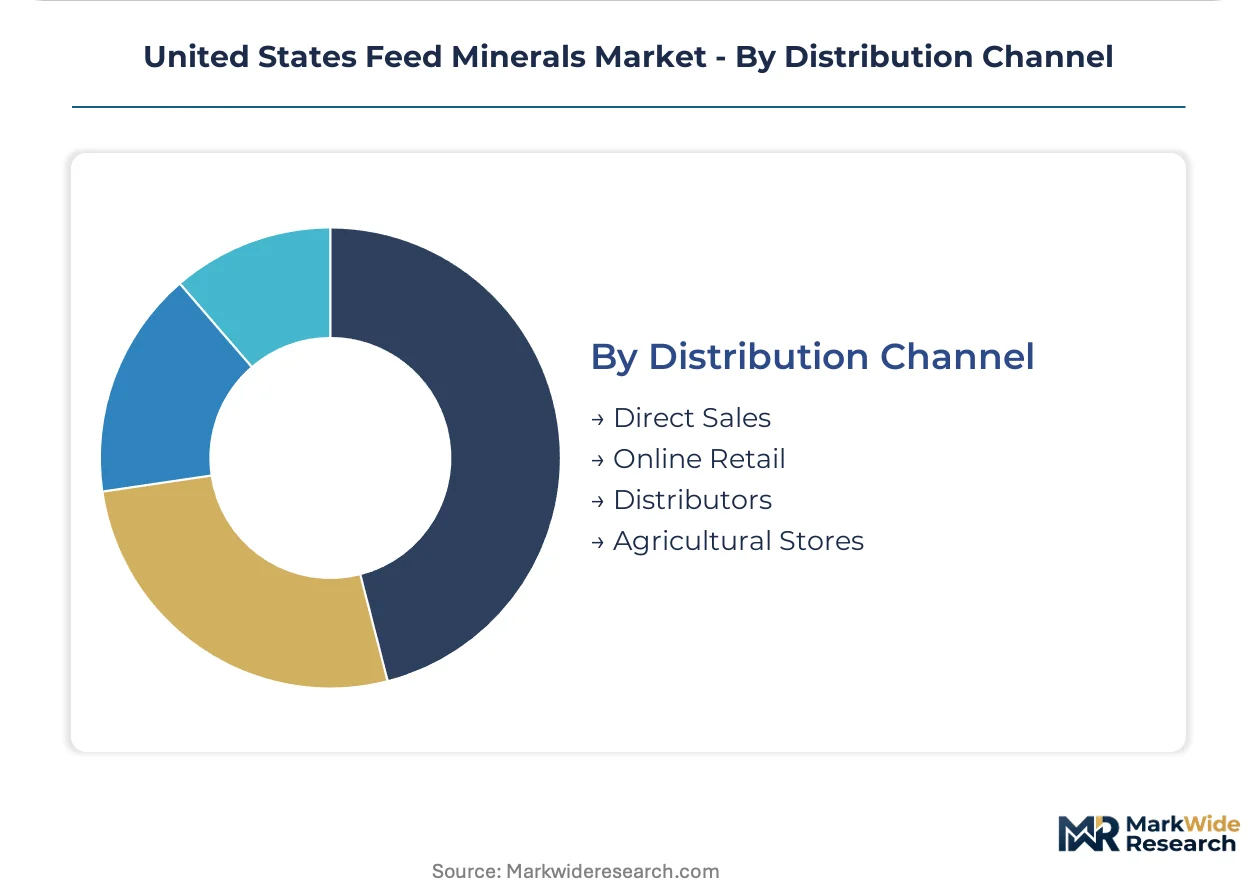
Distribution Channel:
Customer scale and procurement sophistication determine channel economics, with direct manufacturer relationships displacing traditional distributor intermediaries.
- Direct Sales:Manufacturer-to-integrator contracts serving the top twenty beef packers and dairy cooperatives. Nebraska and Kansas operations now source sixty percent of finished cattle mineral specifications through three packer-controlled procurement programs.
- Distributors:Regional feed dealers maintaining inventory positions for mid-scale independent livestock operations. Upper Midwest distributors are losing share to direct relationships as buyer concentration accelerates.
- Agricultural Stores:Farm supply retailers serving hobby farmers and small-scale producers with bagged mineral products.
- Online Retail:E-commerce platforms for specialty organic minerals and hobby farm quantities, currently marginal in total volume.
Direct sales channels command the largest volume flows; online retail is expanding most quickly from a small base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mineral processing capacity clusters in the Midwest while consumption concentrates in livestock-dense corridors, creating freight-dependent supply chains that reshape regional pricing power and inventory positioning.
Midwest Corn Belt
Iowa, Illinois, and Nebraska host the densest beef feedlot and swine finishing operations in the country, generating mineral demand that outstrips local processing capacity. The USDA monitors residue limits through regional laboratories in Ames and Peoria. Indiana and Ohio bulk mineral facilities supply this corridor through just-in-time delivery contracts that compress distributor margins.
California Central Valley
Dairy herds in Fresno and Tulare counties sustain replenishment cycles for calcium-phosphorus blends supporting high milk yields exceeding 25,000 pounds per cow annually. The California Department of Food and Agriculture maintains distinct mineral product registration requirements that add 90-120 day approval delays. Dairy cooperatives in the San Joaquin Valley have consolidated procurement through direct manufacturer relationships.
Texas Panhandle
Cattle-on-feed numbers in the Texas-Oklahoma corridor continue climbing past 7 million head, creating underpenetrated demand for custom mineral programs. The FDA's FSMA enforcement through the Dallas district office mandates current Good Manufacturing Practices for feed mills serving this region. Amarillo and Lubbock have emerged as logistics hubs for high-roughage finishing diet formulations.
Southeast Poultry Belt
Broiler and layer operations in Georgia and Arkansas have adopted hydroxy trace mineral technologies at scale, reducing environmental excretion loads while maintaining feed conversion ratios. State departments of agriculture in the region administer inspection protocols aligned with Association of American Feed Control Officials standards. Integrators in the Delmarva Peninsula and North Carolina are reconfiguring premix specifications to eliminate therapeutic overlaps under Veterinary Feed Directive constraints.
Wisconsin Dairyland
High-producing herds in Dane and Brown counties require precision mineral balancing to sustain reproductive performance and milk component quality. The Wisconsin Department of Agriculture, Trade and Consumer Protection enforces feed labeling standards that exceed federal baselines. Mineral premix suppliers maintain dedicated formulation chemists in Madison to manage copper-molybdenum-sulfur antagonism in regional forage-based diets.
United States Feed Minerals Market Competitive Environment
The competitive structure tilts toward diversified agricultural conglomerates with captive ingredient sourcing. Consolidation among the top twenty beef packers and dairy cooperatives has compressed supplier negotiation leverage, with procurement teams demanding volume-tiered pricing and extended payment terms. Three archetypes dominate: integrated nutrition platforms controlling base mineral supply chains, biotechnology specialists delivering enhanced bioavailability formats, and trace mineral pure-play operators serving species-specific segments. M&A activity targets regional premix formulators, while technology licensing agreements proliferate around yeast-encapsulated delivery systems.
Among the named participants, Cargill Inc. and Archer Daniels Midland Co. occupy positions as diversified agricultural conglomerates with backward integration into base ingredient supply. Alltech, Inc. sits within the biotechnology specialist tier, while Phibro Animal Health Corporation anchors the trace mineral specialization archetype for poultry and swine applications. Land O'Lakes, Inc. represents cooperative-owned distribution leverage in dairy-dense geographies. These entities exemplify how scale, captive supply, and species-specific formulation expertise stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Land O'Lakes, Inc. |
| Alltech, Inc. |
| Phibro Animal Health Corporation |
| Solvay S.A. |
| Nutreco NV |
| Cargill Inc. |
| Archer Daniels Midland Co. |
| BASF SE |
| Kemin Industries |
| Others |
Value Chain & Pricing Dynamics
Family-owned mineral processors in the Corn Belt and Midwest have consolidated through private-equity rollups, concentrating ownership patterns that discipline pricing through captive sulfate and oxide sourcing while squeezing distributor margins across Iowa and Nebraska feed corridors.
Pricing Analysis
Margin tightening in standard-grade mineral premixes reflects copper sulfate and zinc oxide cost volatility from smelter capacity constraints. Three-tier pricing structure across chelated premium, standard inorganic, and economy sulfate tiers differentiates on bioavailability certification and volume scale. Cost-down pressure on spot-market distributors accelerates because direct manufacturer contracts now capture sixty percent of finished cattle mineral specifications. Poultry integrators in Georgia and Arkansas show least price sensitivity for hydroxy trace mineral premiums; independent Midwest feed dealers face greatest compression.
Supply Chain Analysis
Freight costs from Indiana and Ohio bulk processing facilities to Iowa and Nebraska feedlots determine regional pricing spreads, with weather disruptions amplifying single-source dependency risks. Supply concentrates in domestic mining corridors for copper and zinc, with manganese drawn from South African and Gabonese ore imports. Raw material dependencies rest on sulfuric acid availability, phosphate rock quality, and amino acid chelation reagents. Tariff exposure on imported manganese compounds threatens margin stability. Distribution runs through direct manufacturer-to-integrator contracts displacing traditional Upper Midwest distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States feed minerals sector sits in a technology-transition phase as hydroxy trace minerals displace legacy sulfate forms in swine and poultry operations, rewriting absorption benchmarks and forcing formulation chemists to recalibrate inclusion economics.
For Market Incumbents: Lock in captive sulfate supply through long-term offtake agreements with Midwest smelters before hydroxy mineral conversion accelerates. Deepen backward integration into phosphate rock processing to defend margin position against chelated mineral price premiums. Prioritize yeast-encapsulated delivery technology licensing to differentiate from commodity sulfate suppliers.
For New Entrants and Emerging Players: FSMA Animal Food Safety Rules in the United States open a window for certified premix specialists to capture share from non-compliant regional blenders. Target Texas Panhandle feedlot expansion corridors with custom high-roughage mineral programs. Pursue direct-to-integrator subscription models bypassing distributor intermediaries entirely.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional premix formulators with captive ingredient positions in Wisconsin and California dairy corridors. Long-term viability hinges on hydroxy mineral patent portfolios and precision livestock convergence capabilities. Watch for FDA organic mineral approval pathway acceleration as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Mineral Supply | Cargill's captive phosphate sourcing locks in cost structures against sulfate volatility. |
| Hydroxy Trace Mineral Patent Licensing | North Carolina poultry integrators adopted these forms at scale, compressing sulfate inclusion rates. |
| Precision Livestock Technology Partnership | Real-time mineral intake monitoring enables dynamic ration adjustment subscription models. |
| Yeast-Encapsulated Delivery System Development | Alltech's bioavailability technology differentiates ruminant formulations from commodity competitors. |
| Texas Panhandle Distribution Hub Expansion | Amarillo logistics positioning captures underpenetrated cattle-on-feed mineral demand. |
Study Parameters
USDA production databases, FDA FSMA enforcement records, and Association of American Feed Control Officials ingredient definitions formed the secondary backbone, cross-referenced with primary interviews involving feed mill quality managers, dairy cooperative procurement directors, poultry integrator nutritionists, and mineral premix formulation chemists. Bottom-up volume estimates from state-level livestock inventories triangulated against top-down mineral consumption benchmarks derived from customs and trade flow analysis.
Historical trendline analysis across mineral inclusion rate evolution, chelated mineral adoption curves, and feedlot concentration patterns informed the projection framework. Segmentation dimensions modeled include mineral form, species application, delivery format, and geographic production cluster. CAGRs were derived from regression analysis of input cost trajectories and substitution elasticity parameters, with hydroxy mineral conversion rates and precision livestock technology penetration serving as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for hydroxy trace mineral uptake would alter the outlook if sulfate suppliers successfully defend on cost. Forecasts reflect documented assumptions regarding FSMA enforcement intensity, organic mineral approval timelines, and feedlot geographic consolidation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Europe Diatomite Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Pyrites Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
North America Silica Sand Market
Industrial Minerals
Pyrophyllite Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Global Commercial Perlite Market
Industrial Minerals
Limestone Market
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Potash Ores Market
Industrial Minerals
Slate Market
Industrial Minerals
Inorganic Salts Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Barite Mining Market