
 Dolomite Powder Market | 2026-2036
Dolomite Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Dolomite Powder Market Analysis
Long-term supply contracts with embedded technical service tiers is restructuring how dolomite powder moves from quarry to furnace. Sibelco leverages its coastal logistics network to lock in glass-plant customers across Western Europe. Imerys S.A. anchors its position through captive calcination assets that cut third-party dependency. Lhoist Group dominates the high-purity flux segment for specialty ceramics producers.
Dolomite powder is a carbonate mineral composed of calcium magnesium carbonate (CaMg(CO3)2), typically processed through crushing, calcination, and micronization to achieve particle sizes between 10 and 100 microns for industrial use. Its primary commercial purpose centers on supplying magnesium oxide and calcium oxide as fluxing agents, soil conditioners, and functional fillers. Bulk delivery formats occupy the largest volume share in cement and steel applications where continuous feed systems minimize handling costs. High-purity grades command the strongest margin pools in pharmaceutical and food-grade channels where arsenic and lead thresholds sit below 10 ppm. Soil amendment applications across precision agriculture are expanding fastest as growers substitute dolomitic lime for synthetic magnesium fertilizers.
EPA air-quality standards for particulate emissions at mining and milling sites push operators toward enclosed processing systems and baghouse upgrades. REACH registration requirements in Europe mandate full toxicological dossiers for dolomite destined for consumer-contact applications. India's BIS certification for construction-grade minerals creates a compliance gate for imports from non-FTA sources. Stakeholders must weigh calcination energy costs against regulatory tightening on Scope 1 emissions when committing to multi-year quarry expansion plans.
Market Dynamics
Calcination energy costs and tightening Scope 1 emissions thresholds are forcing quarry operators to restructure long-term expansion commitments around carbon-capture retrofits and renewable thermal integration.
Growth Catalysts
- Glass furnace flux demand:Container and flat-glass producers in India, China, and Brazil are specifying higher-purity dolomite grades to reduce alkali carryover and extend refractory campaign life.
- REACH heavy-metal thresholds:ECHA-mandated toxicological dossiers for consumer-contact applications are compressing supply bases toward certified producers with in-house testing laboratories.
- Precision agriculture substitution:Growers across the US Corn Belt and Brazilian Cerrado are replacing synthetic magnesium fertilizers with dolomitic lime to address soil pH and micronutrient deficits simultaneously.
Market Restraints
- Natural gas price volatility:Calcination requires sustained 900-1100°C thermal input, exposing margin structures to European TTF and Henry Hub price swings.
- Quarry concentration in Alpine and Appalachian belts:Limited alternative sourcing geography creates logistics vulnerability for Asian buyers dependent on European bulk shipping lanes.
- Ground calcium carbonate substitution:Paper and plastics compounders in Southeast Asia are reformulating toward GCC in cost-sensitive filler applications where magnesium content provides no functional advantage.
Strategic Opportunities
- Pharmaceutical-grade certification:USP and EP monograph compliance for magnesium carbonate derivatives opens formulation partnerships with generic drug manufacturers in India and Eastern Europe.
- Soil amendment e-commerce channels:Direct-to-farm micronized powder sales through agronomy platforms bypass traditional co-op distribution markups in the US Midwest and Australian wheat belt.
- EU Green Deal carbon border adjustments:Early calcination electrification using grid-connected kilns positions exporters for preferential treatment under CBAM phase-in schedules.
Industry Challenges
- Process control engineering talent:Automated calcination and micronization lines require operators trained in continuous thermal monitoring and particle-size distribution analytics, skills concentrated in legacy ceramics and cement sectors.
- BIS certification timelines:India's construction-grade mineral import gates involve 12-18 month laboratory validation cycles that freeze spot-market participation from non-FTA sources.
- Baghouse and enclosed-system retrofit capex:EPA particulate emission standards at mining and milling sites demand capital deployment that mid-tier quarries struggle to finance without offtake guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dolomite Powder Market |
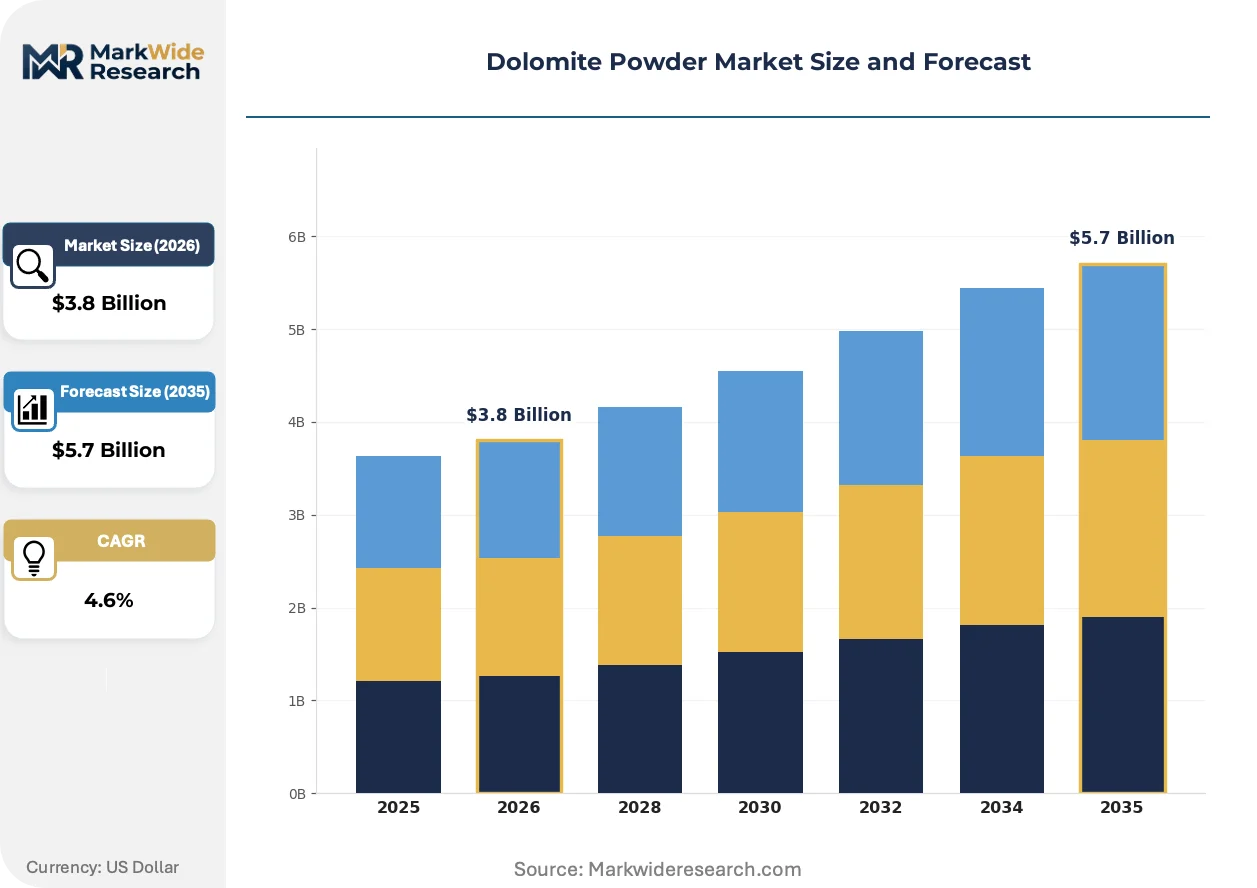
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bagged, Bulk, Pellets, Granules End User: Construction, Agriculture, Glass Manufacturing, Ceramics Grade: Industrial Grade, High Purity, Chemical Grade, Food Grade Application: Soil Amendment, Filler, Flux, Coating |
| Companies Covered | Sibelco, Imerys S.A., Minerals Technologies Inc., Carmeuse, Lhoist Group, Omya Group, Beihai Group, Arihant MinChem, Nordkalk Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dolomite Powder Market Emerging Trajectories
Dry grinding and air-classification technologies are compressing particle-size distribution bands below 10 microns, enabling dolomite powder displacement of precipitated calcium carbonate in premium polymer applications.
Micronization towers with integrated online laser diffraction sensors are expanding into specialty ceramics and engineered plastics compounding, where narrow PSD control justifies 40-60% price premiums over bulk construction grades. Japanese and German automotive suppliers are qualifying these powders for thermoplastic polyolefin interior panels, shifting volume away from commodity glass and steel channels.
REACH registration requirements for calcium magnesium carbonate are compressing supplier lists in European food-contact and cosmetic applications, forcing traders to document full supply-chain provenance or exit the market. ECHA's 2024 updated guidance on nanomaterial thresholds has triggered additional testing protocols for sub-100nm fractions, advantaging producers with captive analytical capabilities.
Long-term offtake contracting with embedded technical service tiers is displacing spot-market purchasing among Western European glass manufacturers seeking campaign-life guarantees. Sibelco and Imerys are embedding process engineers at customer furnace sites to optimize flux dosing ratios, converting transactional supply relationships into multi-year partnerships with penalty clauses for purity variance. This bundling is most advanced in container-glass clusters across northern Italy and eastern France.
Dolomite Powder Market Segmentation
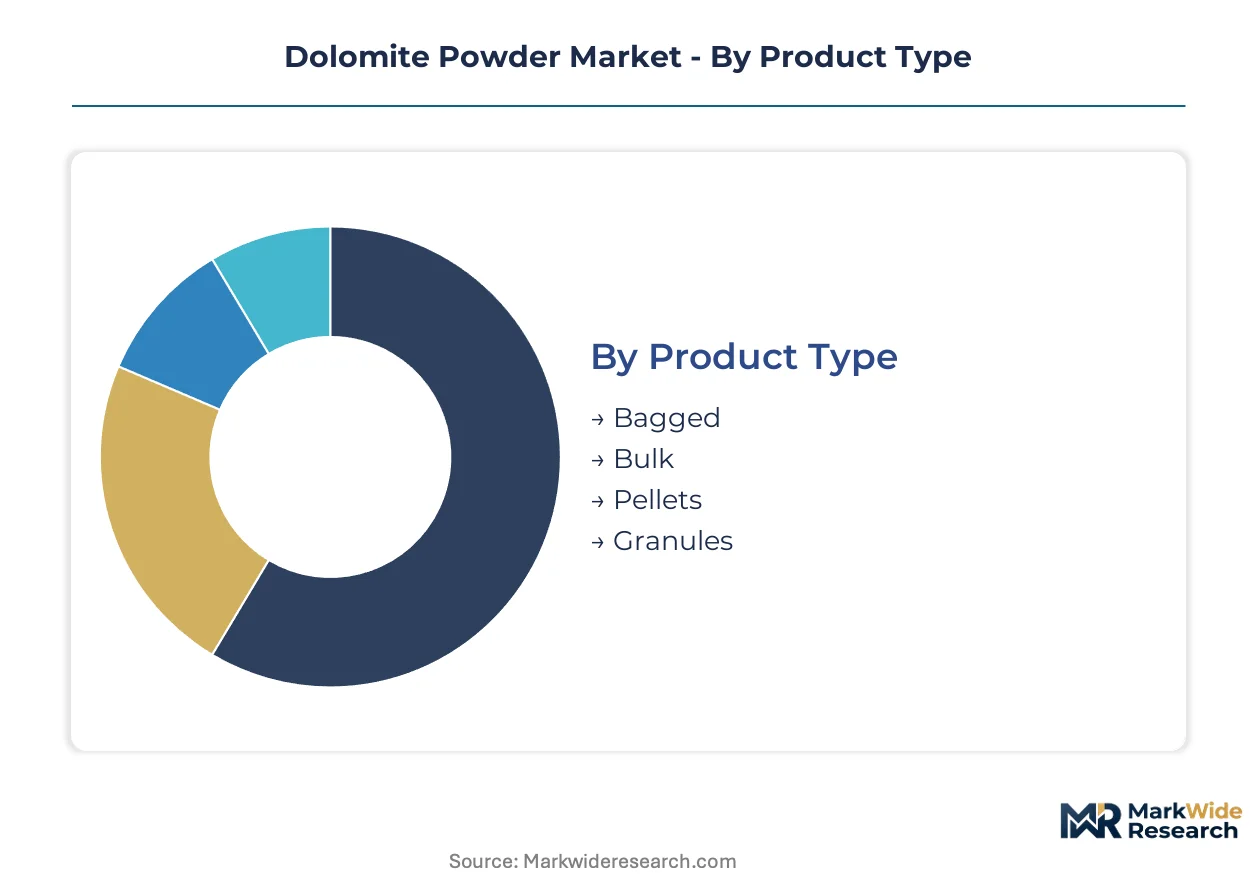
Dolomite powder specifications diverge sharply across end-use channels, with calcination intensity and heavy-metal thresholds determining commercial viability. Procurement teams segment supply by physical format, chemical grade, and particle-size distribution to match continuous feed systems or batch processing requirements.
Product Type:
Physical delivery format dictates handling infrastructure requirements and logistics cost structures across customer sites.
- Bulk:Unpackaged powder or granular material delivered via pneumatic tanker or ocean-going bulk carrier. Container-glass furnaces in northern Italy and eastern France specify bulk delivery to minimize handling losses and integrate with automated silo systems.
- Bagged:Multi-wall paper or woven polypropylene sacks ranging from 25 kg to 1 tonne. Precision agriculture distributors across the US Corn Belt prefer bagged micronized grades for direct-to-farm e-commerce fulfillment.
- Pellets:Compacted spherical forms engineered for controlled dissolution rates. Soil amendment applications in Brazilian Cerrado regions specify pelletized dolomitic lime to reduce wind drift during aerial application.
- Granules:Coarse particulate forms with particle sizes between 2 and 10 millimeters. Specialty ceramics producers in Germany and Japan source granular flux grades for batch furnace charging.
Mature deployment sits with bulk delivery at integrated glass and steel plants. Newer deployment is concentrated in bagged micronized grades for precision agriculture e-commerce channels.
End User:
Customer industry determines purity thresholds, certification requirements, and technical service intensity.
- Glass Manufacturing:Flat-glass and container-glass producers specify dolomite for magnesium oxide content that reduces alkali carryover and extends refractory campaign life. Indian and Chinese furnace operators are contracting for higher-purity grades with embedded technical service tiers.
- Agriculture:Growers deploy dolomitic lime as a dual-function soil amendment addressing pH correction and magnesium supplementation. Brazilian Cerrado and US Midwest operations are substituting synthetic magnesium fertilizers with precision-applied dolomitic lime.
- Construction:Cement and concrete producers incorporate dolomite as aggregate and mineral filler. India's BIS certification requirements for construction-grade imports create compliance gates for non-FTA sourcing.
- Ceramics:Specialty ceramics and refractory manufacturers require tight particle-size distribution control for engineered thermal properties. Japanese automotive interior panel suppliers are qualifying micronized grades for thermoplastic polyolefin compounding.
Volume concentration remains heaviest in glass manufacturing. Steepest expansion trajectory is appearing in agriculture as synthetic fertilizer substitution accelerates.
Grade:
Chemical purity stratification separates commodity construction supply from certified pharmaceutical and food-contact channels.
- Industrial Grade:Standard purity dolomite with calcium magnesium carbonate content above 90% and controlled iron oxide levels. Cement kiln operators and steel desulfurization plants specify industrial grade for cost-sensitive bulk applications.
- High Purity:Refined grades with heavy-metal content below 10 ppm arsenic and lead, suitable for consumer-contact applications. REACH registration requirements in Europe are compressing supply bases toward certified producers with captive analytical laboratories.
- Chemical Grade:Intermediate purity tier for industrial chemical synthesis and water treatment applications. Magnesium salt manufacturers in India and Eastern Europe source chemical-grade feedstock for carbonate derivative production.
- Food Grade:Certified dolomite meeting USP and EP monograph standards for direct food contact and pharmaceutical formulations. Generic drug manufacturers in India are qualifying food-grade magnesium carbonate derivatives for antacid and supplement applications.
Margin pools concentrate in food-grade certification. Volume scale dominates industrial-grade supply.
Application:
Functional use case determines particle-size requirements, surface treatment, and thermal processing intensity.
- Flux:Calcined dolomite supplying magnesium oxide and calcium oxide to lower melting temperatures in glass and metallurgical furnaces. Western European container-glass producers are locking in multi-year offtake contracts with campaign-life guarantees.
- Soil Amendment:Agricultural lime applications correcting soil pH and delivering plant-available magnesium. Australian wheat belt and US Midwest growers are adopting direct-to-farm micronized powder channels.
- Filler:Functional extender in polymers, paints, and paper coatings where particle-size distribution controls rheological properties. Southeast Asian plastics compounders are reformulating toward ground calcium carbonate in cost-sensitive applications where magnesium content provides no functional advantage.
- Coating:Surface treatment applications in corrosion protection and architectural finishes. Specialty coatings manufacturers in Germany specify air-classified ultrafine grades below 10 microns for premium polymer displacement.
Established application dominance rests with flux demand at integrated furnaces. Emerging application growth is clustering in soil amendment precision agriculture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quarry reserves cluster in Alpine and Appalachian belts while consumption tilts toward glass furnace corridors in India, China, and Brazil. This geographic mismatch forces logistics-heavy supply chains across maritime bulk lanes. Regulatory divergence on heavy-metal thresholds and calcination emissions is fragmenting trade routes and certification requirements.
India
Container-glass furnace operators in Gujarat and Maharashtra are contracting higher-purity dolomite grades to extend refractory campaign life. BIS certification for construction-grade mineral imports creates 12-18 month validation gates that freeze spot-market participation from non-FTA sources. The Mundra-Dahej coastal belt anchors import handling infrastructure for Middle Eastern and European supply.
China
Flat-glass producers in the Yangtze River Delta are specifying tighter particle-size distribution bands to reduce alkali carryover. MIIT dual carbon goals and provincial emission intensity targets are pressuring calcination facilities toward natural gas-to-electricity retrofits. The Shandong Peninsula hosts the densest concentration of captive calcination assets serving domestic specialty ceramics demand.
Germany
Specialty ceramics manufacturers in Bavaria and North Rhine-Westphalia require REACH-registered grades with full toxicological dossiers for consumer-contact applications. ECHA's 2024 nanomaterial threshold guidance triggers additional testing protocols for sub-100nm fractions. The Rhine corridor logistics network enables just-in-time bulk delivery to container-glass clusters across northern Italy and eastern France.
United States
Precision agriculture distributors across the Corn Belt are adopting direct-to-farm micronized powder channels to bypass traditional co-op markups. EPA air-quality standards for particulate emissions at mining and milling sites push Appalachian quarry operators toward enclosed processing systems and baghouse upgrades. The Ohio River Valley anchors bulk supply infrastructure for integrated steel desulfurization plants.
Brazil
Growers in the Cerrado region are substituting synthetic magnesium fertilizers with pelletized dolomitic lime for aerial application. ANVISA alignment with international food-contact standards is compressing import supply bases toward certified producers with captive analytical laboratories. The Santos port complex handles bulk discharge for construction-grade supply to São Paulo state cement kilns.
Dolomite Powder Market Vendor Landscape
Capital-heavy quarry operators with captive calcination assets compete with asset-light traders dependent on third-party toll processing. Market structure tilts toward consolidated supply at the high-purity tier and fragmented competition in bulk construction grades. Three archetypes dominate: integrated miners with coastal logistics networks, specialty calciners serving pharmaceutical and food-grade channels, and regional quarry operators selling unprocessed lump to local cement and steel plants. Competitive moves concentrate on long-term offtake contracting with embedded technical service tiers and calcination electrification to position for EU carbon border adjustments.
Within the integrated logistics tier, Sibelco and Imerys S.A. exemplify operators combining coastal shipping infrastructure with captive processing assets. Lhoist Group occupies a position representing specialty calcination expertise focused on high-purity flux grades for ceramics and glass applications. These three names anchor the premium supply vector where REACH registration and pharmaceutical-grade certification create defensive moats against commodity competition.
| Leading Market Players |
|---|
| Sibelco |
| Imerys S.A. |
| Minerals Technologies Inc. |
| Carmeuse |
| Lhoist Group |
| Omya Group |
| Beihai Group |
| Arihant MinChem |
| Nordkalk Corporation |
| Others |
Supply Flow & Price Mechanics
Process control engineering talent concentrated in legacy ceramics and cement sectors across Germany and Japan widens labor-cost spreads between premium calcination facilities and commodity quarries, compressing margin pools at the standard-grade tier while certified producers extract technical-service premiums.
Pricing Analysis
Price erosion across industrial-grade supply traces to ground calcium carbonate substitution in Southeast Asian filler applications where magnesium content provides no functional advantage. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered pharmaceutical grades from BIS-certified construction material and unprocessed quarry lump. Cost-down pressure on bulk flux deliveries accelerates because Indian and Chinese glass producers are consolidating procurement through embedded technical-service contracts. Container-glass furnace operators in Western Europe show least price sensitivity due to campaign-life guarantee requirements, while spot-market construction buyers in Brazil exhibit highest sensitivity to freight-adjusted delivered costs.
Supply Chain Analysis
Maritime bulk freight from Alpine and Appalachian quarry belts to Indian and Chinese furnace corridors absorbs 15-25% of delivered cost for containerized glass producers. Supply concentrates in Belgium, Norway, and the eastern United States where dolomite reserves overlay established calcination infrastructure. Raw material flows draw from natural gas for thermal processing, grid electricity for electrification retrofits, and specialized refractory linings for kiln maintenance. Single-source vulnerability sits with European TTF gas price exposure for calcination energy. Distribution runs through long-term offtake contracts with embedded technical service tiers rather than spot-market trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive calcination assets and coastal logistics networks determine pricing power, with players pursuing downstream control over technical-service relationships to lock in multi-year furnace supply contracts.
For Market Incumbents: Extend campaign-life guarantee offerings to Indian and Chinese container-glass producers, embedding process engineers at customer sites to optimize flux dosing ratios and create switching costs. Deepen upstream control over high-purity quarry reserves in Norway and Belgium to defend margin position against emerging specialty calciners from Eastern Europe. Prioritize calcination electrification using grid-connected kilns to position for EU Green Deal carbon border adjustment preferential treatment.
For New Entrants and Emerging Players: The 40-60% price premium gap between micronized specialty grades and bulk construction material creates entry space for precision agriculture e-commerce channels across the US Corn Belt and Australian wheat belt. Target direct-to-farm bagged micronized sales through agronomy platforms to bypass traditional co-op distribution markups. Pursue pharmaceutical-grade USP and EP certification for magnesium carbonate derivatives to supply generic drug manufacturers in India.
For Investors and Strategic Acquirers: Re-rating potential sits with specialty calcination specialists possessing captive analytical laboratories given REACH registration requirements compressing European supply bases toward certified producers. Long-term viability favors operators with integrated coastal logistics and renewable thermal transition plans over asset-light traders dependent on third-party toll processing. Watch for BIS certification timeline acceleration as the signal indicating inflection in Indian import participation rules.
| Strategic Initiative | Industry Significance |
|---|---|
| Calcination Electrification | Grid-connected kiln retrofits position exporters for EU carbon border adjustment preferential treatment. |
| Pharmaceutical-Grade Certification | USP and EP monograph compliance opens formulation partnerships with Indian generic drug manufacturers. |
| Embedded Technical Service Tiers | Process engineers at customer furnace sites convert transactional supply into multi-year partnership contracts. |
| Precision Agriculture E-Commerce | Direct-to-farm micronized powder channels bypass traditional co-op distribution markups in the US Midwest. |
| Coastal Logistics Network Expansion | Sibelco's bulk shipping infrastructure locks in Western European glass-plant customers through delivered cost advantage. |
Methodological Framework
Multi-period observation of calcination energy costs, REACH registration timelines, and BIS certification validation cycles anchored the trend analysis, supplemented by interviews with quarry operations managers, glass furnace procurement leads, specialty ceramics R&D directors, and precision agriculture distribution channel partners. Secondary validation drew from ECHA guidance documents, EPA air-quality enforcement records, Indian customs trade data, and SEC filings of publicly traded mineral processors. Bottom-up volume estimates by grade tier and application triangulated against top-down industry association aggregates.
Segment-weighting across product type, end-user industry, chemical grade, and functional application dimensions structured the analytical framework across the analysis window. CAGRs were derived from regression analysis of historical consumption patterns against glass furnace capacity additions, synthetic fertilizer substitution rates in agriculture, and construction mineral import flows. Industry-specific inputs included natural gas price volatility scenarios for calcination economics and nanomaterial threshold testing protocols for sub-100nm fraction qualification.
Underlying measurement precision varies by segment; pharmaceutical-grade and food-grade certified supply carry tighter precision than spot-market construction material trade. Forecasts reflect documented assumptions regarding regulatory timeline adherence, energy price trajectories, and substitution elasticity in filler applications. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
Asia Pacific Bentonite Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Kyanite Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Fluorspar Market
Industrial Minerals
Limestone Market
Industrial Minerals
North America Silica Sand Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Pyrites Market
Industrial Minerals
Mineral Adsorbent Market
Industrial Minerals
North America Limestone Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Middle East Feed Minerals Market