
 Limestone Cleaner Market | 2026-2036
Limestone Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Limestone Cleaner Market Analytics
Italian specialty chemical producers is consolidating limestone cleaner formulation capacity around pH-neutral chemistries for porous stone substrates. Prosoco leverages decades of masonry restoration expertise to anchor its position in heritage conservation channels. The Clorox Company competes through retail distribution density, while Henkel sustains European market presence with industrial-grade concentrates for commercial stone maintenance.
Limestone cleaner denotes formulated surfactant systems engineered to dissolve calcium carbonate deposits, atmospheric soiling, and biological growth from calcareous stone surfaces without etching or substrate degradation, typically operating within pH 6.5 to 8.5 and incorporating chelating agents such as gluconates or citrates. These formulations serve primarily to preserve architectural limestone, travertine, and marble in both monumental restoration and routine commercial maintenance contexts. Liquid cleaners dominate volume flows due to ease of application on large vertical and horizontal surfaces, while eco-friendly grades capture expanding margin pools as conservation authorities restrict alkaline runoff near protected waterways. Spray cleaners occupy a faster-growing niche among residential consumers and DIY restoration enthusiasts seeking controlled, low-volume application.
EPA registration requirements govern antimicrobial claims in US stone cleaning products, while REACH restricts phosphonate and NTA content in European formulations, compelling reformulation investments across export-oriented manufacturers. OSHA hazard communication standards further shape industrial-grade product labeling and professional application protocols. Stakeholders must monitor evolving state-level VOC limits and green procurement mandates that will determine which formulation platforms retain channel access.
Market Dynamics
REACH compliance in the European Union is forcing wholesale reformulation of limestone cleaner chemistries, as phosphonate and NTA restrictions eliminate legacy surfactant platforms and redirect R&D investment toward biodegradable chelating agents.
Growth Catalysts
- Heritage Restoration Mandates:Conservation authorities in Italy, France, and Spain are expanding procurement for pH-neutral stone cleaners on UNESCO-protected monuments, creating dedicated specification channels for qualified formulations.
- REACH Biodegradability Requirements:ECHA restrictions on persistent organic pollutants are accelerating substitution of synthetic surfactants with plant-derived alternatives, opening margin capture for early reformulators.
- Travertine Architecture Concentration:Rome, Tivoli, and Florence maintain the densest concentrations of porous limestone facades globally, sustaining specialized contractor demand for substrate-specific cleaning systems.
Market Restraints
- Citrate Supply Volatility:Fermentation-derived citric acid prices fluctuate with Brazilian sugarcane harvests, compressing margins for pH-neutral formulations dependent on this chelating backbone.
- Alkaline Cleaner Substitution:Sodium hydroxide-based masonry cleaners retain cost advantages on non-porous substrates, limiting limestone cleaner penetration in price-sensitive commercial maintenance contracts.
- Professional Application Requirements:OSHA hazard communication standards mandate trained applicator protocols for industrial-grade concentrates, constraining DIY market expansion.
Strategic Opportunities
- Spray Format Innovation:Aerosol and trigger-spray delivery systems are capturing residential restoration enthusiasts seeking controlled application volumes on small architectural elements.
- Green Public Procurement:EU Green Deal-aligned tender specifications are mandating biodegradability certifications, creating preferential access for compliant suppliers in municipal heritage budgets.
- Biological Growth Control:Antimicrobial cleaner segments are expanding as EPA-registered formulations address lichen and algae infestation on shaded limestone facades.
Industry Challenges
- Conservation Chemistry Expertise Gap:Formulators with simultaneous competence in surfactant science and stone substrate pathology remain scarce, slowing product development cycles.
- Multi-Jurisdiction Registration Complexity:Separate EPA antimicrobial claims processes and REACH substance dossiers create parallel compliance burdens for exporters serving both US and EU markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Limestone Cleaner Market |
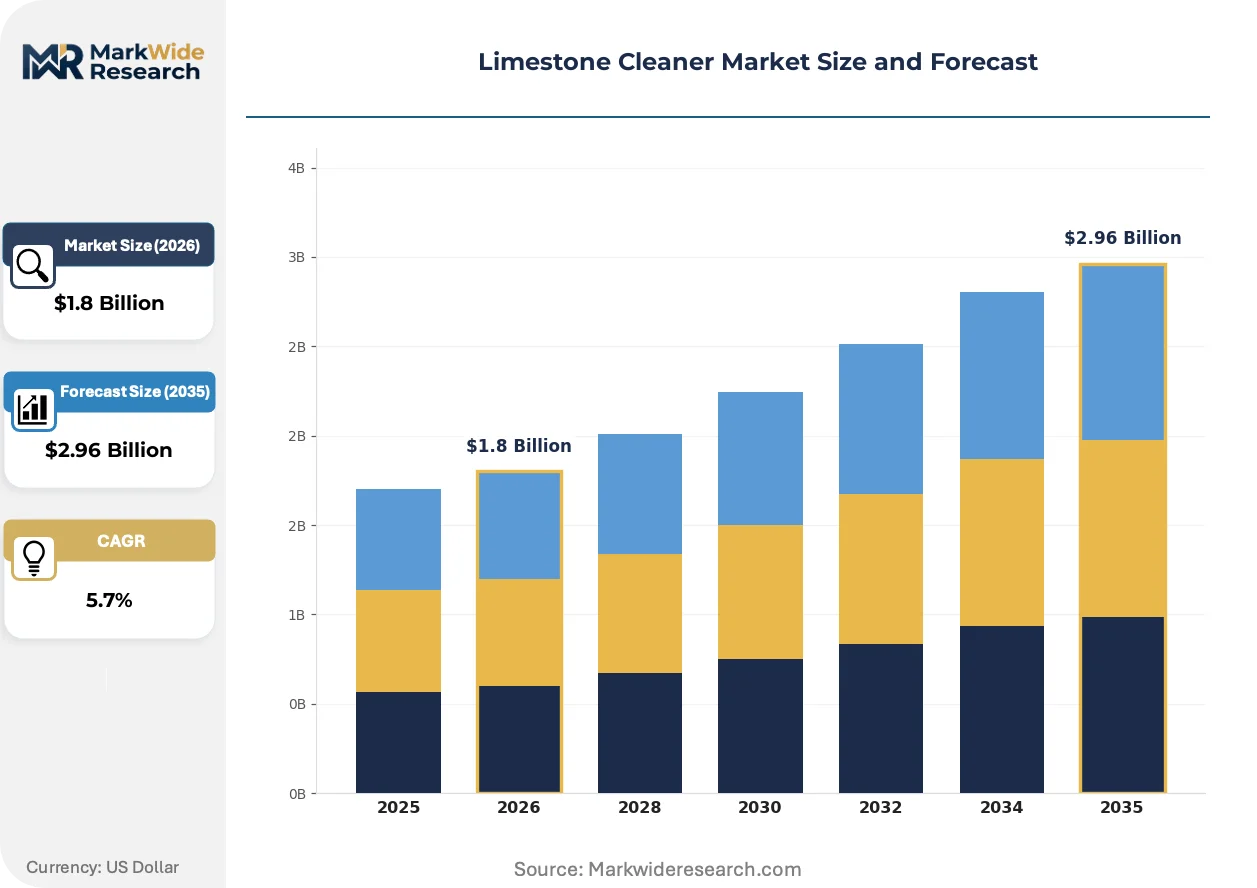
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cleaners, Powder Cleaners, Spray Cleaners, Paste Cleaners Application: Residential Use, Commercial Use, Industrial Cleaning, DIY Projects Packaging Type: Bottles, Tubes, Buckets, Pouches Grade: Eco-Friendly, Industrial Grade, Premium Grade, Standard Grade |
| Companies Covered | Prosoco, The Clorox Company, The Procter & Gamble Company, SC Johnson, Unilever, Henkel, Weiman, Colgate Palmolive, Church & Dwight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Limestone Cleaner Market Evolving Landscape
Formulation science is converging with digital application technologies to reshape how limestone cleaners are specified, delivered, and validated on heritage substrates.
Electrolyzed water systems is automating on-site generation of pH-neutral cleaning solutions for large-scale restoration projects. Conservation contractors in Italy and France are piloting mobile units that eliminate transport of liquid concentrates. This technology is automating dilution control and reducing packaging waste across monument-scale cleaning contracts.
ECHA restrictions on phosphonates under REACH Annex XVII are eliminating sequestrant chemistries that dominated limestone cleaners for three decades. Manufacturers are redirecting formulation investment toward gluconate and polysaccharide chelators. Italian specialty chemical producers face the steepest reformulation timelines given their travertine-specialized product portfolios.
Performance-based specification is displacing brand-loyal procurement among European conservation authorities. Heritage agencies in Spain and Portugal now require第三方 laboratory validation of substrate compatibility before contract award. This shift concentrates demand on suppliers with in-house conservation science capabilities and accredited testing partnerships.
Limestone Cleaner Market Segmentation
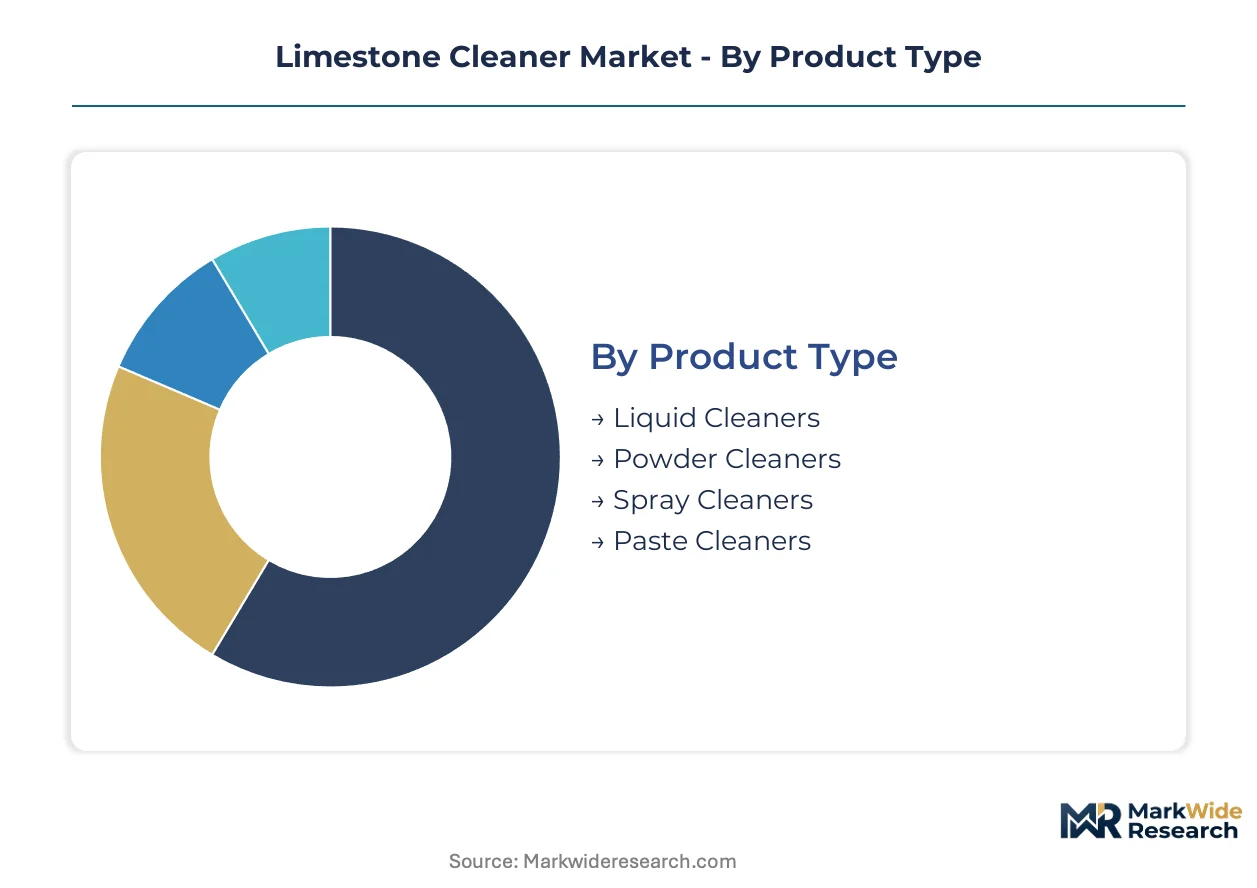
Segmentation in limestone cleaners reflects divergent performance requirements across substrate sensitivity, application scale, and regulatory exposure. Procurement patterns split between heritage conservation authorities demanding pH-neutral precision and commercial maintenance contractors prioritizing cost-efficient coverage.
Product Type:
Replacement cycles accelerate where substrate damage risk elevates switching costs toward specialized formulations.
- Liquid Cleaners:Surfactant systems in aqueous solution dominate monument-scale restoration due to pump-spray compatibility and controlled dwell times on vertical travertine facades. Italian conservation contractors specify these for UNESCO-protected limestone structures requiring documented pH neutrality.
- Spray Cleaners:Aerosol and trigger-delivery formats capture residential restoration enthusiasts seeking metered application on small architectural elements without dilution errors. Rome and Florence DIY suppliers report expanding shelf space for these controlled-volume formats.
- Powder Cleaners:Concentrated alkaline blends serve heavy-duty commercial maintenance on non-porous masonry where limestone substrate risk is absent.
- Paste Cleaners:Thixotropic formulations cling to overhead and vertical surfaces during extended contact times for deep biological growth removal.
Volume placements concentrate in Liquid Cleaners; the faster expansion belongs to Spray Cleaners.
Application:
Cost tier stratification separates specification-driven heritage procurement from price-sensitive commercial contracts.
- Commercial Use:Facility maintenance contractors across Italy, France, and Spain drive recurring demand for mid-grade concentrates on travertine-clad hospitality and retail facades. ECHA REACH compliance mandates now filter supplier qualification for municipal building portfolios.
- Residential Use:Homeowners in limestone-architecture districts maintain periodic cleaning schedules on patios, fireplaces, and decorative stonework, favoring ready-to-use formulations over concentrate economics.
- Industrial Cleaning:Manufacturing facilities with limestone process equipment require heavy-duty degreasing compatibility absent from conservation-grade chemistries.
- DIY Projects:Restoration hobbyists in heritage-dense regions purchase small-format spray products for architectural salvage and antique limestone furniture refurbishment.
Commercial Use commands the largest volume commitment; Residential Use is climbing the fastest as heritage tourism drives homeowner awareness.
Packaging Type:
Supply chain configuration favors formats minimizing transport cost per active unit for concentrate shipments.
- Bottles:HDPE containers from 500ml to 5 liters dominate liquid cleaner distribution through retail hardware and conservation specialty channels. Italian formulators specify recyclable PCR content to meet EU Green Deal procurement preferences.
- Buckets:Industrial concentrates for contractor dilution ship in 20-25 liter formats reducing per-liter packaging cost for large monument cleaning contracts.
- Tubes:Collapsible aluminum or laminate tubes deliver paste cleaners with controlled extrusion for detailed restoration work on carved limestone elements.
- Pouches:Flexible refill formats emerge in eco-positioned lines targeting plastic reduction commitments from municipal heritage agencies.
Bottles retain the dominant volume position; Pouches are gaining share fastest on sustainability specification.
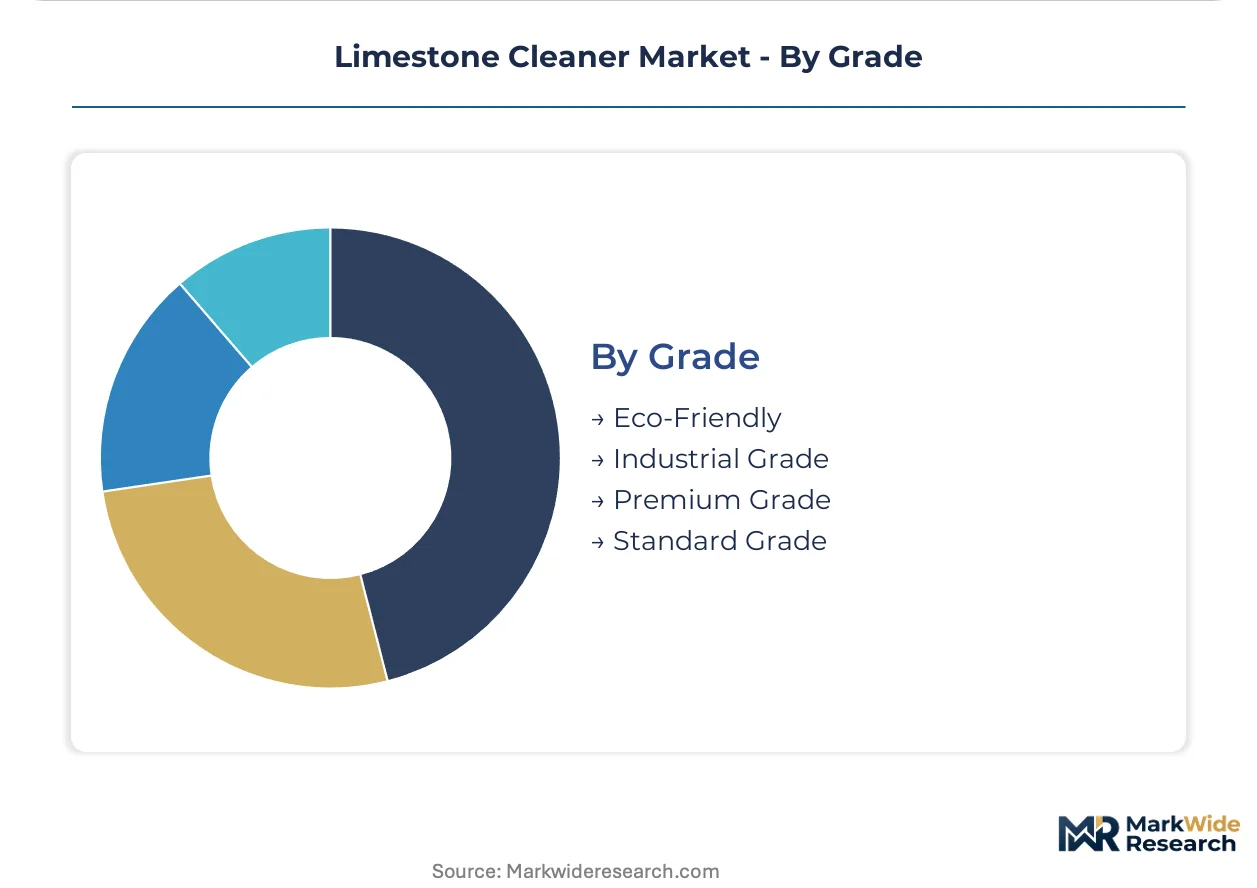
Grade:
Margin structure inverts between certification-heavy conservation segments and commodity commercial maintenance.
- Eco-Friendly:Biodegradable surfactant systems with gluconate or polysaccharide chelators capture premium positioning as ECHA REACH Annex XVII eliminates phosphonate alternatives. Italian travertine specialists reformulate entire portfolios to retain specification access.
- Industrial Grade:Concentrated alkaline and solvent-based cleaners serve non-porous masonry and equipment cleaning where substrate etching tolerance permits aggressive chemistry.
- Premium Grade:Conservation-laboratory-validated formulations with documented substrate compatibility command specification preference for UNESCO and national heritage monument contracts.
- Standard Grade:General-purpose neutral cleaners balance cost and performance for routine commercial limestone maintenance without heritage compliance requirements.
Standard Grade holds the volume concentration; Eco-Friendly shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian sugarcane harvests anchor citric acid supply chains for pH-neutral chelating agents, concentrating formulation cost volatility in limestone cleaner manufacturing. Heritage monument density and REACH compliance timelines are reshaping procurement geography across Europe.
Italy
Rome, Tivoli, and Florence maintain the densest travertine facade concentrations globally, driving specialized contractor demand for substrate-specific cleaning systems. ECHA REACH Annex XVII phosphonate restrictions are compelling Italian specialty chemical producers to reformulate entire portfolios toward gluconate alternatives. Conservation authorities in Lazio and Tuscany now mandate third-party laboratory validation of substrate compatibility before contract award.
France
UNESCO-protected limestone monuments in Paris and the Loire Valley sustain specification-driven procurement for conservation-grade formulations. EU Green Deal-aligned tender specifications mandate biodegradability certifications for municipal heritage budgets. Conservation contractors in Île-de-France are piloting mobile electrolyzed water systems that eliminate transport of liquid concentrates on large-scale restoration projects.
Spain
Heritage agencies in Madrid and Barcelona have shifted from brand-loyal procurement to performance-based specification requiring documented pH neutrality. ECHA restrictions on persistent organic pollutants accelerate substitution of synthetic surfactants with plant-derived alternatives. Andalusian restoration specialists report expanding demand for antimicrobial formulations addressing lichen infestation on shaded limestone facades.
Germany
Industrial-grade concentrate demand from commercial stone maintenance contractors concentrates in North Rhine-Westphalia and Bavaria. REACH compliance dossiers for biodegradable chelating agents redirect R&D investment toward export-oriented manufacturers. Berlin-based heritage conservation institutes are validating electrokinetic cleaning technologies as alternatives to chemical application on sensitive calcareous substrates.
United States
EPA registration requirements govern antimicrobial claims in stone cleaning products, creating parallel compliance burdens for exporters serving both US and EU markets. OSHA hazard communication standards mandate trained applicator protocols for industrial-grade concentrates in commercial maintenance contracts. Metropolitan restoration markets in New York and Chicago favor spray-format delivery systems among residential DIY enthusiasts seeking controlled application volumes.
Limestone Cleaner Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and heritage conservation channel access. The vendor base stratifies between multinational consumer goods conglomerates with retail distribution density and European specialty chemical producers with conservation science capabilities. Two strategic archetypes dominate: heritage restoration specialists leveraging decades of masonry expertise, and mass-market players competing through retail shelf space and pricing power. Capacity expansion in biodegradable surfactant production and strategic partnerships with conservation testing laboratories represent the dominant competitive moves.
Within the heritage restoration specialist tier, Prosoco exemplifies formulation competence anchored in decades of masonry restoration expertise. The Clorox Company and Henkel occupy contrasting positions: the former competes through retail distribution density in consumer channels, while the latter sustains European market presence with industrial-grade concentrates for commercial stone maintenance. These three entities represent the competitive spectrum from specification-driven conservation procurement to volume-driven commercial maintenance contracts.
| Leading Market Players |
|---|
| Prosoco |
| The Clorox Company |
| The Procter & Gamble Company |
| SC Johnson |
| Unilever |
| Henkel |
| Weiman |
| Colgate Palmolive |
| Church & Dwight |
| Others |
Value Network & Pricing Analysis
Brazilian sugarcane futures anchor citric acid cost baselines for pH-neutral chelating agents, transmitting volatility through three distinct pricing tiers as formulators absorb or pass through raw material swings. REACH-driven reformulation mandates concentrate margin pressure on mid-grade producers caught between premium conservation-grade validation costs and economy-tier alkaline substitution threats.
Pricing Analysis
Third-party substrate compatibility validation is unbundled from base product pricing, forcing heritage contractors to absorb separate laboratory testing fees while commercial maintenance buyers receive inclusive technical support. Pricing stratifies across premium-grade conservation formulations with ECHA REACH Annex XVII compliance, standard-grade biodegradable surfactants, and economy-tier alkaline alternatives. Cost compression in standard-grade segments is intensifying as citrate supply volatility squeezes gluconate-dependent formulators. Commercial maintenance contractors exhibit highest price sensitivity, while UNESCO-protected monument procurement tolerates substantial premiums for documented substrate safety.
Supply Chain Analysis
Direct-to-conservation-authority channels handle specification-grade volume for Italian travertine restoration, while retail distributors and industrial chemical suppliers manage commercial maintenance flows. Manufacturing concentrates in Italy, Germany, and France where REACH compliance infrastructure anchors formulation expertise. Raw material dependencies center on Brazilian sugarcane-derived citric acid, European fermentation-based gluconates, and Asian-sourced plant-derived surfactants. Single-source vulnerability in citric acid supply creates exposure to harvest volatility and currency fluctuation. Distribution runs through conservation specialty wholesalers, hardware retail networks, and direct contractor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around REACH-compliant formulation capabilities, with phosphonate-dependent legacy producers facing forced exit as ECHA Annex XVII deadlines eliminate non-compliant chemistries.
For Market Incumbents: Acquire accredited conservation testing laboratory partnerships to lock in specification access for UNESCO and national heritage monument contracts. Build backward integration into biodegradable chelating agent production to reduce exposure to Brazilian citric acid volatility. Defensive priority centers on securing ECHA REACH dossier completion ahead of competitor timelines, as delayed submissions risk permanent exclusion from European procurement channels.
For New Entrants and Emerging Players: Electrolyzed water on-site generation technology offers a service-based wedge against concentrate incumbents, converting capital expenditure into recurring maintenance contracts. Target mobile cleaning system pilots with French and Italian conservation contractors seeking packaging waste reduction. White-space concentration sits in antimicrobial EPA-registered formulations for lichen-infested shaded facades, where incumbent coverage remains sparse. Go-to-market should emphasize performance-based validation rather than brand heritage.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Italian specialty chemical producers with stranded phosphonate-dependent portfolios but intact conservation channel relationships. Long-term viability hinges on five-to-ten year heritage restoration backlogs across Mediterranean UNESCO sites. Acquisition archetype combines reformulation-ready manufacturing assets with existing contractor specification relationships. Signal to monitor: municipal green procurement mandate acceleration in Spain and Portugal as inflection indicator for biodegradable surfactant demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodegradable Chelating Agents | Captive gluconate production insulates margins from Brazilian sugarcane harvest volatility. |
| Conservation Testing Laboratory Partnership | Third-party validation capabilities unlock specification access for UNESCO monument contracts. |
| Electrolyzed Water System Deployment | On-site generation eliminates transport costs and packaging waste for large restoration projects. |
| EPA Antimicrobial Registration Investment | Registered formulations capture expanding biological growth control segments in shaded facade maintenance. |
| EU Green Deal Procurement Certification | Biodegradability credentials secure preferential access to municipal heritage budgets in France and Italy. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for limestone cleaner market sizing, supplemented by primary interviews with conservation contractors, specialty chemical formulators, heritage procurement officers, and distribution channel managers. ECHA REACH substance dossiers, EPA antimicrobial registration databases, and Italian conservation authority tender archives provided regulatory trajectory validation. Bottom-up volume estimates from product-format consumption patterns reconciled against top-down expenditure flows from national heritage budget disclosures.
Data-stream reconciliation across supply-side capacity assessments and demand-side procurement tracking shaped the analytical framework. Segmentation modeling spanned product format, application context, packaging configuration, and grade tier across the projection horizon. CAGRs were derived from trend extrapolation of heritage restoration spending patterns and surfactant substitution timelines. Industry-specific forecast inputs included travertine facade inventory estimates for Italian conservation districts and citric acid price elasticity coefficients for pH-neutral formulation cost structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA regulatory acceleration or Brazilian sugarcane harvest disruption scenarios. Projections reflect assumptions around REACH compliance timeline adherence and conservation budget continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Europe Mastic Remover Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
Green Floor Care Chemical Systems for Commercial Facilities Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Glass Cleaner Market
Cleaning Chemicals
Lens Cleaning Product Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Cleaning Chemicals Market
Cleaning Chemicals
Global Dust Suppression and Control Chemicals Market
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market