
 Global and US Inorganic Salt Market | 2026-2036
Global and US Inorganic Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Global and US Inorganic Salt Market Foresight
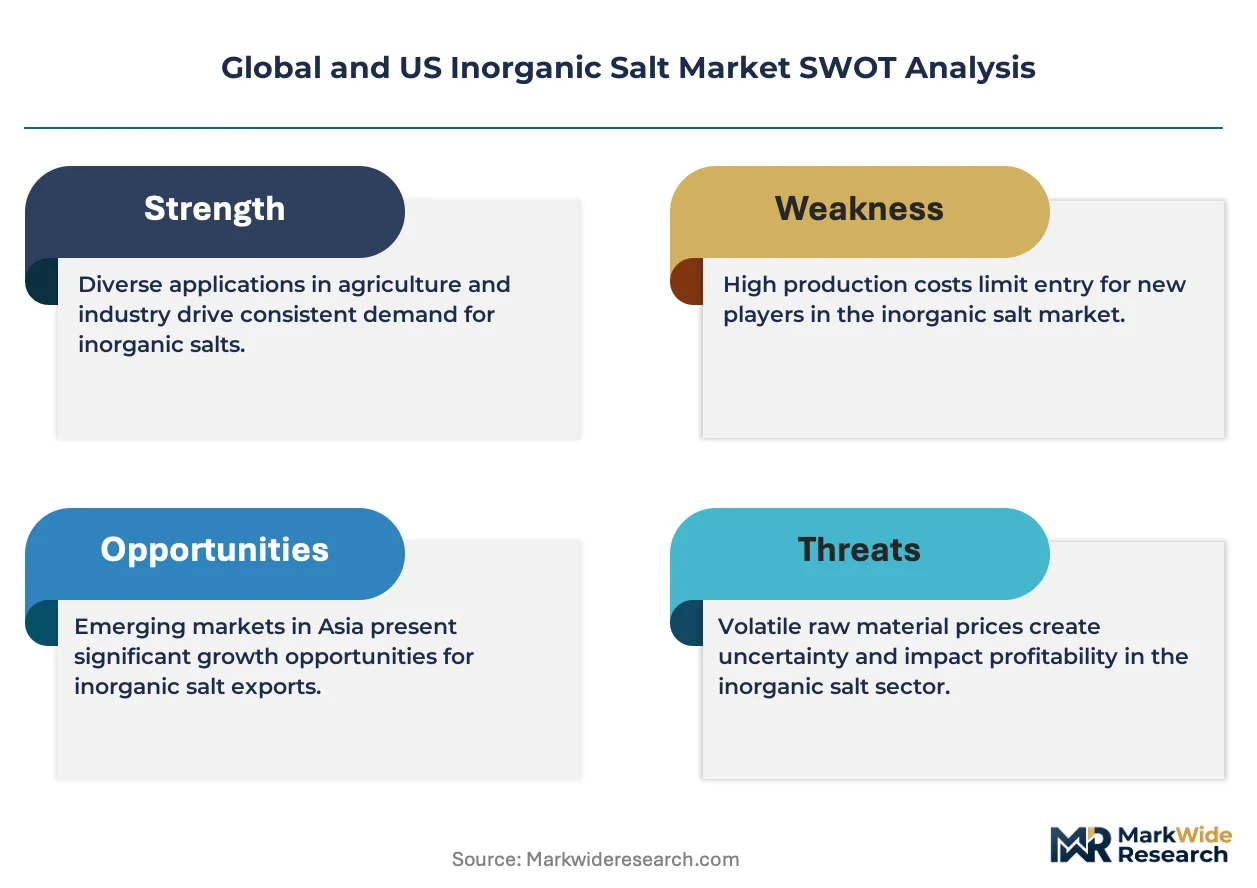
Sodium chloride is realigning economics across chlor-alkali value chains as caustic soda and chlorine derivatives face feedstock cost volatility. K+S Aktiengesellschaft leverages its European potash-salt integrated network to stabilize supply for North American chemical buyers. Tata Chemicals anchors its position through captive soda ash and sodium bicarbonate capacity serving US pharmaceutical formulators. Compass Minerals dominates highway deicing procurement cycles across the US Midwest and Northeast, where state DOT salt stockpiling creates predictable offtake patterns.
Inorganic salts comprise ionic compounds formed through neutralization or direct synthesis, typically characterized by high melting points, water solubility, and crystalline structures; sodium chloride, potassium chloride, and calcium chloride serve as feedstocks, fluxes, electrolytes, and conditioning agents across industrial processes. Sodium chloride and calcium chloride lead volume demand, with the former commanding the largest share in chlor-alkali and food processing applications while calcium chloride captures premium margins in oilfield completion fluids and dust control. Pharmaceutical grade and food grade segments concentrate margin pools, as USP and FCC certification requirements create formulation barriers that industrial grades cannot easily cross.
EPA effluent guidelines under the Clean Water Act constrain chloride discharge limits for municipal and industrial wastewater treatment, forcing operators toward higher-purity salt inputs that minimize secondary contamination. FDA food additive regulations and USP monographs govern sodium bicarbonate and potassium chloride incorporation into ingestible and injectable products, restricting sourcing to qualified GMP facilities. NSF/ANSI Standard 60 certification for drinking water treatment chemicals further narrows the supplier base for municipal procurement. Stakeholders must monitor evolving state-level chloride impairment designations, as Minnesota, Wisconsin, and New York move toward road salt reduction mandates that could reshape seasonal demand patterns and accelerate non-chloride deicing alternatives.
Market Dynamics
Chlor-alkali integration economics and salt dome logistics are compressing procurement cycles across North American chemical corridors, forcing buyers to consolidate supplier relationships around captive feedstock sources.
Growth Catalysts
- EPA effluent tightening:Municipal wastewater operators face stricter chloride discharge limits under Clean Water Act amendments, mandating higher-purity salt inputs that premium-grade suppliers can fulfill.
- Water treatment infrastructure:Aging US municipal systems require continuous regeneration capacity expansion, sustaining volume pull for ion-exchange resins and brine solutions.
- Gulf Coast chemical clustering:Proximity to Louisiana and Texas salt domes reduces inbound logistics costs for chlor-alkali producers, reinforcing regional procurement concentration.
Market Restraints
- Natural gas cost volatility:Evaporative salt production and chlor-alkali electrolysis both depend on natural gas pricing, exposing margin structures to Henry Hub fluctuations.
- Midwest supplier concentration:Highway deicing salt procurement concentrates around Great Lakes evaporative capacity, creating single-source vulnerability during severe winter demand spikes.
- Non-chloride substitution:Beet juice and potassium acetate blends are displacing calcium chloride in environmentally sensitive road maintenance contracts.
Strategic Opportunities
- Pharmaceutical-grade verticals:USP-certified sodium bicarbonate for injectable formulations commands 3-4x industrial-grade pricing, rewarding GMP facility investments.
- Food processing certification:FCC-grade potassium chloride substitution in reduced-sodium products aligns with FDA sodium reduction targets for packaged foods.
- NSF/ANSI Standard 60:Drinking water chemical certification creates a qualified-supplier moat for municipal procurement contracts, filtering out commodity traders.
Industry Challenges
- Geotechnical permitting timelines:Solution mining and salt dome cavern expansion face multi-year state environmental review processes, constraining capacity responsiveness.
- Multi-grade inventory complexity:Simultaneous certification maintenance for USP, FCC, NSF/ANSI, and industrial specifications fragments production scheduling and quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global and US Inorganic Salt Market |
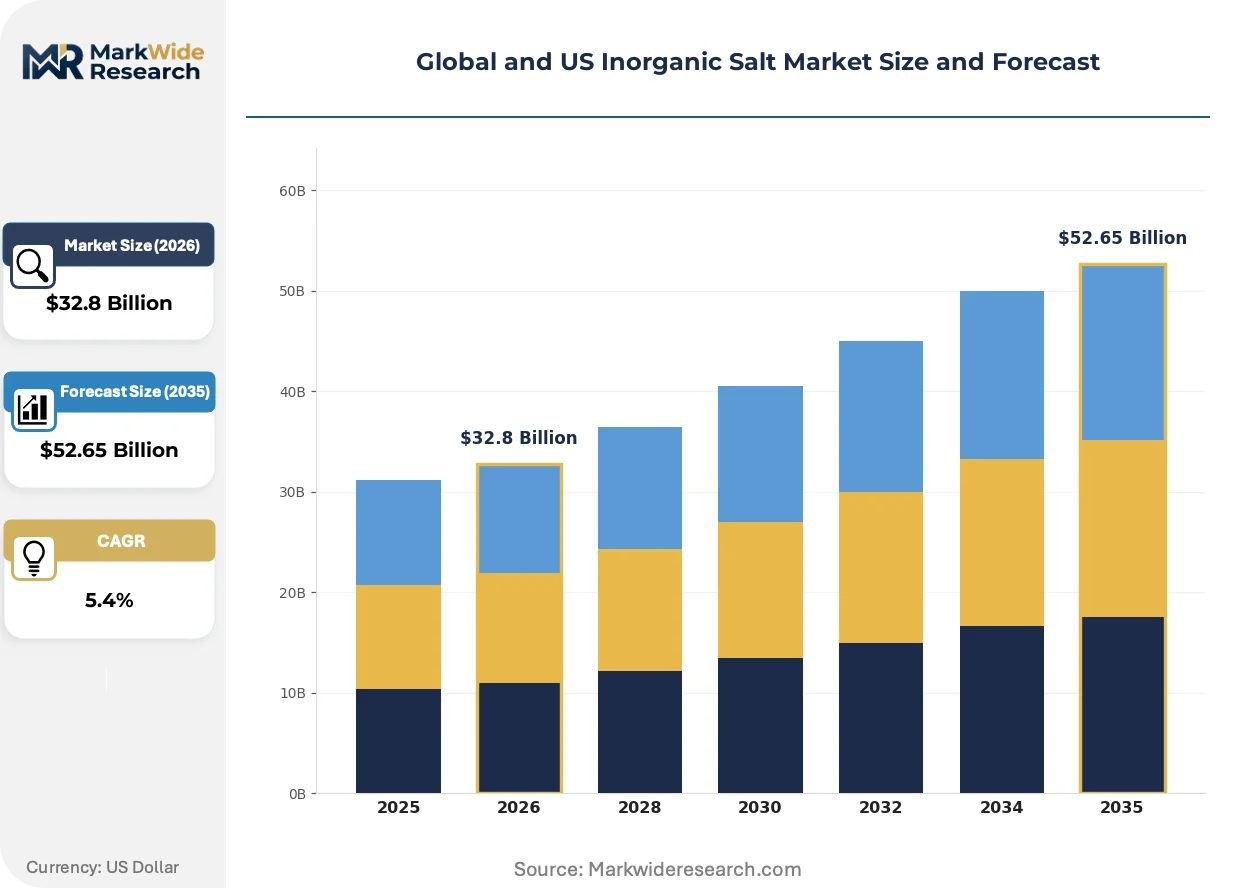
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Chloride, Potassium Chloride, Calcium Chloride, Magnesium Sulfate, Sodium Bicarbonate, Ammonium Chloride Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Agricultural Grade, Technical Grade, Laboratory Grade End Use Industry: Water Treatment, Chemical Manufacturing, Deicing, Animal Nutrition, Textile Processing, Oilfield Services Packaging Type: Bulk Bags, Paper Bags, Plastic Bags, Drums, Jumbo Bags, Loose Bulk |
| Companies Covered | K+S Aktiengesellschaft, Tata Chemicals, Cargill, Morton Salt, China National Salt Industry Corporation, Compass Minerals, INEOS Group Holdings, Nutrien Ltd., ICL Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global and US Inorganic Salt Market Shifts & Advancements
Process intensification and digital brine monitoring are compressing traditional extraction-to-delivery timelines while regulatory grade proliferation fragments supplier economics.
Membrane cell chlor-alkali technology is modularizing plant-scale deployment, enabling mid-cap chemical operators to enter regional chlorine derivatives markets without billion-dollar integrated complexes. US Gulf Coast independents are adopting skid-mounted units at 50-70% faster commissioning timelines than conventional mercury or diaphragm cell retrofits. This distributed architecture is compressing minimum efficient scale thresholds and fragmenting historical supply territory boundaries.
REACH authorization requirements for mercury cell phase-out are forcing European chlor-alkali operators toward membrane conversion or permanent closure, redirecting spot chlorine and caustic soda trade flows toward import dependence. The regulation's 2025 technical deadline is accelerating asset retirement decisions in Germany and Poland. North African and Middle Eastern membrane capacity is capturing displaced European chlorine derivative demand.
State DOTs are consolidating deicing salt procurement into multi-year framework agreements with performance-based delivery clauses, displacing spot-market purchasing that dominated pre-2020 winter seasons. Minnesota, Wisconsin, and New York are embedding chloride reduction mandates into contract specifications, requiring suppliers to certify environmental impact metrics alongside traditional purity standards. This behavioral shift concentrates volume with integrated producers capable of traceability documentation.
Global and US Inorganic Salt Market Segmentation
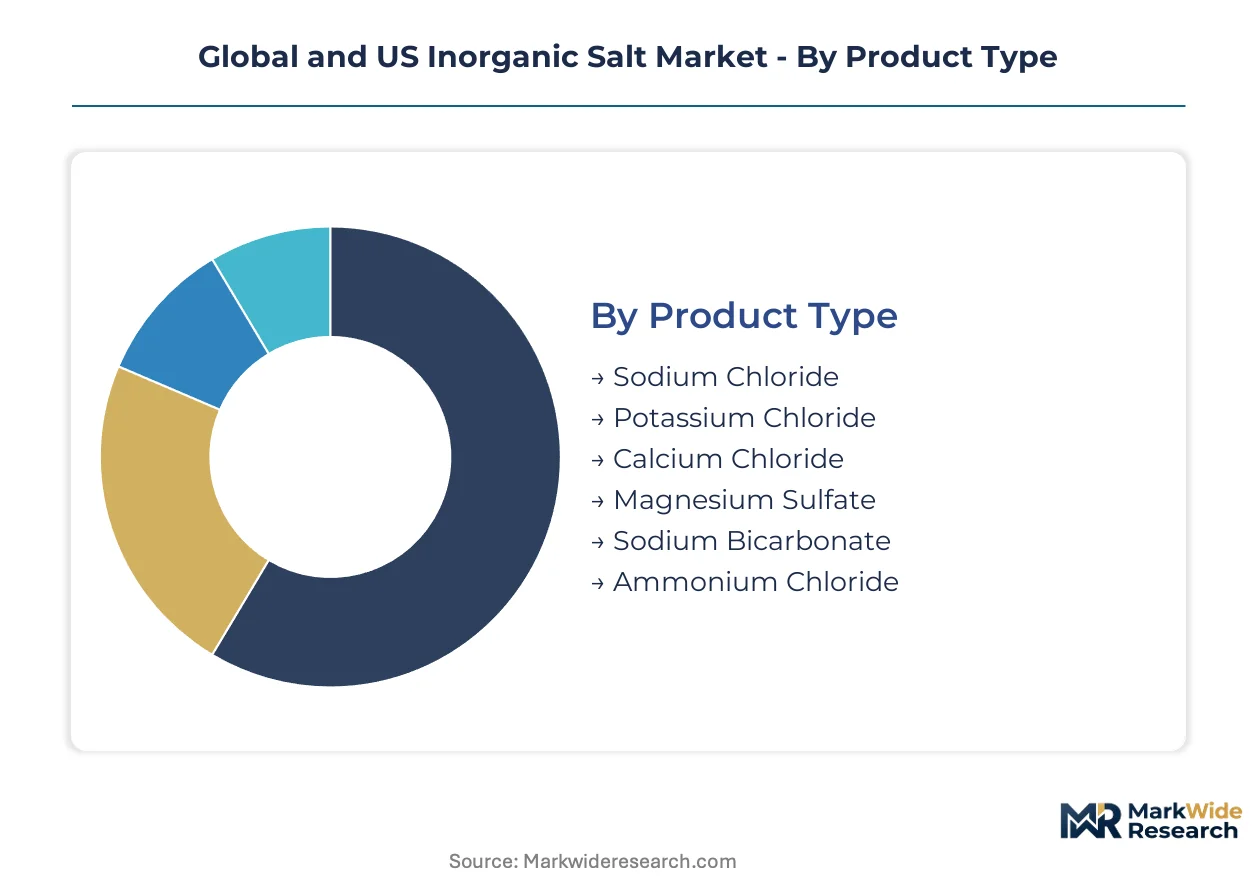
Inorganic salt procurement patterns fragment sharply across certification tiers and end-use specifications. Grade purity requirements and packaging logistics create distinct margin pools that suppliers must navigate simultaneously.
Product Type:
Replacement cycles vary dramatically across salt chemistries, with chlor-alkali feedstocks demanding continuous resupply while specialty grades operate on campaign-based production schedules.
- Sodium Chloride:Halite-derived or solution-mined crystals serve as the foundational electrolyte for membrane cell chlor-alkali operations and water softening regeneration. US Gulf Coast chemical corridors concentrate demand where salt dome access minimizes inbound logistics costs for caustic soda and chlorine producers.
- Potassium Chloride:Sylvinite ore beneficiation yields high-purity KCl for reduced-sodium food formulations and agricultural fertilizer compounding. Midwest grain belt distribution networks and FDA sodium reduction mandates for packaged foods are pulling volume toward FCC-certified grades.
- Calcium Chloride:By-product of Solvay soda ash synthesis or natural brine processing; hygroscopic properties suit oilfield completion fluids and dust suppression. Premium drilling applications in Permian Basin shale plays sustain margin premiums over industrial grades.
- Magnesium Sulfate:Epsom salt applications span agricultural foliar feeding and pharmaceutical laxative formulations. USP monograph compliance for injectable preparations restricts sourcing to qualified GMP facilities.
- Sodium Bicarbonate:Synthetic ash or refined trona processing produces this versatile buffer for antacid pharmaceuticals, baking applications, and flue gas desulfurization. USP certification for hemodialysis and intravenous solutions commands 3-4x industrial-grade pricing.
- Ammonium Chloride:Ammonia-hydrochloric acid neutralization yields this nitrogen source for dry cell batteries and metal surface treatment baths. Electronics-grade specifications for zinc-carbon battery manufacture require heavy metal content below 5 ppm.
Sodium chloride sits at the top of the volume ranking, with sodium bicarbonate climbing the fastest on pharmaceutical and environmental applications.
Grade:
Certification maintenance costs stratify supplier economics, with multi-grade producers capturing procurement consolidation benefits that single-tier competitors cannot match.
- Food Grade:FCC-compliant salts meet FDA food additive regulations for direct human consumption, processing aids, and preservation. Clean label trends and sodium reduction targets in packaged foods are accelerating potassium chloride substitution formulations.
- Pharmaceutical Grade:USP monograph adherence and GMP facility certification govern sodium bicarbonate, potassium chloride, and magnesium sulfate for injectable, oral, and topical drug products. Batch documentation and stability testing requirements create 12-18 month supplier qualification timelines.
- Industrial Grade:Technical specifications prioritize chemical purity over biological safety, serving chlor-alkali electrolysis, textile dyeing, and general chemical synthesis. Henry Hub natural gas pricing directly impacts evaporative production economics.
- Agricultural Grade:Bulk fertilizer and animal feed applications tolerate higher insoluble content in exchange for cost efficiency. Midwest distribution cooperatives and integrated poultry operations dominate procurement patterns.
- Technical Grade:Intermediate purity tier serves water treatment, metal finishing, and oilfield applications where performance specifications exceed industrial baselines but full pharmaceutical documentation is unnecessary.
- Laboratory Grade:ACS or reagent specifications for analytical chemistry and research applications require lot-to-lot consistency and impurity profiling that commodity production cannot sustain.
Industrial grade commands the largest volume position, though pharmaceutical grade expands most quickly on biologics manufacturing growth and parenteral nutrition demand.
End Use Industry:
Application-specific performance requirements fragment demand across regulatory jurisdictions, with each end-use imposing distinct purity, documentation, and logistics constraints.
- Water Treatment:NSF/ANSI Standard 60 certification restricts municipal drinking water chemical procurement to qualified suppliers. EPA effluent guideline tightening under Clean Water Act amendments is mandating higher-purity salt inputs to minimize secondary chloride contamination.
- Chemical Manufacturing:Chlor-alkali integration and chlorine derivative synthesis consume sodium chloride as primary feedstock. Louisiana and Texas salt dome proximity reduces delivered cost advantages for Gulf Coast producers.
- Deicing:State DOT procurement consolidation into multi-year framework agreements is displacing spot-market purchasing. Minnesota, Wisconsin, and New York chloride reduction mandates are embedding environmental impact metrics into contract specifications.
- Animal Nutrition:Feed-grade salts provide essential sodium, chloride, and trace mineral supplementation for livestock and poultry operations. Integrated protein producers and regional feed mills coordinate bulk deliveries around production cycles.
- Textile Processing:Dye bath electrolytes and fabric finishing agents employ sodium chloride and magnesium sulfate. Bangladesh and Vietnam garment manufacturing clusters are pulling Asian salt trade flows.
- Oilfield Services:Completion fluids, workover brines, and dust suppression formulations demand calcium chloride and potassium chloride with specific density and crystallization point requirements. Permian Basin drilling activity sustains regional demand concentration.
Water treatment anchors volume demand, with pharmaceutical manufacturing gaining share fastest on parenteral drug capacity expansion.
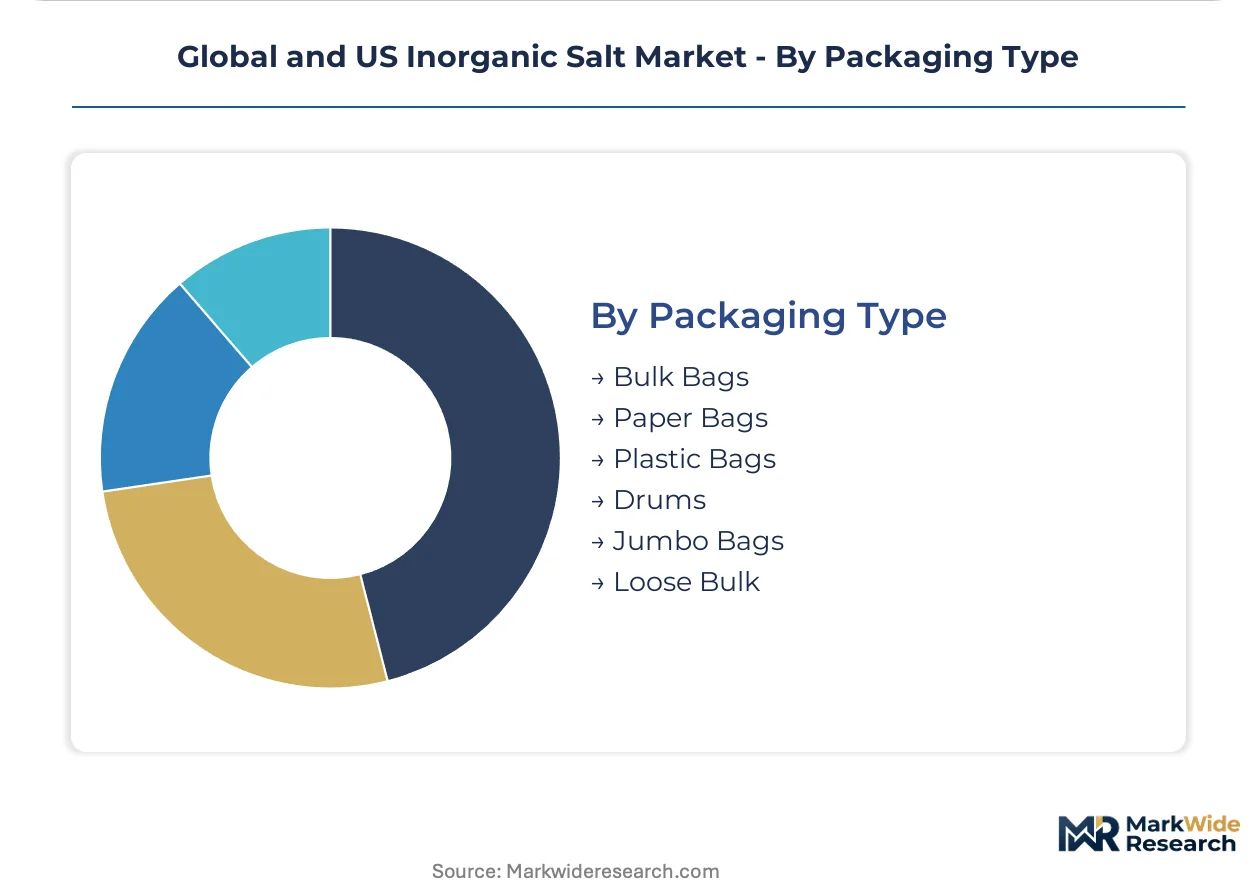
Packaging Type:
Logistics economics and handling infrastructure determine format selection, with bulk systems favoring integrated producers and bagged formats sustaining distributor networks.
- Bulk Bags:Flexible intermediate bulk containers of 500-2000 kg capacity suit food processing and chemical manufacturing with pneumatic handling systems. Midwest grain elevators and Gulf Coast chemical terminals dominate deployment.
- Paper Bags:Multi-wall kraft construction for 25-50 kg food-grade and pharmaceutical-grade distribution. Moisture resistance limitations restrict shelf life in humid climates.
- Plastic Bags:Polyethylene or polypropylene woven sacks for industrial and agricultural grades where moisture protection exceeds sustainability priorities.
- Drums:Fiber or steel containment for laboratory-grade, high-purity, and hazardous classification salts requiring sealed storage. Pharmaceutical and electronics chemical distributors favor this format.
- Jumbo Bags:>2000 kg flexible containers for chlor-alkali and large-volume water treatment operations with dedicated unloading equipment.
- Loose Bulk:Pneumatic or conveyor delivery for integrated chemical producers with captive salt dome access or direct mine mouth arrangements.
Loose bulk leads volume throughput, though bulk bags gain ground fastest on mid-scale food processor automation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast chemical corridor concentrates chlor-alkali feedstock demand where Louisiana salt dome access minimizes inbound logistics costs for caustic soda and chlorine producers.
United States
EPA effluent guideline tightening under Clean Water Act amendments mandates higher-purity salt inputs for municipal wastewater operators. NSF/ANSI Standard 60 certification restricts drinking water chemical procurement to qualified suppliers. Minnesota, Wisconsin, and New York chloride reduction mandates embed environmental impact metrics into state DOT deicing contracts.
Germany
REACH authorization requirements for mercury cell phase-out force chlor-alkali operators toward membrane conversion or permanent closure by 2025. ECHA technical deadlines accelerate asset retirement decisions in Germany and Poland. North Rhine-Westphalia chemical clusters redirect spot chlorine trade flows toward import dependence on North African membrane capacity.
China
GB standards for food-grade salt processing align with FDA sodium reduction targets for packaged foods. MIIT industrial policy prioritizes membrane cell technology deployment in coastal chemical provinces. Shandong Peninsula evaporative salt capacity serves domestic chlor-alkali expansion and Southeast Asian export markets.
India
FSSAI food additive regulations govern sodium bicarbonate and potassium chloride incorporation into processed foods. BIS technical specifications for industrial-grade salts support textile dyeing clusters in Gujarat and Tamil Nadu. Maharashtra pharmaceutical corridors pull USP-certified grades for injectable and oral drug formulations.
Brazil
ANVISA pharmaceutical monographs restrict sourcing of magnesium sulfate and sodium bicarbonate to qualified GMP facilities. Agricultural grade potassium chloride demand concentrates in Mato Grosso and Goiás grain belts for soybean fertilizer compounding. São Paulo state feed mills coordinate bulk salt deliveries around poultry production cycles.
Global and US Inorganic Salt Market Competitive Landscape
Capacity expansion dominates the current landscape as membrane cell chlor-alkali technology modularizes plant-scale deployment. The vendor base stratifies across integrated salt dome operators, specialty chemical diversifiers, and regional evaporative producers. Three archetypes anchor competitive positioning: captive feedstock integrators, multi-grade certification specialists, and seasonal deicing volume players. M&A activity and strategic partnerships concentrate procurement relationships around qualified supplier networks.
Among European integrated operators, K+S Aktiengesellschaft anchors the captive feedstock archetype through its potash-salt network. Tata Chemicals occupies a position within the multi-grade certification tier, exemplifying specialty chemical diversification. Compass Minerals represents the seasonal volume archetype, sitting within North American highway deicing procurement consolidation.
| Leading Market Players |
|---|
| K+S Aktiengesellschaft |
| Tata Chemicals |
| Cargill |
| Morton Salt |
| China National Salt Industry Corporation |
| Compass Minerals |
| INEOS Group Holdings |
| Nutrien Ltd. |
| ICL Group |
| Others |
Supply & Pricing Matrix
Family-owned evaporative salt producers in the US Great Lakes basin and German potash-salt integrated groups anchor supply discipline through generational mine holdings and captive dome access, translating geological scarcity into pricing power across chlor-alkali and deicing procurement cycles.
Pricing Analysis
Natural gas pass-through clauses in long-term chlor-alkali supply contracts tether evaporative salt pricing to Henry Hub volatility, compressing margins when feedstock costs spike. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade levels separates USP-certified sodium bicarbonate at 3-4x premiums from bulk road salt. Price differentiation stems from certification maintenance costs and volume scale, with state DOT bulk tenders commanding lowest unit economics. Pricing pressure intensifies in industrial grades as membrane cell technology modularization lowers minimum efficient scale thresholds for new chlor-alkali entrants. Pharmaceutical buyers exhibit least price sensitivity due to 12-18 month supplier qualification timelines, while agricultural feed mills and textile dyers face acute cost compression.
Supply Chain Analysis
Return flows of spent brine from municipal water softening regeneration create circular input streams for re-evaporation, though contamination risks limit reprocessing to technical-grade applications. Supply concentrates in the United States, Germany, and China, with Louisiana salt dome access and Shandong Peninsula evaporative capacity anchoring regional cost advantages. Raw material dependencies center on natural gas for thermal evaporation, sylvinite ore for potassium chloride beneficiation, and trona deposits for synthetic soda ash synthesis. Single-source vulnerability pervades Midwest highway deicing procurement, where Great Lakes freeze-thaw cycles constrain seasonal production windows. Distribution runs through integrated chemical terminals on the US Gulf Coast and regional distributor networks for bagged specialty grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as EPA effluent tightening and NSF/ANSI Standard 60 certification requirements concentrate procurement around qualified suppliers capable of traceability documentation.
For Market Incumbents: Anchor defensive positioning through captive salt dome expansion in Louisiana and Texas to secure chlor-alkali feedstock supply, while accelerating multi-grade certification investments to capture pharmaceutical and food-grade margin pools. Non-chloride deicing substitutes and REACH-driven European mercury cell phase-outs threaten volume in seasonal and export segments. For New Entrants and Emerging Players: Capture white-space in USP-certified sodium bicarbonate for parenteral formulations and FCC-grade potassium chloride for reduced-sodium food processing, where incumbent qualification backlogs create procurement gaps. Midwest grain belt distribution networks and Maharashtra pharmaceutical corridors represent the most penetrable geographies for specialty-grade market entry through GMP facility partnerships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional evaporative producers with unexploited dome access and single-grade dependence on highway deicing, where multi-year DOT framework agreements provide cash flow visibility. Long-term viability favors backward integration into solution mining and membrane chlor-alkali technology. Monitor state-level chloride impairment designations in Minnesota, Wisconsin, and New York as inflection signals for deicing demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Salt Dome Access | Louisiana and Texas geological reserves secure captive chlor-alkali feedstock economics. |
| Multi-Grade Certification Investment | Simultaneous USP, FCC, and NSF/ANSI qualification opens pharmaceutical and municipal water procurement. |
| Membrane Cell Technology Deployment | Skid-mounted units compress commissioning timelines versus mercury cell retrofits. |
| Long-Term DOT Framework Agreements | Multi-year deicing contracts with performance clauses displace spot-market volatility. |
| Joint Venture for Pharmaceutical-Grade Capacity | GMP facility partnerships with Maharashtra drug manufacturers accelerate qualification timelines. |
Research Methodology
Multiple input streams — executive interviews with chlor-alkali plant managers and procurement leads at downstream chemical OEMs, distributor channel partner discussions, and technical R&D director consultations — were reconciled against customs and trade data, ACC industry reports, SEC 10-K filings, and EPA discharge monitoring records. Bottom-up volume modeling across grade tiers and end-use industries was cross-validated through top-down macroeconomic anchoring.
Historical capacity utilization patterns were cross-referenced against panel input from salt dome operators and membrane technology vendors to construct projection assumptions across the analysis window. Segmentation dimensions modeled include grade purity tier, end-use industry application, packaging format, and regional production hub concentration. CAGRs were derived through regression analysis of feedstock cost trajectories and regulatory compliance cost escalation, with natural gas price volatility and state DOT procurement consolidation serving as primary forecast sensitivity inputs.
Regulatory enforcement intensity, membrane cell adoption velocity, and chloride substitution penetration are the dominant revision risks to volume and value projections. Forecasts embed assumptions regarding EPA effluent guideline implementation timelines and REACH authorization adherence. Practitioners should monitor state-level road salt reduction mandate progression and European mercury cell retirement announcements for early signals of demand displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Pyrophyllite Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Snowflake Salt Market
Industrial Minerals
Kyanite Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
Europe Limestone Market