
 Dicaprylyl Carbonate Market | 2026-2036
Dicaprylyl Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Dicaprylyl Carbonate Market Analytics
Buyer concentration in the prestige cosmetics sector is decoupling from traditional mass-market procurement patterns as indie skin care brands multiply their sourcing relationships. BASF SE leverages its integrated alkoxide chemistry platform to secure feedstock reliability for high-purity grades. Croda International differentiates through biotechnology-derived routes that reduce petrochemical dependency. Solvay anchors European supply with dedicated carbonate ester capacity at its Tavaux site in France.
Dicaprylyl carbonate is a dialkyl carbonate ester synthesized via transesterification of dimethyl carbonate with caprylyl alcohol, yielding a clear, low-viscosity liquid with a dry, silky skin feel and excellent spreadability. It functions primarily as an emollient, solvent, and texture modifier in cosmetic formulations, prized for its ability to dissolve UV filters and pigments without residual greasiness. Skin care applications dominate current volume, while sun care represents the fastest-expanding segment as mineral filter suspensions demand compatible dispersing oils. The formulation dimension shows serum formats capturing disproportionate margin pools compared to lotion and cream bases.
REACH registration requirements govern substance identity and safety dossiers for all European cosmetic ingredient placements, while FDA oversight applies to finished product claims and Good Manufacturing Practice compliance in the United States. South Korea's MFDS enforces functional cosmetics approval pathways that elevate documentation burdens for novel emollients entering the K-beauty supply chain. Stakeholders must monitor evolving biodegradability criteria under the EU Green Deal's sustainable chemicals taxonomy, as these will progressively filter eligible feedstocks and process technologies.
Market Dynamics
Prestige skin care procurement is fragmenting as indie brands multiply sourcing relationships, decoupling from traditional mass-market concentration and forcing suppliers to rebuild commercial models around smaller, more demanding accounts.
Growth Catalysts
- K-Beauty Manufacturing Cluster:South Korea's MFDS functional cosmetics pathway elevates documentation standards that premium brands now demand globally, pulling high-purity dicaprylyl carbonate volumes toward Seoul and Incheon.
- REACH Registration:ECHA substance identity requirements create compliance moats for registered suppliers, squeezing unregistered traders from European cosmetic ingredient supply chains.
- Mineral UV Filter Suspensions:Zinc oxide and titanium dioxide dispersibility needs in sun care formulations are accelerating emollient ester substitution away from legacy petrolatum bases.
Market Restraints
- Caprylyl Alcohol Feedstock Volatility:Palm kernel and coconut oil derivative pricing swings transmit directly into carbonate ester cost structures, compressing margin predictability for non-integrated producers.
- Dimethyl Carbonate Supply Concentration:Chinese producers dominate the transesterification feedstock, exposing European and North American formulators to shipping cost spikes and customs processing delays.
- Biodegradability Certification Gaps:OECD 301B test data scarcity for novel alkyl carbonate grades blocks placement in EU Green Deal-aligned product lines seeking sustainable chemicals taxonomy eligibility.
Strategic Opportunities
- Brazilian Sun Care Expansion:ANVISA's streamlined cosmetic notification pathway enables faster market entry for dispersing oil innovations targeting the hemisphere's highest per-capita sunscreen consumption.
- Biotechnology-Derived Routes:Fermentation-based caprylyl alcohol production converges with enzymatic transesterification to eliminate petrochemical dependency for carbon-conscious beauty brands.
- Direct-to-Formulator Platforms:Specialty chemical distributors are launching digital sample-to-scale portals that bypass traditional regional agent networks and compress qualification timelines.
Industry Challenges
- Alkoxide Chemistry Talent Scarcity:The specialized skill set for high-purity carbonate ester synthesis is concentrating at integrated majors, constraining mid-scale entrants from achieving specification-grade output.
- MFDS Documentation Burden:South Korea's functional cosmetics approval timelines extend 12-18 months for novel emollients, freezing formulation innovation cycles for brands targeting K-beauty manufacturing partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dicaprylyl Carbonate Market |
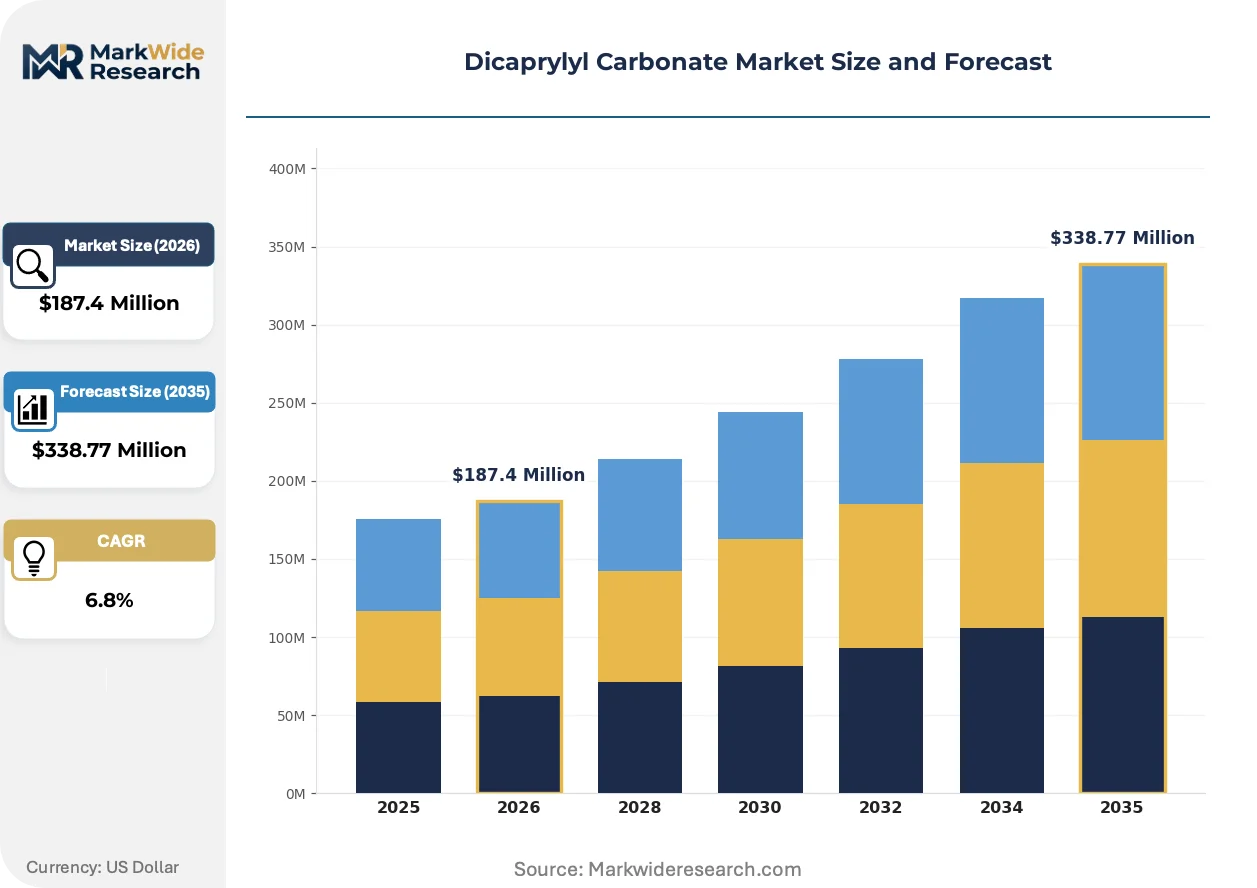
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Pharmaceuticals, Personal Care, Industrial Applications Formulation: Lotion, Cream, Serum, Gel Application: Skin Care, Hair Care, Sun Care, Makeup End User: Manufacturers, Brand Owners, Distributors, Retailers |
| Companies Covered | BASF SE, Solvay, Croda International, Evonik Industries, Taiwan NJC Corporation, Dow Inc., Ashland, Clariant, Symrise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dicaprylyl Carbonate Market Evolving Landscape
Biotechnology pathways and regulatory taxonomy evolution are compressing the viable technology set for cosmetic emollients, while procurement fragmentation forces suppliers to rebuild commercial architectures around dispersed, demanding accounts.
Enzymatic transesterification using immobilized lipase catalysts is electrifying process economics for high-purity dicaprylyl carbonate production. Indie skin care brands and contract manufacturers in South Korea are adopting these grades within compressed qualification cycles. The technology is electrifying competitive positioning by enabling carbon footprint claims that REACH-registered petrochemical routes cannot match.
ECHA's evolving biodegradability criteria under the EU Green Deal sustainable chemicals taxonomy are tightening feedstock eligibility filters. Cosmetic ingredient suppliers must now document OECD 301B pass rates and renewable carbon content percentages to maintain placement in premium formulations. Sun care applications face the steepest compliance ramps as mineral filter suspensions demand dispersing oils with verified environmental fate profiles.
Buyer concentration in prestige cosmetics is splintering as direct-to-consumer brands proliferate and fragment procurement volumes. Traditional regional distributors are losing share to specialty chemical platforms offering sample-to-scale digital workflows and technical formulation support. This restructuring is most visible in South Korea's K-beauty cluster, where Seoul-based indie brands now source directly from European carbonate ester producers rather than through incumbent trading houses.
Dicaprylyl Carbonate Market Segmentation
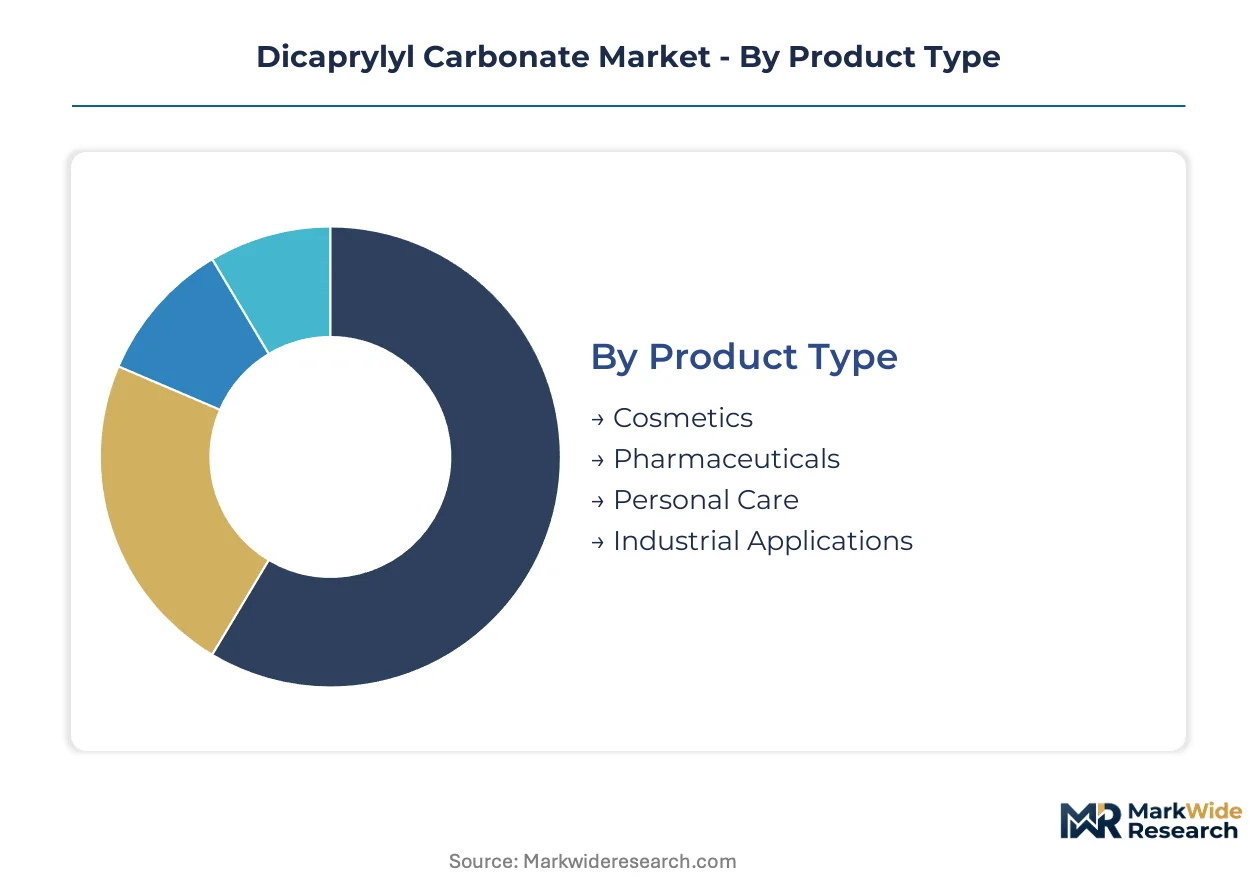
Dicaprylyl carbonate serves distinct functional roles across cosmetic and industrial value chains, with formulation chemistry and end-use specifications determining procurement patterns. Segmentation reveals where premium grades command margin premiums versus commodity applications competing on cost.
Product Type:
Integration depth varies sharply — cosmetics and pharmaceuticals demand certified high-purity grades with full traceability documentation, while industrial applications absorb technical-grade material with minimal regulatory overhead.
- Cosmetics:High-purity dicaprylyl carbonate meeting REACH and MFDS specifications dominates prestige skin care procurement. Seoul-based K-beauty manufacturers specify enzymatic-derived grades for carbon-neutral product lines.
- Pharmaceuticals:USP-grade material with validated impurity profiles serves topical drug delivery systems. FDA compliance requirements create qualification barriers that registered suppliers exploit.
- Personal Care:Mid-tier grades balance performance against cost for mass-market lotion and shampoo applications. Distributors in Brazil and Southeast Asia concentrate procurement volumes here.
- Industrial Applications:Technical-grade carbonate esters function as lubricity modifiers and solvent carriers. Price sensitivity limits supplier margins to volume-scale producers with integrated feedstock positions.
Cosmetics leads volumes today; pharmaceuticals is gaining share fastest.
Formulation:
Cost tier structures segment procurement — serum formats capture premium positioning through concentrated active delivery, while lotion and cream bases compete on manufacturing efficiency.
- Serum:Lightweight, fast-absorbing vehicles demand low-viscosity dicaprylyl carbonate with superior spreadability. South Korean indie brands specify these grades for functional cosmetics requiring MFDS approval pathways.
- Cream:Emulsion stability requirements drive demand for grades with defined polarity and freeze-thaw resistance. European prestige houses anchor procurement volumes through established supply agreements.
- Lotion:Cost-optimized formulations absorb standard-grade material with broader specification tolerances. Mass-market producers in Brazil leverage ANVISA's streamlined notification pathway for faster product launches.
- Gel:Clear-base compatibility restricts eligible grades to ultra-low color and odor specifications. Sun care applications here require verified biodegradability data under EU Green Deal criteria.
Serum commands the highest margins; gel formats are expanding most quickly.
Application:
Customer type determines specification intensity — prestige brand owners demand certified sustainable grades, while contract manufacturers prioritize supply security and formulation flexibility.
- Skin Care:Facial moisturizers and treatment products specify dicaprylyl carbonate for dry, silky after-feel without occlusivity. Biotechnology-derived routes are displacing petrochemical grades in premium European lines.
- Sun Care:Mineral UV filter suspensions require dispersing oils with verified compatibility for zinc oxide and titanium dioxide. OECD 301B biodegradability certification is becoming mandatory for EU placement.
- Hair Care:Leave-in conditioners and styling products employ carbonate esters for heat protection and cuticle sealing. Volume concentration sits with mass-market producers in Asia-Pacific manufacturing hubs.
- Makeup:Pigment wetting and long-wear properties drive specification for low-surface-tension grades. Indie brands fragment procurement through direct-to-formulator platforms.
Skin care anchors current demand; sun care shows the steepest expansion trajectory.
End User:
Supply concentration shapes access patterns — integrated manufacturers capture captive demand, while fragmented brand owners multiply sourcing relationships and compress qualification timelines.
- Manufacturers:Contract producers in South Korea's Seoul-Incheon cluster specify high-purity grades with full documentation packages. REACH registration status filters supplier eligibility for European-bound production.
- Brand Owners:Prestige houses and indie labels increasingly source directly from European carbonate ester producers. Digital sample-to-scale platforms are displacing traditional regional distributor relationships.
- Distributors:Specialty chemical distributors aggregate fragmented demand from mid-scale formulators. Inventory positioning and technical support capabilities differentiate competitive positioning.
- Retailers:Private-label skin care programs specify dicaprylyl carbonate for quality parity with branded alternatives. Sustainability certification requirements are tightening feedstock eligibility.
Manufacturers dominate procurement volumes today; brand owners are restructuring sourcing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alkoxide chemistry specialists concentrate in Germany's industrial Rhine corridor, while enzymatic process engineers cluster around South Korea's biotech research institutes.
United States
Prestige skin care formulators in New York and Los Angeles drive demand for REACH-registered grades. FDA oversight of finished product claims elevates documentation requirements for cosmetic ingredient suppliers. The Northeast corridor hosts contract manufacturers qualifying novel emollients for indie brand portfolios.
Germany
ECHA's substance identity requirements filter supplier eligibility for European cosmetic ingredient placements. The EU Green Deal's sustainable chemicals taxonomy tightens feedstock traceability standards. BASF SE anchors supply through integrated alkoxide chemistry capacity at its Ludwigshafen complex.
France
Solvay maintains dedicated carbonate ester production at its Tavaux site serving prestige cosmetics houses. REACH registration compliance creates competitive moats against unregistered traders. The Rhône-Alpes region concentrates formulation chemistry expertise for high-purity emollient grades.
South Korea
MFDS functional cosmetics approval pathways extend 12-18 months for novel emollients entering K-beauty supply chains. Seoul and Incheon host manufacturing clusters specifying enzymatic-derived grades for carbon-neutral product lines. Indie brands fragment procurement through direct-to-producer relationships.
Brazil
ANVISA's streamlined cosmetic notification pathway enables faster market entry for dispersing oil innovations. The São Paulo state manufacturing belt concentrates sun care production for the hemisphere's highest per-capita sunscreen consumption. Mass-market producers leverage cost-optimized grades for lotion formulations.
Dicaprylyl Carbonate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered supplier base. Integrated chemical majors leverage captive feedstock positions to secure margin predictability. Strategic archetypes separate into biotechnology-derived route pioneers, petrochemical-integrated incumbents, and regional trading intermediaries. Capacity expansion and enzymatic process licensing dominate competitive moves as carbon footprint claims displace legacy positioning.
Among European-integrated majors, BASF SE and Solvay occupy positions anchored by alkoxide chemistry infrastructure and dedicated carbonate ester capacity. Croda International exemplifies the biotechnology-derived archetype, representing enzymatic route capabilities that reduce petrochemical dependency. These three companies sit within distinct strategic tiers rather than competing directly on identical value propositions.
| Leading Market Players |
|---|
| BASF SE |
| Solvay |
| Croda International |
| Evonik Industries |
| Taiwan NJC Corporation |
| Dow Inc. |
| Ashland |
| Clariant |
| Symrise |
| Others |
Value Network & Pricing Analysis
MFDS functional cosmetics documentation requirements are forcing Seoul-based K-beauty manufacturers to specify enzymatic-derived grades with full traceability, compelling European suppliers to absorb certification costs and compress margin structures on high-purity carbonate esters.
Pricing Analysis
Capacity additions in enzymatic transesterification are reshaping price floors for biotechnology-derived grades. Pricing stratifies across premium enzymatic, standard petrochemical, and economy technical tiers, with OECD 301B certification and REACH registration status as primary differentiation drivers. Cost compression in standard petrochemical grades is intensifying as Chinese dimethyl carbonate feedstock volatility transmits into European formulator procurement. Mass-market lotion producers in Brazil exhibit highest price sensitivity; prestige serum formulators in South Korea show lowest.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and São Paulo anchor hub-and-spoke patterns for carbonate ester fulfillment. Manufacturing concentrates in Germany, France, and South Korea, with feedstock dependency on Malaysian palm kernel derivatives and Chinese dimethyl carbonate. Single-source vulnerability in dimethyl carbonate exposes European and North American formulators to shipping cost spikes. Distribution runs through specialty chemical platforms and traditional regional agents serving contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory amplifier where EU Green Deal biodegradability taxonomy and REACH registration requirements continuously elevate compliance barriers for new entrants.
For Market Incumbents: Cement alkoxide chemistry talent pools through dedicated training programs at Ludwigshafen and Tavaux sites, locking in specification-grade output capabilities that mid-scale entrants cannot replicate. Secure backward integration into caprylyl alcohol feedstocks to buffer palm kernel oil price volatility threatening margin predictability. For New Entrants and Emerging Players: Begin with enzymatic transesterification licensing partnerships to bypass alkoxide chemistry talent scarcity and capture carbon-neutral positioning premium. Brazil's ANVISA-streamlined sun care sector offers the most penetrable white space for dispersing oil innovations targeting mineral UV filter suspensions. For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology-derived route specialists holding enzymatic process patents and OECD 301B certification datasets. Long-term viability hinges on sustainable chemicals taxonomy alignment rather than commodity scale. Watch for MFDS approval timeline compression as inflection signal for K-beauty supply chain access.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Licensing | Enables carbon footprint claims that REACH-registered petrochemical routes cannot match for K-beauty procurement. |
| Backward Integration into Caprylyl Alcohol | Captive supply of palm kernel derivatives buffers margin volatility from feedstock price swings. |
| MFDS Documentation Investment | Accelerates functional cosmetics approval timelines for novel emollients entering Seoul-Incheon manufacturing clusters. |
| Direct-to-Formulator Platform Launch | Digital sample-to-scale portals bypass traditional regional agents and compress qualification cycles for indie brands. |
| OECD 301B Certification Program | Verified biodegradability data unlocks EU Green Deal-aligned product line placement for premium formulations. |
Research Methodology
Multiple input streams — primary interviews with cosmetic chemists and procurement leads, trade data reconciliation, and regulatory filing analysis — were reconciled to construct supply-demand balances. Conversations captured formulation preferences at K-beauty contract manufacturers, sustainability certification priorities at European prestige houses, and feedstock sourcing strategies at integrated alkoxide producers. Secondary validation drew from ECHA registration databases, MFDS functional cosmetics approvals, and customs records for dimethyl carbonate and caprylyl alcohol trade flows. Bottom-up volume builds and top-down market sizing were cross-checked for convergence.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include grade tier, formulation type, application, and end-user archetype. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Industry-specific forecast inputs incorporated OECD 301B certification penetration rates and enzymatic process yield improvements.
Several conditions sit outside the modeled scope, including sudden palm kernel oil supply disruptions, unilateral tariff impositions on Chinese dimethyl carbonate, and breakthrough fermentation technologies displacing current caprylyl alcohol production routes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Coagulant Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Formalin Vials Market
Chemicals
Egypt Construction Chemicals Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Monoisopropanolamine (MIPA) Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Asia-Pacific Methanol Market
Chemicals
Peroxyacetic Acid Market
Chemicals
Precious Metal Plating Chemicals Market
Chemicals
India Methanol Market
Chemicals
Cupric Chloride Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
3-Iodoaniline Market
Chemicals
Global Benzalkonium Chloride Market