
 Limestone Market | 2026-2036
Limestone Market Size, Share, and Industry Trends Forecast 2026-2036
Limestone Market Intelligence
Multi-source procurement is pivoting toward captive quarry ownership among integrated building materials groups. Lhoist Group leverages deep vertical integration across European and North American quarry networks to secure feedstock consistency. Carmeuse Group anchors its competitiveness through specialized quicklime and slaked lime production for steel desulfurization. Graymont Limited dominates Pacific Rim supply through long-term mineral leases in British Columbia and New Zealand.
Limestone is a sedimentary rock composed primarily of calcium carbonate, typically formed from marine organism accumulation and lithified under pressure over geological timescales, with industrial grades requiring minimum CaCO₃ content of 90-95% for chemical processing applications. Quicklime and slaked lime command premium positioning in steel and chemical end-use industry segments where purity thresholds and reactivity specifications determine contract value. Ground limestone occupies mature, volume-driven positions in cement formulation where margin pools thin but offtake scale sustains quarry economics.
EPA emissions standards for lime kilns in the United States and REACH chemical registration requirements in Europe constrain operational permits and product market access for non-compliant producers. India's CEA environmental clearances and BIS quality certification for construction minerals add compliance layers that favor organized suppliers with integrated testing infrastructure. Stakeholders must monitor regulatory divergence between carbon-intensive jurisdictions and emerging economies where enforcement timelines remain uncertain.
Market Dynamics
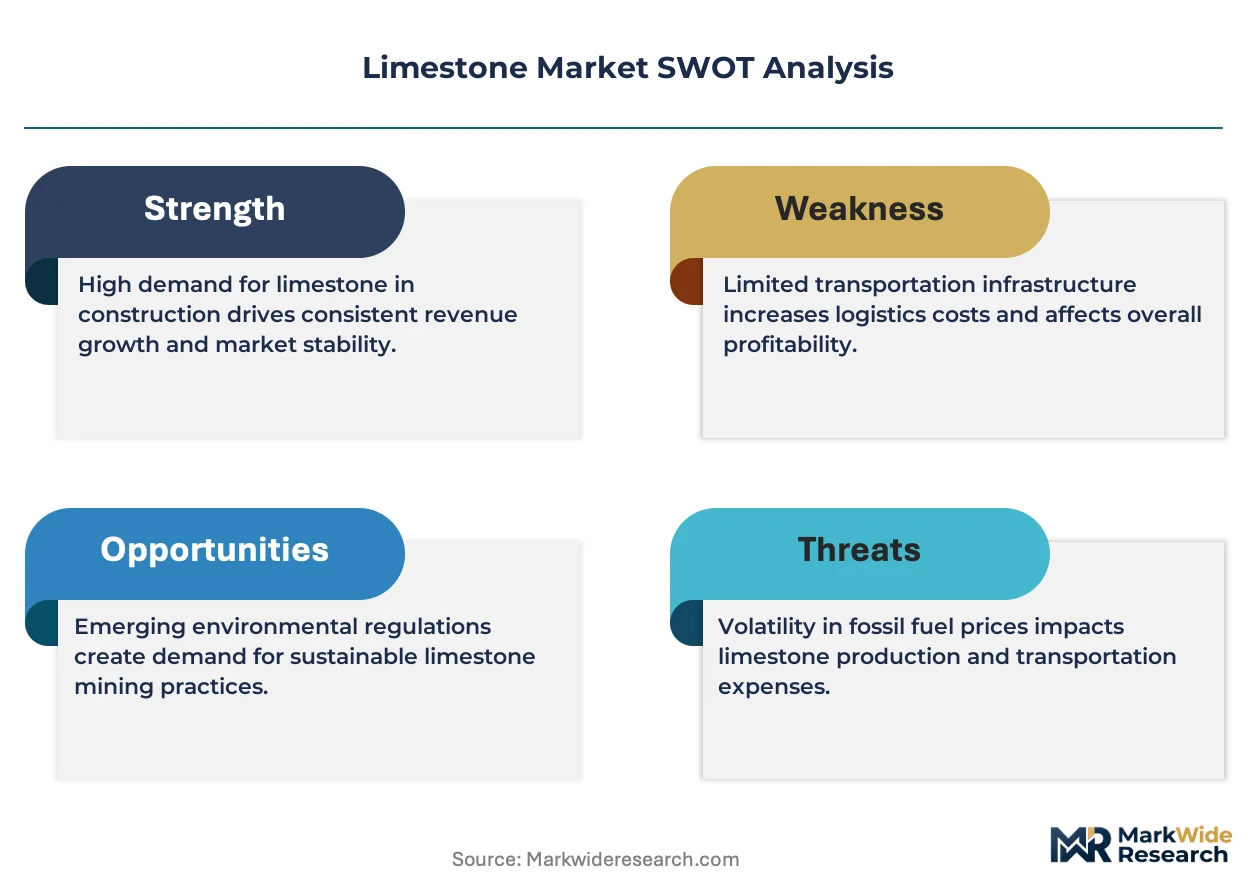
The EU Carbon Border Adjustment Mechanism is forcing European steelmakers to requalify limestone suppliers against embedded carbon metrics, compressing procurement timelines and elevating certified low-carbon feedstock premiums.
Growth Catalysts
- India's PLI-linked industrial corridors:Central government production-linked incentives for cement and steel clusters are accelerating offtake of construction-grade limestone across Gujarat, Maharashtra, and Tamil Nadu.
- REACH chemical registration thresholds:European chemical processors face mandatory re-registration of calcium carbonate derivatives, pulling volume toward organized producers with dedicated ECHA compliance infrastructure.
- Clinker substitution chemistry:Portland limestone cement formulations now permit up to 35% limestone replacement, redirecting quarry output from aggregate toward binder applications in Asia-Pacific kiln operations.
Market Restraints
- Energy input cost volatility:Natural gas and metallurgical coke price swings directly compress quicklime margins, as calcination consumes 60-70% of production energy.
- Quarry permitting concentration:Environmental clearance backlogs in India and EPA New Source Review delays in the United States limit greenfield capacity expansion to incumbent leaseholders.
- Slag substitution threat:Ground granulated blast-furnace slag from steel recycling displaces limestone filler in concrete applications where performance specifications permit.
Strategic Opportunities
- Carbon capture integration:Post-combustion calcium looping at lime kilns is automating CO₂ mineralization, creating tradable carbon credits for early adopters in the Netherlands and Canada.
- Desulfurization grade quicklime:Indian steelmakers under Ministry of Steel emission mandates are opening long-term contracts for high-reactivity lime with sulfur absorption specifications above 95% efficiency.
- Direct-to-mill procurement platforms:Digital mineral marketplaces are compressing trader margins by connecting Rajasthan quarries directly to cement plant procurement desks.
Industry Challenges
- Geological assay talent scarcity:Qualified mining geologists with carbonate deposit modeling expertise command premium compensation, constraining exploration velocity for mid-tier operators.
- Multi-jurisdiction certification timelines:Simultaneous BIS quality marking, CEA environmental clearance, and state mining lease renewals in India extend project commissioning by 18-24 months.
- Kiln refractory integration complexity:Retrofitting vertical shaft kilns for alternative fuel firing requires custom burner geometry and control system overhauls that disrupt production continuity.
Report Scope
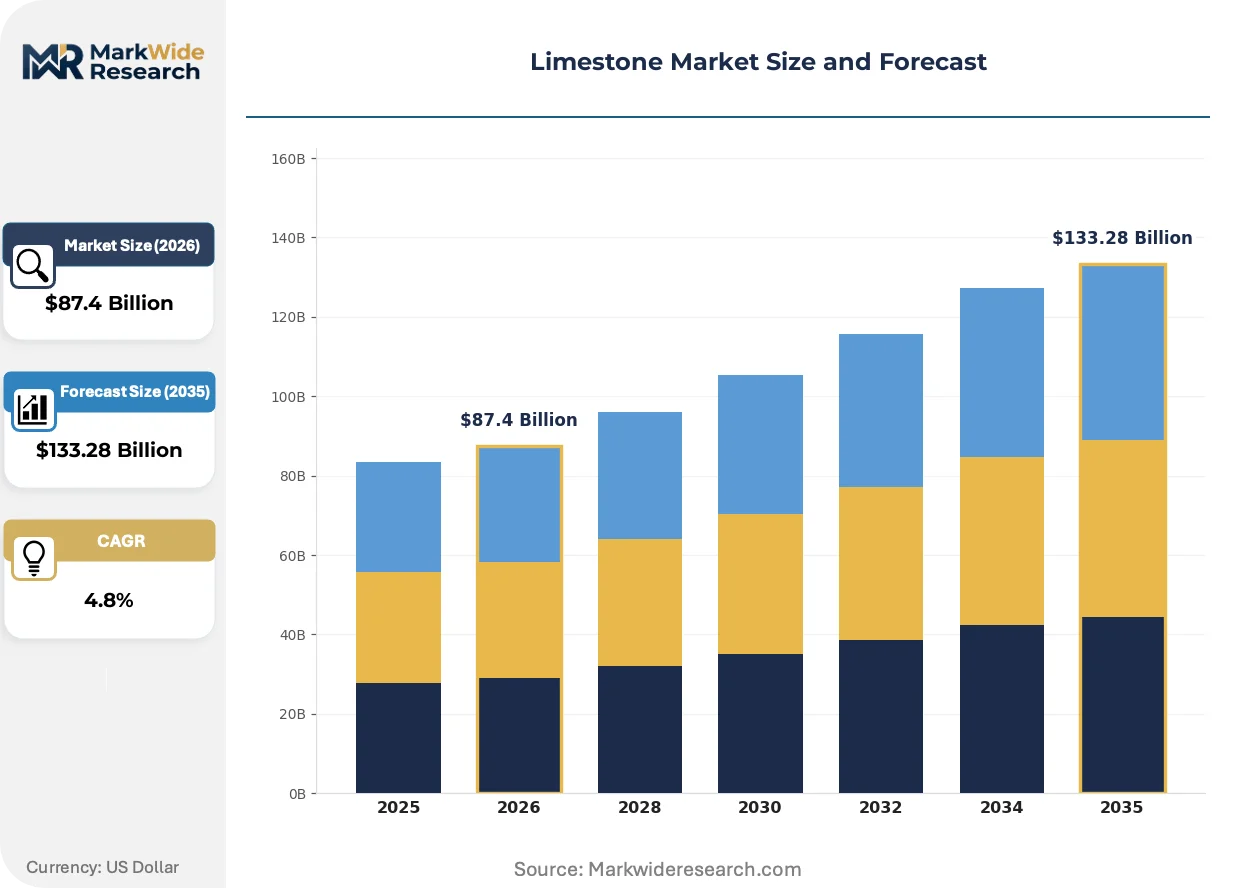
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Limestone Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Limestone, Quicklime, Slaked Lime, Limestone Powder End Use Industry: Cement, Steel, Glass, Agriculture Form: Granular, Powdered, Lump, Liquid Grade: High Purity, Chemical Grade, Industrial Grade, Others |
| Companies Covered | Lhoist Group, Carmeuse Group, Graymont Limited, Omya AG, CRH plc, Holcim Group, Imerys S.A., Cemex S.A.B. de C.V., Mineral Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Limestone Market Strategic Shifts & Innovations
Digital quarry management and emissions tracking systems are compressing the information asymmetry between limestone producers and carbon-accounting buyers, reshaping contract structures toward verified low-carbon premiums.
X-ray fluorescence (XRF) inline analyzers are automating real-time CaCO₃ grade verification at crushing stations. Cement producers in Vietnam and Indonesia are installing these units to eliminate laboratory sampling delays. The technology is automating specification compliance, reducing penalty clauses in supply agreements and compressing working capital cycles for quarries.
The EU Carbon Border Adjustment Mechanism's transitional reporting phase requires embedded emissions documentation for imported lime and limestone. European steelmakers and chemical processors are now demanding supplier-specific carbon intensity data. This regulation is forcing Asian exporters to deploy ISO 14064-compliant monitoring or lose tender eligibility in German and French procurement.
Long-term mineral offtake contracts are displacing spot market purchases among integrated building materials groups. Buyers in Saudi Arabia and the UAE are negotiating 10-15 year quarry lease-back arrangements rather than arm's-length supply. This pattern concentrates procurement power with sovereign wealth-backed construction entities and compresses trader participation in Middle East supply chains.
Limestone Market Segmentation
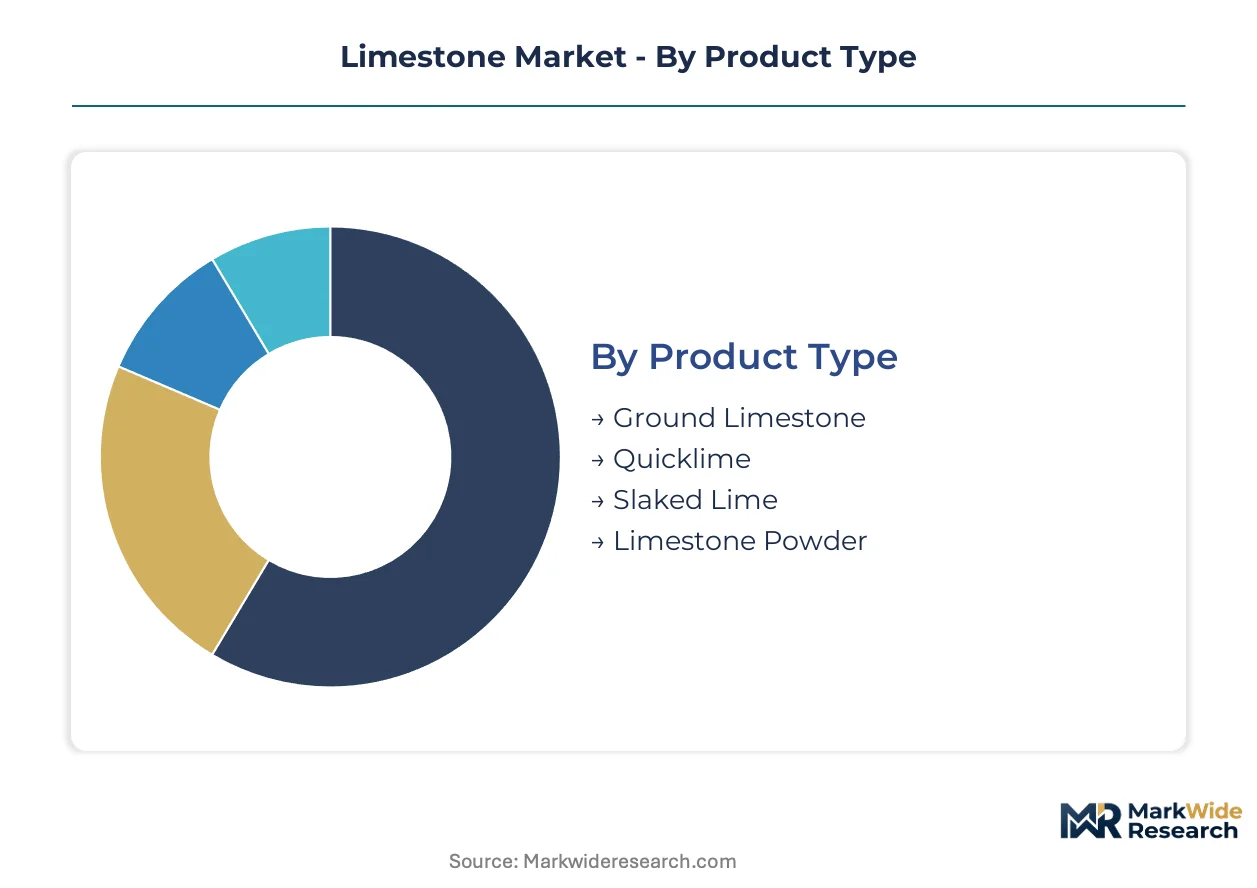
Limestone derivatives span vastly different margin profiles and technical specifications. Product purity thresholds, kiln reactivity requirements, and end-use certification standards fragment procurement into discrete contract tiers with divergent pricing mechanics.
Product Type:
Customization intensity rises with thermal processing depth, separating raw-ground material from calcined derivatives with specialized reactivity profiles.
- Quicklime:Calcium oxide produced through kiln calcination at 900-1000°C achieves 90-95% CaO content with specific surface area dictating reactivity grades. Steel desulfurization contracts in India specify sulfur absorption efficiency above 95%, pulling volume toward integrated producers with vertical shaft kiln control systems.
- Slaked Lime:Hydrated calcium hydroxide manufactured through controlled water addition to quicklime serves flue gas treatment and chemical processing where particle size distribution determines slurry performance. European REACH registration requirements favor organized producers with dedicated ECHA compliance infrastructure.
- Ground Limestone:Milled calcium carbonate with controlled fineness serves cement clinker substitution where Portland limestone cement formulations now permit up to 35% replacement.
- Limestone Powder:Ultra-fine pulverized material below 45 micron particle size targets specialty filler applications in polymers and coatings.
Most installed capacity flows through Ground Limestone. Expansion is steepest in Quicklime.
End Use Industry:
Volume concentration versus value capture splits sharply across this category, with commodity construction applications diverging from premium metallurgical and chemical processing segments.
- Cement:Clinker substitution chemistry redirects quarry output from aggregate toward binder formulations. India's PLI-linked industrial corridors across Gujarat, Maharashtra, and Tamil Nadu are accelerating offtake for construction-grade applications with BIS quality certification requirements.
- Steel:Desulfurization and fluxing applications command premium positioning where high-reactivity quicklime specifications determine contract value. The EU Carbon Border Adjustment Mechanism is forcing European steelmakers to requalify suppliers against embedded carbon metrics.
- Glass:Soda-lime silica formulations require consistent calcium carbonate feedstock with tight iron content controls for optical clarity specifications.
- Agriculture:Soil pH correction and animal feed supplements utilize lower-purity grades with regional distribution networks dominating procurement.
Cement absorbs the highest absolute tonnage. Value per ton peaks in Steel.
Form:
Physical state selection tracks downstream handling infrastructure and reactivity requirements across divergent customer operational setups.
- Powdered:Fine-ground material below 100 micron enables pneumatic conveying and rapid dissolution in chemical processing and cement milling circuits.
- Granular:Controlled particle size distribution between 2-10mm optimizes kiln feed consistency and blast furnace permeability in integrated steel operations.
- Lump:Raw quarry-run material for lime kiln charging where calcination efficiency depends on uniform thermal penetration through coarse fragments.
- Liquid:Slaked lime slurries prepared at 20-30% solids concentration for flue gas desulfurization systems requiring continuous injection capability.
Granular form dominates metallurgical offtake. Slurry systems are gaining share fastest in environmental applications.
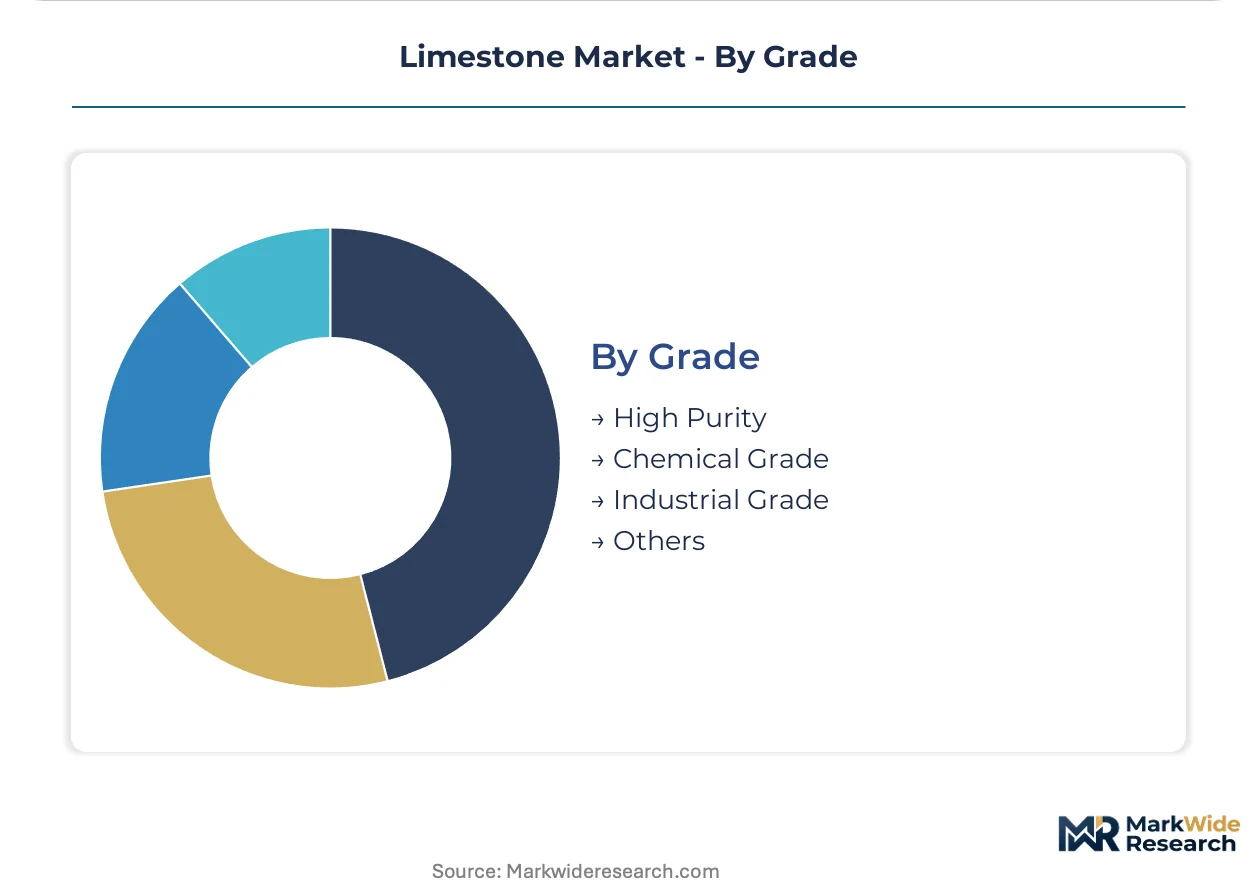
Grade:
Certification tier determines market access and pricing bandwidth, with regulatory thresholds fragmenting supply into compliant and non-compliant pools.
- High Purity:Minimum 98% CaCO₃ content with controlled magnesium and silica levels serves pharmaceutical and food-grade applications where pharmacopeia compliance commands substantial premiums.
- Chemical Grade:95-98% CaCO₃ with specified trace element limits targets precipitated calcium carbonate production and specialty chemical synthesis.
- Industrial Grade:90-95% CaCO₃ satisfies cement, steel, and construction applications where BIS marking and EPA emissions standards govern operational permits.
- Others:Lower-specification material including agricultural lime and aggregate fill where local transport economics outweigh purity premiums.
Industrial Grade carries the highest shipment volumes. Chemical Grade is climbing the fastest as PCC demand expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI-linked industrial corridors across Gujarat, Maharashtra, and Tamil Nadu are concentrating limestone procurement for cement and steel applications. Regulatory divergence between carbon-intensive jurisdictions and emerging economies is fragmenting supplier qualification requirements.
India
Cement and steel clusters in Gujarat, Maharashtra, and Tamil Nadu drive construction-grade limestone offtake. BIS quality certification and CEA environmental clearances favor organized suppliers with integrated testing infrastructure. The Delhi-Mumbai Industrial Corridor accelerates quarry output redirection from aggregate toward Portland limestone cement formulations.
United States
EPA emissions standards for lime kilns constrain operational permits for calcination facilities. New Source Review delays limit greenfield capacity expansion to incumbent leaseholders. Texas and Ohio industrial corridors maintain ground limestone supply for cement clinker substitution chemistry.
Germany
EU Carbon Border Adjustment Mechanism requalification requirements compress procurement timelines for steelmakers. REACH chemical registration thresholds pull calcium carbonate derivative volume toward organized producers with dedicated ECHA compliance infrastructure. The Ruhr industrial basin anchors quicklime demand for metallurgical applications.
China
Dual carbon goals and MIIT industrial policy reshape kiln fuel sourcing toward alternative firing systems. Yangtze River Delta cement producers expand high-purity limestone procurement for clinker reduction mandates. Shandong Peninsula quicklime facilities face GB standards compliance pressure for steel desulfurization supply.
Netherlands
Post-combustion calcium looping pilot installations at lime kilns automate CO₂ mineralization for tradable carbon credit generation. The Rotterdam industrial cluster hosts early adopters integrating carbon capture with quicklime production. EU Green Deal alignment requirements elevate certified low-carbon feedstock premiums in procurement contracts.
Limestone Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue carbon capture integration and digital marketplace disruption. The supplier base concentrates around integrated building materials groups with captive quarry networks and specialized lime producers with metallurgical reactivity expertise. Two strategic archetypes dominate: vertically integrated cement-lime conglomerates controlling upstream feedstock, and standalone quicklime specialists commanding premium positioning in steel desulfurization. Competitive moves center on long-term mineral lease-back arrangements and kiln retrofit partnerships for alternative fuel firing.
Within the European integrated tier, Lhoist Group and Carmeuse Group exemplify archetypal positioning around quarry network depth and metallurgical specialization respectively. Graymont Limited represents Pacific Rim supply concentration through British Columbia and New Zealand mineral lease dominance. Among diversified materials conglomerates, CRH plc and Holcim Group occupy positions spanning cement formulation and aggregate supply, with limestone serving as captive feedstock for clinker substitution chemistry rather than standalone revenue center.
| Leading Market Players |
|---|
| Lhoist Group |
| Carmeuse Group |
| Graymont Limited |
| Omya AG |
| CRH plc |
| Holcim Group |
| Imerys S.A. |
| Cemex S.A.B. de C.V. |
| Mineral Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned quarry operators across Rajasthan and Andhra Pradesh anchor supply discipline through generational leasehold control, translating captive mineral access into pricing power that resists spot-market volatility. Sovereign wealth-backed construction entities in Saudi Arabia and the UAE compress trader margins through direct quarry lease-back arrangements, redirecting value capture from intermediaries to integrated end-users.
Pricing Analysis
Natural gas and metallurgical coke pass-through clauses dominate quicklime contract structures, with calcination energy consuming 60-70% of production costs and amplifying margin sensitivity to fuel price swings. Three-tier pricing structure across premium desulfurization grades, standard construction material, and economy aggregate fill separates steelmakers from cement producers from road builders. Pricing pressure stems from slag substitution in concrete applications where ground granulated blast-furnace slag displaces limestone filler. Cement clinker substitution buyers exhibit highest price sensitivity; pharmaceutical-grade purchasers demonstrate lowest.
Supply Chain Analysis
Reverse-logistics flows for kiln refractory refurbishment and lime slurry tank cleaning create specialized service revenue pools for equipment maintenance contractors. Geographic supply concentrates in India, Vietnam, and the United States, with the Yangtze River Delta and Texas industrial corridors anchoring calcination capacity. Raw material dependencies center on high-purity carbonate deposits, natural gas for kiln firing, and metallurgical coke for shaft kiln operations. Single-source vulnerability runs through long-term mineral lease concentration with incumbent holders. Distribution runs through direct-to-mill procurement platforms that compress trader participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage positioning between EU Carbon Border Adjustment Mechanism compliance costs and India's PLI-subsidized production corridors, with European steelmakers facing embedded carbon documentation requirements that Indian exporters currently bypass.
For Market Incumbents: Extend quarry lease-back arrangements with sovereign wealth-backed construction entities to lock in decade-scale offtake certainty against spot-market erosion. Deepen captive testing infrastructure for BIS quality certification and CEA environmental clearance to defend against organized competitor expansion in Gujarat and Maharashtra.
For New Entrants and Emerging Players: Digital mineral marketplaces connecting Rajasthan quarries directly to cement plant procurement desks offer the most penetrable channel route. Target construction-grade ground limestone for Portland cement formulations in Tamil Nadu industrial corridors. Pursue carbon capture integration partnerships with Dutch and Canadian pilot installations to qualify for premium low-carbon procurement tiers.
For Investors and Strategic Acquirers: Integrated cement-lime conglomerates are the most active acquirer in this space, seeking captive feedstock security for clinker substitution chemistry. Five-to-ten year viability hinges on carbon capture retrofit economics and alternative fuel firing compliance. Monitor EU Carbon Border Adjustment Mechanism full implementation timing as inflection signal for Asian export competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Post-combustion calcium looping at Dutch kilns generates tradable carbon credits for early adopters. |
| Long-term Mineral Lease-back Arrangement | Saudi sovereign wealth entities compress trader margins through direct quarry control. |
| Alternative Fuel Kiln Retrofit | Custom burner geometry overhauls in Indian shaft kilns address MIIT dual carbon compliance pressure. |
| Digital Marketplace Launch | Direct-to-mill platforms eliminate laboratory sampling delays for Vietnamese cement producers. |
| Desulfurization Grade Capacity Expansion | High-reactivity quicklime production captures Indian Ministry of Steel emission mandate contracts. |
Research Approach
Bottom-up cement and steel end-use modeling reconciled against top-down quarry production tracking forms the analytical core of this study. Primary interviews with plant managers at calcination facilities, procurement leads at integrated steelmakers, distribution channel partners in construction materials, and technical R&D directors at lime specialists combined with secondary validation from customs and trade data, SEC filings, BIS certification registers, and ECHA REACH submission databases. Triangulation between demand-side consumption patterns and supply-side capacity utilization ensures cross-verified volume estimates.
Historical trendline analysis of clinker substitution rates, steel desulfurization intensity, and kiln fuel economics established baseline growth parameters across the projection horizon. Segmentation modeling spans product type, end-use industry, physical form, and certification grade tiers, with regional regulatory clusters treated as distinct demand environments. CAGRs derive from fitted trend extrapolation adjusted for policy intervention timing and technology substitution elasticity. Forecast inputs include EU Carbon Border Adjustment Mechanism phase-in schedules and Indian PLI scheme corridor development velocity.
The model assumes a particular technology adoption path; alternative pathways for carbon capture retrofits would alter the outlook if calcium looping economics shift with carbon credit pricing. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and fuel cost normalization. Practitioners should monitor EU embedded carbon documentation requirements, Indian CEA clearance backlogs, and alternative fuel kiln retrofit completion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Mineral Sand Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Snowflake Salt Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Talc Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Pyrites Market
Industrial Minerals
Boron Minerals and Chemicals Market
Industrial Minerals
Anhydrite Market