
 Barite Mining Market | 2026-2036
Barite Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Barite Mining Market Analysis
Automated ore sorting and real-time grade control is tilting extraction economics toward higher-yield deposits. Halliburton Company leverages captive barite reserves to secure vertical integration across its drilling services division. CIMBAR Performance Minerals anchors North American supply through its Georgia processing complex, while Ashapura Group competes on cost from its Indian mining belt.
Barite consists primarily of barium sulfate with a specific gravity exceeding 4.2 for API-qualified drilling grades, extracted through open-pit or underground mining followed by crushing, grinding, and flotation to remove silica and iron impurities. Its dominant commercial purpose lies in weighting drilling muds for oil and gas well control. Drilling grade commands the largest volume share as exploration depths push barite consumption per well higher. Oilfield grade carries tighter purity premiums that concentrate margin pools with processors meeting API 13A and ISO 13500 standards simultaneously.
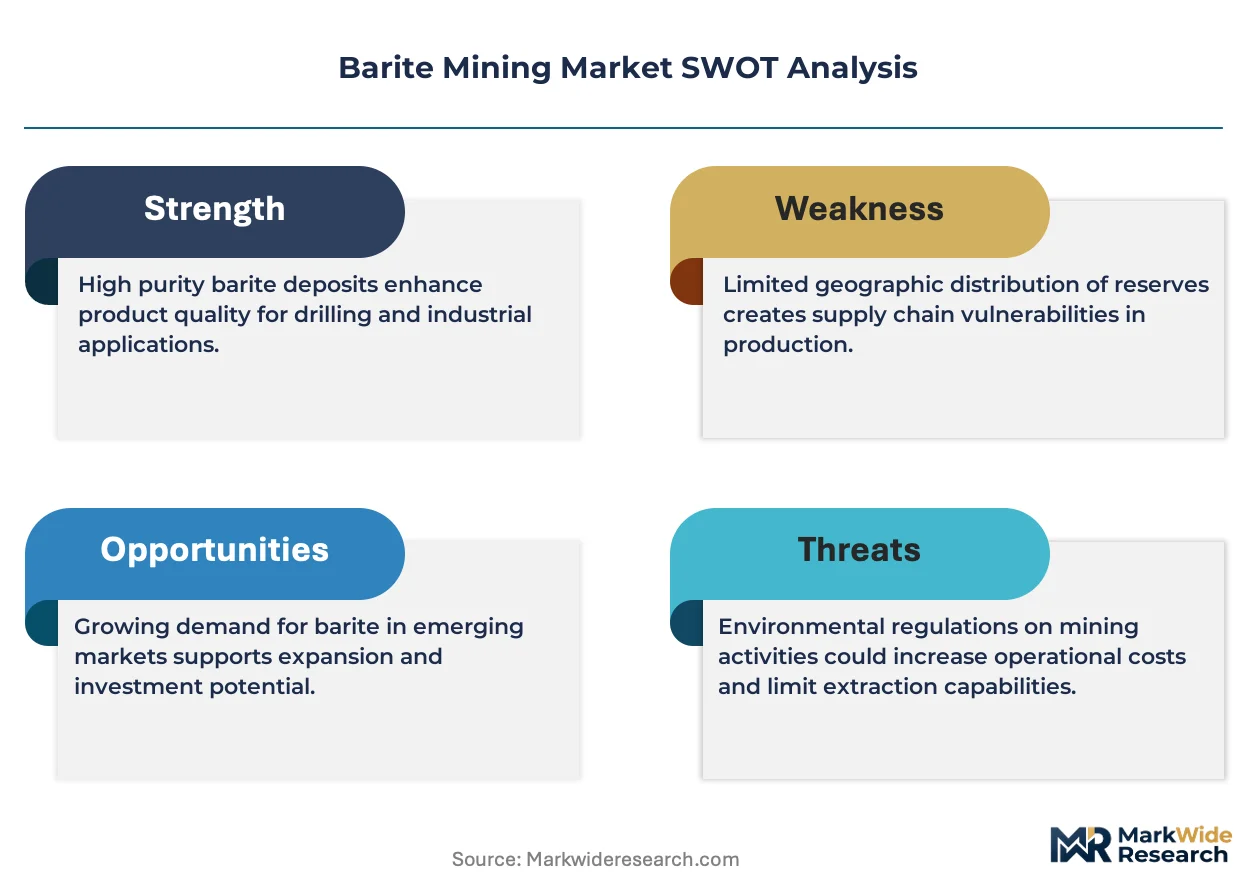
API Specification 13A and ISO 13500 govern barite purity, particle size distribution, and trace-element limits for oilfield service acceptance, while EPA mining waste rules under Subtitle D shape tailings management costs for U.S. operators. India's Ministry of Mines and the country's national mining regulator enforce royalty structures and environmental clearances that affect export competitiveness from Andhra Pradesh and Rajasthan deposits. Stakeholders must track how API revisions on heavy-metal thresholds redirect procurement toward certified flotation-upgraded material versus direct-ship ore.
Market Dynamics
API Specification 13A purity tightening is compressing merchant supply eligibility, forcing processors toward flotation upgrades and captive ore integration to maintain drilling-fluid certification.
Growth Catalysts
- Deepwater drilling expansion:Gulf of Mexico and Brazilian pre-salt developments consume higher barite volumes per well as total vertical depths exceed 25,000 feet.
- EPA Subtitle D tailings rules:Stricter waste containment standards in the United States are accelerating capital deployment toward closed-loop water recovery at processing facilities.
- Ilmenite and hematite substitution limits:API 13A density requirements above 4.2 specific gravity prevent alternative weighting agents from displacing barite in high-pressure formations.
Market Restraints
- Andhra Pradesh export concentration:Indian royalty structures and environmental clearance delays create supply volatility for Asian spot markets.
- Flotation reagent cost inflation:Xanthate collectors and frothers expose processors to petrochemical feedstock swings that erode margin on sub-4.3 SG ore.
- Underground mining depth limits:Missouri and Tennessee deposits face depletion economics as stripping ratios deteriorate below 3:1.
Strategic Opportunities
- Moroccan Atlantic port expansion:New bulk loading infrastructure at Safi and Agadir offers European drillers alternative supply routes bypassing Indian monsoon disruptions.
- Barium carbonate chemical conversion:Battery cathode and ceramic glaze applications open non-oilfield demand channels for 4.0-4.1 SG material rejected by API standards.
- Canada critical minerals designation:British Columbia and Newfoundland projects gain federal tax credits and streamlined permitting under the country's critical minerals strategy.
Industry Challenges
- API 13A-2025 revision timeline:Uncertainty over heavy-metal threshold adjustments delays procurement contract renewals between processors and oilfield service companies.
- Legacy flotation circuit retrofit complexity:Older Georgia and Nevada plants require distributed control system upgrades to achieve real-time grade control without multi-year shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barite Mining Market |
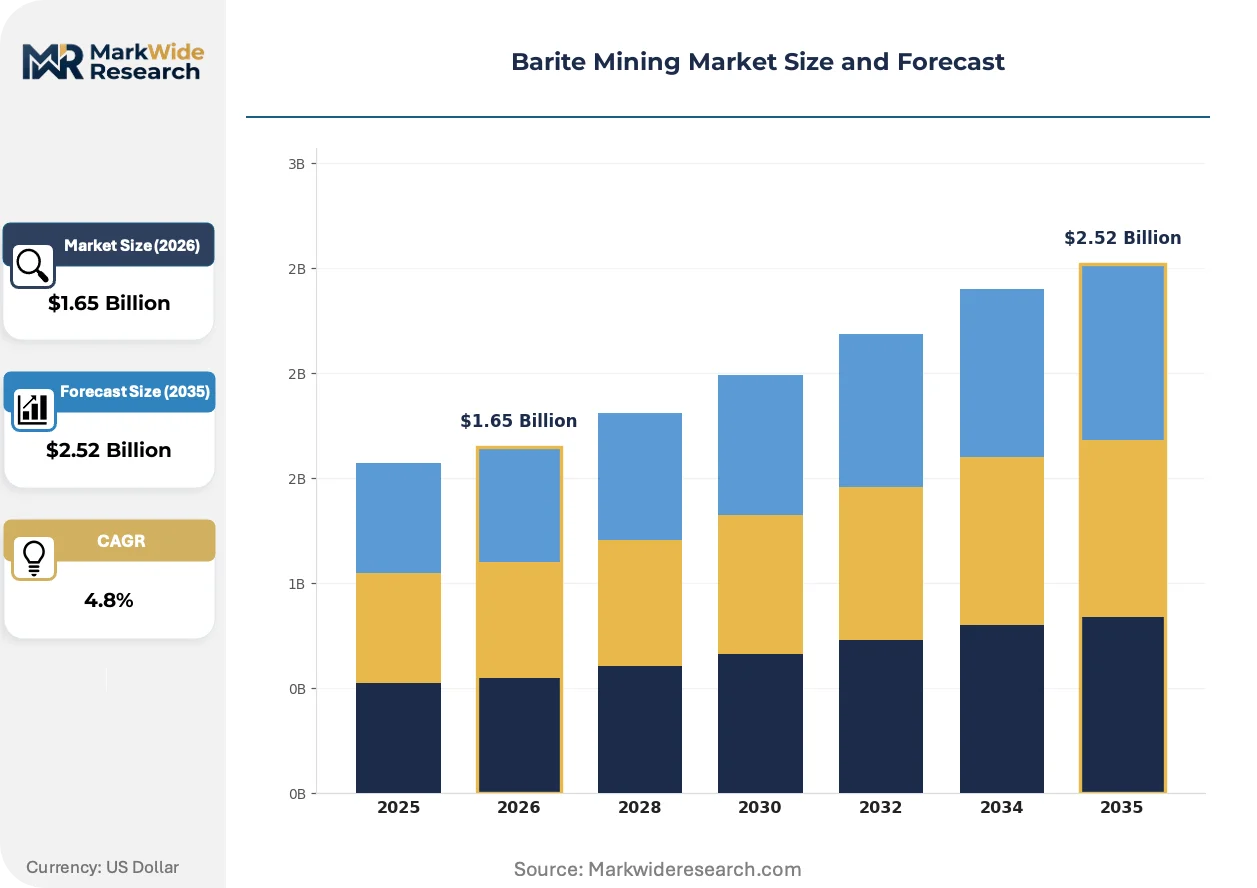
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Grade, Industrial Grade, Oilfield Grade, Chemical Grade Application: Oil & Gas, Construction, Paints & Coatings, Pharmaceuticals Processing Method: Mining, Crushing, Grinding, Flotation End User: Energy Sector, Construction Industry, Manufacturing Sector, Chemical Industry |
| Companies Covered | Anglo Pacific Minerals, Excalibar Minerals, Ashapura Group, SCR-Sibelco, New Riverside Ochre, Halliburton Company, Milwhite, Andhra Pradesh Mineral Development Corporation, CIMBAR Performance Minerals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barite Mining Market Emerging Trajectories
Digital ore characterization and closed-loop beneficiation circuits are compressing processing variability, while regulatory density on trace-element limits reshapes acceptable feedstock sources.
Sensor-based ore sorting is hybridizing X-ray transmission and laser-induced breakdown spectroscopy to reject silica bands before grinding circuits. Nevada and Kazakhstan operators deploy these units to reduce downstream flotation load by 15-20 percent. The technology is compressing capital intensity for marginal deposits previously excluded from reserve calculations.
REACH candidate list expansion for barium compounds is forcing European importers to document supply chain due diligence beyond ISO 13500 certification. German and Dutch processors now require full mass-balance traceability from mine gate to blender. The regulation is concentrating procurement among vertically integrated suppliers with captive African or Middle Eastern ore sources.
Long-term offtake contracting is displacing spot-market purchases as Permian Basin drillers seek price predictability across 24-36 month drilling programs. Master service agreements now embed volume commitments with quality penalties for SG variance above 0.05 points. This pattern is most visible among independent exploration companies lacking captive barite reserves.
Barite Mining Market Segmentation
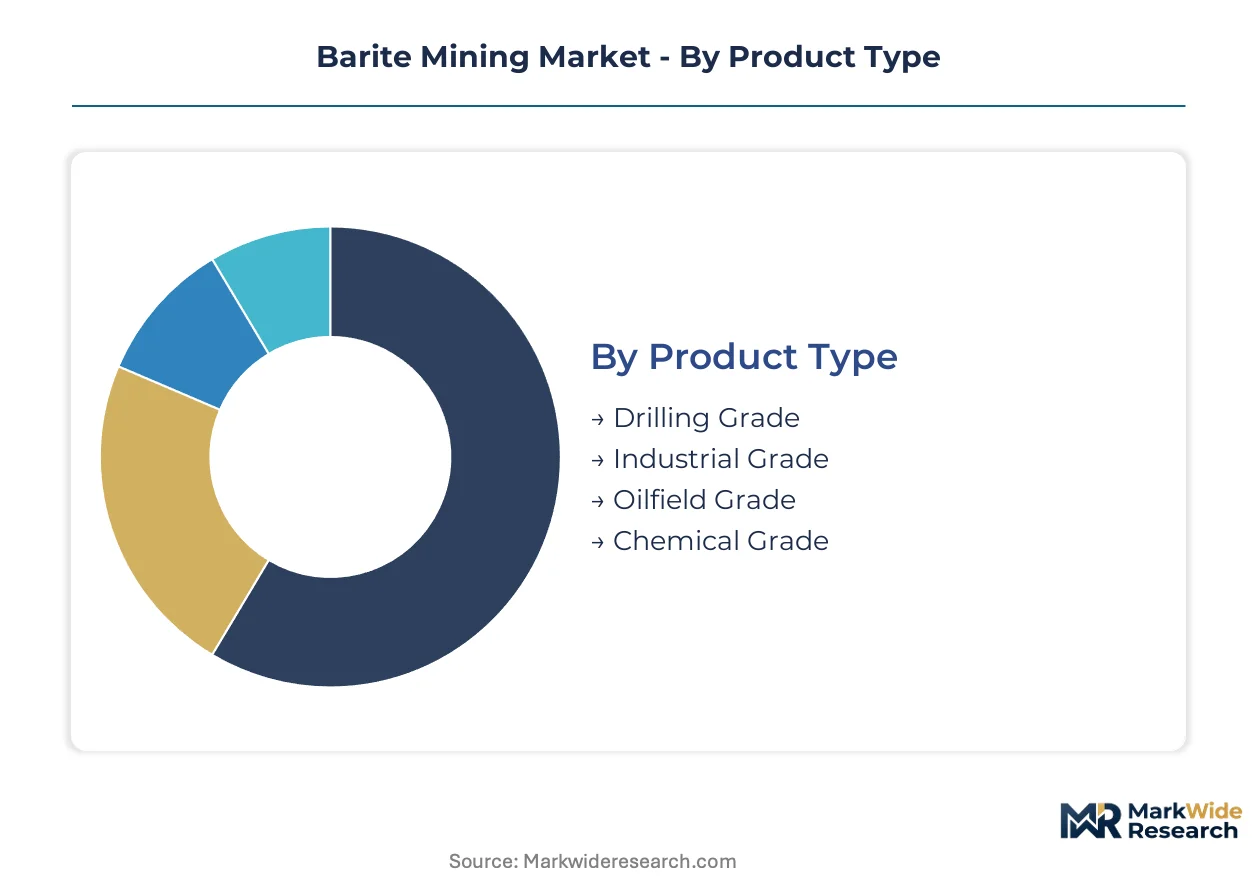
Barite mining economics diverge sharply across purity tiers and processing intensity. Cycle times from mine gate to blender vary from 72 hours for direct-ship drilling ore to 21 days for chemically upgraded material, compressing working capital requirements for some segments while extending them for others.
Product Type:
Drilling-grade barite turns inventory fastest with spot-market offtake, while chemical-grade material sits longest awaiting pharmaceutical and battery cathode qualification.
- Drilling Grade:Barium sulfate content exceeds 92 percent with specific gravity above 4.2, meeting API Specification 13A density minimums for high-pressure formations. Permian Basin independents absorb the bulk of spot volume, though EPA Subtitle D tailings compliance is pushing processing costs upward at Georgia and Nevada facilities.
- Oilfield Grade:Tighter trace-element thresholds under ISO 13500 certification command premium pricing for deepwater Gulf of Mexico deployments. Halliburton and Schlumberger procurement teams now require dual-certified material with full mass-balance documentation, extending qualification cycles to 90 days.
- Industrial Grade:Specific gravity of 4.0-4.1 serves construction aggregate and radiation shielding applications outside oilfield specifications.
- Chemical Grade:Conversion feedstock for barium carbonate production in ceramic glazes and battery cathodes, rejected by API standards but gaining traction in European specialty chemical markets.
Drilling grade dominates installed base. Chemical grade is where expansion concentrates.
Application:
Cost tier separation runs deepest here, with oilfield services paying 3-4x the per-tonne rate that construction contractors accept for lower-density material.
- Oil & Gas:Weighting agent for drilling muds in well control operations, consuming roughly four-fifths of North American production. Deepwater pre-salt developments off Brazil and Gulf of Mexico shelf extensions are pushing per-well consumption past 2,000 tonnes as total vertical depths exceed 25,000 feet.
- Construction:Aggregate filler for concrete density and radiation shielding in medical and nuclear facilities. Indian Andhra Pradesh deposits supply cost-competitive material for Middle Eastern infrastructure projects, though monsoon logistics create seasonal volatility.
- Paints & Coatings:Extender pigment and weighting agent in marine and industrial formulations, competing against precipitated calcium carbonate on cost.
- Pharmaceuticals:Barium sulfate suspensions for diagnostic imaging, requiring food-grade purity certification and trace-heavy-metal documentation under REACH candidate list scrutiny.
Oil and gas commands revenue concentration. Pharmaceuticals is climbing the fastest.
Processing Method:
Volume throughput peaks at crushing and grinding stages, while margin capture concentrates in flotation circuits that upgrade sub-4.3 SG ore to API certification.
- Mining:Open-pit extraction dominates in Missouri and Tennessee, though stripping ratios below 3:1 are forcing operators toward higher-cost underground methods at legacy deposits.
- Crushing:Primary size reduction to minus 3-inch feedstock for downstream grinding circuits, with automated ore sorting increasingly deployed to reject silica bands before energy-intensive comminution.
- Grinding:Ball and rod mills reduce material to 74-micron particle size distribution for API drilling-grade specification, with real-time grade control systems compressing variability.
- Flotation:Xanthate collectors and frothers separate barite from silica and iron impurities, achieving 4.2+ specific gravity upgrades essential for oilfield certification.
Crushing and grinding handle volume scale. Flotation is where margin pools form.
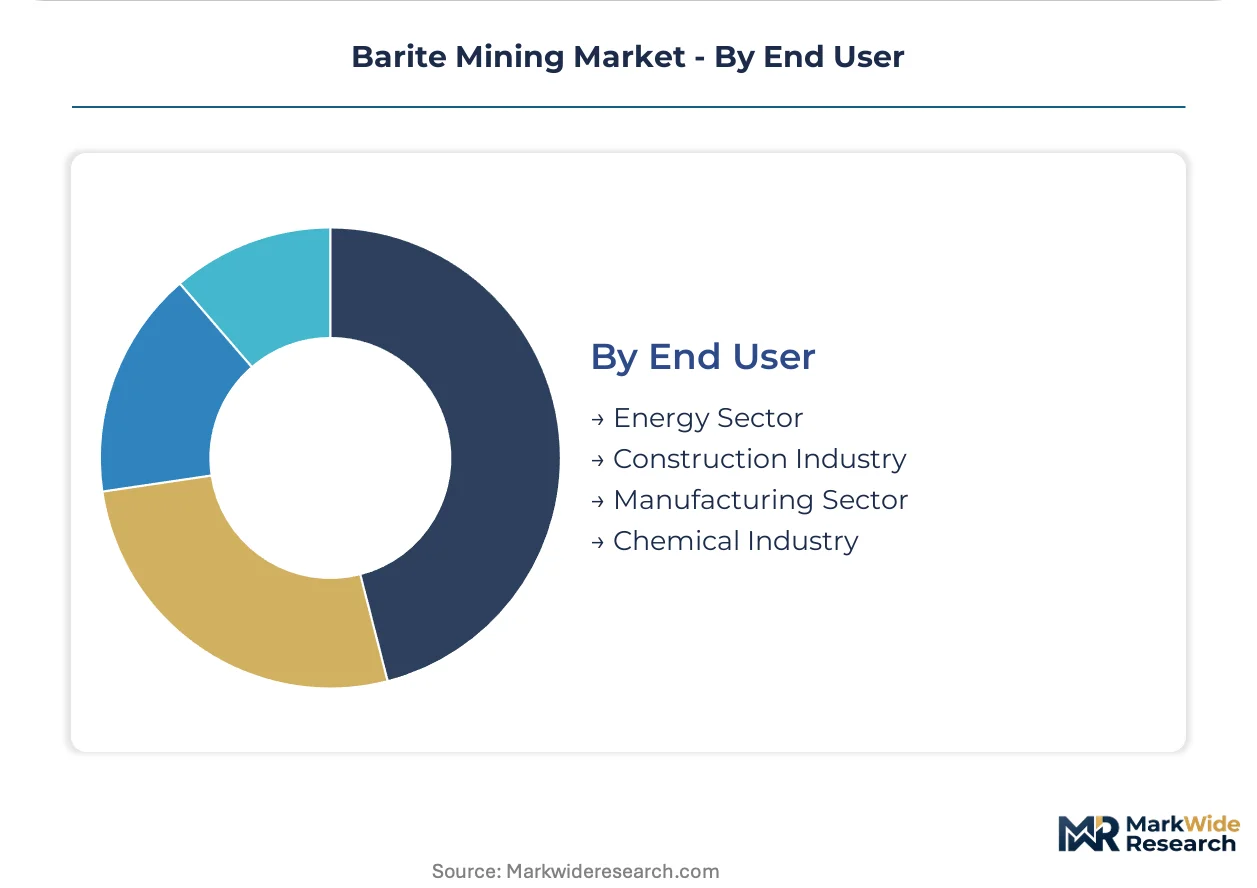
End User:
Customer type determines contract structure, with energy sector buyers locking in 24-36 month offtake agreements while manufacturing purchasers remain spot-market dependent.
- Energy Sector:Oilfield service companies and exploration independents in the Permian Basin, Bakken, and Eagle Ford shale plays. Master service agreements now embed quality penalties for specific gravity variance above 0.05 points, tightening processor compliance burdens.
- Construction Industry:Concrete producers and radiation shielding contractors sourcing industrial-grade material from Indian and Moroccan export channels.
- Manufacturing Sector:Paints, coatings, and plastics compounders accepting 4.0-4.1 SG material rejected by API standards.
- Chemical Industry:Barium carbonate and barium chloride converters serving battery cathode, ceramic glaze, and pyrotechnics applications.
Energy sector anchors procurement volume. Chemical industry is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian export corridors supply the bulk of Asian and Middle Eastern drilling operations, while Moroccan Atlantic ports emerge as alternative routes to European markets bypassing monsoon disruptions.
United States
Permian Basin shale operators consume roughly four-fifths of domestic barite production as total vertical depths push past 25,000 feet. EPA Subtitle D tailings rules under the Resource Conservation and Recovery Act accelerate capital deployment toward closed-loop water recovery at Georgia and Nevada processing facilities. The Cartersville mining district in northwest Georgia anchors North American supply through integrated crushing, grinding, and flotation complexes serving Gulf of Mexico drillers.
India
Andhra Pradesh and Rajasthan deposits feed cost-competitive material into Asian spot markets and Middle Eastern infrastructure projects. The Ministry of Mines enforces royalty structures and environmental clearances that create supply volatility during monsoon logistics disruptions. Visakhapatnam port operations concentrate export volume, though Safi and Agadir in Morocco now compete for European offtake previously routed through Indian channels.
Morocco
New bulk loading infrastructure at Safi and Agadir offers European drillers supply route diversification away from Indian monsoon seasonality. The country's national mining regulator oversees environmental clearances for Atlantic coast extraction projects targeting API Specification 13A certification. Khouribga and Youssoufia mining clusters develop integrated processing capacity to capture margin pools previously retained by Indian exporters.
China
Guizhou and Hunan provinces host underground mining operations supplying domestic oilfield services and chemical conversion feedstock. The Ministry of Ecology and Environment enforces tailings management standards that reshape processing economics at legacy open-pit deposits. Yangtze River Delta chemical processors convert sub-4.2 SG material rejected by API standards into barium carbonate for battery cathode applications.
Canada
British Columbia and Newfoundland projects gain federal tax credits and streamlined permitting under the country's critical minerals strategy. Natural Resources Canada designation as a critical mineral accelerates exploration drilling at high-grade deposits previously uneconomic against Moroccan and Indian supply. Vancouver-based processors evaluate flotation circuit investments to serve Pacific Northwest oilfield demand without transcontinental rail logistics.
Barite Mining Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates margin capture with API-certified processors while fragmenting raw ore supply. The vendor base separates into three strategic archetypes: vertically integrated oilfield service companies with captive reserves, independent merchant processors with flotation upgrading capability, and state-affiliated mining enterprises controlling export corridors. Dominant competitive moves include backward integration into ore sources and strategic port infrastructure partnerships to secure Atlantic and Indian Ocean loading capacity.
Among North American processors, CIMBAR Performance Minerals and Excalibar Minerals exemplify the merchant-processor archetype with established API certification and regional distribution networks. Halliburton Company occupies a distinct position as an oilfield service integrator with captive barite reserves securing supply chain control across its drilling fluids division. Ashapura Group anchors the state-adjacent export tier, leveraging Indian deposit access and coastal logistics to compete on delivered cost into Asian and Middle Eastern markets.
| Leading Market Players |
|---|
| Anglo Pacific Minerals |
| Excalibar Minerals |
| Ashapura Group |
| SCR-Sibelco |
| New Riverside Ochre |
| Halliburton Company |
| Milwhite |
| Andhra Pradesh Mineral Development Corporation |
| CIMBAR Performance Minerals |
| Others |
Supply Flow & Price Mechanics
Indian export corridor concentration at Visakhapatnam and Andhra Pradesh mining clusters funnels margin capture toward API-certified flotation processors in Georgia and Nevada who command premium spreads on drilling-grade material. This geographic asymmetry between raw ore supply and value-added processing creates pricing power dispersion that rewards backward integration into captive reserves.
Pricing Analysis
Prior-generation direct-ship ore pricing faces compression against current-generation flotation-upgraded API 13A material, while next-generation sensor-sorted feedstock promises further cost reduction. Three-tier pricing structure across premium oilfield grade, standard drilling grade, and economy industrial grade segments the market by certification intensity and trace-element documentation. Cost compression in direct-ship tiers intensifies because Indian royalty structures and monsoon logistics erode delivered cost competitiveness. Permian Basin independents exhibit highest price sensitivity due to spot-market procurement exposure, while deepwater Gulf of Mexico drillers demonstrate lowest sensitivity given dual-certification requirements and 90-day qualification cycles.
Supply Chain Analysis
Extended payment terms from oilfield service companies and supply-chain finance facilities at Atlantic port terminals reshape working capital requirements across merchant processor tiers. Raw material supply draws from India, Morocco, and China as dominant extraction geographies, with xanthate flotation reagents and diesel fuel as critical processing inputs. Single-source vulnerability concentrates at Visakhapatnam during monsoon season disruptions, forcing European buyers toward Safi and Agadir alternatives. Distribution runs through master service agreements with 24-36 month volume commitments rather than spot-market spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barite mining operates within oilfield services cyclicality, with drilling activity recovery in Permian Basin and Gulf of Mexico shelf extensions driving demand inflection. Capital deployment timing should align with rig count momentum and API 13A-2025 revision clarity.
For Market Incumbents: Insulate margin pools by accelerating captive reserve integration at Cartersville and Nevada processing complexes before API heavy-metal threshold revisions redirect procurement. Defensive consolidation through flotation circuit retrofit partnerships with sensor-based ore sorting technology suppliers counters ilmenite substitution threats. Certification investment in simultaneous API 13A and ISO 13500 dual qualification extends qualification cycle capture and locks in deepwater premium tier access.
For New Entrants and Emerging Players: Canadian critical minerals designation opportunities in British Columbia and Newfoundland offer underpenetrated jurisdictions with federal tax credit support and streamlined permitting pathways. Battery cathode feedstock conversion from sub-4.2 SG material rejected by API standards represents the most penetrable non-oilfield application, with European specialty chemical markets showing fastest qualification traction. Go-to-market positioning should emphasize REACH-compliant mass-balance traceability to capture German and Dutch processor procurement concentration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed merchant processors in Georgia and Nevada holding API certification but lacking captive ore integration for margin defense. Long-term viability across the next decade hinges on flotation upgrading capability and Atlantic or Indian Ocean port infrastructure control. Watch API 13A-2025 revision timeline clarity as the critical inflection signal for contract renewal velocity and procurement pattern stabilization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Reserves | Halliburton's vertical supply chain control secures drilling fluids division margin pools against merchant processor competition. |
| Sensor-Based Ore Sorting Deployment | Nevada and Kazakhstan operators reduce downstream flotation load by rejecting silica bands before energy-intensive grinding circuits. |
| Atlantic Port Infrastructure Partnership | Safi and Agadir bulk loading capacity offers European drillers supply route diversification away from Indian monsoon disruptions. |
| Dual Certification Investment | Simultaneous API 13A and ISO 13500 qualification extends Gulf of Mexico deepwater premium pricing capture. |
| Battery Cathode Feedstock Conversion | Yangtze River Delta chemical processors transform sub-4.2 SG material into barium carbonate for ceramic glaze applications. |
Methodological Framework
Initial hypotheses were tested against primary input from drilling fluids procurement managers, mine operations engineers, oilfield service supply chain directors, and flotation circuit technology vendors and refined through secondary validation. Primary fieldwork combined structured interviews with downstream blender operators and upstream mining executives across Georgia, Nevada, Andhra Pradesh, and Moroccan extraction zones. Secondary sources encompassed API specification revision documentation, EPA Subtitle D regulatory filings, Indian Ministry of Mines royalty schedules, and customs trade flow data. Bottom-up reserve calculations and top-down drilling activity models were triangulated to cross-validate volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across drilling grade versus chemical grade purity tiers, oil and gas versus battery cathode end-use applications, and open-pit versus underground extraction methods. CAGRs were derived from rig count elasticity modeling and per-well barite intensity curves tied to total vertical depth trajectories. Forecast inputs incorporated EPA tailings compliance cost trajectories and REACH candidate list expansion timelines for barium compound traceability.
Practitioners should monitor API 13A-2025 revision publication timing, Indian monsoon logistics disruption severity, and deepwater pre-salt drilling permit velocity for early signals of forecast deviation. Macroeconomic drilling activity contraction, regulatory heavy-metal threshold adjustment, or sensor-sorting technology cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Kyanite Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Solar Salt Market
Industrial Minerals
Inorganic Salts Market
Industrial Minerals
Mineral Sand Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Fluorspar Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Unexpanded Perlite Market