
 DHCP and IP Address Management Market | 2026-2036
DHCP and IP Address Management Market Size, Share, and Industry Trends Forecast 2026-2036
DHCP and IP Address Management Market Outlook
Telecom service provider demand is decoupling from traditional enterprise IT refresh cycles as 5G core networks and edge computing nodes require real-time IP orchestration at massive scale. Infoblox leverages its DNS-DHCP-IPAM triple-stack architecture to anchor carrier-grade deployments across North American and European networks. EfficientIP competes through integrated DNS security layers that extend address management into threat response workflows. BlueCat Networks specializes in hybrid cloud connectivity, positioning its platform for enterprises navigating distributed Kubernetes clusters.
DHCP and IP Address Management encompasses the automated allocation, tracking, and lifecycle governance of IPv4 and IPv6 addresses across physical, virtual, and cloud-native infrastructure, typically operating through lease-based protocols with configurable TTL parameters and failover redundancy to ensure continuous network availability. Cloud-Based Solutions dominate new procurement as organizations retire on-premises appliance fleets, while Network Automation represents the fastest-expanding technology segment as intent-based networking replaces manual provisioning scripts. IPv6 Management retains niche urgency among telecommunications infrastructure operators facing exhaustion of legacy address pools, though margin concentration sits with integrated DNS Management bundles that consolidate security policy enforcement.
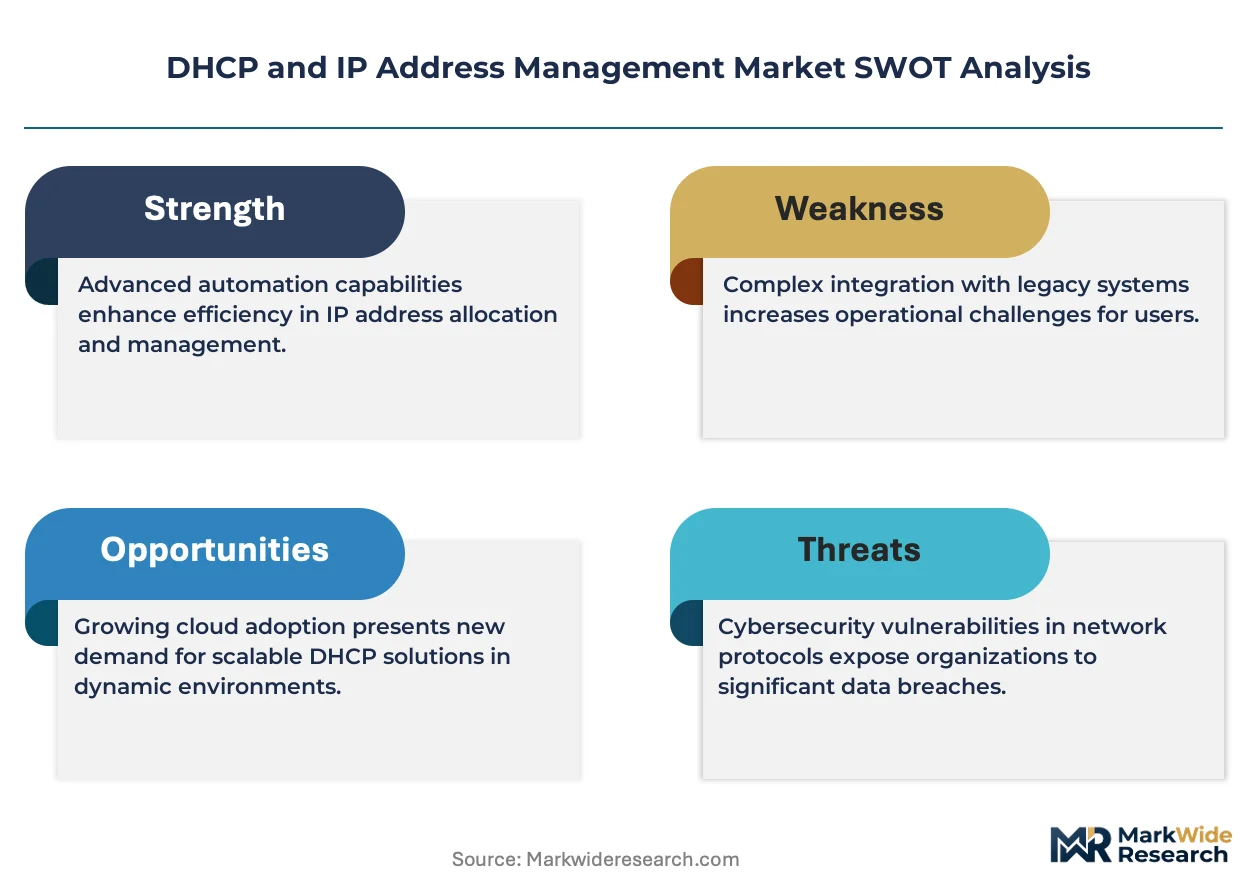
FCC network reliability mandates and NIST SP 800-53 audit controls in the United States compel federal contractors and critical infrastructure operators to maintain immutable IP assignment logs with automated compliance reporting. ISO 27001 and IEC 62443 frameworks further shape product certification requirements for vendors serving European industrial and energy sector buyers. Stakeholders must evaluate whether their address management architectures can absorb zero-touch provisioning demands from emerging private 5G networks without fragmenting policy governance across multi-cloud estates.
Market Dynamics
Zero-touch network provisioning is compressing deployment timelines from weeks to minutes, forcing vendors to embed intent-based automation directly into DHCP orchestration layers rather than bolt it on as a separate module.
Growth Catalysts
- 5G Core Virtualization:Telecom operators in Germany and South Korea are deploying cloud-native IPAM to manage millions of subscriber sessions across distributed user plane functions.
- NIST SP 800-53 Controls:US federal contractors must maintain immutable audit trails for dynamic address assignments, creating mandatory upgrade cycles for legacy systems.
- Industrial IoT Density:Manufacturing facilities in Bavaria and Baden-Württemberg are exhausting IPv4 private ranges, accelerating IPv6 dual-stack mandates.
Market Restraints
- IPv4 Address Exhaustion:Regional internet registries have depleted available IPv4 blocks, forcing secondary market purchases at escalating costs for enterprises delaying IPv6 migration.
- Skills Concentration:Certified network automation engineers cluster in metropolitan tech hubs, leaving mid-market enterprises in secondary cities dependent on outsourced professional services.
- Protocol Interoperability:Legacy DHCPv4 implementations lack native support for emerging SRv6 segment routing, requiring costly middleware development for carrier networks.
Strategic Opportunities
- Private 5G Campus Networks:Industrial enterprises in the Ruhr region are deploying localized DHCP-IPAM stacks to manage thousands of mobile IoT sensors without carrier dependency.
- Edge Kubernetes Orchestration:Cloud-native DHCP controllers are unifying address management across distributed container clusters, enabling consistent policy enforcement from core to far-edge nodes.
- EU Cybersecurity Certification:The EUCC framework creates preferred vendor status for IPAM solutions with built-in cryptographic lease signing, opening public sector procurement channels.
Industry Challenges
- Intent-Based Networking Talent:Organizations struggle to hire engineers fluent in both YANG data modeling and legacy BIND/DHCP daemon administration.
- Multi-Cloud Policy Fragmentation:Enterprises operating across AWS, Azure, and private OpenStack instances face divergent IPAM APIs, complicating unified governance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DHCP and IP Address Management Market |
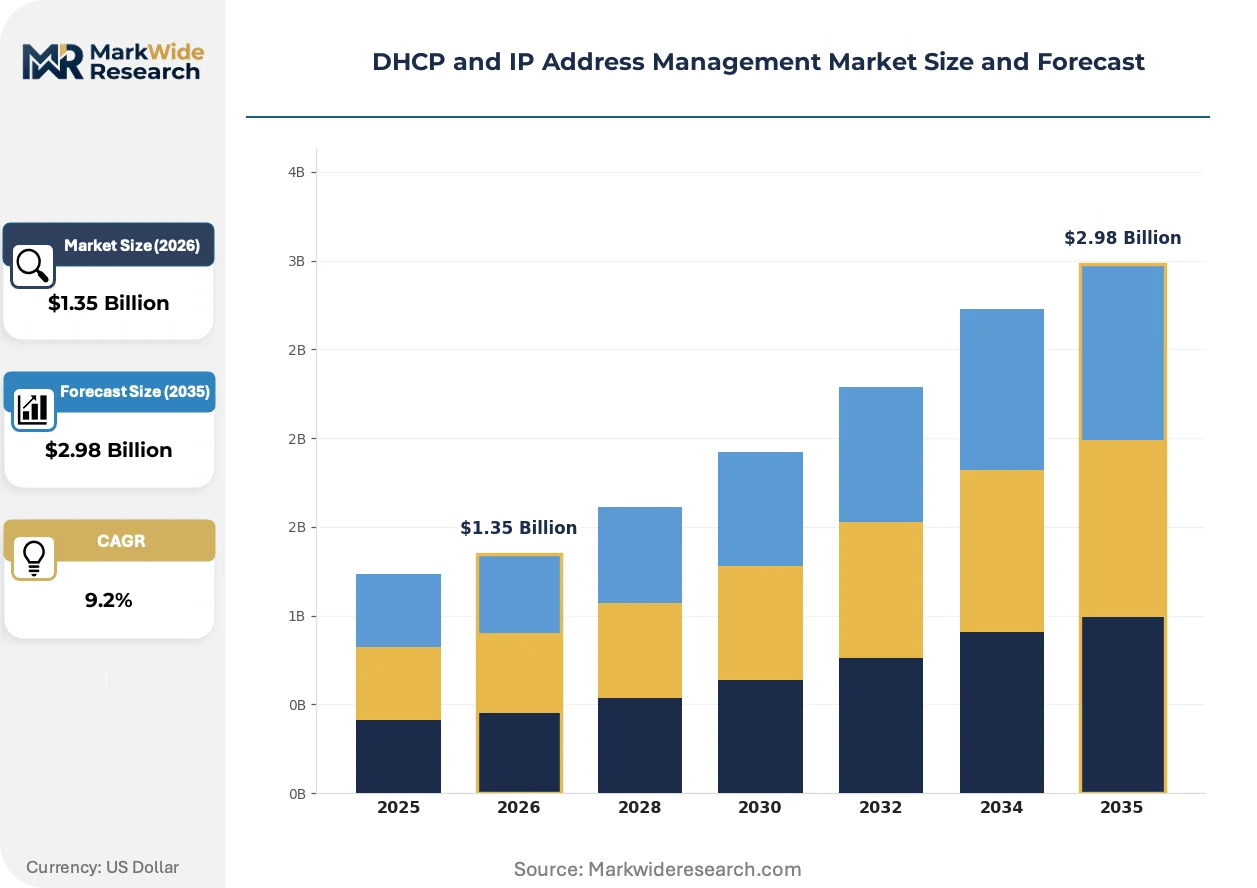
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Managed Services Technology: IPv4 Management, IPv6 Management, DNS Management, Network Automation End User: Enterprises, Service Providers, Government Agencies, Educational Institutions Deployment Model: Public Cloud, Private Cloud, Virtual Appliance, Software as a Service |
| Companies Covered | Infoblox, BlueCat Networks, EfficientIP, Cisco Systems, Cygna Labs, Men & Mice, FusionLayer, SolarWinds, TCPWave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DHCP and IP Address Management Market Strategic Shifts
Artificial intelligence is embedding predictive capacity into address lifecycle management, shifting operational models from reactive troubleshooting to autonomous remediation of lease conflicts and subnet exhaustion.
API-first IPAM architectures are unifying control planes across physical appliances, virtual machines, and serverless compute instances. Large financial institutions in Frankfurt and Singapore are adopting these platforms to collapse provisioning workflows that previously required separate tools for each infrastructure layer. The structural consequence is compressing vendor consolidation timelines as buyers reject point solutions lacking programmable interfaces.
CSRD sustainability reporting mandates in the European Union are forcing data center operators to document energy consumption per IP address assignment. This creates procurement pressure for IPAM platforms with built-in carbon attribution tracking. Telecommunications infrastructure providers face the steepest compliance burden, retrofitting existing deployments to capture granular power metrics.
Subscription-based consumption models are displacing perpetual licensing for on-premises DHCP-IPAM software. Mid-market enterprises in manufacturing and healthcare verticals favor operational expenditure structures that bundle support, training, and automatic feature updates. Germany exhibits the fastest transition pace, driven by conservative IT budgeting practices that defer large capital commitments.
DHCP and IP Address Management Market Segmentation
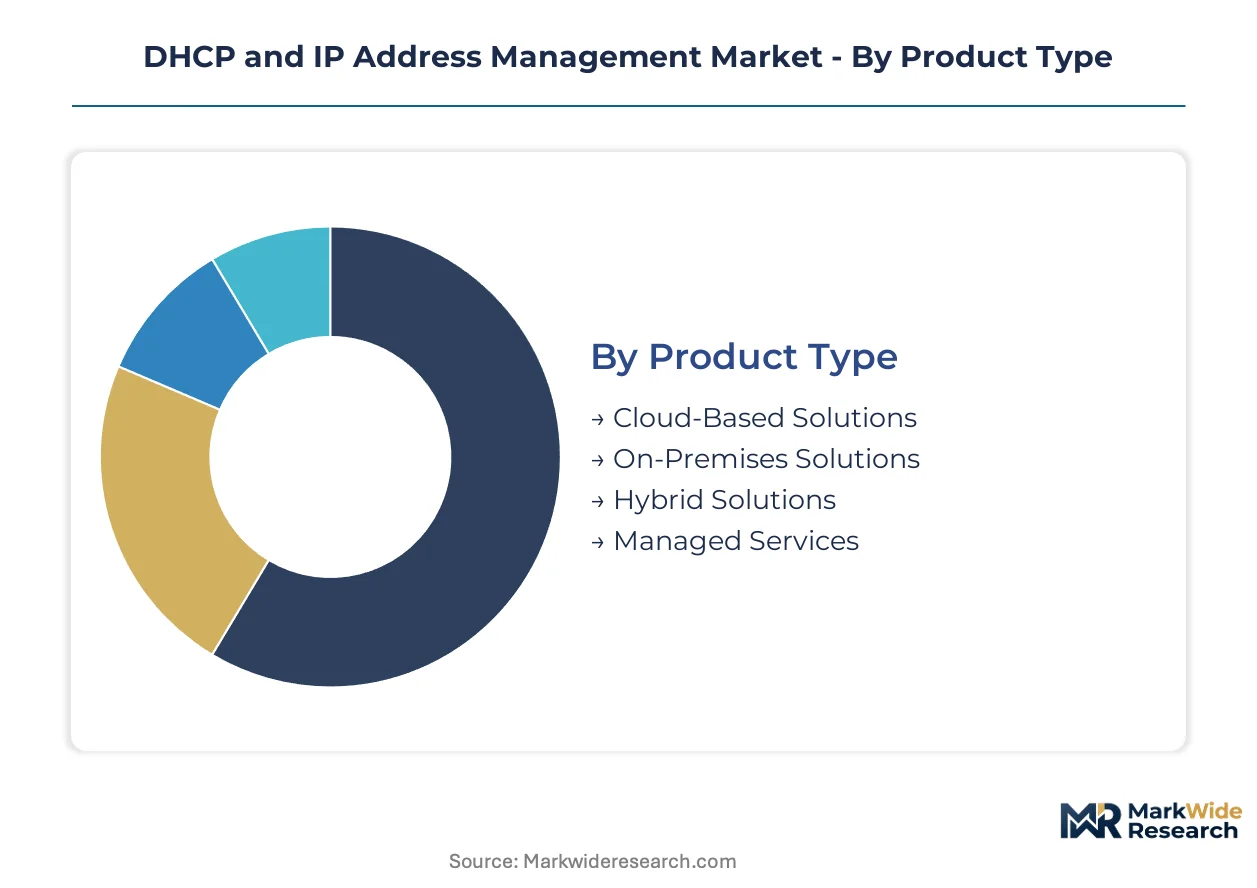
Segmentation in DHCP and IP Address Management reveals divergent procurement patterns between legacy-bound enterprises and cloud-native operators. Buyers prioritize either operational expenditure flexibility or immutable compliance controls depending on regulatory exposure and infrastructure maturity.
Product Type:
Volume procurement concentrates in subscription-based delivery models, while premium pricing attaches to solutions bundling professional services and dedicated support tiers.
- Cloud-Based Solutions:Multi-tenant SaaS architectures enable elastic scaling of DHCP lease tables across distributed regions without hardware refresh cycles. Financial services firms in Singapore and manufacturing conglomerates in Baden-Württemberg favor these platforms for rapid provisioning of edge compute nodes.
- On-Premises Solutions:Dedicated appliance deployments retain dominance where NIST SP 800-53 audit trails require air-gapped infrastructure with immutable local logging. US federal contractors and German energy sector operators mandate these configurations for critical network segments.
- Hybrid Solutions:Unified control planes spanning private data centers and public cloud VPCs address policy fragmentation concerns.
- Managed Services:Outsourced DHCP operations appeal to mid-market enterprises lacking certified network automation engineers.
Today's leader: Cloud-Based Solutions. Tomorrow's challenger: Hybrid Solutions.
Technology:
Functional specialization determines margin structure, with integrated security layers commanding premium positioning over standalone address allocation tools.
- Network Automation:Intent-based provisioning engines embed YANG-modeled policy directly into DHCP orchestration, eliminating manual subnet configuration. Telecommunications operators in South Korea deploy these systems for zero-touch provisioning of 5G core user plane functions.
- IPv4 Management:Legacy lease tracking and NAT traversal optimization remain essential for enterprises deferring IPv6 migration. Secondary market IPv4 block purchases in the United States continue despite regional exhaustion, sustaining demand for sophisticated address reclamation tools.
- IPv6 Management:Dual-stack orchestration and SRv6 segment routing support gain traction among carriers.
- DNS Management:Integrated security policy enforcement and threat response workflows consolidate vendor relationships.
Network Automation climbs the fastest. IPv4 Management retains installed base dominance.
End User:
Procurement authority separates between organizations owning physical infrastructure and those consuming network services as operational inputs.
- Service Providers:Carrier-grade IPAM platforms manage millions of concurrent subscriber sessions across distributed edge locations. Deutsche Telekom and SK Telecom deployments demonstrate scalability requirements driving vendor consolidation toward API-first architectures.
- Government Agencies:Immutable audit logging and FIPS 140-2 cryptographic modules satisfy federal procurement mandates. US civilian agencies and German state-level IT services prioritize compliance certification over feature velocity.
- Enterprises:Hybrid cloud connectivity and Kubernetes-native addressing dominate procurement criteria.
- Educational Institutions:Constrained budgets favor open-source DHCP extensions with commercial support overlays.
Service Providers anchor current revenue. Government Agencies expand most quickly through mandatory upgrade cycles.
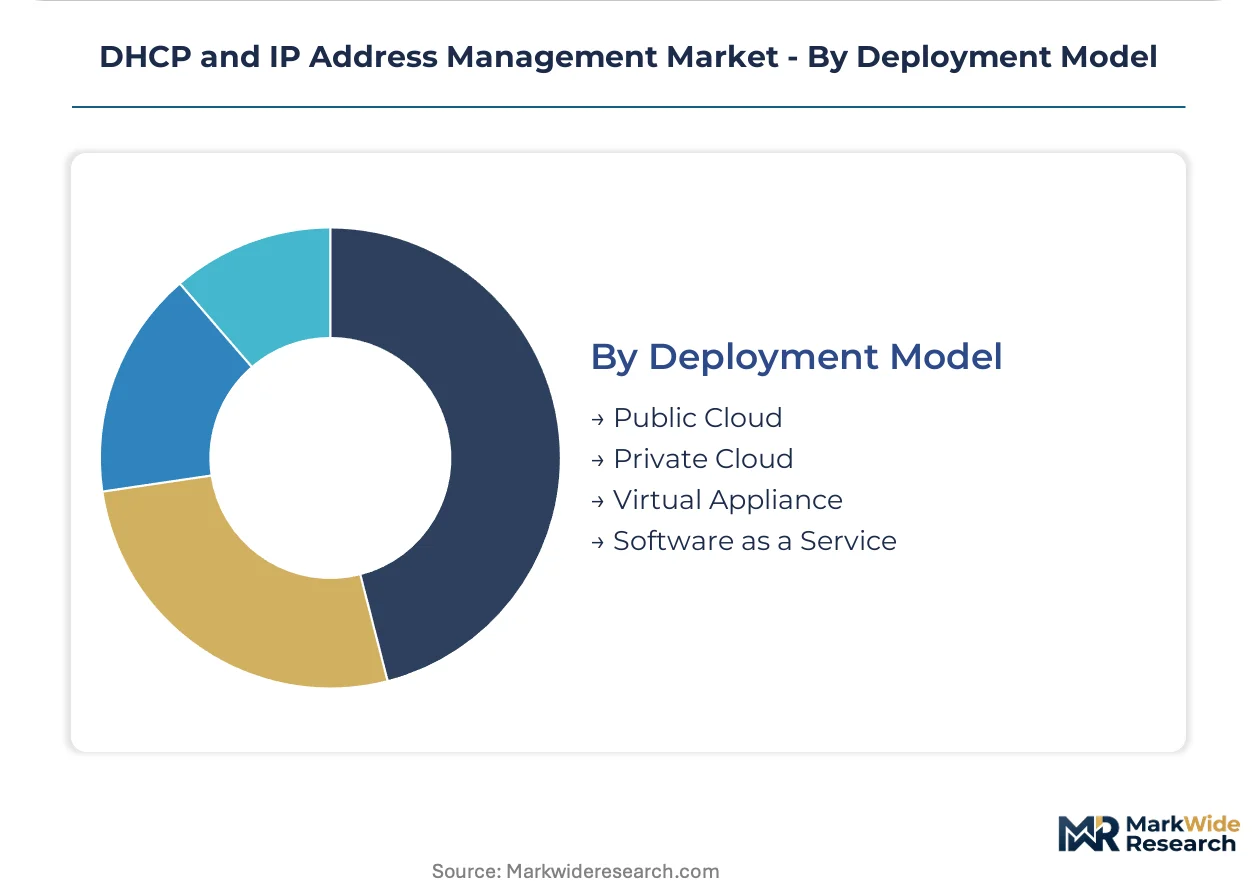
Deployment Model:
Infrastructure abstraction level determines operational control trade-offs between vendor-managed availability and self-directed customization.
- Software as a Service:Fully managed DHCP controllers abstract underlying infrastructure complexity through RESTful APIs. Healthcare systems in Texas and retail chains in Bavaria adopt these models to defer capital expenditure and accelerate provisioning workflows.
- Virtual Appliance:Containerized or VM-based deployments preserve hardware independence while maintaining tenant isolation. Private 5G campus network operators in the Ruhr region favor this flexibility for localized edge deployments.
- Public Cloud:Native integration with AWS VPC DHCP options sets and Azure VNet address management streamlines multi-cloud operations.
- Private Cloud:OpenStack Neutron integration and dedicated tenant environments address sovereignty requirements.
Software as a Service leads new procurement. Virtual Appliance gains share fastest through edge computing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting procurement toward jurisdictions where compliance costs remain manageable relative to infrastructure scale. Vendors face divergent certification burdens across national frameworks, creating positioning advantages for those with pre-validated architectures in high-barrier markets.
United States
NIST SP 800-53 audit mandates and FCC network reliability requirements are forcing federal contractors and critical infrastructure operators into mandatory upgrade cycles. FERC reliability standards compound compliance complexity for energy sector deployments. Financial institutions in Manhattan and defense contractors in Northern Virginia anchor demand for immutable logging and FIPS 140-2 cryptographic modules.
Germany
Industrial IoT density in manufacturing corridors is exhausting IPv4 private ranges and accelerating IPv6 dual-stack mandates. IEC 62443 certification requirements shape vendor selection for energy and automotive sector buyers. Production facilities in Bavaria and Baden-Württemberg strain legacy address infrastructure, while Ruhr region enterprises deploy private 5G campus networks with localized DHCP-IPAM stacks.
South Korea
Telecommunications operators are deploying cloud-native IPAM to manage millions of subscriber sessions across distributed 5G core user plane functions. National broadband initiatives and smart city programs create sustained procurement pipelines. Seoul-based carriers and Busan-Ulsan manufacturing clusters drive API-first architecture requirements for zero-touch provisioning at scale.
Singapore
Financial services firms and maritime logistics operators favor multi-tenant SaaS architectures for rapid edge compute provisioning. The Monetary Authority of Singapore's operational resilience guidelines impose stringent availability requirements. Banking headquarters in the central business district and port automation projects in Tuas anchor regional demand for elastic DHCP lease scaling.
Japan
METI industrial digitalization programs are accelerating network automation adoption among precision manufacturers. JIS standards compatibility remains a procurement gate for domestic enterprise buyers. Automotive suppliers in Aichi Prefecture and electronics fabricators in Kansai are consolidating address management across hybrid cloud estates.
DHCP and IP Address Management Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors race to embed automation layers into carrier-grade deployments. The market exhibits tiered concentration, with integrated DNS-DHCP-IPAM triple-stack providers commanding premium positioning against point-solution specialists. Three archetypes have emerged: legacy networking incumbents with cross-sell advantages, pure-play IPAM vendors with API-first architectures, and managed service providers wrapping open-source cores with compliance overlays. Portfolio diversification and technology licensing agreements represent the dominant competitive vectors, with geographic expansion into private 5G campus networks serving as secondary thrust.
Within the pure-play tier, Infoblox and BlueCat Networks exemplify divergent specialization strategies, while EfficientIP occupies a position emphasizing integrated security layers. These three anchors demonstrate how vendor selection increasingly hinges on whether buyers prioritize DNS threat response workflows, hybrid cloud connectivity, or carrier-grade orchestration scale. The competitive calculus favors those with pre-certified compliance postures in regulated European and North American markets.
| Leading Market Players |
|---|
| Infoblox |
| BlueCat Networks |
| EfficientIP |
| Cisco Systems |
| Cygna Labs |
| Men & Mice |
| FusionLayer |
| SolarWinds |
| TCPWave |
| Others |
Value Chain & Pricing Dynamics
Federal contractors facing NIST SP 800-53 audit mandates are consolidating procurement toward pre-certified vendors, compressing supplier diversity and elevating pricing power for compliance-ready incumbents. This demand concentration forces supply-side specialization around FIPS 140-2 cryptographic modules and immutable logging infrastructure, reshaping cost structures across the vendor base.
Pricing Analysis
Distributor margins on perpetual-license appliances have compressed as subscription-based SaaS delivery captures procurement preference. Pricing stratifies across carrier-grade orchestration tiers, hybrid cloud connectivity bundles, and managed service overlays, with certification grade and after-sales support intensity as the primary differentiation drivers. Cost compression in mid-market segments is intensifying because open-source alternatives with commercial support overlays are eroding base-layer pricing. Government agencies exhibit lowest price sensitivity due to compliance mandates, while educational institutions demonstrate highest sensitivity.
Supply Chain Analysis
Returns and refurbishment flows are minimal in this software-centric market, though virtual appliance redistribution and license reallocation create secondary circulation patterns. Supply concentration centers on the United States, Germany, and South Korea, where carrier-grade development clusters and federal procurement hubs anchor vendor engineering operations. The technology stack draws from cryptographic module suppliers, cloud infrastructure providers, and YANG modeling toolchain developers. Single-source vulnerability around FIPS 140-2 validation laboratories creates certification bottlenecks. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and specialized federal channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on the shift from perpetual licensing to subscription-based consumption, which smooths revenue recognition and reduces customer acquisition cost over time.
For Market Incumbents: Deploy API-first architecture standardization to lock in carrier-grade deployments before intent-based networking talent scarcity widens. Consolidate channel control through pre-certified compliance postures that federal contractors cannot bypass. Counter the threat from open-source alternatives with commercial support overlays by embedding predictive AI remediation into core lease management workflows. For New Entrants and Emerging Players: Begin with private 5G campus network deployments in Germany's Ruhr region, where industrial enterprises lack certified network automation engineers and tolerate higher service premiums. The most penetrable segment is mid-market manufacturing facilities exhausting IPv4 private ranges. A Kubernetes-native addressing angle bypasses incumbent appliance-centric positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play IPAM vendors possessing EUCC framework pre-certification and established API ecosystems. Long-term viability favors those anchoring carrier-grade orchestration scale rather than point-solution specialists facing consolidation pressure. Watch NIST SP 800-53 revision cycles as inflection indicators for mandatory upgrade demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies DNS-DHCP-IPAM control planes across AWS, Azure, and private OpenStack estates. |
| EU Cybersecurity Certification | Opens public sector procurement channels through EUCC cryptographic lease signing validation. |
| Acquisition of Specialist Firm | Absorbs YANG modeling expertise and intent-based networking talent pools. |
| Strategic Partnership | Embeds DHCP orchestration into hyperscaler edge compute provisioning workflows. |
| Geographic Expansion | Targets South Korean 5G core virtualization and Singapore financial services edge deployments. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with network automation engineers, federal procurement officers, carrier infrastructure architects, and cloud platform integration specialists informed demand-side assessments. Secondary sources included NIST SP 800-53 documentation, FCC reliability filings, ETSI NFV specifications, and hyperscaler capex disclosures. Bottom-up lease table modeling and top-down carrier spending analysis provided triangulation.
Rate-of-change decomposition across the analysis window separated volume expansion from price-mix effects. Segmentation dimensions modeled include deployment model, organization scale, vertical regulatory exposure, integration complexity, and regional certification framework. CAGRs were derived from subscriber session growth curves, IPv6 dual-stack migration timelines, and intent-based networking adoption rates. Cloud-native controller penetration and private 5G campus network buildouts served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen protocol standardization shifts, abrupt regional internet registry policy changes, and carrier M&A consolidation effects. Forecasts reflect assumptions around sustained federal compliance mandate enforcement and gradual IPv4 secondary market price escalation. Practitioners should monitor NIST framework revision announcements, EUCC certification timeline acceleration, and hyperscaler edge compute rollout pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Network Packet Broker Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Global Routing Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
2.4GHz Router Market
Network Technology
5G Enterprise Private Network Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Global Home Networking Device Market
Network Technology
5G CPE Device Market
Network Technology
Optical Networking Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Network Devices Market
Network Technology
Global Wireless Router Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
Enterprise Routers Market