
 Mobile Backhaul Market | 2026-2036
Mobile Backhaul Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Backhaul Market Analysis
India's massive tower fiberization program is reshaping competitive dynamics across the mobile backhaul ecosystem. Cisco Systems leverages its routing portfolio to anchor high-capacity Ethernet deployments for operators modernizing legacy TDM infrastructure. Huawei Technologies competes aggressively on microwave radio portfolio breadth, sustaining price pressure across emerging markets where fiber trenching remains uneconomical. Ericsson differentiates through integrated fronthaul-backhaul orchestration software, positioning its transport layer as a 5G standalone enabler.
Mobile backhaul comprises the transport infrastructure connecting cell towers to core network elements, typically operating over fiber, microwave, or millimeter-wave links with latency budgets under 5 milliseconds for 5G services. Its primary purpose is to aggregate radio access traffic and deliver it reliably to packet core gateways. Microwave transmission retains structural importance in terrain-constrained deployments where fiber capex proves prohibitive, while Ethernet continues displacing SDH as the dominant Layer 2 transport protocol across greenfield installations. Managed services represent a growing margin pool as operators outsource network operations to vendors with multi-technology expertise.
The FCC in the United States enforces spectrum coordination rules that shape microwave link deployment density in congested metropolitan corridors. ETSI standards in Europe mandate security hardening for transport nodes handling critical infrastructure traffic, directly influencing product certification requirements. India's TRAI imposes quality-of-service benchmarks on backhaul connectivity to rural towers, creating compliance-driven demand for satellite and wireless alternatives where fiber remains unavailable. Stakeholders must monitor spectrum reallocation timelines and open transport interface standardization to anticipate which technology layers commoditize fastest.
Market Dynamics
5G network densification is compressing transport layer architectures, forcing operators to collapse legacy TDM hierarchies into packet-native Ethernet while maintaining sub-5ms latency budgets across heterogeneous access topologies.
Growth Catalysts
- EU Open RAN interoperability mandates:The European Union's transport interface standardization rules are accelerating IP-based migration across multi-vendor radio deployments, creating retrofit demand for software-defined backhaul controllers.
- India's tower fiberization program:TRAI's quality-of-service benchmarks on rural connectivity are compelling operators to deploy satellite and millimeter-wave alternatives where fiber trenching remains uneconomical.
- Microwave radio portfolio expansion:Terrain-constrained deployments in mountainous and island geographies sustain structural demand for high-capacity wireless transport where civil works capex exceeds radio equipment costs by multiples.
Market Restraints
- Copper and optical component cost volatility:Fiber cable and transceiver supply concentration in East Asian manufacturing clusters exposes operators to input price swings and extended lead times for high-count ribbon fiber.
- Spectrum coordination friction:FCC microwave licensing density limits in congested US metropolitan corridors restrict link deployment and force costly frequency engineering or alternative technology pivots.
- Legacy TDM stranded asset risk:Operators with substantial SDH/SONET installed bases face accelerated depreciation as packet-native equipment renders circuit-switched hardware economically obsolete.
Strategic Opportunities
- Managed services outsourcing:Tier-1 operators in Western Europe are unbundling network operations to vendors with multi-technology orchestration expertise, converting capex into recurring opex relationships.
- Fronthaul-backhaul convergence:Centralized RAN architectures are collapsing traditional transport boundaries, creating demand for unified timing and synchronization platforms that serve both midhaul and backhaul functions.
- ETSI security hardening compliance:European critical infrastructure protection mandates for transport node certification are generating premium-tier hardware demand with embedded encryption and zero-trust access controls.
Industry Challenges
- Packet timing synchronization expertise scarcity:Precision Time Protocol and SyncE deployment require specialized engineering skills that legacy TDM operations teams lack, creating workforce retraining bottlenecks.
- Multi-vendor integration complexity:Open RAN disaggregation fragments responsibility across radio, transport, and orchestration suppliers, complicating root-cause analysis and service level enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Backhaul Market |
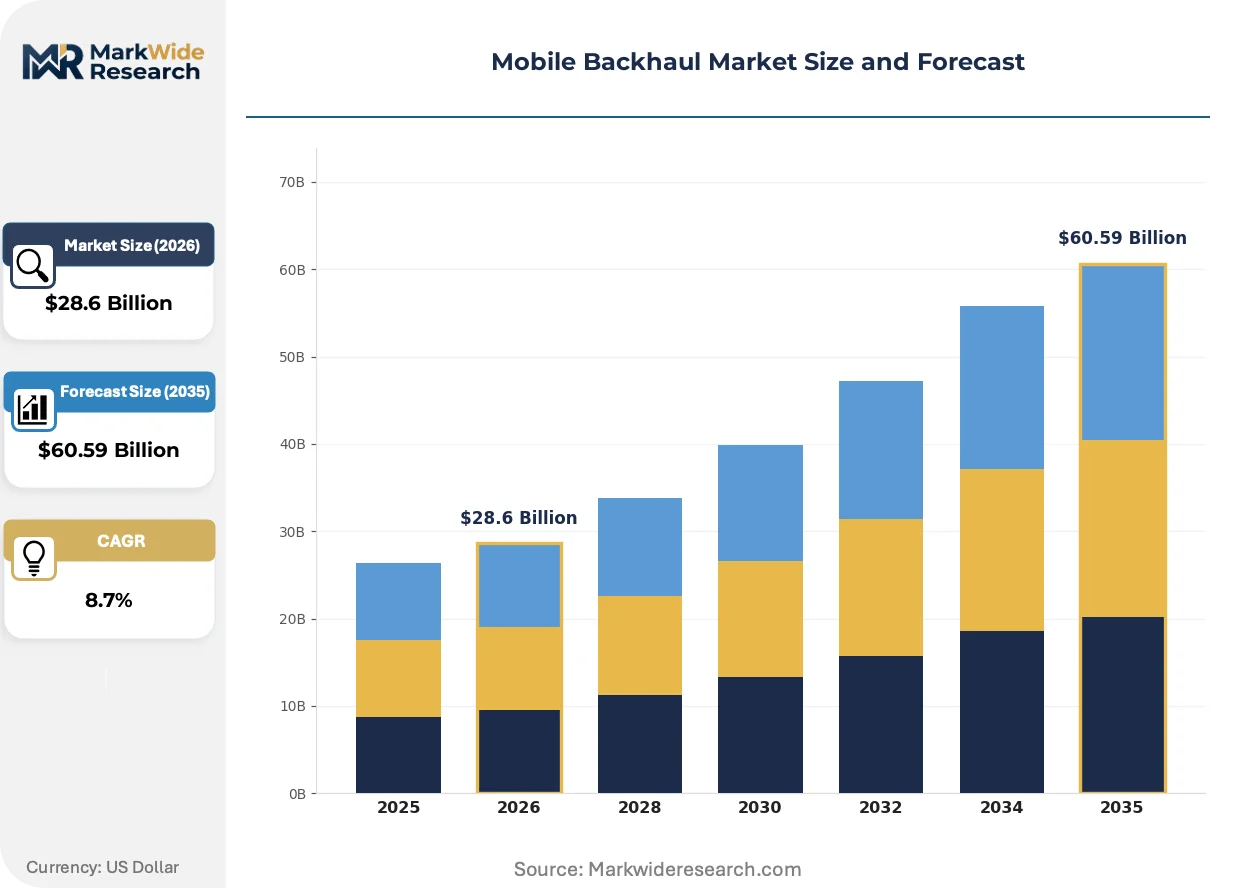
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ethernet, MPLS, SDH, Microwave Service Type: DIA, Managed Services, Optical Transport, Satellite Deployment: On-Premises, Cloud-Based, Hybrid, Edge End User: Telecom Operators, Enterprises, ISPs, Private Networks |
| Companies Covered | Cisco Systems, NEC Corporation, Huawei Technologies, Broadcom, Fujitsu, Nokia, ZTE Corporation, Ceragon Networks, Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Backhaul Market Emerging Trajectories
Ethernet is actively collapsing legacy transport hierarchies while regulatory mandates force security and interoperability upgrades across vendor ecosystems. These shifts are reconfiguring procurement patterns and competitive differentiation.
Segment routing with IPv6 data plane (SRv6) is digitizing traffic engineering across converged 5G transport networks. Tier-1 operators in South Korea and Japan are deploying SRv6-native routers to simplify label distribution protocol dependencies. This compression of control plane complexity is digitizing how operators manage slice-aware connectivity across disaggregated radio access networks.
ETSI's cybersecurity standards for transport infrastructure are mandating hardware root-of-trust and secure boot capabilities across European deployments. Equipment vendors must now certify nodes under Common Criteria or equivalent frameworks before national operator procurement. Mobile network operators in Germany and France are responding by inserting security compliance gates into RFP evaluation criteria, elevating trusted supply chain provenance above pure price competition.
Network-as-a-service commercial models are unbundling traditional capex-heavy procurement for mid-size operators and neutral host providers. Subscription-based access to managed microwave and fiber capacity is displacing perpetual license purchases in Southeast Asian and Latin American markets. This preference shift is most visible among tower companies and private network deployers seeking operational flexibility without balance sheet expansion.
Mobile Backhaul Market Segmentation
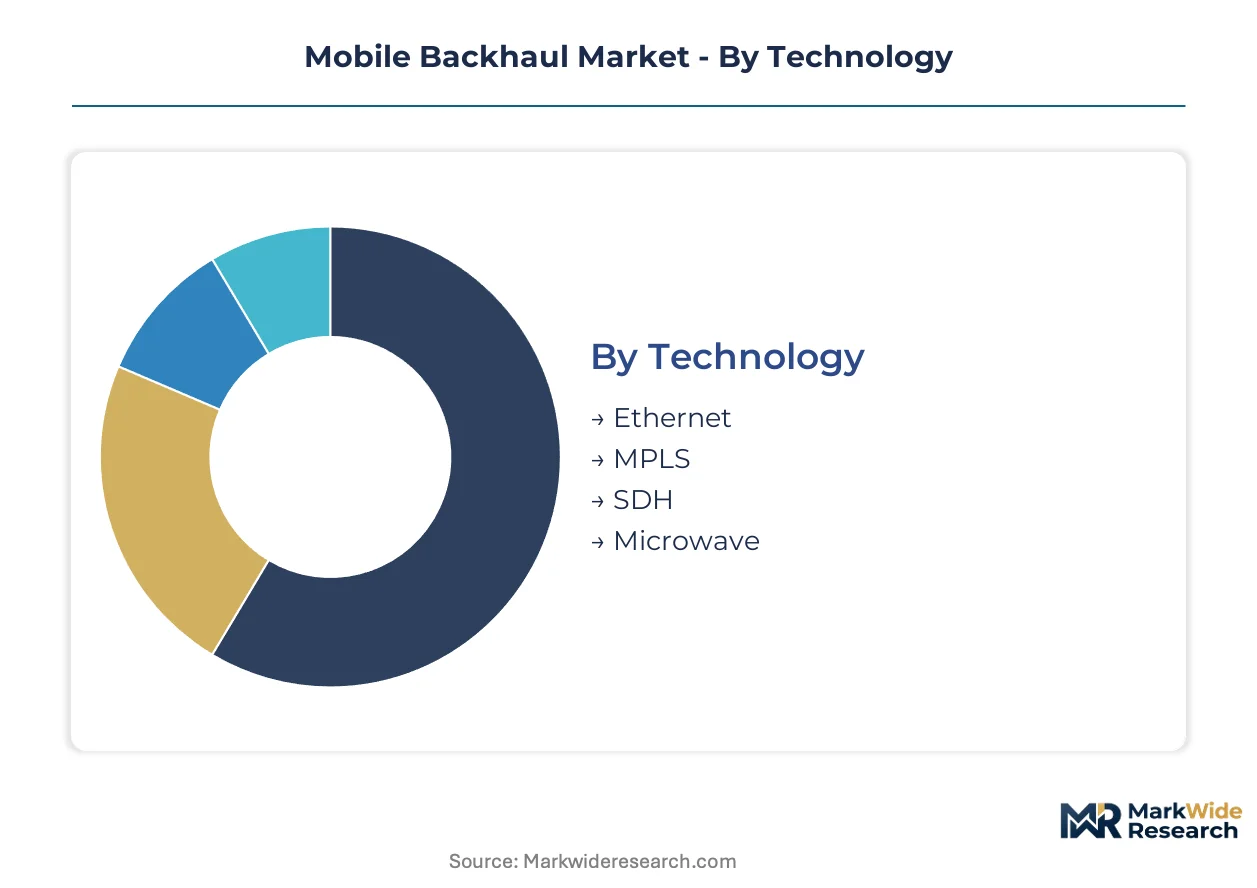
Mobile backhaul segmentation reveals how transport infrastructure fragments across protocol generations, service commercialization models, and deployment topologies. Each dimension carries distinct margin profiles and vendor competitive dynamics that reshape procurement patterns as 5G standalone architectures mature.
Technology:
The use-case spectrum spans legacy circuit-switched hierarchies through packet-native Ethernet and wireless microwave alternatives, each occupying specific latency, capacity, and terrain-constrained deployment scenarios.
- Ethernet:Packet-native Layer 2 transport dominates greenfield installations with simplified provisioning and native IP compatibility. Indian operators deploy Ethernet-over-fiber aggressively where TRAI quality benchmarks mandate rural connectivity upgrades.
- Microwave:Point-to-point and point-to-multipoint radio links serve terrain-constrained deployments where fiber trenching costs exceed equipment expenditure by substantial multiples. Island geographies and mountainous corridors sustain structural demand for high-capacity millimeter-wave variants.
- MPLS:Multi-Protocol Label Switching retains relevance in converged transport networks requiring traffic engineering granularity across heterogeneous access topologies.
- SDH:Synchronous Digital Hierarchy faces accelerated depreciation as operators collapse TDM hierarchies into packet-native architectures, leaving substantial stranded asset exposure.
The dominant share belongs to Ethernet, while Microwave is closing the gap fastest in emerging markets with challenging civil infrastructure.
Service Type:
Cost tier differentiation separates capital-intensive ownership models from operational expenditure structures that unbundle network operations to specialized vendors.
- Managed Services:Tier-1 operators in Western Europe outsource multi-technology orchestration to vendors, converting capex into recurring opex relationships with guaranteed service levels.
- DIA:Dedicated Internet Access provides uncontended connectivity for enterprises and tower companies requiring deterministic performance rather than best-effort broadband.
- Optical Transport:Dense wavelength division multiplexing and coherent optics anchor high-capacity fiber deployments across metropolitan aggregation layers.
- Satellite:Geostationary and low-earth-orbit constellations address rural connectivity gaps where terrestrial infrastructure remains uneconomical, particularly under India's tower fiberization mandates.
Managed Services commands the premium pricing tier, though Satellite is expanding most quickly where regulatory rural coverage obligations bite hardest.
Deployment:
Volume concentration varies dramatically between centralized cloud architectures and distributed edge deployments that collapse fronthaul-backhaul boundaries.
- Edge:Distributed compute and transport nodes positioned at cell tower aggregation points minimize latency for 5G ultra-reliable low-latency services. South Korean operators deploy edge-native transport controllers to support centralized RAN architectures.
- Cloud-Based:Software-defined transport functions virtualized in hyperscale data centers enable rapid scaling without hardware procurement cycles.
- Hybrid:Mixed architectures preserve legacy TDM interworking while migrating control plane functions to cloud infrastructure.
- On-Premises:Physical transport equipment deployed in operator facilities retains relevance where data sovereignty or security hardening requirements preclude cloud migration.
Edge deployments lead volume growth, while Cloud-Based is climbing the fastest as operators pursue operational flexibility.
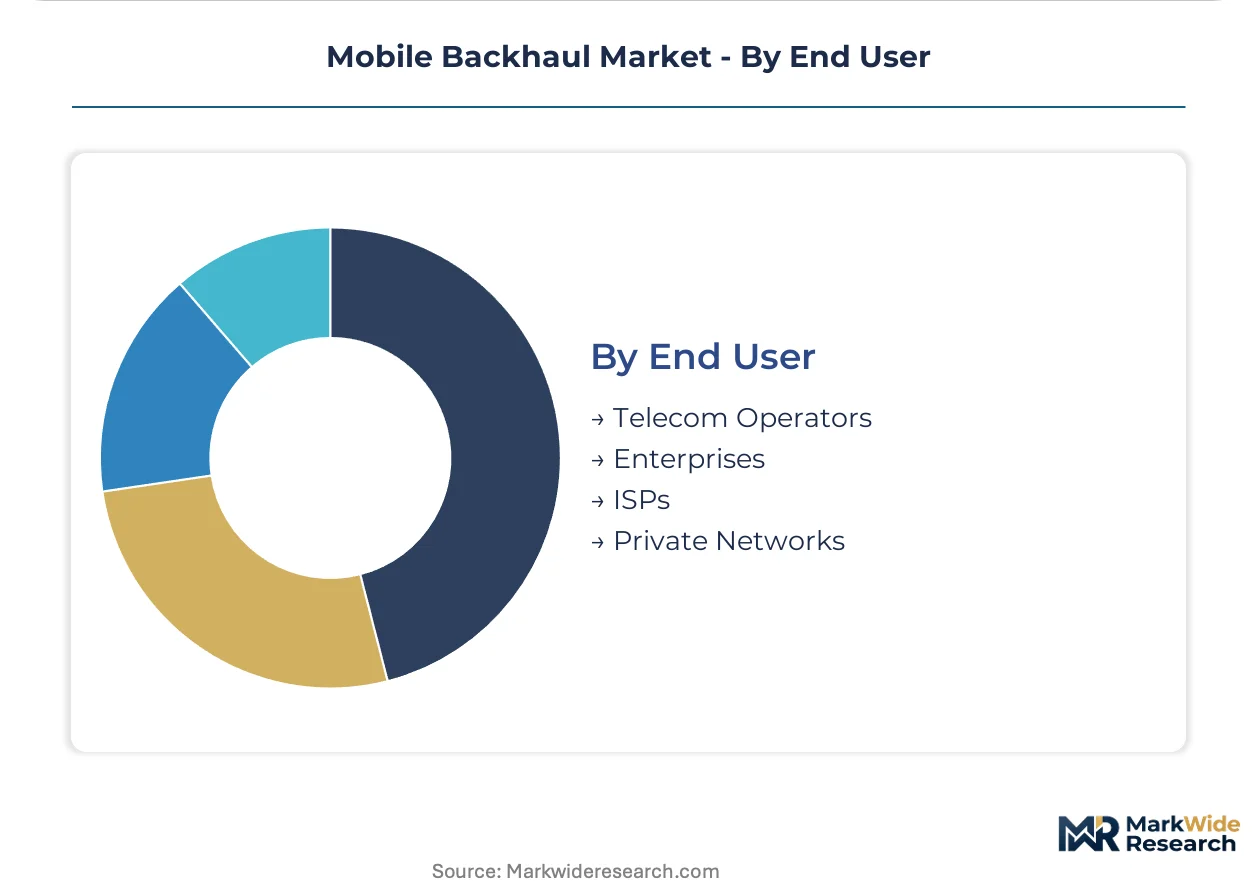
End User:
Customer type segmentation maps directly to procurement sophistication, with telecom operators driving standardization while private networks demand customized security and timing specifications.
- Telecom Operators:Mobile network operators account for the majority of backhaul expenditure, with procurement decisions increasingly centralized under group technology functions. European operators embed ETSI security compliance gates into RFP evaluation criteria.
- Private Networks:Industrial campuses, ports, and mining operations deploy dedicated transport infrastructure with specialized timing and isolation requirements.
- Enterprises:Large corporations procure backhaul capacity for campus networks and branch connectivity, often through managed service wrappers.
- ISPs:Internet service providers aggregate mobile traffic for wholesale resale, typically price-sensitive and volume-focused in procurement.
Telecom Operators retain the dominant procurement volume, though Private Networks are gaining share fastest as 5G standalone enables vertical-specific deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landings at Chennai and Mumbai anchor India's emergence as a mobile backhaul demand center, while terrestrial fiber corridors across Germany and the United States reshape interconnection economics for 5G transport infrastructure.
United States
Metro fiber density in Dallas-Fort Worth and Atlanta drives edge transport deployment for 5G standalone networks. FCC spectrum coordination rules restrict microwave link density in congested corridors, forcing operators toward fiber and millimeter-wave alternatives. Tower companies in the Southeast are consolidating transport procurement under neutral host models.
Germany
Industrial private networks in the Ruhr Valley and Bavaria generate specialized timing and synchronization requirements for backhaul infrastructure. ETSI security hardening mandates under critical infrastructure protection frameworks require hardware root-of-trust certification for transport nodes. Equipment vendors in Munich and Stuttgart are embedding Common Criteria compliance into product roadmaps.
India
TRAI quality-of-service benchmarks on rural tower connectivity compel operators to deploy satellite and wireless backhaul where fiber trenching costs remain prohibitive. The national tower fiberization program targets 70% fiberization of cell sites, driving Ethernet-over-fiber procurement in Maharashtra and Gujarat. Microwave radio vendors are competing aggressively for terrain-constrained deployments in the Himalayan foothills.
South Korea
Seoul Capital Area operators are collapsing fronthaul-backhaul boundaries through centralized RAN architectures, creating demand for unified timing platforms. SRv6-native router deployments in Busan-Ulsan simplify traffic engineering across converged transport networks. Government 5G investment programs are accelerating edge-native transport controller adoption.
United Kingdom
London's financial district generates low-latency backhaul requirements for enterprise 5G services, with operators deploying dedicated fiber rings. Ofcom spectrum management frameworks shape microwave licensing in dense urban corridors. Neutral host providers in the Midlands are unbundling transport capacity for private network deployers.
Mobile Backhaul Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base organizes around three archetypes: diversified telecom equipment conglomerates with end-to-end transport portfolios, microwave radio specialists with terrain-focused hardware, and semiconductor vendors supplying optical and routing silicon. Competitive dynamics center on strategic partnerships for multi-vendor interoperability and portfolio diversification into managed services.
Within the diversified equipment tier, Cisco Systems and Huawei Technologies exemplify platform breadth across routing, optical, and microwave domains. NEC Corporation and Fujitsu occupy positions bridging Japanese industrial standards with international deployment requirements. ZTE Corporation and Ceragon Networks represent microwave-centric specialists competing on radio link density and spectral efficiency. Nokia and Ericsson anchor European-origin positions through integrated radio-transport orchestration software. Broadcom sits upstream as a silicon supplier enabling merchant routing and switching platforms.
| Leading Market Players |
|---|
| Cisco Systems |
| NEC Corporation |
| Huawei Technologies |
| Broadcom |
| Fujitsu |
| Nokia |
| ZTE Corporation |
| Ceragon Networks |
| Ericsson |
| Others |
Supply Flow & Price Mechanics
Fiber cable and transceiver supply concentration in East Asian manufacturing clusters exposes operators to input price swings and extended lead times for high-count ribbon fiber, compressing margins across procurement tiers while forcing inventory buildups among Tier-1 deployers. This dependency architecture widens pricing spreads between premium certified hardware and economy-tier alternatives while reshaping vendor qualification criteria.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts for microwave radio and optical transport equipment, with three-tier pricing separating ETSI-certified secure nodes from standard commercial gear and economy-tier refurbished units. Price differentiation rests on Common Criteria certification grade and guaranteed service level agreements, with European operators paying substantial premiums for hardware root-of-trust compliance. Cost compression in the economy tier is intensifying because Chinese microwave vendors are flooding emerging markets with spectrally efficient radios at aggressive price points. Tower companies and neutral host providers exhibit the highest price sensitivity, while German industrial private network deployers prioritize timing precision over unit cost.
Supply Chain Analysis
Export-control regime restrictions on advanced routing silicon and coherent optical DSPs limit technology flows from US and Dutch suppliers to Chinese equipment vendors, fragmenting procurement channels. Manufacturing concentrates in China, Taiwan, and Malaysia for optical transceivers, with Japan and Finland anchoring specialized microwave radio assembly. Supply chains draw from gallium arsenide substrates, indium phosphide wafers, and rare-earth magnet components for antenna positioning systems. Single-source vulnerability around submarine cable landing stations for India and island geographies threatens continuity. Distribution runs through direct vendor-operator relationships for Tier-1 carriers, with systems integrators and regional distributors serving mid-size operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering talent for Precision Time Protocol and SyncE deployment remains scarce, constraining operator migration timelines and creating premium capture opportunities for vendors with certified field teams. This capability gap shapes competitive positioning across the ecosystem.
For Market Incumbents: Pre-empt margin erosion by embedding managed services orchestration capabilities that capture recurring opex relationships from operators collapsing in-house transport teams. Acquire microwave radio specialists in terrain-constrained geographies to block Chinese vendors from establishing anchor deployments. Secure ETSI Common Criteria certification ahead of procurement gates to disqualify uncertified rivals from European RFPs. For New Entrants and Emerging Players: Establish a beachhead in India's tower fiberization program by offering satellite backhaul solutions where TRAI rural connectivity mandates bite hardest and fiber trenching costs remain prohibitive. Target neutral host providers in Southeast Asia with subscription-based network-as-a-service models that displace perpetual license purchases. Lead with operational flexibility messaging rather than equipment specifications to differentiate from incumbent hardware vendors. For Investors and Strategic Acquirers: ETSI security hardening mandates reshape the acquisition landscape by elevating certified European vendors above price-competitive Asian suppliers in procurement evaluations. Position for a five-to-ten year horizon where managed services revenue multiples exceed hardware trading multiples. Target microwave radio specialists with millimeter-wave portfolios and established terrain-constrained deployment track records. Monitor TRAI enforcement actions on rural quality-of-service benchmarks as the signal indicating accelerated satellite and wireless backhaul procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Services Capability Buildout | Captures recurring opex relationships as European operators unbundle network operations to vendors. |
| ETSI Security Certification Investment | Creates procurement gate compliance that disqualifies uncertified competitors from German and French tenders. |
| Microwave Radio Portfolio Expansion | Secures terrain-constrained deployments in Himalayan and island geographies where fiber proves uneconomical. |
| SRv6-Native Router Development | Simplifies traffic engineering for South Korean operators collapsing fronthaul-backhaul boundaries. |
| Satellite Backhaul Partnership | Addresses TRAI rural connectivity mandates where terrestrial infrastructure remains unavailable. |
Methodological Framework
Operator-level perspectives from transport network engineers, procurement directors at Tier-1 carriers, microwave radio deployment specialists, and ETSI certification auditors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FCC spectrum licensing databases, TRAI quality-of-service enforcement records, ETSI cybersecurity standard drafts, and equipment vendor SEC disclosures. Bottom-up deployment tracking across fiber route announcements and microwave link registrations triangulated against top-down operator capex guidance.
Scenario-bracketing framed the analytical approach across the analysis window, with technology migration curves and regulatory enforcement timelines as primary uncertainty bands. Segmentation modeling incorporated protocol generation, service commercialization model, deployment topology, and end-user procurement sophistication. CAGRs derived from unit deployment trajectories and average revenue per link assumptions, with 5G standalone rollout pace and Open RAN interoperability mandates as key forecast inputs.
Sensitivities concentrate around spectrum reallocation timelines, export-control regime expansions, and fiber trenching cost inflation in emerging markets. Forecasts reflect documented assumptions on technology substitution rates and regulatory enforcement intensity. Material shifts in ETSI certification requirements or FCC microwave licensing density rules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Europe Structured Cabling Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
CPE Router Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
Malaysia Wireless Router Market
Network Technology
Fiber to the Home (FTTH) Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
Gigabit Passive Optical Network (GPON) Market
Network Technology
Gigabit Ethernet Market
Network Technology
Virtual Router Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Global Internet Transit Market
Network Technology
MENA Wireless Routers Market
Network Technology
Fiber to the Premises Market
Network Technology
Europe Self-Healing Networks Market