
 Network Packet Broker Market | 2026-2036
Network Packet Broker Market Size, Share, and Industry Trends Forecast 2026-2036
Network Packet Broker Market Analysis
100G and 400G port density upgrades is unwinding legacy 10G architectures across carrier and enterprise networks. Gigamon leverages silicon photonics integration to sustain throughput leadership at these higher speeds. Arista Networks anchors cloud-scale deployments with its merchant silicon-based visibility fabric. VIAVI Solutions competes through specialized test and monitoring convergence in 5G transport environments.
A network packet broker is a Layer 2-7 device that aggregates, filters, load-balances, and replicates network traffic streams from multiple SPAN ports or tap points to security and performance monitoring tools, with typical specifications including sub-microsecond latency, 1.28 Tbps switching capacity, and support for VXLAN/GRE tunnel decapsulation. Its primary purpose is eliminating tool sprawl and blind spots by ensuring each analytics or security appliance receives precisely the traffic subset it requires without oversubscription. Hardware appliances still dominate revenue due to deterministic performance requirements in carrier core networks, though cloud services represent the fastest-expanding margin pool as SaaS-delivered visibility gains traction among mid-market enterprises. Edge computing deployments are emerging as a structural growth vector where hybrid architectures must extend broker policies from centralized data centers to distributed 5G baseband and industrial IoT gateways.
FCC net neutrality restoration proceedings and NIST cybersecurity framework updates are reshaping lawful intercept and encryption visibility mandates for domestic network operators. The EU AI Act and GDPR cross-border data transfer rules add compliance complexity for multinational enterprises routing European traffic through U.S.-based broker clusters. Stakeholders must weigh silicon supply chain constraints against the transition timeline for 800G-ready platforms as they commit to refresh cycles.
Market Dynamics
The 100G-to-400G port density transition is compressing refresh cycles across carrier and enterprise networks, forcing infrastructure teams to retire 10G architectures before full depreciation. This speed-tier migration creates simultaneous demand pull for high-throughput visibility fabrics while straining capital allocation frameworks.
Growth Catalysts
- SEC transaction surveillance mandates:BFSI compliance teams deploy packet brokers to meet audit trail requirements for electronic trading reconstruction.
- Hyperscale data center buildouts:Northern Virginia and Dallas clusters drive procurement of high-density chassis to support east-west traffic visibility.
- Silicon photonics integration:Optical engine advances enable 400G forwarding at sub-microsecond latency without thermal throttling.
Market Restraints
- Merchant silicon supply concentration:Dependence on two foundry sources for 7nm switching ASICs creates allocation risk during node transitions.
- Encryption visibility gaps:TLS 1.3 and ESNI adoption limits payload inspection depth for lawful intercept applications.
- Legacy tool integration friction:Existing security appliances lack 400G interfaces, forcing expensive media conversion layers.
Strategic Opportunities
- Edge computing extension:5G baseband and industrial IoT gateways require distributed broker policies outside centralized data centers.
- SaaS-delivered visibility:Mid-market enterprises adopt cloud-native packet brokers to avoid hardware lifecycle management.
- EU AI Act compliance:Cross-border data routing mandates create demand for European-hosted broker clusters with GDPR-aligned data residency.
Industry Challenges
- Network engineering talent scarcity:Deep expertise in VXLAN/GRE tunnel decapsulation and Layer 2-7 filtering logic remains concentrated among senior practitioners.
- Multi-vendor interoperability certification:Proprietary metadata formats between broker platforms and analytics tools extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Packet Broker Market |
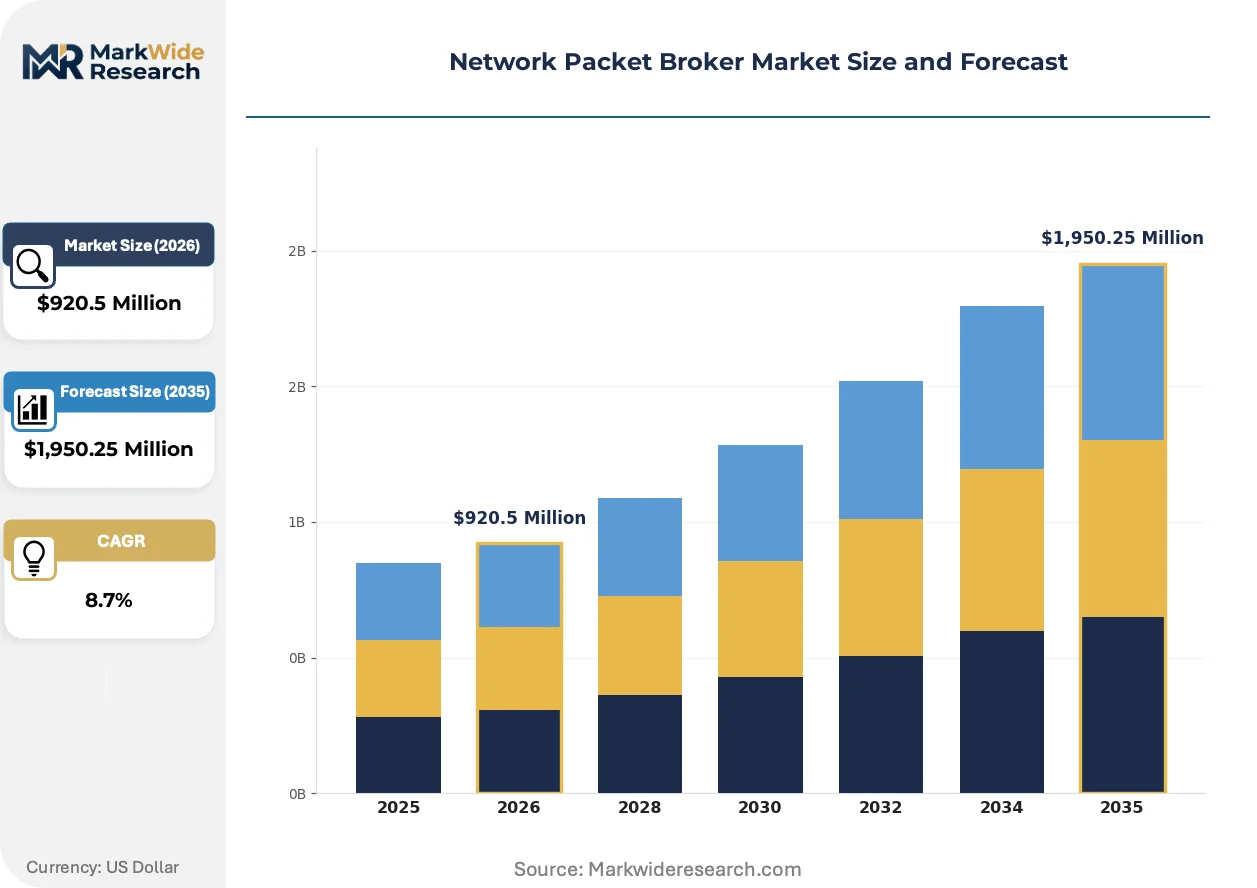
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,950.25 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Virtual Appliances, Cloud Services Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Telecommunications, Government, BFSI, Healthcare Use Case: Network Monitoring, Data Security, Performance Optimization, Traffic Analysis |
| Companies Covered | Arista Networks, APCON, Keysight Technologies, Cubro Network Visibility, VIAVI Solutions, Gigamon, NetScout Systems, Network Critical, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Packet Broker Market Emerging Trajectories
Silicon photonics and merchant silicon roadmaps are converging to redefine packet broker form factors and deployment economics. These advances compress power consumption while expanding throughput ceilings.
Optical switching engines with integrated silicon photonics transceivers are miniaturizing 400G port density into quarter-rack chassis previously requiring full rack-scale installations. Cloud-scale operators in hyperscale facilities adopt these compact platforms to reclaim floor space and cooling capacity. This miniaturization is collapsing the traditional trade-off between port count and physical footprint.
FCC net neutrality restoration proceedings are mandating enhanced lawful intercept capabilities for domestic broadband providers. The proceedings require granular traffic identification and session reconstruction for compliance monitoring. Tier-1 carriers are upgrading broker deployments to meet these visibility mandates ahead of enforcement deadlines.
Enterprise procurement teams are consolidating vendor relationships around integrated visibility fabrics rather than best-of-breed point solutions. Security operations centers favor unified platforms that combine packet brokers with network detection and response in single administrative domains. This consolidation pattern is most pronounced among Fortune 500 financial services firms with complex multi-cloud architectures.
Network Packet Broker Market Segmentation
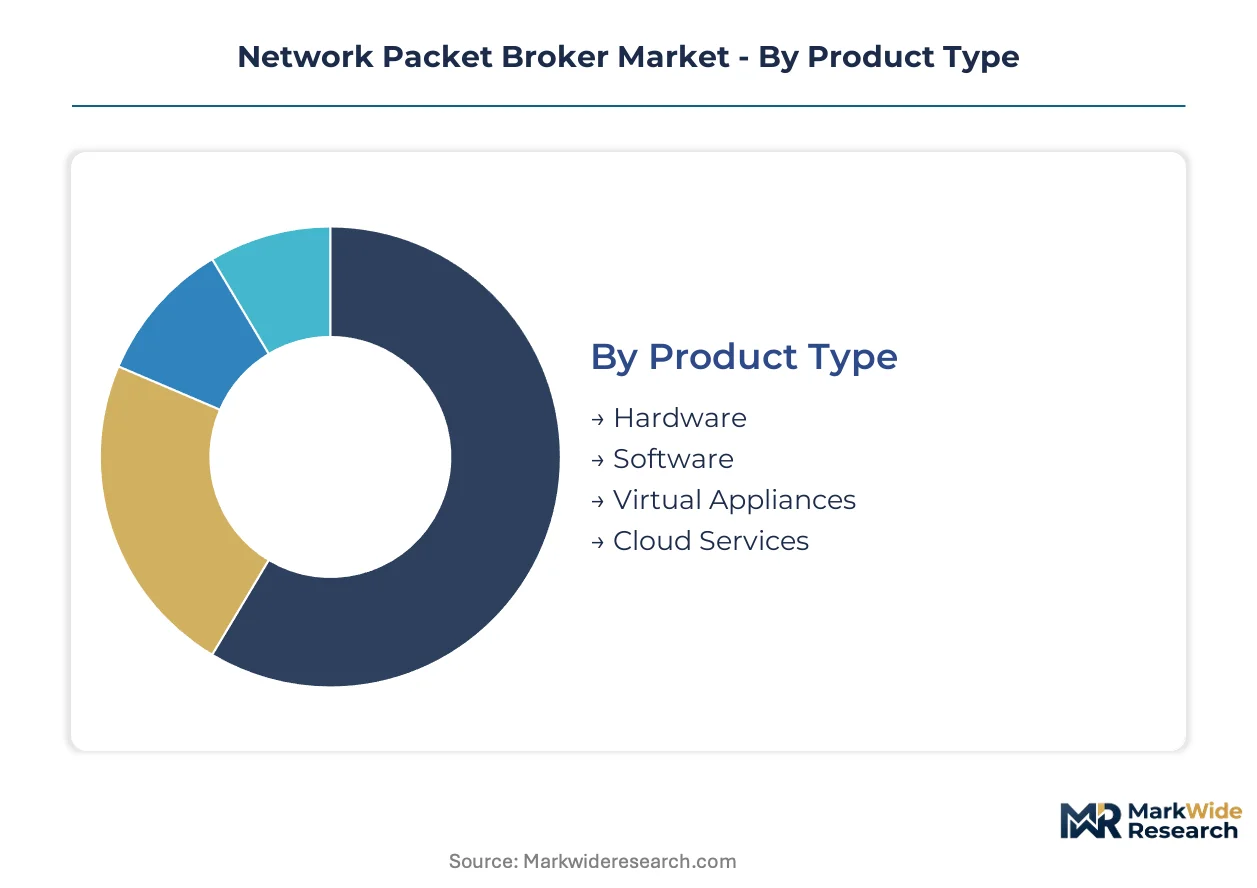
Network packet broker procurement patterns diverge sharply across deployment modes, end-user compliance regimes, and traffic inspection workloads. Understanding these segment boundaries clarifies where hardware refresh cycles concentrate versus where SaaS delivery gains traction.
Product Type:
Domestic hyperscale operators anchor hardware demand, while mid-market enterprises across export markets drive cloud services expansion.
- Hardware:Chassis-based appliances with 400G port density and silicon photonics integration dominate carrier core networks. Tier-1 operators in Northern Virginia and Dallas data centers specify sub-microsecond latency for east-west traffic visibility. This segment holds the largest share; momentum sits with Cloud Services.
- Software:Disaggregated broker functions running on commodity x86 servers appeal to DevOps teams automating policy orchestration. European financial institutions favor software brokers for GDPR-aligned data residency controls. Demand concentrates in containerized environments where Kubernetes-native deployment accelerates provisioning cycles.
- Virtual Appliances:VMware and KVM-hardened images extend visibility into private cloud estates without dedicated hardware sprawl.
- Cloud Services:SaaS-delivered brokers eliminate lifecycle management overhead for mid-market enterprises lacking specialized network engineering talent.
Hardware retains revenue dominance; cloud services climb the fastest as procurement shifts toward operational expenditure models.
Deployment:
Cost tier stratification separates capital-intensive on-premise builds from pay-as-you-consume cloud alternatives.
- On-Premise:Dedicated appliance deployments in carrier hotels and enterprise data centers satisfy deterministic performance requirements for lawful intercept applications. BFSI compliance teams mandate on-premise brokers to meet SEC audit trail specifications for transaction reconstruction. This segment holds the largest share; momentum sits with Edge Computing.
- Cloud-Based:Native AWS, Azure, and GCP broker instances serve cloud-first enterprises with distributed workforce architectures. Healthcare providers migrating electronic health records to public cloud adopt cloud-based visibility to maintain HIPAA-aligned traffic inspection without physical infrastructure.
- Hybrid:Unified policy planes spanning on-premise appliances and cloud-native brokers address multi-cloud complexity.
- Edge Computing:Distributed broker policies at 5G baseband units and industrial IoT gateways extend visibility beyond centralized data centers.
On-Premise captures majority revenue; Edge Computing represents the steepest expansion trajectory as 5G transport networks densify.
End User:
Application intensity varies by sector-specific regulatory burden and traffic inspection depth requirements.
- Telecommunications:Carrier networks require highest port density and lawful intercept compliance for FCC-mandated session reconstruction. Tier-1 broadband providers upgrade broker deployments ahead of net neutrality restoration enforcement deadlines. This segment holds the largest share; momentum sits with BFSI.
- Government:Federal and defense agencies mandate TAA-compliant hardware with FIPS 140-2 encryption validation for classified network visibility.
- BFSI:Electronic trading reconstruction and cross-border payment surveillance drive 400G chassis procurement among global systemically important banks.
- Healthcare:HIPAA-covered entities deploy brokers to monitor protected health information flows across integrated delivery networks.
Telecommunications leads absolute spending; BFSI gains share fastest as transaction surveillance mandates tighten.
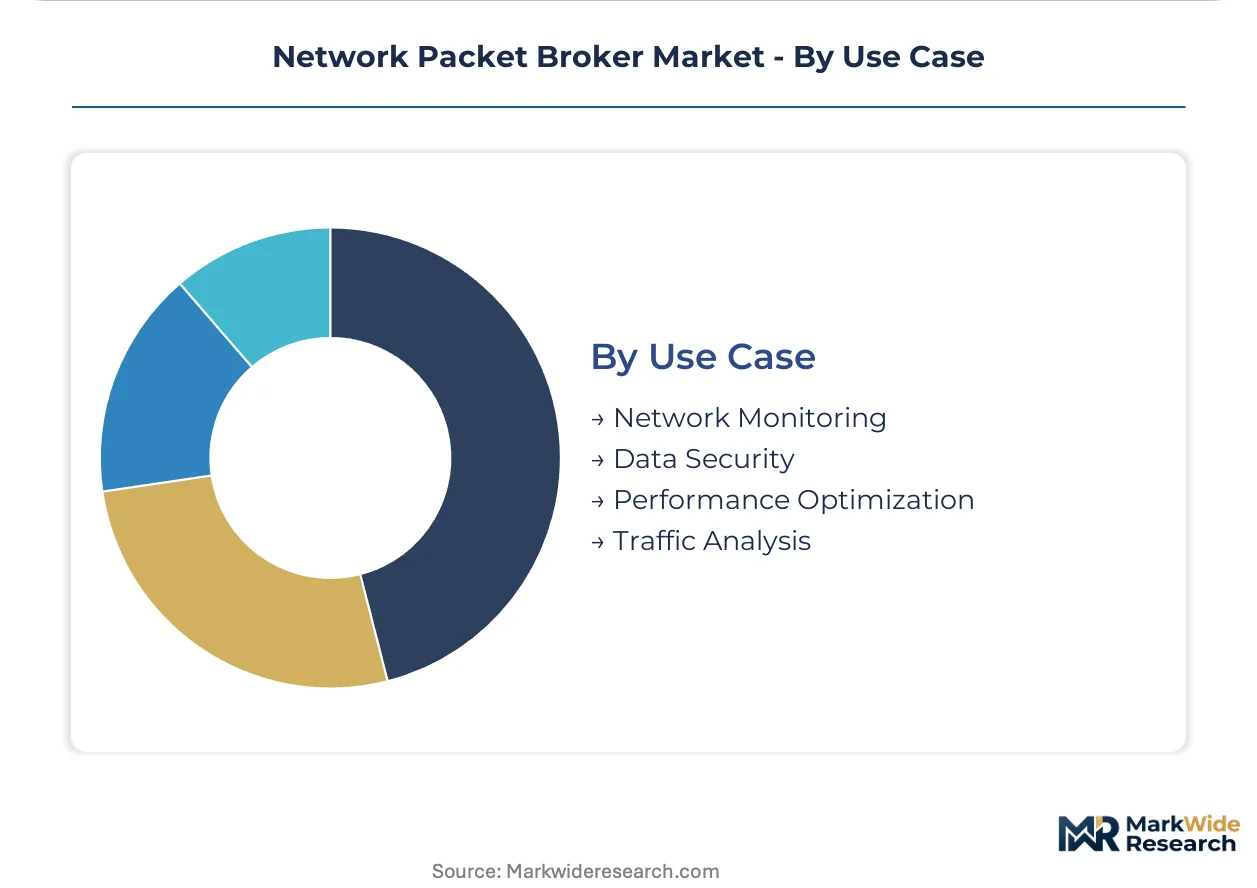
Use Case:
Volume concentration tracks infrastructure lifecycle patterns, with security workloads expanding quicker than performance optimization.
- Network Monitoring:Baseline traffic visibility for mean-time-to-resolution improvement remains the foundational deployment driver. Enterprise network operations centers prioritize this use case for hybrid cloud troubleshooting across MPLS and SD-WAN transports. This segment holds the largest share; momentum sits with Data Security.
- Data Security:Inline threat inspection and encrypted traffic analysis feed next-generation firewalls and intrusion prevention systems. Financial services security operations centers consolidate broker and network detection response platforms to reduce tool sprawl.
- Performance Optimization:Application-aware traffic steering identifies latency anomalies in microservices architectures.
- Traffic Analysis:Deep packet inspection for quality-of-service policy enforcement and bandwidth allocation optimization.
Network Monitoring dominates current deployments; Data Security shows the fastest expansion as encryption visibility gaps drive appliance upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows concentrate in American and European manufacturing bases, while import dependence shapes procurement patterns across Asia-Pacific emerging markets. Trade balances reflect specialized silicon photonics component sourcing from Taiwan and Japan against finished appliance assembly in the United States and Germany.
United States
Hyperscale operators in Northern Virginia and Dallas drive chassis procurement for east-west traffic visibility. FCC net neutrality restoration proceedings mandate enhanced lawful intercept capabilities ahead of enforcement deadlines. The Ashburn-Loudoun County corridor anchors domestic demand as cloud providers expand 400G switching fabrics.
Germany
Industrial IoT gateway deployments and automotive manufacturing networks require distributed broker policies at production facilities. The EU AI Act and GDPR cross-border data transfer rules compel European-hosted cluster configurations with data residency controls. The Munich-Stuttgart industrial belt concentrates procurement for smart factory visibility.
Japan
Telecommunications carriers upgrade core networks to support 5G transport monitoring and sub-microsecond latency requirements. METI guidance on critical infrastructure cybersecurity shapes procurement specifications for lawful intercept compliance. The Tokyo-Osaka corridor dominates domestic deployment as NTT and KDDI densify optical switching capacity.
India
BFSI sector expansion and digital payment infrastructure drive transaction surveillance deployments meeting SEBI audit requirements. TRAI regulations on lawful interception mandate packet-level visibility for domestic broadband operators. Mumbai and Bangalore financial districts concentrate procurement among systemically important banks.
South Korea
5G baseband unit densification and semiconductor manufacturing networks require edge-computing broker extensions. The country's national cybersecurity framework mandates deep packet inspection for critical infrastructure protection. The Seoul-Suwon corridor anchors demand as Samsung and SK Telecom expand industrial IoT visibility.
Network Packet Broker Market Vendor Landscape
Listed leaders compete with private specialists across capital access and R&D velocity dimensions. The vendor base stratifies into three tiers: merchant silicon-anchored scale players, optical switching specialists, and converged test-and-monitoring integrators. Dominant competitive moves include strategic partnerships for silicon photonics sourcing and portfolio diversification into SaaS-delivered visibility.
Within the merchant silicon tier, Arista Networks and Cisco Systems exemplify scale-driven positioning through cloud-native fabric architectures. Among optical switching specialists, Gigamon occupies a position representing silicon photonics integration leadership. VIAVI Solutions anchors the test-and-monitoring convergence archetype where visibility platforms merge with 5G transport assurance.
| Leading Market Players |
|---|
| Arista Networks |
| APCON |
| Keysight Technologies |
| Cubro Network Visibility |
| VIAVI Solutions |
| Gigamon |
| NetScout Systems |
| Network Critical |
| Cisco Systems |
| Others |
Supply Flow & Price Mechanics
FCC net neutrality restoration proceedings gate both supplier qualification and price differentiation by mandating enhanced lawful intercept capabilities that only certified chassis architectures satisfy. This regulatory threshold splits procurement between premium silicon photonics-integrated platforms and standard merchant silicon alternatives, with compliance investment directly feeding into quoted price bands.
Pricing Analysis
Industrial OEM buyers anchor a tiered pricing structure across premium, standard, and economy levels, with sub-microsecond latency specifications and FIPS 140-2 encryption validation commanding material premiums over baseline 10G-compatible configurations. Price differentiation tracks certification grade and volume scale, as Fortune 500 financial services firms with complex multi-cloud architectures negotiate enterprise-wide visibility fabric contracts while mid-market enterprises face steeper per-port economics. Cost compression in standard-tier hardware is intensifying because merchant silicon supply concentration forces allocation bidding during node transitions. Cloud services represent the least price-sensitive segment, converting capital expenditure avoidance into recurring subscription tolerance.
Supply Chain Analysis
Taiwan Strait transit risk underwrites supply chain vulnerability for 7nm switching ASICs and silicon photonics transceivers, with finished appliance assembly concentrated in the United States and Germany. Raw material dependencies center on indium phosphide substrates, germanium-on-silicon photodetectors, and advanced packaging substrates sourced from Japan and South Korea. Single-source vulnerability in foundry capacity for 400G-ready platforms creates allocation risk during refresh cycle peaks. Distribution runs through direct carrier procurement teams in Northern Virginia and Dallas, supplemented by channel partners serving European industrial IoT gateway deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed security service attach rates for packet broker policy orchestration are expanding faster than hardware revenue as mid-market enterprises outsource lifecycle management. This recurring-revenue layer restructures vendor economics toward multi-year service contracts with embedded hardware refresh rights.
For Market Incumbents: Fortify silicon photonics integration leadership through captive supply agreements with Taiwan-based foundry partners, insulating against allocation risk during 800G platform transitions. Deepen vertical integration into optical engine manufacturing to defend margin position against merchant silicon-based challengers. Prioritize certification investment for FIPS 140-2 and EU AI Act-aligned data residency controls to maintain pricing power in government and European financial services segments.
For New Entrants and Emerging Players: SaaS-delivered visibility for mid-market enterprises lacking specialized network engineering talent offers the most penetrable white-space, as incumbent hardware vendors under-serve operational expenditure preferences. Target healthcare providers migrating electronic health records to public cloud with HIPAA-aligned traffic inspection solutions. Pursue a Kubernetes-native go-to-market angle emphasizing policy orchestration automation against legacy chassis-based deployment friction.
For Investors and Strategic Acquirers: EU AI Act cross-border data routing mandates reshape the acquisition landscape by elevating European-hosted broker clusters with GDPR-aligned data residency above pure technology plays. Long-term viability favors vertically integrated specialists with optical switching expertise over disaggregated software vendors lacking hardware differentiation. Watch for Tier-1 carrier 400G chassis upgrade announcements as inflection indicators for silicon photonics demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Enables 400G forwarding at sub-microsecond latency for Northern Virginia hyperscale operators. |
| SaaS Platform Launch | Eliminates hardware lifecycle management overhead for mid-market enterprise procurement teams. |
| Edge Computing Extension | Distributes broker policies to 5G baseband units and industrial IoT gateways beyond centralized data centers. |
| GDPR-Aligned Data Residency | Positions European-hosted clusters for EU AI Act compliance and cross-border payment surveillance mandates. |
| Managed Security Service Expansion | Captures recurring revenue from policy orchestration outsourcing by talent-constrained enterprises. |
Methodological Framework
The analysis maps hardware chassis, software disaggregation, virtual appliances, and cloud services segments, each validated through network operations center directors, carrier procurement officers, and security operations center leads. Primary interviews with infrastructure architects at hyperscale operators and compliance officers at global systemically important banks combined with secondary validation against SEC 10-K filings, FCC proceeding dockets, and hyperscaler capex disclosures. Bottom-up port shipment estimates and top-down enterprise IT spending analysis triangulate market sizing across deployment modes.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product type, deployment mode, end-user sector, and use case workload intensity, with CAGRs derived from infrastructure refresh cycle timing and regulatory compliance deadline clustering. Forecast inputs incorporated silicon foundry capacity roadmaps and 5G transport network densification schedules without specifying implementation years.
Underlying assumptions cover carrier capital expenditure continuity and enterprise cloud migration velocity, with deviation risk concentrated in merchant silicon supply allocation disruptions and encryption visibility mandate enforcement timing. Practitioners should keep alternative scenarios live as FCC net neutrality restoration proceedings and EU AI Act implementation guidance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
WAN Optimization Controllers Market
Network Technology
2.4GHz Router Market
Network Technology
Mobile Backhaul Market
Network Technology
Global Network Monitoring Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
Germany Residential Gateway Market
Network Technology
Fiber to the Premises Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
ISP Management Systems Market
Network Technology
Global LWAN Market
Network Technology
Enterprise Routers Market
Network Technology
Digital Repeater Market
Network Technology
MENA Wireless Routers Market
Network Technology
Global Self-Organizing Network Market