
 Hyperconnectivity Market | 2026-2036
Hyperconnectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperconnectivity Market Intelligence
Enterprise manufacturing buyers is bifurcating from telecom-centric deployments toward private industrial networks. Samsung Electronics Co., Ltd. leverages its semiconductor foundry scale to dominate 5G baseband chip supply. Fujitsu Limited anchors Japanese enterprise demand through integrated optical-electronic switching platforms. Broadcom Inc. specializes in merchant silicon for programmable network fabrics serving both carrier and enterprise verticals.
Hyperconnectivity denotes the architectural state where devices, infrastructure, and services maintain persistent, low-latency data exchange through heterogeneous protocols including sub-1ms 5G NR, multi-access edge computing nodes, and AI-driven traffic orchestration. Its primary purpose is eliminating decision latency across distributed systems. The technology dimension shows 5G and edge computing commanding current infrastructure budgets while AI integration captures expanding margin pools through autonomous optimization. Application traction concentrates in smart cities and autonomous vehicles where municipal and automotive procurement cycles favor multi-year framework contracts over point solutions.
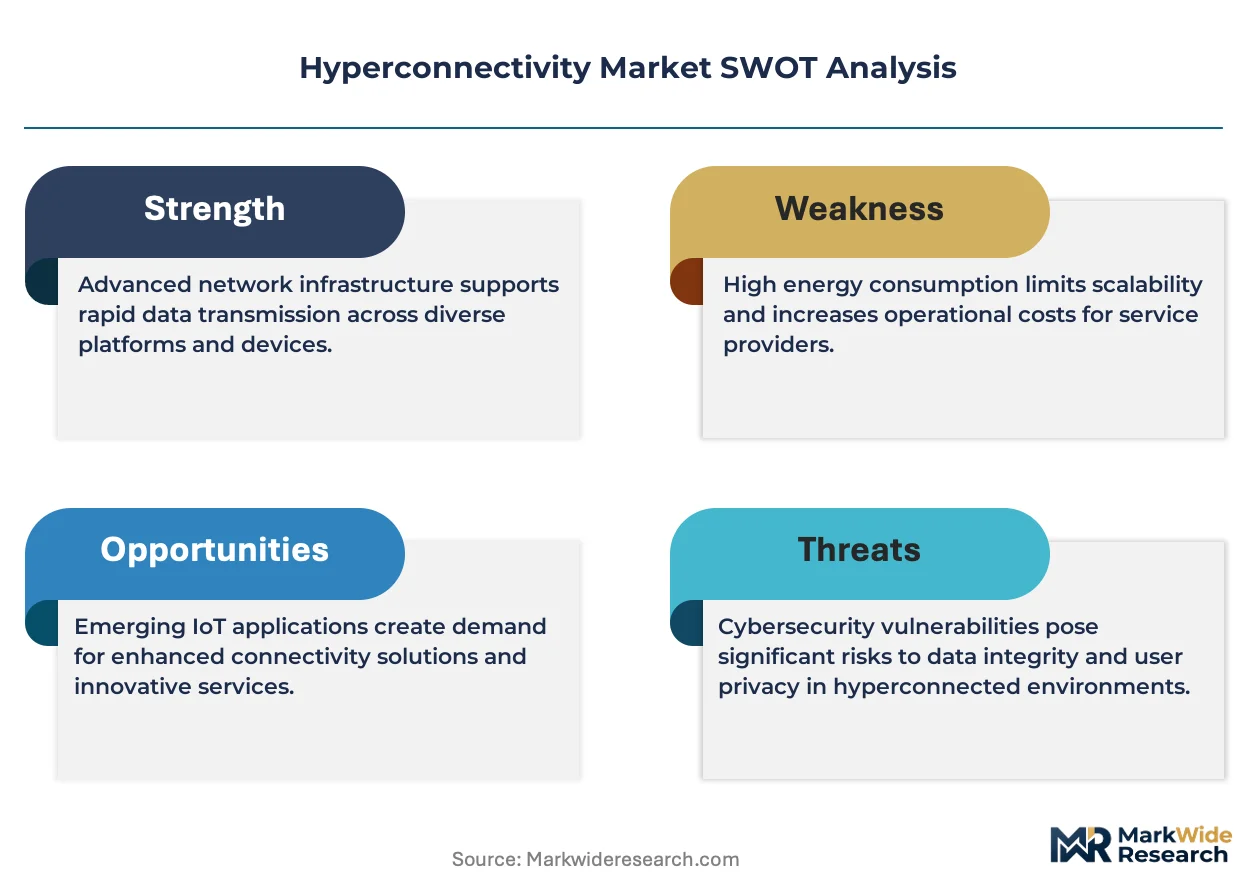
The FCC in the United States governs spectrum allocation for private 5G networks, directly conditioning where enterprises may deploy unlicensed or CBRS infrastructure. The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that reshape solution architecture across cloud and edge deployments. The EU Green Deal's digital-energy nexus standards further constrain power budgets for always-on connectivity hardware. Stakeholders must weigh spectrum sovereignty against interoperability costs when selecting regional deployment architectures.
Market Dynamics
Enterprise manufacturing buyers are abandoning legacy Ethernet for 5G private networks, creating a structural bifurcation where telecom-centric deployments lose ground to industrial-optimized infrastructure with sub-1ms latency requirements.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for edge-AI nodes are accelerating certified hardware procurement across German automotive OEM supply chains.
- Automotive predictive maintenance:Edge-AI deployment for real-time equipment monitoring is driving dense node installation in Stuttgart and Wolfsburg industrial corridors.
- CBRS spectrum liberalization:FCC unlicensed and lightly licensed band allocations are enabling private 5G deployment without carrier intermediation in US manufacturing facilities.
Market Restraints
- Baseband silicon concentration:Foundry capacity constraints for 5G NR chipsets create supply vulnerability tied to East Asian semiconductor fabrication.
- GDPR data residency friction:Cross-border edge computing architectures face architectural redesign costs to maintain EU citizen data within territorial boundaries.
- Optical-electronic switching integration:Hybrid photonic-electronic platform complexity extends qualification timelines for mission-critical industrial networks.
Strategic Opportunities
- EU Green Deal power budgeting:Always-on connectivity hardware faces mandatory efficiency standards, creating first-mover advantage for low-energy edge node designs.
- Smart city framework contracting:Municipal procurement cycles favoring multi-year integrated service agreements over point solutions open vendor consolidation paths.
- Multi-access edge computing convergence:5G NR and AI-driven traffic orchestration integration enables autonomous network optimization with minimal human intervention.
Industry Challenges
- Interoperability certification backlog:Vendor hardware must clear multiple national spectrum and safety regimes simultaneously, stretching engineering resources across FCC, CE marking, and BIS compliance tracks.
- Legacy Ethernet integration complexity:Brownfield manufacturing sites require protocol translation layers that introduce latency penalties conflicting with sub-1ms performance guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperconnectivity Market |
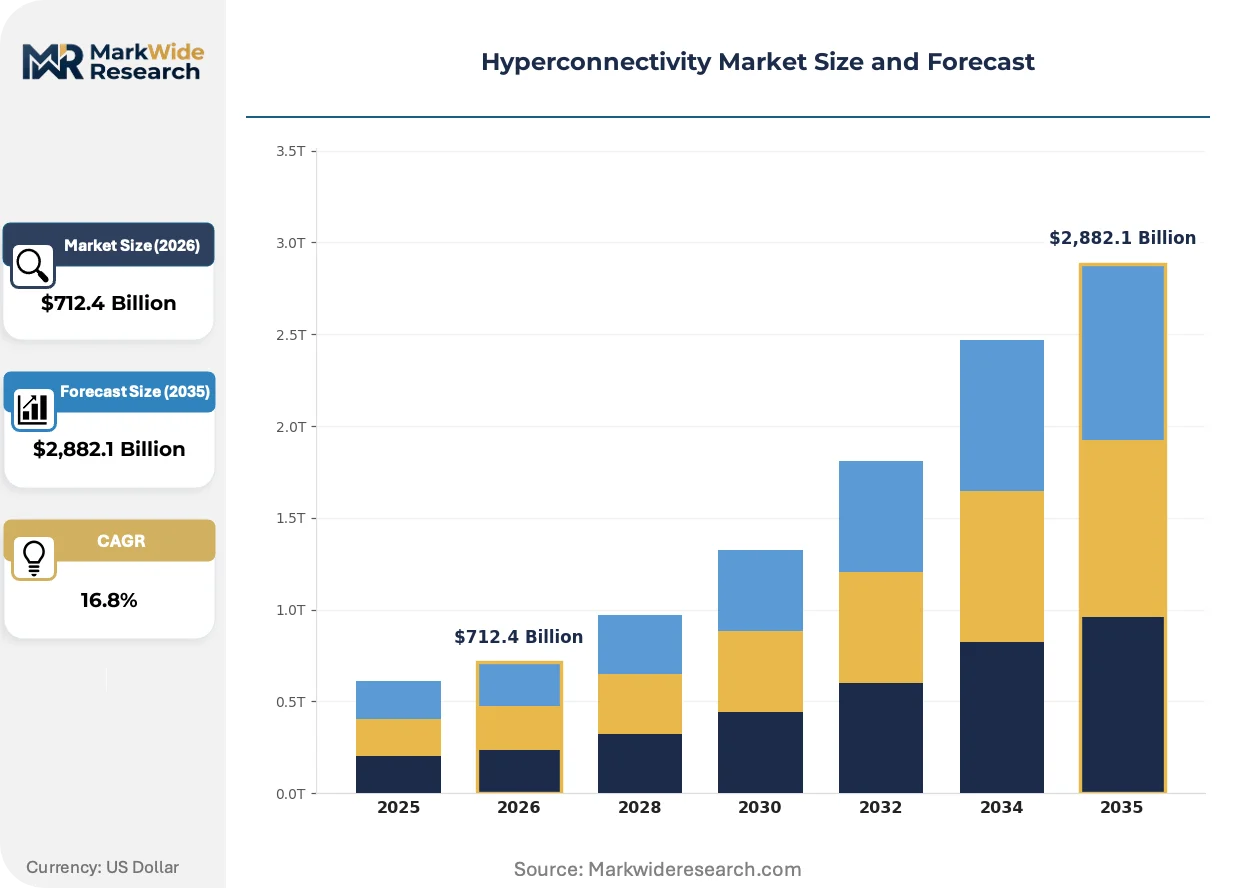
| Market Size in 2026 | $712.4 Billion |
| Market Size in 2035 | $2,882.1 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Cities, IoT Devices, Autonomous Vehicles, Wearable Technology Technology: 5G, Edge Computing, AI, Blockchain End User: Telecommunications, Automotive, Healthcare, Manufacturing Solution: Network Management, Data Analytics, Cybersecurity, Cloud Services |
| Companies Covered | Broadcom Inc., Extreme Networks, IBM Corporation, Samsung Electronics Co., Ltd., Fujitsu Limited, Microsoft, Avaya, Orange IT Solutions, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperconnectivity Market Strategic Shifts & Innovations
Network function virtualization is decomposing monolithic hardware stacks into software-defined components, enabling programmable infrastructure that adapts to workload-specific latency and bandwidth requirements without physical reconfiguration.
Optical switching platforms are decomposing traditional electronic packet processing for high-throughput industrial backbones. Japanese automotive suppliers and German machine builders are piloting photonic-electronic hybrid fabrics for factory-floor connectivity. This decomposition collapses power consumption and thermal management requirements for always-on edge nodes.
The EU AI Act's algorithmic transparency mandates are forcing edge-AI vendors to deploy explainable inference models with auditable decision trails. Industrial buyers in automotive and smart city verticals now require certified AI hardware before procurement approval. German OEMs are responding by pre-qualifying only vendors with EU-notified body certification, narrowing the supplier pool.
Buyer contracting patterns are consolidating around multi-year framework agreements with embedded service-level guarantees. Municipal smart city departments and automotive procurement offices are abandoning transactional hardware purchases for outcome-based connectivity subscriptions. This shift is most pronounced in Stuttgart, where regional utilities now bundle network infrastructure with energy management services.
Hyperconnectivity Market Segmentation
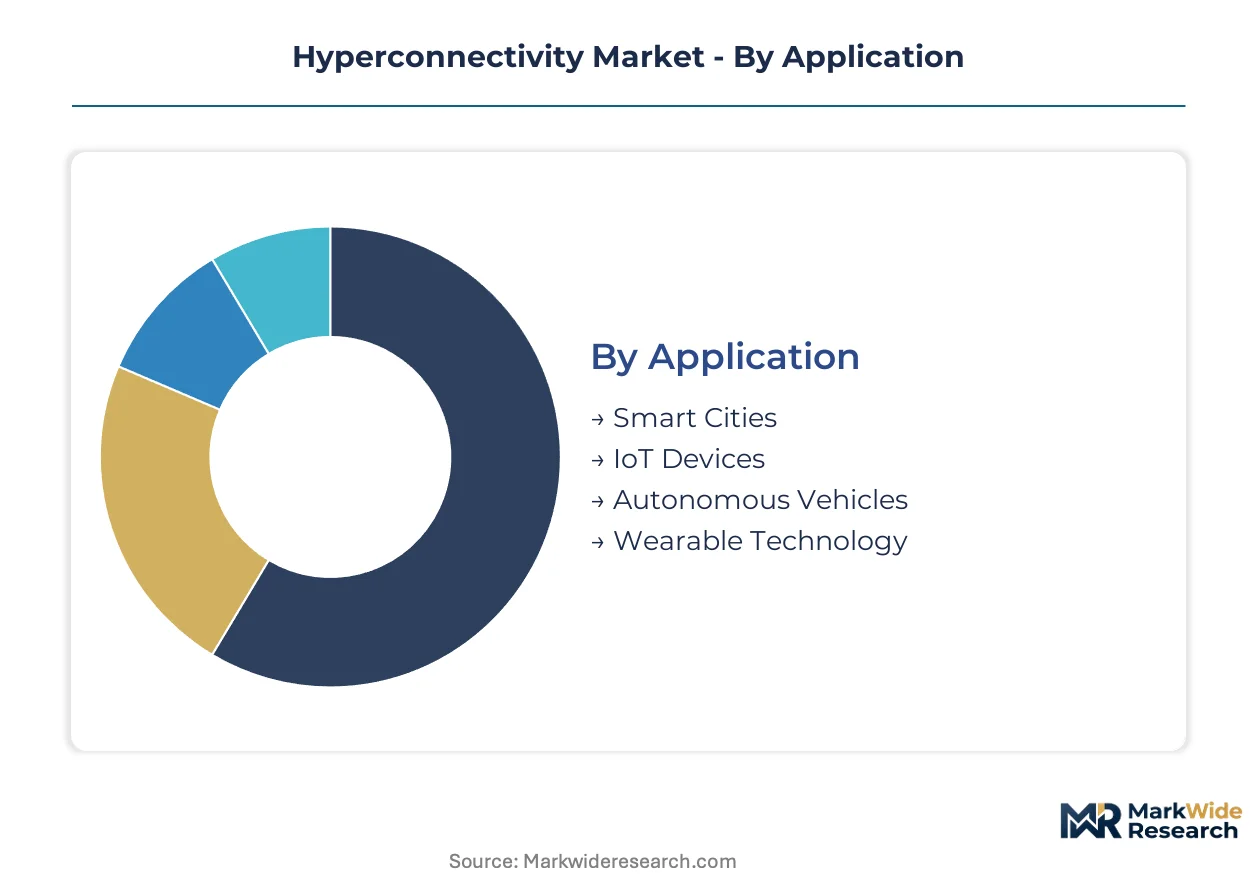
Hyperconnectivity architectures fragment across four intersecting dimensions where regulatory, technical, and procurement requirements diverge sharply. Application context dictates latency thresholds. Technology selection determines compliance pathways. End-user verticals impose distinct certification regimes. Solution bundling reflects contracting maturity.
Application:
GDPR data residency rules and EU AI Act algorithmic transparency mandates reshape deployment architectures differently across use cases.
- Smart Cities:Municipal infrastructure integrates multi-access edge computing with traffic, energy, and public safety systems. Stuttgart and Wolfsburg pilot programs require EU-notified body certification for AI-driven optimization layers, favoring vendors with pre-qualified hardware.
- IoT Devices:Dense sensor networks for industrial monitoring and environmental tracking operate under FCC Part 15 in the US and CE marking in Europe. German automotive OEMs demand sub-1ms latency guarantees for factory-floor deployments.
- Autonomous Vehicles:V2X communication stacks must clear NHTSA guidance in the US and UNECE WP.29 regulations in Europe simultaneously.
- Wearable Technology:Health-adjacent devices face FDA 510(k) pathways in the US and MDR conformity assessment in Europe.
Established volume favors Smart Cities; emerging adoption favors Autonomous Vehicles.
Technology:
Cost tier differentiation separates capital-intensive infrastructure from software-overlay investments.
- 5G:Private network deployments using CBRS in the US and licensed local spectrum in Germany displace legacy Ethernet in manufacturing. Baseband silicon supply concentrates in East Asian foundries, creating procurement vulnerability for European and North American integrators.
- Edge Computing:Multi-access edge nodes co-locate compute with 5G base stations to collapse latency for industrial automation. EU Green Deal power budgeting mandates favor low-energy designs from first-mover vendors.
- AI:Explainable inference models with auditable decision trails satisfy EU AI Act requirements for high-risk system categories.
- Blockchain:Distributed ledger applications for supply chain provenance remain niche outside pharmaceutical serialization mandates.
Deployment scale favors 5G; margin expansion favors Edge Computing.
End User:
Customer type determines procurement cycle length and service-level guarantee structure.
- Telecommunications:Carrier-grade infrastructure demands carrier aggregation and network slicing capabilities. Traditional telecom vendors face margin pressure from enterprise-direct private network competition.
- Automotive:German OEMs pre-qualify vendors based on EU AI Act certification status, narrowing supplier pools for edge-AI components. Predictive maintenance applications drive dense node installation in Stuttgart industrial corridors.
- Healthcare:HIPAA compliance in the US and GDPR health data provisions in Europe constrain cross-border edge architectures.
- Manufacturing:Brownfield sites require protocol translation layers that introduce latency penalties conflicting with sub-1ms performance requirements.
Contract value favors Telecommunications; certification urgency favors Automotive.
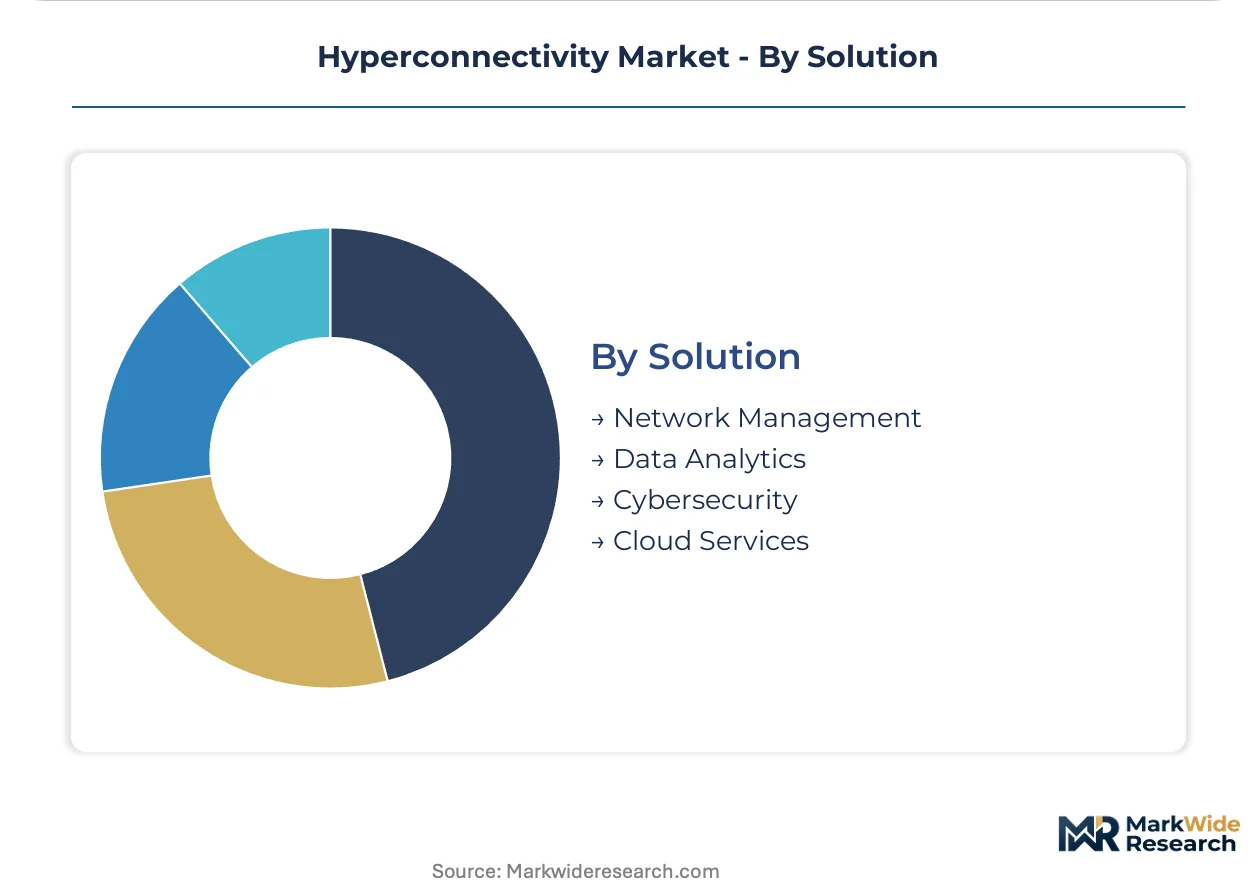
Solution:
Margin structure separates commodity connectivity from value-added orchestration layers.
- Network Management:Software-defined orchestration platforms enable autonomous traffic optimization with minimal human intervention. Municipal smart city departments favor multi-year framework agreements with embedded service-level guarantees over transactional hardware purchases.
- Data Analytics:Real-time stream processing at the edge supports predictive maintenance and quality control applications. German machine builders pilot photonic-electronic hybrid fabrics to collapse power consumption for always-on analytics nodes.
- Cybersecurity:Zero-trust architectures for distributed edge environments face interoperability certification backlog across FCC, CE marking, and BIS compliance tracks.
- Cloud Services:Hyperscaler edge extensions compete with carrier-neutral colocation for enterprise workload placement.
Recurring revenue favors Network Management; differentiation potential favors Data Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Cologne rail corridor underwrites Germany's industrial data exchange density, while the US CBRS spectrum allocation enables private 5G deployment without carrier intermediation. Japan's Kanto-Tokyo fiber ring anchors East Asian edge computing infrastructure.
United States
Automotive OEMs in Michigan and Ohio deploy private 5G networks for predictive maintenance. FCC CBRS spectrum rules enable unlicensed industrial deployment without carrier intermediation. Detroit-Warren industrial corridor hosts dense edge-AI node installation for real-time equipment monitoring.
Germany
Machine builders in Baden-Württemberg replace legacy Ethernet with sub-1ms latency private networks. EU AI Act mandates algorithmic transparency for edge-AI hardware certification. Stuttgart automotive cluster pre-qualifies vendors based on EU-notified body certification status.
Japan
Optical-electronic switching platforms serve precision manufacturing in Aichi Prefecture. METI standards govern industrial 5G spectrum allocation for factory automation. Nagoya-Toyota industrial belt pilots photonic-electronic hybrid fabrics for power-efficient connectivity.
South Korea
Semiconductor foundries in Gyeonggi Province drive baseband silicon demand for 5G NR chipsets. National 5G spectrum policy prioritizes industrial verticals over consumer applications. Seoul-Incheon metro anchors multi-access edge computing node deployment for smart manufacturing.
China
MIIT spectrum allocation shapes private 5G deployment in Yangtze River Delta manufacturing zones. GB standards compliance requirements constrain foreign vendor participation in critical infrastructure. Shanghai-Suzhou industrial corridor concentrates edge computing investment for automotive supply chains.
Hyperconnectivity Market Key Industry Players
Concentration sits with semiconductor foundry scale and integrated platform providers. The vendor base separates between chip-level suppliers, systems integrators, and software-overlay specialists. Three archetypes dominate: foundry-integrated silicon vendors, optical-electronic platform builders, and merchant silicon specialists. Competitive moves center on private network certification partnerships and edge-AI hardware pre-qualification with automotive OEMs.
Among Asia-Pacific-based electronics conglomerates, Samsung Electronics Co., Ltd. and Fujitsu Limited exemplify the integrated platform archetype, combining semiconductor or optical capabilities with systems-level deployment. Broadcom Inc. represents the merchant silicon specialist tier, supplying programmable network fabrics across carrier and enterprise verticals without captive manufacturing infrastructure.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Extreme Networks |
| IBM Corporation |
| Samsung Electronics Co., Ltd. |
| Fujitsu Limited |
| Microsoft |
| Avaya |
| Orange IT Solutions |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
Foundry-scale economies in East Asian semiconductor fabrication create asymmetric pricing power where 5G baseband silicon suppliers command premium positioning while downstream integrators face margin compression. This concentration simultaneously elevates price floors for certified edge-AI hardware and restricts supply flexibility for European and North American network deployers.
Pricing Analysis
Volume-discount tiering structures separate automotive OEM framework contracts from municipal smart city procurement, with three-tier pricing stratification across premium certified, standard compliant, and economy unverified hardware levels. EU AI Act certification status drives price differentiation between pre-qualified vendors and uncertified challengers, with algorithmic transparency mandates adding compliance premiums. Cost compression in economy-tier edge nodes is intensifying because merchant silicon vendors compete on programmable fabric density. Manufacturing buyers in Germany's industrial corridor show lowest price sensitivity due to latency-performance guarantees, while municipal smart city departments exhibit highest sensitivity favoring multi-year subscription bundling.
Supply Chain Analysis
Inventory lead times for 5G NR chipsets extend qualification timelines as foundry capacity constraints in Taiwan, South Korea, and China create procurement bottlenecks for European integrators. Raw material dependencies center on advanced node silicon wafers, compound semiconductor substrates, and rare-earth magnet components for optical-electronic switching platforms. Single-source vulnerability concentrates in East Asian semiconductor fabrication where geopolitical friction threatens supply continuity. Distribution runs through carrier-neutral colocation facilities and direct enterprise channels, with automotive OEMs increasingly procuring through pre-qualified vendor pools to bypass traditional telecom intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperconnectivity represents a high-growth infrastructure disruption where private 5G networks displace legacy Ethernet, accelerated by EU AI Act compliance mandates reshaping vendor certification pathways.
For Market Incumbents: Fortify market position through captive foundry partnerships or long-term capacity agreements that secure baseband silicon supply against East Asian concentration risk. Deepen backward integration into optical-electronic switching platforms to capture EU Green Deal efficiency premiums. Prioritize EU-notified body certification investment to maintain automotive OEM pre-qualification status as German machine builders narrow supplier pools. For New Entrants and Emerging Players: Anchor in municipal smart city framework contracting where outcome-based connectivity subscriptions displace transactional hardware purchases, creating white-space for software-overlay specialists. Target brownfield manufacturing protocol translation as the most penetrable segment where latency penalties create demand for innovative edge-AI integration. Pursue carrier-neutral colocation partnerships as the primary go-to-market angle to bypass entrenched telecom vendor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors merchant silicon specialists with programmable network fabric capabilities and optical-electronic platform builders serving precision manufacturing verticals. Long-term viability across the 5-10 year window rests on vendors capturing edge-AI hardware certification moats before automotive procurement consolidation completes. Watch FCC CBRS spectrum allocation expansion and EU AI Act enforcement intensity as dual inflection indicators for private network deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Algorithmic transparency mandates from Brussels reshape automotive OEM procurement pre-qualification requirements. |
| Optical-Electronic Platform Integration | Hybrid photonic fabrics collapse power consumption for always-on edge nodes under EU Green Deal constraints. |
| Private 5G Spectrum Partnership | FCC CBRS and German licensed local spectrum access enable carrier-bypass deployment for manufacturing verticals. |
| Multi-Access Edge Computing Convergence | 5G NR and AI-driven orchestration integration enables autonomous network optimization with minimal human intervention. |
| Framework Contracting Consolidation | Municipal smart city departments in Stuttgart favor multi-year integrated service agreements over point solutions. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with network infrastructure executives, automotive procurement officers, municipal smart city directors, and semiconductor supply chain managers; and secondary validation through SEC filings, hyperscaler capex disclosures, FCC spectrum allocation records, and EU regulatory filings. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against infrastructure investment flows ensured cross-verification.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning application context, technology layer, end-user vertical, and solution bundling structure, with CAGRs derived from installed base progression and replacement cycle dynamics. Edge-AI node density projections and private 5G spectrum license trajectories served as industry-specific forecast inputs.
Material uncertainties — semiconductor foundry capacity constraints, EU AI Act enforcement calibration, and CBRS spectrum allocation timing — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
North America Structured Cabling Market
Network Technology
Network Packet Broker Market
Network Technology
Network Management Solutions Market
Network Technology
5G CPE Device Market
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
MENA Wireless Routers Market
Network Technology
Germany Residential Gateway Market
Network Technology
Passive Optical LAN (POL) Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
ISP Management Systems Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Mobile Backhaul Market
Network Technology
Carrier Routing Equipment Market
Network Technology
Digital Repeater Market
Network Technology
Microduct Market