
 Europe Structured Cabling Market | 2026-2036
Europe Structured Cabling Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Structured Cabling Market Foresight
Market Context
France is tilting toward higher-grade copper and fiber production to serve continental data center build-outs. CommScope Holding Company, Inc. leverages its European distribution hubs to shorten lead times for hyperscale contractors. Schneider Electric SE anchors its position through integrated power-and-cabling bundles that reduce installation complexity. Nexans competes on specialized fire-resistant jacketing that meets French and German building codes.
Technical Definition and Segment Structure
Europe Structured Cabling comprises the standardized physical layer infrastructure—twisted-pair copper cables, optical fiber assemblies, connecting hardware, and patch panels—that transmits voice, data, and video signals across commercial and industrial premises, typically engineered to ISO/IEC 11801 and EN 50173 performance tiers. Fiber optic segments lead value contribution as 400G and 800G switch-to-switch links displace copper backbones in new data center construction. Copper persists in horizontal distribution where Power over Ethernet drives single-cable topologies for smart building endpoints. Installation type skews toward retrofit and upgrades across aging commercial stock in Northern Europe, while Southern Europe tilts toward new construction tied to logistics and manufacturing greenfield projects.
Regulatory Frame and Outlook
CE marking under the Construction Products Regulation, EU Green Deal energy efficiency benchmarks, and national implementations of the Energy Performance of Buildings Directive shape material selection and flame-retardant specifications. ECHA REACH restrictions on halogenated flame retardants are forcing compound reformulation across cable jacket suppliers. Stakeholders must monitor how the EU AI Act's infrastructure transparency requirements interact with physical layer documentation standards to determine compliance investment priorities.
Market Dynamics
The EU Green Deal is compressing copper-to-fiber migration timelines as data center operators in Frankfurt and Paris race to provision AI-ready infrastructure before connectivity bottlenecks materialize.
Growth Catalysts
- Energy Efficiency Directive mandates:Revised EU building codes are accelerating retrofit cycles across Northern European commercial stock, forcing landlords to replace aging Category 5e with fiber-grade infrastructure.
- Hyperscale data center clustering:Frankfurt-Rhine-Main corridor operators are pre-leasing dark fiber capacity three years ahead of server deployment, pulling forward structured cabling demand.
- Power over Ethernet proliferation:Smart building endpoints—LED lighting, access control, environmental sensors—are consolidating onto single-cable topologies that favor higher-grade copper and hybrid fiber-copper architectures.
Market Restraints
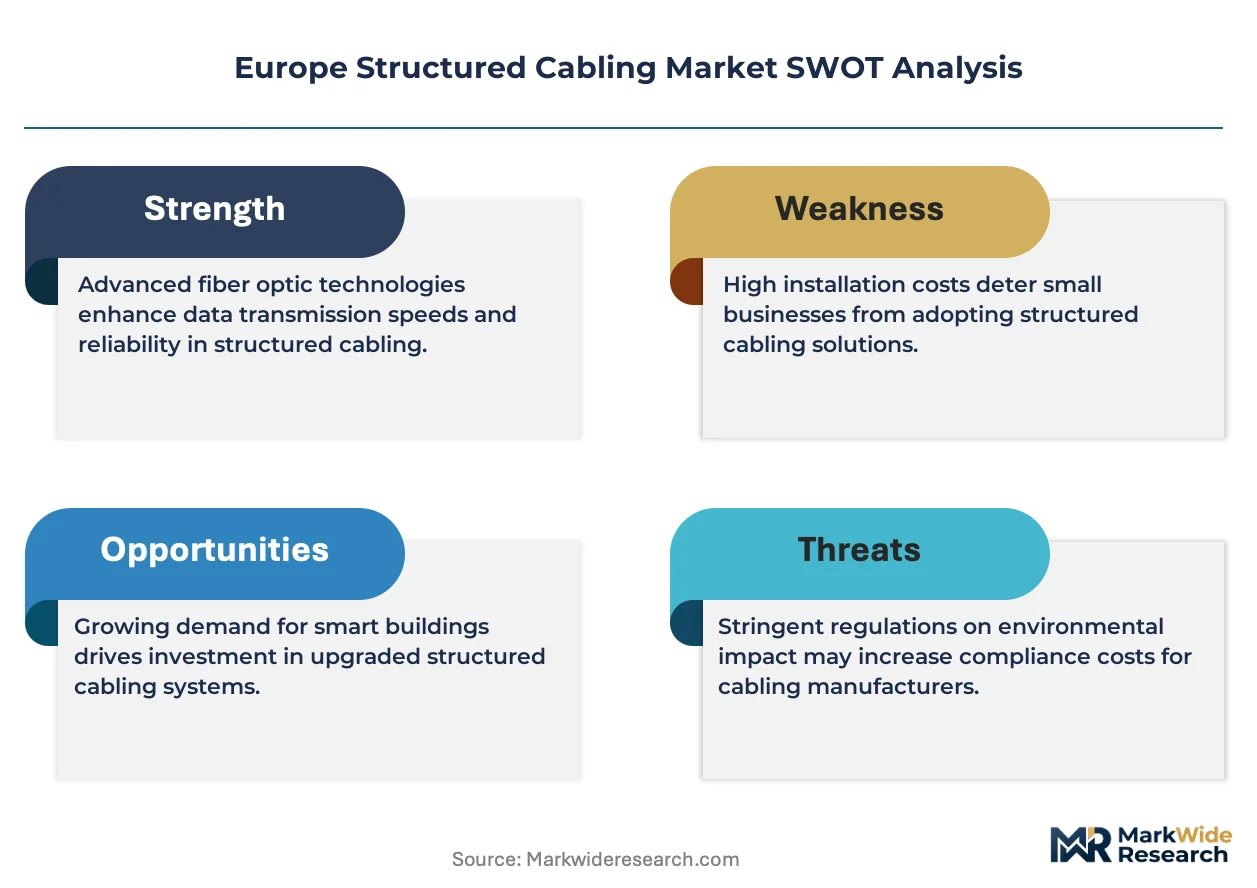
- Halogenated compound phase-out:ECHA REACH restrictions on legacy flame retardants are forcing jacket reformulation, extending compound qualification timelines by 8-12 months for cable suppliers.
- Optical fiber feedstock concentration:Preform and draw tower capacity concentrates in Asian manufacturing bases, exposing European installers to ocean freight volatility and extended lead times.
- Copper backbone substitution:400G switch-to-switch links are rendering Category 8 copper solutions economically unviable for new data center construction, stranding R&D investments.
Strategic Opportunities
- Polish logistics corridor build-outs:Greenfield distribution centers near Łódź and Wrocław are specifying pre-terminated fiber assemblies for automated material handling systems.
- Integrated power-cabling bundles:Converged physical layer and electrical distribution designs are reducing installation labor hours by 30-40% in German industrial retrofits.
- EU AI Act infrastructure documentation:Transparency requirements for high-risk AI systems are creating audit-grade cable labeling and traceability service revenue streams.
Industry Challenges
- BICSI-certified technician scarcity:Installer certification backlogs in France and Germany are extending project commissioning timelines by 6-10 weeks during peak construction seasons.
- Legacy building penetration:Concrete core drilling restrictions in Paris and Milan historic districts are forcing micro-duct and blown-fiber techniques that demand specialized tooling investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Structured Cabling Market |
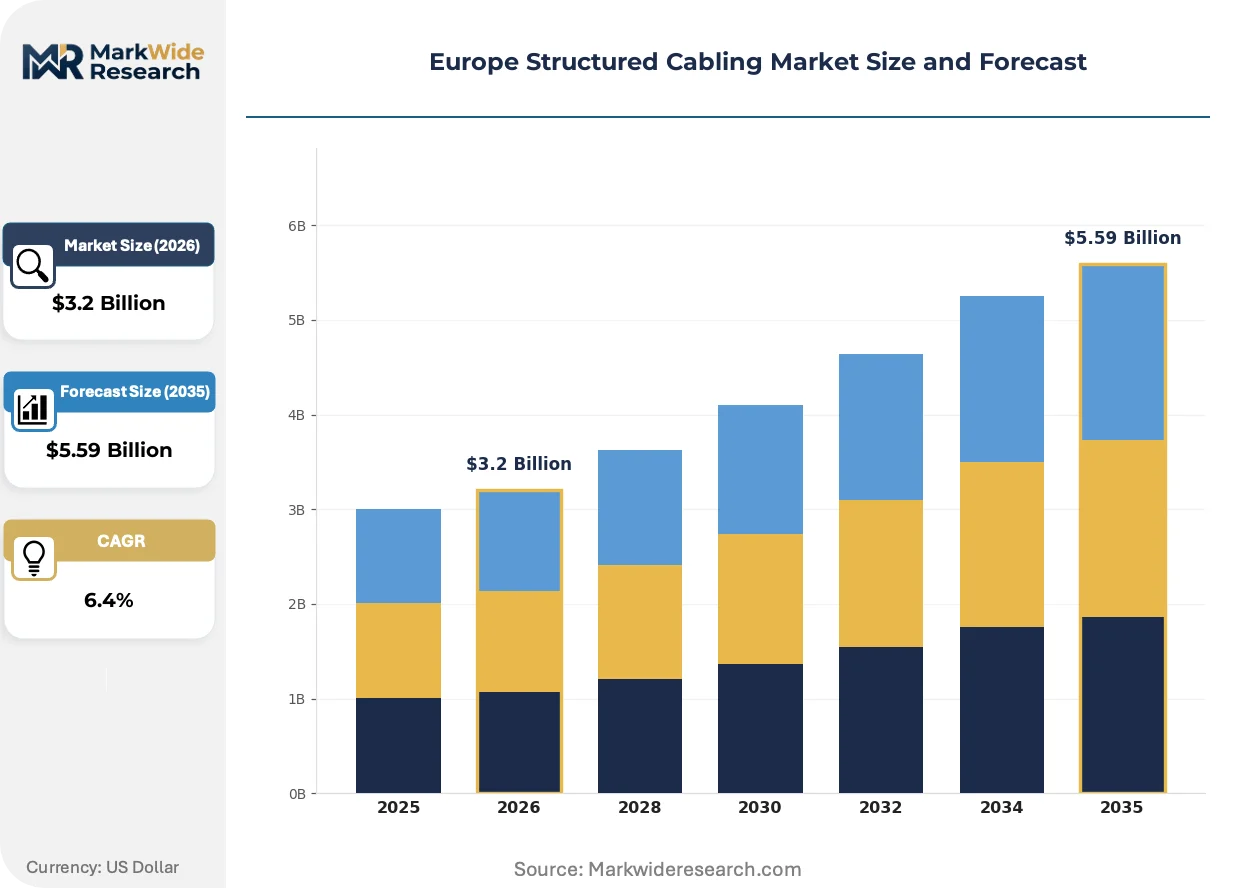
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic, Copper, Patch Panels, Connectors Installation Type: New Construction, Retrofit, Expansion, Upgrades End User: Commercial, Residential, Industrial, Data Centers Technology: Ethernet, Power over Ethernet, PoE++, 10GBASE-T |
| Companies Covered | Belden Inc., CommScope Holding Company, Inc., Corning Incorporated, Schneider Electric SE, Legrand SA, Nexans, Prysmian, Datwyler IT Infra GmbH, The Siemon Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Structured Cabling Market Shifts & Advancements
Physical layer infrastructure is fragmenting into application-specific performance tiers as AI workloads and building automation impose divergent latency, power, and thermal constraints on cable selection.
Single-mode fiber is hybridizing with copper Power over Ethernet in horizontal distribution zones. Data center operators in Amsterdam and Frankfurt are deploying composite cable assemblies that carry 90W PoE++ alongside single-fiber links to edge compute nodes. This convergence is compressing rack-cable counts by 40% while complicating pathway fill calculations for facilities engineers.
CE marking under the Construction Products Regulation now requires extended fire-reaction testing for cables installed in high-rise residential towers. French and German regulators are enforcing smoke density and toxicity thresholds that disqualify legacy PVC-jacketed products from new construction. Jacket compound suppliers are accelerating silicone and low-smoke zero-halogen formulations to maintain market access.
Buying committees at hyperscale tenants are consolidating vendor panels to three approved structured cabling suppliers per region. Procurement teams in Frankfurt and Dublin are demanding 10-year performance warranties and embedded installation services rather than component-only transactions. This concentration is squeezing mid-tier distributors and favoring vertically integrated manufacturers with captive installation labor pools.
Europe Structured Cabling Market Segmentation
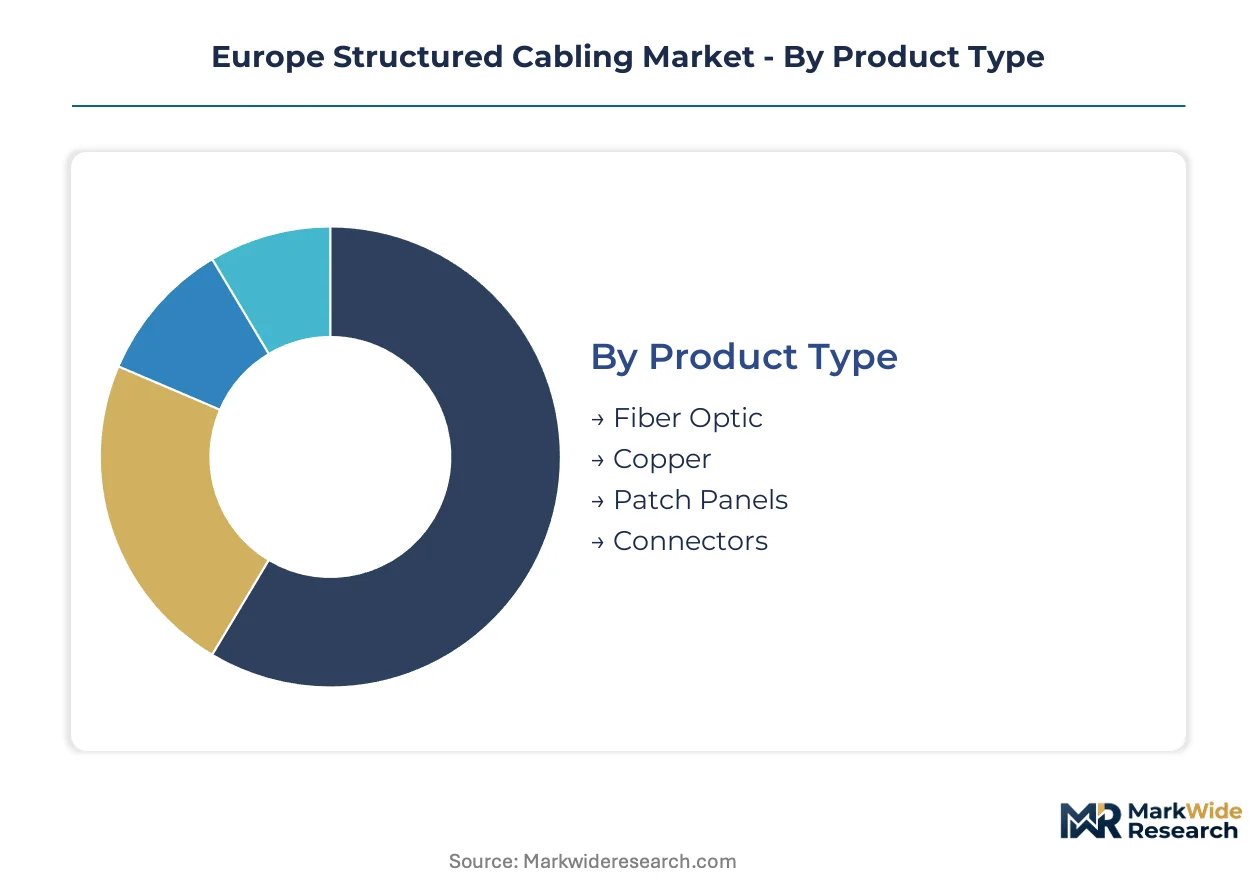
Structured cabling procurement in Europe fragments across physical layer technologies, deployment contexts, and performance requirements. Each dimension carries distinct specification standards, certification burdens, and margin structures that reshape competitive positioning across the value chain.
Product Type:
Material composition determines fire-reaction classification, bandwidth headroom, and installation labor intensity across European building codes.
- Fiber Optic:Single-mode and multimode assemblies engineered to OS2 and OM4/OM5 standards carry 400G switch-to-switch traffic in Frankfurt and Amsterdam hyperscale facilities. German data center operators are pre-ordering MPO-16 trunk cables eighteen months ahead of server deployment to lock in supply.
- Copper:Twisted-pair Category 6A and Category 8 solutions retain horizontal distribution roles where PoE++ delivers 90W to smart building endpoints. French commercial retrofits specify shielded copper for electromagnetic compatibility in dense urban cores.
- Patch Panels:Modular fiber distribution frames and copper punch-down blocks consolidate cross-connect points in telecommunications rooms.
- Connectors:LC duplex, MPO, and RJ45 modular plugs terminate cable assemblies with factory-polished or field-installable variants.
Fiber optic holds installed capacity. Copper is rotating up the share rankings in smart building horizontal zones.
Installation Type:
Deployment context shapes pathway engineering, disruption tolerance, and regulatory compliance sequencing.
- New Construction:Greenfield sites in Poland and Spain specify pre-terminated fiber assemblies with pull-tested load ratings for automated logistics centers. Integrated design-build contracts bundle structured cabling with electrical and HVAC scopes.
- Retrofit:Aging commercial stock across Northern Europe demands micro-duct and blown-fiber techniques where concrete core drilling faces heritage preservation restrictions. Paris and Milan historic districts impose 48-hour work windows that compress labor productivity.
- Expansion:Phased data center builds add structured cabling capacity in 500-rack increments to match power provisioning timelines.
- Upgrades:Category 5e-to-6A replacements in German office towers accelerate under Energy Efficiency Directive retrofit mandates.
New construction captures the steepest expansion trajectory. Retrofit commands the largest absolute project volume.
End User:
Customer archetypes impose divergent latency, density, and documentation requirements on physical layer specifications.
- Data Centers:Hyperscale tenants in the Frankfurt-Rhine-Main corridor specify single-mode fiber for 800G-ready spine-leaf architectures with 10-year performance warranties. Procurement teams consolidate vendor panels to three approved suppliers per region.
- Commercial:Multi-tenant office buildings across France and Germany deploy hybrid fiber-copper topologies supporting converged IP networks for access control, environmental monitoring, and LED lighting.
- Industrial:Manufacturing facilities near Stuttgart and Turin specify armored fiber and industrial-grade copper for electromagnetic immunity in automated production environments.
- Residential:High-rise towers in Madrid and Barcelona require extended fire-reaction testing under revised Construction Products Regulation CE marking protocols.
Data centers concentrate premium fiber demand. Commercial buildings distribute volume across copper and hybrid architectures.
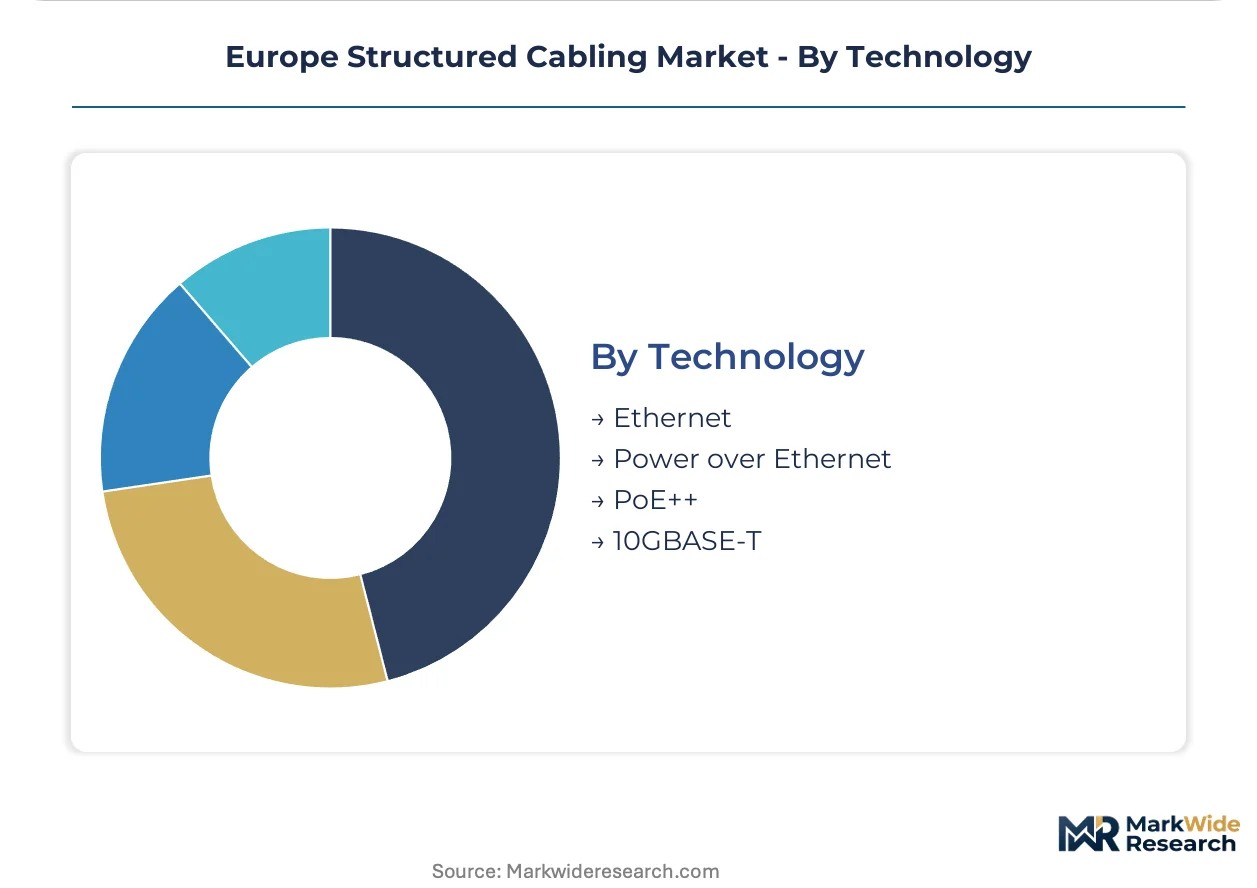
Technology:
Protocol standards determine cable performance tiers, power delivery capacity, and switch compatibility matrices.
- Power over Ethernet:90W PoE++ enables single-cable topologies for pan-tilt-zoom cameras, digital signage, and wireless access points across smart building deployments. Composite cable assemblies carrying PoE alongside single-fiber links compress rack-cable counts by 40% in Amsterdam edge compute nodes.
- Ethernet:10GBASE-T and 25GBASE-T copper standards retain relevance in server access layers where fiber cost premiums face procurement scrutiny.
- PoE++:Enhanced power sourcing equipment specifications support high-draw endpoints without separate electrical circuits.
- 10GBASE-T:Twisted-pair copper standard for 10 Gbps transmission over 100-meter channels in enterprise LAN environments.
Power over Ethernet anchors horizontal distribution specifications. Ethernet fiber variants are climbing the fastest in data center spine layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Preform and draw tower capacity concentrates in Asian manufacturing bases, exposing European installers to ocean freight volatility. Installer certification backlogs in France and Germany are extending project commissioning timelines by 6-10 weeks during peak construction seasons.
Germany
Hyperscale operators in the Frankfurt-Rhine-Main corridor are pre-leasing dark fiber capacity three years ahead of server deployment. The Energy Efficiency Directive accelerates Category 5e-to-6A replacements in office towers. Stuttgart manufacturing facilities specify armored fiber for electromagnetic immunity in automated production environments.
France
Commercial retrofits in dense urban cores specify shielded copper for electromagnetic compatibility. ECHA REACH restrictions on halogenated flame retardants force jacket reformulation across cable suppliers. Paris historic districts impose 48-hour work windows that compress labor productivity for micro-duct installations.
United Kingdom
Data center builds in Slough and London add structured cabling capacity in 500-rack increments to match power provisioning timelines. CE marking under the Construction Products Regulation shapes material selection for high-rise residential towers. Procurement teams in London are consolidating vendor panels to three approved suppliers per region.
Netherlands
Amsterdam edge compute nodes deploy composite cable assemblies carrying 90W PoE++ alongside single-fiber links. The EU Green Deal energy efficiency benchmarks accelerate copper-to-fiber migration timelines. Rotterdam logistics hubs specify pre-terminated fiber assemblies with pull-tested load ratings for automated systems.
Poland
Greenfield distribution centers near Łódź and Wrocław specify pre-terminated fiber assemblies for automated material handling systems. New construction captures the steepest expansion trajectory across the region. Integrated design-build contracts bundle structured cabling with electrical and HVAC scopes.
Europe Structured Cabling Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base organizes around three strategic archetypes: vertically integrated manufacturers with captive installation labor pools, specialized jacket compound suppliers competing on fire-reaction certification, and distribution-focused intermediaries shortening lead times for hyperscale contractors. Consolidation pressures favor players bundling power and cabling infrastructure. Procurement teams now demand 10-year performance warranties rather than component-only transactions.
Among European-headquartered conglomerates, Schneider Electric SE and Legrand SA exemplify the integrated power-cabling bundle archetype that reduces installation complexity. Nexans occupies a position within the specialized cable manufacturing tier, competing on fire-resistant jacketing that meets French and German building codes. Corning Incorporated represents the optical fiber feedstock concentration that shapes European supply security calculations.
| Leading Market Players |
|---|
| Belden Inc. |
| CommScope Holding Company, Inc. |
| Corning Incorporated |
| Schneider Electric SE |
| Legrand SA |
| Nexans |
| Prysmian |
| Datwyler IT Infra GmbH |
| The Siemon Company |
| Others |
Supply & Pricing Matrix
Rotterdam-to-Frankfurt freight corridors transmit optical fiber preform cost volatility directly into German data center contractor pricing, amplifying the spread between CE-marked premium assemblies and standard-grade copper products as ECHA REACH compliance timelines extend compound qualification cycles.
Pricing Analysis
CE marking under the Construction Products Regulation dictates the pricing tier structure across European structured cabling procurement. Three-tier pricing stratifies across plenum-rated premium fiber, standard LSZH-jacketed copper, and economy-grade PVC alternatives still permitted in select Southern European jurisdictions. Cost compression in standard-grade copper runs through aggressive volume bundling by vertically integrated manufacturers with captive installation labor pools. Hyperscale data center operators exhibit the lowest price sensitivity due to 10-year performance warranty requirements, while French commercial retrofit contractors face acute margin pressure from compressed 48-hour work windows in Paris historic districts.
Supply Chain Analysis
Export control regimes on semiconductor manufacturing equipment indirectly constrain European fiber draw tower capacity expansion by limiting access to precision furnace components and process control systems. Preform and draw tower manufacturing concentrates in China, the United States, and Japan, drawing from high-purity silicon tetrachloride feedstock and specialized germanium-doping compounds. Single-source vulnerability in Asian optical fiber substrate production exposes Frankfurt and Amsterdam installers to ocean freight rate volatility and extended replenishment cycles. Distribution runs through authorized distributor networks serving hyperscale contractors with just-in-time pre-terminated assembly programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless 5G private networks and free-space optical links constitute an emerging substitution threat that structured cabling incumbents must neutralize through performance differentiation and installation service bundling.
For Market Incumbents: Insulate fiber backbone revenue by accelerating backward integration into preform supply partnerships that bypass Asian manufacturing concentration risks. Deepen captive installation labor pools in the Frankfurt-Rhine-Main corridor to lock out mid-tier distributors from hyperscale vendor panels. Counter wireless substitution threats with guaranteed latency SLAs on physical layer deployments that free-space optical cannot match in dense urban cores. For New Entrants and Emerging Players: Polish logistics corridors near Łódź and Wrocław offer underpenetrated greenfield specification opportunities where integrated design-build contracts remain unconsolidated. Target armored fiber segments for Stuttgart manufacturing automation environments where electromagnetic immunity requirements exceed standard product capabilities. Pursue fire-resistant jacket compound specialization as ECHA REACH restrictions disqualify legacy suppliers from French and German commercial retrofits. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with captive installation labor pools and CE marking certification depth. Long-term viability hinges on exposure to data center fiber spine-layer demand rather than copper horizontal distribution facing Power over Ethernet saturation. Monitor hyperscale vendor panel consolidation velocity as the inflection signal—three-supplier regional limits will extinguish mid-tier distributor margins and trigger acquisition premiums for qualified installation service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Supply | Reduces exposure to Asian draw tower concentration and ocean freight volatility for Frankfurt contractors. |
| CE Marking Certification Expansion | Unlocks French high-rise residential construction where smoke density thresholds disqualify legacy PVC suppliers. |
| Captive Installation Labor Pool Buildout | Secures vendor panel positioning as hyperscale procurement teams consolidate to three approved suppliers per region. |
| Fire-Resistant Compound R&D Investment | Addresses ECHA REACH halogenated flame retardant phase-out forcing 8-12 month qualification timeline extensions. |
| Composite Cable Assembly Development | Captures Amsterdam edge compute demand for PoE++ and single-fiber convergence compressing rack-cable counts. |
Research Methodology
Operator-level perspectives from data center infrastructure directors, BICSI-certified installation contractors, French and German building code inspectors, and hyperscale procurement managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through ECHA REACH regulatory filings, EU Construction Products Regulation technical documentation, customs trade data on optical fiber preform imports, and SEC disclosures from listed cable manufacturers. Bottom-up project pipeline analysis across Frankfurt-Rhine-Main, Paris, and Amsterdam markets triangulated against top-down macroeconomic indicators.
Scenario-bracketing framed low, base, and high cases across the projection horizon without discrete year anchoring. Segmentation modeling incorporated product type, installation context, end-user archetype, and technology protocol dimensions. CAGRs derived from fitted growth curves applied to disclosed hyperscale pre-leasing timelines and Energy Efficiency Directive retrofit mandates. Forecast inputs included BICSI technician certification backlog durations, ECHA compound qualification cycle extensions, and pre-terminated fiber assembly lead time distributions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian fiber substrate manufacturers establishing European draw tower joint ventures would shift outcomes. Material shifts in EU AI Act infrastructure transparency enforcement or accelerated REACH restriction timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
CPE Router Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Private Network Services Market
Network Technology
North America Structured Cabling Market
Network Technology
Microduct Market
Network Technology
Global Network Switches Market
Network Technology
5G CPE Device Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
Dark Fiber Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Europe SD-WAN Market
Network Technology
Wi-Fi Router Market
Network Technology
Enterprise Routers Market
Network Technology
Global Network Monitoring Market
Network Technology
Mobile Network Optimization Market
Network Technology
Netops Market