
 DIY Furnitures Market | 2026-2036
DIY Furnitures Market Size, Share, and Industry Trends Forecast 2026-2036
DIY Furnitures Market Analysis
Flat-pack engineering and parametric design software is reshaping how DIY furniture is manufactured, distributed, and assembled by end users. IKEA leverages its captive supply of engineered wood and global store footprint to dominate accessible flat-pack segments. Herman Miller anchors premium ergonomic DIY kits through controlled direct-to-consumer channels. Ashley Furniture Industries sustains manufacturing scale across mid-market wood and composite lines.
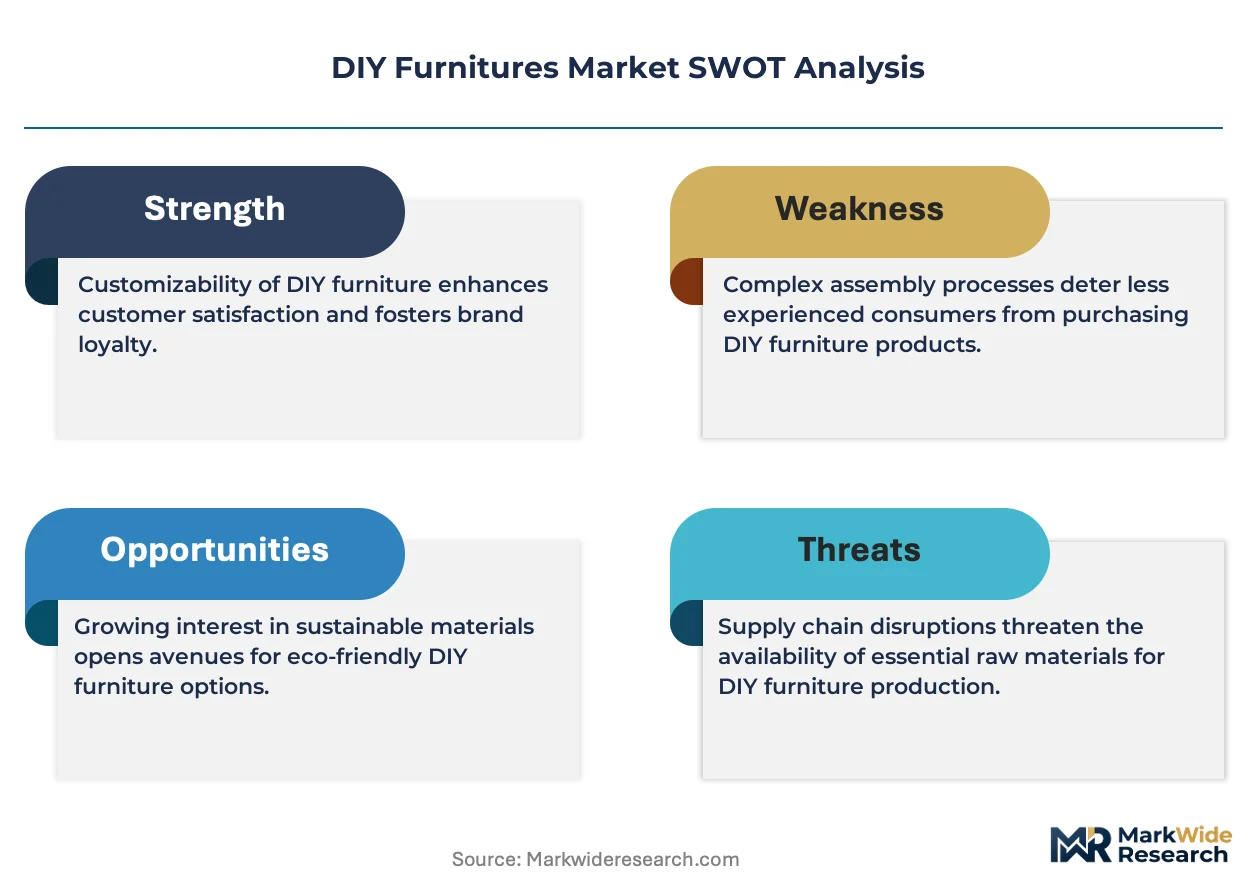
DIY furniture comprises ready-to-assemble units shipped in kit form, typically using cam-lock fasteners, dowel joints, or bracket systems with particleboard, MDF, or solid wood substrates, designed for consumer assembly without specialized tools. The product category serves cost-conscious households, rental property managers, and hobbyist makers seeking customizable spatial solutions. Wood material lines command the deepest margin pools due to sustainability premiums and certification complexity, while composite segments compete on price-driven volume in student and first-apartment demographics. Modern and minimalist style categories are capturing growing share among urban professionals prioritizing space efficiency.
EPA TSCA Title VI formaldehyde emission standards and California Air Resources Board Phase II requirements govern composite wood products sold in the United States, compelling manufacturers to certify supply chains or pivot to solid wood alternatives. The EU Ecodesign Directive and REACH chemical restrictions shape material choices and finishing processes for European market access. Stakeholders must monitor evolving extended producer responsibility frameworks and carbon border adjustments that will redefine cost structures for cross-border kit furniture sourcing.
Market Dynamics
Flat-pack engineering is forcing a fundamental restructuring of how DIY furniture reaches end users, compressing logistics costs while elevating assembly complexity as the primary customer friction point. This tension between distribution efficiency and user experience defines competitive positioning across all price tiers.
Growth Catalysts
- CARB Phase II compliance:California's formaldehyde emission standards for composite wood products are accelerating certified supply chain investments among manufacturers serving North American markets.
- Rental housing density:Urban millennials in Germany, Japan, and the United States are prioritizing disassemblable furniture for frequent relocation cycles.
- Parametric design software:CAD-to-cut workflows are reducing prototype-to-production timelines for customized flat-pack configurations.
Market Restraints
- Engineered wood input volatility:Particleboard and MDF substrate costs fluctuate with resin and timber feedstock markets, squeezing margin predictability for volume producers.
- Chinese manufacturing concentration:Cam-lock fastener and bracket hardware sourcing remains heavily dependent on Zhejiang and Guangdong province suppliers.
- Dimensional accuracy limits:CNC tolerance stacking in multi-panel kits creates assembly failure rates that erode brand trust in entry-tier segments.
Strategic Opportunities
- India urban housing:Tier-2 city apartment construction is outpacing furnished unit supply, creating white space for localized flat-pack distribution partnerships.
- EU Ecodesign Directive:Repairability and recyclability mandates are opening premium positioning for solid wood kit manufacturers with circular economy certification.
- Augmented reality assembly:AR-guided build apps are hybridizing with physical kits to reduce return rates and expand the non-handy buyer demographic.
Industry Challenges
- CAD-to-factory translation:Furniture designers lack manufacturing engineering expertise, creating specification gaps between digital models and producible components.
- Multi-jurisdiction certification:Simultaneous EPA TSCA Title VI, CARB Phase II, and EU REACH compliance requires parallel testing protocols that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DIY Furnitures Market |
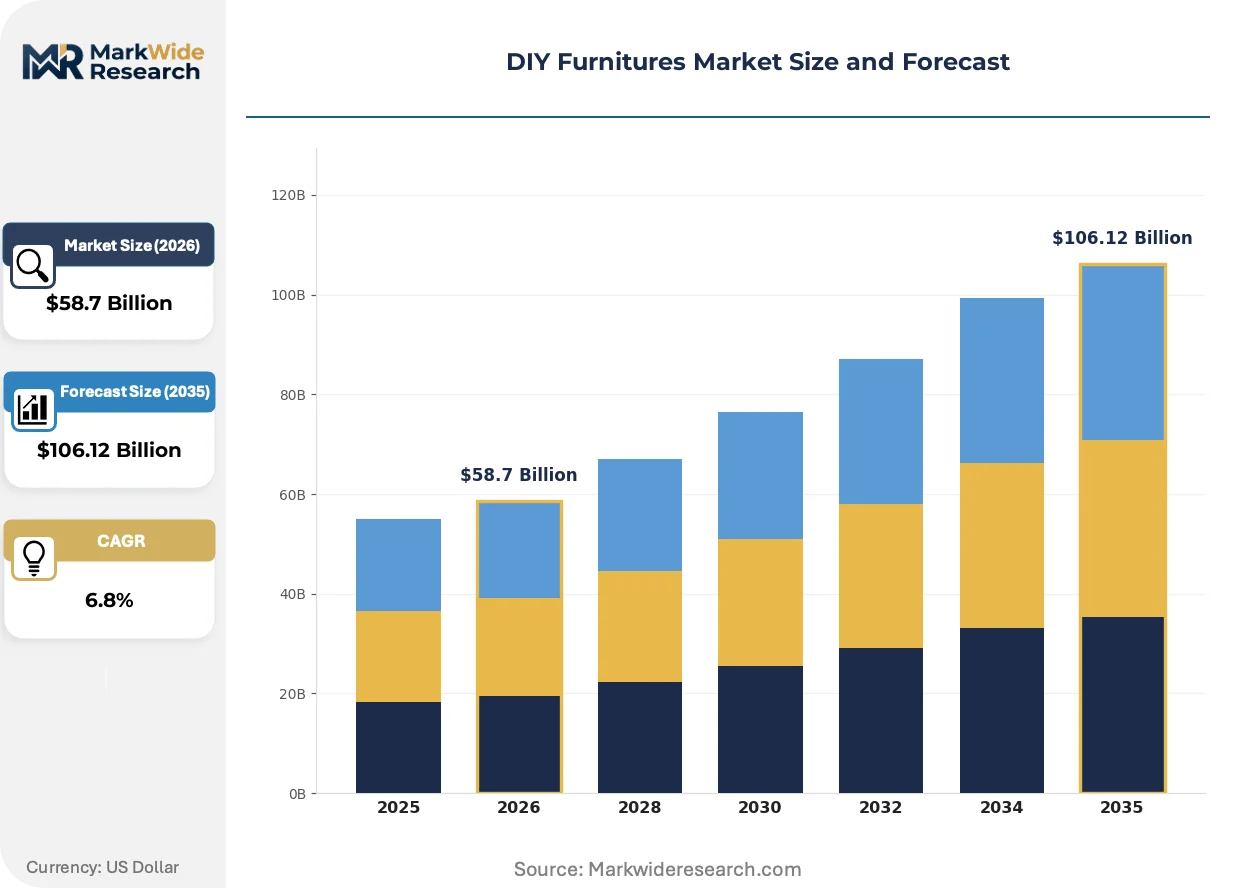
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Shelves, Cabinets Material: Wood, Metal, Plastic, Composite Style: Modern, Rustic, Vintage, Minimalist Target Customer: Students, Professionals, Families, Hobbyists |
| Companies Covered | IKEA, Herman Miller, Steelcase, Godrej & Boyce, Wipro Furniture, Williams-Sonoma, Ashley Furniture Industries, Kinnarps, The Home Depot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DIY Furnitures Market Emerging Trajectories
Digital fabrication and regulatory chemistry constraints are converging to redefine material selection and customer interaction models across the DIY furniture value chain. These forces are compressing traditional manufacturing advantages while elevating software and certification capabilities.
Bio-based adhesives derived from lignin and soy protein formulations are hybridizing with conventional urea-formaldehyde resins to meet emission standards without sacrificing bond strength. German and Austrian panel producers are piloting these hybrids at commercial scale for IKEA-adjacent suppliers. The technology is enabling engineered wood producers to maintain California market access while avoiding the cost premium of fully synthetic zero-emission alternatives.
EPA TSCA Title VI formaldehyde standards are compelling composite wood manufacturers to revalidate their entire supplier networks for third-party certification. The regulation's chain-of-custody requirements are favoring vertically integrated producers who control substrate manufacturing in-house. Medium-density fiberboard lines serving the student housing and first-apartment segments face the steepest compliance cost escalation.
Rental property managers are consolidating furniture procurement through direct manufacturer relationships, bypassing traditional retail markup structures. This channel compression is most pronounced in Berlin, Amsterdam, and Austin where institutional multi-family housing operators specify standardized flat-pack room sets. The shift is forcing specialized retailers to pivot toward assembly services and damage protection add-ons to defend their intermediary role.
DIY Furnitures Market Segmentation
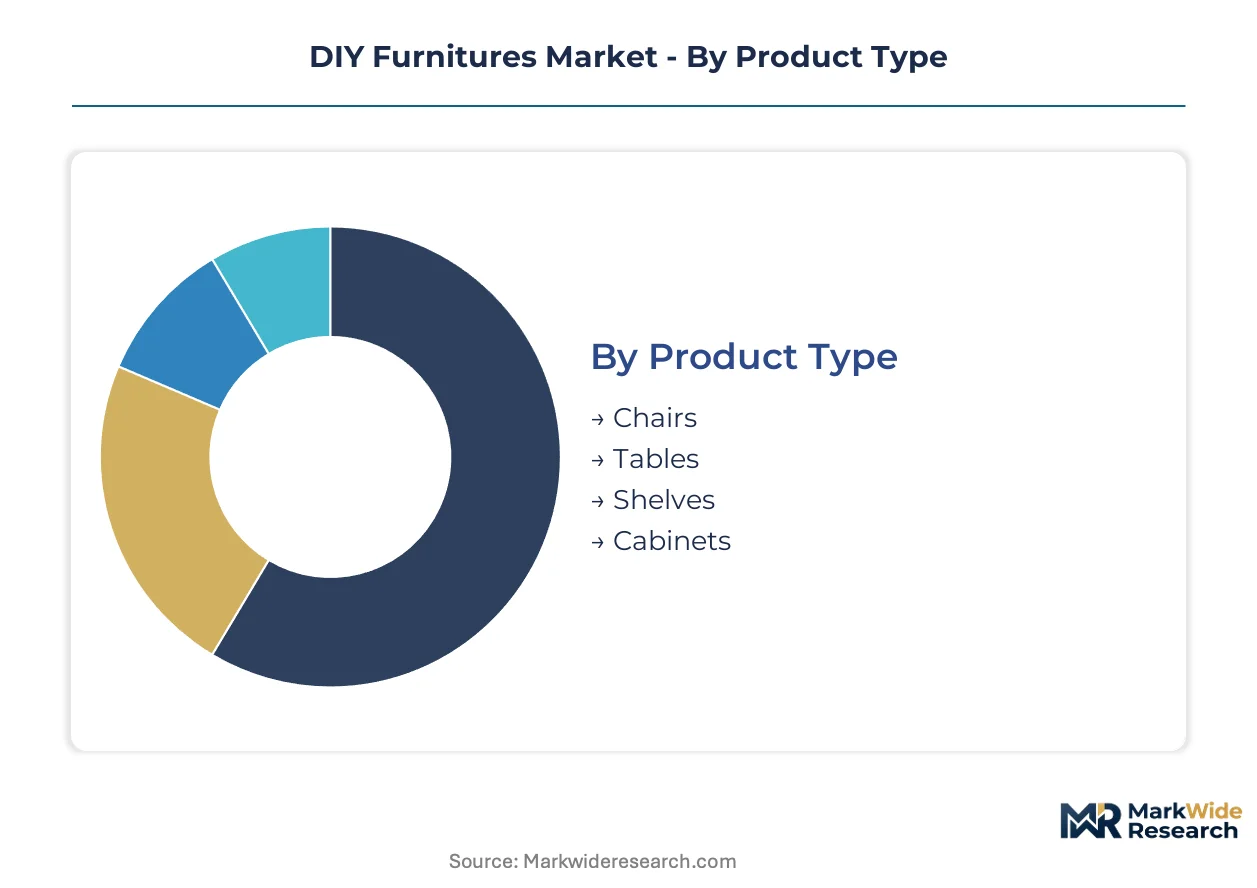
DIY furniture segmentation reveals how assembly complexity, material certification requirements, and housing mobility patterns split demand across distinct purchasing cohorts. Manufacturers configure kit engineering and distribution channels differently for each slice, with material compliance costs and style longevity driving margin dispersion.
Product Type:
Mature flat-pack categories dominate volume flows while emerging modular systems reshape assembly expectations.
- Chairs:Ergonomic frames with cam-lock joints and dowel reinforcement dominate home office procurement. German rental housing operators specify disassemblable task chairs for furnished unit turnover. Demand concentrates among remote professionals prioritizing lumbar adjustability over aesthetic customization.
- Tables:Panel-based dining and desk surfaces with bracket leg systems carry the heaviest freight cost-to-value ratio in flat-pack logistics. California CARB Phase II certification requirements elevate sourcing costs for composite tabletops serving North American student housing.
- Shelves:Wall-mounted bracket systems and freestanding cube configurations serve space-constrained urban apartments. Modular shelf kits allow reconfiguration across multiple rental cycles.
- Cabinets:Multi-panel storage units with hinge and slide hardware require the highest assembly skill threshold. Kitchen and bathroom cabinet kits face moisture-resistance specification gaps in humid climates.
Tables handle the majority of throughput; cabinets are expanding most quickly on share as modular kitchen systems penetrate rental refurbishment cycles.
Material:
Cost tier stratification separates certified solid wood premiums from price-driven engineered substrates.
- Wood:Solid hardwood and plywood substrates command sustainability premiums through FSC chain-of-custody certification. EU Ecodesign Directive repairability mandates favor solid wood kit manufacturers with circular economy positioning.
- Metal:Steel tube and aluminum extrusion frames serve industrial and outdoor furniture segments with minimal formaldehyde compliance burden. Powder-coat finishing lines face REACH chemical restriction complexity for European market access.
- Plastic:Injection-molded polypropylene and ABS components enable tool-free snap assembly for entry-tier demographics. Student housing procurement favors plastic chair and storage segments for damage replacement economics.
- Composite:Particleboard and MDF substrates with laminate facing compete on unit cost in first-apartment and institutional volume channels. EPA TSCA Title VI certification requirements favor vertically integrated producers controlling substrate manufacturing.
Composite handles the majority of throughput; wood is gaining share fastest as emission standards squeeze uncertified competitors.
Style:
Application context determines whether aesthetic permanence or disposability drives purchase decisions.
- Modern:Clean lines and hidden fastener systems align with professional urban demographics prioritizing space efficiency. Berlin and Amsterdam rental property managers specify modern flat-pack room sets for standardized unit staging.
- Rustic:Distressed finishes and visible joinery appeal to hobbyist makers seeking farmhouse aesthetics. Solid wood construction supports higher price points in rural and suburban homeownership markets.
- Vintage:Reproduction hardware and decorative molding details target collectors and short-term rental hosts curating period-consistent interiors. Assembly complexity limits adoption among non-handy buyers.
- Minimalist:Reduced component counts and neutral palettes serve Japanese and Scandinavian-influenced urban housing. Parametric design software enables rapid customization of minimalist configurations.
Modern handles the majority of throughput; minimalist is climbing the fastest as space-constrained housing density rises.
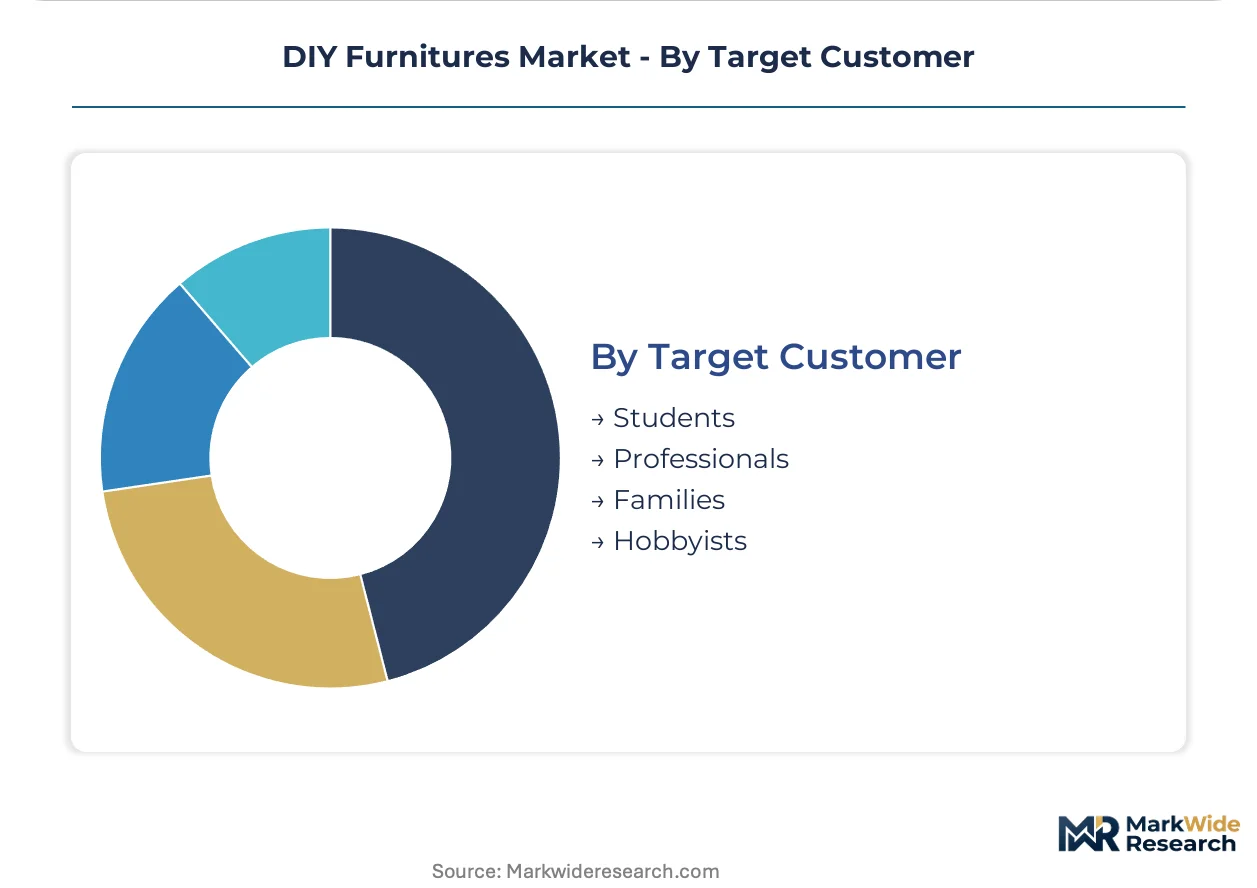
Target Customer:
Customer type segmentation maps directly to relocation frequency and assembly tolerance thresholds.
- Students:Price-sensitive cohorts prioritizing disposability over durability drive volume in composite chair and desk segments. Campus housing partnerships and back-to-school retail cycles concentrate demand seasonally.
- Professionals:Remote work infrastructure investment sustains premium ergonomic chair and height-adjustable desk kit demand. Direct-to-consumer channels bypass retail markup for this digitally native segment.
- Families:Multi-functional storage and expandable dining configurations serve household formation stages with varying space constraints. Safety certification and tip-resistance standards govern procurement for children's furniture.
- Hobbyists:Maker culture participants seek unfinished wood kits and customizable parametric designs for personal fabrication. This segment tolerates highest assembly complexity and tool requirements.
Students handle the majority of throughput; professionals are expanding most quickly on share as hybrid work normalizes home office investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German flat-pack manufacturers export engineered wood kits to rental housing operators across the Netherlands and Denmark, establishing a north European procurement corridor that shapes regional supply patterns.
United States
California's CARB Phase II standards compel composite wood suppliers to revalidate certification chains for particleboard and MDF substrates serving student housing markets. EPA TSCA Title VI enforcement tightens formaldehyde testing protocols nationwide. Austin and Brooklyn rental property managers consolidate direct procurement of disassemblable room sets, bypassing traditional retail channels.
Germany
Bauhaus-inspired DIY culture sustains specialized retail networks for minimalist flat-pack configurations across Berlin and Hamburg rental markets. EU Ecodesign Directive repairability mandates favor solid wood kit manufacturers with circular economy positioning. Bavarian panel producers pilot lignin-based adhesive hybrids to maintain emission compliance without synthetic resin cost premiums.
China
Zhejiang and Guangdong province suppliers dominate cam-lock fastener and bracket hardware production for global kit furniture assembly systems. GB standards for indoor air quality govern formaldehyde limits in engineered wood products sold domestically. Shenzhen manufacturers face margin pressure from EPA and EU certification requirements for export-bound composite substrates.
India
Tier-2 city apartment construction in Maharashtra and Karnataka outpaces furnished unit supply, creating white space for localized flat-pack distribution partnerships. BIS certification requirements for furniture safety and material standards govern domestic market access. Mumbai and Bangalore furniture fabricators scale CNC cutting capacity to serve emerging rental housing operators.
Japan
Space-constrained Tokyo and Osaka apartments drive demand for minimalist kit configurations with reduced component counts. METI energy efficiency guidelines influence material selection for domestic furniture production. Japanese manufacturers prioritize disassemblable designs aligned with frequent relocation patterns among urban professional demographics.
DIY Furnitures Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Mass-market retailers leverage captive supply chains and global store footprints to dominate accessible flat-pack segments. Premium ergonomic specialists anchor direct-to-consumer positioning through controlled digital channels. Mid-market wood and composite fabricators sustain manufacturing scale across standardized kit lines. Competitive moves concentrate on backward integration into substrate production and strategic partnerships with rental housing operators.
Among Swedish-origin retailers, IKEA exemplifies the channel-controlling archetype through engineered wood supply dominance. Herman Miller and Steelcase occupy positions within the premium ergonomic tier, anchoring direct-to-consumer strategies for remote work infrastructure investment. These three entities represent the primary competitive anchors shaping price and assembly complexity expectations across market tiers.
| Leading Market Players |
|---|
| IKEA |
| Herman Miller |
| Steelcase |
| Godrej & Boyce |
| Wipro Furniture |
| Williams-Sonoma |
| Ashley Furniture Industries |
| Kinnarps |
| The Home Depot |
| Others |
Supply Flow & Price Mechanics
Zhejiang and Guangdong province hardware suppliers anchor global cam-lock fastener production, concentrating margin capture upstream while downstream kit assemblers compete on logistics efficiency and certification speed. Engineered wood substrate costs fluctuate with resin feedstock markets, transmitting volatility through particleboard and MDF lines serving price-sensitive student housing segments.
Pricing Analysis
Current-generation CARB Phase II-certified composite kits command premium positioning against prior-generation uncertified alternatives, while next-generation lignin-adhesive hybrids promise cost-neutral compliance. Three-tier pricing structure across premium solid wood, standard certified composite, and economy uncertified particleboard segments separates FSC-certified sustainability premiums from basic utility positioning. Pricing pressure stems from EPA TSCA Title VI enforcement tightening, squeezing margins for non-vertically integrated substrate importers. Students represent the most price-sensitive cohort, prioritizing disposable unit economics over durability certification.
Supply Chain Analysis
Timber feedstock and urea-formaldehyde resin inputs draw from Southeast Asian plantation forests and Chinese petrochemical complexes, creating dual-source dependency for engineered wood producers. Manufacturing concentrates in China for hardware components, Germany for precision panel production, and Vietnam for labor-intensive finishing operations. Single-source vulnerability runs through Zhejiang cam-lock suppliers, where concentrated fastener production creates chokepoint exposure for global kit assembly. Distribution runs through direct-to-consumer channels for remote work professionals and consolidated procurement relationships for rental property operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DIY furniture is approaching a platform-economics inflection where parametric design software interoperability determines ecosystem lock-in, with CAD-to-cut workflow standardization enabling modular kit reconfiguration across multiple housing cycles.
For Market Incumbents: Entrench certification advantages by accelerating backward integration into lignin-adhesive substrate production, neutralizing synthetic resin cost premiums that threaten CARB Phase II margins. Deepen captive supply control over engineered wood manufacturing to compress launch timelines against emerging parametric-design entrants. Prioritize direct procurement partnerships with Berlin and Amsterdam rental operators to defend channel position against retail disintermediation.
For New Entrants and Emerging Players: Tier-2 Indian cities present the most penetrable white space, where Maharashtra and Karnataka apartment construction outpaces furnished unit supply. Target localized flat-pack distribution partnerships with Mumbai and Bangalore fabricators scaling CNC capacity. Pursue AR-guided assembly apps as the primary go-to-market angle, reducing return rates among non-handy first-apartment demographics.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated substrate producers with simultaneous EPA TSCA Title VI and EU Ecodesign Directive certification coverage, capturing regulatory complexity as a competitive moat. Long-term viability hinges on circular economy positioning as extended producer responsibility frameworks mature. Monitor EU carbon border adjustment implementation as the critical inflection signal for cross-border kit sourcing cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Production | Lignin-hybrid resin manufacturing secures CARB Phase II compliance without synthetic premium costs. |
| Parametric Design Platform Launch | CAD-to-cut interoperability enables rapid customization for minimalist urban housing configurations. |
| Rental Housing Direct Procurement Partnership | Bypassing retail markup captures institutional volume from Berlin and Austin multi-family operators. |
| AR Assembly App Development | Hybrid physical-digital kits expand addressable market beyond traditional handy buyer demographics. |
| Circular Economy Certification Program | EU Ecodesign Directive repairability mandates favor solid wood kit producers with documented recyclability. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with flat-pack manufacturing executives, rental property procurement managers, and parametric design software developers; and secondary validation through EPA TSCA Title VI certification databases, EU Ecodesign Directive regulatory filings, and customs trade records for engineered wood substrate flows. Bottom-up triangulation across component-level cost structures and top-down demand modeling across student, professional, and family housing segments ensured cross-verification.
Forecast inputs include material certification tier adoption curves, rental housing turnover frequency by metropolitan density, and parametric design penetration rates across maker demographics. Segmentation dimensions span product type, material substrate, style category, and target customer archetype, with additional modeling for regulatory compliance cost pass-through by geography. CAGRs derive from elasticity-adjusted demand projections and supply-side capacity expansion schedules across the analysis window.
Practitioners should monitor EPA enforcement intensity, EU carbon border adjustment timing, and resin feedstock price volatility for early signals necessitating forecast revision. Cross-checking against BIS certification timelines for Indian market entry and METI energy efficiency guideline updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
Bays and Bows Window Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
Automatic Curtain Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
Home Remodeling Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market