
 Italy Do-It-Yourself (DIY) Home Improvement Retailing Market | 2026-2036
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market Insights
Market Context with Strategic Players
Capital-intensity divergence between large-format operators and digital-native entrants is rotating competitive dynamics across the Italian DIY landscape. Leroy Merlin leverages its hypermarket footprint to anchor category leadership in Lombardy and Veneto. ManoMano competes through marketplace aggregation, reducing fixed-asset exposure while extending reach into secondary cities. Brico io S.p.A. specializes in compact urban formats, navigating Italy's constrained retail zoning with neighborhood accessibility.
Technical Definition and Structural Segments
Italy Do-It-Yourself (DIY) Home Improvement Retailing encompasses the sale of tools, materials, fixtures, and equipment directly to consumers and semi-professionals for residential modification, repair, and aesthetic enhancement, typically involving SKUs measured by torque ratings, lumens output, or VOC compliance for paint formulations. The product-type dimension shows power tools commanding the dominant margin pool due to battery-platform ecosystems, while paint segments attract repeat traffic through color-matching services. Among customer types, homeowners generate the highest basket values as Superbonus-driven renovations elevate project scope beyond routine maintenance.
Regulatory Frame and Forward-Looking Close
Italy's Agenzia delle Entrate administers Superbonus fiscal incentives, while BIS-equivalent technical standards govern product safety for electrical and gas-powered equipment sold through retail channels. CE marking requirements under EU harmonized regulations shape import sourcing and private-label development for distributors. Stakeholders must monitor whether Rome extends or modifies renovation subsidies, as this single policy lever determines project pipelines and inventory planning cycles across the entire retail network.
Market Dynamics
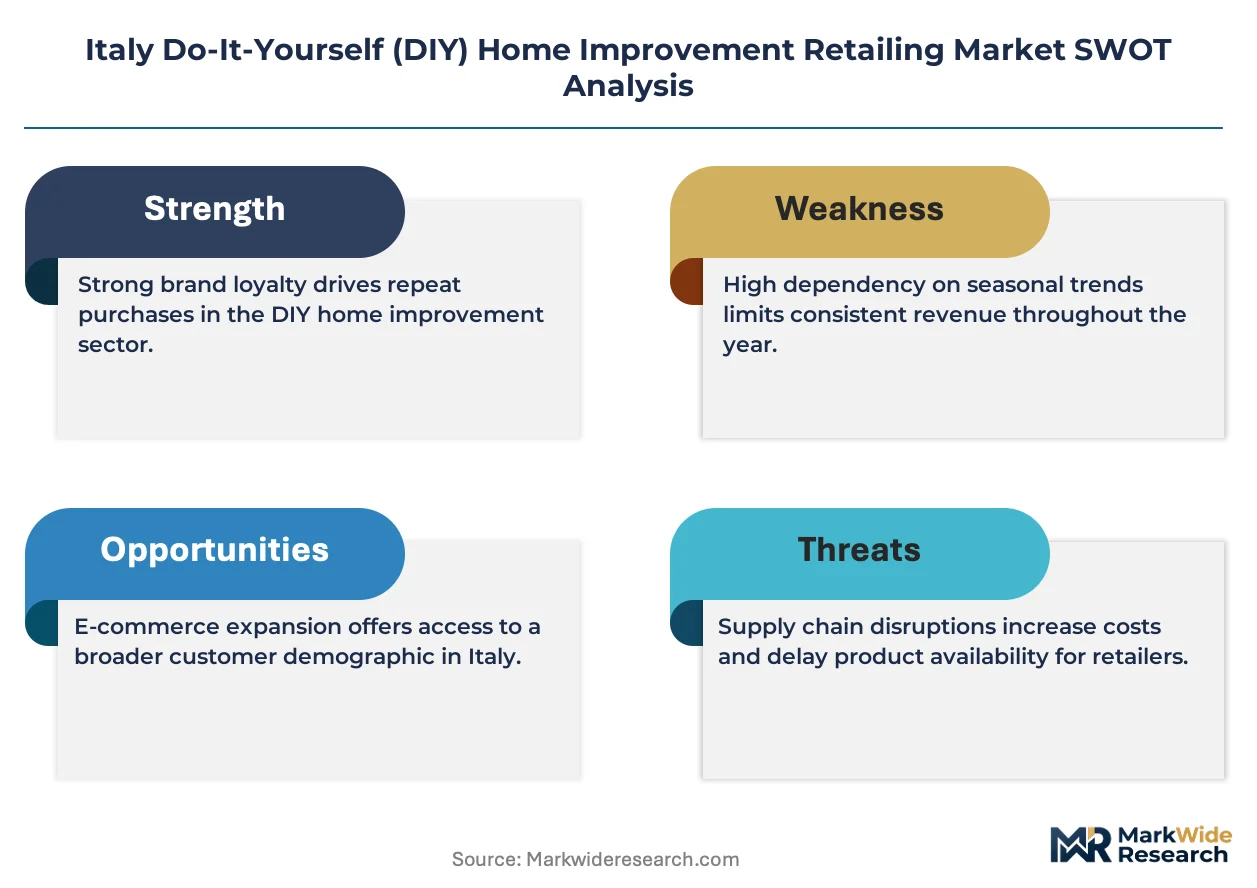
Italy's Superbonus 110% tax incentive scheme is compressing renovation timelines and elevating project complexity, forcing retailers to recalibrate inventory depth toward structural retrofit materials and energy-efficiency SKUs.
Growth Catalysts
- Superbonus Fiscal Architecture:Italy's Agenzia delle Entrate administers renovation tax credits that channel consumer liquidity toward seismic upgrades and thermal insulation, expanding addressable project scope for building material suppliers.
- Battery Platform Ecosystems:Cordless power tools with interchangeable battery systems are displacing corded alternatives in homeowner segments, driving repeat accessory purchases and brand lock-in effects across Lombardy and Veneto.
- Aging Housing Stock Concentration:Northern Italy's pre-1970 residential inventory generates sustained demand for modernization, with Milan-Turin corridor municipalities recording elevated permit volumes for energy retrofit work.
Market Restraints
- CE Marking Compliance Friction:EU harmonized regulations governing electrical and gas-powered equipment create certification bottlenecks for private-label development, extending product launch timelines by 8-14 months for distributor sourcing teams.
- Zoning Density Constraints:Italy's constrained retail zoning regulations limit large-format expansion in historic urban centers, compressing Leroy Merlin and Brico io S.p.A. format options in Rome, Florence, and Bologna municipal boundaries.
- Substitute Channel Displacement:Professional contractor networks with direct wholesale accounts are capturing Superbonus-driven structural projects that bypass retail entirely, eroding high-value basket capture for DIY operators.
Strategic Opportunities
- Southern Italy Underpenetration:Campania, Sicily, and Calabria exhibit DIY retail density gaps of 40-60% below northern benchmarks, creating whitespace for compact urban format replication in Naples, Palermo, and Catania metro zones.
- Digital Marketplace Aggregation:Secondary cities including Verona, Padua, and Brescia show elevated online tool and material search volumes with limited same-day fulfillment, rewarding marketplace models with localized logistics partnerships.
- Superbonus Extension Contingency:Parliamentary debate over subsidy program renewal through 2027-2028 creates inventory positioning windows for retailers who secure thermal insulation and HVAC equipment ahead of policy confirmation.
Industry Challenges
- Energy Auditor Certification Bottlenecks:Superbonus eligibility requires certified technician assessments, and Italy's qualified energy auditor pool of approximately 12,000 professionals creates project initiation delays that stall material procurement cycles.
- Legacy ERP Integration Friction:Established retailers with 1990s-era inventory management systems face technical debt when implementing real-time color-matching services and battery-platform SKU tracking demanded by younger homeowner segments.
Report Scope
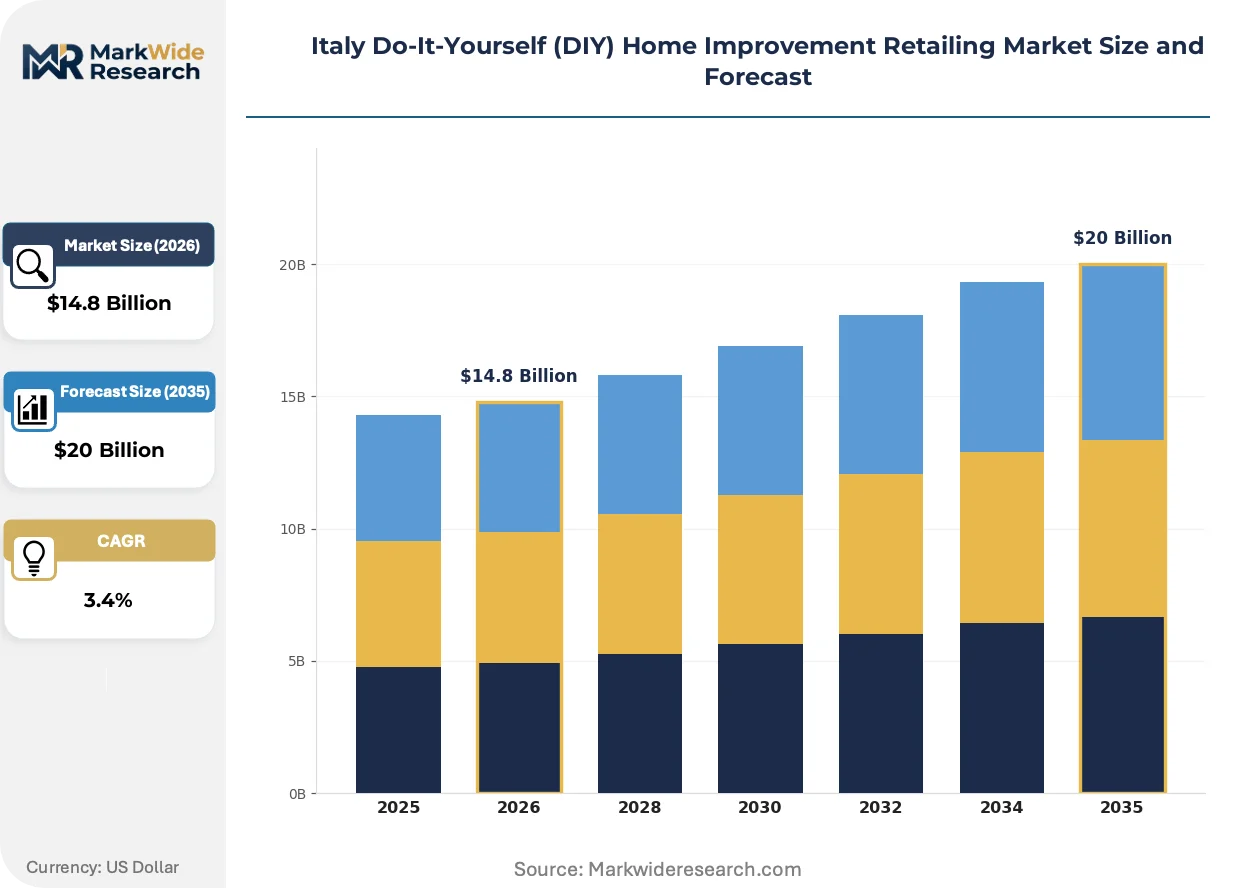
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Do-It-Yourself (DIY) Home Improvement Retailing Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Tools, Hand Tools, Paint, Lighting Fixtures Customer Type: Homeowners, Contractors, Renters, Interior Designers Distribution Channel: Online Retail, Physical Stores, Wholesale, Direct Sales End Use: Interior Renovation, Exterior Improvement, Gardening, Maintenance |
| Companies Covered | OBI GmbH & Co. Deutschland KG, Bricofer, Groupe Adeo SA, ManoMano, Bricocenter Italia, Brico io S.p.A., Kingfisher plc, Brico OK, Leroy Merlin, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market Trends and Innovations
Battery chemistry advances and regulatory compliance automation are actively restructuring how Italian homeowners specify tools and materials, compressing traditional channel hierarchies while elevating service-layer differentiation.
Brushless motor technology is decomposing the torque-per-watt efficiency hierarchy in cordless power tools, enabling 18V platforms to deliver performance previously requiring 36V architectures. Semi-professional homeowners in Emilia-Romagna and Tuscany are adopting these systems for medium-duty renovation work, collapsing the price-performance gap between prosumer and professional-grade equipment categories.
Italy's Agenzia delle Entrate has digitized Superbonus documentation workflows through pre-filled tax return integration, reducing claim rejection rates and accelerating reimbursement timelines. This administrative streamlining is compressing the cash-flow gap for renovation households, with knock-on inventory velocity effects for retailers stocking thermal break windows and heat pump systems in Lombardy distribution centers.
Homeowner specification behavior is migrating toward project-bundle purchasing rather than single-SKU acquisition, with Superbonus-driven renovations requiring coordinated material procurement across insulation, HVAC, and electrical categories. Retailers with cross-category technical consultation capabilities are capturing these consolidated baskets, while single-category specialists face margin compression in Milan and Turin competitive zones.
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market Segmentation
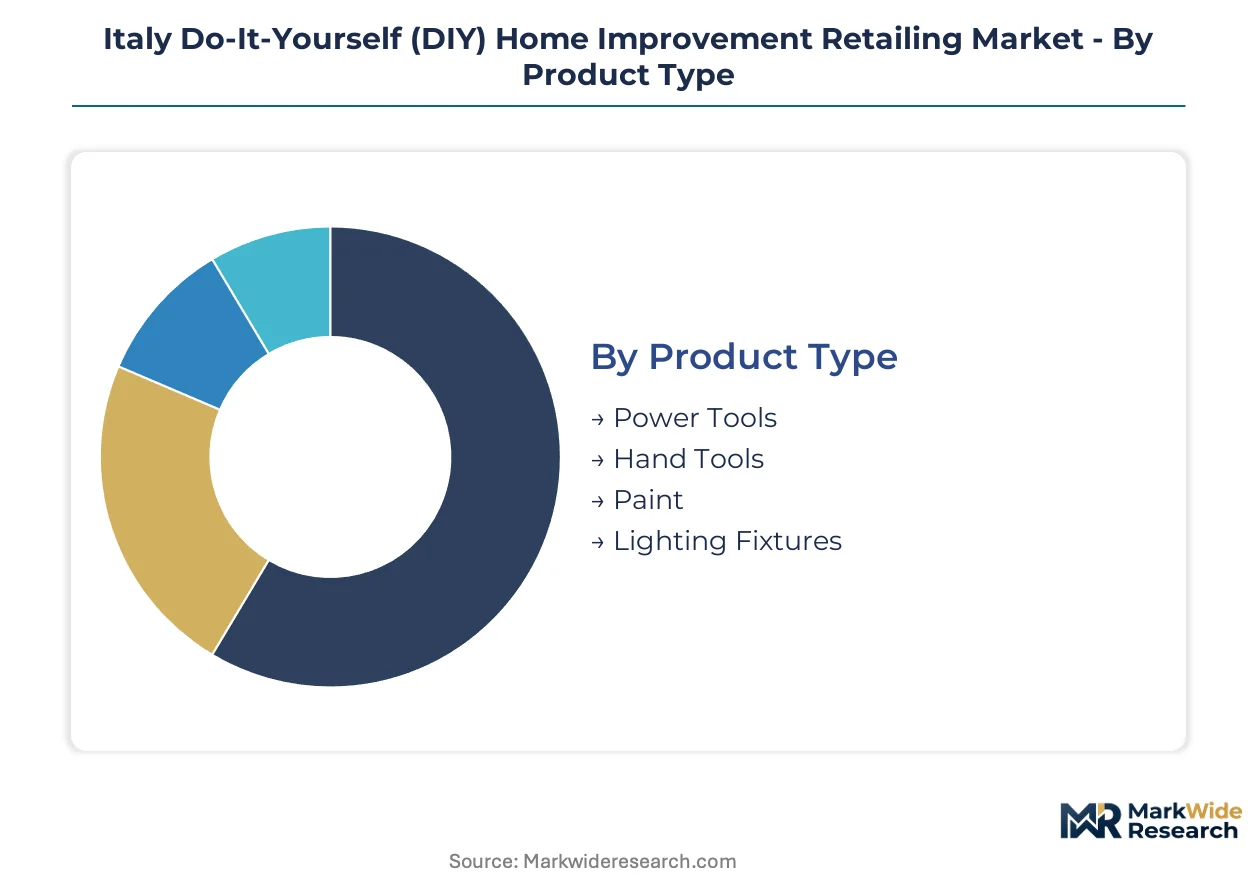
Segmentation in Italy's DIY retailing market reveals how Superbonus-driven renovation cycles reshape category priorities. Retailers aligning inventory depth with structural retrofit demand capture disproportionate basket values against maintenance-focused competitors.
Product Type:
Professional contractor networks and direct wholesale channels exert the strongest substitution pressure on power tools and hand tools, diverting high-margin commercial-grade sales from retail storefronts.
- Power Tools:Cordless platforms with brushless motor architectures dominate specification behavior, with 18V interchangeable battery systems collapsing the performance gap between prosumer and professional tiers. Demand concentrates in Lombardy distribution corridors where Superbonus seismic retrofit projects elevate torque requirements for structural anchoring and concrete drilling.
- Paint:Low-VOC formulations with color-matching precision anchor repeat traffic strategies, as Agenzia delle Entrate documentation requirements for thermal insulation projects drive coordinated aesthetic finishing. Milan-Turin retailers report elevated basket attachment rates when technical consultation accompanies tinting services.
- Hand Tools:Chrome-vanadium and carbon steel assortments serve maintenance-oriented households with lower project complexity.
- Lighting Fixtures:LED retrofit SKUs with lumens-per-watt optimization align with Superbonus energy-efficiency eligibility criteria.
Power tools anchors the volume base while paint gains share at the steepest rate through service-layer differentiation.
Customer Type:
Cost tier stratification separates project-scale commitments, with tax-credit-eligible renovations commanding capital outlays that dwarf routine maintenance expenditures.
- Homeowners:Superbonus 110% beneficiaries generate the highest basket values as seismic upgrades and thermal insulation projects require cross-category material coordination. Northern Italy's pre-1970 housing stock concentrates permit activity in Milan, Turin, and Bologna metropolitan zones.
- Contractors:Semi-professional renovators purchasing through retail channels bridge the gap between pure DIY and wholesale-procured professional networks, particularly in Veneto's secondary cities.
- Renters:Portable, non-structural solutions dominate acquisition patterns with minimal permanence requirements.
- Interior Designers:Specification influence extends through color-matching service dependencies and curated material palettes.
Homeowners anchors the volume base while contractors expand most quickly as Superbonus complexity drives technical consultation demand.
Distribution Channel:
Geography determines format viability, with historic urban zoning constraints in Rome and Florence compressing large-format expansion while secondary cities reward digital penetration.
- Physical Stores:Compact urban formats navigate Italy's constrained retail zoning with neighborhood accessibility in dense municipal boundaries. Brico io S.p.A. specializes in this architecture, bypassing Leroy Merlin's hypermarket dependence.
- Online Retail:Marketplace aggregation reduces fixed-asset exposure while extending reach into Campania, Sicily, and Calabria whitespace where retail density trails northern benchmarks.
- Wholesale:Direct contractor accounts capture Superbonus structural projects that bypass retail entirely.
- Direct Sales:Manufacturer-owned channels serve brand-loyal power tool ecosystems with battery-platform lock-in.
Physical stores anchors the volume base while online retail climbs the fastest through logistics partnership localization.
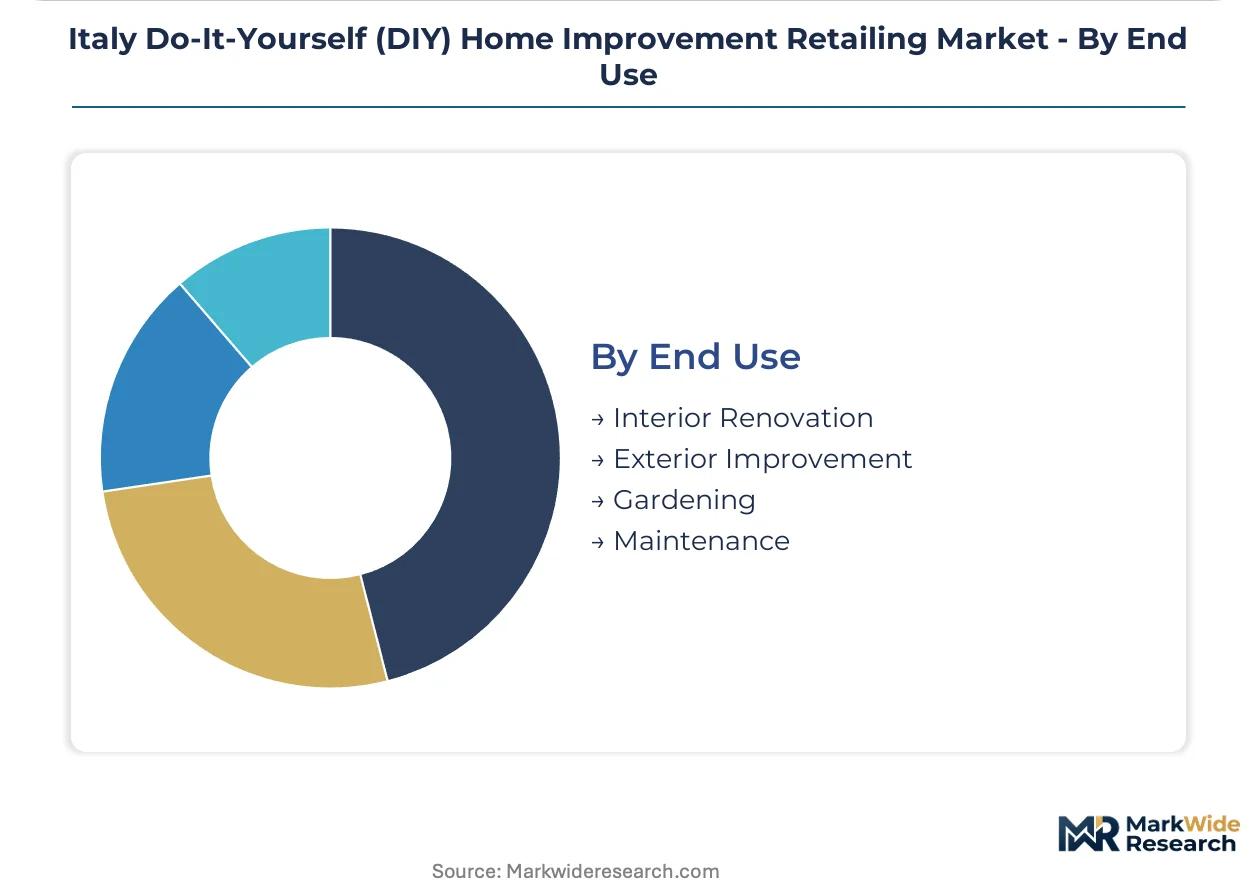
End Use:
Maturity differentials separate cyclical maintenance demand from structural retrofit cycles tied to policy expiration timelines.
- Interior Renovation:Thermal insulation, HVAC replacement, and seismic anchoring dominate Superbonus-eligible expenditure, with Agenzia delle Entrate digitized workflows accelerating reimbursement timelines and compressing cash-flow gaps for material procurement.
- Exterior Improvement:Façade thermal break windows and heat pump installations concentrate in Lombardy distribution centers serving Milan-Turin corridor municipalities.
- Gardening:Seasonal demand patterns with limited Superbonus eligibility constrain project scale.
- Maintenance:Routine repair cycles provide baseline traffic with lower basket values and reduced cross-selling attachment.
Interior renovation anchors the volume base while exterior improvement follows the steepest expansion trajectory as thermal envelope upgrades gain regulatory priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Italy's peninsula, with northern homeowners exhibiting lower price sensitivity due to Superbonus liquidity injection while southern buyers remain highly responsive to promotional pricing and credit availability.
Lombardy
Milan's metropolitan zone generates the densest concentration of Superbonus renovation permits in Italy. Agenzia delle Entrate's digitized tax credit workflows accelerate reimbursement timelines for thermal insulation projects. The Milan-Turin corridor anchors national distribution networks for heat pump systems and seismic retrofit materials.
Piedmont
Turin municipalities record elevated permit volumes for energy-efficiency retrofits in pre-1970 housing stock. Italy's 110% tax incentive scheme channels consumer liquidity toward structural improvements across the province. Industrial suburbs surrounding Turin concentrate contractor procurement activity for large-scale residential upgrades.
Veneto
Secondary cities including Verona and Padua show elevated online tool search volumes with limited same-day fulfillment infrastructure. CE marking requirements under EU harmonized regulations shape import sourcing for electrical equipment sold through regional retail channels. The Veneto plain hosts compact urban format expansion targeting neighborhood accessibility.
Emilia-Romagna
Bologna's historic urban core constrains large-format retail zoning, compressing hypermarket expansion options. Semi-professional homeowners in the region adopt brushless motor power tool platforms for medium-duty renovation work. Municipal energy auditor certification bottlenecks stall project initiation timelines across the province.
Lazio
Rome's constrained retail zoning limits physical format penetration in dense municipal boundaries. Parliamentary debate over Superbonus extension through 2027-2028 creates inventory positioning uncertainty for thermal insulation suppliers. The capital region exhibits DIY retail density gaps compared to northern benchmarks.
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hypermarket operators commanding fixed-asset advantages while digital-native entrants reduce capital exposure through marketplace aggregation. The competitive structure separates format-scale players from neighborhood-accessibility specialists and online fulfillment platforms. Two dominant competitive moves are reshaping positioning: compact urban format replication in zoning-constrained historic centers, and logistics partnership localization for same-day delivery in secondary cities.
Among France-based retail conglomerates, Groupe Adeo SA and Leroy Merlin exemplify the hypermarket-scale archetype with extensive fixed-asset networks. ManoMano occupies a position within the digital-native tier, representing marketplace aggregation models that bypass traditional retail zoning constraints. Brico io S.p.A. anchors the compact-format specialist segment, demonstrating how neighborhood accessibility strategies navigate Italy's dense urban regulatory environments.
| Leading Market Players |
|---|
| OBI GmbH & Co. Deutschland KG |
| Bricofer |
| Groupe Adeo SA |
| ManoMano |
| Bricocenter Italia |
| Brico io S.p.A. |
| Kingfisher plc |
| Brico OK |
| Leroy Merlin |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with thermal insulation and heat pump manufacturers lock in supply access for Italian retailers while anchoring price visibility against Superbonus policy volatility. These contract structures tether inventory positioning to Agenzia delle Entrate reimbursement timelines, compressing working capital risk for distributors serving Lombardy and Veneto renovation corridors.
Pricing Analysis
After-sales revenue from battery-platform accessories and extended service contracts drives lifetime value beyond initial tool purchases. Three-tier pricing structure across premium brushless systems, standard cordless platforms, and economy corded alternatives stratifies by motor architecture and battery interchangeability. Cost compression in entry-level tiers intensifies as Chinese OEMs expand CE-marked product lines, eroding margin pools for private-label distributors. Semi-professional contractors exhibit lowest price sensitivity due to project-bundled procurement, while maintenance-oriented homeowners in southern regions remain highly promotional-responsive.
Supply Chain Analysis
Inventory cycles for seismic retrofit materials and HVAC equipment stretch lead times when Superbonus permit volumes spike in Milan-Turin municipalities. Manufacturing concentrates in China for power tool platforms, Germany for brushless motor components, and Poland for thermal insulation products. Lithium-ion cell supply draws from South Korean and Chinese producers, creating single-source vulnerability for battery ecosystem rollouts. Distribution runs through Lombardy regional distribution centers serving northern retail networks, with secondary city fulfillment increasingly tethered to marketplace logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Italy's DIY retailing creates entry niches as Superbonus complexity splits demand between structural retrofit specialists and maintenance-focused generalists. The policy-driven renovation cycle rewards format-specific positioning over scale-based competition.
For Market Incumbents: Consolidate neighborhood accessibility advantages in zoning-constrained historic centers before compact-format replication accelerates. Defend against marketplace aggregation by deepening technical consultation capabilities that anchor project-bundle purchasing. Prioritize backward integration into thermal insulation and HVAC equipment categories most exposed to Superbonus extension uncertainty. For New Entrants and Emerging Players: Anchor in Campania, Sicily, and Calabria whitespace where retail density trails northern benchmarks by 40-60%. Target Naples, Palermo, and Catania metro zones with compact urban formats bypassing large-format zoning restrictions. Pursue localized logistics partnerships for same-day fulfillment in secondary cities showing elevated online search volumes with limited infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward digital-native marketplace operators with proven secondary city penetration and battery-platform ecosystem partnerships. Long-term viability hinges on Superbonus policy continuity and the shift from transactional tool sales to project-bundle service layers. Monitor parliamentary debate over subsidy renewal as the critical inflection signal for inventory positioning cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Compact Urban Format Replication | Neighborhood accessibility bypasses Rome and Florence zoning constraints where hypermarket expansion stalls. |
| Battery Platform Ecosystem Partnership | Interchangeable 18V system lock-in elevates repeat accessory revenue and reduces price transparency. |
| Localized Logistics Network Buildout | Same-day fulfillment in Verona and Padua captures elevated online search volumes with limited competition. |
| Technical Consultation Service Layer | Cross-category project guidance captures Superbonus-driven bundle purchasing away from single-SKU competitors. |
| Thermal Insulation Inventory Positioning | Pre-policy confirmation stocking ahead of Superbonus extension debates secures supply access for retrofit demand spikes. |
Research Methodology
The analysis maps power tool platforms, thermal insulation categories, paint formulations, and lighting retrofit SKUs, each validated through retail category managers, energy auditor certification bodies, and regional distribution operators. Primary fieldwork with Lombardy and Veneto store operations directors, Agenzia delle Entrate policy administrators, and contractor purchasing coordinators combined with secondary validation against EU CE marking databases, Italian customs import records, and municipal permit filings. Bottom-up SKU-level demand modeling and top-down macroeconomic triangulation anchored volume estimates.
Consistency checks against external benchmarks validated output ranges across the projection horizon. Segmentation modeling incorporated product type, customer archetype, distribution channel, and end-use application dimensions. CAGRs derived from policy-driven renovation cycle assumptions, housing stock age demographics, and battery platform adoption curves. Forecast inputs included Superbonus reimbursement velocity, energy auditor certification pipeline constraints, and retail zoning regulatory trajectories.
Decision-makers should treat outputs as directional under assumptions of Superbonus policy continuity and northern Italian housing stock renovation rates; material deviation in subsidy extension timelines or permit processing velocity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
Vietnam Home Improvement Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
Automatic Curtain Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
Home Remodeling Market