
 US Home Remodeling Market | 2026-2036
US Home Remodeling Market Size, Share, and Industry Trends Forecast 2026-2036
US Home Remodeling Market Analysis
Millennial owner-occupants is bifurcating demand away from speculative flippers. Power Home Remodeling leverages direct-to-consumer sales infrastructure to capture this shift. BELFOR Holdings Inc. anchors catastrophic restoration volume that feeds recurring renovation pipelines. Lennar Corp. competes through builder-affiliated remodeling arms tied to existing community footprints.
US home remodeling encompasses structural, mechanical, and finish upgrades to existing residential buildings, typically involving permit-submitted alterations to framing, electrical, plumbing, or HVAC systems with adherence to local IRC amendments and energy code cycles. Its commercial purpose centers on extending asset life, improving habitability, and capturing utility-cost savings. Kitchen and bathroom project types concentrate margin pools because material markups and labor specialization resist commoditization. Wood material categories sustain dominant share in structural and finish applications despite engineered-product encroachment. Design and construction service types are consolidating as integrated design-build firms capture premium pricing from time-constrained homeowners.
OSHA governs residential jobsite safety protocols, while the EPA administers lead-safe renovation rules under RRP certification requirements that filter contractor eligibility. FERC indirectly shapes demand through grid-interconnection standards that affect residential electrification retrofits. Stakeholders must monitor how state-level adoptions of IECC energy codes reshape permissible material specifications and contractor credentialing thresholds.
Market Dynamics
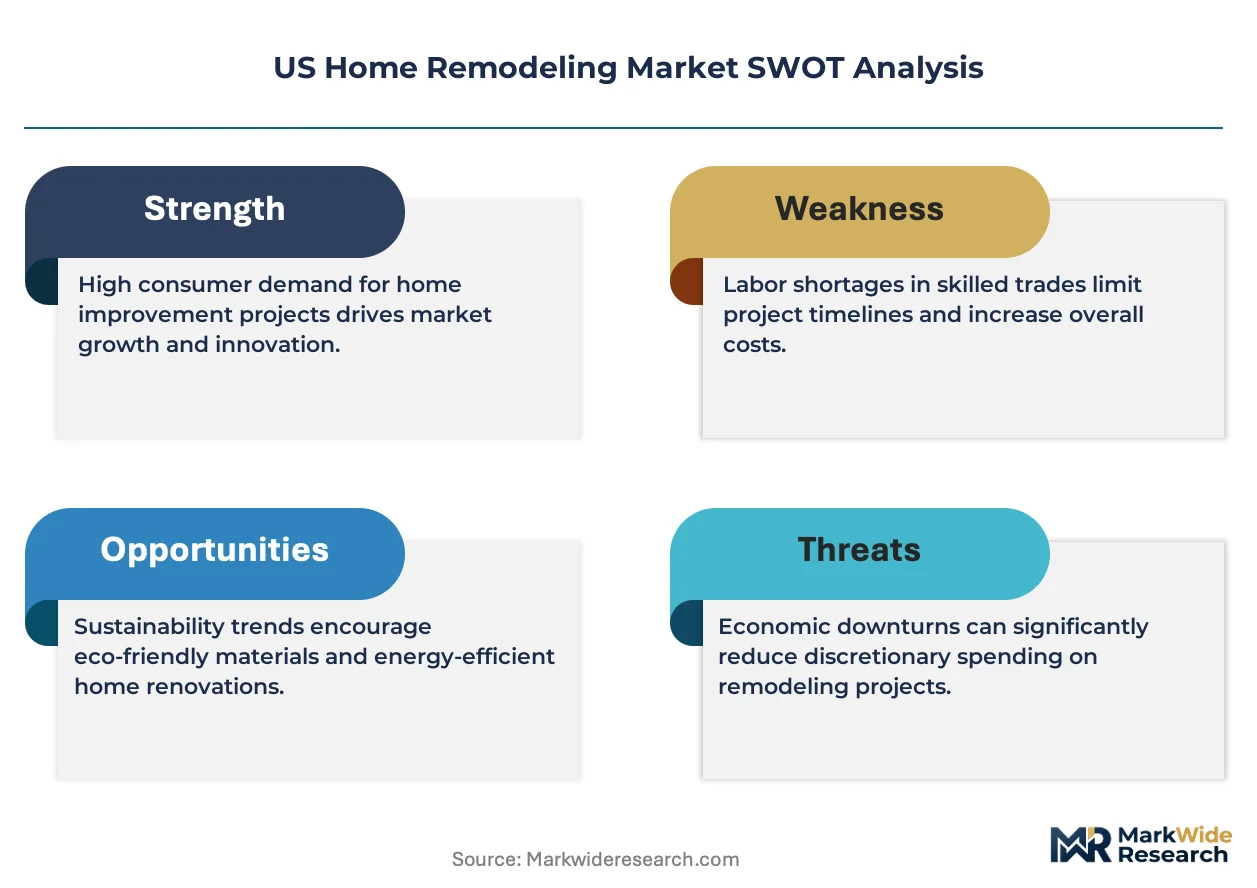
The Inflation Reduction Act's tax credits for heat pumps and weatherization are compressing contractor availability across Sun Belt metros, creating a supply-demand asymmetry that rewards firms with pre-built installation capacity and direct-to-consumer sales infrastructure.
Growth Catalysts
- IRA Energy Credits:Federal tax incentives for residential electrification retrofits are accelerating heat pump and solar panel installations in Austin, Phoenix, and Tampa.
- Aging Housing Stock:The median US home age exceeds 40 years, forcing structural upgrades to framing, electrical, and plumbing systems to meet current IRC amendments.
- Grid-Interconnection Standards:FERC protocols for residential battery storage and solar export are enabling whole-home energy system overhauls in deregulated utility territories.
Market Restraints
- Lumber Price Volatility:Structural wood categories face input cost swings from Canadian softwood tariff fluctuations and domestic mill capacity constraints.
- Contractor Concentration Risk:EPA RRP certification requirements filter eligible lead-safe renovators, concentrating project backlogs among credentialed firms in high-growth metros.
- Skilled Labor Scarcity:Electrician and HVAC technician pipeline gaps limit installation velocity for electrification retrofits regardless of consumer demand.
Strategic Opportunities
- Weatherization Mandates:State-level IECC energy code adoptions in California, New York, and Massachusetts are creating compliance-driven renovation pipelines for insulation and air-sealing contractors.
- Integrated Design-Build:Time-constrained homeowners are consolidating architectural and construction services, enabling premium pricing capture for firms with in-house design capacity.
- Accessory Dwelling Units:Zoning liberalization in Seattle, Denver, and Austin is opening garage conversion and backyard cottage construction as adjacent revenue streams.
Industry Challenges
- Permit Timeline Compression:Municipal building department backlogs in high-growth metros are extending project start dates and compressing contractor utilization rates.
- Cross-Trade Coordination:Whole-home renovations require synchronized electrical, plumbing, and HVAC sequencing, with scheduling failures cascading into margin erosion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Home Remodeling Market |
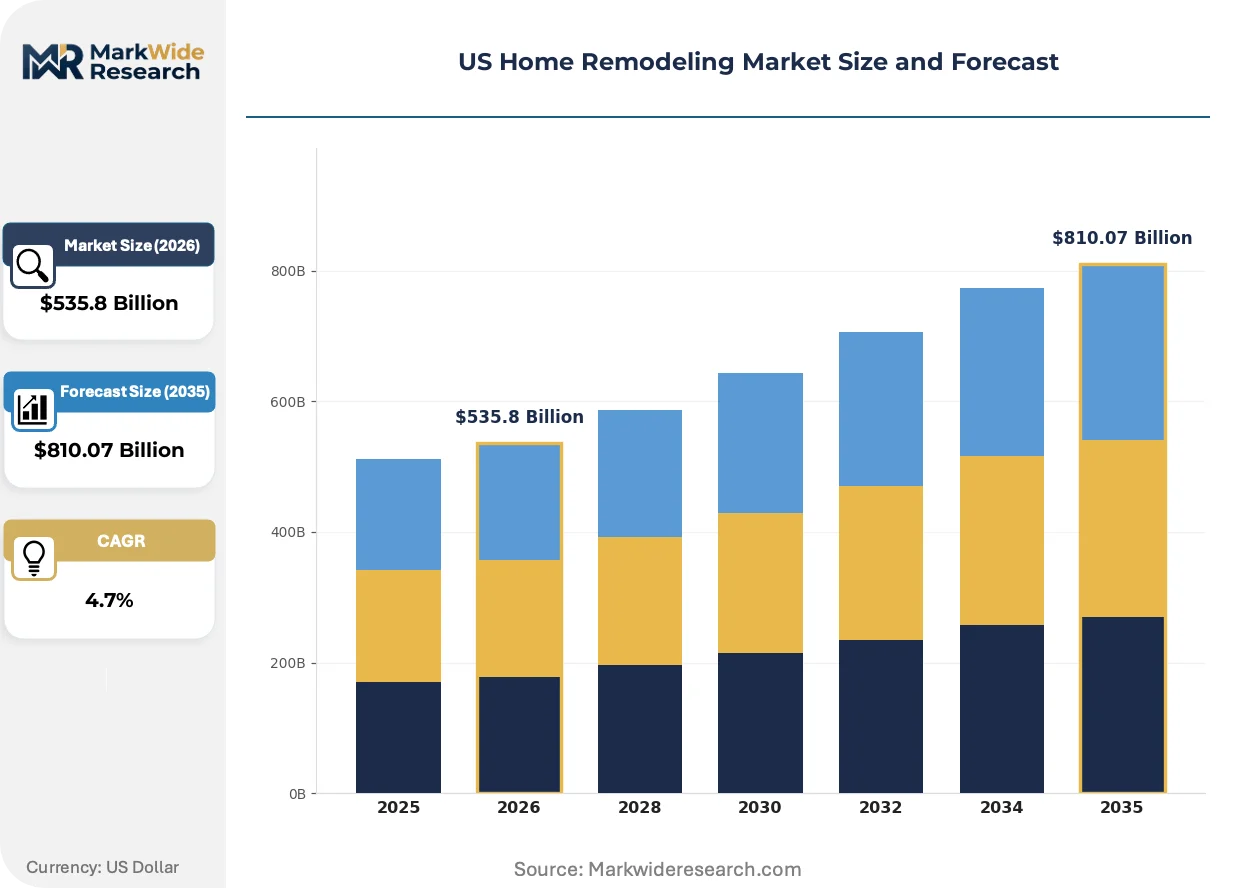
| Market Size in 2026 | $535.8 Billion |
| Market Size in 2035 | $810.07 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Kitchens, Bathrooms, Basements, Additions Material Type: Wood, Concrete, Steel, Glass Service Type: Design, Construction, Renovation, Consultation End User: Homeowners, Real Estate Agents, Contractors, Investors |
| Companies Covered | Great Day Improvements LLC, PulteGroup, Power Home Remodeling, NVR, D.R. Horton, BELFOR Holdings Inc., Lennar Corp., Taylor Morrison, Leaf Home, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Home Remodeling Market Emerging Trajectories
Residential remodeling is experiencing a structural shift toward electrification readiness and prefabrication, with regulatory mandates and labor scarcity forcing adoption of factory-built components and digital measurement tools.
Cross-laminated timber and mass timber structural systems are decomposing traditional stick-frame construction in whole-home additions and ADU projects. Custom builders in Portland and Minneapolis are specifying engineered wood for speed of erection. The technology is decomposing the competitive advantage of conventional framing crews by compressing on-site labor hours and reducing weather-dependent delays.
OSHA's updated silica exposure rules for residential demolition and the EPA's expanded RRP enforcement are elevating jobsite documentation requirements. Contractors now deploy real-time air monitoring and digital certification tracking to avoid penalty exposure. Kitchen and bath specialists in lead-heavy pre-1978 housing stock face the steepest compliance cost increases.
Homeowner purchasing for renovation services is fragmenting across channel types, with direct-to-consumer platforms capturing Millennial owner-occupants while traditional referral networks retain older demographics. Design-build firms are unbundling architectural services into fixed-fee consultations to compete with online planning tools. This pattern concentrates in Sun Belt metros where transplanted buyers lack established contractor relationships.
US Home Remodeling Market Segmentation
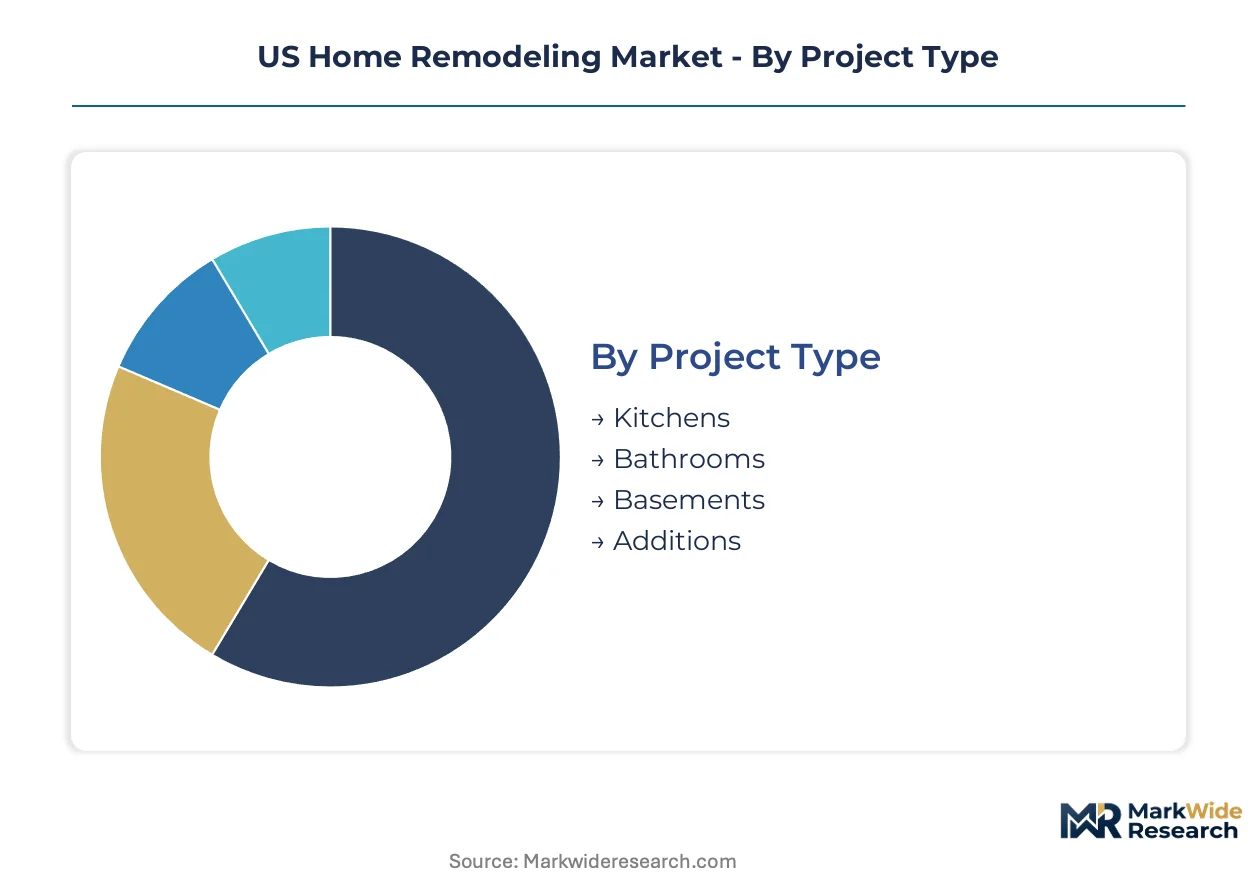
Remodeling market segmentation reveals how distinct project scopes, material specifications, and service delivery models create divergent margin profiles and regulatory exposure. Understanding these boundaries helps contractors allocate installation capacity and compliance resources across fragmented demand pools.
Project Type:
EPA RRP certification thresholds vary sharply by project scope, with lead-safe renovation rules concentrating compliance costs in pre-1978 housing interventions.
- Kitchens:Cabinet replacement and appliance integration dominate material spend. Sun Belt metros including Austin and Phoenix show concentrated demand from owner-occupants pursuing open-concept reconfigurations and energy-efficient appliance upgrades under IRA tax credits.
- Bathrooms:Wet-area waterproofing and fixture replacement require specialized plumbing permits. Aging housing stock in Northeast and Midwest markets drives systematic gut renovations to address deteriorating cast-iron drain lines and outdated electrical service.
- Basements:Below-grade moisture mitigation and egress window installation trigger IRC egress requirements. Demand concentrates in Midwest and Mountain West markets with unfinished lower levels.
- Additions:Structural integration with existing framing demands engineered lumber and foundation tie-ins. Zoning liberalization in Seattle, Denver, and Austin accelerates accessory dwelling unit construction as an adjacent revenue stream.
Established volume favors Kitchens; emerging adoption favors Additions.
Material Type:
Cost tier differentiation separates commodity structural inputs from premium finish specifications that resist price compression.
- Wood:Structural and finish applications sustain dominant share despite engineered-product encroachment. Canadian softwood tariff fluctuations and domestic mill capacity constraints create input cost volatility that compresses margins for stick-frame specialists.
- Concrete:Foundation repair and slab-on-grade additions require specialized placement crews. Demand clusters in Gulf Coast and California markets with expansive soil conditions and seismic retrofit mandates.
- Steel:Beam reinforcement and moment-frame retrofits address IRC seismic amendments. High material cost and specialized fabrication limit adoption to high-value whole-home renovations.
- Glass:Window replacement and exterior wall systems capture energy-code compliance premiums. State-level IECC adoptions in California, New York, and Massachusetts drive specification upgrades for thermal performance.
Volume concentration rests with Wood; specification upgrades favor Glass.
Service Type:
Customer type fragmentation separates time-constrained homeowners seeking single-point accountability from cost-sensitive buyers unbundling architectural and construction phases.
- Design:Architectural planning and permit documentation command fixed-fee structures. Design-build firms leverage in-house capacity to capture premium pricing from Millennial owner-occupants lacking established contractor relationships.
- Construction:Structural, mechanical, and finish execution requires synchronized trade sequencing. Skilled labor scarcity for electricians and HVAC technicians limits installation velocity regardless of consumer demand.
- Renovation:Whole-home systematic upgrades integrate multiple project types under single contracts. IRA energy credits accelerate heat pump and weatherization bundling in Sun Belt metros.
- Consultation:Feasibility studies and code-compliance advisory support pre-construction decision-making. Municipal backlog compression in high-growth metros extends project timelines and elevates planning-phase revenue.
Revenue scale favors Construction; margin expansion favors Design.
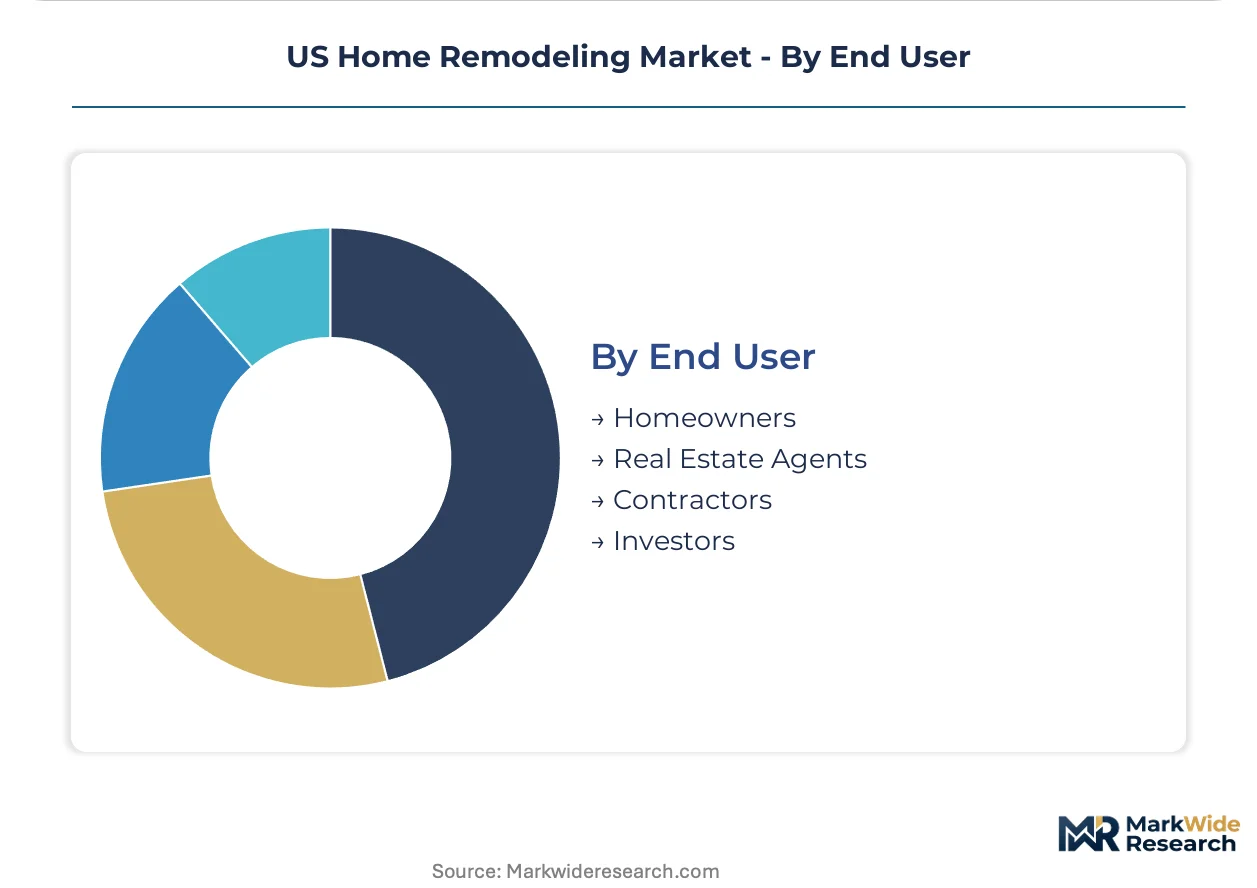
End User:
Geography shapes end-user composition, with transplanted Sun Belt buyers driving direct-to-consumer platform adoption while legacy Northeast markets retain referral-network dependency.
- Homeowners:Owner-occupants pursue habitability improvements and utility-cost capture. Millennial demographic weight concentrates demand in design-build integration and electrification readiness.
- Real Estate Agents:Pre-listing cosmetic upgrades target transaction velocity. Commission-driven timelines favor rapid-turnaround kitchen and bath refreshes over structural interventions.
- Contractors:Subcontractor specialization creates tiered procurement for general contractors assembling project teams. EPA RRP certification filters concentrate eligible lead-safe renovators in high-growth metros.
- Investors:Speculative flippers and rental-portfolio operators prioritize cost-controlled material packages. Aging housing stock and energy-efficiency mandates pull investor capital toward whole-home renovations over cosmetic-only approaches.
Transaction frequency favors Homeowners; project scale favors Investors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian lumber shipments feed framing material demand across US border states, while Mexican manufactured fixtures cross into Texas and Arizona markets. Regional remodeling intensity tracks housing age, energy-code stringency, and IRA credit uptake.
Southwest
Texas and Arizona metros absorb heat pump retrofits at accelerated velocity. Austin and Phoenix contractors face compressed availability from IRA-driven electrification backlogs. Dallas-Fort Worth anchors manufactured housing component flows from Mexican assembly plants.
Southeast
Florida and Georgia markets concentrate catastrophic restoration volume feeding recurring renovation pipelines. Tampa and Orlando show elevated kitchen-bath demand from transplanted owner-occupants pursuing open-concept reconfigurations. Atlanta distributes materials to secondary markets across the coastal plain.
West Coast
California IECC energy code adoptions drive compliance-driven insulation and air-sealing pipelines. Los Angeles and San Francisco Bay Area contractors specialize in ADU construction from zoning liberalization. Seattle anchors cross-laminated timber specification for whole-home additions.
Northeast
New York and Massachusetts weatherization mandates create systematic renovation pipelines for envelope specialists. Greater Boston and New York Metro exhibit aging housing stock forcing structural upgrades to pre-1978 electrical and plumbing systems. EPA RRP certification filters concentrate eligible lead-safe renovators.
Mountain West
Denver and Salt Lake City markets show ADU construction acceleration from garage conversion zoning reforms. Colorado and Utah energy code cycles push window replacement specifications for thermal performance. Regional contractors face skilled electrician scarcity limiting electrification retrofit velocity.
US Home Remodeling Market Vendor Landscape
Player mix skews toward national homebuilders with affiliated remodeling arms and specialized direct-to-consumer platforms. Market structure shows moderate consolidation around vertically integrated operators with captive installation capacity. Strategic archetypes include builder-affiliated remodelers, catastrophic restoration specialists, and design-build integrators. Dominant competitive moves encompass geographic expansion into Sun Belt metros and portfolio diversification into electrification-ready retrofits.
Among national-scale operators, Power Home Remodeling and BELFOR Holdings Inc. exemplify divergent archetypes within the US market. Power Home Remodeling occupies a position as a direct-to-consumer platform targeting Millennial owner-occupants with pre-built sales infrastructure. BELFOR Holdings Inc. anchors catastrophic restoration volume that converts into recurring renovation pipelines. Lennar Corp. represents the builder-affiliated remodeling arm model, leveraging existing community footprints for cross-sell opportunities.
| Leading Market Players |
|---|
| Great Day Improvements LLC |
| PulteGroup |
| Power Home Remodeling |
| NVR |
| D.R. Horton |
| BELFOR Holdings Inc. |
| Lennar Corp. |
| Taylor Morrison |
| Leaf Home |
| Others |
Supply Flow & Price Mechanics
Engineered wood substitution for dimensional lumber redraws sourcing geography toward Pacific Northwest mill clusters while compressing price spreads between commodity stick-frame packages and premium structural systems. This displacement simultaneously elevates transport cost sensitivity for cross-laminated timber and rewards contractors with captive fabrication partnerships.
Pricing Analysis
Technology-generation pricing gaps separate legacy stick-frame construction from emerging mass timber systems and next-generation prefabricated panel assemblies. Project-based contracting dominates residential remodeling, with price differentiation driven by EPA RRP certification tier and vertical integration depth. Pricing pressure stems from Canadian softwood tariff exposure and domestic mill capacity constraints. Cost-sensitive speculative investors favor unbundled material procurement, while time-constrained owner-occupants absorb premium design-build pricing.
Supply Chain Analysis
Canadian border crossings at Blaine and Detroit anchor softwood lumber flows into US framing markets, creating chokepoint vulnerability to tariff policy shifts. Raw material dependencies center on British Columbia hemlock-fir, Oregon Douglas fir, and engineered wood adhesives. Single-source vulnerability concentrates in cross-border rail terminals serving West Coast and Midwest construction markets. Distribution runs through regional building material distributors with last-mile delivery to contractor yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies early-cycle expansion positioning as IRA energy credits penetrate Sun Belt housing stock and electrification retrofits accelerate contractor backlog formation.
For Market Incumbents: Consolidate installation capacity in Austin, Phoenix, and Tampa metros where electrification demand outstrips credentialed contractor supply. Acquire EPA RRP-certified lead-safe renovation specialists to capture pre-1978 housing interventions. Deepen backward integration into engineered wood fabrication to offset Canadian tariff exposure and secure structural material margins. For New Entrants and Emerging Players: EPA RRP certification fast-tracks entry into Northeast and Midwest pre-1978 housing corridors where lead-safe renovator scarcity concentrates project backlogs. Target accessory dwelling unit construction in Seattle, Denver, and Austin zoning liberalization zones. Deploy direct-to-consumer sales infrastructure to capture Millennial owner-occupant demand fragmentation. For Investors and Strategic Acquirers: The market sits at a capacity-constrained expansion phase that favors design-build integrators with captive installation networks. Long-term viability hinges on electrification-ready retrofit positioning and weatherization mandate compliance exposure. Monitor state-level IECC energy code adoption velocity as inflection indicator for insulation and air-sealing contractor valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| EPA RRP Certification Investment | Unlocks pre-1978 housing renovation pipelines in aging Northeast and Midwest markets. |
| Heat Pump Installation Capacity Buildout | Captures IRA tax credit-driven demand compression in Sun Belt electrification corridors. |
| Cross-Laminated Timber Fabrication Partnership | Reduces on-site labor hours and weather-dependent scheduling risk for whole-home additions. |
| Direct-to-Consumer Sales Platform | Targets Millennial owner-occupants lacking established contractor referral networks. |
| ADU Construction Specialization | Exploits zoning liberalization in Seattle, Denver, and Austin garage conversion markets. |
Methodological Framework
Desk research of municipal building permit databases, EPA enforcement records, and FERC grid-interconnection filings preceded structured interviews with general contractors, HVAC installation firms, building material distributors, and municipal building department officials. Primary fieldwork captured contractor capacity constraints, permit timeline compression, and electrification retrofit sequencing challenges. Secondary validation drew from OSHA safety violation datasets, state energy code adoption trackers, and lumber trade flow customs records. Bottom-up project-type demand modeling triangulated against top-down housing stock age demographics.
Variance decomposition across project type, material specification, and service delivery model shaped the analytical framework throughout the projection horizon. Segmentation dimensions encompassed kitchen-bath-addition-basement project scopes, wood-concrete-steel-glass material categories, design-construction-renovation-consultation service types, and homeowner-agent-contractor-investor end-user archetypes. CAGRs derived from housing stock aging curves, energy code adoption schedules, and IRA credit uptake velocity. Industry-specific forecast inputs included electrician and HVAC technician pipeline graduation rates and Canadian softwood tariff policy scenarios.
Underlying assumptions cover sustained IRA credit authorization, state-level IECC adoption continuity, and skilled labor scarcity persistence, with deviation risk concentrated in federal energy policy reversal and lumber trade war escalation. Practitioners should keep alternative scenarios live as grid-interconnection standards and municipal permitting capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
Home Remodeling Market
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
Global DIY Home Improvement Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
Vietnam Home Improvement Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
Automatic Curtain Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market