

Residential Interior Wood Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Interior Wood Doors Market Insights
The EU Timber Regulation is recalibrating sourcing standards across the residential interior wood doors supply chain, forcing manufacturers to document chain-of-custody compliance. JELD-WEN leverages its vertically integrated manufacturing footprint to control raw material provenance from forest to finish. Masonite anchors its competitive position through engineered wood expertise that reduces dependence on tropical hardwoods while meeting performance benchmarks. Simpson Door Company differentiates via FSC-certified product lines that command specification in green building projects.
Residential interior wood doors are factory-built or site-finished movable barriers installed within dwelling interiors, typically constructed with stile-and-rail joinery or monolithic cores ranging from 35mm to 45mm thickness, designed to provide privacy, acoustic separation, and aesthetic continuity between rooms. Panel doors occupy the largest volume share due to their adaptability across architectural styles and price tiers. Engineered wood is displacing solid wood in mid-market specifications as dimensional stability and moisture resistance improve, while flush doors lead in rental unit and multifamily applications where cost efficiency and speed of installation dominate procurement criteria.
The EPA regulates formaldehyde emissions in composite wood products through TSCA Title VI, directly affecting MDF and plywood core door manufacturing. The EU Ecodesign Framework and REACH restrictions on wood preservatives shape product chemistry and finishing protocols for doors entering European markets. Stakeholders must monitor evolving carbon border adjustment mechanisms and building code energy efficiency amendments that will increasingly fold interior material specifications into whole-home certification schemes.
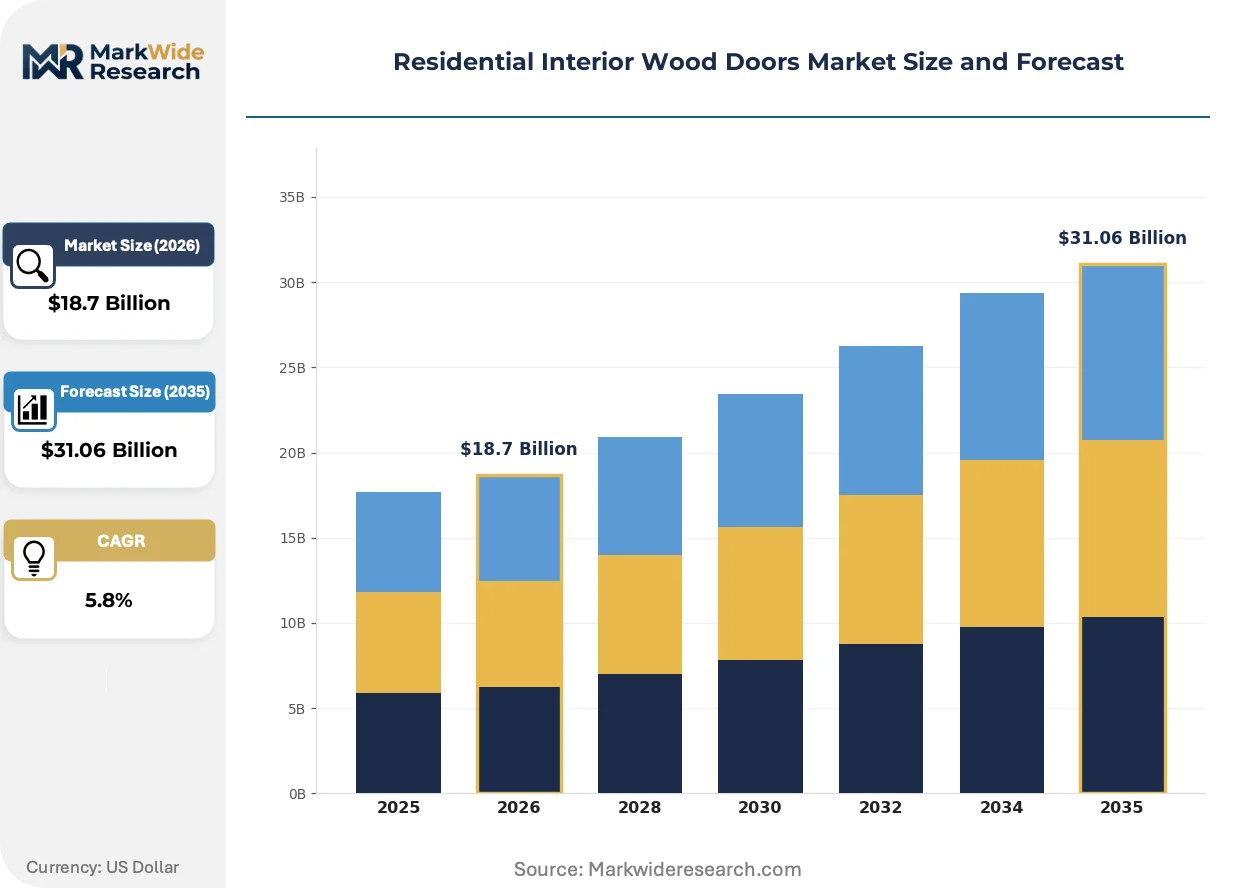
Market Dynamics
Engineered wood core technology is compressing traditional stile-and-rail construction timelines while EPA TSCA Title VI compliance costs filter through composite wood supply chains. Manufacturers must now balance dimensional stability gains against formaldehyde testing documentation burdens.
Growth Catalysts
- LEED Certification Mandates:North American green building codes specify FSC-certified interior doors in multifamily developments, pulling volume toward verified sustainable supply chains.
- China Residential Construction Recovery:Tier-1 city renovation waves favor premium wood door replacements as homeowners upgrade acoustic and thermal performance.
- Cross-Laminated Timber Integration:Mass timber building systems specify factory-finished interior doors with matching veneer species for aesthetic continuity.
Market Restraints
- Tropical Hardwood Sourcing Constraints:EU Timber Regulation chain-of-custody documentation raises compliance costs for solid wood panel door producers sourcing from Southeast Asia.
- MDF Core Resin Volatility:Urea-formaldehyde binder prices fluctuate with natural gas feedstock costs, squeezing mid-market flush door margins.
- Regional Mill Concentration:Softwood lumber supply concentrates in Pacific Northwest and Nordic regions, exposing door manufacturers to freight cost spikes.
Strategic Opportunities
- German Passive House Specification:Ultra-low-energy residential standards create demand for thermally broken door frames with triple-seal gasketing.
- Direct-to-Builder Digital Platforms:Configurator tools bypass traditional distributor markups in United States custom home segments.
- Carbon Border Adjustment Positioning:Early adopters of verified low-carbon engineered cores gain preference in EU public housing tenders.
Industry Challenges
- Certification Timeline Compression:FSC and PEFC audit backlogs delay product launches by four to six months for new door collections.
- Finish Chemistry Reformulation:REACH Annex XVII restrictions on certain wood preservatives force solvent-based coating line conversions.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Interior Wood Doors Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to redefine how interior wood doors are engineered, finished, and specified across residential construction tiers.
Moisture-resistant MDF substrates bonded with phenol-formaldehyde resins are unifying fire-rating and acoustic performance in a single core specification. United States multifamily developers specify these engineered cores for corridor-to-unit separation assemblies. The convergence compresses SKU proliferation while meeting ASTM E90 and E119 test requirements.
REACH restrictions on biocidal wood preservatives are forcing water-based coating system adoption across doors entering European markets. Finish manufacturers reformulate primers and topcoats to eliminate restricted active substances. German and French door fabricators face eighteen-month validation cycles for new coating chemistries.
Builder procurement teams consolidate interior door specifications across hundred-plus unit developments, replacing individualized homeowner selection with pre-curated palette systems. United States production homebuilders now specify three finish options maximum per elevation type. The compression reduces field variation claims and accelerates close-out timelines.
Residential Interior Wood Doors Market Segmentation
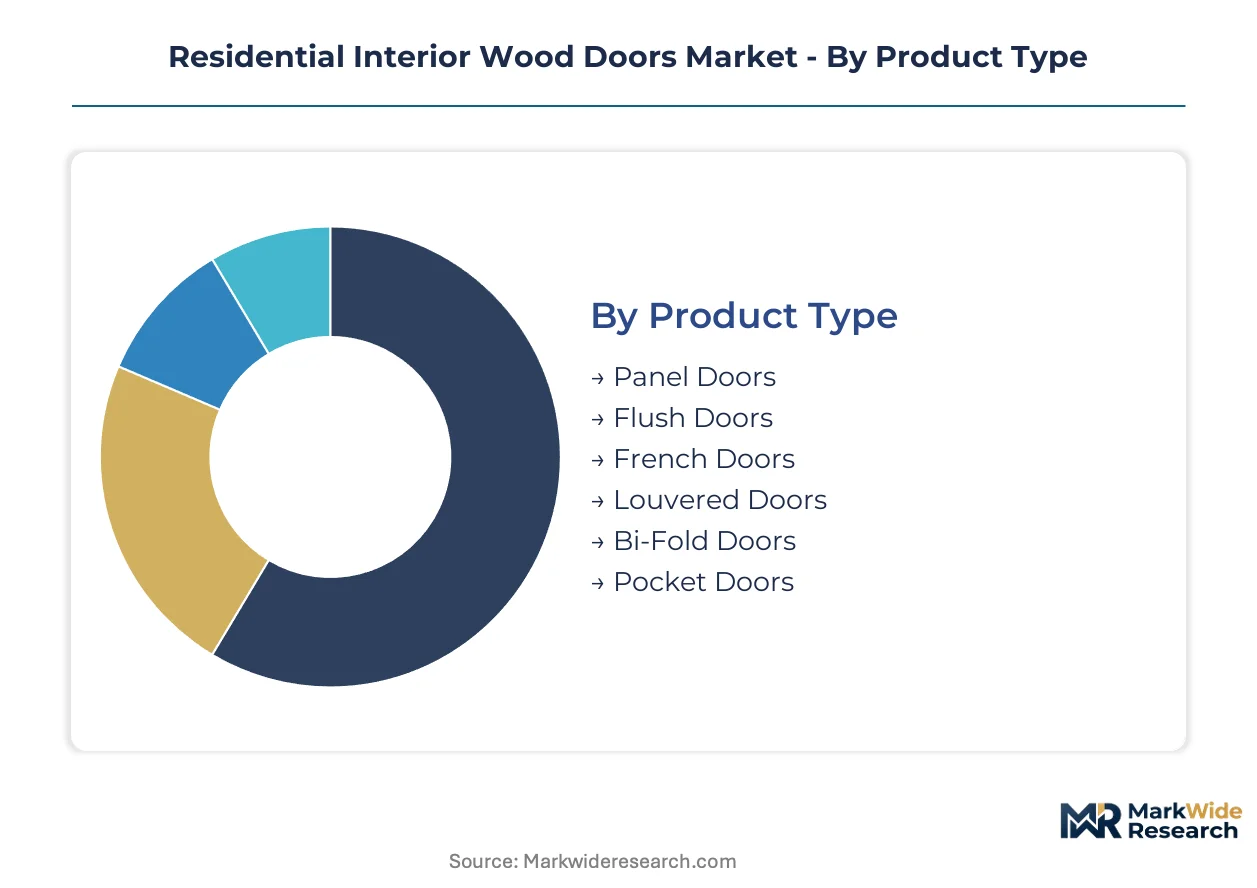
Residential interior wood doors fragment across four dimensions that each dictate distinct manufacturing footprints, certification requirements, and margin structures. Product type and material composition determine factory tooling investments, while application and end-user channels shape distribution economics and specification authority.
Product Type:
Supply concentration tilts toward high-volume, factory-finished formats that amortize capital equipment across predictable production runs.
- Panel Doors:Stile-and-rail joinery with raised or flat panels accommodates hollow-core or solid-core construction across 35mm to 45mm thicknesses. United States production homebuilders specify these for bedroom and bathroom separation in tract developments, with specification consolidation around three finish options per elevation type compressing SKU proliferation.
- Flush Doors:Monolithic slab construction with particleboard or MDF cores bonded to hardwood or softwood veneers offers dimensional stability superior to solid wood in humid climates. Rental unit and multifamily developers in China favor these for corridor-to-unit assemblies where fire-rating and acoustic performance converge in a single engineered specification.
- French Doors:Paired hinged panels with extensive glazing inserts require specialized joinery for glass retention and thermal break compatibility.
- Louvered Doors:Angled slat construction demands dedicated routing equipment for ventilation-oriented closet and utility applications.
- Bi-Fold Doors:Hinged panel pairs running on overhead tracks serve wardrobe and pantry openings with minimal swing clearance.
- Pocket Doors:Single panels sliding into wall cavities require precise jamb integration and structural framing coordination.
Panel doors absorb the bulk of installed capacity; flush doors are expanding most quickly.
Material:
Cost tier stratification separates premium solid wood from mid-market engineered alternatives, with raw material provenance now subject to escalating compliance documentation.
- Solid Wood:Traditional stile-and-rail construction from hardwood species including oak, maple, and cherry delivers acoustic mass and refinishing longevity. German and French custom builders specify these for heritage renovations, though EU Timber Regulation chain-of-custody requirements extend lead times by four to six months for Southeast Asian tropical hardwoods.
- Engineered Wood:Cross-laminated or finger-jointed substrates bonded with phenol-formaldehyde resins unify dimensional stability with moisture resistance. United States multifamily developers specify engineered cores for Passive House-aligned projects where thermal bridging constraints favor thermally broken frame integration.
- Veneer:Thin decorative hardwood layers over economical substrates provide aesthetic continuity at reduced material intensity.
- MDF:Medium-density fiberboard cores with urea-formaldehyde binders dominate economy flush door production, with resin costs tracking natural gas feedstock volatility.
- Plywood:Cross-banded veneer construction offers screw-holding strength for hardware-intensive applications.
- Composite Wood:Hybrid formulations combining wood fiber with synthetic binders target specific fire-rating or moisture-resistance benchmarks.
Engineered wood captures the largest production volume; composite wood formulations are climbing the fastest as carbon border adjustment mechanisms favor verified low-carbon cores.
Application:
Volume distribution follows residential construction cycles, with new construction and renovation waves operating on divergent procurement timelines and specification flexibility.
- New Construction:Production homebuilders and multifamily developers specify doors through master procurement agreements covering hundred-plus unit developments. United States builders consolidate specifications around pre-curated palette systems, eliminating individualized homeowner selection to accelerate close-out timelines.
- Remodeling Projects:Replacement demand concentrates in Tier-1 Chinese cities where homeowners upgrade acoustic and thermal performance in existing dwellings. Renovation specifications tolerate longer lead times for custom dimensions and specialty finishes unavailable in new construction procurement.
- Rental Units:Cost efficiency and durability dominate procurement criteria, with property managers prioritizing flush door formats for speed of installation and damage resistance.
- Vacation Homes:Seasonal occupancy patterns favor moisture-resistant engineered cores in coastal and mountain climates.
- Boutique Properties:Small-scale hospitality developers specify statement doors as interior design focal points.
- Custom Builds:Single-family architectural commissions accommodate bespoke dimensions, species selection, and hardware integration.
New construction commands the dominant share of factory throughput; custom builds are gaining share fastest as direct-to-builder digital platforms bypass traditional distributor markups.
End User:
Specification authority fragments across stakeholders with divergent priorities—design aesthetics, installed cost, durability, or compliance documentation.
- Homeowners:Individual purchasers exercising selection authority in renovation and custom build contexts, with preference consolidation around three finish options maximum per project type.
- Property Managers:Institutional owners of rental portfolios prioritizing lifecycle cost over first cost, with standardization across unit counts reducing field variation claims.
- Interior Designers:Specification professionals curating aesthetic continuity across material palettes, with FSC-certified lines commanding premium positioning in green building projects.
- Real Estate Developers:Volume purchasers negotiating master agreements for new construction, with LEED certification mandates pulling specifications toward verified sustainable supply chains.
- Contractors:Installation professionals influencing procurement through relationships with distributor and direct-manufacturer channels.
- Furnishers:Interior outfitters bundling doors with complementary millwork and hardware packages.
Real estate developers absorb the bulk of volume through consolidated procurement; interior designers are expanding their specification influence fastest as green building certification requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Charlotte, North Carolina anchors North American door manufacturing capacity, with clustered millwork operations serving the Southeast's residential construction surge. Production corridors in Germany's North Rhine-Westphalia and China's Pearl River Delta concentrate finishing expertise for premium export specifications.
United States
Production homebuilders in Texas and Florida drive volume through consolidated palette specifications, compressing SKU diversity to three finish options per elevation type. EPA TSCA Title VI enforcement tightens formaldehyde documentation for MDF-core doors entering multifamily developments. The Pacific Northwest softwood corridor supplies dimensionally stable substrates for engineered core production, though freight cost spikes expose margin pressure.
Germany
Passive House certification in Bavaria and Baden-Württemberg creates specification pull for thermally broken door frames with triple-seal gasketing. EU Ecodesign Framework amendments fold interior material specifications into whole-building energy calculations. The North Rhine-Westphalia millwork cluster concentrates factory-finished production for cross-border distribution into Benelux and France.
China
Tier-1 city renovation waves in Shanghai and Beijing favor premium wood door replacements as homeowners prioritize acoustic separation. The country's national building materials regulator enforces GB standards for formaldehyde emissions in composite wood products. The Pearl River Delta manufacturing corridor supplies moisture-resistant engineered cores for humid climate specifications across Southeast Asia.
France
Heritage renovation mandates in Paris and Lyon sustain demand for solid hardwood panel doors with documented chain-of-custody compliance. REACH Annex XVII restrictions on wood preservatives force eighteen-month validation cycles for new water-based coating chemistries. The Auvergne-Rhône-Alpes region hosts finish manufacturers reformulating primers to eliminate restricted active substances.
Residential Interior Wood Doors Market Competitive Landscape
The competitive structure tilts toward vertically integrated manufacturers controlling raw material provenance from forest to finish. Mid-scale specialists occupy specification niches through certified product lines, while regional fabricators compete on installation speed and distributor relationships. Two dominant competitive moves are reshaping positioning: backward integration into captive timber supply and direct-to-builder digital platform deployment that bypasses traditional distributor markups.
Among North American-based manufacturers, JELD-WEN, Masonite, and Simpson Door Company exemplify divergent strategic archetypes. JELD-WEN represents the vertically integrated model with controlled supply chain reach from forest operations through finishing facilities. Masonite occupies the engineered materials specialization tier, reducing tropical hardwood dependence through composite core expertise. Simpson Door Company anchors the sustainability-premium position, with FSC-certified product lines commanding specification authority in green building projects where LEED mandates pull procurement toward verified supply chains.
| Leading Market Players |
|---|
| JELD-WEN |
| Masonite |
| ASSA ABLOY |
| Pella Corporation |
| Simpson Door Company |
| TruStile Doors |
| Woodgrain Doors |
| Steves & Sons |
| Barausse |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FSC-verified premium lines and commodity-grade flush doors manifests in both margin structures and raw material sourcing configurations, with chain-of-custody documentation costs compressing mid-market pricing power while EPA TSCA Title VI compliance filters through composite wood supply tiers.
Pricing Analysis
Value-based pricing anchored in LEED certification outcomes commands specification premiums in North American multifamily developments, with FSC-certified lines separating from standard offerings through documented carbon intensity. Price differentiation rests on formaldehyde compliance grade and veneer species provenance. Pricing pressure intensifies in MDF-core segments as natural gas feedstock volatility squeezes binder costs. Production homebuilders exhibit highest price sensitivity through consolidated palette procurement, while custom builders tolerate premium positioning for heritage-grade solid wood.
Supply Chain Analysis
Direct-to-builder digital channels handle custom home segment demand, bypassing traditional distributor markups in United States residential construction. Geographic supply concentration centers on the Pacific Northwest softwood corridor, Nordic timber regions, and China's Pearl River Delta finishing cluster. Raw material dependencies draw from phenol-formaldehyde resin supply, tropical hardwood feedstock, and cross-laminated timber substrates. Single-source vulnerability concentrates in Southeast Asian hardwood documentation chains subject to EU Timber Regulation audit backlogs. Distribution runs through master procurement agreements for volume developers and specialty millwork distributors for renovation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive timber supply and in-house finishing capacity determine margin defense against resin cost volatility and certification timeline compression.
For Market Incumbents: Anchor competitive position through backward integration into controlled forest operations that secure FSC-certified feedstock independent of Southeast Asian documentation bottlenecks. Expand thermally broken frame manufacturing capacity in Germany's Passive House corridor to capture ultra-low-energy specification pull. Defend against engineered core commoditization by investing in phenol-formaldehyde resin hedging mechanisms. For New Entrants and Emerging Players: Direct-to-builder configurator platforms offer the most penetrable route into United States custom home segments where traditional distributor relationships remain underdeveloped. Target boutique property developers in Tier-1 Chinese cities seeking acoustic-upgrade renovation specifications with moisture-resistant engineered core offerings. Pursue carbon border adjustment positioning in EU public housing tenders as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by building materials conglomerates seeking millwork vertical integration. Long-term viability favors manufacturers with verified low-carbon core capabilities and digital specification tools. Acquisition target archetypes include regional fabricators with Passive House-certified product lines and established chain-of-custody documentation systems. Watch FSC audit backlog resolution timelines as the inflection signal for certification-constrained supply availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Timber Supply | FSC-certified forest operations insulate against EU Timber Regulation documentation delays and tropical hardwood sourcing constraints. |
| Digital Configurator Platform Deployment | Direct-to-builder tools bypass distributor markups in United States custom home segments where specification authority fragments. |
| Phenol-Formaldehyde Resin Hedging | Long-term binder supply agreements stabilize MDF-core margins against natural gas feedstock volatility in composite wood manufacturing. |
| Passive House Certification Investment | Thermally broken frame capabilities capture specification pull from Bavaria and Baden-Württemberg ultra-low-energy residential standards. |
| Water-Based Coating Line Conversion | REACH Annex XVII compliance positions European market entry against eighteen-month validation cycles facing solvent-based finish competitors. |
Research Methodology
Trade association filings, customs documentation, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with millwork procurement directors, plant operations managers, and green building specification consultants. Bottom-up and top-down triangulation validated volume estimates across product type and material composition segments.
Bottom-up modeling of factory throughput by product category anchored the analytical lens, with top-down construction spending allocation providing cross-check calibration across the projection horizon. Segmentation dimensions spanned product type, material composition, application context, and end-user specification authority. CAGRs derived from weighted average of historical volume trajectories and forward-looking regulatory impact coefficients, with engineered core adoption curves and certification penetration rates serving as primary forecast inputs.
The model holds under stable regulatory enforcement intensity and continued residential construction recovery; deviation in tropical hardwood trade restriction severity or natural gas feedstock disruption would shift volume and value trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.