
 Double-Hung Windows Market | 2026-2036
Double-Hung Windows Market Size, Share, and Industry Trends Forecast 2026-2036
Double-Hung Windows Market Insights
Vietnam is narrowing its cost advantage as a fabrication hub for North American window suppliers, yet domestic U.S. production retains edge in custom sizing and rapid fulfillment. Andersen Corporation leverages vertical integration from extrusion to final assembly, sustaining tighter quality control across its fiberglass and composite lines. Pella Corporation anchors its position through captive distribution, while Marvin Windows and Doors specializes in premium architectural-grade wood systems for heritage restoration projects.
Double-hung windows incorporate two operable sashes that slide vertically within a single frame, typically achieving U-factors between 0.20 and 0.30 through dual-pane low-emissivity glazing and warm-edge spacer systems; this design maximizes ventilation control while preserving wall space for interior furnishings. Vinyl material dominates volume production due to injection-molded scalability and minimal maintenance requirements, though fiberglass commands the strongest margin pool among premium residential applications. Replacement installation now outpaces new construction as the largest channel, reflecting the aging stock of single-family homes built during prior housing booms.
Energy Star certification administered by the EPA and the Department of Energy establishes minimum thermal performance benchmarks that filter non-compliant products from federally backed mortgage channels. NFRC labeling requirements provide standardized U-factor and solar heat gain coefficient disclosures that shape consumer comparison shopping and contractor specification habits. State-level stretch codes in California and Massachusetts extend beyond federal baselines, creating a bifurcated compliance landscape that rewards manufacturers with flexible product platforms. Stakeholders must monitor whether emerging federal appliance efficiency standards expand to cover advanced glazing configurations.
Market Dynamics
Retrofit demand in aging U.S. suburban housing stocks is compressing replacement cycles and forcing manufacturers to reconfigure fulfillment networks around custom sizing and rapid turnaround.
Growth Catalysts
- EPA Energy Star Certification:The EPA's fenestration performance thresholds filter non-compliant products from federally backed mortgage channels. Lenders now require documented U-factors below 0.30 for refinancing eligibility.
- Fiberglass Composite Adoption:Pultruded fiberglass frames deliver thermal expansion coefficients matching glass units. High-end residential builders specify these systems for coastal humidity zones.
- Southeastern U.S. Replacement Cycles:Humidity-driven vinyl degradation in Florida, Georgia, and the Carolinas shortens functional window lifespans. Contractors report 12-15 year replacement intervals versus 20-25 years in arid climates.
Market Restraints
- Raw Material Cost Volatility:PVC resin prices fluctuate with ethylene feedstock costs tied to Gulf Coast petrochemical capacity. Window fabricators absorb margin compression when resin spikes coincide with fixed-price retrofit contracts.
- Vietnamese Fabrication Concentration:North American suppliers rely on Ho Chi Minh City extrusion partners for standard vinyl profiles. Shipping delays through the Panama Canal extend lead times by 6-8 weeks.
- Wood Frame Substitution Threat:Heritage restoration projects specify mahogany and Douglas fir for architectural authenticity. Premium wood systems capture margin pools that fiberglass cannot penetrate.
Strategic Opportunities
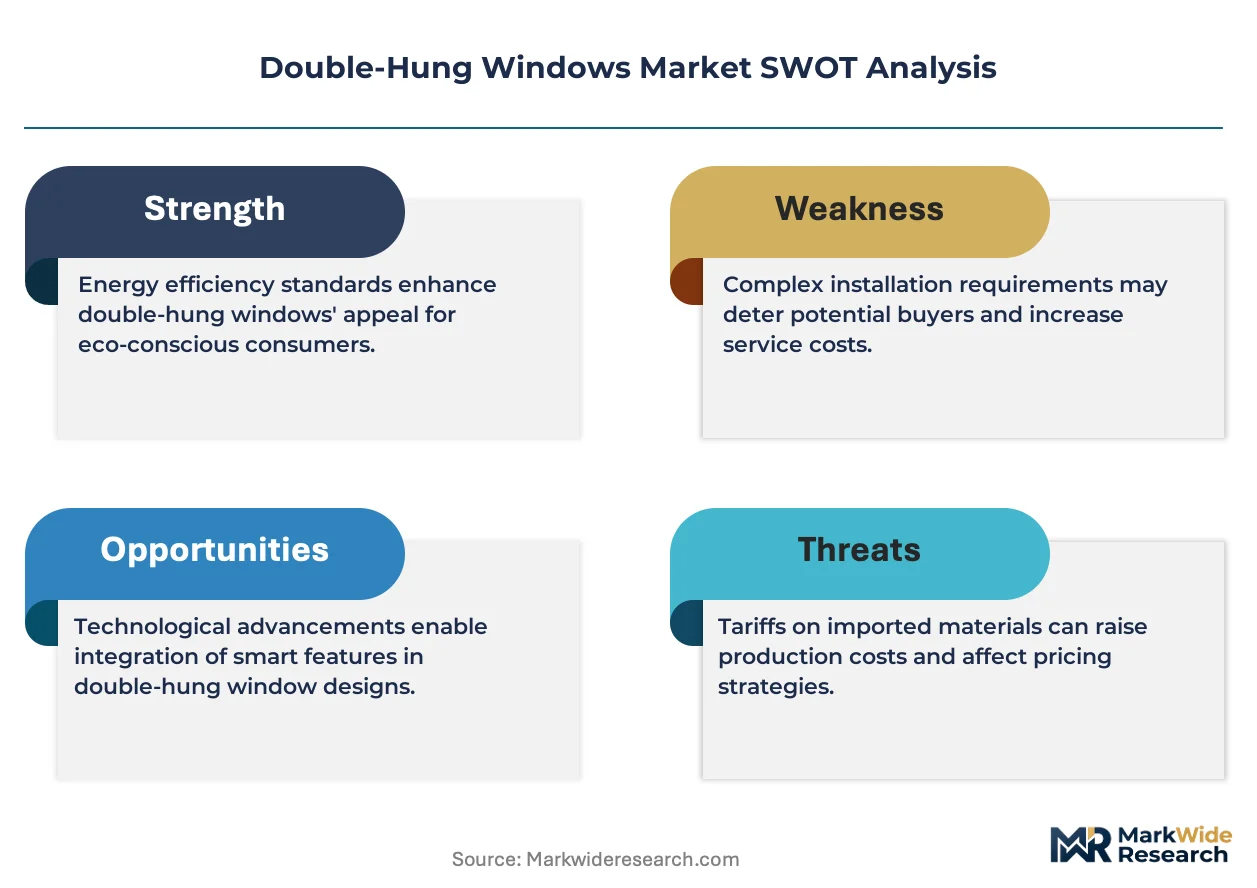
- Massachusetts Stretch Code Expansion:The state's net-zero building mandate requires U-factors below 0.20 for all replacement windows. Manufacturers with triple-pane platforms capture this high-performance segment.
- Smart Glass Convergence:Electrochromic glazing integration with double-hung sashes enables dynamic solar heat gain control. Early deployments target luxury residential towers in Miami and Austin.
- Direct-to-Contractor Digital Channels:Configurator platforms bypass traditional distributor markups. Independent installers in Texas and Arizona now source 30% of volume through manufacturer portals.
Industry Challenges
- NFRC Certification Timeline:New glazing configurations require 90-120 day laboratory validation before Energy Star eligibility. Product development cycles stretch to 18 months for complex warm-edge spacer systems.
- Installation Labor Scarcity:Skilled carpenters capable of heritage-grade wood window restoration command premium wages. Training pipelines have not scaled to match restoration demand in New England.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double-Hung Windows Market |
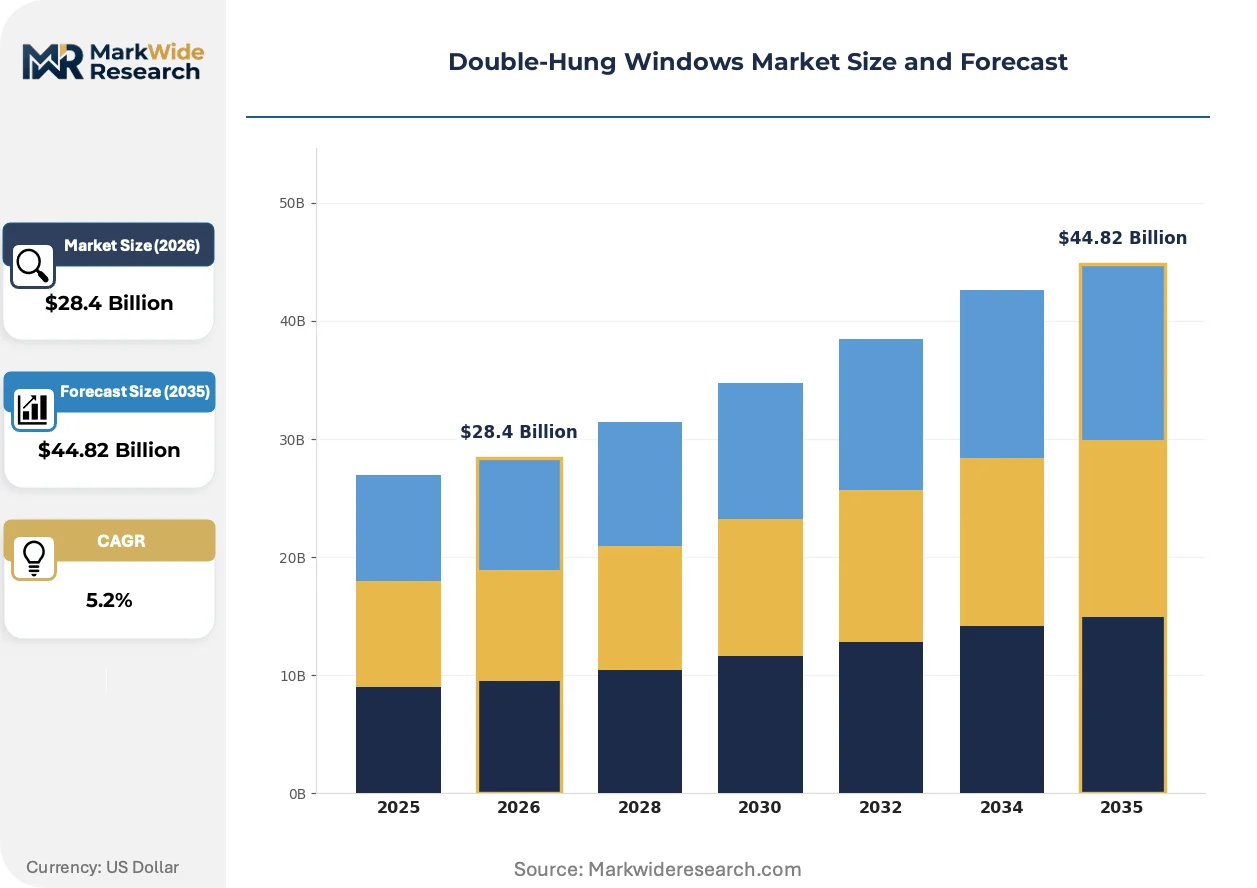
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $44.82 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Vinyl, Aluminum, Fiberglass, Composite Installation Type: New Construction, Replacement, Retrofit, Modular, Custom Fit Application: Residential Buildings, Commercial Complexes, Educational Facilities, Government Institutions, Hospitality Venues Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesale Distributors, Specialty Dealers |
| Companies Covered | Andersen Corporation, Pella Corporation, Marvin Windows and Doors, JELD-WEN, Simonton Windows & Doors, Milgard Windows and Doors, Kolbe Windows and Doors, Harvey Building Products, PGT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double-Hung Windows Market Trends and Innovations
Digital configuration tools and performance-grade materials are compressing the gap between custom architectural specifications and mass-market fulfillment speed.
Integrated sensor arrays embedded in window frames are virtualizing the traditional site-measurement workflow. High-volume replacement contractors deploy laser-scanning apps that transmit rough-opening dimensions directly to fabrication scheduling systems. This compression eliminates measurement errors that previously drove 15% of remake orders.
California's Title 24 building energy code now mandates solar heat gain coefficients below 0.23 for all residential replacements. Manufacturers must redesign product platforms to meet this threshold without sacrificing visible light transmission. The compliance burden falls heaviest on vinyl-dominant suppliers lacking low-emissivity coating partnerships.
Homeowners increasingly unbundle window procurement from installation services. Big-box retailers capture specification traffic through in-store digital kiosks, then refer fulfillment to certified local installers. This channel fragmentation is most advanced in Arizona and Nevada, where consumer price transparency tools have eroded traditional contractor markup structures.
Double-Hung Windows Market Segmentation
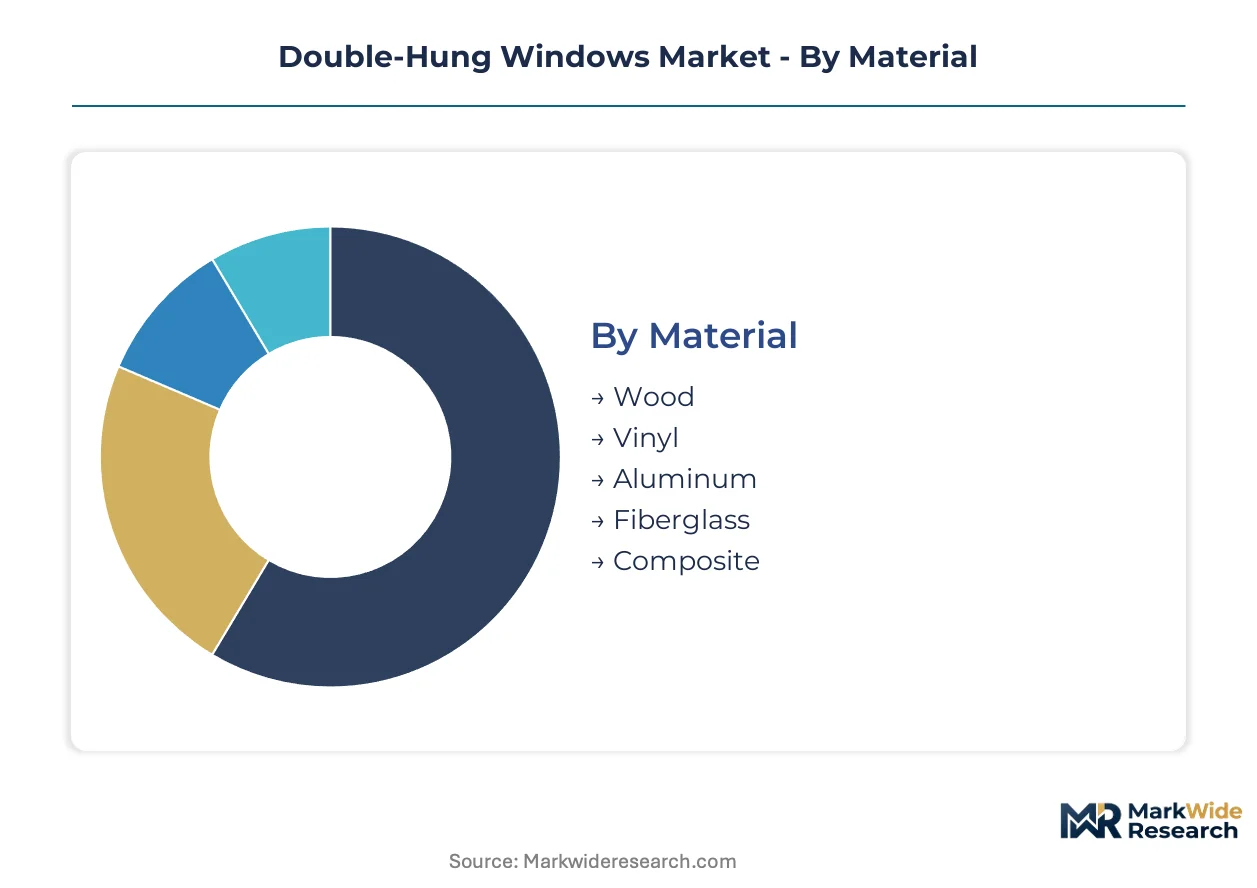
Material selection dictates thermal performance thresholds and maintenance obligations across the double-hung windows market. Installation type segmentation reveals channel profitability differences, while application and distribution dimensions expose where specification authority concentrates.
Material:
After-sales service intensity varies sharply by frame substrate, with wood demanding periodic refinishing and vinyl requiring minimal intervention.
- Vinyl:Injection-molded PVC profiles dominate volume production through scalable extrusion processes. Demand concentrates in Southeastern U.S. suburban retrofits where humidity-driven replacement cycles compress intervals to 12-15 years.
- Fiberglass:Pultruded composite frames match glass thermal expansion coefficients for superior seal longevity. High-end residential builders in Florida coastal zones specify these systems for moisture resistance and dimensional stability.
- Wood:Solid timber frames serve heritage restoration projects requiring architectural authenticity. Mahogany and Douglas fir systems command premium positioning in New England preservation markets.
- Aluminum:Thermally broken extrusions deliver structural strength for commercial facades. Anodized finishes suit mid-rise buildings in arid Southwestern climates.
- Composite:Engineered wood-polymer blends balance aesthetics with moisture resistance. Emerging adoption targets transitional climate zones seeking wood appearance without rot vulnerability.
Vinyl holds the largest share; momentum sits with fiberglass.
Installation Type:
Cost tier stratification separates turnkey contractor services from self-directed homeowner procurement.
- Replacement:Full-frame removal and insertion dominates current volume as aging U.S. housing stock drives retrofit activity. Independent installers in Texas and Arizona now source 30% of volume through manufacturer direct portals.
- Retrofit:Insert window installation preserves existing frames for faster turnaround. Massachusetts net-zero mandates push this segment toward triple-pane configurations.
- New Construction:Rough-opening specifications align with builder production schedules. Volume correlates with single-family housing permit activity in Sun Belt metros.
- Custom Fit:Non-standard dimensions serve historical renovations requiring site-specific fabrication. Lead times extend 6-8 weeks when sourcing from Vietnamese extrusion partners.
- Modular:Pre-assembled wall-integrated units accelerate multi-family project timelines. Factory-sealed glazing eliminates field installation variables.
Replacement commands the largest share; retrofit is climbing the fastest.
Application:
Volume concentration in residential retrofits obscures specification complexity differences across building types.
- Residential Buildings:Single-family homes drive the preponderance of unit demand. EPA Energy Star certification filters non-compliant products from federally backed mortgage channels.
- Commercial Complexes:Office and retail facades prioritize U-factor performance over operational aesthetics. California Title 24 mandates solar heat gain coefficients below 0.23 for compliance.
- Educational Facilities:K-12 and university projects emphasize durability under institutional use cycles. State procurement protocols favor NFRC-labeled products with documented thermal performance.
- Government Institutions:Federal and municipal buildings follow GSA specification standards. Compliance documentation requirements extend procurement timelines.
- Hospitality Venues:Hotels and resorts balance guest comfort with operational energy costs. Miami and Austin luxury towers pilot electrochromic glazing integration.
Residential Buildings holds the largest share; Commercial Complexes show steepest expansion trajectory.
Distribution Channel:
Customer type fragmentation separates professional contractors from end-user specification behavior.
- Direct Sales:Manufacturer-to-contractor relationships bypass distributor markups. Configurator platforms enable 48-hour quoting for standard dimensions.
- Wholesale Distributors:Regional stocking locations serve mid-sized installation contractors. Inventory depth determines contractor loyalty in volatile resin price environments.
- Specialty Dealers:Showroom-based consultation supports premium product selection. Captive distribution networks anchor Pella Corporation's market position.
- Retail Stores:Big-box kiosks capture consumer traffic for referral to certified installers. Channel fragmentation is most advanced in Arizona and Nevada markets.
- Online Platforms:Digital specification tools transmit rough-opening dimensions to fabrication systems. Laser-scanning apps eliminate measurement errors driving historical remake orders.
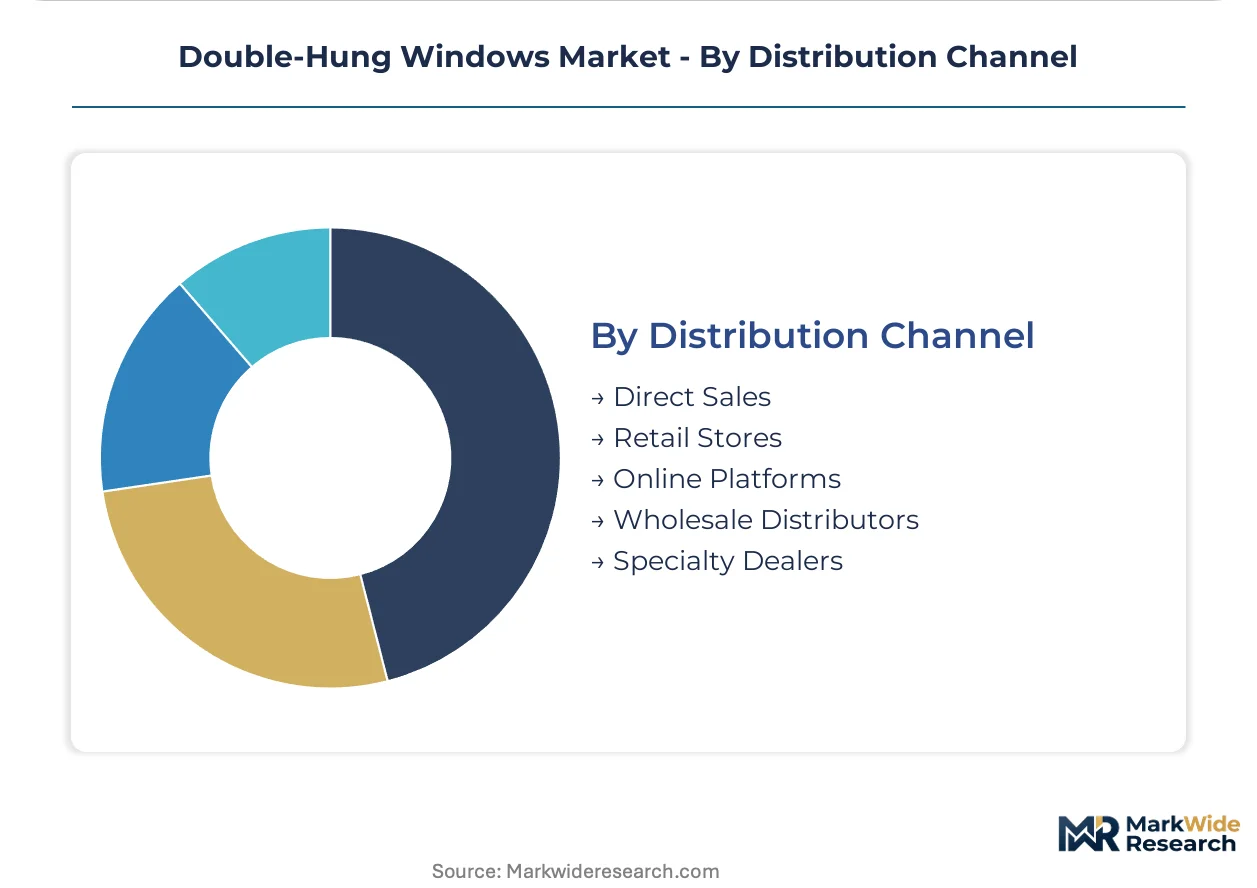
Wholesale Distributors holds the largest share; Online Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion capacity clusters in the United States, Vietnam, and China serve distinct tiers of the North American replacement market. Domestic fabricators dominate custom sizing and rapid fulfillment, while Asian partners handle standardized vinyl profile production.
United States
Retrofit demand in aging suburban housing stocks compresses replacement cycles across the Sun Belt. The EPA's Energy Star certification filters non-compliant products from federally backed mortgage channels. Installation contractors in Florida and Georgia report 12-15 year replacement intervals driven by humidity-driven vinyl degradation.
Vietnam
Ho Chi Minh City extrusion partners supply standard vinyl profiles to North American window fabricators. Shipping delays through the Panama Canal extend lead times by 6-8 weeks during peak seasons. Vietnamese producers are narrowing their cost advantage as domestic logistics and labor costs rise.
China
Glass processing and spacer system manufacturing concentrate in the Yangtze River Delta. The country's national building materials regulator enforces thermal performance disclosure standards for exported fenestration components. Zhejiang and Jiangsu provinces host low-emissivity coating facilities serving global window assemblers.
Canada
Cold-climate U-factor requirements drive specification of triple-pane configurations in Ontario and Quebec. Health Canada's energy efficiency regulations align with federal mortgage insurance programs. Toronto-area distributors stock deeper inventories of high-performance frames to serve cross-border replacement demand.
Mexico
Nuevo León and Baja California fabrication plants supply vinyl profiles to southwestern U.S. contractors. The country's national standards body certifies thermal performance for cross-border window shipments. Monterrey-based extruders benefit from proximity to Texas replacement markets and reduced shipping complexity.
Double-Hung Windows Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying extrusions, hardware, and glazing packages. The vendor base separates into three tiers: vertically integrated national brands, regional fabricators with captive distribution, and import-dependent assemblers. Two strategic archetypes dominate: manufacturers controlling extrusion-to-assembly workflows, and specialists outsourcing fabrication while owning local installation relationships. Consolidation pressure is accelerating through distributor acquisitions and direct-to-contractor digital channel investments.
Among North American fabricators, Andersen Corporation and Pella Corporation exemplify contrasting platform strategies, while Marvin Windows and Doors occupies a position in premium architectural-grade wood systems. Andersen represents the vertically integrated archetype with in-house extrusion capabilities. Pella exemplifies captive distribution networks that bypass wholesale markups. Marvin anchors the heritage restoration segment where specification authority concentrates with preservation architects. These three firms collectively illustrate how material specialization and channel control define competitive positioning in residential fenestration.
| Leading Market Players |
|---|
| Andersen Corporation |
| Pella Corporation |
| Marvin Windows and Doors |
| JELD-WEN |
| Simonton Windows & Doors |
| Milgard Windows and Doors |
| Kolbe Windows and Doors |
| Harvey Building Products |
| PGT |
| Others |
Pricing and Supply Chain Analysis
Panama Canal transit costs and scheduling volatility directly compress margin pools for North American window fabricators sourcing standardized vinyl profiles from Southeast Asia, while domestic producers leverage proximity to command premium positioning in custom sizing segments where buyers prioritize rapid fulfillment over unit cost.
Pricing Analysis
EPA Energy Star certification dictates the pricing tier structure across the double-hung windows market, separating compliant products eligible for federally backed mortgage channels from lower-performance alternatives. Three-tier pricing structure across premium, standard, and economy levels aligns with U-factor performance thresholds, with triple-pane fiberglass systems commanding the highest tier. Cost compression in the standard vinyl tier intensifies because Vietnamese fabrication partners face rising domestic logistics expenses. Retrofit contractors represent the most price-sensitive buyer segment, while heritage restoration architects demonstrate minimal sensitivity to unit cost.
Supply Chain Analysis
Ethylene feedstock derived from Gulf Coast petrochemical capacity anchors raw material costs for PVC resin production, with secondary concentration in Ho Chi Minh City extrusion facilities and Yangtze River Delta glass processing centers. Window fabrication draws from PVC resin, low-emissivity coated glass, and warm-edge spacer systems as core inputs. Single-source vulnerability concentrates in Vietnamese standard profile supply, where shipping delays through the Panama Canal extend lead times. Distribution runs through wholesale distributors serving regional contractor networks, with direct-to-contractor digital channels gaining fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Massachusetts stretch code expansion and California Title 24 mandates are reshaping competitive positioning by filtering non-compliant products from high-value replacement channels and forcing rapid product platform redesign.
For Market Incumbents: Build certification moats by accelerating triple-pane platform development to capture Massachusetts net-zero mandate compliance and deepening captive distribution networks to bypass wholesale markups. Wood frame substitution threats from heritage restoration projects require defending fiberglass margins through pultruded composite thermal performance differentiation. For New Entrants and Emerging Players: Pursue direct-to-contractor digital channel penetration in Texas and Arizona markets where independent installers now source substantial volume through manufacturer portals. Smart glass convergence in Miami and Austin luxury towers offers the most penetrable white-space target, with electrochromic glazing integration as the specific go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from vertically integrated national brands seeking to divest non-core regional fabrication assets. Long-term viability centers on manufacturers controlling extrusion-to-assembly workflows with flexible product platforms spanning multiple state-level stretch codes. Monitor NFRC certification timeline extensions as the inflection indicator signaling product development cycle strain.| Strategic Initiative | Industry Significance |
|---|---|
| Triple-Pane Platform Expansion | Massachusetts net-zero mandates require U-factors below 0.20 for replacement eligibility. |
| Direct-to-Contractor Digital Channel Investment | Texas and Arizona installers now source 30% of volume through manufacturer portals. |
| Electrochromic Glazing Integration | Miami and Austin luxury towers pilot dynamic solar heat gain control systems. |
| Captive Distribution Network Acquisition | Pella Corporation's showroom-based consultation model anchors premium positioning. |
| Vietnamese Fabrication Partnership Restructuring | Ho Chi Minh City extruders face narrowing cost advantage from rising domestic logistics. |
Research Methodology
A spread of perspectives from fenestration product managers, EPA certification specialists, independent installation contractors, and wholesale distribution executives converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against NFRC labeling databases, Energy Star certification registries, state building code filings, and customs trade records. Bottom-up unit demand modeling and top-down construction spending allocation were triangulated for cross-verification.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by material substrate, installation type, application building category, and distribution channel. CAGRs were derived from replacement cycle compression trends in humidity-exposed climates and new construction permit trajectories in Sun Belt metros. Industry-specific inputs included EPA Energy Star threshold revisions and state-level stretch code adoption schedules.
Macroeconomic conditions sit as an overlay; deviation in residential mortgage rates, single-family housing starts, and Gulf Coast petrochemical capacity utilization would shift the trajectory. Forecasts reflect documented assumptions about replacement interval compression and certification compliance timelines. Cross-checking against state building permit databases and NFRC product certification listings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
Global DIY Home Improvement Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
Bays and Bows Window Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
Automatic Curtain Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
Vietnam Home Improvement Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Home Remodeling Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market