
 Vietnam Home Improvement Market | 2026-2036
Vietnam Home Improvement Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Home Improvement Market Analytics
Vietnam is fragmenting its home improvement supplier base as provincial manufacturing zones in Binh Duong and Dong Nai expand tile, sanitary ware, and metal fixture capacity. LIXIL Vietnam leverages its Japanese-engineered production lines to dominate premium bathroom segments in Ho Chi Minh City. Viglacera Corporation anchors the northern market with integrated ceramic and glass manufacturing at Phu Ly and Mong Cai. Eurowindow differentiates through aluminum-window systems engineered for Vietnam's tropical monsoon climate.
Home improvement encompasses the alteration, repair, and aesthetic upgrading of residential structures through replacement of surfaces, fixtures, and functional systems, typically involving moisture-resistant coatings with VOC content below 50 g/L, termite-treated timber flooring with 12-18mm wear layers, and LED lighting modules rated IP44 or higher for humid environments. Its primary commercial purpose is to extend building service life while elevating property resale value and occupant comfort. Paint and flooring together capture the deepest margin pools, as homeowners prioritize visible transformation over concealed infrastructure. DIY installation is gaining share among urban apartment owners with sub-100-square-meter units, though professional renovation retains dominance in villa and townhouse projects where structural modifications trigger building-code compliance requirements.
Vietnam's Ministry of Construction enforces QCVN construction standards that mandate fire-retardant ratings for interior finishes in high-rise residential towers, directly elevating demand for certified metal and glass products. BIS-equivalent conformity assessment procedures for imported building materials create compliance barriers that favor domestic manufacturers with established testing laboratory relationships. Stakeholders must monitor how forthcoming amendments to the National Technical Regulation on Building Materials affect cross-border sourcing strategies and local certification timelines.
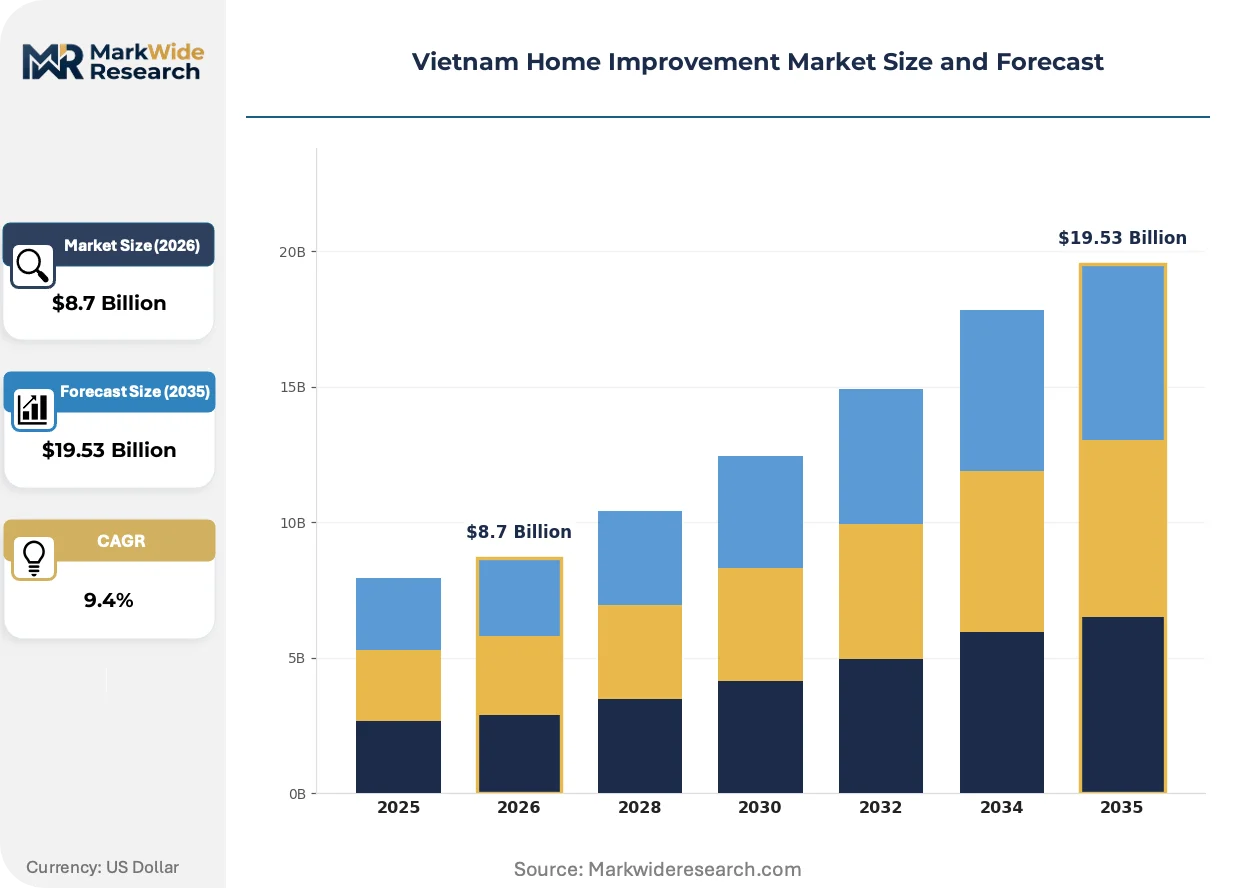
Market Dynamics
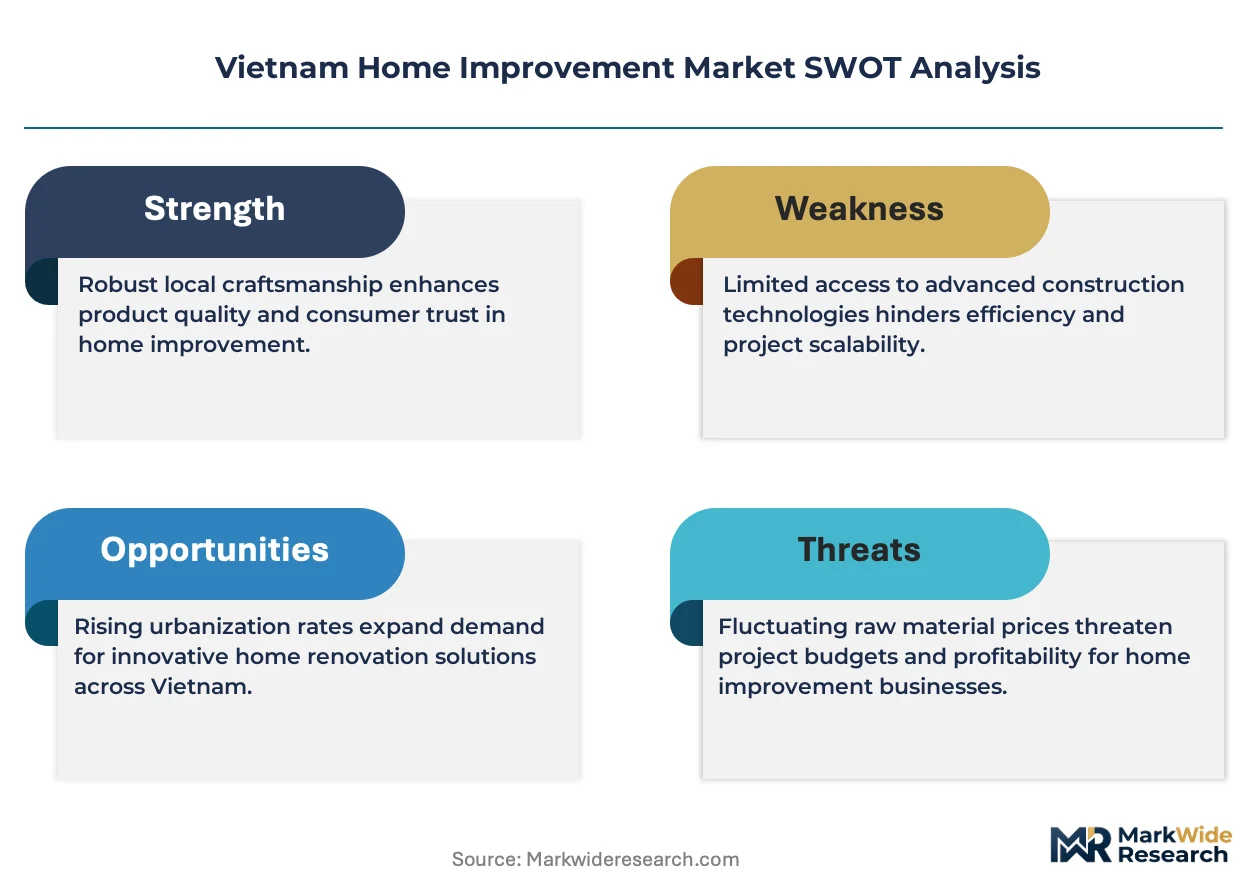
Urbanization in Vietnam's Red River Delta and Southeast regions is compressing renovation cycles as condominium dwellers replace fixtures before structural fatigue mandates full rebuilds, tightening the link between disposable income trajectories and replacement demand timing.
Growth Catalysts
- QCVN Fire-Retardant Mandates:Vietnam's Ministry of Construction enforces certified metal and glass specifications in high-rise towers, elevating demand for tested interior finishes that comply with national technical regulations.
- LED Module IP44 Adoption:Humidity-rated lighting systems penetrate apartment bathrooms and kitchens as homeowners prioritize moisture-resistant electrical infrastructure over conventional fixtures.
- Red River Delta Income Concentration:Rising household purchasing power in Hanoi and surrounding provinces concentrates renovation spending on premium kitchen and bathroom upgrades.
Market Restraints
- Imported Material Compliance Friction:BIS-equivalent conformity assessment procedures for cross-border building materials create certification delays that favor domestic manufacturers with established laboratory relationships.
- Timber Input Cost Volatility:Termite-treated flooring with 12-18mm wear layers faces price pressure from raw lumber supply fluctuations and chemical treatment input costs.
- DIY Skill Ceiling:Structural modifications in villa and townhouse projects trigger building-code compliance requirements that force professional contractor engagement, limiting homeowner self-execution.
Strategic Opportunities
- Dong Nai-Binh Duong Manufacturing Zones:Provincial expansion of tile, sanitary ware, and metal fixture capacity creates captive supply bases for contractors serving Ho Chi Minh City demand.
- VOC-Sub-50 g/L Coating Transition:Low-emission paint formulations capture margin pools as environmental consciousness shifts specification preferences among urban renovators.
- Monsoon-Engineered Window Systems:Aluminum framing designed for tropical climate performance addresses unmet needs in coastal provinces where standard products fail prematurely.
Industry Challenges
- Certified Installer Scarcity:Shortage of technicians trained in fire-retardant material installation and QCVN compliance documentation slows project completion timelines.
- Supply Chain Reconfiguration Costs:Shifting from imported to domestic certified materials requires supplier relationship rebuilding and testing protocol investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Home Improvement Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paint, Flooring, Lighting, Fixtures Customer Type: Homeowners, Contractors, Retailers, Builders Installation Type: DIY, Professional, Semi-Professional, Renovation Material: Wood, Metal, Glass, Plastic |
| Companies Covered | LIXIL Vietnam, Viglacera Corporation, Eurowindow, TOTO Vietnam, Austdoor Group, Hoa Phat Group, AkzoNobel (Dulux), Coteccons, SCG Vietnam, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Home Improvement Market Evolving Landscape
Digital tools and climate-adaptive specifications are compressing design-to-installation timelines while regulatory pressure on material safety is elevating certified product premiums across Vietnam's renovation value chain.
Building information modeling software is digitizing renovation planning for urban apartment owners with sub-100-square-meter units. Younger homeowners in Ho Chi Minh City adopt 3D visualization platforms to preview kitchen and bathroom layouts before contractor engagement. This compression of decision cycles is digitizing traditional showroom-dependent purchase patterns and accelerating fixture selection velocity.
Vietnam's QCVN construction standards amendments are tightening fire-retardant rating requirements for interior finishes in residential towers above six stories. The Ministry of Construction's technical regulations now mandate third-party testing documentation for metal and glass products used in common areas. High-rise developers in Hanoi are responding by pre-specifying certified materials in tender packages to avoid construction delays.
Urban renovators are unbundling design and installation services that were historically packaged by general contractors. Apartment owners in the Red River Delta now engage independent designers through digital platforms before sourcing fixtures directly from Binh Duong manufacturers. This disintermediation is most visible among Hanoi condominium dwellers renovating 70-90 square meter units on compressed timelines.
Vietnam Home Improvement Market Segmentation
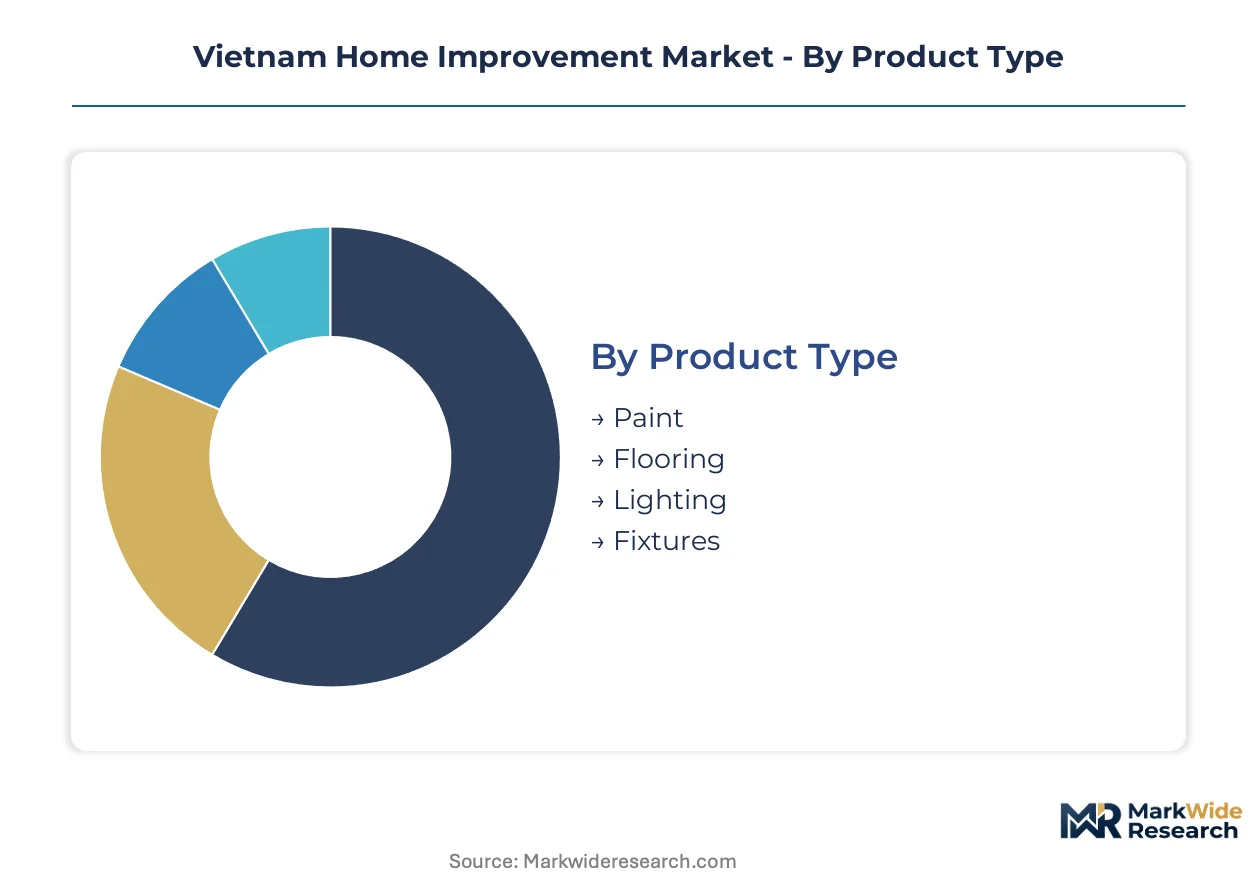
Segmentation in Vietnam's home improvement market reveals how purchasing decisions split across technical specifications, installation capabilities, and regulatory compliance requirements. Understanding these divides allows suppliers to align inventory and certification investments with actual demand concentration.
Product Type:
Cost tier separates visible transformation products from concealed infrastructure, with premium margins clustering where homeowners seek immediate aesthetic impact.
- Paint:Low-VOC formulations below 50 g/L dominate urban specifications as Hanoi and Ho Chi Minh City renovators prioritize indoor air quality. Red River Delta disposable income growth is accelerating specification upgrades from economy to premium emulsion grades.
- Flooring:Termite-treated timber with 12-18mm wear layers commands the deepest margin pool through visible transformation and tactile quality perception. Dong Nai and Binh Duong manufacturing zones are expanding laminate and engineered wood capacity to serve this demand.
- Lighting:IP44-rated LED modules penetrate apartment bathrooms and kitchens where humidity resistance is non-negotiable.
- Fixtures:Sanitary ware and metal hardware face QCVN fire-retardant compliance mandates in high-rise residential towers.
Paint holds installed capacity. Flooring is rotating up the share rankings.
Customer Type:
Application context dictates procurement behavior, with project scale and regulatory exposure determining whether buyers prioritize price, speed, or compliance documentation.
- Homeowners:Sub-100-square-meter apartment owners in Ho Chi Minh City increasingly self-source fixtures after independent designer engagement, compressing traditional contractor margins. Digital visualization tools accelerate their decision velocity before physical showroom visits.
- Contractors:Professional renovation firms retain dominance in villa and townhouse projects where structural modifications trigger QCVN compliance requirements and certified installer documentation.
- Retailers:Provincial distributors in the Red River Delta corridor aggregate demand from smaller contractors and direct homeowners, creating buffer inventory positions.
- Builders:High-rise developers in Hanoi pre-specify certified materials in tender packages to avoid construction delays from testing documentation gaps.
Contractors hold installed capacity. Homeowners are rotating up the share rankings.
Installation Type:
Skill ceiling and regulatory exposure create sharp boundaries between self-execution and professional engagement, with semi-professional hybrids emerging in mid-market segments.
- DIY:Urban apartment owners with compact units leverage online tutorials and 3D planning tools for fixture replacement without structural modification. This segment concentrates in Ho Chi Minh City's younger homeowner demographic.
- Professional:Full-service renovation retains dominance where QCVN compliance documentation, fire-retardant material installation, and structural engineering are mandatory. Certified installer scarcity currently constrains project completion timelines.
- Semi-Professional:Hybrid approaches emerge where homeowners self-source materials before engaging technicians for regulated installation phases.
- Renovation:Comprehensive project types encompassing multiple product categories and installation methods, typically triggered by property resale preparation or lease turnover.
Professional installation holds installed capacity. DIY is rotating up the share rankings.
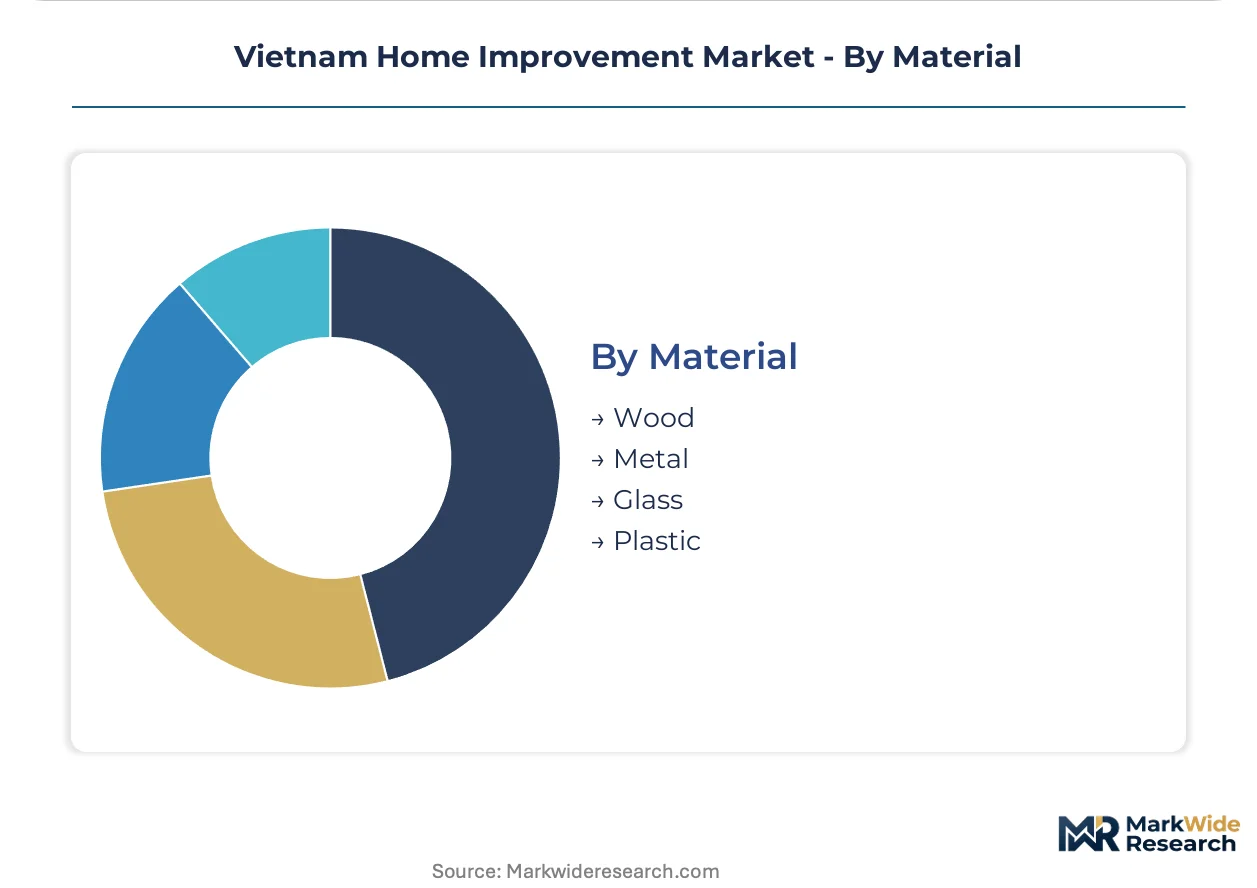
Material:
Supply concentration and import dependency shape competitive dynamics, with domestic manufacturing expansion in key categories reducing certification friction.
- Wood:Termite-treated timber faces raw lumber price volatility and chemical treatment input cost pressure. Domestic plantation supply from central highland provinces is expanding to reduce import dependency.
- Metal:Fire-retardant rated aluminum and steel products benefit from QCVN mandate enforcement in high-rise towers. Viglacera Corporation and provincial manufacturers in Phu Ly are expanding certified metal fixture capacity.
- Glass:Tempered and laminated variants for windows and interior partitions require third-party testing documentation under Ministry of Construction technical regulations.
- Plastic:PVC and composite materials serve moisture-resistant applications in bathrooms and kitchens, with formulation shifts addressing durability concerns in tropical monsoon conditions.
Metal holds installed capacity. Wood is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Construction anchors Vietnam's regulatory framework through QCVN construction standards that govern material certification across all provincial markets.
Red River Delta
Rising disposable incomes in Hanoi and surrounding provinces concentrate renovation spending on premium kitchen and bathroom upgrades. The Ministry of Construction's fire-retardant mandates for high-rise residential towers above six stories elevate demand for certified metal and glass products. Phu Ly hosts Viglacera Corporation's integrated ceramic and glass manufacturing complex serving northern demand clusters.
Southeast Region
Ho Chi Minh City's urban homeowners drive specification upgrades toward Japanese-engineered bathroom fixtures and moisture-resistant electrical infrastructure. QCVN compliance documentation requirements for imported building materials create certification friction that favors domestic manufacturers with established testing laboratory relationships. Binh Duong and Dong Nai manufacturing zones expand tile, sanitary ware, and metal fixture capacity to serve this demand concentration.
Central Coast
Da Nang and coastal provinces generate unmet demand for aluminum window systems engineered for tropical monsoon climate performance. The Ministry of Construction's technical regulations on building materials affect cross-border sourcing strategies for developers in this corridor. Provincial distributors aggregate fragmented contractor and direct homeowner demand through buffer inventory positions.
Mekong Delta
Rural renovation cycles lag urban compression patterns as household purchasing power accumulates more gradually in this agricultural zone. Central highland plantation supply expansion targets termite-treated timber demand to reduce import dependency for flooring applications. Can Tho anchors regional distribution networks connecting to Ho Chi Minh City supply chains.
Vietnam Home Improvement Market Competitive Landscape
Capability concentration sits with integrated manufacturers possessing certified testing laboratory relationships; scale advantage sits with provincial manufacturing zone operators expanding tile and fixture capacity. The market structures around three tiers: Japanese-engineered premium specialists, state-linked integrated producers, and regional fabrication clusters. Dominant competitive moves include backward integration into raw material processing and geographic expansion through provincial distribution network capture.
Within the integrated manufacturing tier, Viglacera Corporation exemplifies state-linked vertical control through ceramic, glass, and metal fixture production. LIXIL Vietnam and TOTO Vietnam represent Japanese-engineered premium positioning through technical specification leadership in bathroom segments. Eurowindow occupies a distinct climate-adaptive specialization anchored in monsoon-engineered aluminum window systems.
| Leading Market Players |
|---|
| LIXIL Vietnam |
| Viglacera Corporation |
| Eurowindow |
| TOTO Vietnam |
| Austdoor Group |
| Hoa Phat Group |
| AkzoNobel (Dulux) |
| Coteccons |
| SCG Vietnam |
| Others |
Value Network & Pricing Analysis
QCVN certification friction for imported building materials compresses margin spreads between domestic and foreign-sourced products while reshaping procurement patterns toward Binh Duong and Dong Nai manufacturing zones. This regulatory chokepoint simultaneously elevates pricing power for certified domestic producers and forces supply chain reconfiguration among contractors serving high-rise residential towers in Hanoi and Ho Chi Minh City.
Pricing Analysis
Ho Chi Minh City commands 15-25% premiums over Hanoi for identical Japanese-engineered bathroom fixtures due to logistics costs and southern market concentration. Pricing stratifies across premium certified grades, standard domestic production, and economy unbranded tiers based on QCVN compliance documentation and fire-retardant rating levels. Cost compression in economy paint and flooring segments is intensifying because Dong Nai capacity expansion outpaces Red River Delta absorption rates. DIY-oriented apartment owners in sub-100-square-meter units exhibit highest price sensitivity, while high-rise developers pre-specifying certified materials show lowest sensitivity due to delay-avoidance priorities.
Supply Chain Analysis
Vietnam's BIS-equivalent conformity assessment procedures for cross-border building materials function as de facto export controls, limiting flows of uncertified metal and glass products into high-rise construction. Manufacturing concentrates in China for ceramic raw materials, Thailand for specialty chemical coatings, and domestic Binh Duong-Dong Nai corridors for finished tile and sanitary ware. The supply chain rests on imported titanium dioxide for premium paint formulations, Malaysian timber for engineered flooring substrates, and South Korean LED chipsets for IP44-rated modules. Single-source vulnerability concentrates in fire-retardant additive supply for QCVN-compliant metal fixtures. Distribution runs through provincial distributors in the Red River Delta corridor aggregating fragmented contractor and direct homeowner demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's home improvement market sits at a regulatory-inflection disruption where QCVN fire-retardant mandates are compressing certification timelines and elevating certified product premiums across the renovation value chain.
For Market Incumbents: Build certification-laboratory relationships as the primary moat against import competitors facing BIS-equivalent conformity assessment delays. Secure captive supply of fire-retardant-rated aluminum and steel through backward integration into Phu Ly metal processing capacity. Expand QCVN testing documentation services for contractor clients to lock in specification influence against emerging domestic rivals. For New Entrants and Emerging Players: Pursue white-space capture in Central Coast monsoon-engineered window systems where Eurowindow's specialization has left coastal provinces underserved. Target Da Nang and Hue contractor networks with climate-adaptive aluminum framing priced below premium Japanese imports. Penetrate through direct digital engagement with independent designers unbundling from traditional general contractors. For Investors and Strategic Acquirers: The market sits at an early-consolidation phase that favors integrated manufacturers with certified testing laboratory relationships over pure distribution plays. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch QCVN amendment timing as the signal for accelerated domestic manufacturing investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| QCVN Certification Investment | Establishes compliance moat against imported competitors facing BIS-equivalent assessment delays. |
| Binh Duong Manufacturing Expansion | Captures Ho Chi Minh City demand concentration with reduced logistics costs versus northern supply. |
| Fire-Retardant Material Backward Integration | Secures input supply for high-rise tower specifications under Ministry of Construction mandates. |
| Digital Designer Platform Partnership | Accesses unbundled procurement flows from apartment owners self-sourcing after independent design engagement. |
| Monsoon Climate Product Engineering | Addresses Central Coast vulnerability where standard aluminum window systems fail prematurely. |
Research Methodology
The analysis maps paint formulations, flooring systems, lighting modules, and fixture categories, each validated through contractor procurement managers, high-rise developer specification teams, provincial distributor inventory planners, and Ministry of Construction certification officers. Primary interviews with renovation firm owners and DIY-platform users combined with secondary validation from customs trade records, QCVN technical regulation filings, provincial manufacturing zone investment disclosures, and SEC filings of listed building materials suppliers. Bottom-up project pipeline assessments triangulate against top-down disposable income trajectory modeling across the Red River Delta and Southeast regions.
Assumptions held fixed include QCVN enforcement intensity and urbanization rates in Hanoi and Ho Chi Minh City metropolitan areas, while variables included timber input cost volatility and LED module import tariff exposure. Segmentation dimensions modeled encompass product type, customer archetype, installation method, and material composition across the projection horizon. CAGRs derive from replacement cycle compression analysis and premium specification upgrade elasticity. Forecast inputs incorporated high-rise residential tower completion permits and Red River Delta household disposable income indices.
Macroeconomic conditions sit as an overlay; deviation in Vietnamese dong stability, central bank lending rate policy, or China-Vietnam trade corridor fluidity would shift the trajectory. Material shifts in QCVN amendment scope or BIS-equivalent mutual recognition agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
Bays and Bows Window Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
Automatic Curtain Market
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
Global DIY Home Improvement Market