
 Modular Kitchen Market | 2026-2036
Modular Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Kitchen Market Intelligence
Heightened consumer and regulatory focus on sustainable materials, such as bamboo and recycled wood composites, is restructuring product development priorities. Nobilia leverages its large-scale manufacturing to offer certified sustainable product lines across Europe. Meanwhile, OPPEIN Home Group dominates the Asia-Pacific market through extensive customization options and a strong retail network. SieMatic positions its brand in the premium segment by emphasizing bespoke design and high-end material finishes.
A modular kitchen comprises pre-fabricated units, including cabinets and countertops, designed for assembly on-site. These systems utilize standardized dimensions and hardware, such as drawer runners and hinges from suppliers like Hettich Group, to ensure interoperability and efficient installation. Base cabinets and countertops constitute the largest product segments by volume. While MDF remains a dominant material for its cost-effectiveness, the residential end-user segment shows increasing preference for engineered wood and stainless steel for durability and aesthetics.
Product safety and material composition are governed by a complex web of standards. In the United States, the EPA enforces formaldehyde emission limits for composite wood products, while in Europe, manufacturers must comply with REACH regulations on chemical substances. These frameworks dictate material selection and supply chain verification. Consequently, navigating the trade-offs between material cost, design customization, and compliance with evolving sustainability mandates remains the central strategic challenge for manufacturers.
Market Dynamics
The central dynamic shaping the modular kitchen market is the conflict between mass-production economics and the growing regulatory and consumer pressure for sustainable, low-emission materials. This requires manufacturers to re-engineer supply chains for compliance without sacrificing cost-competitiveness.
Growth Catalysts
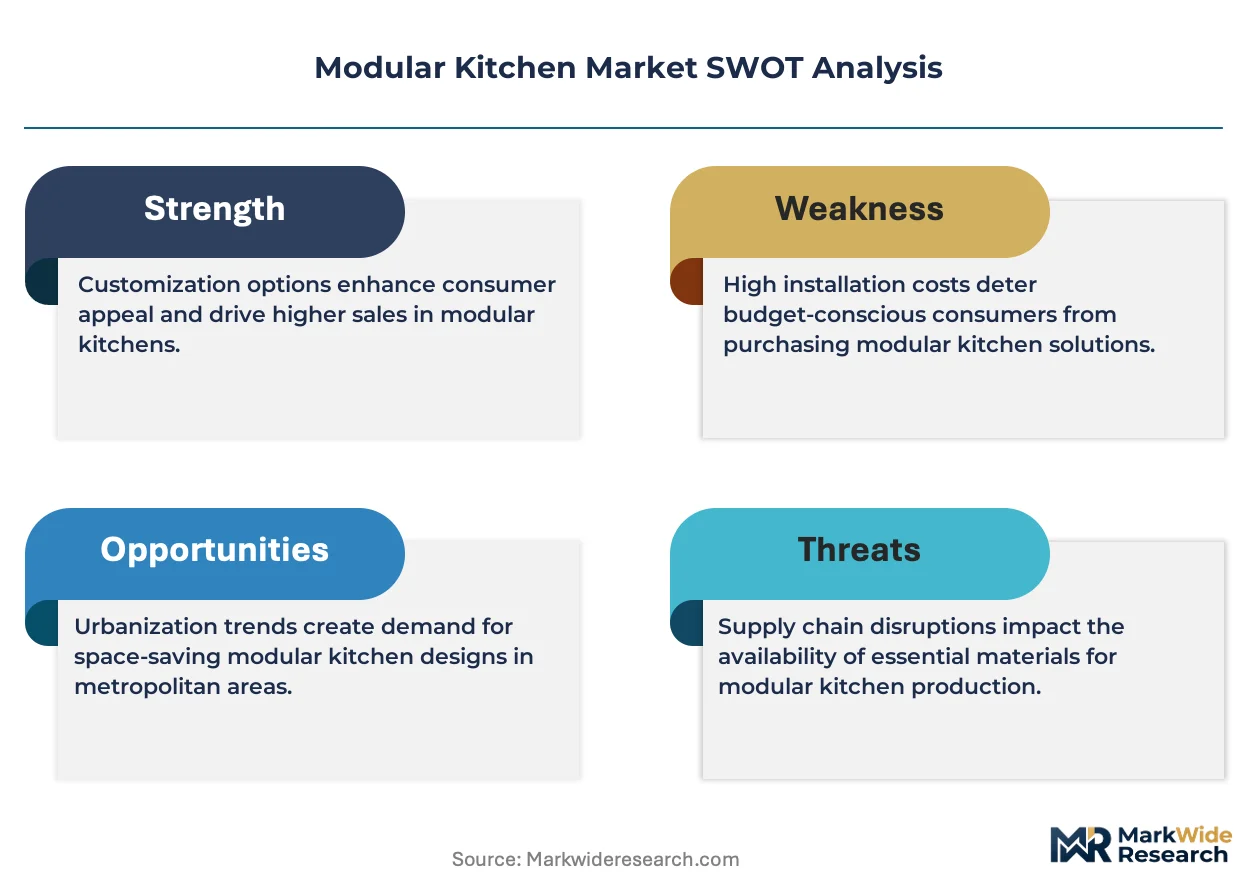
- Urban Real Estate Expansion:Rapid urbanization in countries like India fuels demand from residential developers for standardized, quick-to-install kitchen solutions in new multi-family housing projects.
- Health and Safety Regulations:Stringent standards, including Europe's E1 classification and US EPA rules on formaldehyde, compel the use of certified low-emission composite woods, boosting a new product class.
- Material and Hardware Innovation:The availability of advanced, durable materials like engineered quartz and sophisticated hardware from specialized suppliers improves the functionality and aesthetic appeal of modular systems.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of core materials such as stainless steel, engineered wood, and high-grade laminates create margin pressure for manufacturers.
- Hardware Supplier Dependence:The market relies on a concentrated group of specialized hardware manufacturers, creating potential supply bottlenecks for critical components like hinges and drawer runners.
- Fragmented Global Standards:Manufacturers face complexity and higher costs navigating disparate regulations, such as REACH in Europe and composite wood rules from the EPA in the United States.
Strategic Opportunities
- Smart Kitchen Integration:Incorporating smart technology, such as integrated charging, lighting, and appliance connectivity, into cabinet units offers a new frontier for product differentiation and value.
- Circular Economy Materials:Developing product lines using recycled composites, reclaimed wood, or other circular materials appeals to environmentally conscious consumers and aligns with corporate sustainability goals.
- DTC Channel Development:Building direct-to-consumer sales channels with online 3D configurators allows manufacturers to capture higher margins and control the customer experience.
Industry Challenges
- Installation Skill Scarcity:A shortage of trained installers capable of executing precise on-site assembly for customized, high-end projects can lead to project delays and damage brand reputation.
- Supply Chain Verification:Documenting and verifying the origin and composition of all materials to meet standards like REACH is an operationally intensive and costly compliance burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Kitchen Market |
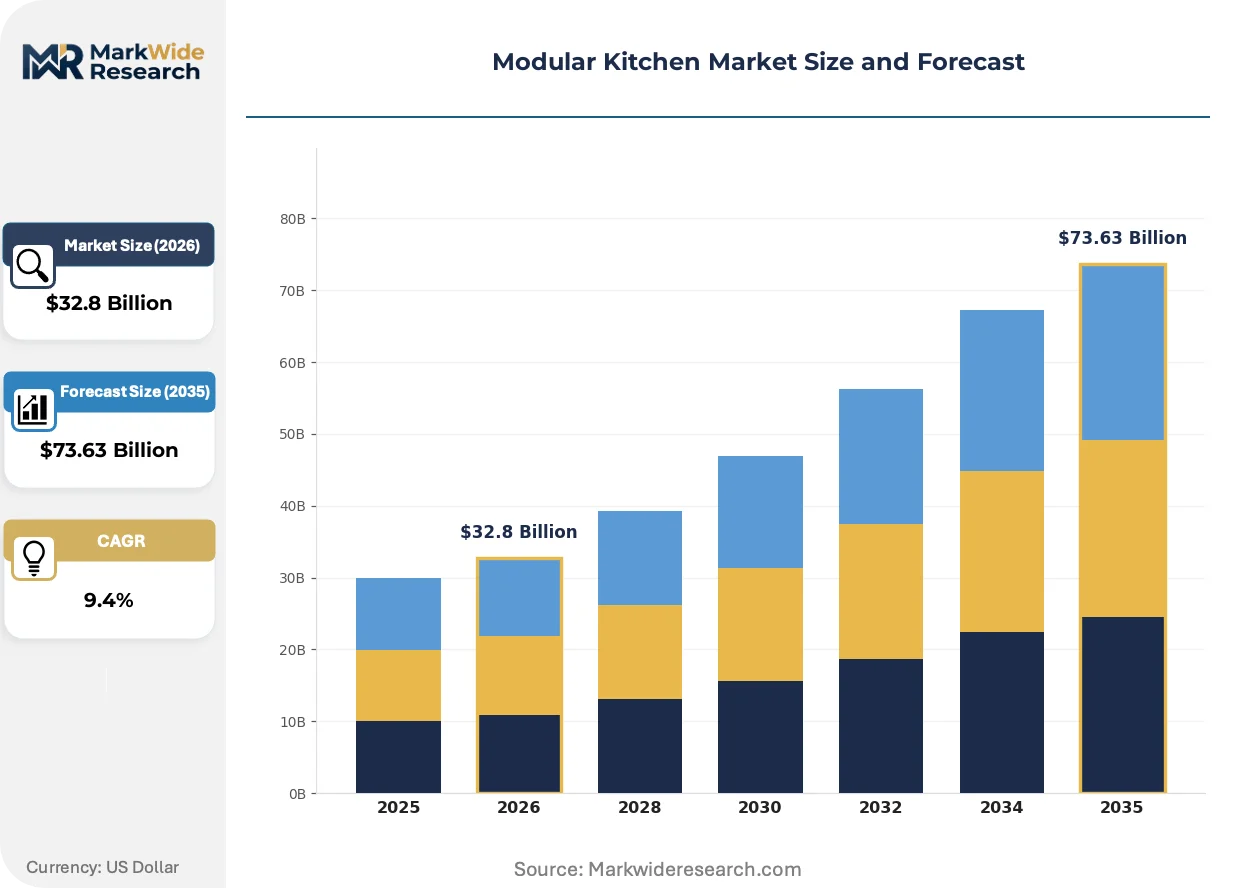
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $73.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Cabinets, Wall Cabinets, Countertops, Kitchen Islands Material: Wood, MDF, Plywood, Stainless Steel Design Style: Contemporary, Traditional, Rustic, Minimalist End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | Godrej and Boyce, MasterBrand Cabinets, Nobilia, Snaidero Rino, SieMatic, Häcker Küchen, OPPEIN Home Group, Pedini, Hettich Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Kitchen Market Strategic Shifts & Innovations
Product development is being redefined by the fusion of digital design tools with sustainable material science. This allows for greater personalization while navigating a complex landscape of environmental regulations, pushing manufacturers toward more agile and transparent production models.
Digital 3D configuration software allows customers to visualize and customize kitchen layouts in real time. Residential buyers are increasingly using these tools in both online and retail environments. This technology is expanding into the supply chain, linking customer designs directly to automated factory orders, thereby reducing lead times and costly specification errors.
The European Union’s REACH regulation governs chemical substances used in manufacturing. This forces producers to verify and often reformulate the adhesives, coatings, and binders in composite wood products. The entire European supply chain is affected, creating a strong market preference for products with certified low-VOC (Volatile Organic Compound) materials and finishes.
A distinct behavioral shift toward hyper-personalization is evident, with buyers demanding unique combinations of materials, finishes, and hardware. This model disrupts traditional inventory-based retail, favoring on-demand manufacturing and more consultative sales processes. This trend is most visible in affluent urban centers across North America and Europe, where design individuality commands a premium.
Modular Kitchen Market Segmentation
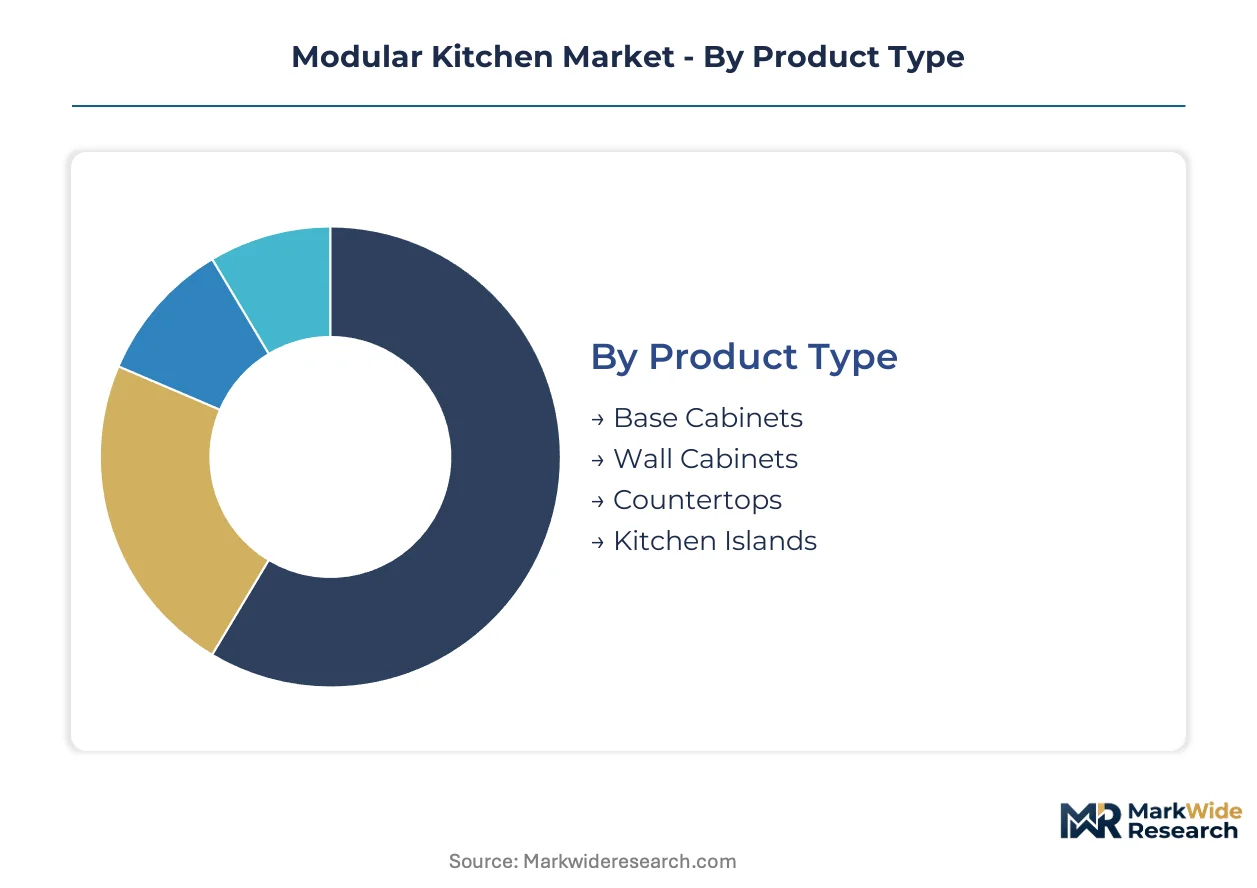
Modular kitchen market segmentation reveals distinct consumer preferences and operational efficiencies critical for manufacturers. Understanding these divisions allows producers to tailor offerings and optimize supply chains. This detailed analysis highlights the varied demands influencing product development and market penetration strategies.
Product Type:
Buyers in the modular kitchen market differentiate their purchases significantly based on the functional components required for a complete kitchen system.
- Base Cabinets:These foundational units provide storage and support for countertops, typically featuring drawers, shelves, or pull-out mechanisms. Demand concentrates in multi-family housing projects in urban centers, driven by the need for standardized, quick-to-install solutions.
- Countertops:These work surfaces are fabricated from durable materials like engineered quartz or stainless steel, designed for food preparation and aesthetic integration. The residential end-user segment shows increasing preference for these durable options, particularly in North America and Europe, for their longevity and modern appeal.
- Wall Cabinets:These overhead storage units maximize vertical space, often featuring glass inserts or integrated lighting.
- Kitchen Islands:Freestanding or fixed units offer additional counter space, storage, and often serve as a dining area.
Volume sits with Base Cabinets; growth tilts toward Kitchen Islands.
Material:
Material selection is dictated by a blend of performance characteristics, aesthetic preferences, and regulatory compliance requirements across different market applications.
- MDF:This engineered wood product offers a smooth surface and cost-effectiveness, making it a dominant material for cabinet carcasses. The residential end-user segment utilizes MDF extensively for its versatility and paintability, especially in budget-conscious projects across India.
- Stainless Steel:Valued for its durability, hygiene, and modern aesthetic, stainless steel is increasingly preferred for professional kitchens and high-end residential applications. Demand from the hospitality sector and affluent urban centers in Europe drives its adoption, aligning with stringent cleanliness standards.
- Wood:Solid wood provides a classic, natural aesthetic and durability, often chosen for traditional or rustic design styles.
- Plywood:This composite wood offers structural stability and moisture resistance, frequently used for cabinet boxes and drawer construction.
The adoption of materials is heavily influenced by cost-effectiveness and stringent health and safety regulations.
Design Style:
Customer aesthetic preferences significantly influence the chosen design style, reflecting broader lifestyle trends and individual tastes.
- Contemporary:Characterized by clean lines, smooth surfaces, and often a mix of materials like glass and metal, this style appeals to modern urban dwellers. This design style finds strong demand in North American and European urban centers, where design individuality commands a premium.
- Minimalist:Emphasizing simplicity, functionality, and uncluttered spaces, minimalist designs feature handle-less cabinets and neutral color palettes. Residential buyers in affluent urban centers across Germany and Japan increasingly prefer minimalist aesthetics for their sophisticated and streamlined appearance.
- Traditional:This style features ornate details, classic finishes, and often natural wood, appealing to a more classic aesthetic.
- Rustic:Characterized by natural textures, distressed finishes, and earthy tones, rustic designs evoke a warm, country-inspired ambiance.
The market for design styles is segmenting around evolving consumer tastes and the desire for personalized living spaces.
End User:
The functional requirements and scale of projects vary significantly across different end-user segments, driving distinct product specifications and service models.
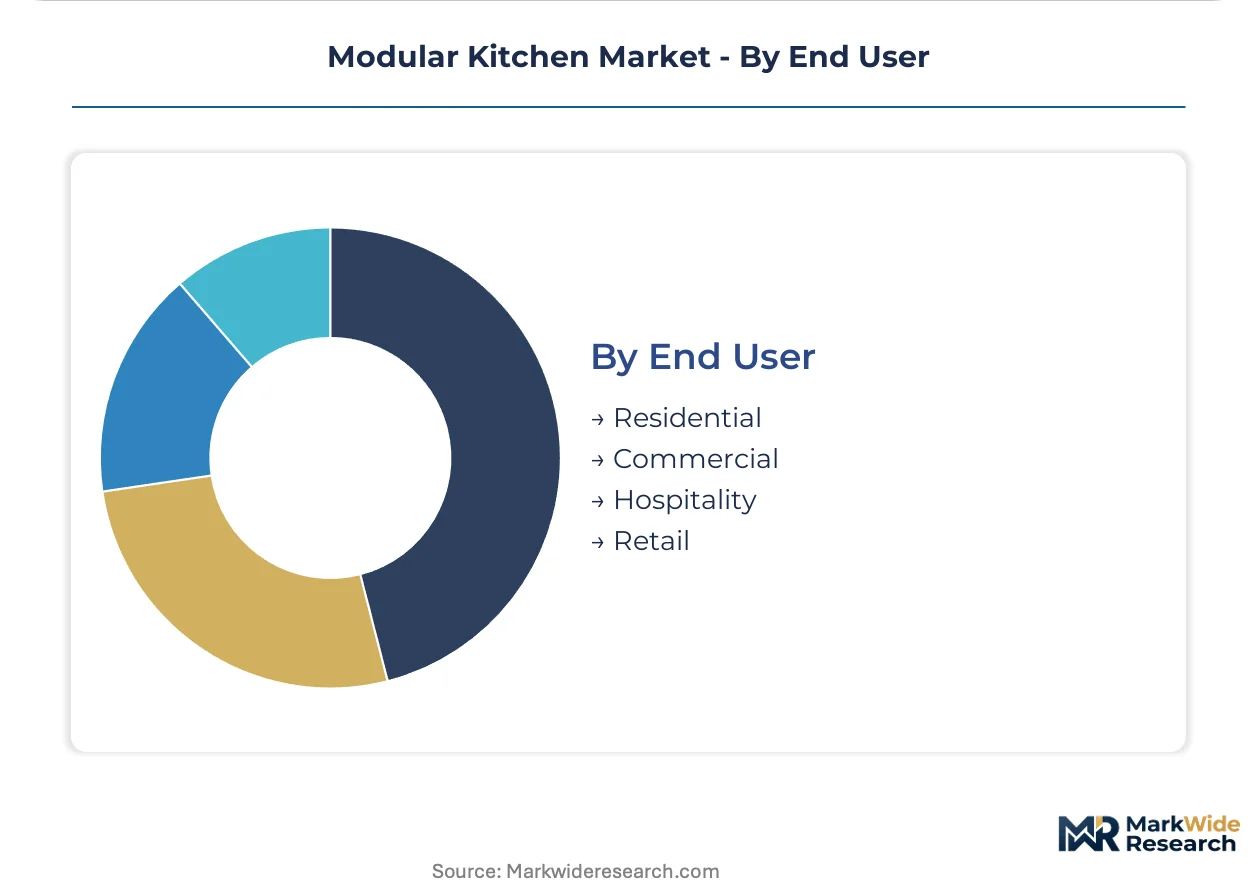
- Residential:This segment encompasses single-family homes and multi-family apartments, requiring diverse kitchen solutions from basic functional units to bespoke luxury designs. Demand concentrates in high-growth urban centers across India, fueled by rapid urbanization and new housing developments.
- Hospitality:Hotels, resorts, and restaurants demand durable, high-performance modular kitchens capable of handling heavy use and stringent hygiene standards. Commercial developers in Europe and the United States prioritize suppliers offering robust materials and efficient installation for large-scale projects.
- Commercial:This segment includes offices and institutional facilities, requiring functional and durable kitchenettes or breakroom solutions.
- Retail:Showrooms and specialized kitchen stores utilize modular systems for display purposes and direct sales to consumers.
Growth in this segment is primarily driven by urban real estate expansion and the evolving demands of modern living.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai, India, exhibits significant demand for modular kitchen solutions. Rapid urbanization and new multi-family housing projects drive this expansion. Developers seek standardized, quick-to-install kitchen systems for numerous residential units.
India
Rapid urbanization and new housing developments fuel demand for modular kitchens in India. The Bureau of Indian Standards (BIS) guides product quality and safety for local manufacturers. The Delhi-NCR region sees concentrated activity, with manufacturers focusing on cost-effective MDF solutions for mass residential projects.
Germany
Germany's modular kitchen market is driven by affluent urban centers and a strong preference for minimalist aesthetics and high-quality materials. Europe's E1 classification for low-formaldehyde emissions and REACH regulations significantly influence material choices. Bavaria, known for precision engineering, defines product development for premium brands emphasizing sustainable manufacturing practices.
United States
United States demand stems from commercial developer projects and residential upgrades prioritizing durability. The Environmental Protection Agency (EPA) enforces formaldehyde emission limits for composite wood products. The New York City metro area, with its high-rise residential construction, requires bespoke and durable modular systems for luxury renovations.
France
France's market for modular kitchens emphasizes design individuality and a growing focus on sustainable materials for high-end residential applications. EU Green Deal initiatives influence material sourcing and product lifecycle assessments across the country. The Île-de-France region, especially Paris, drives demand for customized, high-quality modular kitchen installations among design-conscious consumers.
Modular Kitchen Market Key Industry Players
Premium-margin players sit above commodity-margin players across product customization and material quality. The market exhibits a tiered structure, with a few large global manufacturers alongside numerous regional and niche specialists. Strategic archetypes include integrated manufacturers offering extensive product lines, bespoke design houses focusing on high-end customization, and volume producers targeting cost-effective segments. Companies pursue geographic expansion and portfolio diversification to capture market share.
On the premium-tier vector, Nobilia and SieMatic exemplify manufacturers focused on high-end design and certified sustainable product lines within Europe. Nobilia leverages its large-scale manufacturing capabilities, while SieMatic positions its brand through bespoke design and high-end material finishes. OPPEIN Home Group, a China-based entity, anchors the Asia-Pacific market, demonstrating strength through extensive customization options and a robust retail network. These companies represent distinct strategic approaches, from volume-driven sustainability to bespoke luxury and regional dominance through customization.
| Leading Market Players |
|---|
| Godrej and Boyce |
| MasterBrand Cabinets |
| Nobilia |
| Snaidero Rino |
| SieMatic |
| Häcker Küchen |
| OPPEIN Home Group |
| Pedini |
| Hettich Group |
| Others |
Cost & Logistics Intelligence
Multi-family housing project developers often negotiate project-based pricing, which reflects volume-based contracting for standardized modular kitchen solutions. This approach balances cost-effectiveness with efficient large-scale installations.
Pricing Analysis
Value delivered through customization and certified materials underpins pricing across the modular kitchen market. Project-based pricing dominates for large residential developments, while bespoke luxury designs command premium-tier pricing. Price differentiation stems from material quality, customization level, and brand premium. Margin pressure affects manufacturers due to input cost volatility for stainless steel and engineered wood. Residential end-users in budget-conscious projects across India exhibit high price sensitivity, contrasting with affluent urban centers in Europe and North America.
Supply Chain Analysis
Dual-sourcing requirements for critical hardware components are becoming more prevalent to mitigate supply chain risks. The supply chain draws from manufacturing hubs in China, India, and Germany for modular kitchen systems. Key dependencies include specialized hardware like hinges and drawer runners, alongside core materials such as MDF, engineered wood, and stainless steel. The concentrated group of specialized hardware manufacturers creates potential bottlenecks for critical components. Distribution runs through established retail networks for individual consumers and direct-to-developer channels for large-scale residential projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The modular kitchen market is currently engaged in a vertical-integration race, as manufacturers pursue upstream control over material sourcing to ensure compliance with evolving sustainability mandates. This strategic move aims to secure certified low-emission materials and streamline production.
For Market Incumbents: Lock in long-term supply agreements for certified low-emission materials, especially for engineered wood and adhesives, to meet stringent European E1 classification and US EPA regulations. Consolidate market share by expanding direct-to-consumer channels with online 3D configurators, capturing higher margins and controlling the customer experience. This counters the threat of emerging regulatory complexity and ensures material compliance. Invest in training programs to address installation skill scarcity, maintaining brand reputation for high-end projects.
For New Entrants and Emerging Players: Digital 3D configuration software offers a technology-first wedge for new entrants to penetrate the modular kitchen market. Target the residential end-user segment in high-growth urban centers across India with cost-effective, low-formaldehyde MDF solutions. Focus on developing product lines using circular economy materials like recycled composites, appealing to environmentally conscious consumers. A direct-to-consumer sales model leveraging online configurators provides a scalable go-to-market angle, reducing traditional retail overheads and offering hyper-personalization.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate fragmented capabilities within the modular kitchen market. Long-term viability hinges on securing intellectual property related to sustainable material science and digital design tools. Target specialized hardware manufacturers to mitigate supply chain bottlenecks or bespoke design houses for premium market access. The signal to watch is the increasing stringency of global chemical substance regulations, driving demand for certified low-VOC materials and verifying supply chain compliance.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch Smart Kitchen Product Lines | Integrates technology like charging and lighting, offering new differentiation and value. |
| Expand Direct-to-Consumer Channels | Captures higher margins and provides direct control over the customer experience. |
| Invest in Low-Emission Material R&D | Addresses stringent regulatory compliance and consumer demand for sustainable products. |
| Form Strategic Hardware Partnerships | Secures critical components and mitigates supply chain bottlenecks from concentrated suppliers. |
| Acquire Bespoke Design Houses | Strengthens premium market positioning and enhances customization capabilities for affluent segments. |
Research Approach
Independent corroboration across industry association reports, government regulatory bodies, and company financial filings underwrites the qualitative findings. This approach combines primary interviews with residential developers, kitchen manufacturers, material suppliers, and design consultants. Secondary validation draws from trade publications and academic research. A rigorous bottom-up and top-down triangulation process ensures data integrity and comprehensive market understanding.
Rate-of-change decomposition forms the basis for projecting market dynamics across the analysis window. The analytical framework models market segmentation by product type, material, design style, end user, and geographic region. Compound annual growth rates are derived from historical trends and projected influences of urban real estate expansion. Health and safety regulations, particularly regarding formaldehyde emissions, serve as key industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical instability and unforeseen rapid technological disruptions in manufacturing processes. Forecasts reflect assumptions regarding stable regulatory environments and consistent consumer behavior patterns. Deviation in global economic downturns or significant shifts in raw material availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Popover Pan Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
US Tableware Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
North America Countertop Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Asia-Pacific Kitchen Furniture Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
United Arab Emirates Modular Kitchen Market
Kitchen and Dining
Brightwood Tray Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market