
 DIY Home Decor Market | 2026-2036
DIY Home Decor Market Size, Share, and Industry Trends Forecast 2026-2036
DIY Home Decor Market Analysis
Subscription-based design consultation and replenishment services is rebalancing how consumers engage with home improvement, shifting loyalty from transactional retail to ongoing relationships. The Home Depot leverages its physical-digital hybrid network to sustain repeat purchases across project cycles. Wayfair competes through algorithm-driven room visualization tools that reduce return rates. Sherwin-Williams anchors professional-grade pigment systems while extending color-matching software to amateur renovators.
DIY home decor encompasses self-installed aesthetic and functional enhancements to residential interiors and exteriors, spanning wall coverings, movable furnishings, ambient lighting, and soft textiles typically manufactured through CNC routing, powder-coating, digital printing, and hand-finishing processes designed for non-professional assembly. Wall art and lighting segments lead current revenue pools due to lower skill barriers and faster refresh cycles, while textiles and furniture categories carry higher margin potential through customization interfaces. The indoor application dimension dominates volume, though outdoor and seasonal subsets are expanding fastest in climates with extended temperate periods.
The EPA governs volatile organic compound limits in architectural coatings across the United States, while REACH and RoHS frameworks in Europe restrict hazardous substances in metal finishes and synthetic fabrics, collectively elevating compliance costs for cross-border suppliers. California's Air Resources Board imposes stricter VOC thresholds than federal baselines, creating a de facto premium tier for compliant formulations. Stakeholders must monitor how proliferating state-level chemical standards fragment product lines and whether bio-based material certifications become mandatory market access conditions rather than optional positioning.
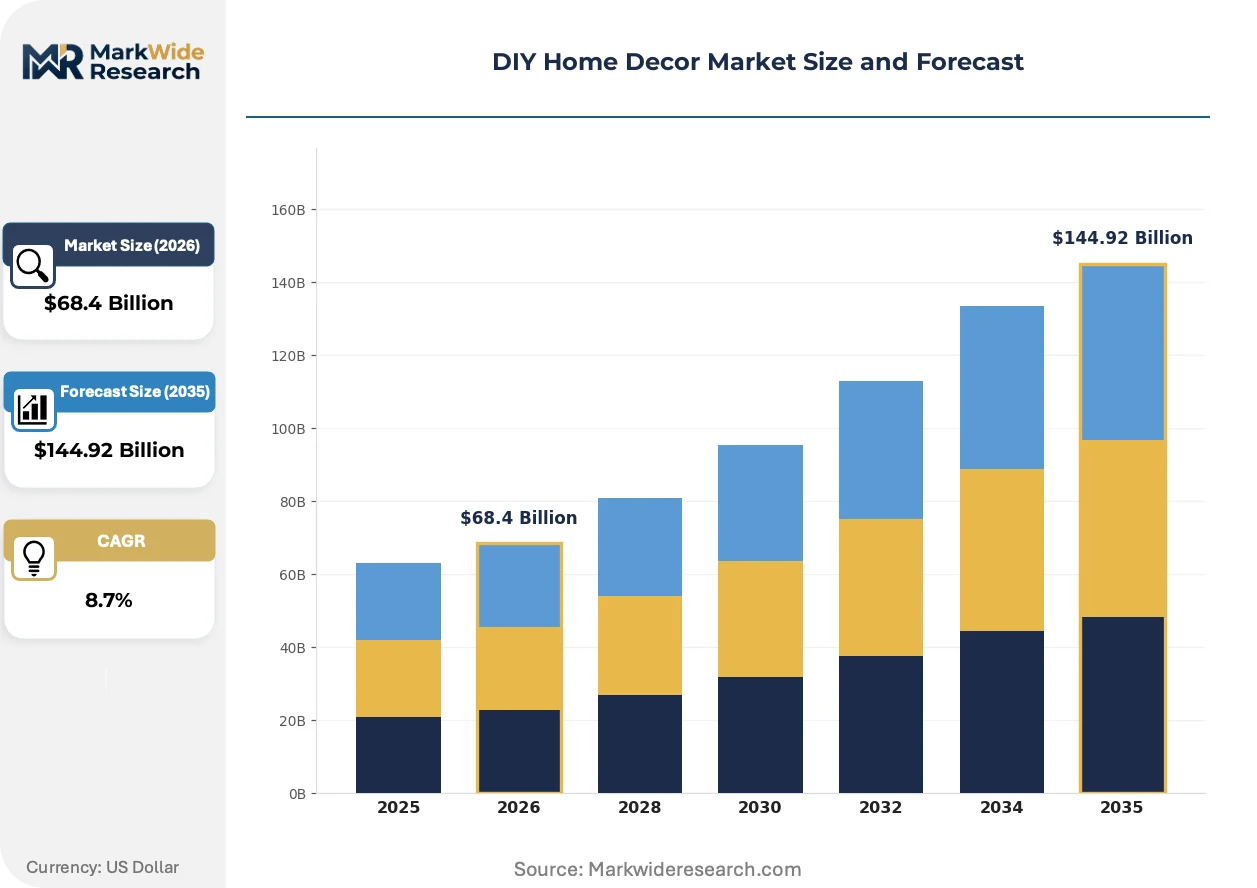
Market Dynamics
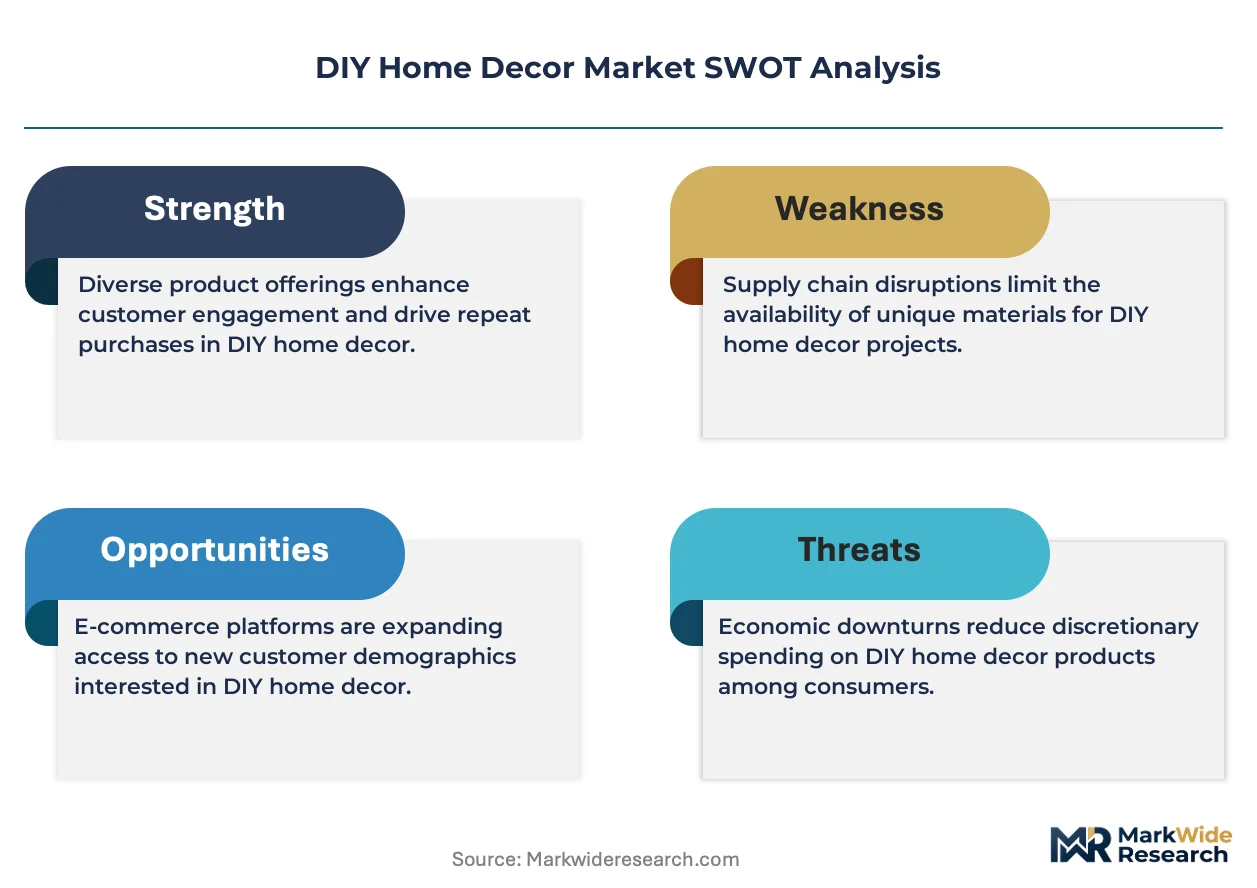
Millennial and Gen Z homeowners are reshaping demand structures through preference for personalized interior spaces, while REACH and EPA VOC regulations simultaneously compress material formulation options and elevate compliance costs for cross-border suppliers.
Growth Catalysts
- EU Green Deal implementation:The framework mandates circular economy principles in textile and furniture production, accelerating bio-based material R&D investment across European manufacturing clusters.
- Digital printing on textiles:On-demand production eliminates inventory risk for small-batch wall coverings and soft furnishings, enabling micro-brands to compete with established decorators.
- China's e-commerce infrastructure:Live-streaming commerce and same-day delivery networks in tier-one cities collapse the purchase-to-installation timeline for DIY renovators.
Market Restraints
- California Air Resources Board VOC thresholds:Stricter state-level limits than federal EPA baselines force product line fragmentation, raising per-SKU compliance overhead for coatings suppliers.
- Pigment supply concentration:Titanium dioxide and rare earth colorants cluster in Chinese and Russian extraction zones, exposing finish manufacturers to geopolitical input volatility.
- Skill threshold for furniture assembly:CNC-routed flat-pack systems with complex joinery exclude novice DIYers, capping category penetration among older demographics.
Strategic Opportunities
- India's urban housing stock:Rapid homeownership expansion in Mumbai and Bangalore metro corridors outpaces organized retail penetration, creating first-mover advantage for direct-to-consumer platforms.
- AR-powered room visualization:Smartphone-based spatial mapping converges with AI color matching, collapsing the design consultation barrier that previously required professional intermediaries.
- US Inflation Reduction Act efficiency incentives:Tax credits for energy-efficient window treatments and smart lighting systems redirect renovation budgets toward premium certified products.
Industry Challenges
- Cross-border chemical certification timelines:REACH registration dossiers and EPA PMN submissions for novel bio-based binders extend 18-36 months, delaying product launches behind trend cycles.
- Legacy retail inventory systems:Big-box distributors with seasonal reset calendars struggle to synchronize with micro-trend velocity in TikTok-driven decor cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DIY Home Decor Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Art, Furniture, Lighting, Textiles Application: Indoor, Outdoor, Seasonal, Thematic Style: Modern, Rustic, Vintage, Minimalist Material: Wood, Metal, Fabric, Glass |
| Companies Covered | Adeo Group, Stanley Black & Decker, The Home Depot, Wayfair, Sherwin-Williams, Lowe's Companies, Ace Hardware, Menards, Kingfisher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DIY Home Decor Market Emerging Trajectories
Technology convergence between spatial computing and sustainable materials is collapsing traditional boundaries between professional interior design and amateur renovation, while regulatory fragmentation accelerates regional product specialization.
Augmented reality visualization tools are absorbing the traditional role of in-store design consultants. Gen Z renters and first-time buyers adopt smartphone-based room scanning at three times the rate of prior cohorts. The technology is absorbing margin from physical showrooms by enabling confident online purchasing of large-format furniture without tactile inspection.
REACH Annex XVII restrictions on phthalates in synthetic leathers and PVC wall coverings are forcing reformulation across European supply chains. Manufacturers face substitution costs for bio-based polyurethane alternatives that currently trade at 40% input premiums. German and French textile finishers are responding by consolidating testing capabilities in shared compliance facilities to amortize certification overhead.
Rental-property customization without permanent alteration is displacing traditional ownership-model decor purchasing. Peel-and-stick wall coverings and modular lighting systems now dominate urban apartment turnover corridors. This pattern concentrates in US coastal metros and Northern European capitals where lease terms average under 24 months.
DIY Home Decor Market Segmentation
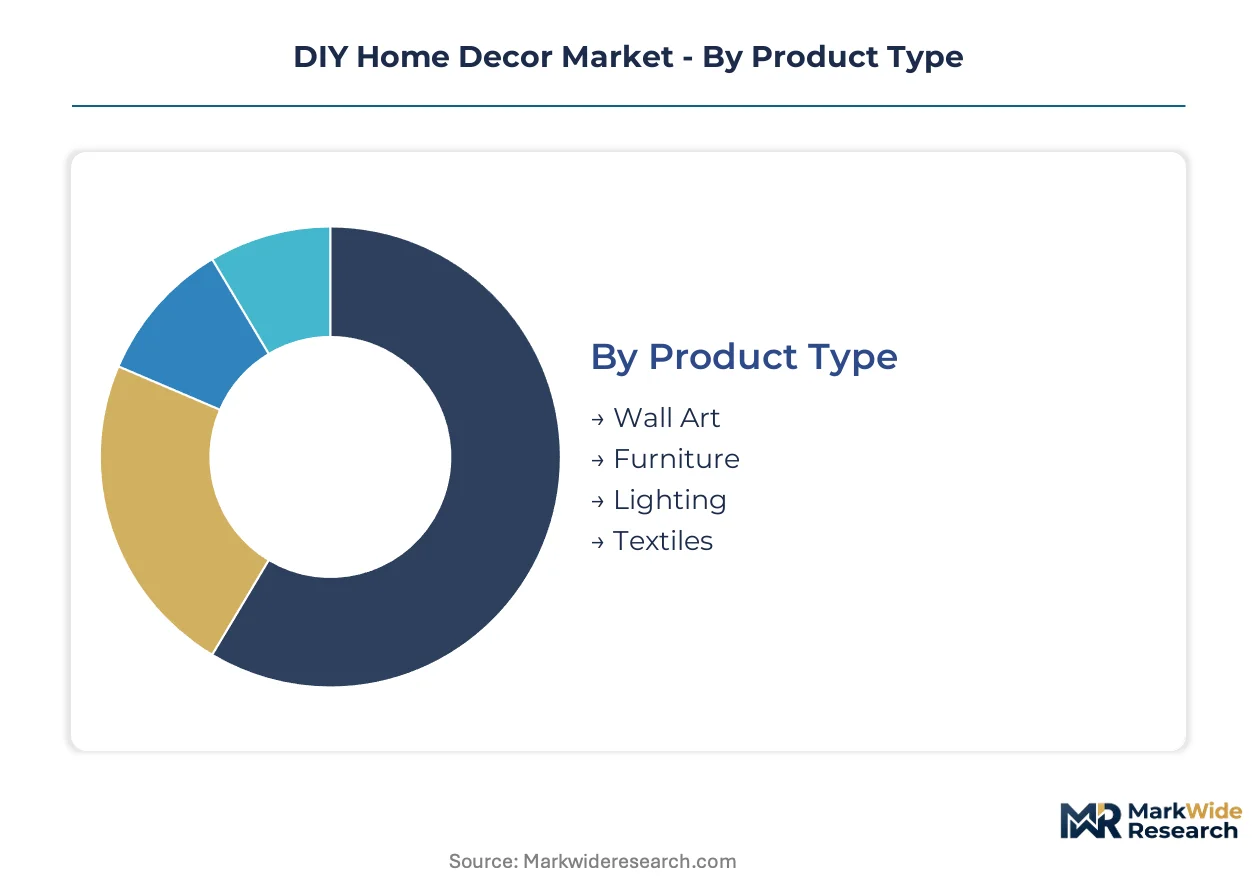
DIY home decor segmentation reveals divergent margin structures across product categories and application contexts. Material choices and regulatory compliance costs fragment supplier strategies, while style preferences concentrate demand in distinct generational cohorts.
Product Type:
Wall art and lighting dominate current volume throughput, while furniture and textiles concentrate premium pricing power through customization interfaces.
- Wall Art:Canvas prints, framed photography, and adhesive murals deploy digital printing and CNC routing for mass personalization. Demand clusters in United States and Germany where e-commerce infrastructure supports rapid refresh cycles for seasonal redecorating.
- Furniture:Flat-pack systems with powder-coated metal frames and engineered wood substrates require intermediate assembly skills. China's manufacturing clusters supply cost-optimized components, though REACH and EPA VOC regulations elevate compliance overhead for cross-border finished goods.
- Lighting:Ambient fixtures and task lamps integrate LED drivers and smart home protocols.
- Textiles:Soft furnishings including curtains, throws, and upholstery fabrics.
Today's leader: Wall Art. Tomorrow's challenger: Textiles.
Application:
Indoor installations absorb the majority of material throughput, though outdoor and seasonal subsets are expanding most quickly in climates with extended temperate periods.
- Indoor:Living spaces, bedrooms, and kitchens receive permanent aesthetic enhancements through wall coverings, built-in storage, and fixed lighting. United States and Chinese metropolitan markets drive volume through high homeownership turnover and renovation frequency.
- Outdoor:Patio furniture, weather-resistant lighting, and exterior wall treatments employ powder-coated aluminum and marine-grade synthetics. Demand concentrates in German and Australian suburban corridors where outdoor living space integration commands premium positioning.
- Seasonal:Temporary installations for holiday and weather-driven redecoration cycles.
- Thematic:Coordinated room transformations around specific aesthetic concepts or licensed properties.
Indoor applications currently anchor supplier revenue. Outdoor categories are climbing the fastest as climate-adaptive materials improve durability thresholds.
Style:
Modern and minimalist aesthetics command price premiums through material simplicity and manufacturing precision, while rustic and vintage styles absorb higher labor inputs in finishing processes.
- Modern:Clean lines, neutral palettes, and geometric forms characterize this segment. German and Japanese manufacturing clusters specialize in precision-engineered components that satisfy millennial preferences for uncluttered residential environments.
- Minimalist:Extreme reduction in visual elements and multifunctional furniture systems. Scandinavian design houses and Chinese direct-to-consumer platforms compete through material efficiency and flat-pack logistics optimization.
- Rustic:Distressed wood, hand-forged metal accents, and natural fiber textures.
- Vintage:Reproduction and reclaimed aesthetics referencing historical design periods.
Modern styling leads current procurement volumes. Minimalist approaches are gaining share fastest among urban apartment dwellers with space constraints.
Material:
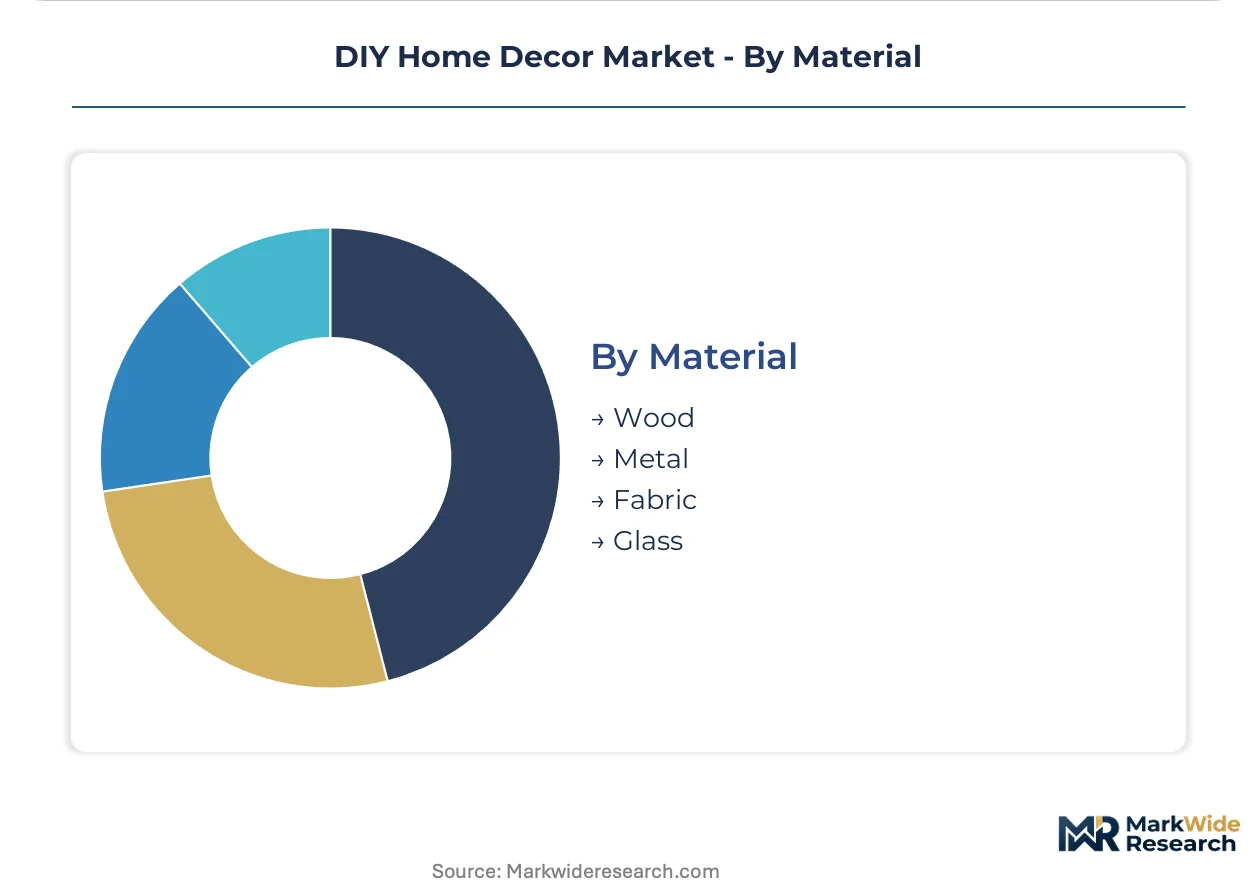
Wood and metal provide structural integrity for furniture and lighting categories, while fabric and glass enable softer aesthetic transitions in textiles and decorative objects.
- Wood:Solid hardwoods, engineered composites, and bamboo substrates serve furniture and wall art substrates. Sustainable forestry certifications from FSC and PEFC are becoming mandatory market access conditions in European Union member states under EU Green Deal procurement guidelines.
- Metal:Steel, aluminum, and brass components undergo powder coating or plating for corrosion resistance. REACH Annex XVII restrictions on hexavalent chromium and nickel release rates force reformulation in French and Italian finishing facilities.
- Fabric:Natural and synthetic textiles for upholstery, window treatments, and soft furnishings.
- Glass:Tempered and blown glass for lighting enclosures and decorative objects.
Wood materials anchor current supply chain configurations. Metal alternatives are expanding most quickly as durability requirements intensify for outdoor application segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing production capacity as manufacturers relocate finishing operations to jurisdictions with streamlined chemical certification pathways. The EU Green Deal and California's Air Resources Board create divergent compliance cost structures that reshape where pigment formulation and textile finishing concentrate.
United States
Millennial homeownership turnover in Texas and Florida metros sustains demand for rapid-refresh decor categories. The EPA governs VOC limits in architectural coatings, though California's Air Resources Board imposes stricter thresholds that fragment product lines. The Home Depot anchors omnichannel distribution from Atlanta, while Wayfair's Boston-based algorithm teams drive visualization tool adoption.
Germany
REACH Annex XVII restrictions on phthalates and heavy metals in metal finishes elevate reformulation costs for furniture suppliers. The EU Green Deal mandates circular economy principles in textile production, accelerating shared compliance facilities in North Rhine-Westphalia. German manufacturing clusters specialize in precision-engineered flat-pack systems for minimalist aesthetic segments.
China
Live-streaming commerce and same-day delivery networks in Shanghai and Shenzhen collapse purchase-to-installation timelines for DIY renovators. GB standards on indoor air quality and the Ministry of Ecology and Environment's dual carbon goals reshape material sourcing for export-oriented finishers. Pearl River Delta manufacturing bases supply cost-optimized components to global furniture assemblers.
India
Rapid homeownership expansion in Mumbai and Bangalore metro corridors outpaces organized retail penetration, creating first-mover advantage for direct-to-consumer platforms. The Bureau of Indian Standards governs product safety certifications, though enforcement remains fragmented across states. Maharashtra and Gujarat textile clusters are investing in digital printing capacity for small-batch wall covering production.
United Kingdom
Rental-property customization without permanent alteration concentrates demand for peel-and-stick wall coverings in London and Southeast England. The UK's post-REACH chemical regulatory framework maintains substance restrictions aligned with EU baselines. Kingfisher's B&Q and Screwfix banners anchor big-box distribution from Buckinghamshire while testing subscription-based design consultation models.
DIY Home Decor Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with big-box retailers commanding volume throughput and digital-native platforms capturing margin through visualization tools. The vendor base organizes around three strategic archetypes: physical-digital hybrid networks, algorithm-driven e-commerce specialists, and professional-grade material suppliers extending to amateur renovators. Dominant competitive moves include M&A to absorb visualization technology capabilities and strategic partnerships to secure bio-based material supply chains.
Among North American retail giants, The Home Depot, Lowe's Companies, and Wayfair occupy distinct positions within the competitive structure. The Home Depot exemplifies the physical-digital hybrid archetype through its store network and Pro loyalty programs. Lowe's Companies sits within the same tier with comparable geographic footprint. Wayfair represents the algorithm-driven specialist model, anchoring digital-first demand capture through room visualization investments.
| Leading Market Players |
|---|
| Adeo Group |
| Stanley Black & Decker |
| The Home Depot |
| Wayfair |
| Sherwin-Williams |
| Lowe's Companies |
| Ace Hardware |
| Menards |
| Kingfisher |
| Others |
Supply Flow & Price Mechanics
Titanium dioxide pigment indices cascade through DIY home decor supply chains, compressing margins for coatings suppliers exposed to Chinese and Russian extraction zones while elevating price premiums for REACH-compliant bio-based alternatives in European markets. This raw-material volatility stratifies finished goods across premium certified tiers and economy-grade mass-market offerings.
Pricing Analysis
Distributor margin layers absorb the primary cost volatility from pigment and rare earth colorant markets, forcing three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on VOC certification grade and customization depth, with California Air Resources Board compliance commanding substantial premiums. Cost compression in standard-tier wall coverings intensifies as Chinese digital printing capacity floods export markets. First-time renovators and Gen Z renters exhibit highest price sensitivity, while millennial homeowners pursuing permanent installations demonstrate willingness to absorb certification premiums.
Supply Chain Analysis
REACH and EPA qualification gating fragments supplier bases between compliant and non-compliant manufacturing zones. Pearl River Delta clusters in China, North Rhine-Westphalia finishing facilities in Germany, and Gujarat textile hubs in India anchor global component supply. Raw material flows draw from titanium dioxide processors, engineered wood substrate mills, and LED driver assembly lines. Single-source vulnerability concentrates in Chinese pigment extraction, exposing finish manufacturers to geopolitical disruption. Distribution runs through big-box retail networks, direct-to-consumer platforms, and live-streaming commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DIY home decor functions as a geographic-arbitrage play where REACH compliance costs in European markets diverge sharply from Chinese manufacturing economics, rewarding suppliers with dual-registered production footprints.
For Market Incumbents: Anchor defensive positioning through backward integration into bio-based binder R&D and captive certification testing facilities. The Home Depot and Wayfair face margin compression from TikTok-native micro-brands with faster trend-cycle velocity. Prioritize vertical control over pigment formulation and shared compliance infrastructure to amortize REACH dossier costs.
For New Entrants and Emerging Players: Capture white-space in India's Mumbai and Bangalore metro corridors where organized retail penetration lags homeownership expansion. Rental-property customization without permanent alteration represents the most penetrable segment, with peel-and-stick wall coverings and modular lighting systems commanding repeat purchase cycles. Deploy AR-powered room visualization as primary go-to-market mechanism to collapse design consultation barriers.
For Investors and Strategic Acquirers: Asymmetric upside sits with digital-native platforms possessing algorithm-driven personalization engines and bio-based material supply partnerships. Long-term viability favors acquirers targeting visualization technology capabilities and circular economy certification pipelines. Monitor EPA state-level VOC standard proliferation as inflection indicator for compliance-cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Material R&D Investment | REACH Annex XVII restrictions on phthalates force polyurethane substitution at 40% input premiums. |
| AR Visualization Platform Acquisition | Wayfair's algorithm-driven tools reduce return rates and absorb margin from physical showrooms. |
| Shared Compliance Facility Consolidation | German and French textile finishers amortize certification overhead through joint testing infrastructure. |
| Direct-to-Consumer Platform Launch | Live-streaming commerce in Shanghai and Shenzhen collapses purchase-to-installation timelines. |
| Circular Economy Certification Program | EU Green Deal procurement guidelines mandate FSC and PEFC forestry certifications as market access conditions. |
Methodological Framework
Direct dialogue with brand managers at big-box retailers, category buyers at e-commerce platforms, procurement leads at coatings manufacturers, and supply planners at textile finishers grounds qualitative findings. Secondary validation draws from EPA VOC filings, ECHA REACH registration databases, customs trade data for pigment and engineered wood substrates, and SEC 10-K disclosures from listed home improvement retailers. Bottom-up SKU-level demand modeling triangulates against top-down macroeconomic consumption patterns.
Segmentation outputs across product type, application context, style preference, and material composition inform volume and value projections throughout the forecast period. CAGRs derive from trend-cycle velocity analysis, regulatory compliance cost trajectories, and generational cohort purchasing behavior shifts. Forecast inputs incorporate live-streaming commerce penetration rates, AR adoption curves among first-time buyers, and state-level chemical standard proliferation patterns.
Underlying measurement precision varies by segment; wall art and lighting categories carry tighter precision than textiles and furniture due to more standardized SKU structures. Forecasts reflect assumptions about regulatory enforcement consistency and bio-based material cost convergence. A model refresh is warranted upon material change in EPA state-level VOC standard adoption or REACH Annex XVII expansion to additional substance categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
Home Remodeling Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Automatic Curtain Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Bays and Bows Window Market
Home Improvement and Renovation
DIY Furnitures Market