
 Automatic Curtain Market | 2026-2036
Automatic Curtain Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Curtain Market Outlook
Leasing and subscription-based financing for smart home infrastructure is narrowing the competitive field for automatic curtain providers. Somfy leverages its motor technology leadership to sustain premium positioning across European installer channels. Hunter Douglas anchors North American distribution through designer and architect relationships. IKEA competes on cost structure with flat-pack motorized systems that reduce last-mile complexity.
An automatic curtain is a motorized window covering system employing tubular or track-mounted electric drives, typically operating at 12-24V DC or 110-240V AC, designed to open, close, or adjust opacity via electronic control for light management, thermal regulation, or privacy. Its primary commercial purpose centers on reducing HVAC load in commercial buildings while enabling programmable daylight harvesting. Motorized curtains dominate current revenue as the established retrofit-friendly category with mature installer networks. Smart curtains represent the fastest-expanding segment, driven by Wi-Fi and Zigbee integration with voice assistants and energy management platforms. Bluetooth-enabled systems occupy a niche in premium residential projects where localized control without cloud dependency appeals to privacy-conscious buyers.
The EU Energy Performance of Buildings Directive and REACH chemical standards shape product material selection and motor efficiency requirements across European markets. The US FCC regulates wireless communication protocols in connected curtain systems, while OSHA guidelines influence commercial installation safety standards. China's GB standards and MIIT radio-frequency rules govern smart home device certification for products sold domestically. Stakeholders must monitor evolving interoperability mandates between competing smart home ecosystems as a determinant of technology platform viability.
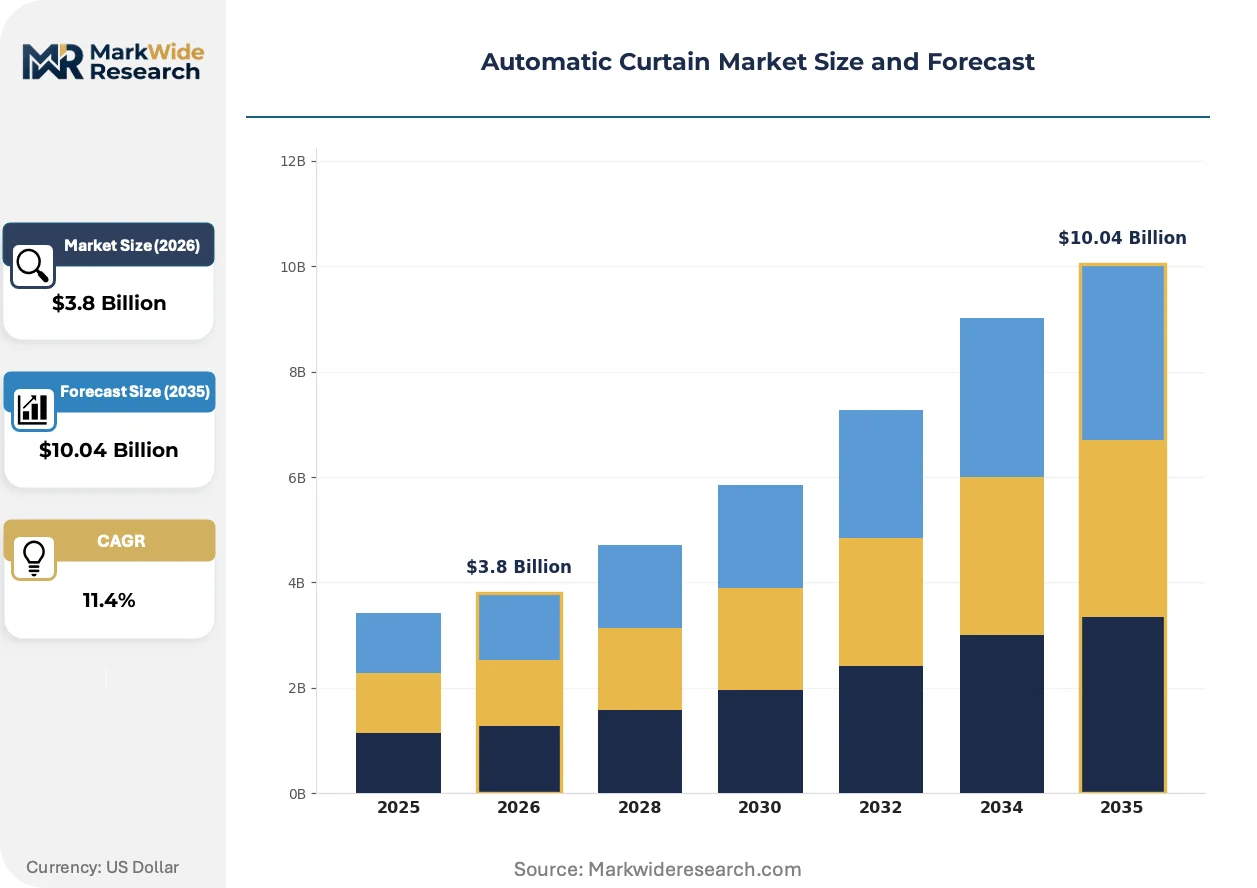
Market Dynamics
Integration mandates between competing smart home ecosystems are forcing motor manufacturers to commit to multi-protocol hardware architectures before standards consolidate.
Growth Catalysts
- EU Energy Performance of Buildings Directive:Automated solar shading mandates in large commercial renovations across member states create replacement demand for existing manual systems.
- China's tier-one smart home penetration:Retrofit installations in high-rise residential towers accelerate as property developers bundle motorized systems with building automation packages.
- Tubular motor efficiency gains:Advances in 24V DC brushless designs reduce standby power consumption below one watt, satisfying stringent building energy codes.
Market Restraints
- Copper and rare-earth magnet volatility:Motor core materials face price swings that compress margins for mid-tier suppliers unable to pass through costs.
- Installer network concentration:European markets depend on specialized electrical contractors whose limited geographic coverage extends project timelines.
- Manual shade substitution:Cordless spring-operated systems satisfy basic light management needs at one-fifth the installed cost.
Strategic Opportunities
- India's nascent smart home channel:Underpenetrated metro markets present first-mover advantage for Wi-Fi-native systems bypassing proprietary protocols.
- Zigbee-to-Matter bridge integration:Protocol convergence enables single hardware SKUs to serve multiple ecosystem buyers simultaneously.
- Subscription-based maintenance:Predictive motor monitoring contracts create recurring revenue streams in commercial property portfolios.
Industry Challenges
- Multi-protocol firmware complexity:Engineering teams must maintain simultaneous compatibility with Apple HomeKit, Google Home, and Amazon Alexa certification requirements.
- Legacy building electrical infrastructure:Pre-1990 commercial structures lack neutral wiring at switch locations, complicating retrofit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Curtain Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorized Curtains, Smart Curtains, Remote-Controlled Curtains, Automated Drapes Technology: Wi-Fi, Zigbee, Bluetooth, Infrared Application: Residential, Commercial, Hospitality, Healthcare End User: Homeowners, Business Owners, Interior Designers, Contractors |
| Companies Covered | Coulisse, Dooya Tubular Motor, Somfy, QMotion, Graber, Hunter Douglas, IKEA, Draper, Lutron Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Curtain Market Strategic Shifts
Silent motor technology and cloud-independent control architectures are reshaping product roadmaps as privacy-conscious buyers resist always-connected devices.
Tubular motor design is hybridizing mechanical reliability with software-defined functionality. Hospitality operators in Dubai specify units with local processing chips that execute schedules without internet connectivity. This architecture compresses cloud dependency risks while maintaining guest room automation.
REACH chemical standards are restricting flame-retardant fabric treatments used in motorized curtain assemblies. Manufacturers reformulate polymer coatings to maintain fire ratings without restricted halogen compounds. Commercial specifiers in Germany now demand third-party material safety documentation before approving installations.
Leasing arrangements for smart home infrastructure are displacing upfront capital expenditure in multi-unit residential development. Property managers in Singapore's new-build towers prefer operational expense models that bundle hardware, installation, and maintenance. This shift concentrates purchasing authority with facility management platforms rather than individual unit owners.
Automatic Curtain Market Segmentation
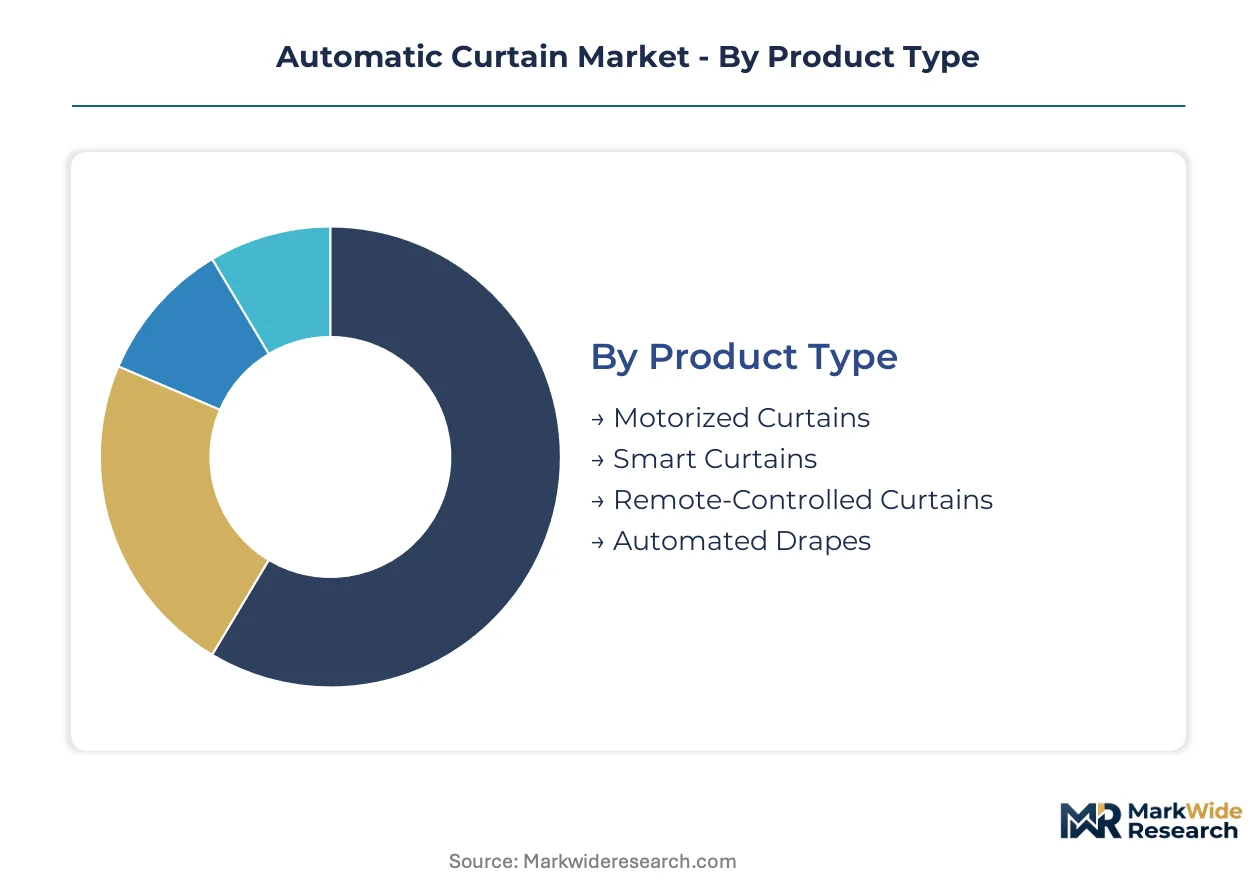
Automatic curtain segmentation reveals how motorization sophistication, connectivity protocols, and buyer economics fragment demand across installation contexts. Product architecture and control technology choices determine margin structures and channel access for suppliers.
Product Type:
Cost tier differentiation separates retrofit-friendly solutions from integrated smart home systems with premium positioning.
- Motorized Curtains:Tubular or track-mounted electric drives operating at 12-24V DC or 110-240V AC power ratings deliver programmable open-close functionality without network connectivity. Demand concentrates in European commercial retrofits where the EU Energy Performance of Buildings Directive mandates automated solar shading in large renovations, with electrical contractors specifying these systems for their installation familiarity and proven reliability records.
- Smart Curtains:Wi-Fi and Zigbee-enabled systems integrate with voice assistants and building management platforms for scheduled operation and energy optimization. China's tier-one cities drive volume as property developers bundle these with high-rise residential automation packages, capturing buyers who prioritize smartphone control and ecosystem interoperability over standalone motorization.
- Remote-Controlled Curtains:Radio-frequency handheld remotes provide localized wireless operation without internet dependency. Hospitality operators in Dubai favor these for guest room deployments where cloud connectivity risks outweigh automation benefits.
- Automated Drapes:Heavy-duty track systems engineered for substantial fabric weights in theatrical and ceremonial applications. Institutional buyers in Singapore specify these for convention center and hotel ballroom installations.
Motorized curtains command the established base. The steepest expansion runs through smart curtains.
Technology:
Connectivity protocol selection shapes hardware BOM costs, certification requirements, and buyer ecosystem lock-in.
- Wi-Fi:Direct router connectivity eliminates hub requirements but increases standby power consumption. India's nascent smart home channel favors Wi-Fi-native systems for their installation simplicity and compatibility with existing residential networks.
- Zigbee:Mesh networking delivers lower latency and reduced power draw for battery-operated installations. Matter protocol convergence enables single hardware SKUs to serve multiple ecosystem buyers simultaneously, compressing inventory complexity for manufacturers.
- Bluetooth:Localized control without cloud dependency appeals to privacy-conscious premium residential buyers. German specifiers increasingly demand these systems for healthcare and legal office deployments.
- Infrared:Line-of-sight control architecture persists in legacy hospitality installations where replacement cycles extend beyond technology obsolescence.
Zigbee solutions anchor professional installer preference. Wi-Fi systems are climbing the fastest among consumer-direct channels.
Application:
End-use environment dictates motor specification, fabric fire rating, and control integration depth.
- Residential:Retrofit installations in high-rise towers and new-build smart homes prioritize aesthetic integration and quiet operation. China's property developers bundle motorized systems with building automation packages to differentiate premium units.
- Commercial:HVAC load reduction and programmable daylight harvesting drive specification in office renovations. The EU Energy Performance of Buildings Directive creates replacement demand for manual systems in member state commercial buildings.
- Hospitality:Guest room automation and back-of-house energy management require reliable scheduling without internet dependency. Dubai and Singapore operators outfit new properties with systems integrating to building management platforms.
- Healthcare:Infection control and patient privacy requirements demand motorized solutions with minimal touch surfaces. REACH chemical standards restrict flame-retardant fabric treatments in German healthcare specifications.
Commercial applications command specification volume. Residential retrofits are expanding most quickly.
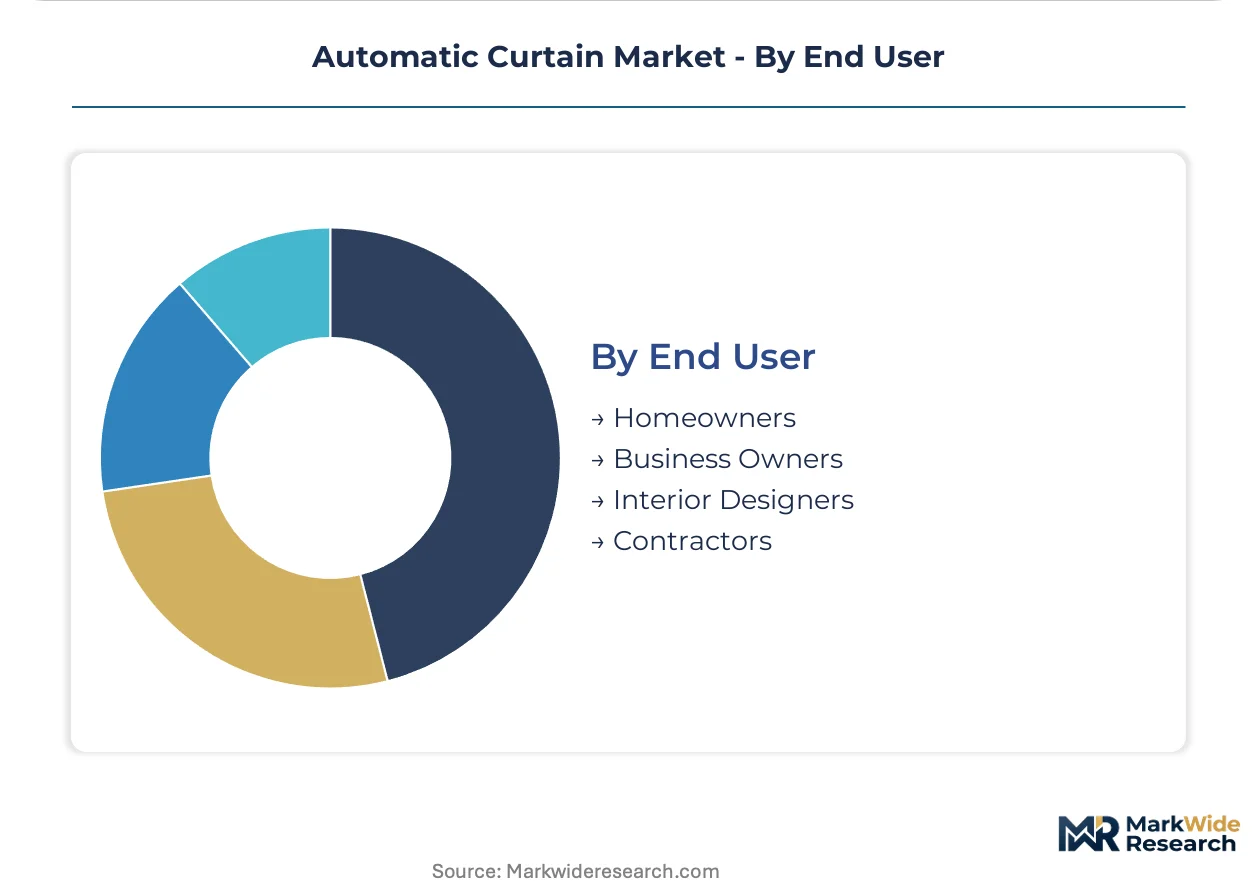
End User:
Customer type determines purchasing authority, financing preference, and technical support expectations.
- Homeowners:Direct purchasers prioritize smartphone control and voice assistant compatibility for single-unit installations. Singapore's leasing arrangements for smart home infrastructure are displacing upfront capital expenditure among this segment.
- Business Owners:Facility managers evaluate total cost of ownership across energy savings and maintenance contracts. Predictive motor monitoring subscriptions create recurring revenue appeal for commercial property portfolios.
- Interior Designers:Specification influencers demand material safety documentation and silent motor technology for premium residential projects. REACH compliance documentation has become mandatory for German commercial approvals.
- Contractors:Installation specialists concentrate purchasing power in European markets where specialized electrical contractor networks extend project timelines. Multi-protocol firmware complexity strains engineering resources maintaining simultaneous HomeKit, Google Home, and Alexa certifications.
Contractors channel the majority of commercial volume. Interior designers are gaining specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for tubular motors and rare-earth magnets shapes regional trade flows, with manufacturing concentration in East Asia and European assembly operations drawing heavily on Chinese motor supplies. The EU Energy Performance of Buildings Directive and China's MIIT radio-frequency certification create divergent compliance pathways that fragment procurement strategies across markets.
China
MIIT radio-frequency rules govern smart home device certification for domestic sales, while GB standards enforce motor efficiency and safety requirements. Property developers in Shanghai and Beijing bundle motorized systems with high-rise residential automation packages, driving retrofit installations across tier-one cities. The Yangtze River Delta manufacturing corridor hosts tubular motor production facilities supplying both domestic installers and export markets.
Germany
REACH chemical standards and the EU Energy Performance of Buildings Directive mandate automated solar shading in large commercial renovations, creating replacement demand for manual systems. ECHA restrictions on halogenated flame retardants force fabric coating reformulations for healthcare and hospitality specifications. The North Rhine-Westphalia industrial cluster anchors motor assembly and distribution networks serving installer channels across Central Europe.
United States
FCC regulations on wireless communication protocols shape connected curtain system certification requirements, while OSHA guidelines influence commercial installation safety standards. Facility managers evaluate total cost of ownership across energy savings and predictive maintenance subscriptions for commercial property portfolios. The Southeast corridor sees hospitality-driven demand as hotel operators outfit properties with building management platform integration.
India
BIS certification requirements and the CEA's energy efficiency standards govern electrical equipment imports and domestic manufacturing. Underpenetrated metro markets present first-mover advantage for Wi-Fi-native systems bypassing proprietary protocols. Mumbai and Bangalore residential towers show early adoption of subscription-based smart home infrastructure financing models.
Singapore
The Building and Construction Authority's Green Mark certification incentivizes automated solar shading in new commercial and residential developments. Hospitality operators outfit new properties with motorized systems integrating to building management platforms. Leasing arrangements for smart home infrastructure displace upfront capital expenditure among property managers in new-build towers.
Automatic Curtain Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying motors and drive mechanisms to branded assemblers. The vendor base organizes into three tiers: global motor technology leaders with installer channel dominance, regional fabricators competing on cost structure, and flat-pack retailers simplifying last-mile logistics. Strategic moves center on multi-protocol hardware architectures and subscription-based maintenance contracts that create recurring revenue in commercial portfolios.
Within the motor technology tier, Somfy and Dooya Tubular Motor exemplify contrasting geographic positioning—European and Chinese respectively—while anchoring divergent channel strategies. Hunter Douglas occupies a position among North American specification influencers, leveraging designer and architect relationships. IKEA represents the cost-structure archetype, competing through flat-pack motorized systems that reduce last-mile complexity for residential buyers.
| Leading Market Players |
|---|
| Coulisse |
| Dooya Tubular Motor |
| Somfy |
| QMotion |
| Graber |
| Hunter Douglas |
| IKEA |
| Draper |
| Lutron Electronics |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta manufacturing corridor anchors global tubular motor capacity, with production concentration in Ningbo and Suzhou compressing margins for European assemblers who lack backward integration into rare-earth magnet sourcing. This geographic asymmetry transfers pricing power to motor specialists who control magnet procurement channels, while fabric finishers in Germany and Italy absorb REACH compliance costs that tier-one suppliers pass through to commercial specifiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification documentation for EU Energy Performance of Buildings Directive compliance and silent motor technology, while economy tiers compete on per-meter track pricing for residential retrofits. Cost compression in the mid-tier is intensifying because copper and neodymium price volatility erodes contract margins. Property developers in China's tier-one cities exhibit lowest price sensitivity due to bundled automation packages, whereas Indian residential buyers in Mumbai and Bangalore drive hardest bargaining on Wi-Fi-native systems.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for motor-dependent assemblers. Manufacturing concentrates in China for tubular motors and rare-earth magnets, with secondary motor winding operations in Vietnam and Mexico serving regional demand. Raw material dependencies center on copper wire, neodymium-iron-boron magnets, and flame-retardant polymer coatings. Distribution runs through specialized electrical contractor networks in Europe, direct-to-developer bulk procurement in China, and flat-pack retail channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic curtain market sits at an inflection where Matter protocol convergence and EU building energy mandates are compressing technology fragmentation. This regulatory-technological alignment favors suppliers who commit early to multi-protocol hardware architectures.
For Market Incumbents: Pre-empt margin erosion in European commercial channels by deepening captive supply of brushless DC motor cores. Invest in predictive maintenance platform development to capture recurring revenue from facility managers who prioritize operational expenditure models over capital outlays. The threat of proprietary protocol obsolescence demands simultaneous HomeKit, Google Home, and Alexa certification maintenance.
For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated metro markets by bypassing Zigbee hub complexity with Wi-Fi-native systems that leverage existing residential infrastructure. Target Singapore's property management platforms with subscription-based infrastructure financing that displaces upfront hardware purchases. The most penetrable white space sits in healthcare specifications where REACH-compliant fabric coatings and silent motor technology command premium positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with captive magnet sourcing and multi-protocol firmware capabilities. Acquisition targets should demonstrate installed base scale in commercial property portfolios where predictive maintenance contracts create recurring revenue visibility. The signal to watch is Matter certification velocity as an indicator of which hardware architectures will survive ecosystem consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Single hardware SKUs serving Apple, Google, and Amazon ecosystems compress inventory complexity for manufacturers. |
| Backward Integration into Rare-Earth Magnets | Captive magnet sourcing insulates margin structures from NdFeB price volatility affecting mid-tier competitors. |
| Predictive Maintenance Platform Launch | Recurring revenue contracts with commercial facility managers displace transactional hardware sales. |
| REACH-Compliant Fabric Coating Reformulation | Third-party material safety documentation unlocks German healthcare and hospitality specification channels. |
| Wi-Fi-Native System Development | Hub-free installation simplicity captures India's nascent smart home channel without proprietary protocol investment. |
Study Parameters
A spread of perspectives from motor technology R&D directors, electrical contractor purchasing managers, property developer procurement leads, and facility management platform executives converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs records, MIIT certification databases, EU Energy Performance of Buildings Directive implementation reports, and SEC filings from publicly traded component suppliers. Bottom-up triangulation across installer channel shipment data and top-down reconciliation with building automation capex disclosures anchored volume estimates.
Demand-supply balance modeling segmented the market by motorization sophistication, connectivity protocol, and buyer economics across the projection horizon. Segmentation dimensions included product architecture, control technology, application environment, and end-user purchasing authority. CAGRs were derived from fitting logistic adoption curves to smart home penetration rates and commercial building renovation cycles, with sensitivity analysis on copper and rare-earth magnet price scenarios.
Macroeconomic conditions sit as an overlay; deviation in construction activity indices, residential mortgage availability, and commercial real estate investment flows would shift the trajectory. Forecasts reflect documented assumptions about protocol convergence timing and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Bays and Bows Window Market
Home Improvement and Renovation
Home Remodeling Market
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
Residential Interior Wood Doors Market