
 Home Improvement Spending Market | 2026-2036
Home Improvement Spending Market Size, Share, and Industry Trends Forecast 2026-2036
Home Improvement Spending Market Outlook
DIY homeowners is bifurcating the Home Improvement Spending landscape as labor shortages and wage inflation push more consumers toward self-directed projects. The Home Depot leverages its Pro Xtra loyalty program and contractor-desk infrastructure to sustain dual-channel dominance across consumer and trade segments. Lowe's Companies Inc. anchors its position through focused appliance and seasonal merchandising in suburban markets. Sherwin-Williams Company dominates architectural coatings through captive distribution and color-matching technology leadership.
Home improvement spending encompasses all residential property alterations, repairs, and upgrades executed through material procurement and skilled labor engagement, spanning structural modifications, system replacements, and aesthetic refinements with project durations from same-day installations to multi-month renovations. Flooring and fixtures command the largest material outlays due to unit costs and installation complexity, while paint generates the highest transaction frequency with compressed project cycles. Installation services capture premium pricing relative to product-only transactions, though maintenance and repair segments exhibit more recession-resistant demand patterns across economic cycles.
EPA lead-safe certification requirements under the Renovation, Repair, and Painting Rule mandate contractor training and containment protocols for pre-1978 housing, directly elevating compliance costs and reshaping contractor qualification structures. OSHA workplace safety standards and local building code enforcement by municipal inspectors further constrain unlicensed participation and consolidate demand toward credentialed providers. Stakeholders must monitor how building electrification mandates and appliance efficiency tier upgrades in jurisdictions like California and New York redirect renovation priorities and material specifications.
Market Dynamics
DIY homeowners are gaining ground against contractor-led projects as labor costs and wage inflation reshape how residential renovations get executed across the United States.
Growth Catalysts
- EPA Lead-Safe Certification:The Renovation, Repair, and Painting Rule mandates contractor training for pre-1978 housing, consolidating demand toward credentialed providers who can command premium pricing.
- Energy-Efficiency Building Codes:Jurisdictions like California and New York are implementing appliance efficiency tier upgrades that redirect renovation priorities toward electrification retrofits.
- Labor Cost Escalation:Skilled trade shortages in metropolitan construction markets are pushing discretionary project owners toward self-directed material procurement and installation.
Market Restraints
- Lumber and Copper Volatility:Framing materials and electrical wiring face input cost swings that compress contractor margins and delay project starts.
- Licensed Contractor Concentration:OSHA workplace safety standards and municipal inspector enforcement constrain unlicensed participation, creating supply bottlenecks in high-demand markets.
- Technical Skill Barriers:Complex HVAC and electrical system upgrades exceed typical homeowner capabilities, limiting DIY penetration in high-value renovation categories.
Strategic Opportunities
- Building Electrification Mandates:State-level decarbonization policies are creating retrofit demand for heat pumps, induction cooking, and panel upgrades.
- Proprietary Loyalty Platforms:Contractor-desk infrastructure and trade-specific credit programs capture professional repeat purchase behavior.
- Color-Matching Technology:Digital tinting systems and in-store spectrophotometry reduce project rework and drive paint category attachment rates.
Industry Challenges
- EPA Certification Timelines:Lead-safe renovator training requirements create onboarding delays for contractor workforce expansion.
- Legacy System Integration:Smart home device installation faces compatibility friction with older residential electrical and communication infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Improvement Spending Market |
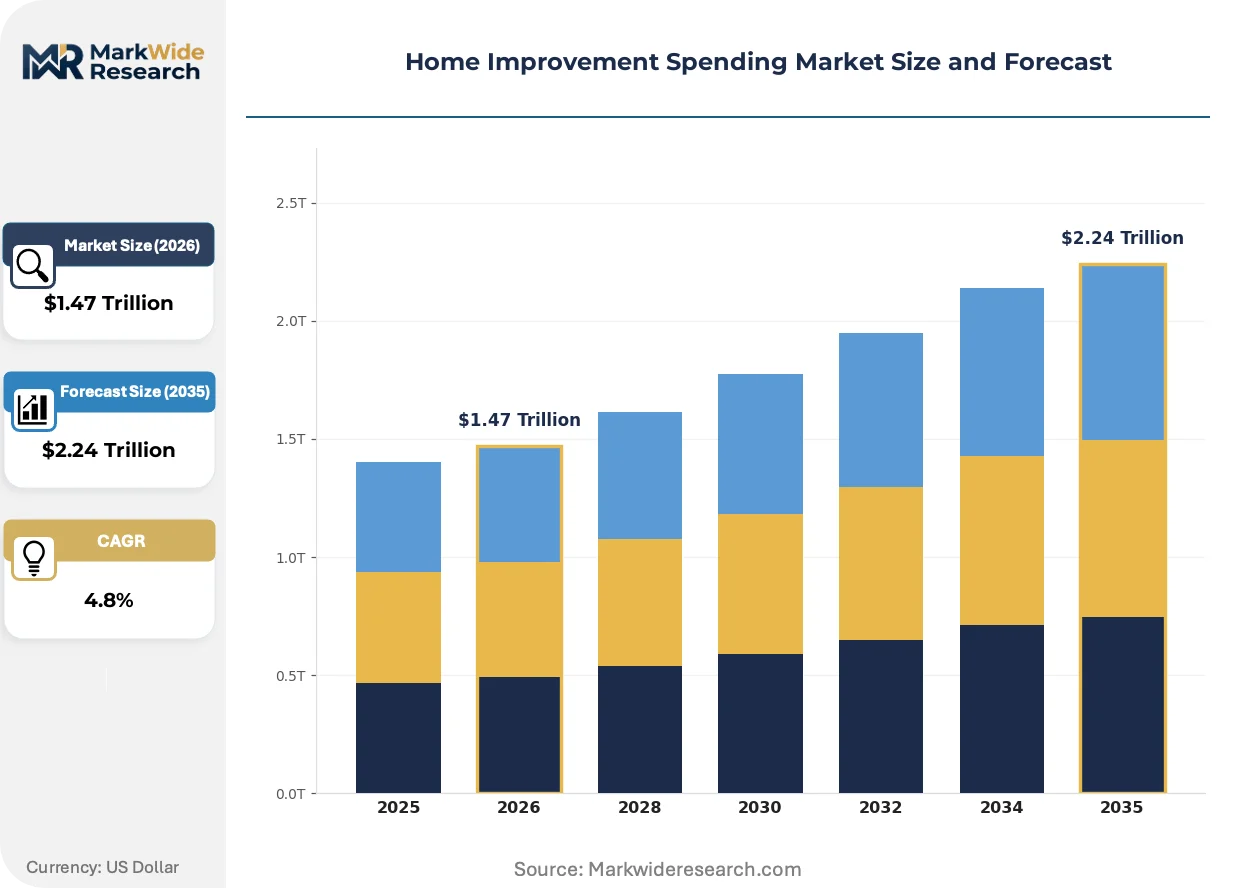
| Market Size in 2026 | $1.47 Trillion |
| Market Size in 2035 | $2.24 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paint, Flooring, Fixtures, Appliances Service Type: Installation, Renovation, Repair, Maintenance End User: Homeowners, Contractors, Property Managers, Realtors Distribution Channel: Retail Stores, Online Platforms, Wholesale Distributors, Trade Shows |
| Companies Covered | The Home Depot, Lowe’s Companies Inc., Menards, Ace Hardware, Wayfair Inc., Amazon.com Inc., Ferguson Enterprises, Sherwin-Williams Company, Builders FirstSource, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Improvement Spending Market Strategic Shifts
Digital tools and regulatory mandates are compressing project cycles and elevating material specifications across residential renovation workflows.
Prefabricated bathroom and kitchen modules are displacing traditional stick-built renovation methods. Multifamily developers and hospitality operators are adopting volumetric construction for bathroom pods to compress construction schedules. Factory-controlled quality environments are displacing on-site craftsmanship variability and reducing moisture intrusion warranty claims.
OSHA silica dust exposure limits are tightening enforcement across residential demolition and concrete cutting operations. Contractors face expanded personal protective equipment requirements and medical surveillance obligations. Drywall installation and tile removal segments are absorbing compliance costs through respirator fit-testing programs and wet-cutting equipment upgrades.
Same-day delivery and curbside pickup are reshaping how homeowners stage renovation materials. Big-box retailers capture project-planning traffic through digital inventory visibility and load-out logistics. Suburban markets with high vehicle access show the strongest adoption of self-serve material procurement over full-service contractor supply.
Home Improvement Spending Market Segmentation
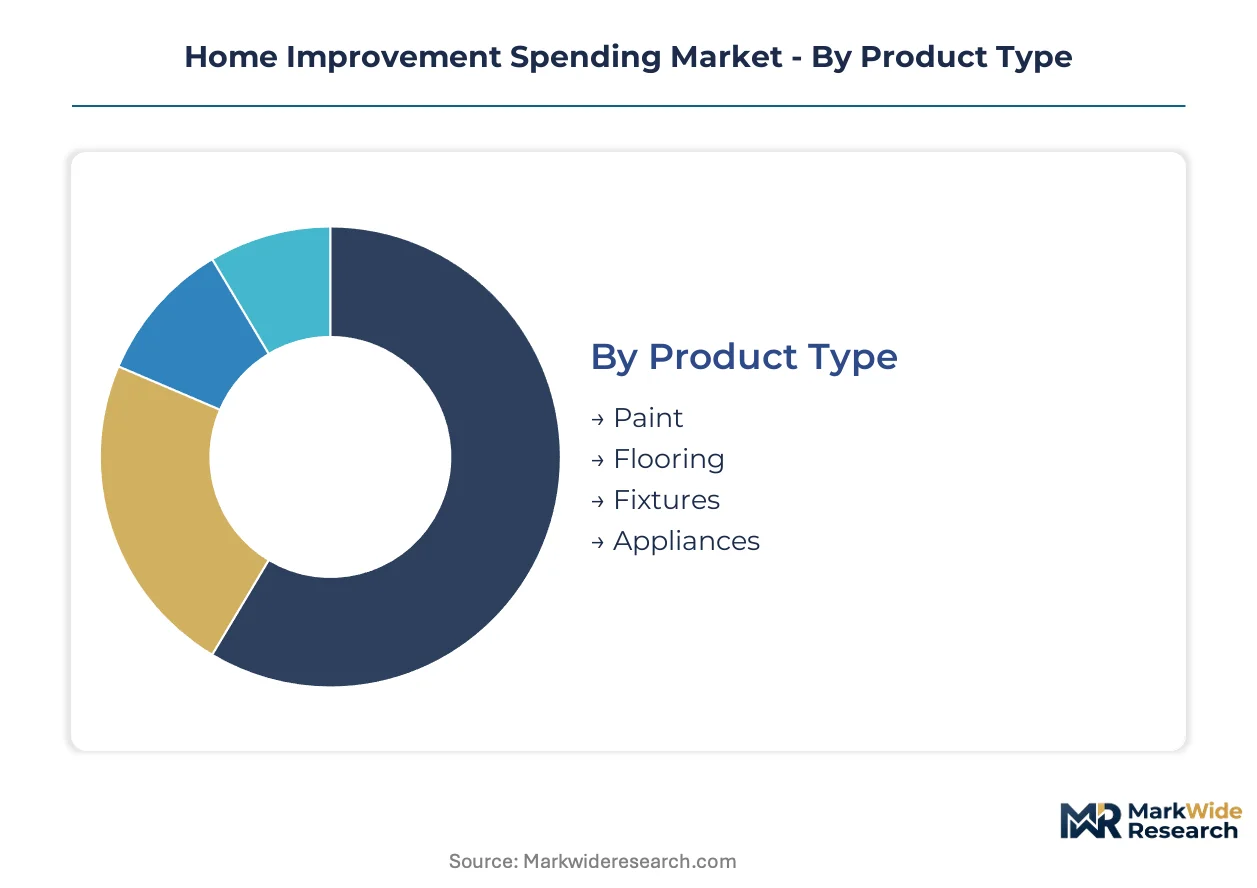
Home improvement spending segments respond differently to labor cost inflation and regulatory mandates. Understanding substitution dynamics between DIY material procurement and professional service engagement shapes strategic positioning across product and service categories.
Product Type:
Paint faces the strongest substitution pressure from private-label alternatives, while appliances confront cross-category competition from bundled housing developer specifications.
- Paint:Water-based acrylic and latex formulations dominate residential interior applications due to low VOC compliance requirements. Demand concentrates in kitchen and bathroom renovations across suburban markets, driven by same-day color-matching services that reduce project rework.
- Flooring:Engineered hardwood and luxury vinyl plank products balance durability with installation accessibility for DIY homeowners. Demand concentrates in primary residence renovations throughout metropolitan construction markets, constrained by lumber input cost volatility that compresses contractor margins.
- Fixtures:Plumbing and lighting fixtures command premium pricing through WaterSense and ENERGY STAR certification tiers.
- Appliances:Induction ranges and heat pump water heaters gain share under state electrification mandates.
Paint retains volume leadership; appliances hold the steepest expansion curve.
Service Type:
Cost tier stratification separates premium full-service renovation from economy self-directed installation, with repair occupying a resilient middle position.
- Installation:Professional flooring and fixture mounting commands 40-60% labor premiums over material-only transactions. Demand concentrates in HVAC and electrical system upgrades, limited by technical skill barriers that exceed typical homeowner capabilities.
- Renovation:Whole-room kitchen and bathroom overhauls absorb the largest share of discretionary improvement budgets. Demand concentrates in pre-1978 housing stock under EPA lead-safe certification requirements, elevating compliance costs for credentialed providers.
- Repair:Emergency plumbing and electrical fixes exhibit recession-resistant demand patterns across economic cycles.
- Maintenance:Seasonal HVAC servicing and gutter cleaning generate recurring revenue through subscription arrangements.
Installation captures the highest margin premiums; repair demonstrates the most stable demand trajectory.
End User:
Customer type determines procurement channel preference and project complexity tolerance, with contractors facing the most concentrated regulatory compliance burdens.
- Homeowners:DIY-oriented consumers drive material procurement through big-box retail and digital platforms. Demand concentrates in paint and flooring categories, propelled by labor cost escalation that pushes discretionary project owners toward self-directed execution.
- Contractors:Licensed trade professionals anchor wholesale distributor relationships and loyalty program enrollment. Demand concentrates in installation and renovation services, shaped by OSHA workplace safety standards and municipal inspector enforcement that constrain unlicensed participation.
- Property Managers:Multifamily operators prioritize maintenance and rapid-turnover repair services.
- Realtors:Pre-sale cosmetic improvements concentrate in paint and fixture refreshes with compressed project cycles.
Homeowners represent the largest addressable base; contractors generate the highest per-transaction value.
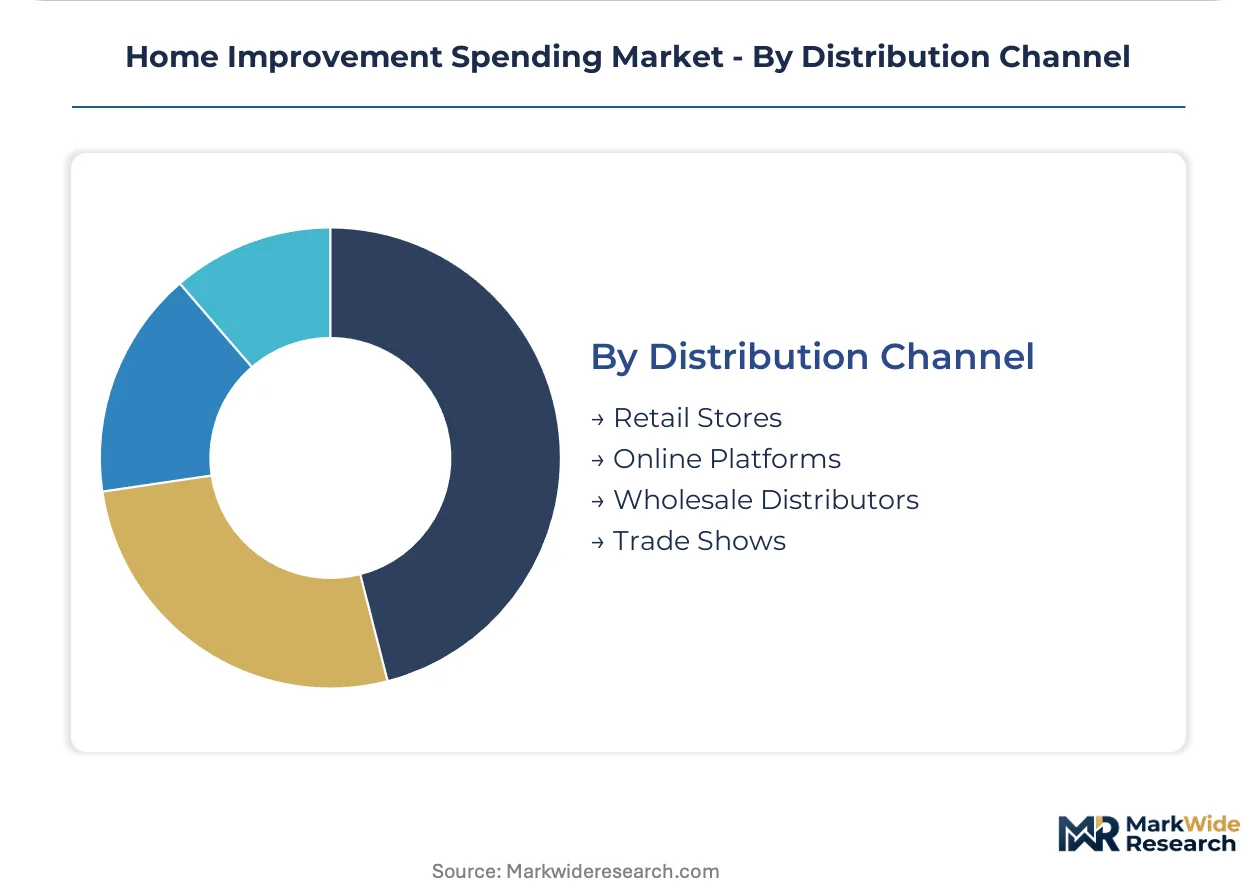
Distribution Channel:
Geography dictates channel efficiency, with vehicle-dependent suburban markets favoring self-serve retail over trade-exclusive supply arrangements.
- Retail Stores:Big-box home centers combine material staging with contractor-desk infrastructure for dual-channel capture. Demand concentrates in metropolitan exurbs with high vehicle access, supported by same-day delivery and curbside pickup logistics.
- Online Platforms:Digital inventory visibility and project planning tools reshape how homeowners stage renovation materials. Demand concentrates in tech-forward metropolitan markets, enabled by load-out logistics and subscription-based design consultation.
- Wholesale Distributors:Trade-exclusive supply houses serve licensed contractor accounts with volume pricing and credit programs.
- Trade Shows:Industry events concentrate product launches and continuing education for EPA certification maintenance.
Retail stores maintain volume dominance; online platforms are climbing the fastest in transaction growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors trans-Pacific building material flows into North America, while the Rhine-Main-Danube canal network underwrites European distribution density for renovation supplies.
United States
Metropolitan construction markets in Texas and Florida absorb elevated kitchen and bathroom renovation volumes. EPA lead-safe certification requirements under the Renovation, Repair, and Painting Rule consolidate demand toward credentialed contractors. The Dallas-Fort Worth corridor concentrates big-box retail distribution centers serving DIY homeowners.
Germany
Energy-efficiency retrofit mandates drive heat pump and insulation material procurement across aging housing stock. The EU Green Deal and national building codes enforce appliance efficiency tier upgrades. The Rhine-Ruhr industrial cluster hosts wholesale distributor networks serving licensed trade professionals.
China
Urban renewal programs in tier-one cities generate fixture and flooring replacement cycles. GB standards and MIIT regulations govern building material quality specifications. The Yangtze River Delta manufacturing belt supplies engineered hardwood and luxury vinyl plank products for export markets.
United Kingdom
Pre-1919 housing stock dominates renovation demand for period-appropriate fixtures and heritage-compliant materials. Building Regulations Part L and F-Gas Regulation constrain HVAC system specifications. The Southeast England corridor concentrates property manager activity for rapid-turnover rental refurbishment.
Canada
Cross-border material procurement from US distributors shapes contractor supply chains in Ontario and British Columbia. Natural Resources Canada efficiency programs redirect renovation priorities toward electrification retrofits. The Greater Toronto Area anchors wholesale trade relationships for licensed renovation professionals.
Home Improvement Spending Market Competitive Environment
Concentration sits with big-box retailers commanding dual-channel infrastructure for consumer and trade segments. The vendor base stratifies across national chains, regional cooperatives, and pure-play digital platforms. Three archetypes dominate: omnichannel retailers with contractor-desk capabilities, specialty coating distributors with captive color-matching technology, and logistics-heavy digital platforms. Competitive moves center on loyalty program enrollment for professional repeat purchase capture and same-day delivery infrastructure deployment in vehicle-dependent suburban markets.
Among North American retailers, The Home Depot and Lowe's Companies Inc. exemplify the omnichannel archetype through Pro Xtra enrollment and contractor-desk staffing. Sherwin-Williams Company occupies the specialty distributor position with spectrophotometry-enabled tinting systems. These three anchors demonstrate how scale-driven logistics and trade-specific credit programs consolidate professional procurement behavior.
| Leading Market Players |
|---|
| The Home Depot |
| Lowe's Companies Inc. |
| Menards |
| Ace Hardware |
| Wayfair Inc. |
| Amazon.com Inc. |
| Ferguson Enterprises |
| Sherwin-Williams Company |
| Builders FirstSource |
| Others |
Value Chain & Pricing Dynamics
Luxury vinyl plank displacement of engineered hardwood is redrawing sourcing maps toward China and Vietnam while compressing price premiums that once separated domestic from imported flooring tiers.
Pricing Analysis
Volume-discount tiering structures separate big-box retail from wholesale distributor channels, with contractor-desk accounts capturing 15-25 point advantages on bulk paint and flooring orders. Price differentiation rests on EPA lead-safe certification status and regional building code compliance tiers, where credentialed installers command labor premiums over unlicensed competitors. Cost compression in lumber-dependent categories is intensifying because framing material volatility transfers directly to project quotes. DIY homeowners exhibit highest price sensitivity, while property managers prioritize rapid-turnover service reliability over per-unit savings.
Supply Chain Analysis
Just-in-time inventory preferences dominate big-box retail operations, whereas wholesale distributors maintain strategic stockpiles of EPA-certified containment materials and lead-safe renovation equipment. Manufacturing concentrates in China, Vietnam, and Mexico for flooring and fixture production, with domestic U.S. mills retaining share in specialty lumber and architectural coatings. Raw material flows draw from Canadian softwood, Chilean copper, and Chinese petrochemical feedstocks. Single-source vulnerability sits with trans-Pacific container routing through the Port of Long Beach. Distribution runs through metropolitan exurb retail centers with contractor-desk infrastructure and trade credit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents early-cycle expansion as building electrification mandates in California and New York accelerate retrofit demand for heat pumps and panel upgrades ahead of code enforcement deadlines.
For Market Incumbents: Secure contractor loyalty through Pro Xtra-style enrollment programs and exclusive trade credit terms that lock in professional repeat purchase behavior. Expand captive distribution of architectural coatings with spectrophotometry-enabled tinting systems that reduce project rework. Vertical integration into prefabricated bathroom modules defends margin position against stick-built cost escalation. For New Entrants and Emerging Players: Differentiate on same-day delivery logistics in vehicle-dependent suburban markets where big-box incumbents retain distribution density advantages. Target rapid-turnover repair services for property managers in multifamily housing corridors, where subscription-based maintenance arrangements show lowest penetration. Pursue digital-first project planning tools with load-out logistics as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty coating distributors lacking captive color-matching technology or contractor-desk infrastructure. Long-term viability favors platforms with dual-channel capabilities spanning consumer DIY and professional trade segments. Monitor EPA certification training backlog as an inflection indicator for contractor workforce expansion constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Loyalty Platform Launch | Pro Xtra-style enrollment captures professional repeat purchase behavior through contractor-desk credit programs. |
| Prefabricated Module Manufacturing Scale-Up | Factory-controlled bathroom pods reduce moisture intrusion warranty claims versus on-site craftsmanship variability. |
| Same-Day Delivery Infrastructure Deployment | Curbside pickup logistics in metropolitan exurbs reshape how DIY homeowners stage renovation materials. |
| EPA Lead-Safe Certification Training Expansion | Credentialed provider networks command premium pricing under Renovation, Repair, and Painting Rule enforcement. |
| Color-Matching Technology Acquisition | Spectrophotometry-enabled tinting systems drive paint category attachment rates and reduce project rework. |
Study Parameters
A spread of perspectives from big-box retail category managers, licensed contractor network heads, municipal building inspectors, and paint manufacturer R&D directors converged on the working assumptions. Primary fieldwork combined structured interviews with EPA-certified renovators and wholesale distributor account executives. Secondary validation drew from OSHA enforcement data, municipal permit filings, SEC 10-K disclosures from listed retailers, and building code adoption tracking across state jurisdictions. Bottom-up project pipeline estimates and top-down residential construction spending aggregates were triangulated to anchor volume assumptions.
Segmentation dimensions modeled include product type, service type, end user archetype, and distribution channel across the analysis window. CAGRs were derived from regression-based trending of historical spending patterns against housing stock age demographics and regulatory adoption curves. Forecast inputs incorporated electrification mandate phase-in schedules and skilled trade labor force growth projections from Bureau of Labor Statistics occupational data.
The analysis sits within stated boundaries; outcomes outside sustained single-family housing turnover and continued EPA enforcement funding would require recalibration. Forecasts reflect assumptions about lumber input cost stabilization and contractor certification pipeline expansion. Revision becomes warranted when electrification mandate adoption crosses thresholds that redirect material specifications faster than supply chain reconfiguration permits.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Global DIY Home Improvement Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
DIY Furnitures Market