
 Bays and Bows Window Market | 2026-2036
Bays and Bows Window Market Size, Share, and Industry Trends Forecast 2026-2036
Bays and Bows Window Market Insights
Skilled glazing labor availability is rotating toward vinyl fabrication and thermal-break assembly, constraining capacity at specialty manufacturers while unlocking growth for automated production lines. Andersen leverages vertical integration across extrusion and finishing to sustain margin control. Pella anchors its position through R&D intensity in pultruded fiberglass bays. Marvin competes on custom dimension capabilities for high-end residential architects.
Bays and bows windows project outward from a building envelope, typically comprising three or more lites joined at 30- to 45-degree angles with structural head and seat boards, engineered to capture panoramic light and expand interior floor space. The primary commercial purpose centers on enhancing aesthetic value and thermal performance in residential and light commercial facades. Vinyl bays dominate volume through cost efficiency and color stability, while fiberglass bays capture premium margin pools in coastal and extreme-climate zones. Window replacement installations lead revenue contribution as housing stock ages, though new construction channels show faster growth in master-planned communities.
Fenestration standards from NFRC and AAMA regulate U-factor and structural load ratings, directly shaping product design cycles and market access for regional manufacturers. EPA ENERGY STAR specifications and evolving IECC code cycles in multiple states mandate performance thresholds that filter out non-compliant suppliers. Stakeholders must monitor code adoption timelines and thermal performance benchmarks as municipalities tighten envelope requirements.
Market Dynamics
The Bays and Bows Window Market pivots on code-cycle compression as municipalities accelerate IECC adoption timelines, forcing manufacturers to redesign thermal-break assemblies and requalify entire product lines within shortened windows.
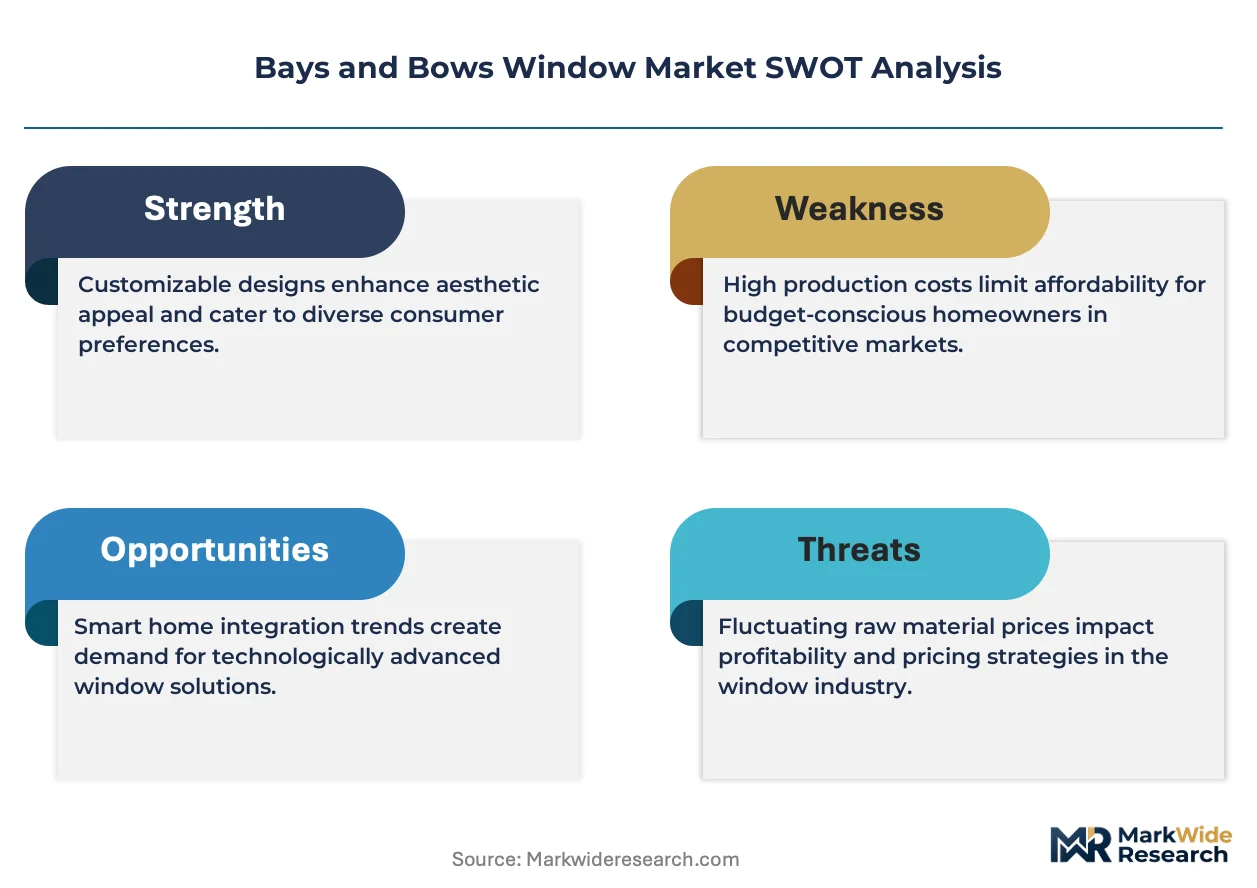
Growth Catalysts
- Residential renovation corridors:Aging housing stock across the United States drives replacement demand as homeowners prioritize envelope upgrades over full rebuilds.
- Low-E glazing mandates:EPA ENERGY STAR performance thresholds filter non-compliant suppliers, elevating certified fabricators and compressing the vendor base.
- Pultruded fiberglass R&D intensity:Material science advances in composite framing expand coastal and extreme-climate applications previously dominated by vinyl.
Market Restraints
- PVC resin price volatility:Feedstock fluctuations compress margin stability for volume-focused vinyl extruders serving cost-sensitive segments.
- Specialty glazing labor scarcity:Skilled thermal-break assembly capacity concentrates at automated production lines, constraining regional fabricators.
- Structural load rating thresholds:NFRC and AAMA fenestration standards raise engineering costs for custom-dimension producers.
Strategic Opportunities
- Master-planned community channels:New construction clusters across the Southeast United States show faster volume growth than replacement channels.
- Smart glass convergence:Electrochromic technology integration with traditional bay geometries opens premium specification opportunities.
- Direct-to-builder platforms:Digital procurement channels bypass traditional distributor markups for multi-unit residential developers.
Industry Challenges
- Thermal modeling talent gaps:Building envelope engineers with NFRC certification command premium wages, slowing product development cycles.
- Multi-code compliance timelines:Simultaneous IECC, AAMA, and ENERGY STAR recertification requirements strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bays and Bows Window Market |
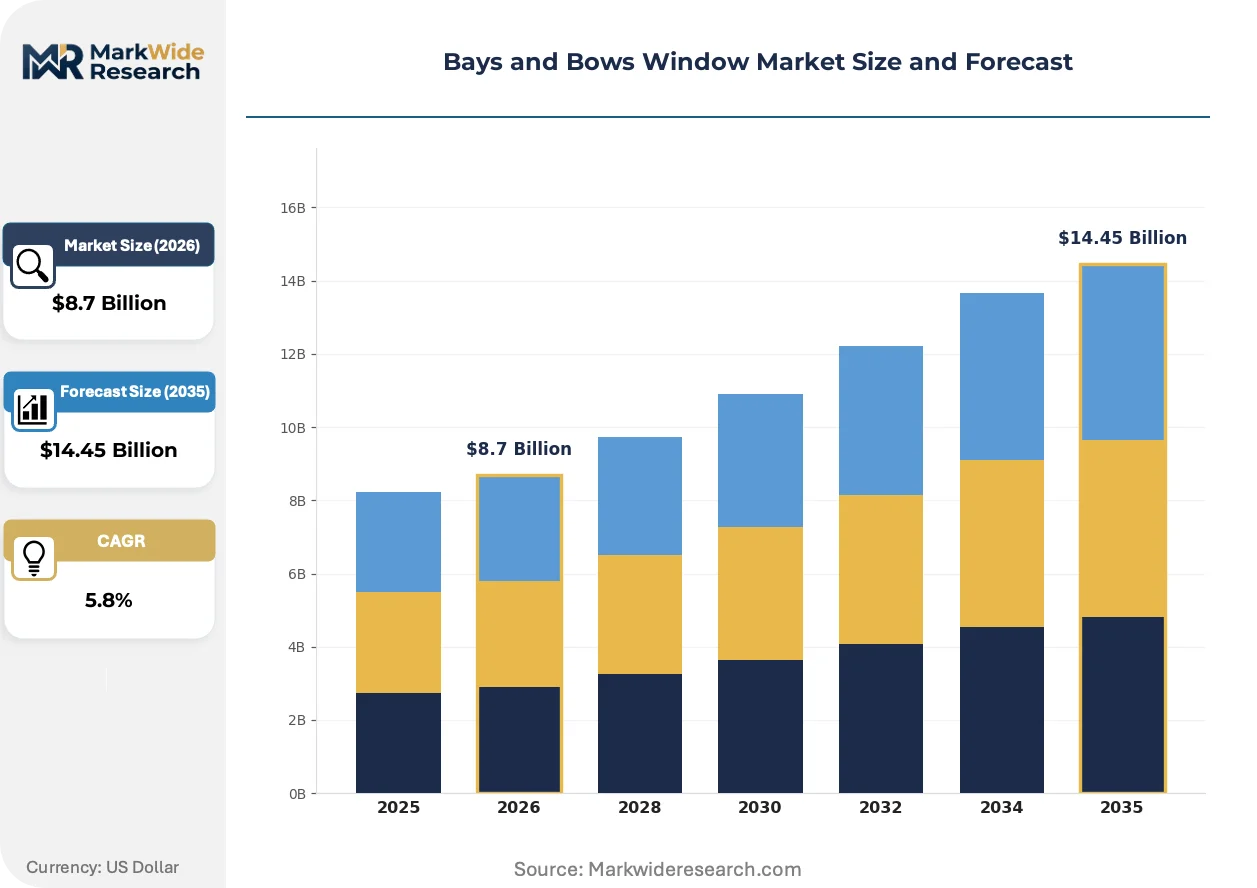
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl Bays, Aluminum Bows, Wood Bays, Composite Bows, Fiberglass Bays Installation Type: New Construction, Window Replacement, Retrofit, Commercial Fit-Out, Custom Installation End User: Residential Homeowners, Property Developers, Housing Contractors, Renovation Experts Distribution Channel: Direct Sales, Specialty Dealers, Home Improvement Stores, Online Platforms, Wholesale Distributors |
| Companies Covered | Andersen, Pella, Marvin, JELD-WEN, Milgard Windows, Ply Gem, ProVia, Atrium, Sierra Pacific Windows, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bays and Bows Window Market Trends and Innovations
Thermal performance engineering and procurement digitization are restructuring how bay and bow windows are specified, fabricated, and delivered to residential and light commercial end-uses.
Pultruded fiberglass composite framing is fragmenting traditional material hierarchies in coastal and extreme-climate zones. High-end residential architects specify these assemblies for dimensional stability and corrosion resistance. The technology is fragmenting premium segment boundaries as fiberglass costs compress toward vinyl parity.
EPA ENERGY STAR Version 7.0 specifications tighten U-factor thresholds for northern climate zones. Manufacturers must redesign glazing packages and spacer systems to maintain certification access. Vinyl fabricators in the Midwest United States face the steepest requalification curves.
Builder-direct procurement platforms disintermediate traditional lumberyard distributors for multi-unit residential projects. Volume developers consolidate specifications around certified fabricators with automated order-to-delivery systems. This channel shift concentrates most visibly in suburban renovation corridors across Texas and Florida.
Bays and Bows Window Market Segmentation
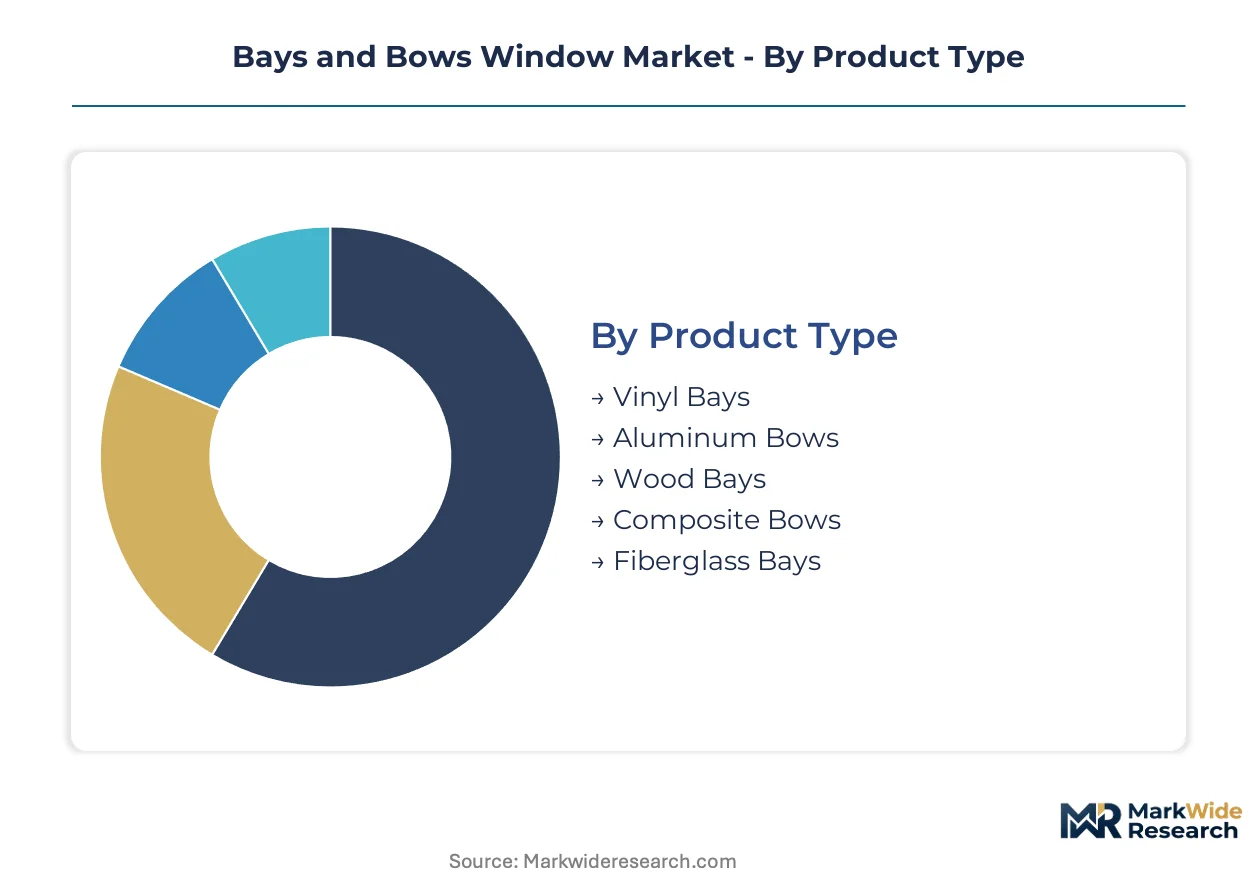
Bays and bows window procurement patterns diverge sharply across material grades and installation contexts. Specification behavior varies by whether the buyer prioritizes thermal performance certification, aesthetic customization, or total installed cost minimization.
Product Type:
Vinyl and fiberglass framing systems face divergent substitution pressures from cross-material specification shifts driven by IECC code tightening and coastal climate resilience requirements.
- Vinyl Bays:Polyvinyl chloride extrusion with multi-chamber thermal breaks dominates volume through cost efficiency and color stability across standard dimensions. Demand concentrates in Midwest suburban renovation corridors where ENERGY STAR Version 7.0 requalification curves are steepest.
- Fiberglass Bays:Pultruded composite framing delivers dimensional stability and corrosion resistance for coastal and extreme-climate applications. Specification intensity is climbing fastest in Southeast master-planned communities where humidity and salt exposure degrade vinyl performance.
- Aluminum Bows:Thermally broken aluminum extrusions serve commercial fit-out segments requiring narrow sightlines and structural span capability.
- Wood Bays:Solid and engineered lumber framing with exterior cladding systems anchor historic renovation and architect-driven residential specifications.
- Composite Bows:Hybrid material systems combining wood interior aesthetics with fiberglass or aluminum exterior skins occupy mid-premium positioning.
Vinyl Bays anchors the volume base while Fiberglass Bays gains share at the steepest rate.
Installation Type:
Channel economics stratify sharply between new construction volume plays and replacement margin capture, with retrofit complexity determining contractor capacity allocation.
- Window Replacement:Full-frame and insert replacement of aging units in existing wall openings generates the largest revenue contribution as US housing stock ages past 40-year median. Demand clusters in suburban renovation corridors where homeowners prioritize envelope upgrades over full rebuilds.
- New Construction:Rough-opening installation in residential and light commercial ground-up projects shows faster volume expansion in Southeast and Southwest master-planned communities. Builders consolidate specifications around certified fabricators with automated order-to-delivery systems.
- Retrofit:Structural modification of existing openings to accommodate bay projections requires engineered head and seat board integration.
- Commercial Fit-Out:Tenant improvement and facade renovation in light commercial buildings specifies aluminum-dominant systems.
- Custom Installation:Non-standard dimensions and angles for architect-specified residential projects command premium pricing and extended lead times.
Window Replacement dominates current revenue while New Construction climbs the fastest in volume expansion trajectory.
End User:
Buyer sophistication and specification authority vary dramatically between individual homeowners negotiating single-unit purchases and volume developers consolidating multi-project standards.
- Residential Homeowners:Individual purchasers driving single-family renovation decisions prioritize ENERGY STAR certification visibility and financing program eligibility. Selection behavior concentrates in suburban corridors across Texas and Florida where digital procurement platforms are penetrating fastest.
- Property Developers:Multi-unit residential and mixed-use project sponsors standardize specifications across building portfolios to compress procurement cycles and warranty complexity. Volume concentration is shifting toward direct-to-builder platforms bypassing traditional distributor markups.
- Housing Contractors:Production homebuilders and custom residential generalists manage trade-offs between installed cost and callback risk exposure.
- Renovation Experts:Design-build firms and specialty window contractors curate product portfolios based on installation crew skill alignment and supplier reliability.
Residential Homeowners anchors the transaction count base while Property Developers expands most quickly in specification consolidation.
Distribution Channel:
Channel power is fragmenting as digital procurement platforms disintermediate legacy lumberyard networks and manufacturer-direct relationships deepen with volume accounts.
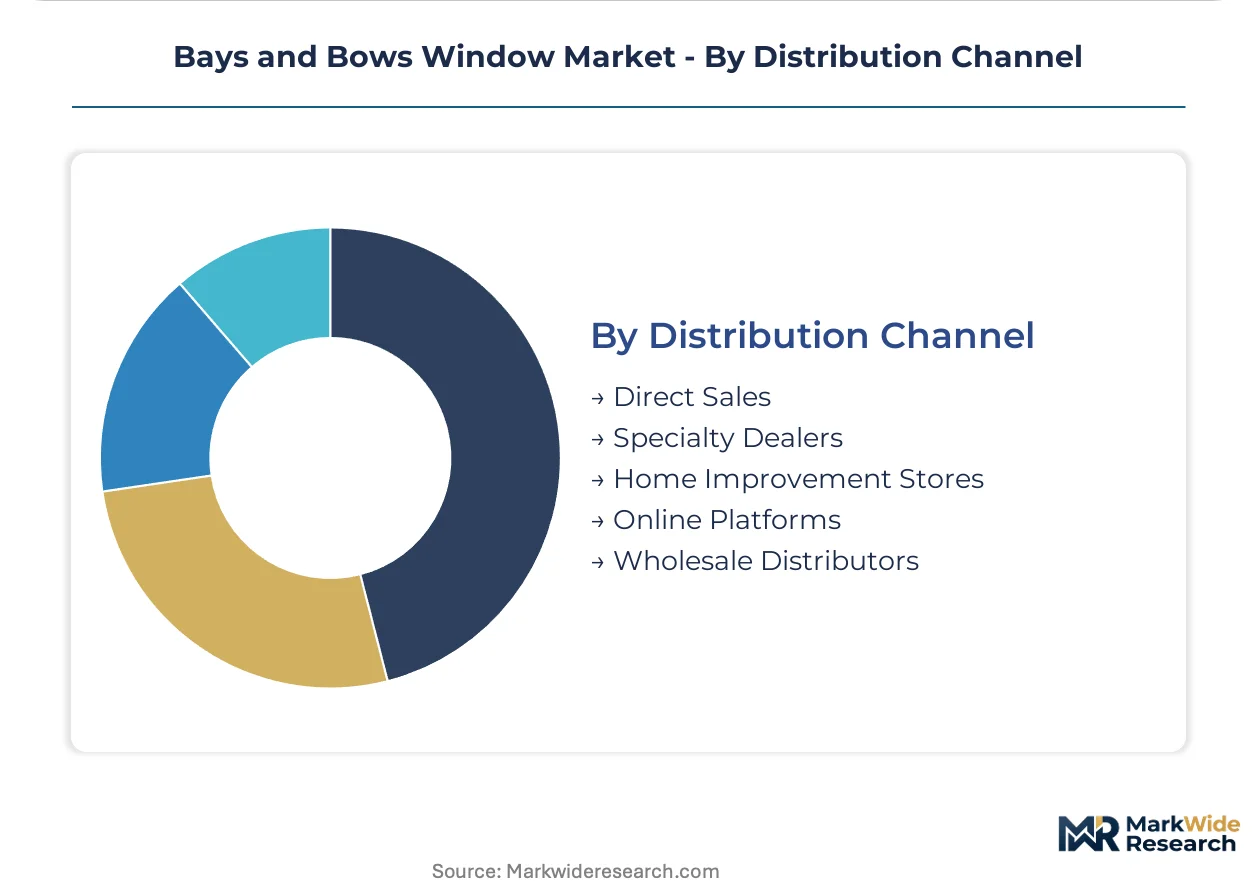
- Specialty Dealers:Independently owned window and door showrooms with in-house installation services capture premium residential specifications through consultative selling and thermal performance modeling. Geographic concentration follows affluent suburban corridors in the United States.
- Direct Sales:Manufacturer-employed sales organizations serving national and regional builders bypass distributor markups for multi-unit residential projects. Channel investment is intensifying around automated configuration and order-to-delivery systems.
- Home Improvement Stores:Big-box retailers with private-label and national brand offerings serve cost-sensitive replacement demand.
- Online Platforms:Digital-native procurement channels with virtual measurement and remote configuration tools are penetrating faster in tech-forward metropolitan markets.
- Wholesale Distributors:Regional lumber and building material distributors maintain contractor credit relationships and local inventory positioning.
Specialty Dealers holds the premium specification share while Direct Sales expands at the steepest rate in volume developer penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for bays and bows windows diverge sharply by climate zone and housing vintage. Northern markets prioritize thermal performance certification, while coastal regions emphasize material durability against salt and humidity exposure.
United States
Suburban renovation corridors across the Southeast and Midwest drive replacement volume as aging housing stock exceeds 40-year median age. EPA ENERGY STAR Version 7.0 specifications tighten U-factor thresholds, forcing manufacturers serving northern climate zones to redesign glazing packages. Texas and Florida master-planned communities show the fastest new construction specification consolidation around direct-to-builder procurement platforms.
Canada
Cold-climate envelope upgrades dominate demand as homeowners face escalating heating costs across Ontario and Quebec. Natural Resources Canada's ENERGY STAR program aligns with EPA specifications while adding province-specific thermal performance tiers. Toronto and Vancouver metropolitan clusters concentrate specialty dealer networks with in-house thermal modeling capabilities.
Germany
Passivhaus-certified renovation standards drive premium fiberglass and composite framing specifications in Baden-Württemberg and Bavaria. The German Energy Agency (dena) subsidizes envelope retrofits meeting stringent U-value thresholds. Stuttgart and Munich industrial corridors host fabricators specializing in custom-dimension architect specifications.
United Kingdom
Heritage conservation requirements in London and Southeast England preserve wood bay specifications for listed building renovations. Building Regulations Part L updates mandate improved window U-values for replacement installations. Manchester and Birmingham renovation markets show rising vinyl specification penetration in post-war housing stock.
Australia
Coastal humidity and bushfire resistance ratings reshape material selection in New South Wales and Queensland. The National Construction Code (NCC) bushfire attack level (BAL) ratings restrict window framing options in high-risk zones. Sydney and Melbourne metropolitan builders consolidate specifications around certified fabricators with automated compliance documentation systems.
Bays and Bows Window Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with material science capabilities and thermal certification bandwidth determining competitive position. The vendor base stratifies into three archetypes: vertically integrated extruders controlling resin supply and finishing operations, R&D-intensive composite specialists, and custom-dimension fabricators serving architect-specified residential projects. Capacity expansion in automated thermal-break assembly and strategic partnerships for smart glass integration represent the dominant competitive moves reshaping positioning.
Among North American fabricators, Andersen, Pella, and Marvin exemplify distinct strategic archetypes within the premium tier. Andersen represents the vertically integrated model with captive extrusion and finishing operations. Pella occupies the R&D-intensive position in pultruded fiberglass development. Marvin anchors the custom-dimension capability segment for high-end residential architects. These three companies illustrate how material specialization, manufacturing integration depth, and specification channel access combine to define competitive position in a market pressured by code-cycle compression and labor scarcity.
| Leading Market Players |
|---|
| Andersen |
| Pella |
| Marvin |
| JELD-WEN |
| Milgard Windows |
| Ply Gem |
| ProVia |
| Atrium |
| Sierra Pacific Windows |
| Others |
Pricing and Supply Chain Analysis
Automated thermal-break assembly capacity utilization at tier-one fabricators creates scale advantages that compress unit economics and establish price floors vinyl extruders cannot match. This concentration of production scale in the United States and Canada shapes procurement leverage for volume developers while forcing regional manufacturers toward specialty custom-dimension segments.
Pricing Analysis
Project-based contracting dominates multi-unit residential procurement, with volume developers negotiating frame-plus-glazing packages against standardized specification sheets. Price differentiation separates ENERGY STAR Version 7.0-certified fabricators from non-compliant regional suppliers, while customization level for architect-specified bays commands substantial premiums. Cost compression in vinyl extrusion intensifies as PVC resin feedstock volatility squeezes margin stability for cost-sensitive segments. Residential homeowners in suburban renovation corridors exhibit highest price sensitivity, whereas high-end architects demonstrate lowest sensitivity to secure custom dimension capabilities.
Supply Chain Analysis
Inventory positioning and lead-time compression favor fabricators with captive extrusion operations in the United States, Canada, and Germany. Raw material flows draw from PVC resin producers in the US Gulf Coast, pultruded fiberglass composite suppliers in North America, and Low-E coated glass from specialized float-glass operations. Single-source vulnerability concentrates in thermal-break spacer systems sourced from limited qualified vendors. Distribution runs through specialty dealer networks for premium residential specifications and direct-to-builder platforms for multi-unit volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA ENERGY STAR Version 7.0 implementation constitutes a regulatory inflection compressing the vendor base and accelerating specification consolidation around certified fabricators with automated quality systems.
For Market Incumbents: Shield market position by deepening backward integration into pultruded fiberglass composite production to capture coastal climate substitution away from vinyl. Prioritize thermal modeling talent acquisition to accelerate IECC requalification cycles before code adoption timelines tighten further. For New Entrants and Emerging Players: Differentiate on smart glass integration capabilities for premium residential architects seeking electrochromic bay specifications. Target master-planned community channels in Texas and Florida through direct-to-builder digital procurement platforms bypassing established distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fabricators with captive thermal-break assembly and NFRC certification bandwidth. Acquisition targets should demonstrate automated production scale and ENERGY STAR compliance infrastructure. Monitor IECC code adoption acceleration across Midwest municipalities as the critical inflection signal for vendor base consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Thermal-Break Assembly Investment | Reduces labor dependency while accelerating ENERGY STAR requalification cycles for IECC compliance. |
| Pultruded Fiberglass Capacity Expansion | Captures coastal and extreme-climate substitution demand degrading vinyl performance in humidity exposure. |
| Direct-to-Builder Platform Development | Bypasses specialty dealer markups for volume developers consolidating specifications in master-planned communities. |
| Smart Glass Integration Partnership | Opens premium specification opportunities with architects seeking electrochromic technology in traditional bay geometries. |
| Thermal Modeling Talent Acquisition | Accelerates product development cycles constrained by NFRC-certified building envelope engineer scarcity. |
Research Methodology
Initial hypotheses were tested against primary input from fenestration product managers, thermal performance engineers, residential construction procurement directors, and specialty window dealers and refined through secondary validation. Sources included NFRC certification databases, AAMA fenestration standards documentation, EPA ENERGY STAR program filings, and IECC code adoption records across state jurisdictions. Bottom-up demand modeling triangulated against top-down construction spending forecasts.
Variance decomposition across material type, installation context, end-user sophistication, and climate-zone regulatory stringency shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions across the projection horizon. Forecast inputs incorporated housing stock age distributions, code-cycle compression timelines, and substitution elasticities between vinyl and fiberglass framing systems.
The analysis sits within stated boundaries; outcomes outside sustained IECC adoption acceleration or PVC resin price stability would require recalibration. Forecasts reflect documented assumptions regarding labor availability and certification bandwidth. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
Home Remodeling Market
Home Improvement and Renovation
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Automatic Curtain Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Vietnam Home Improvement Market